
 India Cloud Robotics Market | 2026-2036
India Cloud Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
India Cloud Robotics Market Insights
AI-grade compute specification is rotating toward the center of vendor positioning in India. Addverb leverages its Noida manufacturing base to control domestic fulfillment timelines for warehouse automation clients. GreyOrange Robotics sustains R&D intensity in software-defined orchestration layers that separate its stack from hardware-centric competitors. Fanuc India anchors high-precision industrial installations across automotive OEM supply chains.
Cloud robotics fuses robotic hardware with distributed cloud infrastructure to enable real-time data processing, remote fleet management, and collective machine learning across deployed units. Systems rely on sub-50 millisecond latency thresholds between edge actuators and cloud inference nodes to execute collaborative tasks safely. Industrial robots and collaborative robots occupy the largest revenue pools today, while AI-powered robots represent the fastest-expanding category as computer vision models migrate from on-device to cloud-resident architectures. Hybrid cloud deployments capture disproportionate interest from manufacturers balancing data sovereignty requirements against elastic compute needs.
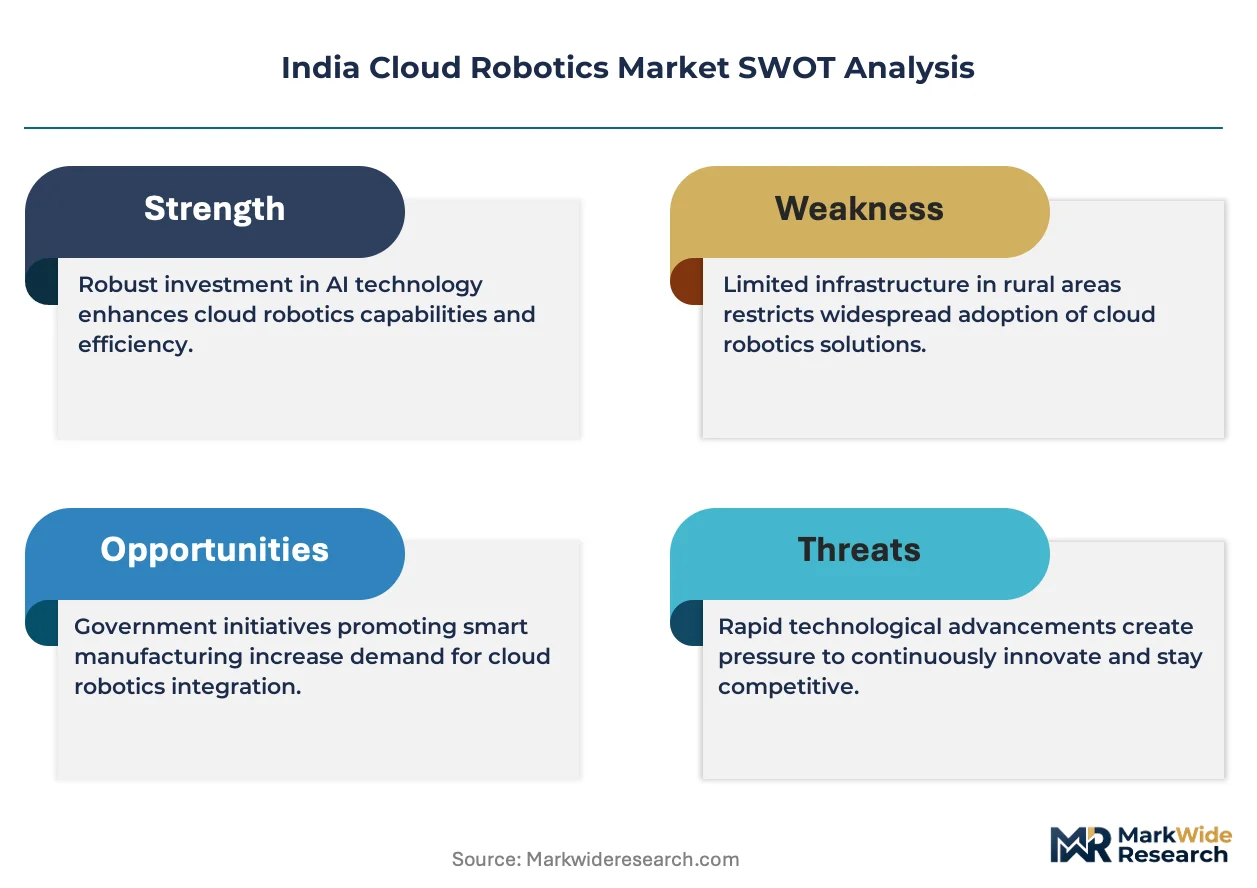
MeitY's National Strategy on Robotics, BIS standards for industrial automation safety, and RBI guidelines on data localization for cloud service providers collectively determine architecture choices and vendor eligibility. The central bank's data residency mandates force private cloud or hybrid configurations for financial services robotics applications. Stakeholders must monitor evolving BIS certification timelines and state-level electronics cluster incentives to time capital deployment cycles effectively.
Market Dynamics
Edge-cloud latency compression below 50 milliseconds is restructuring deployment architectures across Indian manufacturing corridors, forcing vendors to locate inference nodes within 300 kilometers of industrial clusters.
Growth Catalysts
- MeitY National Strategy on Robotics:Central policy framework mandates domestic value addition thresholds, accelerating local assembly of cloud-connected robotic systems for public sector procurement eligibility.
- Automotive OEM demand concentration:Pune and Chennai manufacturing hubs deploy collaborative robot fleets with centralized cloud orchestration to synchronize multi-factory production schedules.
- Sub-50ms latency threshold achievement:5G private network rollouts across Maharashtra's industrial corridor enable real-time kinematic control previously requiring on-premise compute.
Market Restraints
- GPU compute import dependency:Cloud robotics inference workloads rely on NVIDIA and AMD accelerators subject to DGFT licensing variability and rupee-dollar volatility.
- BIS certification timeline uncertainty:Industrial automation safety standards lack predictable approval windows, delaying fleet deployment schedules by 8-14 months.
- Data residency compliance cost:RBI guidelines force financial services robotics adopters into hybrid cloud configurations with 40-60% higher infrastructure overhead than pure public cloud.
Strategic Opportunities
- Tamil Nadu electronics manufacturing clusters:State-level subsidies for capital equipment create first-mover advantage for cloud-integrated robot deployments in underpenetrated southern corridors.
- Computer vision model convergence:Migration from edge-resident to cloud-resident AI architectures enables collective learning across heterogeneous robot fleets.
- PLI scheme for robotics components:Production-linked incentives for precision gearboxes and servo motors reduce import dependency for domestic system integrators.
Industry Challenges
- Cloud-edge integration specialist scarcity:Indian engineering talent pools lack depth in ROS-2 middleware configuration for distributed robotic systems.
- Legacy SCADA interoperability friction:Brownfield manufacturing facilities require protocol translation layers that introduce latency and reliability risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Cloud Robotics Market |
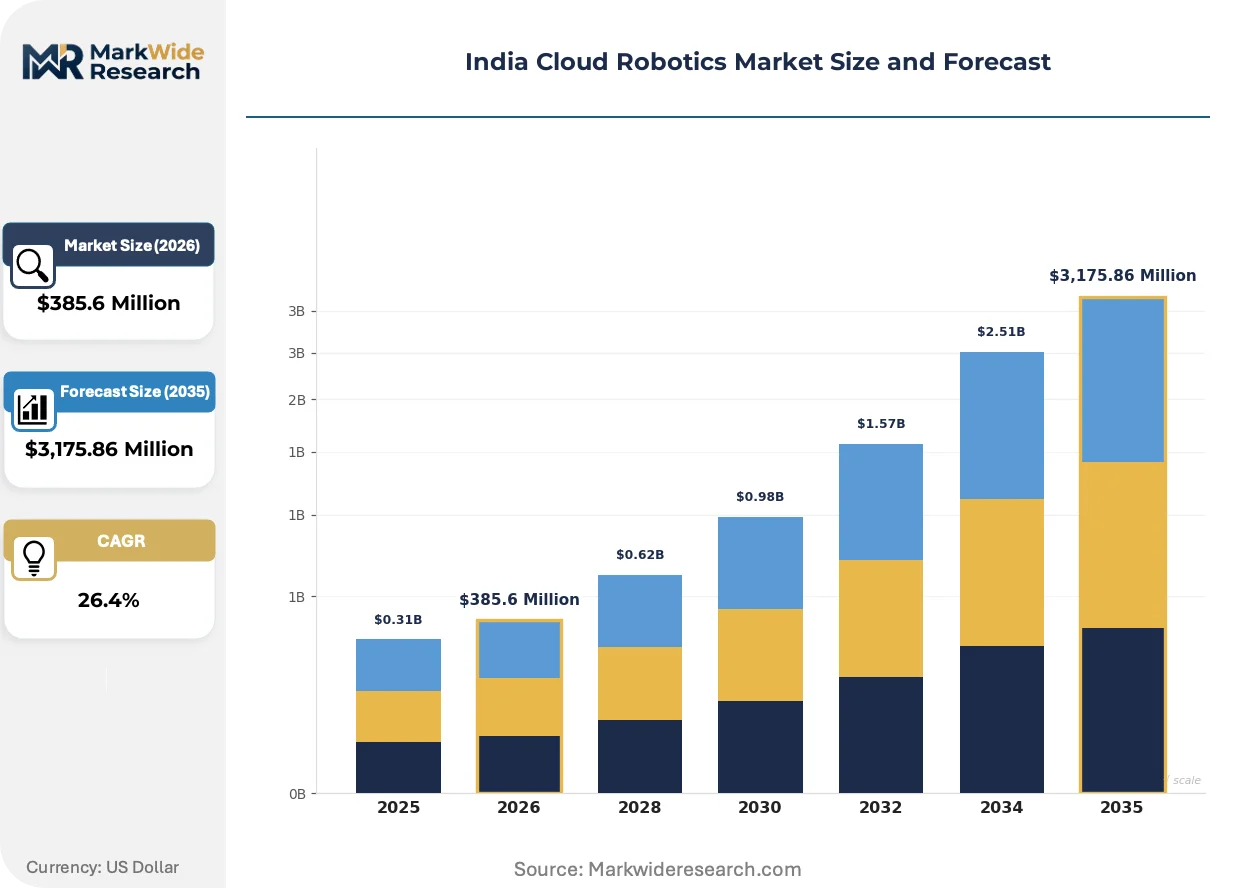
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $3,175.86 Million |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, Collaborative Robots, Service Robots, AI-Powered Robots End User: Manufacturing, Healthcare, Retail, Logistics Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Edge Computing Application: Automation, Surveillance, Maintenance, Telepresence |
| Companies Covered | Addverb, Asimov Robotics, GreyOrange Robotics, DiFACTO Robotics and Automation, Systemantics Robotics, Rapyuta Robotics, Gridbots, FlytBase, Fanuc India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Cloud Robotics Market Trends and Innovations
Software-defined orchestration is separating control intelligence from mechanical hardware, enabling subscription-based robot fleet management that restructures vendor-customer relationships across Indian industry.
Cloud-resident AI inference is decomposing the traditional monolithic robot controller architecture. Tier-1 automotive suppliers in Pune now deploy "dumb" manipulator arms with kinematic computation offloaded to Maharashtra-based edge data centers. This shift compresses hardware BOM costs by eliminating redundant on-device GPUs while centralizing model updates.
BIS certification requirements for industrial automation safety equipment are tightening electromagnetic compatibility testing protocols. Manufacturers must now submit cloud connectivity modules for separate radio frequency approval, extending product launch timelines. Small and mid-size system integrators in Gujarat and Karnataka are consolidating compliance functions to absorb these fixed costs.
Buyer preference is migrating from capital purchase to robot-as-a-service contracting. Third-party logistics operators in NCR and Mumbai now demand outcome-based pricing tied to picks-per-hour rather than equipment ownership. This compresses vendor cash conversion cycles and forces balance sheet restructuring among hardware-centric suppliers.
India Cloud Robotics Market Segmentation
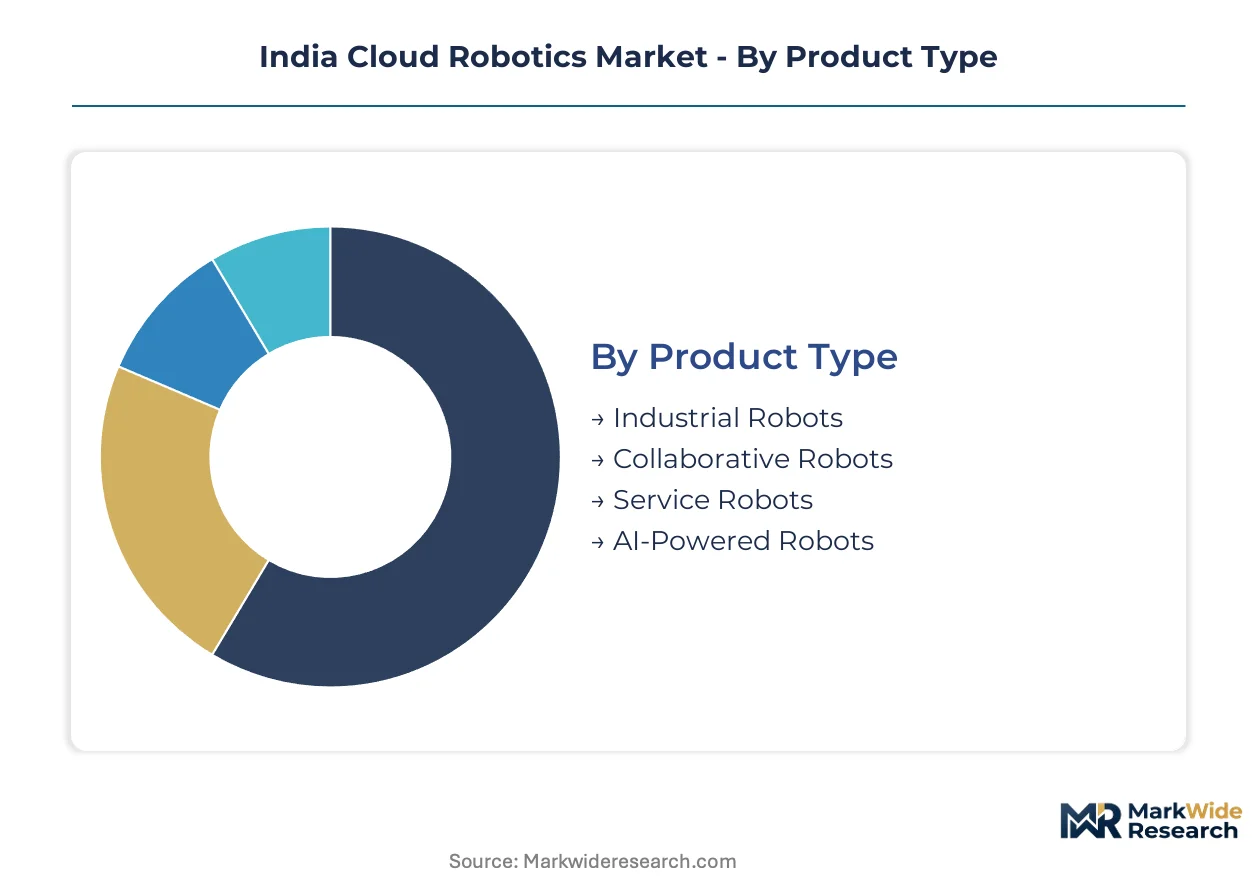
Cloud robotics architectures in India fragment across hardware form factors, deployment topologies, and regulatory compliance tiers. Procurement decisions hinge on BIS certification pathways and RBI data localization mandates that reshape total cost of ownership calculations.
Product Type:
BIS electromagnetic compatibility testing protocols apply differentially across hardware categories, with industrial automation equipment facing the most stringent radio frequency module approvals.
- Industrial Robots:High-payload articulated arms and Cartesian systems dominate automotive OEM installations in Pune and Chennai. Maharashtra's electronics manufacturing clusters absorb the majority of cloud-connected heavy industrial deployments, constrained by DGFT licensing variability for GPU accelerators.
- Collaborative Robots:Force-limited manipulators with embedded safety sensors enable human-robot workcell sharing. Tier-1 automotive suppliers across Tamil Nadu deploy these with centralized cloud orchestration to synchronize multi-factory production schedules.
- Service Robots:Mobile platforms for hospitality and facility management applications.
- AI-Powered Robots:Computer vision-enabled systems with cloud-resident inference models gaining share fastest in brownfield logistics operations.
Established volume favors Industrial Robots; emerging adoption favors AI-Powered Robots.
End User:
Customer procurement maturity varies sharply, with automotive manufacturers demanding outcome-based contracting while healthcare adopters prioritize compliance documentation.
- Manufacturing:Automotive OEMs and electronics contract manufacturers represent the dominant revenue pool, concentrated in Maharashtra and Tamil Nadu industrial corridors. MeitY domestic value addition thresholds accelerate local assembly requirements for public sector eligibility.
- Logistics:Third-party operators in NCR and Mumbai drive robot-as-a-service demand with picks-per-hour pricing models.
- Healthcare:Surgical assistance and sterilization automation subject to CDSCO device registration timelines.
- Retail:Inventory scanning and customer service applications in metro malls.
Manufacturing commands current procurement volume; Logistics exhibits the steepest expansion trajectory.
Deployment:
Infrastructure configuration choices reflect data sovereignty requirements and latency sensitivity tradeoffs specific to Indian network topology.
- Hybrid Cloud:Combines on-premise edge nodes with burst compute to public infrastructure. RBI guidelines force financial services adopters into this architecture with 40-60% infrastructure overhead premium.
- Private Cloud:Captive data centers within 300 kilometers of industrial clusters achieve sub-50ms latency thresholds.
- Public Cloud:Pure SaaS robotics management for non-regulated applications.
- Edge Computing:On-premise inference for latency-critical kinematic control.
Hybrid Cloud captures disproportionate interest; Private Cloud anchors high-precision installations.
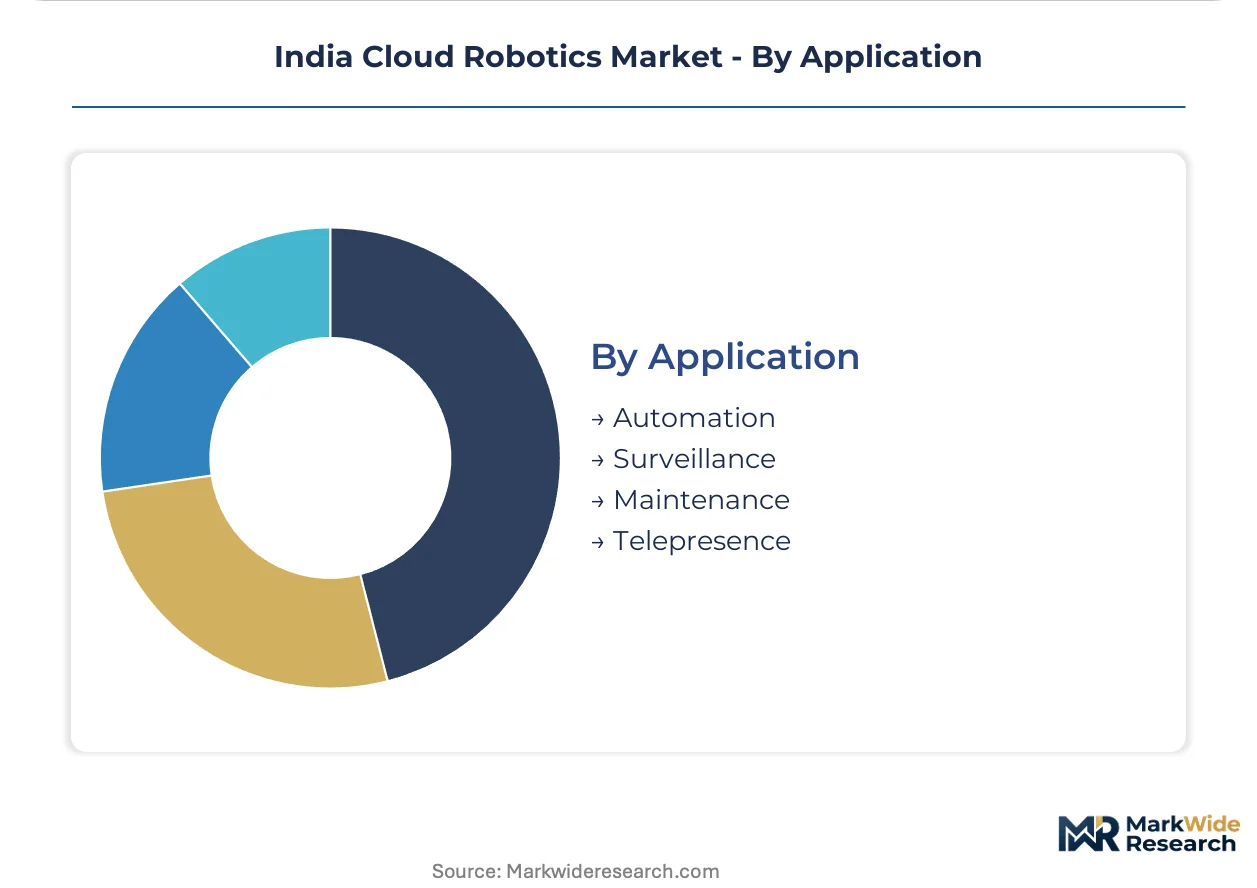
Application:
Use case prioritization follows manufacturing automation maturity curves and facility retrofit feasibility.
- Automation:Material handling, assembly, and quality inspection workflows dominate current deployments across automotive supply chains.
- Maintenance:Predictive diagnostics and remote troubleshooting for distributed industrial assets.
- Surveillance:Perimeter security and anomaly detection in critical infrastructure.
- Telepresence:Remote expert guidance and training applications.
Automation absorbs the majority of capital deployment; Maintenance is climbing fastest as fleet scales mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's cloud robotics trade balance tilts toward component imports, with GPU accelerators and precision servo motors arriving from East Asian supply chains while domestically assembled systems serve public sector procurement. State-level electronics manufacturing clusters absorb the majority of deployed capital across five industrialized sub-regions.
Maharashtra
Pune's automotive OEM supply chains deploy collaborative robot fleets with centralized cloud orchestration. The state's electronics manufacturing cluster policy attracts system integrators seeking PLI scheme benefits for precision components. Mumbai-NCR logistics operators now demand robot-as-a-service contracts tied to throughput metrics.
Tamil Nadu
Chennai's automotive manufacturing belt concentrates high-payload industrial robot installations with cloud-resident kinematic control. State subsidies for capital equipment create first-mover advantage for cloud-integrated deployments in underpenetrated southern corridors. Sriperumbudur electronics manufacturing clusters anchor new edge data center construction.
Gujarat
Small and mid-size system integrators consolidate BIS compliance functions to absorb electromagnetic compatibility testing costs. The state's industrial corridor development authority accelerates 5G private network licensing for sub-50 millisecond latency achievement. Sanand automotive plants pilot predictive maintenance robotics with cloud-edge hybrid architectures.
Karnataka
Bengaluru's software engineering base supplies ROS-2 middleware specialists for distributed robotic systems. The state's electronics manufacturing cluster incentives target precision gearbox and servo motor production under PLI schemes. Peenya industrial area hosts brownfield logistics automation retrofits with computer vision-enabled mobile platforms.
Telangana
Hyderabad's pharmaceutical manufacturing sector explores sterilization automation subject to CDSCO device registration timelines. The state's emerging electronics manufacturing policy competes with Tamil Nadu for cloud robotics component assembly investments. Genome Valley life sciences cluster pilots telepresence robotics for remote expert guidance.
India Cloud Robotics Market Competitive Landscape
Listed leaders compete with private specialists across capital structure flexibility, with publicly held industrial automation conglomerates accessing deeper balance sheets for R&D intensity while venture-backed challengers pivot faster on software-defined orchestration. The vendor base organizes into three tiers: multinational subsidiaries with captive manufacturing, domestic system integrators with state-level cluster relationships, and software-native startups with cloud-resident AI architectures. Dominant competitive moves include strategic partnerships with telecom operators for 5G private network deployment and backward integration into precision mechanical component production.
Within the domestic specialist tier, Addverb leverages its Noida manufacturing base to control fulfillment timelines for warehouse automation clients. GreyOrange Robotics exemplifies the software-defined orchestration archetype, separating its stack from hardware-centric competitors through centralized fleet management capabilities. Fanuc India anchors the multinational subsidiary position across high-precision automotive OEM installations in Pune and Chennai supply chains.
| Leading Market Players |
|---|
| Addverb |
| Asimov Robotics |
| GreyOrange Robotics |
| DiFACTO Robotics and Automation |
| Systemantics Robotics |
| Rapyuta Robotics |
| Gridbots |
| FlytBase |
| Fanuc India |
| Others |
Pricing and Supply Chain Analysis
Robot-as-a-service contracts with throughput-linked pricing lock in multi-year supply commitments for GPU accelerators while capping buyer exposure to rupee-dollar volatility. This structure concentrates procurement power among third-party logistics operators in NCR and Mumbai who can aggregate fleet-scale demand.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers bundle BIS-certified systems with embedded electromagnetic compatibility testing and localized edge data center access. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because domestic system integrators absorb fixed compliance costs through consolidation. Tier-1 automotive suppliers exhibit the lowest price sensitivity due to outcome-based contracting tied to production uptime metrics.
Supply Chain Analysis
Singapore port congestion and Red Sea transit disruptions expose Indian cloud robotics deployments to GPU accelerator delivery delays. Supply concentrates in Taiwan, South Korea, and the United States for NVIDIA and AMD inference chips. The ecosystem draws from Japanese precision servo motors, German precision gearboxes, and Chinese structural components. Single-source vulnerability in high-end GPU sourcing creates procurement risk given DGFT licensing variability. Distribution runs through Mumbai and Chennai port complexes to Maharashtra and Tamil Nadu electronics manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment topologies creates niche specialization opportunities as buyer preference splits between capital purchase and subscription contracting. This demand-side divergence rewards focused positioning over full-stack competition.
For Market Incumbents: Consolidate compliance functions to absorb BIS electromagnetic compatibility testing costs that now extend product launch timelines. Acquire ROS-2 middleware capabilities to address specialist scarcity in distributed robotic systems. Defensive positioning against software-native challengers requires backward integration into precision mechanical components to preserve margin structure.
For New Entrants and Emerging Players: Brownfield logistics automation in Gujarat and Karnataka presents under-served retrofit demand where legacy SCADA interoperability friction deters established vendors. Target facility management applications in Telangana's pharmaceutical corridor with telepresence robotics subject to CDSCO registration timelines. Lead with hybrid cloud architecture expertise to differentiate from hardware-centric incumbents.
For Investors and Strategic Acquirers: Software-defined orchestration specialists with centralized fleet management platforms capture durable value as the control intelligence layer separates from mechanical hardware. Monitor 5G private network licensing velocity across state industrial corridor development authorities as the inflection indicator for latency-critical deployment scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Data Center Partnership | Locates inference nodes within 300 kilometers of Maharashtra and Tamil Nadu clusters to achieve sub-50ms latency thresholds. |
| ROS-2 Middleware Acquisition | Addresses specialist scarcity in distributed robotic systems configuration for cloud-edge integration. |
| BIS Certification Pre-Investment | Accelerates electromagnetic compatibility approval timelines that currently delay fleet deployments by 8-14 months. |
| Precision Component Backward Integration | Captures PLI scheme benefits for servo motors and gearboxes while reducing import dependency exposure. |
| Robot-as-a-Service Platform Launch | Aligns vendor economics with third-party logistics operator demand for picks-per-hour outcome pricing. |
Research Methodology
Initial hypotheses were tested against primary input from robotics system integrators, automotive OEM procurement directors, warehouse automation engineers, and cloud infrastructure architects and refined through secondary validation. Sources included BIS certification records, RBI data localization guidelines, MeitY policy circulars, state electronics manufacturing cluster filings, and hyperscaler edge data center expansion disclosures. Bottom-up deployment estimates triangulated against top-down industrial automation capex projections.
Variance decomposition across hardware form factors, deployment topologies, and regulatory compliance tiers structured the analytical framework over the projection horizon. Segmentation dimensions modeled encompassed product type, end-use industry, infrastructure configuration, and application workflow. CAGRs were derived from installed base growth trajectories and average selling price evolution. Industry-specific inputs incorporated 5G private network rollout schedules and PLI scheme uptake rates for precision components.
Underlying assumptions cover sustained DGFT licensing stability for GPU imports and state-level cluster subsidy continuity, with deviation risk concentrated in BIS certification timeline unpredictability and rupee exchange rate volatility. Practitioners should keep alternative scenarios live as central bank data residency enforcement intensity and state electronics policy competitiveness evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Delivery Robots Market
Robotics and Automation
Global Automated Parcel Delivery Terminals Market
Robotics and Automation
Delta Robotics Market
Robotics and Automation
Global Articulated Robot Market
Robotics and Automation
Electric Power Intelligent Inspection Robot Market
Robotics and Automation
Robotic Air Purifier Market
Robotics and Automation
Wearable Robotic Exoskeleton Market
Robotics and Automation
Europe Robotics and Automation Actuators Market
Robotics and Automation
Robotics and Automation Actuators Market
Robotics and Automation
Robotic Waste Sorting System Market
Robotics and Automation
Robot Market
Robotics and Automation
Industrial Robotics Market
Robotics and Automation
Cyber-Physical System Market
Robotics and Automation
Germany Cloud Robotics Market
Robotics and Automation
Cleaning Robot Market
Robotics and Automation
Smart Worker Market