
 Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market | 2026-2036
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market Size, Share, and Industry Trends Forecast 2026-2036
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market Insights
Power line inspection is decoupling from traditional manned helicopter methods as utilities seek safer, more frequent asset monitoring. Cyberhawk leverages its offshore platform monitoring heritage to anchor long-term contracts with North Sea oil and gas operators. Skydio specializes in autonomous navigation for confined-space infrastructure, while DJI dominates manufacturing scale for multi-sensor payload integration across thermal and visual inspection drones.
Drone-based NDT inspection systems for energy and infrastructure assets combine unmanned aerial vehicles with non-destructive testing payloads—ultrasonic transducers, eddy current arrays, and infrared sensors—to detect subsurface corrosion, delamination, and thermal anomalies without disassembly or shutdown. These systems typically operate at altitudes below 400 feet with flight endurance of 30-55 minutes, transmitting real-time data to ground control stations for immediate defect classification. Thermal imaging drones lead product type adoption due to mature sensor costs and straightforward interpretation protocols, while LiDAR-enabled systems represent the fastest-growing technology segment as point-cloud accuracy improves for structural deformation mapping. Pipeline surveillance applications command the deepest margin pools given regulatory mandates for continuous integrity management.
FAA Part 107 and EASA Specific Category frameworks shape operational demand by defining beyond-visual-line-of-sight certification pathways that directly determine fleet scalability for power grid operators. OSHA fall-protection enforcement and ISO 21351 drone inspection standards further constrain market access for uncertified service providers. Stakeholders must monitor evolving type-certification requirements as regulators classify heavy-payload NTD drones into distinct airworthiness categories.
Market Dynamics
Autonomous navigation algorithms are compressing inspection cycle times for wind turbine blade assessment, forcing utilities to renegotiate service contracts around flight-hour pricing rather than per-turbine fees.
Growth Catalysts
- FAA Part 107 waiver expansion:Beyond-visual-line-of-sight approvals for utility-scale solar farms in Arizona and Texas are unlocking recurring revenue streams for drone service operators.
- Offshore wind buildout:North Sea installations require corrosion monitoring at heights and sea states inaccessible to rope-access technicians, pulling autonomous systems into mandatory maintenance protocols.
- Eddy current array miniaturization:Subsurface crack detection payloads now deploy from quadcopters under 25 kilograms, eliminating the need for heavy-lift hexacopter platforms and their associated certification burdens.
Market Restraints
- LiDAR sensor supply concentration:German and Japanese component manufacturers control 70% of high-precision ranging modules, exposing fleet operators to 14-week lead time volatility.
- OSHA fall-protection enforcement:Ground crews supporting drone operations near transmission towers face elevated insurance premiums that inflate total contract costs by 12-18%.
- Battery energy density plateau:Lithium-polymer cell chemistry limits flight endurance to 35-50 minutes, forcing frequent battery swaps that interrupt thermal anomaly detection workflows.
Strategic Opportunities
- India transmission grid digitization:State electricity boards in Maharashtra and Gujarat are piloting drone corridors for 765kV line inspection, creating first-mover advantages for certified operators.
- EU Green Deal carbon accounting:Asset owners must document inspection-related emissions reductions to satisfy CSRD disclosure requirements, favoring drone methods over helicopter surveys.
- AI-driven defect classification:Convolutional neural networks trained on blade delamination datasets are reducing analyst review time from hours to minutes, enabling per-flight pricing premiums.
Industry Challenges
- Part 107 remote pilot certification bottlenecks:The FAA's 6-8 week processing window for BVLOS waivers delays contract mobilization and strains client relationships.
- ISO 21351 implementation gaps:Inconsistent auditor interpretation of drone inspection documentation standards forces operators to maintain parallel quality systems for different utility clients.
- Legacy SCADA integration complexity:Thermal anomaly data streams require custom middleware to feed into existing asset management platforms, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market |
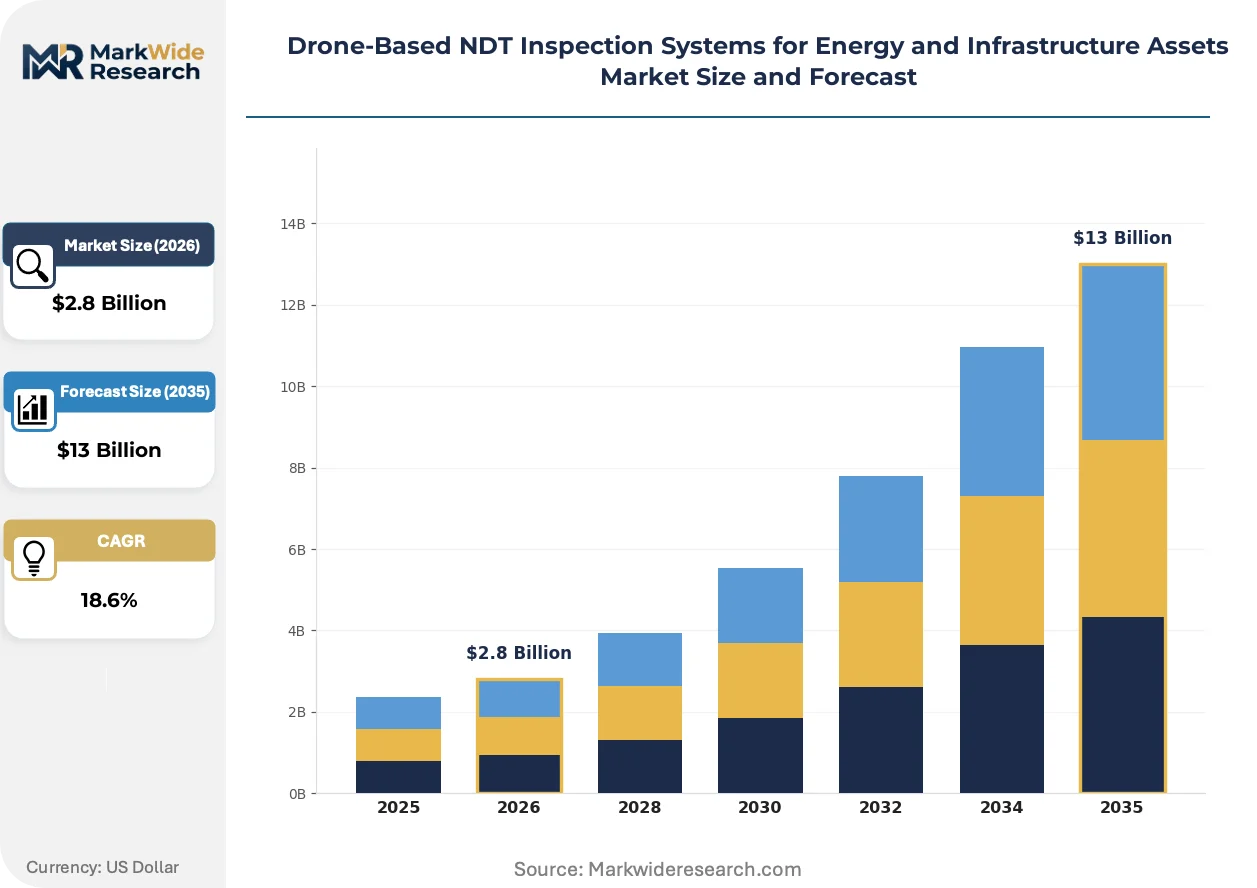
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Drones, Magnetic Flux Leakage Drones, Visual Inspection Drones, Thermal Imaging Drones, Eddy Current Drones Technology: LiDAR, High-Resolution Cameras, Infrared Sensors, Ultrasonic Sensors, Radar Sensors Application: Power Line Inspection, Pipeline Surveillance, Bridge Assessment, Wind Turbine Examination, Offshore Platform Monitoring End User: Energy Operators, Infrastructure Maintenance Firms, Oil & Gas Companies, Utilities Providers, Renewable Energy Companies |
| Companies Covered | Flyability, Cyberhawk, Skydio, Gecko Robotics, Percepto, DJI, Intertek Group, MISTRAS Group, Wipro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market Trends and Innovations
Edge computing architectures are relocating defect detection from ground stations to onboard processors, compressing latency for real-time decision-making during autonomous flights.
Swarming coordination protocols are decentralizing inspection task allocation across multiple UAVs operating simultaneously on large solar arrays. California utility-scale developers now deploy 4-6 unit fleets that partition 500-acre sites into concurrent survey zones, collapsing inspection duration from days to hours. This topology eliminates single-point-of-failure risks while reducing per-megawatt inspection costs.
EASA Specific Category frameworks are mandating geo-awareness and detect-and-avoid capabilities for operations above 120 meters. German transmission system operators must now equip fleets with ADS-B transponders and optical collision avoidance sensors, adding 15-20% to hardware procurement budgets. French nuclear facility inspectors face additional cybersecurity certification requirements under the EU AI Act's high-risk system classification.
Asset owners are unbundling inspection data ownership from flight services, demanding raw thermal imagery and point-cloud archives rather than summarized reports. Texas wind farm operators now stipulate API-accessible databases in RFPs, enabling integration with predictive maintenance platforms. This shift compresses margins for pure-flight providers while rewarding analytics-capable vendors with multi-year platform subscriptions.
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market Segmentation
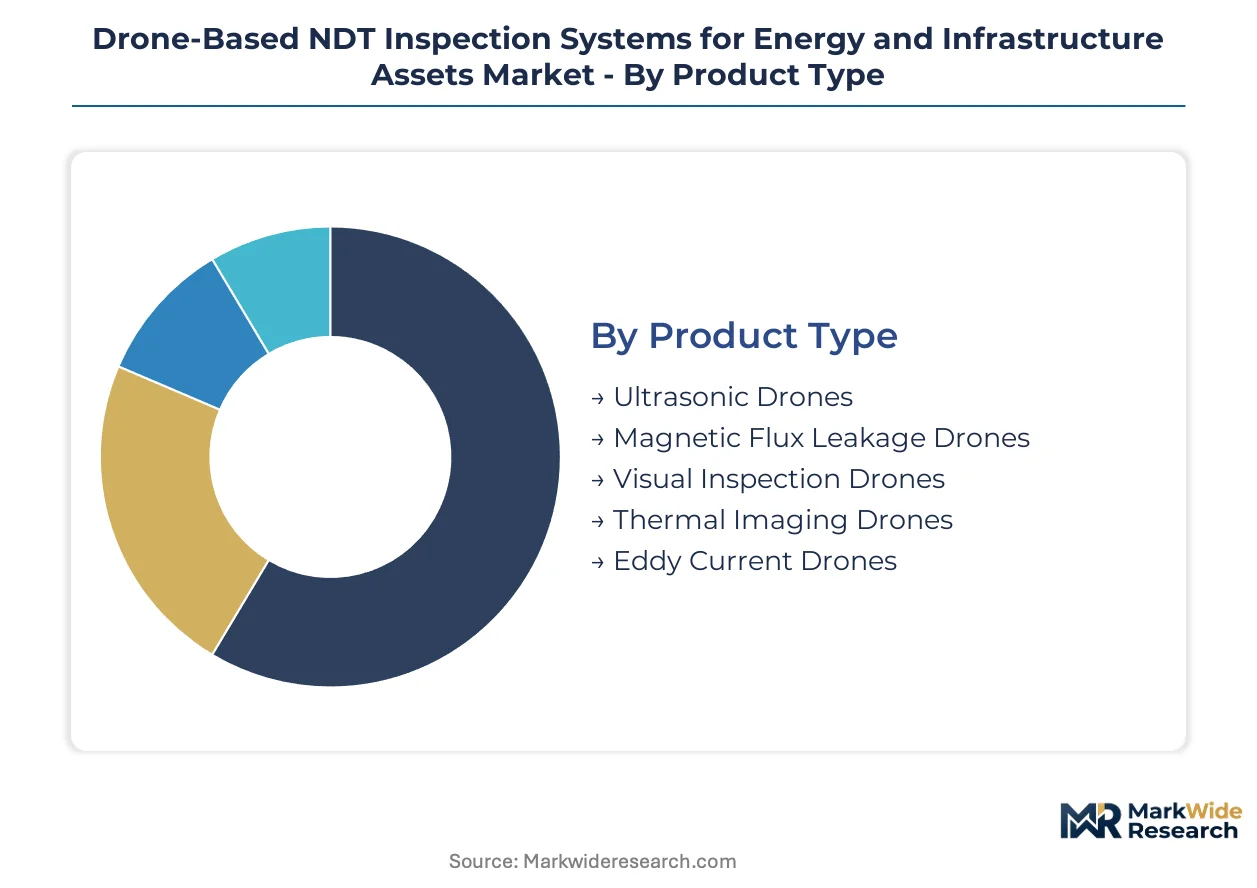
Drone-based NDT inspection systems fragment across sensor modalities, deployment technologies, and asset-specific applications. Each segmentation axis reveals distinct procurement patterns, certification requirements, and margin structures that shape vendor positioning.
Product Type:
Supply concentration for airborne NDT payloads varies sharply by detection physics and regulatory certification burden.
- Thermal Imaging Drones:Infrared focal plane arrays detect subsurface delamination and electrical hot spots through thermal gradient mapping. Demand concentrates in United States utility-scale solar farms where FAA Part 107 waivers enable recurring blade and panel surveys. Sensor cost curves have flattened, compressing hardware margins while expanding addressable volume.
- Visual Inspection Drones:High-resolution RGB and multispectral cameras capture surface corrosion, coating failures, and structural deformation. Infrastructure maintenance firms in Texas and Arizona deploy these systems for bridge deck assessment under state DOT performance-based contracts. Interpretation workflows remain labor-intensive, preserving service-provider margins.
- Ultrasonic Drones:Piezoelectric transducer arrays measure material thickness and detect internal voids through pulse-echo techniques.
- Magnetic Flux Leakage Drones:Magnetizing yokes and flux sensors identify pipeline corrosion anomalies in ferromagnetic steel.
- Eddy Current Drones:Miniaturized coil arrays now deploy from sub-25kg platforms for conductive material crack detection.
Thermal imaging drones absorb the bulk of installed capacity; eddy current drones are expanding most quickly as payload miniaturization eliminates heavy-lift certification requirements.
Technology:
Cost tier differentiation separates mature optical sensors from emerging ranging and penetrating modalities.
- LiDAR:Time-of-flight and phase-shift laser scanners generate millimeter-accuracy point clouds for structural deformation quantification. German transmission system operators under EASA Specific Category mandates drive premium procurement for geo-referenced tower lean analysis. Supply concentrates in Japanese and German component manufacturers, exposing operators to extended lead times.
- High-Resolution Cameras:CMOS and CCD sensors with gimbal stabilization deliver sub-centimeter ground sample distance for visual defect documentation. Volume demand clusters in United States wind farm operators seeking standardized blade condition records for warranty claims.
- Infrared Sensors:Uncooled microbolometer arrays dominate thermal payload integration for electrical and mechanical anomaly detection.
- Ultrasonic Sensors:Contact and non-contact transducers enable thickness gauging and flaw detection in metallic structures.
- Radar Sensors:Ground-penetrating and synthetic aperture radar penetrate non-metallic surfaces for subsurface void mapping.
High-resolution cameras anchor current fleet deployment; LiDAR is climbing the fastest as point-cloud accuracy improves for predictive deformation modeling.
Application:
Application segmentation reflects divergent regulatory intensity, access difficulty, and contract renewal cycles across infrastructure asset classes.
- Power Line Inspection:Corridor surveys for conductor wear, vegetation encroachment, and insulator degradation. United States utilities in California and Texas are decoupling from manned helicopter methods under OSHA fall-protection cost pressures. Recurring annual contracts dominate revenue models.
- Pipeline Surveillance:Long-linear integrity assessment for corrosion, coating damage, and third-party interference. Regulatory mandates for continuous monitoring under PHMSA and state PUC rules create sticky, multi-year service relationships with margin depth exceeding other verticals.
- Wind Turbine Examination:Blade leading-edge erosion, lightning receptor damage, and structural crack detection.
- Bridge Assessment:Deck delamination, bearing condition, and superstructure element rating for DOT compliance.
- Offshore Platform Monitoring:Corrosion under insulation, flare stack integrity, and structural member assessment in marine environments.
Pipeline surveillance commands the deepest margin pools; offshore platform monitoring is gaining share fastest as North Sea buildouts accelerate.
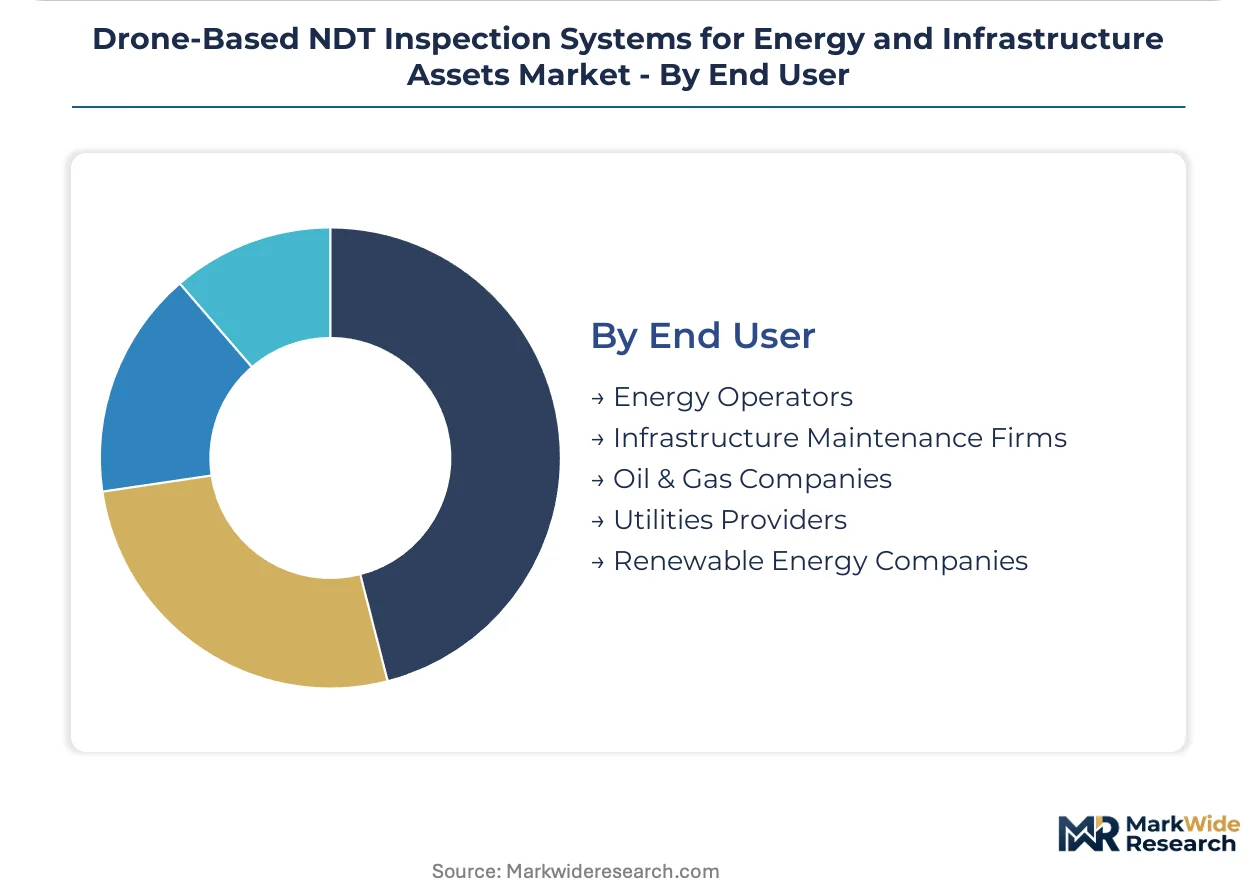
End User:
Customer type determines procurement sophistication, data ownership demands, and integration complexity with legacy asset management platforms.
- Utilities Providers:Vertically integrated electric and gas distribution operators with captive inspection teams and standardized RFP processes. United States IOUs and munis in Florida and Illinois now mandate API-accessible raw data archives rather than summary reports, compressing pure-flight provider margins.
- Renewable Energy Companies:Wind and solar asset owners with geographically dispersed portfolios and limited in-house aviation expertise. California and Texas developers prioritize per-megawatt pricing and fleet swarming capabilities to collapse inspection duration.
- Oil & Gas Companies:Upstream and midstream operators with offshore exposure and corrosion-intensive asset bases.
- Infrastructure Maintenance Firms:Third-party service contractors performing DOT-compliant bridge and roadway assessment.
- Energy Operators:Integrated generation and transmission entities with mixed fossil and renewable portfolios.
Utilities providers absorb the bulk of current contract value; renewable energy companies are expanding procurement fastest as capacity buildouts outpace internal aviation team scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of drone-based NDT inspection systems concentrates in Chinese and American industrial corridors, while deployment demand clusters in North Sea offshore zones, American solar belts, and Indian transmission corridors.
United States
Utility-scale solar farms in Arizona and Texas drive recurring blade and panel inspection contracts under FAA Part 107 waiver expansion. OSHA fall-protection enforcement pressures utilities to abandon manned helicopter methods for power line corridors. California developers now mandate API-accessible raw data archives in procurement RFPs.
Germany
EASA Specific Category frameworks mandate ADS-B transponders and optical collision avoidance for transmission system operators conducting tower lean analysis. The country's national aviation regulator requires geo-awareness capabilities above 120 meters. Bavarian and North Rhine-Westphalian grid operators absorb premium procurement costs for LiDAR-enabled deformation mapping systems.
China
Dual carbon goals accelerate wind turbine buildouts in coastal provinces, pulling autonomous inspection systems into mandatory maintenance protocols. The Ministry of Industry and Information Technology classifies heavy-payload NDT drones into distinct airworthiness categories. Yangtze River Delta manufacturing clusters supply 70% of global high-precision ranging modules.
India
State electricity boards in Maharashtra and Gujarat pilot drone corridors for 765kV transmission line inspection under central electricity authority digitization mandates. The country's national standards body develops certification pathways for beyond-visual-line-of-sight operations. First-mover advantages accrue to operators securing Bureau of Indian Safety compliance for thermal payload integration.
United Kingdom
North Sea offshore wind installations require corrosion monitoring at heights and sea states inaccessible to rope-access technicians. The Civil Aviation Authority processes BVLOS waivers for platform inspection fleets operating beyond 12 nautical miles. Scottish and English North Sea clusters anchor long-term service relationships with margin depth exceeding onshore verticals.
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market Competitive Landscape
Top-tier vendors anchor manufacturing scale and autonomous navigation IP, while mid-tier service providers compete on regional certification depth and utility relationship density. The vendor base stratifies across three archetypes: sensor-integrated platform manufacturers, inspection-as-a-service operators, and predictive analytics software vendors. Consolidation pressures intensify as asset owners unbundle data ownership from flight services. Dominant competitive moves include backward integration into sensor manufacturing and strategic partnerships with transmission system operators for multi-year platform subscriptions.
Within the confined-space autonomy tier, Flyability and Skydio exemplify specialized navigation architectures for infrastructure interiors. Cyberhawk occupies a position among offshore service operators leveraging North Sea platform monitoring heritage. DJI anchors the manufacturing-scale vector for multi-sensor payload integration. Gecko Robotics and Percepto sit within the predictive analytics tier, representing vendors where asset owners demand raw thermal imagery archives rather than summarized reports.
| Leading Market Players |
|---|
| Flyability |
| Cyberhawk |
| Skydio |
| Gecko Robotics |
| Percepto |
| DJI |
| Intertek Group |
| MISTRAS Group |
| Wipro |
| Others |
Pricing and Supply Chain Analysis
Certified remote pilot concentrations in Arizona and Texas create labor-cost differentials that widen pricing-tier spreads between FAA Part 107 waiver holders and uncertified operators. These geographic workforce disparities compress margins for commodity thermal inspection services while preserving premiums for BVLOS-certified analytics providers.
Pricing Analysis
Price erosion across standard-tier inspection services traces to fleet operator overcapacity in United States solar belt markets. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and data-analytics bundling. Cost compression in economy-tier visual inspections intensifies because DJI hardware commoditization eliminates equipment differentiation. Renewable energy companies exhibit highest price sensitivity; offshore oil and gas operators remain least sensitive due to regulatory compliance mandates.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for drone manufacturing are reshaping component sourcing for transmission corridor operators. High-precision LiDAR modules concentrate in German and Japanese supplier bases; thermal sensor arrays draw from Chinese Yangtze River Delta clusters. Supply chain risk centers on single-source vulnerability for uncooled microbolometer arrays. Distribution runs through OEM-direct procurement for major fleet operators and regional distributor networks for mid-tier service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where sensor payload manufacturing and predictive analytics software represent the critical upstream and downstream levers players are pursuing.
For Market Incumbents: Deploy backward integration into LiDAR sensor production to escape Japanese and German supply bottlenecks. Anchor long-term platform subscriptions with United States IOUs by mandating API-accessible raw data archives in contract renewals. Cyberhawk's offshore heritage demonstrates how North Sea monitoring contracts resist pure-flight commoditization.
For New Entrants and Emerging Players: FAA Part 107 waiver expansion in Arizona and Texas opens a window for certified operators to capture recurring utility-scale solar inspection contracts. Target Maharashtra and Gujarat transmission corridors where Bureau of Indian Safety compliance creates first-mover barriers. Lead with AI-driven defect classification capabilities that reduce analyst review time and justify per-flight pricing premiums.
For Investors and Strategic Acquirers: Re-rating potential sits with predictive analytics software vendors given asset owner demands for raw thermal imagery archives rather than summarized reports. Long-term viability favors vendors with captive sensor manufacturing and multi-year platform subscription revenue. Watch EASA Specific Category framework evolution as the inflection signal for European fleet hardware upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive LiDAR production insulates against 14-week lead time volatility from Japanese suppliers. |
| AI-Driven Defect Classification Platform | Convolutional neural networks trained on blade datasets reduce analyst review from hours to minutes. |
| BVLOS Certification Investment | FAA Part 107 waiver expansion unlocks recurring revenue streams for utility-scale solar operators. |
| Raw Data Archive API Development | Texas wind farm RFPs now mandate API-accessible databases for predictive maintenance integration. |
| Offshore Platform Monitoring Service | North Sea corrosion monitoring contracts exceed onshore margins due to rope-access inaccessibility. |
Research Methodology
Multi-period observation of FAA Part 107 waiver issuance patterns, EASA Specific Category framework evolution, and utility RFP documentation anchored the trend analysis, supplemented by interviews with utility planning officers, drone fleet operations managers, transmission system operator procurement leads, and predictive maintenance software engineers. Secondary validation drew from FERC filings, EIA renewable capacity deployment data, OSHA enforcement records, and ISO 21351 implementation guidance. Bottom-up fleet operator revenue estimates triangulated against top-down addressable infrastructure asset counts.
Segment-weighting across sensor modality, deployment technology, and asset-specific application dimensions shaped the analytical framework. CAGRs were derived from installed base growth rates and replacement cycle assumptions across the projection horizon. Modeled inputs included lithium-polymer battery energy density trajectories, thermal sensor cost curves, and BVLOS regulatory approval velocity by jurisdiction.
The model assumes a particular technology adoption path for edge-computing defect detection; alternative pathways for onboard AI processing architectures would alter the outlook. Forecasts reflect assumptions about EASA and FAA regulatory harmonization progress, battery chemistry breakthroughs, and utility data-ownership unbundling velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Automotive Robotic Painting Market
Robotics and Automation
Global Robotic Process Automation in Healthcare Market
Robotics and Automation
GCC AUV Market
Robotics and Automation
Commercial Service Robotics Market
Robotics and Automation
Hospital Logistics Robots Market
Robotics and Automation
Global Adaptive Robot Market
Robotics and Automation
Robotics Sweeper Market
Robotics and Automation
Bionic Glove's Market
Robotics and Automation
Europe Robotics and Automation Actuators Market
Robotics and Automation
Europe Data Center Robotics Market
Robotics and Automation
AI Assisted Robots Market
Robotics and Automation
Autonomous Drilling Robots Market
Robotics and Automation
Autonomous Navigation Robots Market
Robotics and Automation
US Cloud Robotics Market
Robotics and Automation
Consumer Robotics Market
Robotics and Automation
Global Wafer Handling Robots Market