
 LAMEA Waste Sorting Robots Market | 2026-2036
LAMEA Waste Sorting Robots Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Waste Sorting Robots Market Insights
CE marking under the EU Machinery Directive is unwinding competitive access for European-origin equipment suppliers entering LAMEA markets. TOMRA Sorting GmbH leverages its sensor-based sorting heritage to anchor premium installations across Brazilian recycling complexes. Bollegraaf Recycling Solutions competes through integrated plant engineering that extends from feed systems to robotic extraction. AMP Robotics differentiates via AI-driven vision pipelines that specialize in identifying food-grade PET streams at municipal throughput scales.
Waste sorting robots are electromechanical systems combining articulated arms, computer vision arrays, and pneumatic grippers to autonomously segregate commingled refuse streams by material composition, color, and contamination level. These units typically operate at throughputs exceeding sixty picks per minute with sorting purity above ninety-five percent for single-stream recyclables. Stationary robots dominate current LAMEA deployments due to lower capital requirements and retrofit compatibility with existing conveyor infrastructure. AI-Based technology segments are gaining fastest as Brazilian and Mexican operators prioritize machine-learning classification over rule-based sensor configurations. Vision Systems occupy the broadest addressable base across mid-tier recycling facilities lacking dedicated technical staff.
Brazil's National Solid Waste Policy and Mexico's General Law for Prevention and Integral Management of Waste establish landfill diversion targets that directly mandate automated sorting investments. ANVISA in Brazil and COFEPRIS in Mexico regulate occupational exposure limits at waste handling sites, pushing facility operators toward robotic substitution in hazardous material lines. Stakeholders must monitor how LAMEA central banks calibrate infrastructure lending rates against equipment import duties, as this balance determines payback periods for robotic capital deployments.
Market Dynamics
AI-driven vision systems are compressing payback periods for robotic sorting investments across Brazilian and Mexican recycling complexes, redirecting capital flows from sensor-based legacy equipment toward machine-learning configurations that reduce contamination rates in post-consumer plastic streams.
Growth Catalysts
- Brazil's National Solid Waste Policy:Landfill diversion mandates require municipalities to deploy automated sorting infrastructure, creating binding procurement schedules for robotic extraction systems in São Paulo and Rio de Janeiro waste complexes.
- Food-grade PET recovery:AI vision pipelines now identify resin grades at conveyor speeds exceeding sixty picks per minute, unlocking premium pricing for high-purity recyclables that manual sorting cannot achieve.
- ANVISA occupational exposure regulations:Hazardous material handling limits at Brazilian waste sites accelerate robotic substitution in medical waste and chemical container lines where human exposure risks previously constrained throughput.
Market Restraints
- Import duty volatility:Brazilian and Mexican central bank rate calibrations against equipment import tariffs create unpredictable total cost of ownership for European and Asian robot suppliers.
- Technical integration barriers:Retrofitting pneumatic grippers and vision arrays onto existing conveyor infrastructure requires facility-specific engineering that extends deployment timelines.
- CE marking friction:European-origin equipment faces competitive access barriers in LAMEA markets as local certification requirements diverge from EU Machinery Directive standards.
Strategic Opportunities
- Mid-tier facility automation:Mexican recycling operators outside Mexico City and Monterrey remain underpenetrated, presenting white space for vision-system configurations that require minimal dedicated technical staff.
- AI-sensor convergence:Integration of hyperspectral imaging with deep-learning classification enables simultaneous material and contamination detection, opening premium service contracts with beverage brand owners seeking closed-loop recycling verification.
- Municipal leasing structures:Equipment-as-a-service models are emerging in Brazilian states where municipal budget constraints block outright capital purchases of robotic sorting lines.
Industry Challenges
- Mechatronics talent scarcity:Maintenance of articulated arm systems and pneumatic subsystems requires technicians with cross-functional skills that recycling facilities struggle to recruit and retain.
- Legacy conveyor incompatibility:Older Brazilian sorting plants built for manual picking stations face structural constraints on robot reach envelopes and vision array mounting positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Waste Sorting Robots Market |
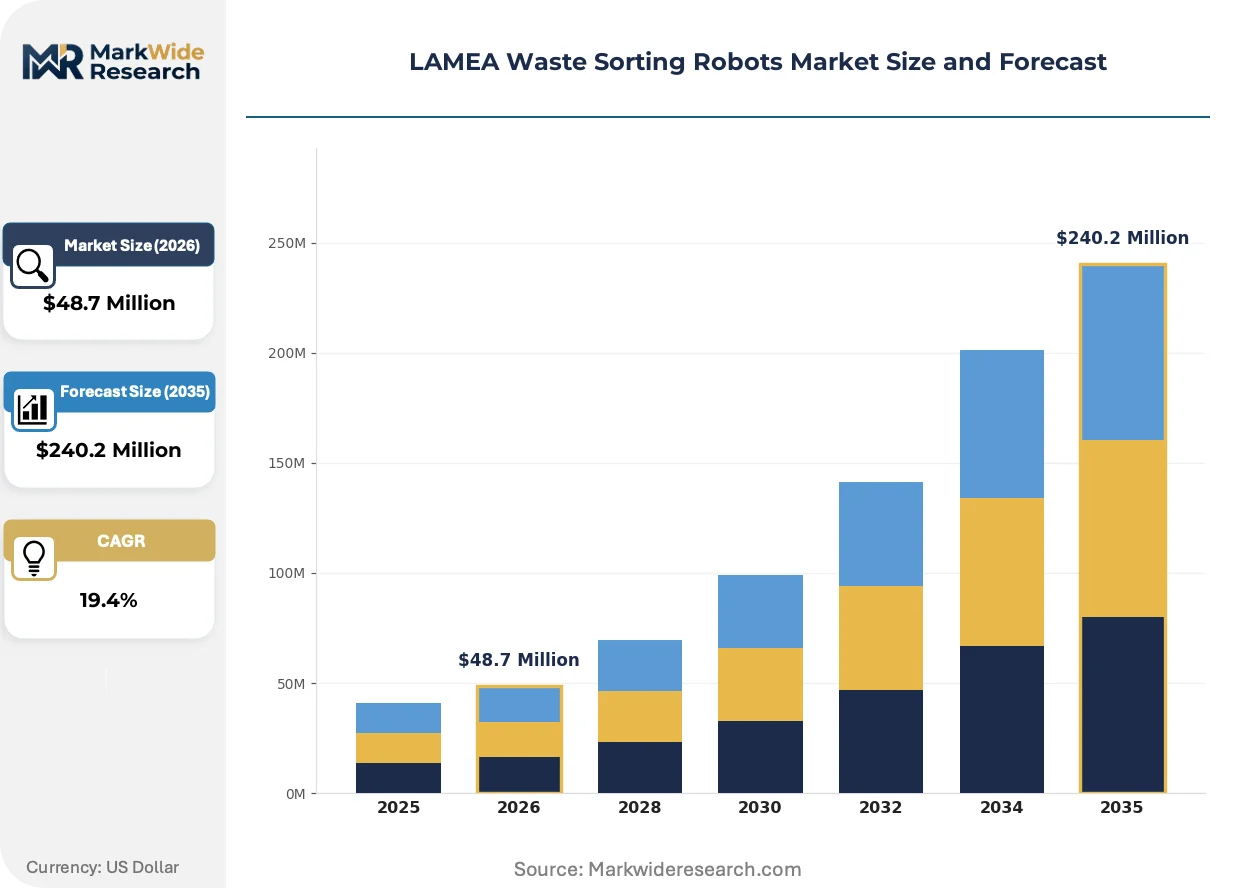
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $240.2 Million |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Robots, Stationary Robots, Hybrid Robots, Autonomous Vehicles Technology: AI-Based, Vision Systems, LIDAR, Sensor Technologies End User: Municipalities, Recycling Facilities, Industrial Plants, Commercial Establishments Installation: On-site, Off-site, Turnkey Solutions, Modular Systems |
| Companies Covered | TOMRA Sorting GmbH, Bollegraaf Recycling Solutions, Machinex Industries Inc., ZenRobotics, AMP Robotics, Bulk Handling Systems, Sadako Technologies, Waste Robotics, ecoBali, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Waste Sorting Robots Market Trends and Innovations
Machine-learning classification architectures are displacing rule-based sensor configurations across LAMEA recycling infrastructure. This shift compresses equipment replacement cycles and reconfigures supplier competitive positioning around software update velocity rather than hardware durability.
Hyperspectral imaging coupled with convolutional neural networks is displacing near-infrared and X-ray fluorescence systems as the primary detection modality for mixed-plastic streams. Brazilian operators in São Paulo's ABC Paulista industrial corridor are adopting these configurations at the fastest clip, driven by export contract requirements for food-grade PET purity verification. The structural consequence is a supplier landscape where vision software providers capture margin previously retained by mechanical subsystem manufacturers.
Mexico's General Law for Prevention and Integral Management of Waste establishes extended producer responsibility frameworks that obligate packaging manufacturers to fund municipal sorting infrastructure. This policy mechanism redirects investment flows from landfill construction toward robotic extraction systems in Mexico City and Guadalajara metropolitan zones. The affected segment is mid-scale municipal facilities, which are consolidating procurement through state-level purchasing cooperatives to achieve volume pricing on AI-enabled sorting lines.
Leasing and performance-based service contracts are displacing outright equipment purchases among Brazilian municipal operators facing fiscal constraints from inflation-indexed debt service obligations. The channel being disrupted is traditional distributor networks that historically financed sales through extended payment terms. This behavioral shift is most visible in São Paulo state's interior municipalities, where consignment arrangements tying payments to tonnage sorted are gaining traction against capital-intensive ownership models.
LAMEA Waste Sorting Robots Market Segmentation
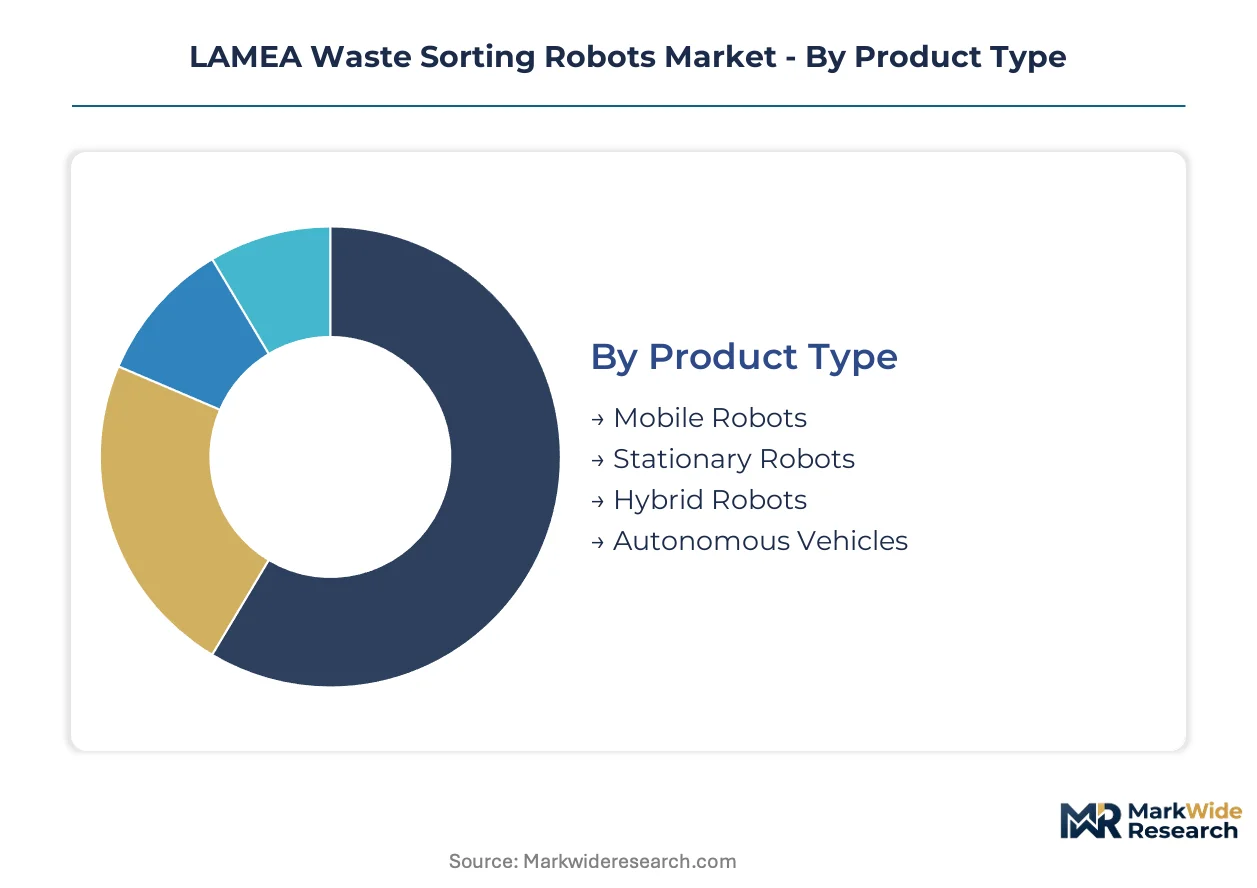
Segmentation in the LAMEA waste sorting robots market reveals how technology choices map to facility maturity and capital constraints across Brazilian and Mexican recycling infrastructure. Each dimension exposes distinct procurement patterns between established metropolitan complexes and emerging regional operators.
Product Type:
Stationary robots dominate Brazilian municipal deployments due to retrofit compatibility with existing conveyor lines, while mobile configurations concentrate in Mexican industrial zones seeking flexible feedstock handling.
- Mobile Robots:Articulated units mounted on rail or wheeled platforms navigate variable facility layouts to intercept mixed waste streams before primary sorting. Mexican recycling operators outside Monterrey favor these for seasonal agricultural plastic campaigns where line configurations shift quarterly.
- Stationary Robots:Fixed-base electromechanical systems with pneumatic grippers and overhead vision arrays process single-stream recyclables at throughputs exceeding sixty picks per minute. São Paulo's ABC Paulista corridor hosts the densest concentration, driven by ANVISA occupational exposure limits that mandate robotic substitution in high-volume lines.
- Hybrid Robots:Configurations combining stationary precision with limited mobility for line repositioning during maintenance windows.
- Autonomous Vehicles:Self-guided transport units for bulk material movement between sorting stages and bale storage.
Stationary robots hold the largest share; momentum sits with hybrid configurations as Brazilian operators seek flexibility without full mobile complexity.
Technology:
Cost tier differentiation separates premium AI-enabled systems from mid-tier vision configurations, with sensor-based legacy equipment occupying budget-constrained municipal segments.
- AI-Based:Deep-learning classification pipelines process hyperspectral imaging data to identify resin grades and contamination levels in real-time. Brazilian operators in Rio de Janeiro's waste complexes deploy these for food-grade PET recovery contracts tied to beverage brand closed-loop verification.
- Vision Systems:Rule-based camera arrays with color and shape recognition algorithms handle high-volume single-stream sorting at lower capital intensity. Mid-tier Mexican facilities in Guadalajara's metropolitan zone standardize on these due to limited technical staffing for machine-learning maintenance.
- LIDAR:Laser-based spatial mapping for robot arm trajectory optimization in cluttered waste environments.
- Sensor Technologies:Near-infrared and X-ray fluorescence configurations for material composition detection in legacy installations.
Vision systems capture the broadest installed base; AI-based segments are expanding most quickly as payback periods compress below thirty-six months.
End User:
Application urgency varies sharply between hazardous material mandates and commercial efficiency targets, with municipalities facing the most binding procurement schedules.
- Municipalities:Public waste management authorities in São Paulo and Rio de Janeiro operate under Brazil's National Solid Waste Policy landfill diversion mandates that specify automated sorting infrastructure deployment timelines. These entities consolidate procurement through state-level purchasing cooperatives to offset budget constraints from inflation-indexed debt service.
- Recycling Facilities:Private operators processing post-consumer plastics for export markets concentrate AI-enabled lines in coastal Brazilian complexes serving European food-grade PET buyers.
- Industrial Plants:Manufacturing-integrated recycling for captive material recovery.
- Commercial Establishments:Retail and hospitality sector on-site sorting for compliance with extended producer responsibility frameworks.
Municipalities account for the dominant procurement volume; recycling facilities are gaining share fastest as export contract purity requirements tighten.
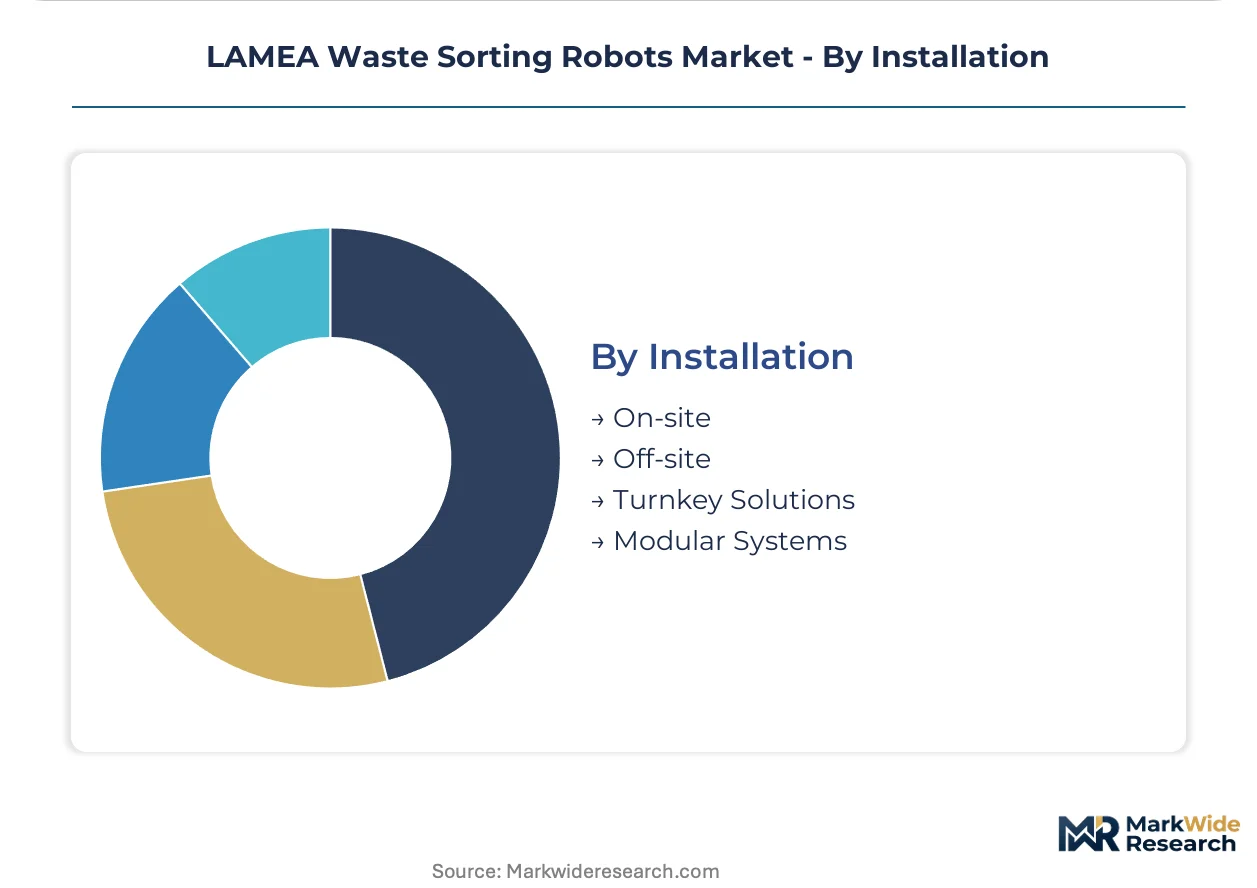
Installation:
Supply concentration among integrated plant engineers versus specialized component vendors determines deployment risk profiles for facility operators with varying technical capabilities.
- On-site:Direct installation at existing waste processing facilities with integration into operational conveyor infrastructure.
- Off-site:Pre-commissioned sorting modules delivered as operational units requiring minimal site preparation.
- Turnkey Solutions:Comprehensive engineering packages spanning feed systems, robotic extraction, and bale handling delivered by European-origin suppliers with CE marking heritage.
- Modular Systems:Standardized subunits permitting phased capacity expansion that aligns with Brazilian municipal budget cycles and leasing structures.
Turnkey solutions command premium positioning; modular systems are climbing the fastest as equipment-as-a-service models penetrate São Paulo state's interior municipalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement authorities and private recycling operators across Latin America, the Middle East, and Africa drive equipment demand. Brazil and Mexico dominate capital deployment. Smaller markets in the Gulf States and North Africa are emerging as automation targets.
Brazil
São Paulo and Rio de Janeiro municipal waste complexes anchor regional demand. ANVISA occupational exposure regulations mandate robotic substitution in hazardous material handling lines. The ABC Paulista industrial corridor hosts densest AI-enabled sorting concentration serving food-grade PET export contracts.
Mexico
Mexico City and Guadalajara metropolitan zones lead landfill diversion infrastructure spending. The General Law for Prevention and Integral Management of Waste establishes extended producer responsibility funding streams for municipal automation. State-level purchasing cooperatives in Jalisco consolidate procurement for mid-tier facilities.
United Arab Emirates
Dubai and Abu Dhabi waste management authorities pursue automation for landfill diversion targets ahead of 2030 sustainability commitments. MOHAP regulations on medical waste handling accelerate robotic deployment in healthcare waste streams. Jebel Ali industrial zone clusters sorting infrastructure serving Gulf export markets.
Saudi Arabia
Riyadh and Eastern Province municipalities invest in sorting automation under Vision 2030 circular economy mandates. SFDA oversight of pharmaceutical waste streams drives robotic substitution in controlled substance destruction lines. NEOM development zone pilots next-generation AI sorting configurations.
South Africa
Gauteng and Western Cape provinces lead automated recycling infrastructure deployment. National Waste Management Strategy landfill diversion targets bind municipal procurement schedules. Cape Town's industrial zones concentrate mid-tier facilities adopting vision-system configurations for post-consumer plastic recovery.
LAMEA Waste Sorting Robots Market Competitive Landscape
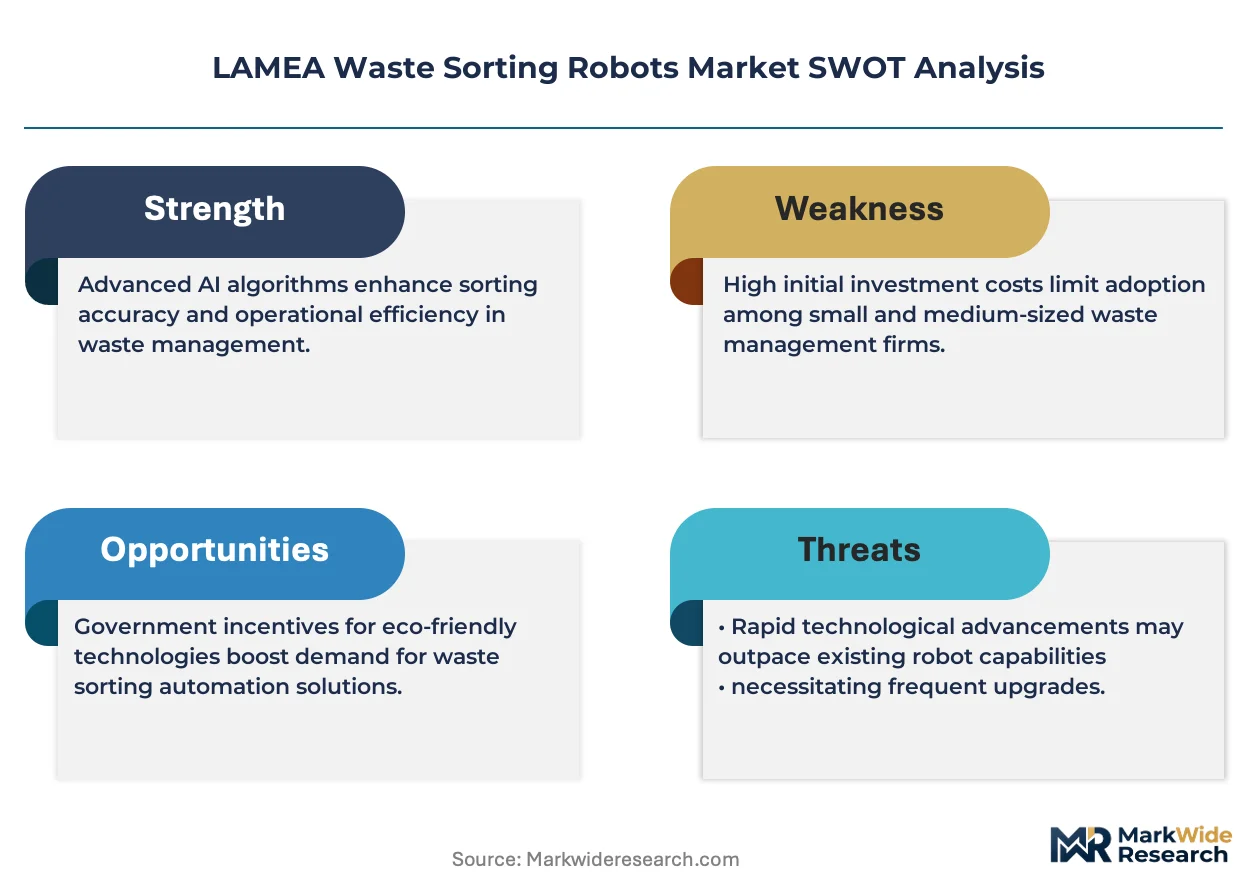
Player mix skews toward European-origin integrated plant engineers and North American AI-vision specialists. Market structure concentrates premium installations among heritage sorting equipment suppliers with CE marking pedigree. Two strategic archetypes dominate: sensor-based legacy vendors defending installed base through retrofit compatibility, and AI-native entrants capturing greenfield municipal contracts through machine-learning differentiation. Competitive moves center on equipment-as-a-service financing structures and hyperspectral imaging partnerships with beverage brand owners.
Within the European-heritage tier, TOMRA Sorting GmbH and Bollegraaf Recycling Solutions exemplify integrated plant engineering archetypes. TOMRA leverages sensor-based sorting heritage to anchor premium Brazilian installations. Bollegraaf competes through turnkey solutions spanning feed systems to robotic extraction. Among AI-native specialists, AMP Robotics occupies a position representing machine-learning classification pipelines that identify food-grade PET streams. These three companies illustrate competitive positioning around software velocity versus hardware durability.
| Leading Market Players |
|---|
| TOMRA Sorting GmbH |
| Bollegraaf Recycling Solutions |
| Machinex Industries Inc. |
| ZenRobotics |
| AMP Robotics |
| Bulk Handling Systems |
| Sadako Technologies |
| Waste Robotics |
| ecoBali |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at European sensor-manufacturing plants creates dual leverage over LAMEA equipment pricing, compressing margin buffers for Brazilian municipal buyers while elevating floor prices for AI-native configurations that draw from constrained semiconductor foundry output.
Pricing Analysis
Cost-plus contracts with steel and rare-earth indexation dominate procurement between European integrated plant engineers and Brazilian state-level purchasing cooperatives. Three-tier pricing structure across premium AI-enabled, standard vision-system, and economy sensor-based levels separates TOMRA's hyperspectral installations from mid-tier Mexican facilities lacking technical staffing. Pricing pressure stems from Brazilian central bank rate volatility against equipment import tariffs, which extends payback period calculations for municipal leasing structures. Municipalities in São Paulo's interior exhibit highest price sensitivity, while coastal export-oriented recycling complexes serving food-grade PET buyers demonstrate lowest sensitivity due to premium pricing on high-purity output.
Supply Chain Analysis
Suez Canal transit disruptions and Red Sea routing alternatives expose LAMEA robotic sorting deployments to logistics chokepoints that inflate landed costs for European-origin equipment. Component sourcing concentrates in Germany for precision pneumatic grippers, Japan for hyperspectral imaging sensors, and China for steel conveyor subsystems. Raw material dependencies span high-grade aluminum for robot arm construction, rare-earth elements for vision array magnetics, and specialized polymers for gripper pads. Single-source vulnerability sits with Japanese hyperspectral sensor suppliers serving Brazilian food-grade PET recovery lines. Distribution runs through São Paulo-based technical integrators who handle ANVISA compliance and on-site commissioning for municipal contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LAMEA waste sorting robotics sits in early-cycle expansion, with Brazil's National Solid Waste Policy landfill diversion mandates creating binding procurement schedules that guarantee equipment demand regardless of macroeconomic softness.
For Market Incumbents: Consolidate retrofit service capabilities around legacy conveyor infrastructure to defend against AI-native entrants capturing greenfield municipal contracts. Acquire Brazilian technical staffing firms to address mechatronics talent scarcity constraining maintenance response times. CE marking heritage remains defensible only if paired with local certification fast-track partnerships that neutralize competitive access barriers for European-origin equipment. For New Entrants and Emerging Players: ANVISA occupational exposure compliance fast-tracks open immediate procurement channels in hazardous material handling lines where incumbents lack specialized configurations. Target mid-tier Mexican facilities in Guadalajara's metropolitan zone through vision-system configurations requiring minimal dedicated technical staff. Pursue equipment-as-a-service financing structures that align with Brazilian municipal budget constraints and inflation-indexed debt service obligations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among AI-vision specialists with software update velocity and hyperspectral imaging partnerships serving beverage brand closed-loop verification contracts. Long-term viability across the projection horizon favors suppliers with backward integration into vision software rather than mechanical subsystem manufacturing. Monitor equipment-as-a-service adoption rates in São Paulo state's interior municipalities as inflection indicator for capital-deployment model disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Financing | Consignment arrangements tying payments to tonnage sorted bypass Brazilian municipal budget constraints. |
| Hyperspectral Imaging Partnership | Deep-learning classification pipelines unlock premium pricing from beverage brand closed-loop verification contracts. |
| Local Certification Fast-Track | ANVISA and COFEPRIS compliance acceleration neutralizes CE marking friction for European-origin suppliers. |
| Retrofit Compatibility Investment | Pneumatic gripper and vision array integration with legacy conveyor infrastructure extends addressable base. |
| Mechatronics Talent Acquisition | Cross-functional technician recruitment addresses maintenance scarcity constraining articulated arm system uptime. |
Research Methodology
Cross-validation between facility operator interviews and customs import data anchors the qualitative findings on equipment deployment patterns. Primary fieldwork encompassed recycling plant managers, municipal procurement officers, pneumatic subsystem engineers, and aftermarket service heads across São Paulo, Rio de Janeiro, Mexico City, and Guadalajara. Secondary sources span ANVISA regulatory filings, COFEPRIS occupational exposure guidelines, Brazilian National Solid Waste Policy implementation schedules, Mexican extended producer responsibility fund disbursement records, and trade data on European-origin equipment imports. Bottom-up installation counts triangulate against top-down market sizing derived from state-level purchasing cooperative budgets.
Sensitivity analysis on central bank rate calibrations and import duty volatility brackets the forecast range without specifying discrete scenarios. Segmentation modeling spans product type mobility configuration, technology tier from sensor-based to AI-enabled, end-user category between municipal and private recycling facilities, and installation approach from turnkey to modular. CAGRs derive from equipment replacement cycle compression as machine-learning classification displaces rule-based configurations. Industry-specific inputs include food-grade PET export contract purity requirements and ANVISA-mandated robotic substitution timelines in hazardous material lines.
Underlying assumptions cover steady landfill diversion policy enforcement, with deviation risk concentrated in Brazilian fiscal constraints affecting municipal capital availability and Mexican extended producer responsibility fund allocation delays. Forecasts reflect these conditions without claiming certainty bounds. Practitioners should keep alternative scenarios live as LAMEA central bank rate decisions and equipment import tariff adjustments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
China Cloud Robotics Market
Robotics and Automation
SCARA Robots Market
Robotics and Automation
AI Assisted Robots Market
Robotics and Automation
Restaurant Delivery Robot Market
Robotics and Automation
Global Robotics Parking System Market
Robotics and Automation
Latin America Cloud Robotics Market
Robotics and Automation
Indonesia Robotics Market
Robotics and Automation
Asia Pacific Industrial Robots Market
Robotics and Automation
Case and Box Handling Robots Market
Robotics and Automation
Cognitive Robotics Market
Robotics and Automation
United Kingdom Cloud Robotics Market
Robotics and Automation
Autonomous Drilling Robots Market
Robotics and Automation
Rotary Gripper Module Market
Robotics and Automation
Middle East and Africa Medical Robots Market
Robotics and Automation
Wearable Robotic Exoskeleton Market
Robotics and Automation
Sweden Robotic Lawn Mower Market