
 Cloud Robotics Market | 2026-2036
Cloud Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Robotics Market Analysis
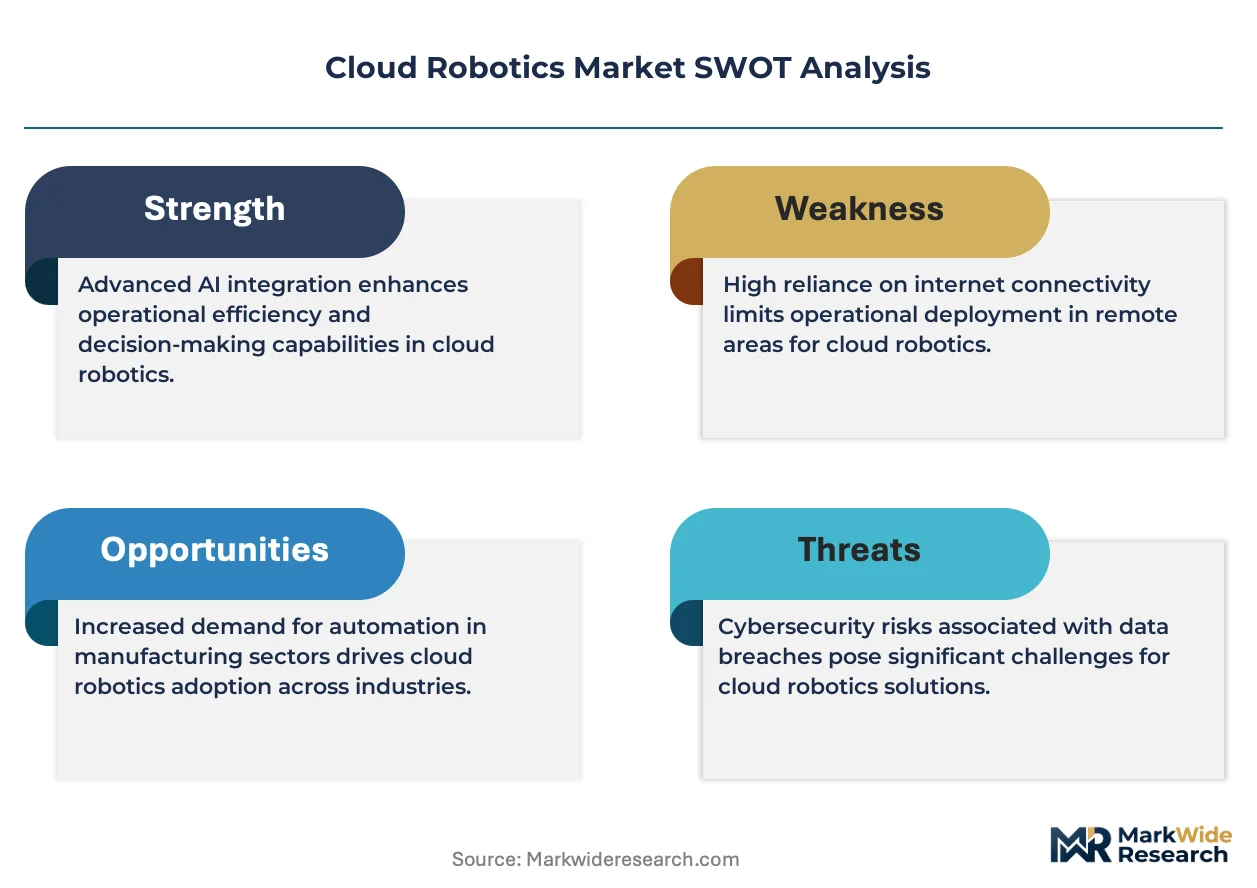
Multi-source cloud infrastructure procurement is hardening among enterprise robotics buyers. Amazon Web Services, Inc. leverages its serverless compute stack to anchor high-throughput robot fleet orchestration. Microsoft Corporation competes through edge-to-cloud synchronization for manufacturing execution systems.
Cloud robotics fuses distributed computing architectures with physical automation endpoints, enabling real-time sensor fusion, path planning, and collective learning across geographically dispersed machine fleets. The architecture depends on sub-50 millisecond latency thresholds between edge nodes and centralized model repositories to sustain closed-loop operational safety. Public cloud deployment captures the dominant share of new installations as hyperscalers subsidize compute onboarding, while edge computing represents the fastest-expanding technology layer as latency-sensitive applications multiply. Manufacturing applications command the deepest margin pools due to uptime guarantees and predictive maintenance contracts.
The EU AI Act imposes conformity assessment obligations on autonomous robotic systems deployed in European industrial zones, while ISO 10218 governs collaborative robot safety interoperability. The US FAA maintains separate certification pathways for aerial robotics operating beyond visual line of sight. Stakeholders must weigh regulatory fragmentation against the standardization push from IEC 62443 for industrial cybersecurity in connected automation architectures.
Market Dynamics
Third-party logistics providers are accelerating warehouse automation deployments, compressing procurement cycles from multi-year pilots to 12-month rollouts as hyperscaler subsidies reduce cloud compute onboarding friction.
Growth Catalysts
- EU AI Act risk classification:The conformity assessment framework for autonomous systems is creating compliant product categories that command premium pricing in European industrial zones.
- Predictive maintenance contracts:Manufacturing uptime guarantees are deepening margin pools as automotive and electronics producers bundle cloud robotics with outcome-based service agreements.
- Serverless compute stacks:Hyperscaler infrastructure subsidies are eliminating capital barriers for mid-sized fleet operators in Germany's industrial manufacturing corridor.
Market Restraints
- Sub-50 millisecond latency thresholds:The technical requirement for closed-loop operational safety forces expensive edge node deployment in remote facilities lacking fiber backhaul.
- Regulatory fragmentation:Divergent certification pathways between the US FAA for aerial robotics and ISO 10218 for collaborative ground systems multiply compliance costs for multi-national vendors.
- Industrial cybersecurity standards:IEC 62443 implementation creates recurring audit burdens that extend sales cycles by 6-9 months in critical infrastructure deployments.
Strategic Opportunities
- Edge-to-cloud synchronization:Manufacturing execution systems integration represents white space as discrete automation vendors lack software-native orchestration capabilities.
- Beyond-visual-line-of-sight aerial robotics:Regulatory clarity from the US FAA is opening commercial inspection and logistics corridors previously restricted to piloted operations.
- Collective learning architectures:Sensor fusion models trained across geographically dispersed fleets create network effects that single-site deployments cannot replicate.
Industry Challenges
- Robotics DevOps talent scarcity:The intersection of embedded systems engineering and cloud-native development remains severely under-supplied across industrial automation hubs.
- Legacy PLC integration complexity:Brownfield manufacturing facilities require costly protocol translation layers to connect proprietary control systems with open cloud robotics stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Robotics Market |
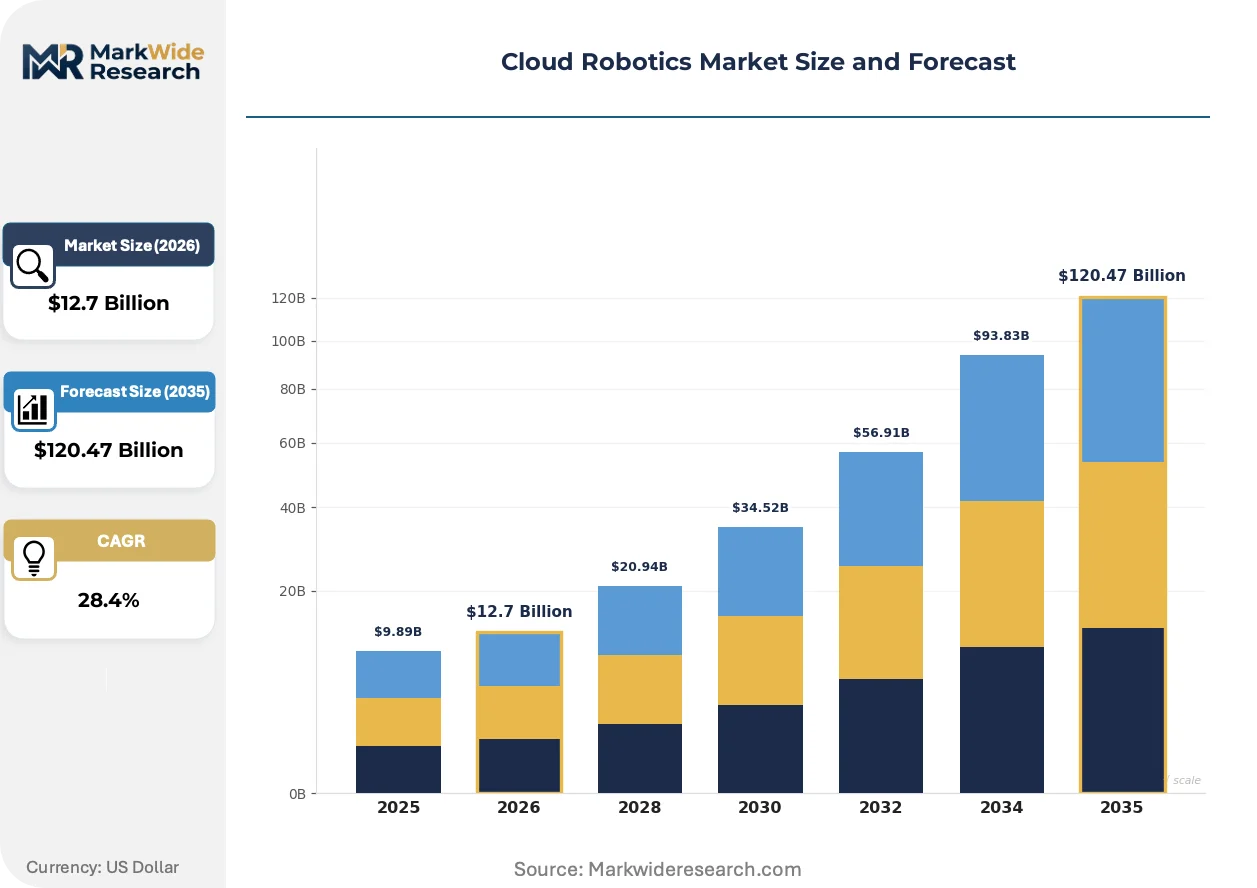
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $120.47 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Technology: Machine Learning, Computer Vision, Natural Language Processing, Edge Computing Application: Manufacturing, Logistics, Healthcare, Agriculture End User: OEMs, Retailers, Service Providers, Enterprises |
| Companies Covered | Amazon Web Services, Inc., Microsoft Corporation, Google LLC, IBM Corporation, ABB, Huawei Technologies Co., Ltd., Rockwell Automation Inc., Rapyuta Robotics, CloudMinds Technologies Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Robotics Market Emerging Trajectories
Real-time sensor fusion architectures are compressing decision loops from seconds to milliseconds, enabling collective learning across machine fleets that transforms isolated automation islands into coordinated operational networks.
Edge computing is decentralizing computational workloads from centralized hyperscaler regions to factory-floor nodes, reducing round-trip latency for path planning algorithms. Automotive tier-one suppliers are deploying these architectures at scale in Stuttgart and Wolfsburg assembly plants. The shift is compressing infrastructure costs for latency-sensitive applications while fragmenting vendor power away from pure-cloud providers.
The EU AI Act's conformity assessment obligations are forcing autonomous robotic systems deployed in European industrial zones to document risk mitigation measures before market entry. Industrial equipment manufacturers are restructuring product development cycles to front-load compliance documentation. German and French automation clusters are responding fastest, with dedicated regulatory affairs functions now embedded in engineering teams.
Buyer concentration among third-party logistics providers is consolidating vendor selection authority into procurement teams with cloud-native expertise. Traditional automation distributors are losing influence as direct hyperscaler partnerships displace channel-mediated sales in high-volume warehouse deployments. This pattern is most visible in the Netherlands and Belgium, where e-commerce fulfillment density has compressed supplier shortlists to three cloud-integrated robotics platforms.
Cloud Robotics Market Segmentation
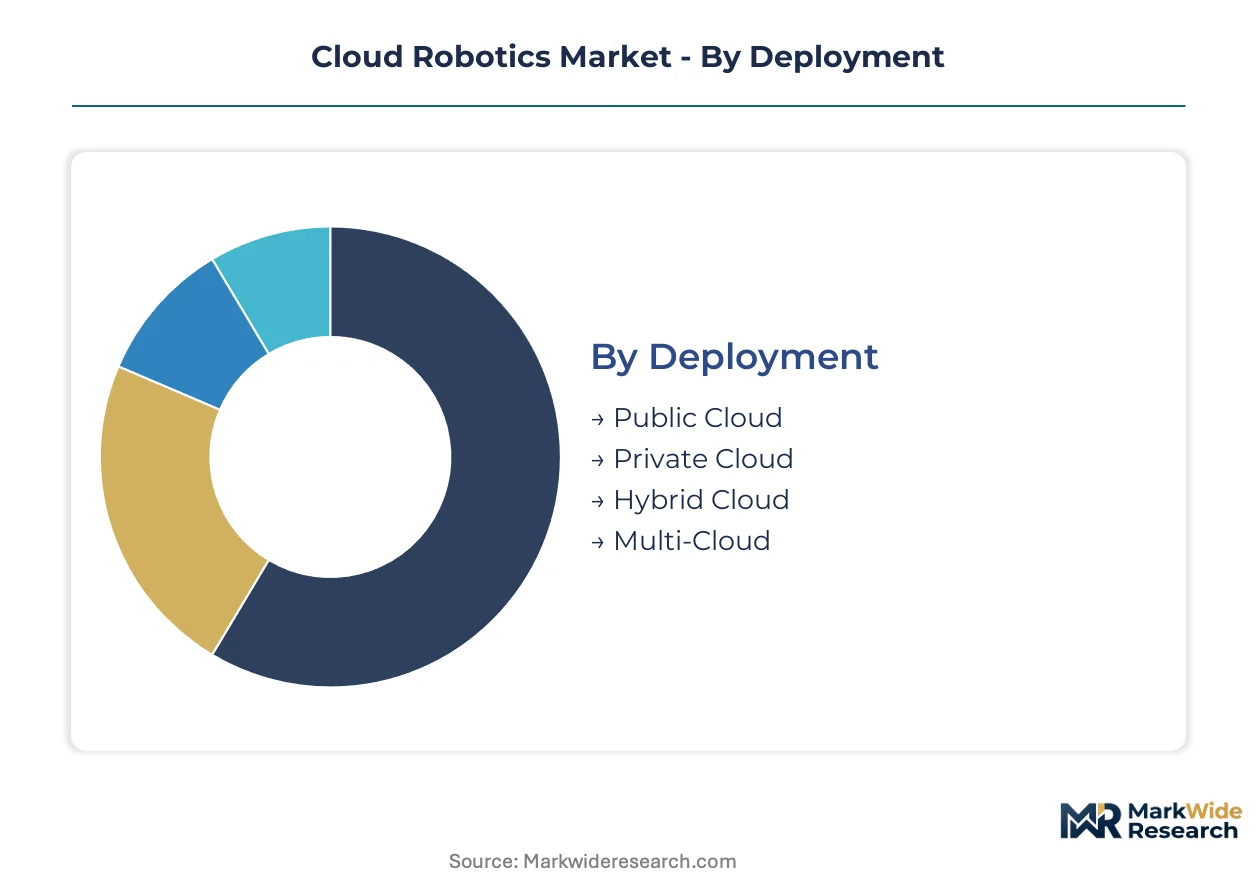
Cloud robotics architectures fragment across deployment models, processing layers, and operational domains. Procurement patterns diverge sharply between latency-sensitive manufacturing floors and batch-oriented logistics hubs. Understanding these fault lines reveals where vendor power concentrates and where integration complexity inflates project costs.
Deployment:
Hyperscaler infrastructure subsidies are concentrating procurement authority among providers with serverless compute stacks.
- Public Cloud:Centralized hyperscaler regions host model training and fleet orchestration for non-latency-critical workloads. German automotive producers dominate uptake, leveraging subsidized onboarding to compress multi-year pilots into 12-month rollouts.
- Private Cloud:On-premises infrastructure isolates sensitive operational data within facility perimeters. Healthcare systems in Stuttgart and Wolfsburg deploy these architectures to satisfy EU AI Act conformity assessment obligations for patient-adjacent automation.
- Hybrid Cloud:Split workloads route real-time control to local nodes while pushing analytics to centralized repositories. Edge-to-cloud synchronization protocols from Microsoft Corporation anchor manufacturing execution system integrations.
- Multi-Cloud:Redundancy architectures distribute risk across AWS, Azure, and Google Cloud regions. Third-party logistics providers in the Netherlands and Belgium adopt these configurations to avoid vendor lock-in during high-volume warehouse expansions.
Public cloud absorbs the bulk of installed capacity; edge computing is expanding most quickly as sub-50 millisecond latency requirements multiply.
Technology:
Processing layer selection directly determines where computational bottlenecks form in distributed robot fleets.
- Machine Learning:Centralized model repositories enable collective learning across geographically dispersed fleets. Path planning algorithms trained on aggregate sensor data create network effects that single-site deployments cannot replicate.
- Computer Vision:Real-time object detection and localization pipelines process camera feeds at the edge. Automotive tier-one suppliers in Wolfsburg deploy these systems for quality inspection on Stuttgart assembly lines.
- Natural Language Processing:Voice-directed human-robot interaction modules simplify operator training in multilingual European industrial zones. German and French automation clusters front-load compliance documentation for EU AI Act risk classifications.
- Edge Computing:Factory-floor nodes decentralize workloads from hyperscaler regions, compressing round-trip latency for safety-critical control loops. Brownfield facilities lacking fiber backhaul face expensive node deployment to satisfy closed-loop operational thresholds.
Machine learning commands the deepest engineering investment; edge computing gains share fastest as latency-sensitive applications multiply.
Application:
End-use domain selection shapes whether contracts bundle outcome-based uptime guarantees or remain transactional equipment sales.
- Manufacturing:Predictive maintenance contracts with automotive and electronics producers deepen margin pools through uptime guarantees. ISO 10218 governs collaborative robot safety interoperability in these deployments.
- Logistics:Warehouse automation by third-party logistics providers compresses procurement cycles as e-commerce fulfillment density rises. The Netherlands and Belgium have consolidated supplier shortlists to three cloud-integrated robotics platforms.
- Healthcare:Patient-adjacent systems face EU AI Act conformity assessment obligations requiring documented risk mitigation measures. German automation vendors embed dedicated regulatory affairs functions within engineering teams.
- Agriculture:Remote field robotics operate beyond reliable fiber infrastructure, forcing expensive satellite or cellular backhaul for cloud connectivity. US FAA certification pathways for beyond-visual-line-of-sight aerial inspection are opening previously restricted commercial corridors.
Manufacturing captures the dominant revenue share; logistics is climbing the fastest as warehouse automation accelerates.
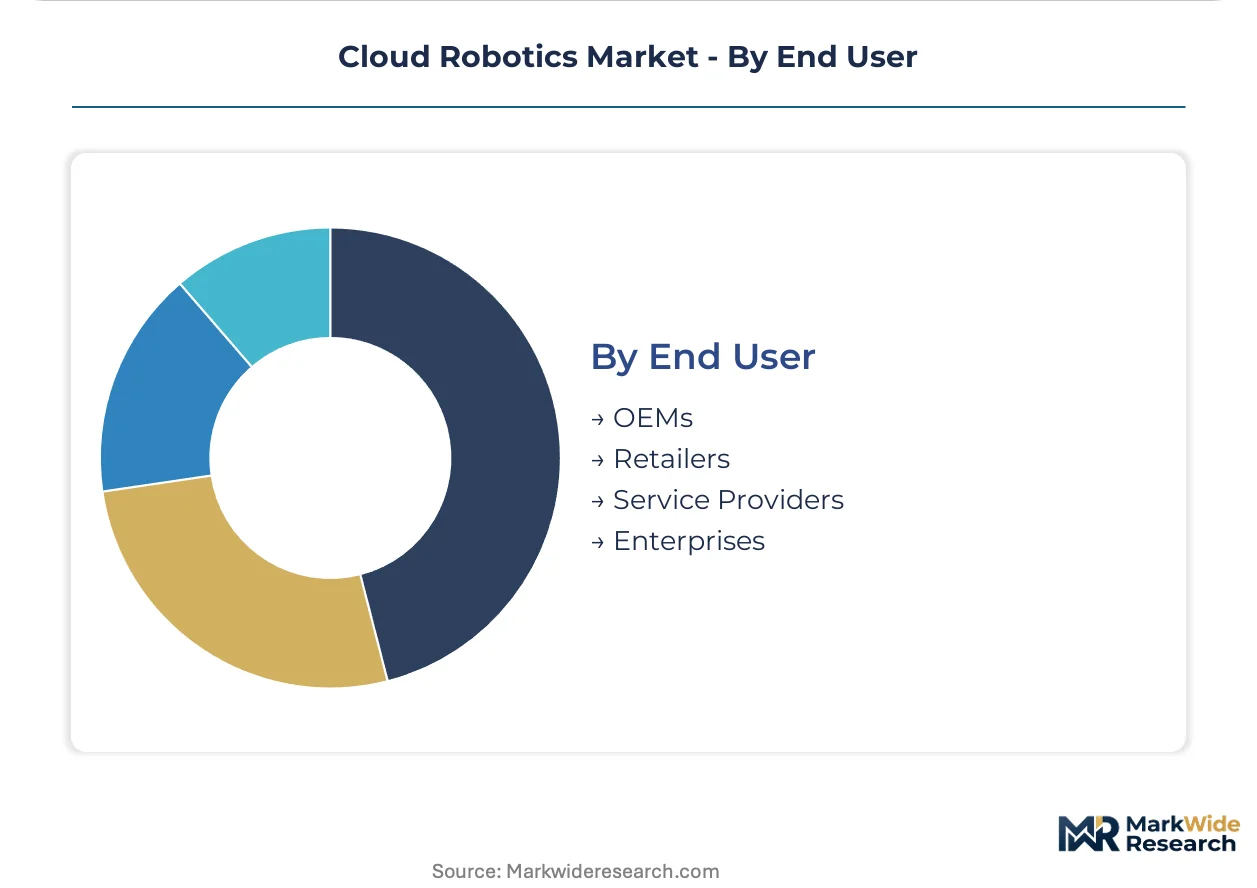
End User:
Buyer sophistication around cloud-native architectures determines whether procurement flows through traditional automation distributors or direct hyperscaler partnerships.
- OEMs:Original equipment manufacturers integrate cloud robotics stacks into product offerings for downstream industrial customers. These vendors must navigate regulatory fragmentation between ISO 10218 for collaborative ground systems and US FAA pathways for aerial robotics.
- Retailers:E-commerce fulfillment operators concentrate vendor selection authority in procurement teams with cloud-native expertise. Direct hyperscaler partnerships displace channel-mediated sales in high-volume deployments.
- Service Providers:Third-party logistics firms and managed automation vendors bundle cloud robotics with outcome-based service agreements. IEC 62443 industrial cybersecurity standards create recurring audit burdens that extend sales cycles.
- Enterprises:Discrete manufacturing and process industry end-users require costly protocol translation layers to connect legacy PLC systems with open cloud robotics stacks. Brownfield integration complexity remains a primary adoption barrier.
Enterprises account for the largest installed base; service providers are expanding most quickly as outsourcing of fleet management accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler data center clusters in Frankfurt anchor European cloud robotics infrastructure. Germany's industrial manufacturing corridor generates concentrated demand for latency-sensitive automation systems.
United States
Beyond-visual-line-of-sight aerial robotics and warehouse automation drive procurement intensity. The FAA maintains separate certification pathways for commercial drone operations. Seattle and San Francisco Bay Area hyperscaler regions host model training clusters for distributed robot fleets.
Germany
Automotive predictive maintenance contracts and EU AI Act compliance obligations shape vendor selection. The KBA and EU AI Act impose conformity assessments on autonomous systems. Stuttgart and Wolfsburg assembly plants deploy edge computing nodes for sub-50 millisecond control loops.
China
Manufacturing execution system integration and smart factory initiatives accelerate cloud-native robotics uptake. MIIT and GB standards govern industrial automation interoperability. Shenzhen and Shanghai automation clusters concentrate domestic robot fleet orchestration demand.
Japan
Collaborative robot safety interoperability and aging workforce automation sustain market expansion. METI and JIS standards regulate industrial robotics deployment. Nagoya automotive suppliers integrate edge-to-cloud synchronization for quality inspection pipelines.
Netherlands
E-commerce fulfillment density compresses procurement cycles among third-party logistics providers. The EU AI Act risk classification framework applies to automated warehouse systems. Rotterdam and Amsterdam distribution hubs consolidate supplier shortlists to cloud-integrated robotics platforms.
Cloud Robotics Market Vendor Landscape
Strategic partnerships dominate the current landscape as hyperscalers anchor cloud infrastructure subsidies and discrete automation vendors seek software-native orchestration capabilities. The vendor base stratifies across three tiers: hyperscaler platforms with serverless compute stacks, industrial automation incumbents with legacy PLC integration expertise, and emerging specialists in edge-to-cloud synchronization. Competitive intensity concentrates on M&A activity targeting collective learning architectures and geographic expansion into Germany's industrial corridor.
Among hyperscaler platforms, Amazon Web Services, Inc. and Microsoft Corporation exemplify the infrastructure subsidy archetype, while ABB represents industrial automation incumbents navigating brownfield integration complexity. These anchors occupy positions across the serverless compute and edge orchestration vectors without exclusive segment lock-in.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| Google LLC |
| IBM Corporation |
| ABB |
| Huawei Technologies Co., Ltd. |
| Rockwell Automation Inc. |
| Rapyuta Robotics |
| CloudMinds Technologies Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Backward integration into edge computing hardware anchors supply positions for cloud robotics vendors while compressing margin structures for pure-software orchestration providers. Hyperscaler infrastructure subsidies have shifted pricing power toward AWS and Microsoft, forcing discrete automation vendors to absorb integration costs or surrender margin to retain manufacturing accounts in Germany's automotive corridor.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium-tier cloud robotics contracts from transactional equipment sales. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10218 certification grades and EU AI Act conformity documentation depth. Cost compression in mid-tier manufacturing deployments intensifies as hyperscaler subsidies eliminate capital barriers for German automotive producers. Third-party logistics providers in the Netherlands and Belgium exhibit highest price sensitivity due to compressed procurement cycles, while healthcare systems in Stuttgart accept premium pricing for private-cloud isolation of patient-adjacent systems.
Supply Chain Analysis
Robotics DevOps talent scarcity in Germany, Japan, and the United States constrains deployment velocity for complex edge-to-cloud synchronization projects. Component sourcing draws from Taiwan for GPU accelerators, China for sensor modules, and South Korea for memory subsystems. Single-source vulnerability in specialized edge node manufacturing amplifies lead time risk for brownfield facilities lacking fiber backhaul. Distribution runs through direct hyperscaler partnerships that displace traditional automation distributors in high-volume warehouse deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into serverless compute infrastructure represents the decisive competitive race, with control over edge node manufacturing determining margin capture in latency-sensitive automotive and electronics deployments.
For Market Incumbents: Extend predictive maintenance contract coverage to capture outcome-based revenue streams before emerging specialists consolidate collective learning architectures. Fortify ISO 10218 and EU AI Act certification depth to defend against hyperscaler encroachment in German manufacturing accounts. Anchor edge computing hardware production in Stuttgart and Wolfsburg to secure sub-50 millisecond latency guarantees.
For New Entrants and Emerging Players: Enter via manufacturing execution system integration white space where discrete automation vendors lack software-native orchestration capabilities. Target brownfield facilities in Germany's industrial corridor requiring protocol translation layers for legacy PLC integration. Pursue direct partnerships with Microsoft Azure or AWS to bypass channel-mediated sales friction.
For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler acquisition of edge-to-cloud synchronization specialists with proven manufacturing execution system deployments. Long-term viability hinges on captive control over latency-critical hardware rather than pure-software orchestration stacks. Monitor FAA regulatory clarity on beyond-visual-line-of-sight aerial robotics as inflection signal for logistics corridor commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Node Manufacturing Scale-Up | Captive production of sub-50 millisecond latency hardware secures automotive tier-one supplier contracts in Wolfsburg. |
| EU AI Act Compliance Documentation | Front-loaded conformity assessment obligations create premium pricing tiers in German and French automation clusters. |
| Collective Learning Architecture Acquisition | Sensor fusion models trained across dispersed fleets generate network effects unattainable through single-site deployments. |
| Manufacturing Execution System Partnership | Microsoft Azure edge-to-cloud synchronization anchors brownfield integration for Stuttgart assembly plant deployments. |
| Beyond-Visual-Line-of-Sight Certification | FAA pathway completion opens commercial inspection corridors previously restricted to piloted aerial operations. |
Methodological Framework
Document review covered hyperscaler capex disclosures, EU AI Act implementation guidance, and ISO 10218 technical specifications, complemented by interviews with fleet operations directors at third-party logistics providers, automation procurement leads at German automotive OEMs, regulatory affairs specialists in French industrial clusters, and edge computing architects at cloud infrastructure vendors. Secondary validation drew from IEC 62443 cybersecurity standards documentation, FAA certification pathway records, and industrial automation trade data. Bottom-up deployment estimates triangulated against top-down infrastructure investment projections.
Historical hyperscaler subsidy patterns cross-referenced against panel input from procurement officers at Netherlands distribution hubs anchored the analytical framework across the analysis window. Segmentation dimensions modeled encompass deployment architecture, processing layer technology, operational application domain, and buyer sophistication tier. CAGRs derived from unit economics of serverless compute onboarding and predictive maintenance contract attach rates. Edge node deployment density and fiber backhaul availability served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU AI Act enforcement escalation or FAA certification pathway delays. Projections reflect assumptions regarding hyperscaler infrastructure subsidy continuity and German automotive capital expenditure stability. Material deviation in regulatory implementation timelines or edge computing hardware cost curves warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Adaptive Robot Market
Robotics and Automation
Surgical Robots Market
Robotics and Automation
Logistics Robotics Market
Robotics and Automation
Cleaning Robot Market
Robotics and Automation
Asia-Pacific Cloud Robotics Market
Robotics and Automation
Malaysia Robotics Market
Robotics and Automation
Cybersecurity in Robotics Market
Robotics and Automation
Underwater Exploration Robots Market
Robotics and Automation
Servo Gripper Market
Robotics and Automation
Medical Automation Technologies Market
Robotics and Automation
Europe AUV Market
Robotics and Automation
Robotic Process Automation in Legal Services Market
Robotics and Automation
Europe Service Robotics Market
Robotics and Automation
Wearable Robotic Exoskeleton Market
Robotics and Automation
Singapore Cloud Robotics Market
Robotics and Automation
Robotics Technology Market