
 Automated Plate Handlers Market | 2026-2036
Automated Plate Handlers Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Plate Handlers Market Outlook
A shortage of certified automation engineers is unwinding capacity expansion timelines across the automated plate handler supply base. Tecan Group Ltd leverages its Swiss manufacturing heritage to sustain premium positioning in liquid-handling integration. Hudson Robotics competes through specialized modular architectures that reduce deployment complexity for mid-size laboratories. PerkinElmer anchors North American service infrastructure with field-engineer density that rivals direct competitors.
Automated plate handlers electromechanically transport microplates between workstations at throughputs exceeding 400 plates per hour with positional accuracy below 0.1 millimeter, serving primarily pharmaceutical screening and genomic-sample-preparation pipelines. Robotic handlers dominate installed-base value owing to their flexibility across assay formats, while vision-based systems capture expanding share as laboratories prioritize error reduction in complex multi-step protocols. Conveyor systems occupy mature-margin territory where aftermarket service contracts generate recurring revenue streams.
FDA 21 CFR Part 11 and EU MDR frameworks compel vendors to embed audit-trail functionality and electronic-signature compatibility as standard features rather than premium options. ISO 13485 quality-system certification has become a de facto gate for supplier qualification at tier-one diagnostic manufacturers. Stakeholders must weigh regulatory-validation burden against speed-to-market advantage when selecting between established platforms and emerging AI-powered motion-control architectures.
Market Dynamics
Pharmaceutical laboratories are compressing assay timelines through high-throughput screening consolidation, forcing automation vendors to embed traceability and interoperability as baseline requirements rather than premium features.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature and audit-trail mandates in the US are accelerating replacement cycles for legacy plate-handling equipment that lacks compliant data architecture.
- Genomic-sample-preparation pipelines:CRISPR-based screening workflows are expanding plate throughput requirements beyond manual handling capacity in academic and commercial biobanks.
- German automation engineering cluster:Concentrated talent around Siemens Healthineers in Erlangen is shortening development cycles for next-generation motion-control systems.
Market Restraints
- Certified automation engineer scarcity:Workforce shortages in Switzerland and Germany are extending deployment timelines by 4-8 months for complex multi-module installations.
- Pneumatic subsystem cost volatility:Precision linear actuator and vacuum generator prices fluctuate with rare-earth magnet supply disruptions from Chinese processing facilities.
- EU MDR validation burden:Extended conformity assessment timelines for diagnostic-integrated handlers are delaying commercial launches by 12-18 months.
Strategic Opportunities
- Indian CDSCO pathway acceleration:Streamlined medical device registration for Class B automation equipment is opening access to contract research organization expansion in Hyderabad and Bengaluru.
- AI-powered motion-control convergence:Machine-vision-guided adaptive positioning is reducing calibration downtime in multi-format screening environments.
- Service contract unbundling:Modular aftermarket packages for predictive maintenance are capturing margin from laboratories with in-house engineering capabilities.
Industry Challenges
- ISO 13485 certification timelines:Tier-one diagnostic manufacturers are disqualifying suppliers lacking active quality-system certification, compressing vendor qualification windows.
- Legacy LIMS integration complexity:Proprietary communication protocols in established laboratory information management systems are forcing custom middleware development for new automation deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Plate Handlers Market |
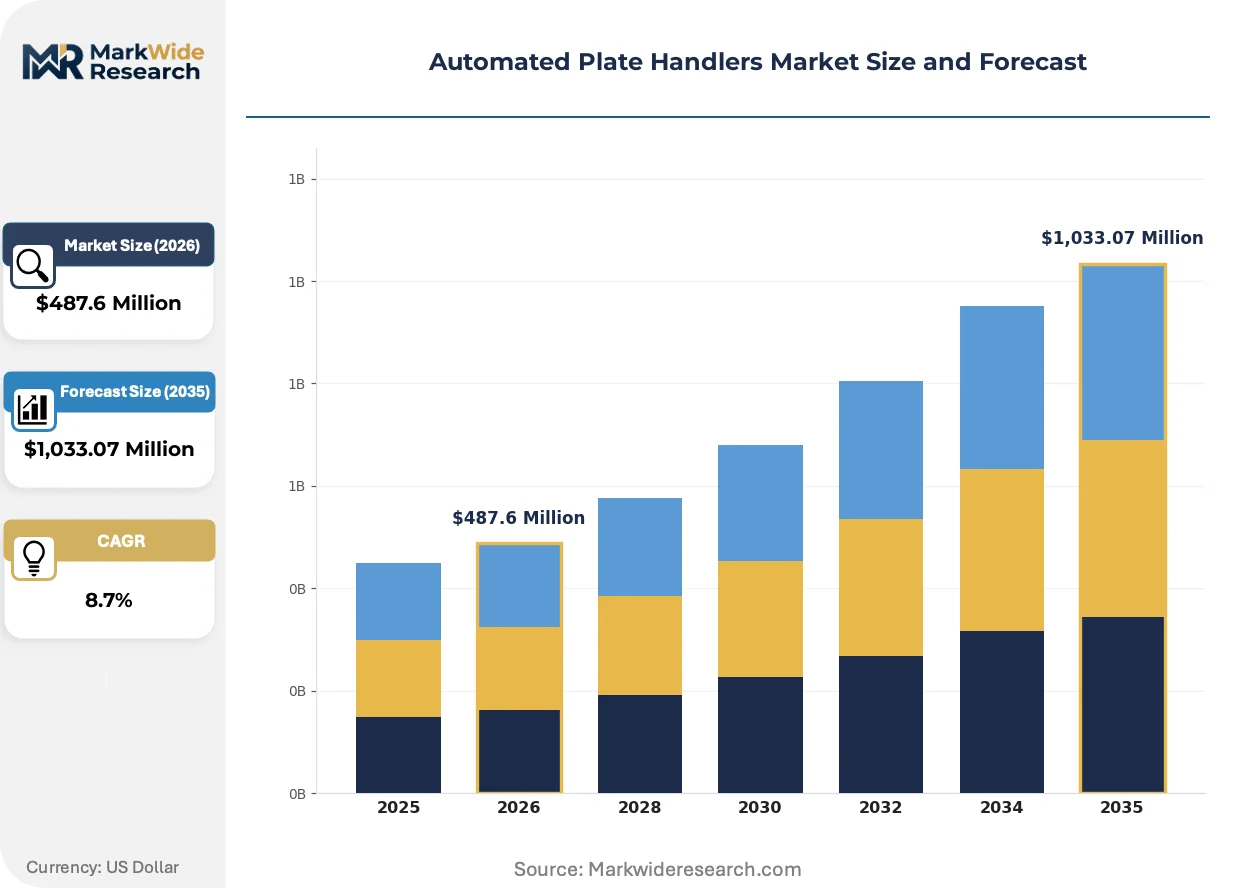
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Handlers, Conveyor Systems, Automated Storage, Pick and Place Systems End User: Manufacturers, Warehouses, Distribution Centers, Automotive Industry Technology: Vision-Based Systems, AI-Powered Solutions, Sensor Integration, Motion Control Application: Material Handling, Assembly Lines, Packaging Automation, Production Systems |
| Companies Covered | Siemens Healthineers AG, Becton Dickinson, Tecan Group Ltd, PerkinElmer, Agilent Technologies, Hudson Robotics, Eppendorf AG, Molecular Devices LLC, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Plate Handlers Market Strategic Shifts
Vision-based plate identification systems are displacing barcode-only tracking architectures as error tolerance tightens in multi-step therapeutic screening protocols. Three concurrent developments are restructuring competitive requirements.
Machine-vision subsystems with sub-millimeter fiducial recognition are decomposing the traditional mechanical-alignment hardware stack in mid-throughput installations. Biotech startups in Boston and Basel are specifying vision-guided handlers for 384-well format flexibility without mechanical retooling. This capability compression is eroding the service-revenue base tied to mechanical calibration visits.
EU MDR Article 10 technical documentation requirements are mandating design-dossier traceability for plate handlers integrated into IVD workflows. Manufacturers must now maintain post-market surveillance systems equivalent to diagnostic-device obligations. German and Swiss vendors are absorbing compliance costs into platform pricing, while emerging competitors delay EU market entry.
Consolidated procurement through group purchasing organizations is compressing vendor negotiation cycles and standardizing specification templates across multi-site pharmaceutical networks. Equipment selection committees now prioritize interoperability certifications over proprietary ecosystem lock-in. This pattern is most pronounced in US East Coast biopharma clusters where site standardization reduces training overhead.
Automated Plate Handlers Market Segmentation
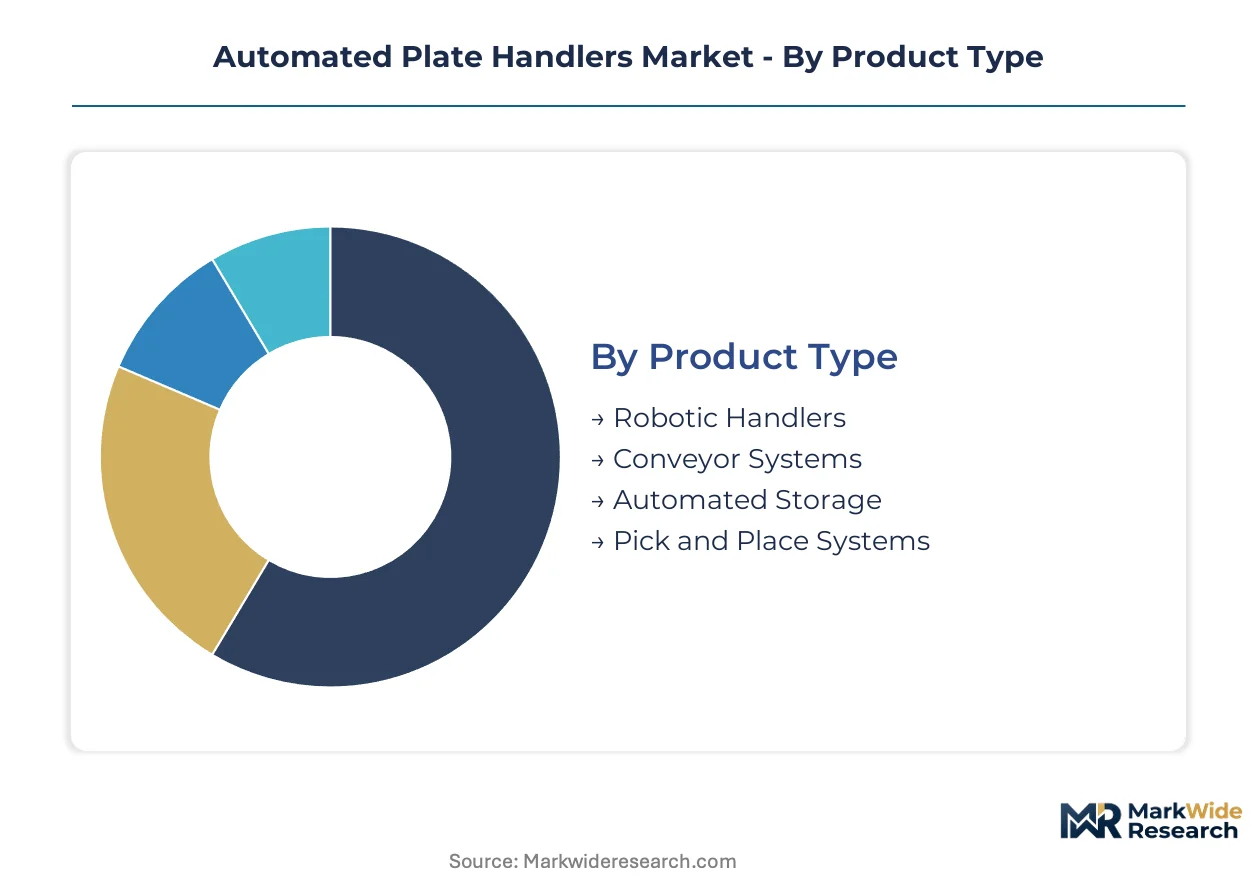
Segmentation in automated plate handlers reveals where substitution pressure from alternative automation architectures reshapes vendor investment priorities. Laboratories and production facilities select handler categories based on throughput requirements, integration complexity, and regulatory validation burden rather than hardware specifications alone.
Product Type:
Robotic handlers face intensifying substitution pressure from vision-guided modular systems that reduce mechanical complexity in mid-throughput environments.
- Robotic Handlers:Electromechanical arms with multi-axis positioning deliver sub-millimeter accuracy across 96-well to 1536-well formats. Demand concentrates in German pharmaceutical screening facilities where Siemens Healthineers integration requirements favor proven kinematic platforms. FDA 21 CFR Part 11 audit-trail mandates accelerate replacement of legacy units lacking electronic signature architecture.
- Conveyor Systems:Continuous belt mechanisms transport microplates between fixed stations at sustained throughputs exceeding 400 plates per hour. Mature-margin installations in US East Coast biopharma clusters generate recurring revenue through aftermarket service contracts rather than initial equipment sales.
- Automated Storage:Vertical carousel and rack-based retrieval systems manage plate inventory with barcode or vision-based tracking. Biobanks in Basel and Boston specify these for CRISPR sample preparation workflows requiring temperature-controlled archiving.
- Pick and Place Systems:Cartesian coordinate robots execute simple transfer operations between adjacent workstations. Contract research organizations in Hyderabad favor these for cost-sensitive genomic pipeline expansion under streamlined CDSCO registration pathways.
Robotic handlers retain volume leadership; vision-integrated pick and place systems hold the steepest expansion curve.
End User:
Cost tier stratification separates validated pharmaceutical deployments from price-sensitive warehouse automation where specification flexibility dominates procurement.
- Manufacturers:Diagnostic device producers require ISO 13485-certified handlers with design-dossier traceability for IVD-integrated workflows. EU MDR Article 10 technical documentation obligations extend validation timelines, compressing supplier qualification windows for tier-one vendors.
- Warehouses:High-volume distribution facilities prioritize throughput over positional precision, accepting mechanical alignment systems that pharmaceutical laboratories reject. These installations favor conveyor architectures with standardized maintenance protocols.
- Distribution Centers:Regional logistics hubs deploy modular handler configurations that scale with seasonal demand fluctuations. Procurement committees emphasize interoperability certifications over proprietary ecosystem lock-in.
- Automotive Industry:Precision component manufacturers adapt plate handler architectures for non-biological material transport, driving cross-industry technology transfer into life-science automation.
Manufacturers command premium pricing tiers; distribution centers are climbing fastest in unit volume.
Technology:
Application maturity divides established motion-control architectures from emerging AI-powered positioning systems still navigating regulatory acceptance.
- Vision-Based Systems:Machine-vision subsystems with sub-millimeter fiducial recognition eliminate mechanical retooling for format changes. Biotech startups in Boston and Basel specify these for 384-well flexibility, eroding service revenue tied to calibration visits.
- AI-Powered Solutions:Adaptive motion control using machine learning reduces calibration downtime in multi-format screening environments. EU MDR validation burden delays commercial launches by 12-18 months as manufacturers establish post-market surveillance equivalence to diagnostic devices.
- Sensor Integration:Multi-modal feedback combining force, proximity, and optical sensing enables collision avoidance in densely configured workstations. German automation engineering clusters around Erlangen shorten development cycles for these integrated platforms.
- Motion Control:Proprietary servo and stepper motor architectures dominate installed-base value through proven reliability in 24/7 production environments. Pneumatic subsystem cost volatility from rare-earth magnet supply disruptions pressures margin structures.
Motion control retains installed-base dominance; AI-powered solutions face the steepest regulatory climb.
Application:
Customer type concentration separates high-complexity pharmaceutical screening from standardized packaging automation where specification templates compress vendor negotiation cycles.
- Material Handling:Core plate transport between workstations represents the foundational use case across all handler architectures. Demand concentrates in high-throughput screening consolidation where traceability and interoperability function as baseline requirements.
- Assembly Lines:Sequential handler integration with liquid-handling and detection modules enables walk-away automation of multi-step therapeutic protocols. Swiss and German vendors absorb EU MDR compliance costs into platform pricing.
- Packaging Automation:End-of-line plate sealing and labeling integration serves mature-margin territory where group purchasing organization consolidation standardizes specifications across multi-site networks.
- Production Systems:Fully integrated manufacturing execution system connectivity enables real-time throughput monitoring and predictive maintenance scheduling. Certified automation engineer scarcity in Switzerland and Germany extends deployment timelines by 4-8 months.
Material handling anchors volume; assembly lines are gaining share fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss engineering clusters while Indian manufacturing hubs compete on deployment cost. This asymmetry shapes procurement patterns across pharmaceutical screening networks. Regional differentiation stems from regulatory validation depth rather than hardware specifications alone.
Germany
FDA 21 CFR Part 11 replacement cycles and EU MDR Article 10 obligations drive validated handler demand among diagnostic device producers. The country's national pharmaceutical regulator enforces design-dossier traceability for IVD-integrated workflows. Siemens Healthineers anchors a dense automation engineering cluster in Erlangen that shortens motion-control development cycles.
United States
High-throughput screening consolidation and CRISPR-based biobank expansion compress assay timelines beyond manual capacity. FDA electronic signature mandates accelerate obsolescence of legacy plate-handling equipment lacking compliant data architecture. Greater Boston biotech startups specify vision-guided handlers for 384-well format flexibility.
Switzerland
Premium liquid-handling integration and precision manufacturing heritage sustain vendor positioning in validated pharmaceutical environments. Swissmedic medical device requirements enforce post-market surveillance systems equivalent to diagnostic-device obligations. Tecan Group leverages Swiss manufacturing heritage to command pricing tiers above cost-competitive alternatives.
India
Contract research organization expansion in genomic pipelines drives cost-sensitive handler procurement under streamlined regulatory pathways. CDSCO Class B medical device registration acceleration opens market access for mid-throughput installations. Hyderabad and Bengaluru CRO clusters favor pick-and-place systems for price-sensitive pipeline scaling.
China
Rare-earth magnet supply concentration creates pneumatic subsystem cost volatility that pressures precision actuator pricing. NMPA medical device registration requirements extend validation timelines for diagnostic-integrated handlers. Yangtze River Delta manufacturing bases absorb supply chain disruptions through vertical integration into linear motion components.
Automated Plate Handlers Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the automated plate handler supply base. The market structures around three tiers: validated premium platforms, modular mid-range systems, and cost-optimized standard configurations. Swiss and German engineering heritage defines the premium tier through precision manufacturing credibility. Strategic moves concentrate on regulatory pre-certification investments and service infrastructure density rather than price competition.
Among Swiss- and German-based precision engineering groups, Tecan Group Ltd and Siemens Healthineers AG exemplify the validated-platform archetype through heritage positioning in pharmaceutical screening environments. Hudson Robotics occupies a specialist position in modular architectures that reduce deployment complexity for mid-size laboratories. PerkinElmer anchors North American service infrastructure through field-engineer density that rivals direct competitors in response-time metrics.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Becton Dickinson |
| Tecan Group Ltd |
| PerkinElmer |
| Agilent Technologies |
| Hudson Robotics |
| Eppendorf AG |
| Molecular Devices LLC |
| Thermo Fisher Scientific |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification gates both supplier qualification and price differentiation simultaneously, forcing uncertified vendors into steeper discount territory while validated platforms command premium positioning in pharmaceutical procurement cycles. This regulatory threshold compresses the supplier base into discrete pricing tiers that reflect compliance investment depth rather than hardware performance alone.
Pricing Analysis
German and Swiss engineered systems transact at 40-60% premiums above Indian-manufactured alternatives, reflecting precision manufacturing heritage and validated quality-system documentation. Three-tier pricing structure across premium, standard, and economy levels segments buyers by validation burden: diagnostic device producers absorb premium tiers for ISO 13485-certified platforms, while contract research organizations in Hyderabad gravitate toward economy configurations under streamlined CDSCO pathways. Cost compression in mid-range robotic handlers is intensifying because vision-guided modular architectures reduce mechanical complexity and erode traditional service-revenue attachments. Academic biobanks exhibit highest price sensitivity; tier-one pharmaceutical manufacturers prioritize total cost of ownership over unit acquisition price.
Supply Chain Analysis
Rare-earth magnet processing concentration in Chinese facilities creates chokepoint vulnerability for precision linear actuator and vacuum generator sourcing. Component manufacturing draws from Germany, Switzerland, and China, with pneumatic subsystems and motion-control electronics resting on East Asian semiconductor fabrication. Single-source vulnerability in rare-earth supply chains exposes margin structures to commodity price volatility and export restriction risk. Distribution runs through authorized dealer networks for validated pharmaceutical installations, while cost-optimized segments leverage direct manufacturer-to-CRO relationships in Indian contract research clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through group purchasing organization consolidation across US East Coast biopharma networks, compressing vendor negotiation cycles and standardizing specification templates that favor interoperability over proprietary lock-in.
For Market Incumbents: Shield premium positioning by embedding predictive maintenance modules that capture recurring revenue streams before vision-guided competitors erode mechanical calibration service bases. Accelerate ISO 13485 certification pre-investment for emerging AI-powered motion-control architectures to preempt EU MDR validation timeline delays that disqualify late entrants from tier-one diagnostic manufacturer supplier lists. For New Entrants and Emerging Players: CDSCO Class B medical device registration fast-tracks open access to Hyderabad and Bengaluru contract research organization expansion, the most penetrable geography for cost-optimized pick-and-place configurations. Target genomic-sample-preparation pipeline scaling as the entry application, leveraging streamlined Indian regulatory pathways against burdened EU MDR timelines that delay established competitors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across vision-guided modular system development as machine-vision component costs decline and software-defined positioning reduces mechanical hardware stacks. Five-to-ten year viability favors acquisition targets with active ISO 13485 quality systems and installed base density in German pharmaceutical clusters, where Siemens Healthineers integration requirements create sticky demand. Watch AI-powered motion-control regulatory acceptance velocity as the inflection signal distinguishing premium-platform durability from commodity-margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Active quality-system documentation gates tier-one diagnostic manufacturer supplier qualification windows. |
| AI-Powered Motion-Control Development | Machine-learning adaptive positioning reduces calibration downtime in multi-format CRISPR screening environments. |
| CDSCO Regulatory Pathway Navigation | Streamlined Class B medical device registration accelerates market access for Indian CRO expansion clusters. |
| Vision-Guided Modular Architecture Launch | Sub-millimeter fiducial recognition eliminates mechanical retooling for 384-well format flexibility demands. |
| Predictive Maintenance Service Unbundling | Modular aftermarket packages capture margin from laboratories with in-house engineering capabilities. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with laboratory automation directors, biomedical engineers, GPO contracts managers, and regulatory affairs leads at diagnostic device manufacturers; and secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CDSCO medical device registration records, and SEC 10-K disclosures from listed automation vendors. Bottom-up triangulation across product-type unit economics and top-down reconciliation against end-user procurement survey data anchored volume and value estimates.
Across the analysis window, the forecasting framework modeled handler demand through product type, end-user industry, technology architecture, and application workflow segmentation dimensions. CAGRs were derived from regression analysis against pharmaceutical R&D expenditure trajectories and biobank capacity expansion pipelines, with cross-validation against CRISPR screening throughput growth curves and regulatory replacement cycle timing.
Decision-makers should treat outputs as directional under sustained FDA 21 CFR Part 11 enforcement and EU MDR Article 10 compliance trajectories; material deviation in regulatory acceptance timelines for AI-powered architectures would warrant model refresh. Practitioners should keep alternative scenarios live as rare-earth magnet supply chain disruptions and certified automation engineer scarcity in German and Swiss engineering clusters evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Surgical Robots Market
Robotics and Automation
Africa Cloud Robotics Market
Robotics and Automation
UV-C Disinfection Robots Market
Robotics and Automation
Social Robots Market
Robotics and Automation
Cleaning Robot Market
Robotics and Automation
Case and Box Handling Robots Market
Robotics and Automation
Smart Exoskeleton Market
Robotics and Automation
Rotary Gripper Module Market
Robotics and Automation
Global Machine Vision and Vision Guided Robotics Market
Robotics and Automation
Dispensing Robots Market
Robotics and Automation
Healthcare Mobile Robots Market
Robotics and Automation
Global Medical Robotic Systems Market
Robotics and Automation
Commercial Service Robotics Market
Robotics and Automation
Foundry and Forging Robots Market
Robotics and Automation
Underwater Drone Market
Robotics and Automation
Robot Controller, Integrator and Software Market