
 Global IT Robotic Automation Market | 2026-2036
Global IT Robotic Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global IT Robotic Automation Market Outlook
ISO/IEC 27001 certification is redrawing competitive boundaries in IT robotic automation procurement. UiPath sustains technology leadership through its native AI integration layer and extensive partner ecosystem. Automation Anywhere dominates cloud-native deployment architectures with its web-based platform. Blue Prism anchors enterprise-grade governance capabilities that appeal to regulated industries.
IT robotic automation encompasses software-based systems that emulate human interaction with digital interfaces, executing rule-based workflows through API orchestration, screen scraping, and cognitive recognition engines with sub-second response thresholds. Its primary purpose is to reduce operational expenditure while eliminating human error in high-volume transactional processes. Process Automation solutions capture the largest margin pools as enterprises prioritize end-to-end workflow digitization over isolated task scripting. Cloud-Based deployment is expanding fastest as hyperscaler marketplaces reduce procurement friction and accelerate time-to-value. Machine Learning integration is maturing from bolt-on feature to core platform requirement, shifting vendor evaluation criteria toward model training efficiency and inference latency.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that reshape platform architecture decisions for European deployments. The US SEC and HIPAA frameworks enforce audit trail integrity and access controls that filter vendor eligibility in financial services and healthcare segments. Stakeholders must monitor how emerging algorithmic accountability standards in China and Japan will fragment compliance requirements and force modular platform designs.
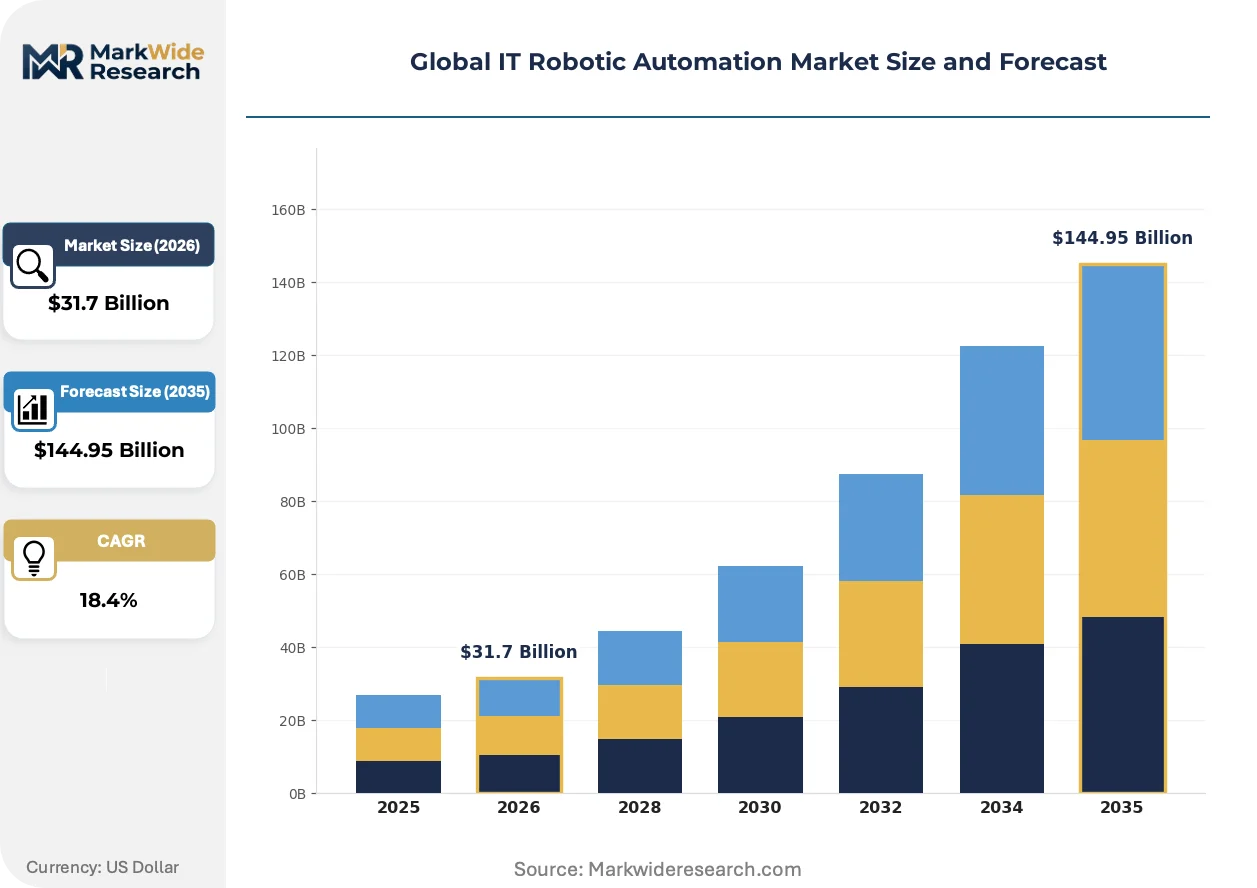
Market Dynamics
The EU AI Act is compressing vendor qualification timelines and forcing platform architectures toward modular compliance layers, redrawing procurement criteria for financial services and healthcare automation deployments.
Growth Catalysts
- Federal cloud-first mandates:United States government agencies accelerate robotic process automation deployment through standardized procurement vehicles and modernization budgets.
- ISO/IEC 27001 certification requirements:Enterprise buyers filter vendor pools based on information security management credentials, elevating certified platforms in competitive tenders.
- Hyperscaler marketplace integration:Amazon Web Services, Microsoft Azure, and Google Cloud reduce friction in cloud-native automation procurement and accelerate deployment velocity.
Market Restraints
- Algorithmic audit infrastructure costs:EU AI Act compliance demands explainability tooling and documentation systems that inflate total cost of ownership for European deployments.
- Legacy system integration complexity:Mainframe and custom ERP environments in banking and insurance segments resist API-native automation without expensive middleware layers.
- Specialized talent scarcity:Shortage of process analysts and automation engineers with hybrid business-technical skills constrains enterprise scaling velocity.
Strategic Opportunities
- Process mining convergence:Integration of Celonis and similar discovery platforms with execution engines creates end-to-end optimization suites for manufacturing and logistics verticals.
- Small and medium enterprise penetration:Pre-built industry templates and consumption-based pricing open addressable market beyond Fortune 500 accounts in Germany and Japan.
- Healthcare claims automation:HIPAA-compliant intelligent document processing addresses administrative burden in United States Medicare and Medicaid workflows.
Industry Challenges
- Change management resistance:Unionized workforces in European banking and public sectors obstruct bot deployment through work-rule negotiations and transition timeline disputes.
- Bot maintenance technical debt:Screen-scraping automations break when target applications update, requiring continuous engineering investment that erodes projected savings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IT Robotic Automation Market |
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $144.95 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Process Automation, Task Automation, Decision Management, Integration Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Financial Services, Telecommunications, Healthcare, Manufacturing Technology: Machine Learning, Natural Language Processing, Computer Vision, Others |
| Companies Covered | UiPath, Automation Anywhere, Blue Prism, Appian, Tata Consultancy Services Limited, Infosys Limited, Cognizant Technology Solutions Corp, Capgemini, Atos SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IT Robotic Automation Market Strategic Shifts
Large language models are embedding into automation platforms and transforming rule-based bots into adaptive systems capable of handling exceptions without explicit programming.
Generative AI orchestration layers are supplanting static decision trees in customer service and document processing workflows. Financial services firms in Singapore and the United Kingdom pilot these systems for KYC remediation and contract analysis. The shift compresses implementation timelines from months to weeks while expanding automation feasibility to unstructured data tasks previously requiring human judgment.
GDPR Article 22 enforcement is tightening around automated decision-making in credit and insurance underwriting. European regulators demand human-in-the-loop architectures with documented override protocols. Vendors respond with audit-trail modules and consent management integrations that embed compliance into runtime execution rather than bolt-on reporting.
Subscription pricing with outcome-based tiers is displacing perpetual licenses in mid-market segments. Buyers in Australia and Canada prefer contracts tied to transaction volumes or hours saved rather than bot counts. This restructures vendor revenue recognition and forces product teams toward usage analytics and customer success functions that demonstrate realized value.
Global IT Robotic Automation Market Segmentation
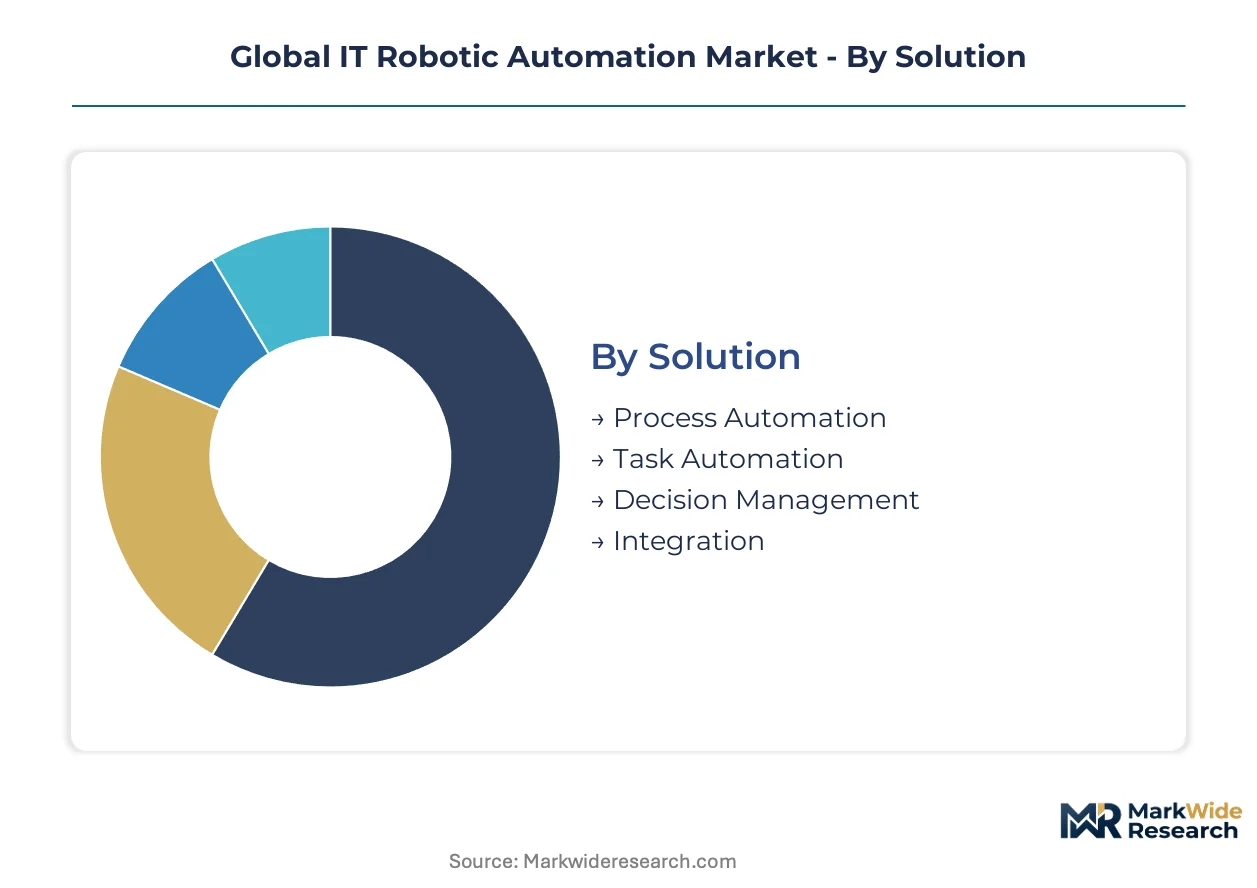
IT robotic automation vendors configure product architectures around deployment constraints, end-user compliance requirements, and technology integration complexity. Segmentation reveals where margin pools concentrate and which buyer profiles drive platform roadmap investments.
Solution:
Process Automation solutions dominate domestic enterprise procurement in the United States and Germany, while Task Automation exports accelerate from Indian development centers serving North American banking clients.
- Process Automation:Orchestrates end-to-end workflows across multiple systems through API integration and cognitive recognition engines. Demand concentrates in United States financial services firms automating compliance reporting and customer onboarding under SEC and HIPAA frameworks.
- Task Automation:Executes isolated, rule-based activities such as data entry and file transfers through screen scraping and keystroke emulation. German automotive suppliers deploy these bots for invoice processing, constrained by EU AI Act documentation requirements for automated decision trails.
- Decision Management:Embeds business rules engines for real-time routing and exception handling.
- Integration:Connects disparate legacy systems through middleware layers and API gateways.
Process Automation holds the largest share; momentum sits with Decision Management as generative AI embeds into runtime engines.
Deployment:
Cost tier structures separate enterprise buyers with dedicated infrastructure budgets from mid-market adopters prioritizing operational expenditure flexibility over capital deployment.
- Cloud-Based:Delivers browser-accessible automation platforms through hyperscaler marketplaces with consumption-based metering. United States federal agencies accelerate procurement through FedRAMP-authorized AWS and Azure listings, satisfying cloud-first mandates without on-premise infrastructure.
- SaaS:Provides multi-tenant architectures with pre-configured industry templates and automatic feature updates. Australian and Canadian mid-market manufacturers favor these offerings for rapid deployment without dedicated DevOps resources.
- On-Premise:Installs within client data centers for air-gapped environments and custom security policies.
- Hybrid:Combines cloud orchestration with on-premise execution nodes for sensitive data processing.
Cloud-Based deployment captures the dominant revenue position; Hybrid architectures are climbing the fastest as regulated industries partition workloads across security zones.
End User:
Application intensity varies by sector maturity, with financial services leading automation density while healthcare navigates stricter consent and audit protocols.
- Financial Services:Deploys automation for KYC verification, trade settlement, and regulatory reporting across investment banking and insurance operations. Singapore and United Kingdom firms pilot generative AI for contract analysis, compressing implementation timelines from quarters to weeks.
- Healthcare:Processes claims, eligibility verification, and clinical documentation under HIPAA audit trail requirements. United States Medicare and Medicaid administrative burden drives intelligent document processing adoption, constrained by algorithmic transparency demands from state insurance regulators.
- Telecommunications:Automates customer service workflows and network provisioning across subscriber management platforms.
- Manufacturing:Integrates robotic process automation with IoT sensor data for supply chain optimization and quality assurance.
Financial Services maintains the largest installed base; Healthcare claims automation shows the steepest expansion trajectory as administrative cost pressures intensify.
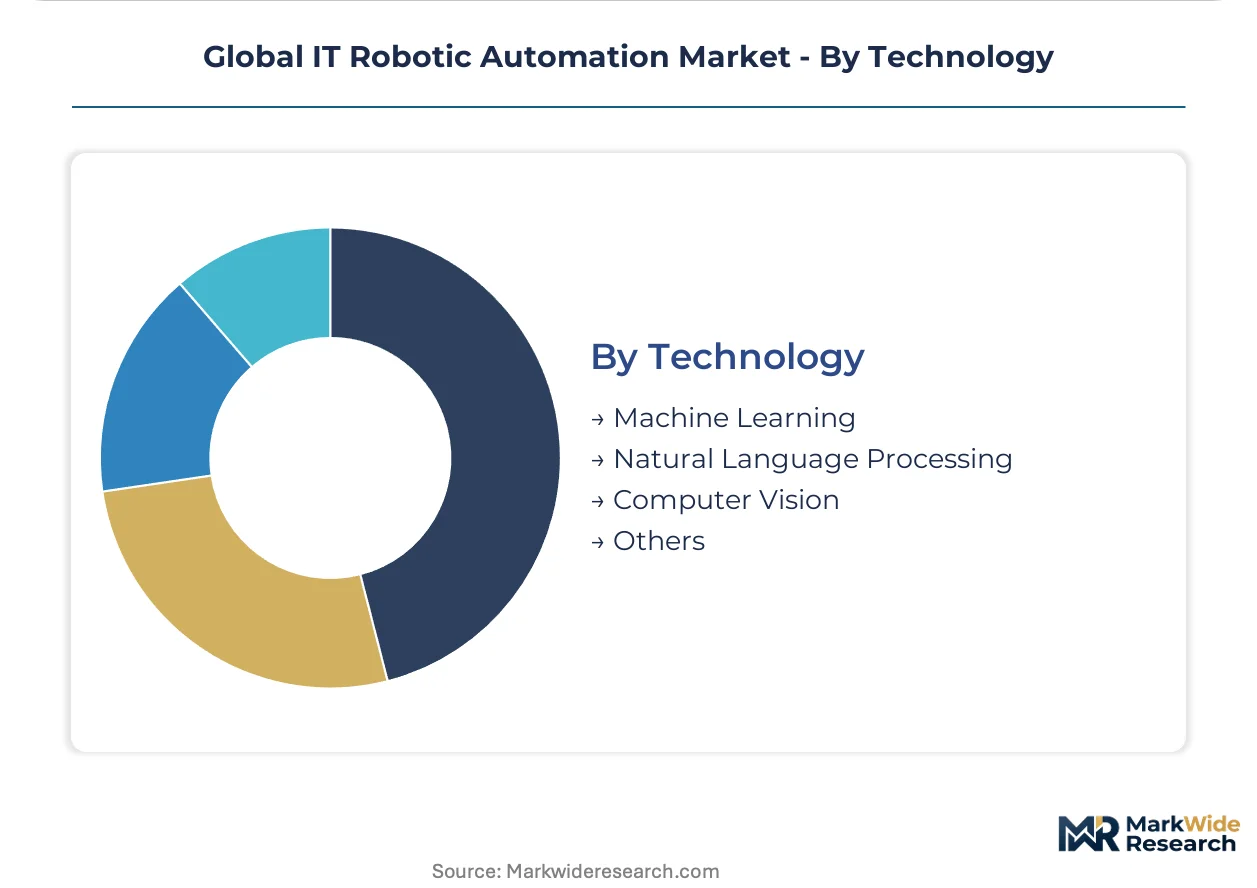
Technology:
Technology maturity curves separate proven capabilities in production environments from emerging layers requiring specialized talent and training infrastructure.
- Machine Learning:Enables predictive exception handling and continuous process optimization through model retraining on execution logs. Japanese manufacturers embed these capabilities for demand forecasting automation, constrained by data residency requirements under METI guidance.
- Natural Language Processing:Extracts meaning from unstructured documents, emails, and chat transcripts for automated classification and routing. United Kingdom financial services firms deploy NLP for KYC remediation, navigating GDPR Article 22 restrictions on automated decision-making.
- Computer Vision:Interprets visual interfaces and document images for data extraction and validation.
- Others:Encompasses emerging cognitive capabilities including sentiment analysis and voice recognition.
Machine Learning anchors current platform architectures; Natural Language Processing is gaining share fastest as large language models compress document processing development cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in the United States, Germany, and Japan concentrate procurement authority for IT robotic automation platforms, with financial services and manufacturing verticals driving deployment density across these markets.
United States
Federal cloud-first mandates and SEC compliance requirements accelerate robotic process automation adoption across government agencies and investment banking operations. HIPAA frameworks enforce audit trail integrity that filters vendor eligibility in healthcare claims processing. The New York financial corridor hosts dense clusters of automation engineering talent serving Wall Street trade settlement and KYC verification workflows.
Germany
Automotive suppliers and industrial machinery manufacturers deploy process automation for invoice processing and supply chain optimization under tight cost discipline. The EU AI Act imposes algorithmic transparency obligations that reshape platform architecture decisions for European deployments. Bavaria's manufacturing belt concentrates bot development centers serving Siemens and BMW production planning systems.
Japan
Manufacturers embed machine learning capabilities for demand forecasting automation, constrained by METI data residency guidance on cross-border data flows. JIS standards and emerging algorithmic accountability requirements fragment compliance specifications for enterprise buyers. The Nagoya industrial corridor anchors deployment of IoT-integrated automation for Toyota and Honda supplier networks.
United Kingdom
Financial services firms pilot generative AI orchestration for contract analysis and KYC remediation, navigating GDPR Article 22 restrictions on automated decision-making. The City of London's regulatory technology cluster drives demand for explainability tooling and documented override protocols. Edinburgh and Manchester host secondary automation centers serving insurance underwriting and pension administration workflows.
Singapore
Wealth management and trade finance operations deploy intelligent document processing for regulatory reporting across ASEAN markets. The Monetary Authority of Singapore's technology risk management guidelines shape procurement criteria for cloud-native automation platforms. The Marina Bay financial district concentrates regional headquarters for vendors serving Southeast Asian banking expansion.
Global IT Robotic Automation Market Competitive Environment
Player mix skews toward platform-native specialists and systems integrators with vertical expertise, creating a tiered structure where certification credentials and partner ecosystem breadth determine competitive positioning. Pure-play vendors compete on native AI integration and low-code development environments, while IT services conglomerates leverage existing enterprise relationships to bundle automation with broader digital transformation contracts. Dominant competitive moves include hyperscaler marketplace integration and pre-built industry template expansion.
Within the pure-play tier, UiPath and Automation Anywhere occupy positions defined by cloud-native architecture choices and partner ecosystem scale, while Blue Prism anchors enterprise-grade governance capabilities that appeal to regulated industries. Tata Consultancy Services Limited and Infosys Limited exemplify the systems integrator archetype, embedding automation capabilities within broader IT modernization engagements. These five entities collectively represent the competitive spectrum from specialized platform vendors to full-service deployment partners.
| Leading Market Players |
|---|
| UiPath |
| Automation Anywhere |
| Blue Prism |
| Appian |
| Tata Consultancy Services Limited |
| Infosys Limited |
| Cognizant Technology Solutions Corp |
| Capgemini |
| Atos SE |
| Others |
Value Chain & Pricing Dynamics
Consumption-based subscription contracts with annual commitment indexation anchor enterprise procurement, locking supply access to hyperscaler marketplaces while constraining price visibility to usage-band thresholds rather than per-bot licensing.
Pricing Analysis
Cost-plus arrangements with CPI indexation govern multi-year enterprise agreements, though three-tier pricing structure across premium, standard, and economy levels dominates mid-market SaaS procurement. Price differentiation rests on ISO/IEC 27001 certification tier and FedRAMP authorization status. Cost compression in economy tiers is intensifying because Indian development centers flood task-automation scripting capacity. Small and medium enterprises exhibit highest price sensitivity; United States federal agencies demonstrate lowest due to modernization budget insulation.
Supply Chain Analysis
India and the Philippines anchor low-code development and process documentation labor pools, while Ireland and Singapore host European and Asia-Pacific customer success functions. Platform engineering draws from cloud compute capacity concentrated in United States hyperscaler regions. Single-source vulnerability sits with Nvidia GPU supply for machine learning training clusters. Distribution runs through AWS Marketplace, Azure Marketplace, and direct enterprise field sales with systems integrator co-sell arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards organizations that control scarce automation engineering talent and pre-built vertical templates, as these assets constrain competitor replication speed more than raw platform functionality.
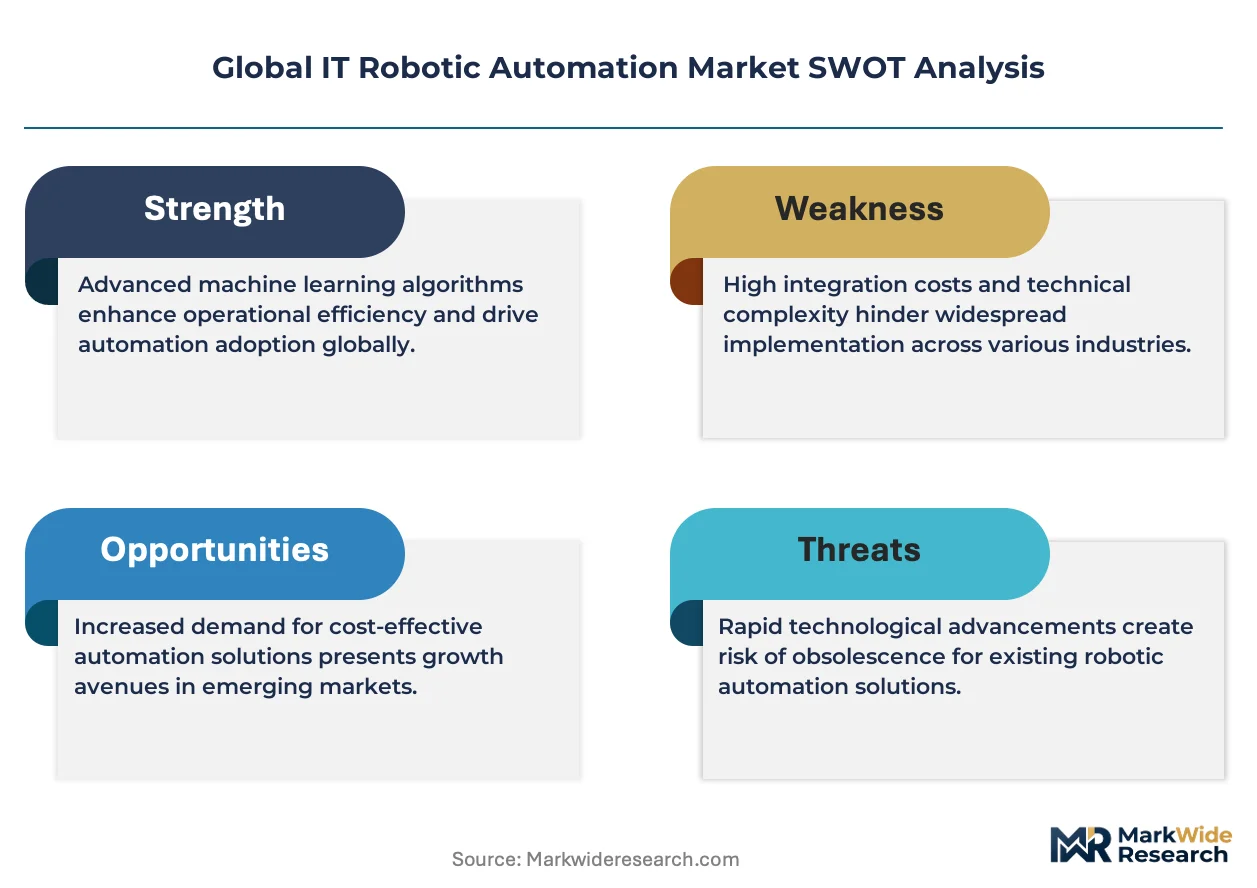
For Market Incumbents: Secure FedRAMP and ISO/IEC 27001 certifications ahead of EU AI Act enforcement waves, insulating against emerging compliance-filtered procurement. Deepen vertical template libraries for healthcare claims and trade settlement workflows to raise switching costs. Acquire specialized process mining firms to preempt Celonis integration moves by rivals. For New Entrants and Emerging Players: Anchor in German automotive supplier invoice processing and Japanese manufacturing demand forecasting, where METI data residency guidance and EU AI Act documentation requirements deter hyperscaler-native platforms. Target mid-market Australian and Canadian manufacturers with consumption-metered SaaS offerings. Lead with pre-built SAP and Oracle ERP connectors to compress implementation timelines. For Investors and Strategic Acquirers: Healthcare-focused intelligent document processing specialists with HIPAA audit-trail modules represent the most defensible acquisition profile for long-term viability. Monitor state insurance regulator algorithmic transparency enforcement as inflection indicator for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | Unlocks United States federal agency procurement through standardized cloud security validation. |
| Vertical Template Expansion | Compresses time-to-value for German automotive and United States healthcare compliance workflows. |
| Process Mining Integration | Creates end-to-end optimization suites competing with Celonis discovery-to-execution convergence. |
| Hyperscaler Marketplace Listing | Reduces procurement friction through AWS and Azure co-sell programs with existing enterprise relationships. |
| Generative AI Orchestration Layer | Transforms rule-based bots into adaptive systems for United Kingdom contract analysis and KYC remediation. |
Study Parameters
The analysis maps process automation, task automation, decision management, and integration segments, each validated through automation engineers, IT procurement officers, platform architects, and systems integrator delivery leads. Primary fieldwork combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory impact assessments anchored estimates. Bottom-up deployment counts and top-down enterprise IT budget allocations were triangulated for consistency.
Forecast outputs were validated against external benchmarks including hyperscaler marketplace growth trajectories and federal modernization budget appropriations. Segmentation modeled deployment model, organization size, vertical compliance intensity, integration complexity, and regional adoption pattern. CAGRs were derived from installed base expansion rates and average revenue per customer trajectory. Machine learning inference latency improvements and generative AI training cost curves informed technology adoption assumptions across the projection horizon.
Decision-makers should treat outputs as directional under stable regulatory enforcement and hyperscaler pricing continuity assumptions; material deviation in EU AI Act implementation timelines or Nvidia supply constraints would warrant model refresh. Recalibration cycles align with material shifts in federal procurement vehicle structures and emerging algorithmic accountability standards in Asian markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Commercial Robotics Market
Robotics and Automation
Solar Panel Cleaning Robot Market
Robotics and Automation
Global Robotics Market
Robotics and Automation
Latin America Cloud Robotics Market
Robotics and Automation
Cleaning Robot Market
Robotics and Automation
China Cloud Robotics Market
Robotics and Automation
Robotics Software Platforms Market
Robotics and Automation
Autonomous Drilling Robots Market
Robotics and Automation
United Kingdom Cloud Robotics Market
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
Aerospace Service Robotics Market
Robotics and Automation
Servo Gripper Market
Robotics and Automation
Agriculture Robotics Market
Robotics and Automation
Europe Articulated Robot Market
Robotics and Automation
North America Underwater Robotics Market
Robotics and Automation
AGV Intelligent Management Systems Market