
 Asia-Pacific AUV Market | 2026-2036
Asia-Pacific AUV Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific AUV Market Outlook
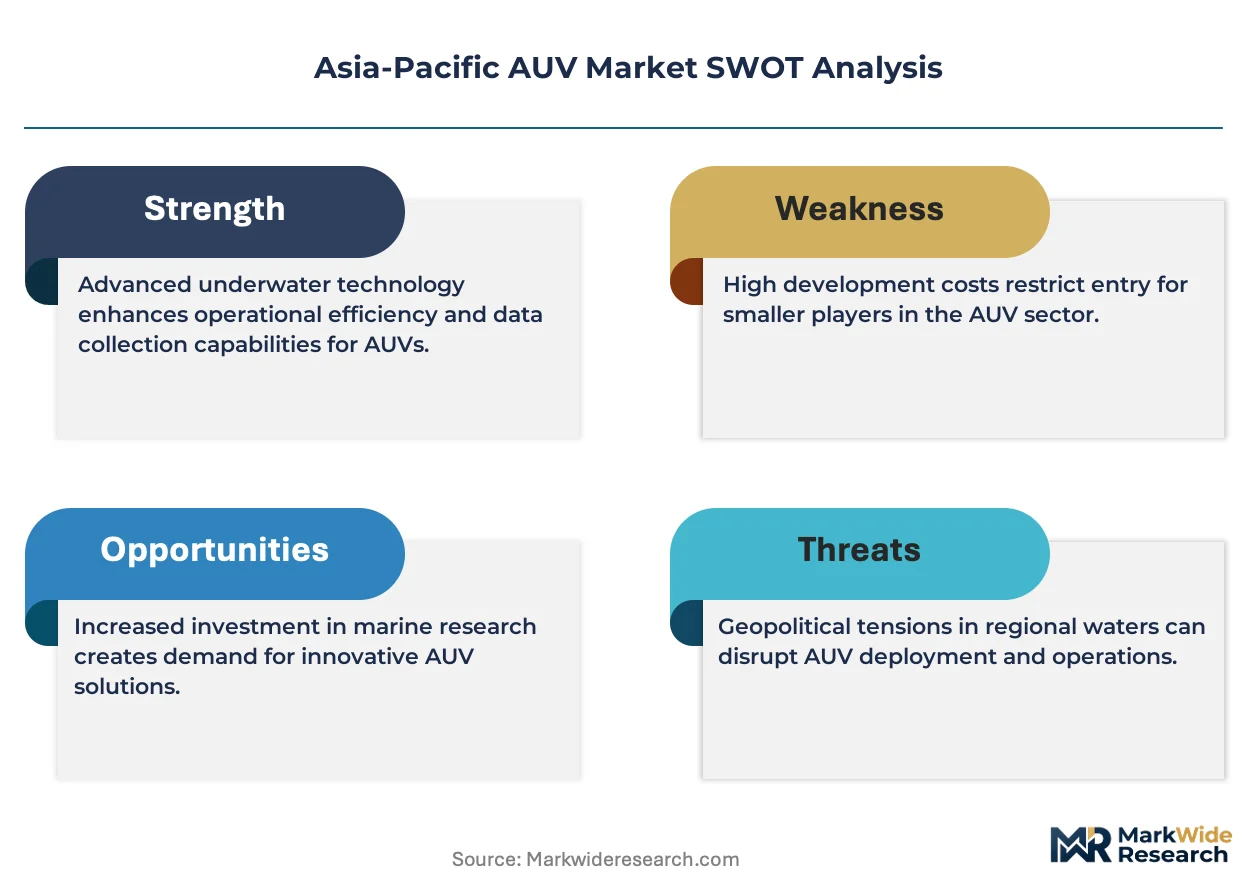
Modular payload configurations is shifting buyer choice across the Asia-Pacific AUV market, allowing operators to swap sensors and energy modules between missions rather than procuring dedicated vehicle fleets. Kongsberg Gruppen ASA leverages its integrated navigation and sonar ecosystem to dominate technology leadership in deep-water survey applications. Kawasaki Heavy Industries anchors manufacturing scale through its defense and industrial robotics heritage, while Larsen & Toubro Ltd competes on geographic dominance across Indian offshore energy contracts.
An autonomous underwater vehicle is a self-propelled, untethered robotic system operating without real-time human control, typically rated for depths from 100 to 6,000 meters and powered by lithium-ion or silver-zinc battery packs with mission durations spanning 8 to 72 hours. Its primary purpose is to execute pre-programmed subsea tasks including seabed mapping, infrastructure inspection, and scientific data collection in environments where tethered systems face operational constraints. Surveying applications lead current revenue contribution across the application dimension, while search and recovery represents the fastest-growing segment driven by naval modernization programs across the region. Within product type, hybrid vehicles are capturing expanding margin pools as operators seek dual-mode flexibility combining autonomous endurance with remote intervention capability.
Japan's METI sets domestic standards for deep-sea resource exploration equipment, while China's MIIT and GB standards govern underwater robotics certification and export controls. Australia's TGA-equivalent functional regulator for maritime safety shapes operational compliance requirements for commercial AUV deployment in territorial waters. Stakeholders must monitor evolving certification reciprocity agreements between national regulators to anticipate fleet deployment barriers and localize service infrastructure.
Market Dynamics
Modular payload architectures are restructuring competitive advantage in the Asia-Pacific AUV market, forcing manufacturers to abandon purpose-built vehicle lines in favor of reconfigurable platforms that swap sensors and power modules between missions.
Growth Catalysts
- Subsea Pipeline Inspection Mandates:Offshore oil and gas operators across Australia and Southeast Asia face regulatory pressure to expand autonomous inspection coverage of aging subsea infrastructure.
- MIIT Certification Acceleration:China's Ministry of Industry and Information Technology standards for underwater robotics are compressing domestic product approval timelines and creating captive demand for locally certified systems.
- Deep-Sea Research Funding:Japan's METI-directed resource exploration programs are generating sustained procurement for 6,000-meter-rated vehicles equipped for seabed mineral survey operations.
Market Restraints
- Lithium-Ion Supply Concentration:Battery pack manufacturing for extended-duration missions depends on concentrated East Asian cell suppliers, exposing fleet operators to input cost volatility and allocation constraints.
- Silver-Zinc Chemistry Obsolescence:Legacy energy systems face displacement pressure from lithium-based alternatives, stranding maintenance infrastructure and technical expertise at established defense contractors.
- Regulatory Fragmentation:Absence of reciprocal certification agreements between Australia's maritime safety regulator and counterparts in Japan and China forces redundant testing protocols for multi-national fleet deployments.
Strategic Opportunities
- Indian Offshore Energy Expansion:Larsen & Toubro's established fabrication yards and survey contracting relationships position early entrants for platform decommissioning and field development AUV services.
- Hybrid Vehicle Architectures:Dual-mode systems combining autonomous endurance with remote operator intervention are capturing premium positioning in inspection applications where real-time decision requirements persist.
- Search and Recovery Modernization:Naval programs across South Korea, Australia, and Japan are replacing legacy tethered systems with autonomous platforms for submarine rescue and wreck location missions.
Industry Challenges
- Subsea Navigation Expertise Scarcity:Integration of inertial navigation with Doppler velocity logs and acoustic positioning demands specialized engineering talent concentrated at a handful of defense heritage firms.
- Extended Certification Timelines:Pressure vessel rating and depth certification for new vehicle classes requires 18-24 month validation cycles at accredited test facilities, compressing product refresh cadences.
- Sensor Integration Complexity:Synthetic aperture sonar and multibeam echosounder payload swaps demand recalibrated hydrodynamic modeling and mission planning software reconfiguration between deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific AUV Market |
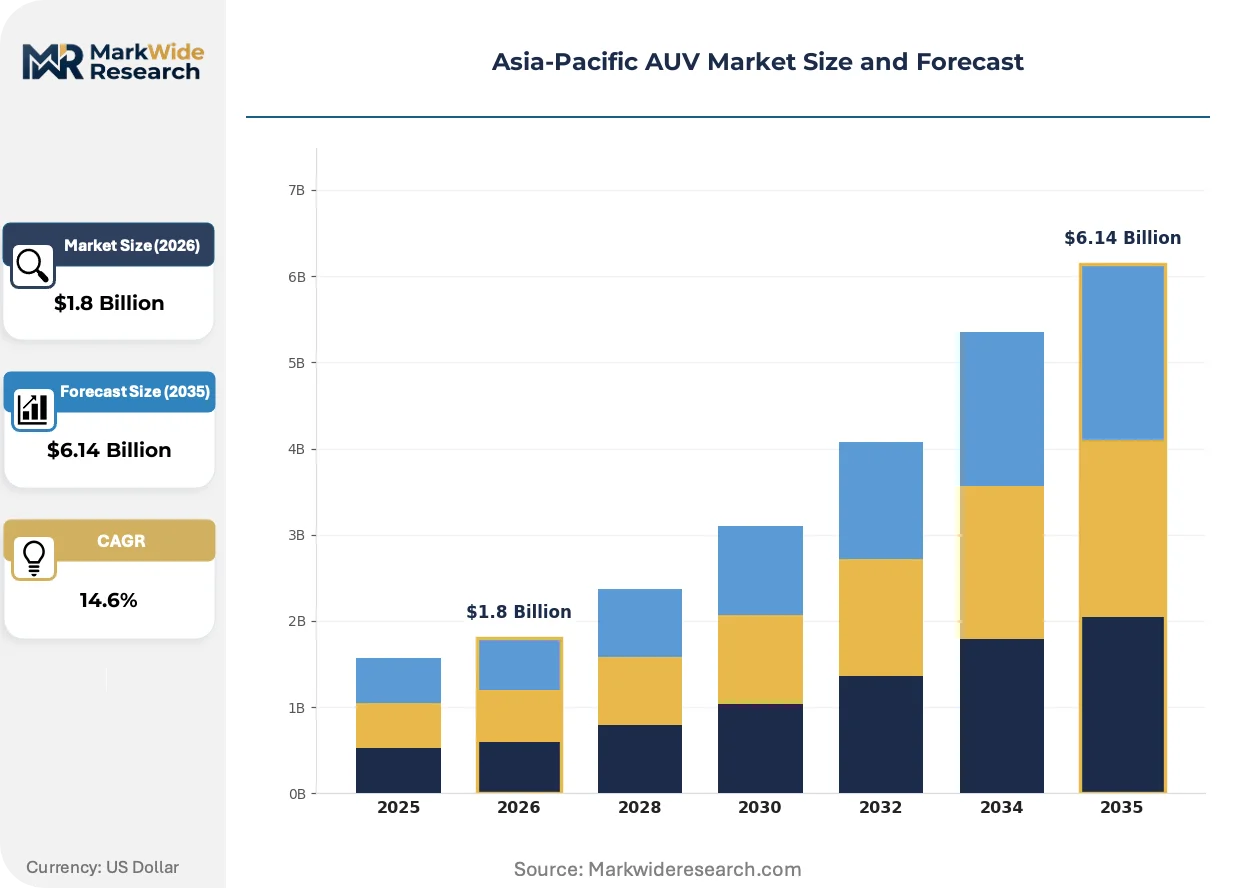
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Underwater Vehicles, Remotely Operated Vehicles, Hybrid Vehicles, AUV Payloads End User: Defense, Oil & Gas, Marine Research, Environmental Monitoring Application: Surveying, Inspection, Mapping, Search & Recovery Technology: Navigation Systems, Communication Systems, Energy Systems, Sensors |
| Companies Covered | DOF Subsea AS, Oceaneering International Inc., Fugro NV, RTSYS, Saipem SpA, Kongsberg Gruppen ASA, Larsen & Toubro Ltd, Kawasaki Heavy Industries, Teledyne Technologies Incorporated, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific AUV Market Strategic Shifts
Autonomous underwater vehicle development in the Asia-Pacific region is converging on standardization of mechanical and electrical interfaces, enabling third-party sensor developers to address niche applications without vehicle-level engineering partnerships.
Hybrid propulsion architectures are unifying the operational envelope previously split between battery-powered survey vehicles and tethered work-class ROVs. Japanese shipyards and Australian offshore contractors are piloting dual-mode systems that transition between autonomous transit and operator-controlled intervention without surface recovery. This convergence is compressing the addressable market for pure-play ROV manufacturers while expanding total accessible mission hours for autonomous platforms.
China's MIIT standards framework for underwater robotics is mandating domestic certification testing for navigation accuracy, acoustic signature, and electromagnetic compatibility before commercial deployment in territorial waters. The regulation is diverting product development resources toward compliance engineering and away from performance differentiation. Export-oriented manufacturers are responding with parallel product lines: GB-certified variants for domestic sale and IEC-aligned versions for regional markets.
Long-term lease arrangements with integrated maintenance provisions are displacing capital purchase models among Australian offshore energy operators. Contractors now procure survey capacity as meterage-rated service agreements rather than owning depreciating vehicle assets. This shift concentrates fleet ownership among specialist lessors with captive drydock and technical support infrastructure, compressing margins for pure equipment vendors without service integration capabilities.
Asia-Pacific AUV Market Segmentation
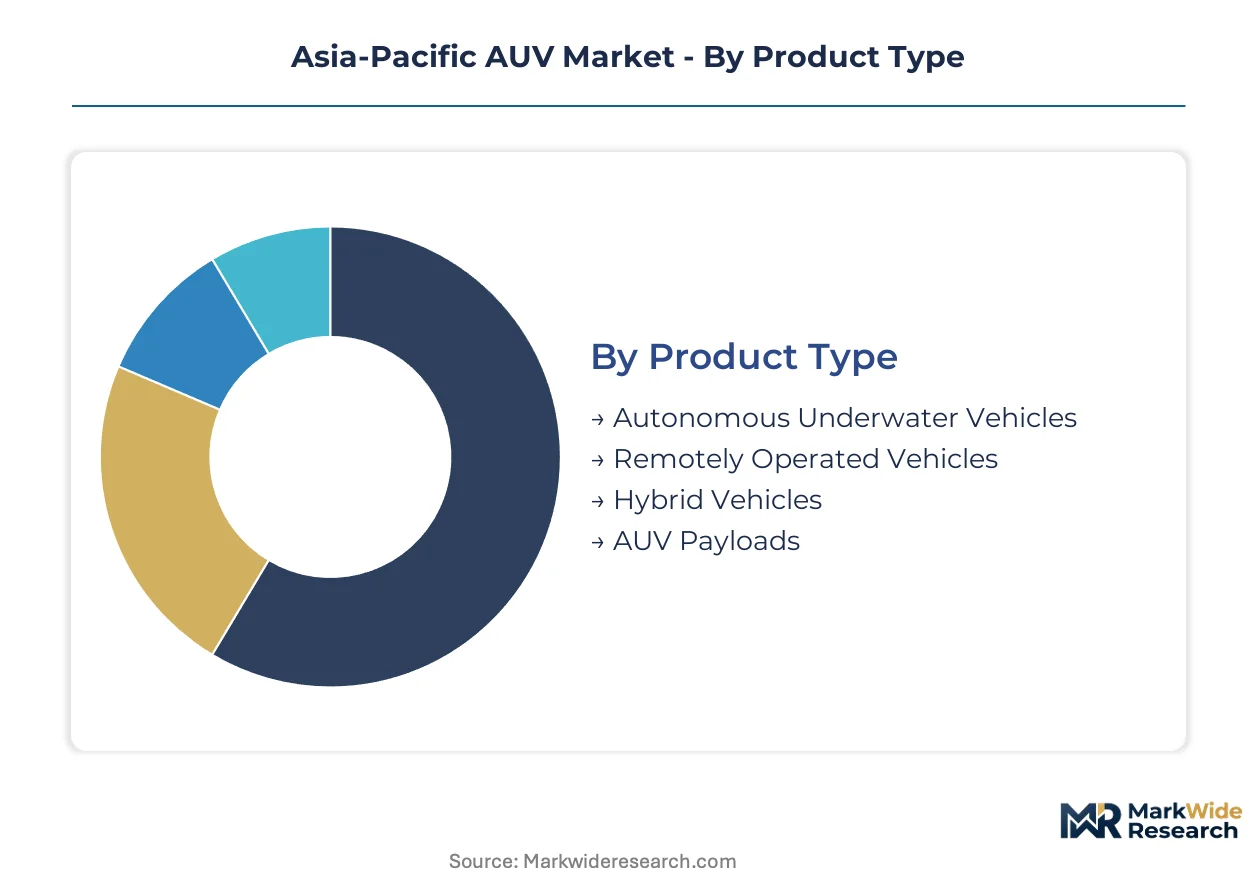
Asia-Pacific AUV procurement cycles vary sharply across operator types, with defense and offshore energy buyers running 8-12 year fleet refresh timelines while research institutions upgrade sensor packages every 3-4 years. Segmentation clarity enables suppliers to align module compatibility and certification pathways with distinct capital deployment rhythms.
Product Type:
Replacement cycles in the Asia-Pacific AUV fleet are compressing as modular architectures allow sensor and energy upgrades without full vehicle retirement, reshaping how operators prioritize initial procurement specifications.
- Autonomous Underwater Vehicles:Self-propelled untethered systems rated for 100-6,000 meter depths with lithium-ion or silver-zinc battery packs delivering 8-72 hour mission endurance. Australian offshore operators and Japan's deep-sea research programs concentrate demand for 6,000-meter-rated survey configurations.
- Hybrid Vehicles:Dual-mode platforms combining autonomous transit with remote operator intervention capability via acoustic or satellite link. Japanese shipyards and Australian contractors pilot these systems for pipeline inspection where real-time decision requirements persist, capturing expanding margin pools as operators seek operational flexibility.
- Remotely Operated Vehicles:Tethered systems with surface power and real-time control for precision intervention tasks.
- AUV Payloads:Modular sensor and energy packages enabling mission reconfiguration without vehicle replacement.
Autonomous Underwater Vehicles sit at the top of the volume ranking, with Hybrid Vehicles climbing the fastest.
End User:
Cost tier stratification separates defense procurement with 15-year platform lifecycles and integrated logistics support from commercial operators seeking meterage-rated service agreements.
- Oil & Gas:Offshore operators across Australia's Northwest Shelf and Southeast Asian production basins deploy AUVs for subsea pipeline inspection and platform decommissioning surveys. Regulatory mandates for autonomous infrastructure coverage are accelerating fleet expansion among integrated majors and national oil companies.
- Defense:Naval modernization programs in South Korea, Australia, and Japan replace legacy tethered systems with autonomous platforms for submarine rescue, mine countermeasures, and wreck location missions. Procurement emphasizes 6,000-meter depth ratings and acoustic signature compliance for covert operations.
- Marine Research:Academic and government laboratories in Japan and Australia operate vehicles for seabed mapping and biodiversity assessment.
- Environmental Monitoring:Regulatory agencies and coastal authorities deploy systems for water quality assessment and habitat surveillance.
Oil & Gas commands the largest installed base, with Defense expanding most quickly.
Application:
Application selection tracks directly to water depth requirements and positioning accuracy demands, with shallow-water mapping tolerating lower-grade navigation while deep-water survey mandates inertial-Doppler fusion.
- Surveying:Systematic seabed mapping using multibeam echosounders, side-scan sonar, and sub-bottom profilers for route planning and site characterization. Australia's offshore energy corridor and Japan's deep-sea resource zones generate sustained procurement for high-resolution bathymetric systems.
- Search & Recovery:Locating submerged objects including aircraft wreckage, sunken vessels, and downed submarines using synthetic aperture sonar and optical sensors. Naval programs across South Korea, Australia, and Japan are displacing legacy tethered systems with autonomous platforms, creating the steepest demand trajectory in the application dimension.
- Inspection:Close-range assessment of subsea pipelines, risers, and platform structures for corrosion and damage detection.
- Mapping:Geological and geophysical characterization for resource exploration and scientific research.
Surveying leads current revenue contribution, with Search & Recovery gaining share fastest.
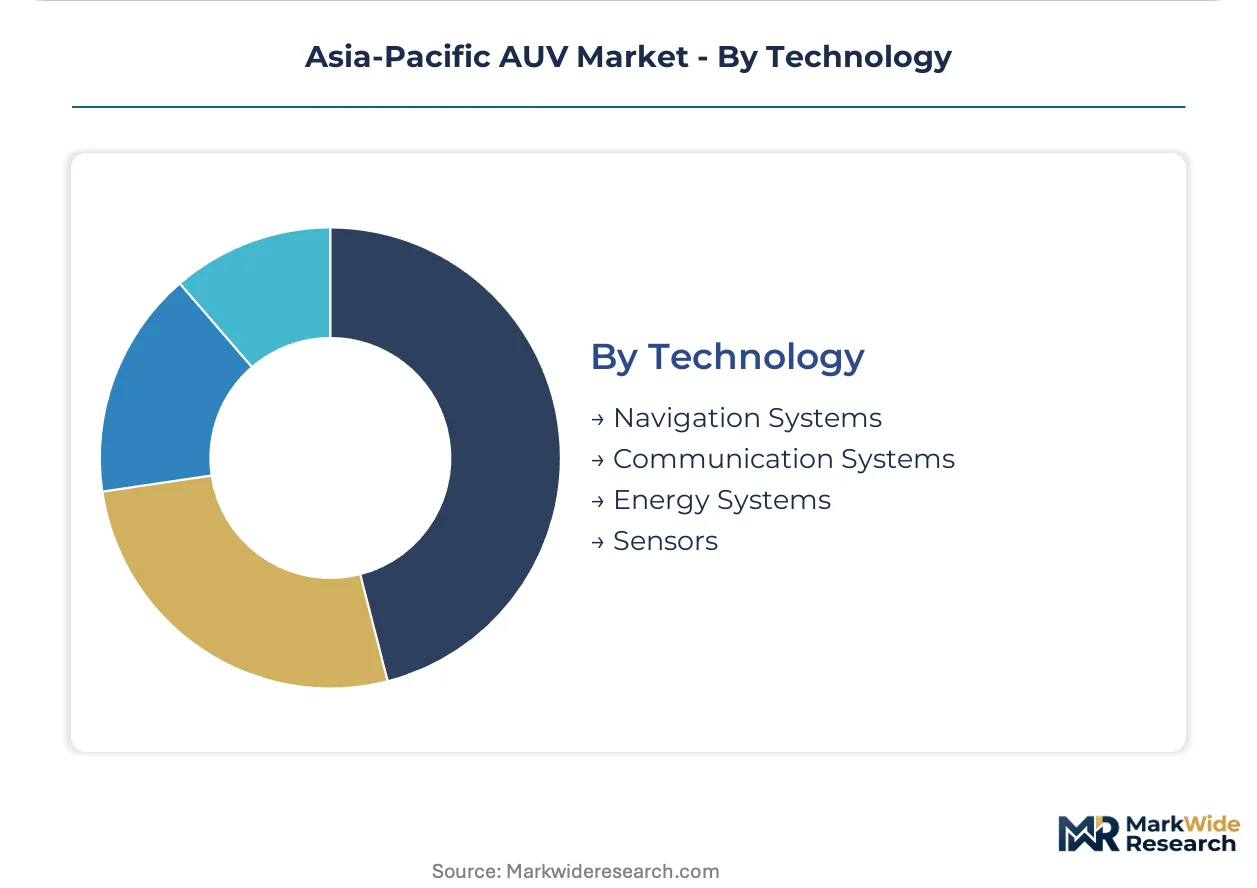
Technology:
Technology stack composition reflects supply concentration in East Asian component manufacturing, with navigation and energy modules sourced from distinct supplier ecosystems.
- Navigation Systems:Integration of inertial measurement units, Doppler velocity logs, and acoustic positioning for subsea georeferencing. Kongsberg Gruppen ASA dominates technology leadership through its integrated navigation and sonar ecosystem for deep-water survey applications.
- Energy Systems:Lithium-ion battery packs for extended-duration missions and silver-zinc alternatives for defense applications requiring specific power density profiles. East Asian cell suppliers concentrate manufacturing, exposing fleet operators to input cost volatility.
- Communication Systems:Acoustic modems and satellite links for command transmission and data exfiltration.
- Sensors:Multibeam echosounders, synthetic aperture sonar, and optical imagers for environmental perception.
Navigation Systems anchor technology investment, with Energy Systems climbing fastest as operators prioritize endurance extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep-water survey operations in the Asia-Pacific trace their commercial lineage to North Sea technology transfers during Australia's 1980s offshore boom. Japanese shipyards adapted Norwegian AUV architectures for Pacific trench operations. Chinese state laboratories reverse-engineered Soviet-era underwater vehicle designs during the 1990s.
Australia
Offshore energy operators on the Northwest Shelf deploy 6,000-meter-rated vehicles for pipeline inspection and platform decommissioning surveys. The country's maritime safety regulator mandates autonomous coverage of aging subsea infrastructure. Perth anchors the regional service hub, with contractors operating meterage-rated lease agreements rather than owned fleets.
China
MIIT certification requirements for underwater robotics are compressing domestic approval timelines and creating captive demand for GB-standard systems. State-directed deep-sea resource programs fund seabed mineral exploration in the South China Sea. Qingdao's ocean technology cluster hosts validation facilities for pressure vessel rating and depth certification.
Japan
METI-directed funding for deep-sea resource exploration sustains procurement for trench-rated survey vehicles. Naval modernization programs displace legacy tethered systems with autonomous platforms for submarine rescue missions. Yokohama's shipyards pilot hybrid architectures combining autonomous transit with operator-controlled intervention.
South Korea
Naval search and recovery programs drive replacement of legacy systems with autonomous wreck-location platforms. The country's defense procurement agency emphasizes acoustic signature compliance for covert operations. Busan-Ulsan shipyards integrate navigation and sonar ecosystems for regional fleet deployment.
India
Offshore energy expansion on the west coast generates demand for platform decommissioning and field development services. Larsen & Toubro's fabrication yards anchor early-entrant positioning for survey contracting. Mumbai's offshore corridor concentrates operator relationships with specialist lessors holding captive drydock infrastructure.
Asia-Pacific AUV Market Competitive Environment
The competitive structure tilts toward defense-heritage conglomerates with integrated navigation ecosystems. Three tiers separate pure equipment vendors from service-integrated lessors and captive state-owned fabricators. Strategic moves concentrate on modular payload standardization and hybrid vehicle architecture development.
Among defense-heritage specialists, Kongsberg Gruppen ASA and Kawasaki Heavy Industries occupy positions defined by integrated sonar and navigation technology. Kongsberg represents the deep-water survey archetype through its ecosystem approach. Kawasaki exemplifies manufacturing scale derived from industrial robotics heritage. Larsen & Toubro Ltd anchors the geographic dominance archetype across Indian offshore energy contracts.
| Leading Market Players |
|---|
| DOF Subsea AS |
| Oceaneering International Inc. |
| Fugro NV |
| RTSYS |
| Saipem SpA |
| Kongsberg Gruppen ASA |
| Larsen & Toubro Ltd |
| Kawasaki Heavy Industries |
| Teledyne Technologies Incorporated |
| Others |
Value Chain & Pricing Dynamics
Captive integration of navigation and sonar ecosystems by Kongsberg Gruppen ASA and Kawasaki Heavy Industries anchors both supply security and pricing power across the Asia-Pacific AUV market. These vertically integrated defense-heritage conglomerates control critical subsea positioning technology, allowing premium capture on 6,000-meter-rated survey configurations while forcing pure equipment vendors toward meterage-rated service agreements to compete.
Pricing Analysis
Meterage-rated service agreements with integrated maintenance provisions now dominate commercial procurement among Australian offshore energy operators. Price differentiation hinges on depth certification tier and sensor payload complexity, with 6,000-meter-rated vehicles commanding substantial premiums over shallow-water configurations. Cost compression in the mid-tier inspection segment is intensifying because specialist lessors with captive drydock infrastructure are consolidating fleet ownership and squeezing pure equipment vendors. National oil companies exhibit lowest price sensitivity due to regulatory mandates for autonomous infrastructure coverage, while independent survey contractors face acute margin pressure under long-term lease arrangements.
Supply Chain Analysis
Refurbishment and remanufacturing flows for lithium-ion battery packs and inertial navigation units are concentrating at Perth and Yokohama service hubs, extending vehicle lifecycles without full replacement. East Asian cell suppliers in China, South Korea, and Japan anchor energy system manufacturing, creating single-source vulnerability for extended-duration mission configurations. Critical inputs including synthetic aperture sonar arrays and pressure vessel alloys draw from concentrated defense-industrial bases. Tariff exposure on navigation components sourced across Japan-China supply corridors elevates landed costs for multi-national fleet operators. Distribution runs through specialist lessors holding captive technical support infrastructure rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's compressed MIIT certification timelines and Australia's extended validation protocols creates margin capture opportunities for manufacturers operating parallel product lines. The cost differential in regulatory compliance engineering favors early localization investments in Qingdao's ocean technology cluster over Perth's mature but higher-cost service infrastructure.
For Market Incumbents: To counter displacement pressure from hybrid vehicle architectures, Kongsberg Gruppen ASA and Kawasaki Heavy Industries should deepen captive control over lithium-ion cell supply through strategic partnerships with South Korean battery manufacturers. Certification investment in China's GB standards framework represents the priority defensive lever, as MIIT mandates increasingly wall off domestic procurement to locally validated systems. For New Entrants and Emerging Players: The premium-to-economy gap in 6,000-meter depth ratings offers white-space entry for modular payload specialists targeting India's offshore energy expansion. Larsen & Toubro's fabrication yard relationships in Mumbai's offshore corridor represent the most penetrable geographic anchor for survey contracting services. A go-to-market angle emphasizing rapid sensor reconfiguration for platform decommissioning missions bypasses entrenched navigation ecosystem dominance. For Investors and Strategic Acquirers: Roll-up economics work for regional service-integrated lessors because fleet ownership concentration under long-term lease arrangements generates predictable meterage-rated revenue streams with captive maintenance attachment. The 5-10 year viability window favors acquisition targets with established drydock infrastructure and multi-certification capabilities across MIIT, METI, and Australian maritime safety frameworks. Practitioners should monitor reciprocity negotiations between national regulators for early signals of cross-border fleet deployment barrier reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Vehicle Architecture Development | Yokohama shipyards pilot dual-mode systems combining autonomous transit with operator-controlled intervention for pipeline inspection. |
| MIIT Certification Localization | Qingdao validation facilities compress domestic approval timelines for GB-standard navigation and energy systems. |
| Service-Integrated Leasing Expansion | Perth contractors displace capital purchase models with meterage-rated agreements concentrating fleet ownership among specialist lessors. |
| Modular Payload Standardization | Mechanical and electrical interface unification enables third-party sensor developers to address niche applications without vehicle-level partnerships. |
| Deep-Sea Research Program Alignment | METI-directed funding for trench-rated vehicles sustains procurement for seabed mineral exploration in Japan's exclusive economic zone. |
Study Parameters
Multiple input streams — primary interviews with AUV program managers at national oil companies and naval procurement officers, secondary validation through MIIT certification databases and METI funding disclosures, and customs records of pressure vessel imports — were reconciled to construct segment-level demand estimates. Bottom-up fleet inventory analysis across Australia's Northwest Shelf operators and top-down budget allocation review for Japan's deep-sea research programs were cross-referenced to anchor volume assumptions.
Historical deployment patterns from North Sea technology transfers during Australia's 1980s offshore boom were cross-referenced against panel input from shipyard integration specialists and subsea navigation engineers. Segmentation dimensions modeled include product type, end user, application, and technology stack, with particular attention to hybrid vehicle adoption trajectories and modular payload refresh cycles. CAGRs were derived from trend extrapolation of defense procurement timelines and commercial lease agreement structures, incorporating lithium-ion supply constraints and certification reciprocity assumptions as scenario variables.
Caveats apply where MIIT regulatory acceleration or sudden certification reciprocity agreements between Australia, Japan, and China could materially shift the outlook for multi-national fleet deployment. Forecasts reflect assumptions regarding battery chemistry transition timelines and defense budget continuity across South Korea, Australia, and Japan. Practitioners should monitor navigation ecosystem integration progress and hybrid vehicle pilot program outcomes for early signals of competitive structure change.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
China Industrial Robots Market
Robotics and Automation
Autonomous Robot Market
Robotics and Automation
Smart Remote Control Market
Robotics and Automation
Japan Articulated Robot Market
Robotics and Automation
Construction Robotics Market
Robotics and Automation
Internet of Robotic Things Market
Robotics and Automation
Smart Curtain Robot Market
Robotics and Automation
Warehouse Robotics Market
Robotics and Automation
Europe AUV and ROV Market
Robotics and Automation
Robotic Waste Sorting System Market
Robotics and Automation
Underwater Robot Market
Robotics and Automation
Human-Robot Collaborative Picking Optimization Platforms Market
Robotics and Automation
Germany Cloud Robotics Market
Robotics and Automation
Delta Robots Market
Robotics and Automation
North America AUV and ROV Market
Robotics and Automation
Automotive Robotic Painting Market