
 Asia-Pacific Service Robotics Market | 2026-2036
Asia-Pacific Service Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Service Robotics Market Insights
Lightweight aluminum alloys replacing traditional steel chassis is realigning cost structures for mobile service robots. Hanwha Robotics leverages in-house actuator production to sustain margin control across South Korean industrial deployments. Ecovacs Robotics anchors its position through dominant channel control in China's consumer cleaning segment. SIASUN Robot & Automation Co Ltd competes on manufacturing scale for heavy-payload logistics platforms.
Service robotics encompasses autonomous or semi-autonomous machines performing non-industrial tasks through integrated perception, locomotion, and manipulation subsystems, typically operating via LIDAR-based SLAM navigation with payload capacities from 5 kg to 500 kg depending on application class. Healthcare applications lead end-user demand as aging demographics in Japan and South Korea expand robot-assisted eldercare and surgical support deployments. Navigation Systems technology represents the fastest-growing segment as outdoor delivery robots and agricultural autonomous platforms require centimeter-level GPS-RTK positioning. Sensor Technologies command concentrated margin pools where multi-spectral fusion for dynamic obstacle detection differentiates premium system tiers.
Japan's METI enforces JIS safety standards for human-robot collaborative environments, while China's SAMR certifies autonomous navigation systems under evolving GB standards. South Korea's MFDS regulates healthcare robot clinical validation pathways, shaping product development timelines for medical applications. Stakeholders must monitor regulatory divergence between national certification regimes when designing cross-border platform architectures.
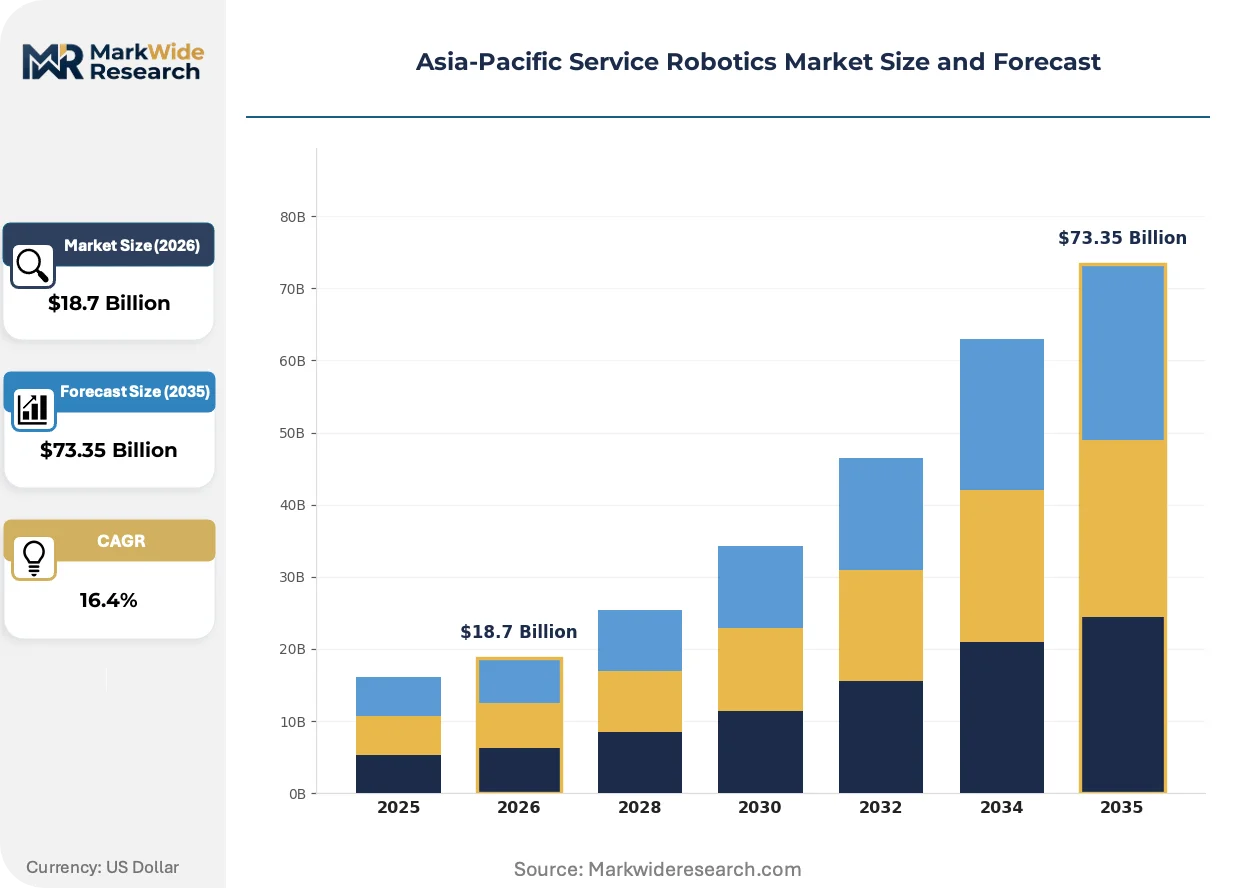
Market Dynamics
Japan's METI robotics roadmaps and China's dual carbon goals are tightening efficiency standards for autonomous systems, forcing platform redesigns across the Asia-Pacific region. Healthcare facilities in Japan and South Korea are expanding robot-assisted patient care programs faster than supply chains can adapt.
Growth Catalysts
- Navigation Systems:Centimeter-level GPS-RTK positioning for outdoor delivery robots and agricultural autonomous platforms is expanding addressable use cases across China's Yangtze River Delta manufacturing corridor.
- Japan's METI JIS Safety Standards:Human-robot collaborative environment certifications are accelerating deployment permits for eldercare facilities in Osaka and Tokyo prefectures.
- Lightweight Aluminum Alloys:Material substitution in mobile robot chassis is reducing power consumption requirements and extending operational range for warehouse logistics fleets.
Market Restraints
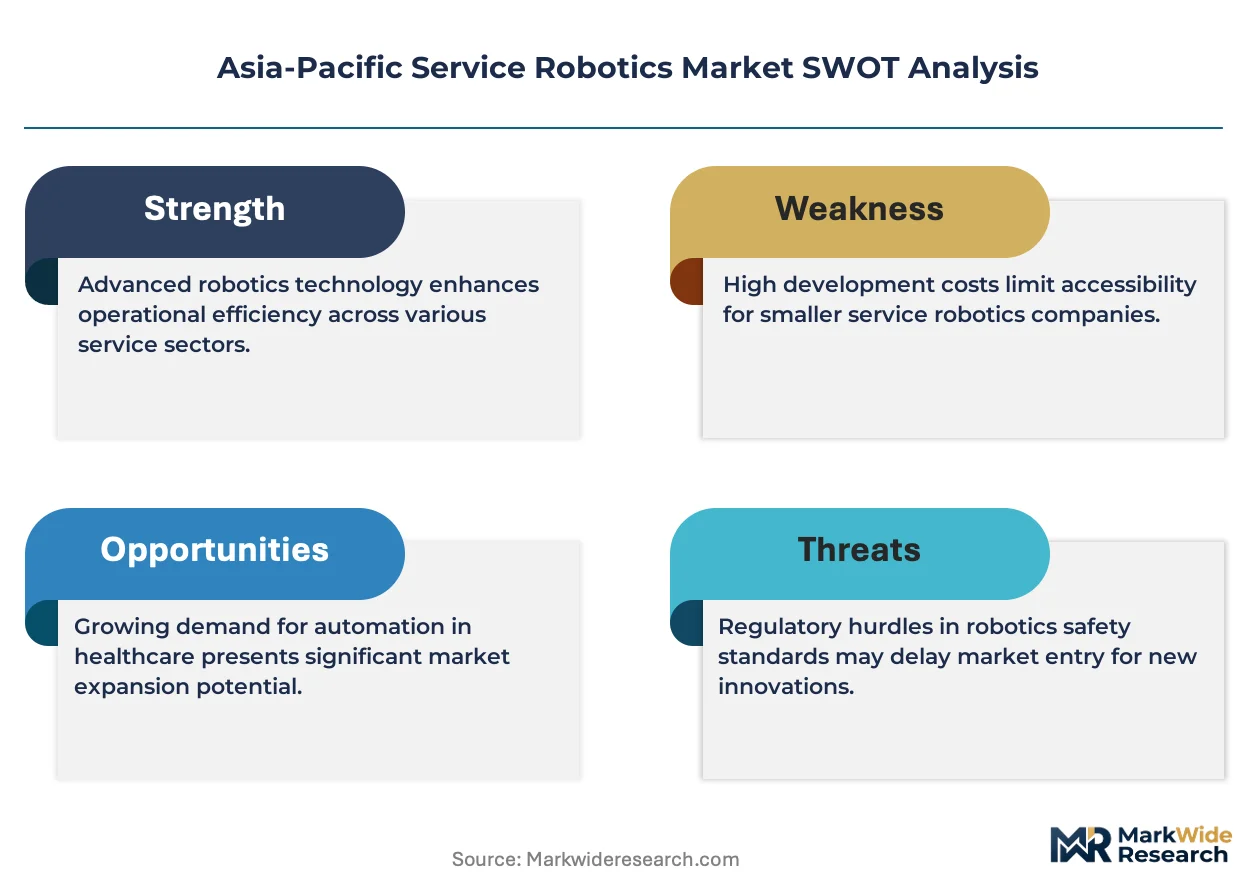
- High-Precision Sensor Cost Volatility:Multi-spectral fusion modules for dynamic obstacle detection command concentrated margin pools, squeezing mid-tier system economics.
- South Korean Actuator Supply Concentration:In-house production capabilities at dominant industrial automation firms limit component access for smaller platform builders.
- China's SAMR GB Certification Timeline:Evolving autonomous navigation standards create product launch delays and force redundant testing cycles.
Strategic Opportunities
- Vietnamese Manufacturing Underpenetration:Electronics assembly and semiconductor packaging facilities lack automated material handling density compared to regional peers.
- Japan-South Korea Healthcare Robot Convergence:Surgical support and rehabilitation platforms face limited cross-border clinical validation reciprocity, creating first-mover advantages for dual-certified systems.
- Indonesia's Agricultural Automation Gap:Palm oil and rice cultivation operations remain dependent on manual labor despite terrain-compatible autonomous platform availability.
Industry Challenges
- SLAM Navigation Engineer Scarcity:LIDAR-based simultaneous localization and mapping expertise concentrates in Shenzhen, Tokyo, and Seoul, creating recruitment bottlenecks for regional expansion.
- Legacy Warehouse Management System Integration:Proprietary protocols at established logistics operators force costly middleware development for robot fleet deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Service Robotics Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Housekeeping, Telepresence, Delivery, Security End User: Healthcare, Hospitality, Retail, Education Technology: AI, Navigation Systems, Machine Learning, Sensor Technologies Application: Agriculture, Logistics, Maintenance, Entertainment |
| Companies Covered | Hanwha Robotics, SIASUN Robot & Automation Co Ltd, LG Electronics Inc., SoftBank Corp., Omron Corporation, UBTECH Robotics Inc., Ecovacs Robotics Co Ltd, Milagrow HumanTech, Hyundai Robotics Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Service Robotics Market Trends and Innovations
Multi-spectral sensor fusion and edge-computing architectures are compressing decision latency for dynamic environments. Platform builders are redesigning around modularity to accommodate rapid hardware refresh cycles.
Sensor fusion technology combining LIDAR, visual cameras, and thermal imaging is converging with edge AI processors to enable real-time obstacle classification without cloud dependency. Japanese eldercare operators in Kanagawa Prefecture are piloting these integrated perception stacks for nighttime patient monitoring. The structural compression of compute-to-sensor latency is converging with battery energy density improvements to extend autonomous operational windows beyond twelve hours.
China's SAMR is tightening GB standard certification requirements for autonomous navigation systems operating in mixed pedestrian-vehicle environments. Industrial logistics operators in Suzhou and Hangzhou are front-loading compliance investments to avoid retroactive platform modifications. Heavy-payload manufacturing applications face the steepest compliance ramps as safety-critical classification thresholds drop from 100 kg to 50 kg rated payloads.
Hospital procurement committees are unbundling after-sales service contracts from hardware acquisition, forcing robot vendors to compete on transparent maintenance cost structures. South Korean healthcare networks in Seoul and Busan are standardizing five-year total cost of ownership models for surgical support platforms. This behavioral shift is most visible in Japan's prefectural hospital systems, where METI efficiency mandates require documented operational cost reductions for capital approvals.
Asia-Pacific Service Robotics Market Segmentation
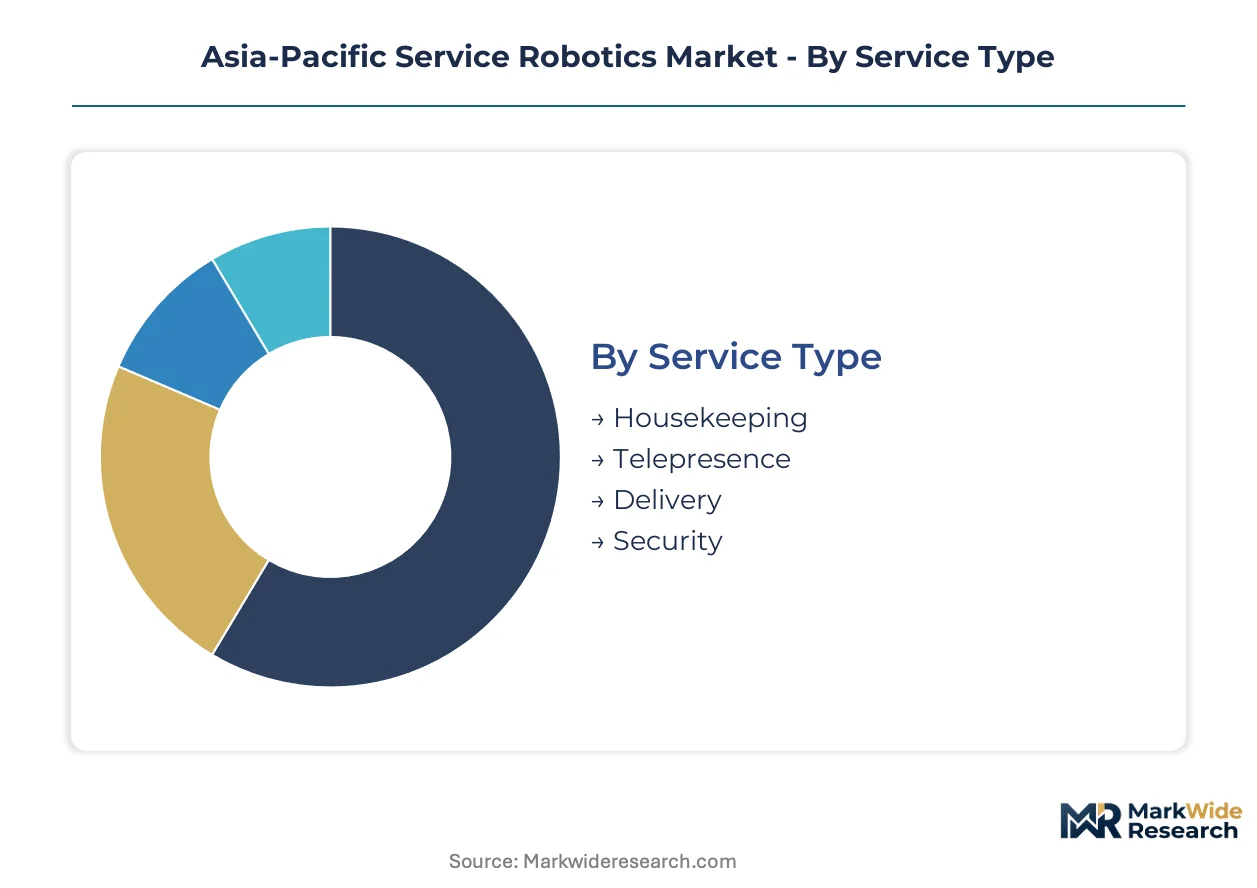
Segmentation reveals how hardware refresh cycles and software upgrade timelines diverge across service robotics applications. Platform vendors calibrate development roadmaps to these replacement rhythms, particularly where regulatory recertification resets competitive positioning.
Service Type:
Upgrade cycles compress where sensor fusion hardware obsolescence outpaces mechanical durability.
- Housekeeping:Autonomous floor-cleaning and window-washing platforms integrate rotating brush assemblies with LIDAR-based room mapping. China's consumer segment concentrates demand in Shanghai and Shenzhen, where residential tower density justifies compact form factors.
- Telepresence:Remote-controlled mobile screens with two-way audio enable distributed workforce participation and eldercare check-ins. Japanese prefectural hospitals in Kanagawa and Osaka deploy these for specialist consultations, driven by METI efficiency mandates requiring documented operational cost reductions.
- Delivery:Last-mile autonomous vehicles with insulated compartments serve food and retail logistics.
- Security:Patrol robots with thermal imaging and acoustic anomaly detection monitor perimeters.
Housekeeping sits at the top of the volume ranking, with Delivery climbing the fastest.
End User:
Customer procurement maturity determines whether vendors compete on upfront hardware cost or lifecycle service contracts.
- Healthcare:Surgical support and rehabilitation platforms require MFDS clinical validation in South Korea and PMDA pathways in Japan. Seoul and Busan hospital networks standardize five-year total cost of ownership models, unbundling after-sales service from hardware acquisition.
- Hospitality:Concierge and room-service robots operate in high-traffic lobbies and corridors. Singapore's integrated resort operators deploy these for guest-facing interactions, prioritizing multilingual natural language processing capabilities.
- Retail:Inventory scanning and customer guidance systems automate shelf monitoring.
- Education:Programmable platforms teach coding and robotics fundamentals in classroom settings.
Healthcare dominates procurement value, with Hospitality expanding most quickly as tourism infrastructure recovers.
Technology:
Margin concentration follows where proprietary algorithmic differentiation creates switching costs.
- AI:Edge-deployed neural networks enable real-time decision-making without cloud dependency. Kanagawa Prefecture eldercare operators pilot integrated perception stacks for nighttime patient monitoring, leveraging compressed compute-to-sensor latency.
- Navigation Systems:Centimeter-level GPS-RTK positioning and LIDAR-based SLAM enable outdoor and dynamic indoor operation. The Yangtze River Delta manufacturing corridor generates concentrated demand as logistics operators seek fleet coordination across warehouse and yard environments.
- Machine Learning:Continuous improvement loops refine object recognition and path planning from operational data.
- Sensor Technologies:Multi-spectral fusion modules combine visual, thermal, and depth sensing for obstacle classification.
Navigation Systems commands the steepest expansion trajectory, with Sensor Technologies anchoring premium tier pricing.
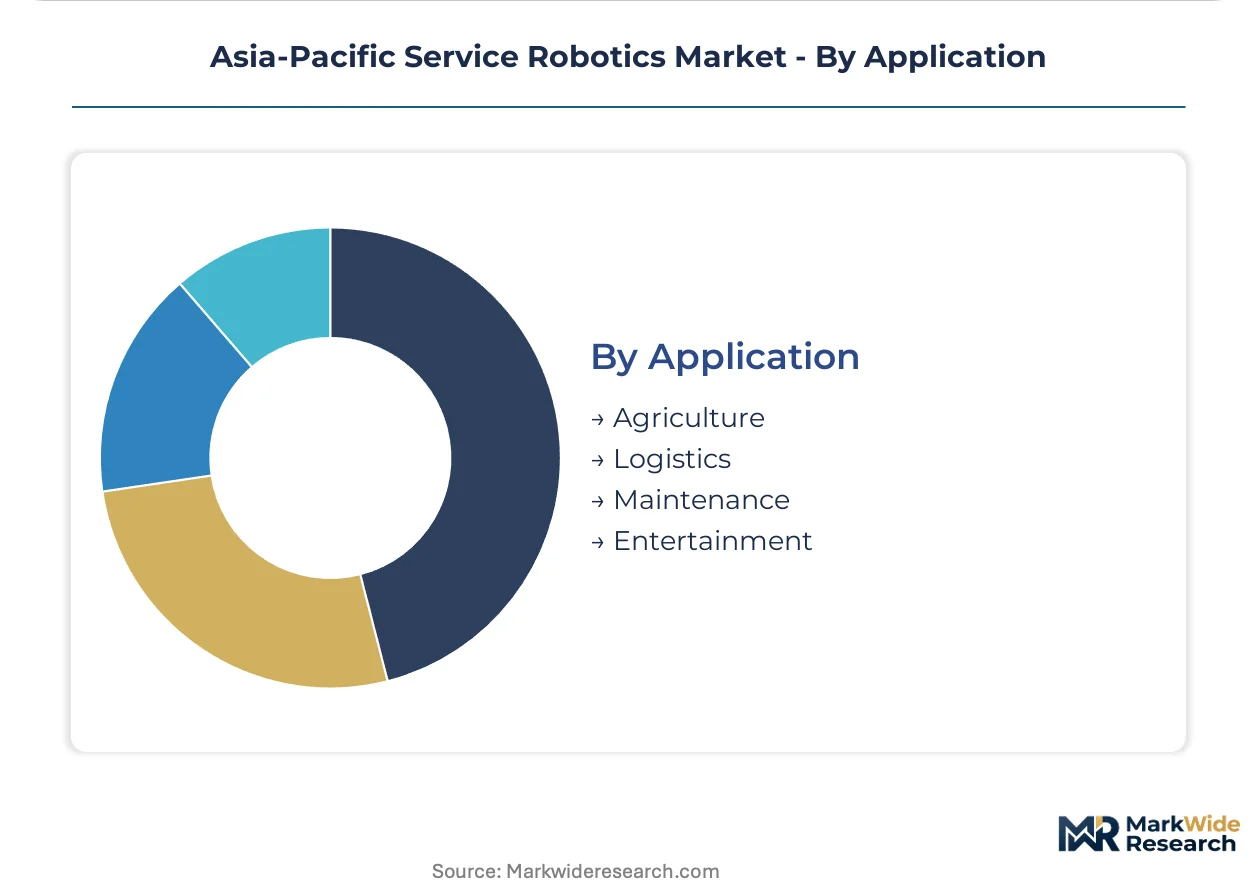
Application:
Geographic terrain compatibility and labor cost arbitrage shape deployment economics across use cases.
- Agriculture:Autonomous tractors and harvesting platforms navigate uneven terrain with RTK-GPS guidance. Indonesia's palm oil and rice cultivation operations remain manual-dependent despite platform availability, creating latent demand as labor costs rise.
- Logistics:Heavy-payload autonomous mobile robots transport materials between warehouse zones. Suzhou and Hangzhou industrial operators front-load SAMR GB certification investments as safety-critical thresholds drop from 100 kg to 50 kg rated payloads.
- Maintenance:Inspection robots assess infrastructure condition in hazardous or confined spaces.
- Entertainment:Animatronic and interactive performers animate theme parks and exhibitions.
Logistics leads current deployment volume, with Agriculture gaining share fastest as terrain-adaptive platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta manufacturing corridor concentrates the highest deployment density of autonomous logistics platforms in the Asia-Pacific region. China's dual carbon goals and Japan's METI robotics roadmaps are tightening efficiency standards across national certification regimes. South Korea's MFDS clinical validation pathways and evolving GB standards from China's SAMR create divergent compliance timelines for cross-border platform architectures.
China
Suzhou and Hangzhou industrial operators are front-loading SAMR GB certification investments as safety-critical payload thresholds drop from 100 kg to 50 kg. The dual carbon goals mandate efficiency improvements for autonomous warehouse fleets operating across the Yangtze River Delta corridor. Shanghai and Shenzhen residential tower density sustains concentrated demand for compact housekeeping robot form factors in the consumer segment.
Japan
Osaka and Tokyo prefectures are accelerating deployment permits for eldercare facilities under METI JIS safety standards for human-robot collaborative environments. Kanagawa Prefecture operators pilot integrated perception stacks for nighttime patient monitoring in hospital settings. Prefectural hospital systems now require documented operational cost reductions for capital approvals under efficiency mandates.
South Korea
Seoul and Busan hospital networks standardize five-year total cost of ownership models for surgical support platforms, unbundling after-sales service from hardware acquisition. MFDS regulates healthcare robot clinical validation pathways, extending product development timelines for medical applications. Hanwha Robotics leverages in-house actuator production to sustain margin control across industrial deployments.
Singapore
Integrated resort operators deploy concierge and room-service robots for guest-facing interactions, prioritizing multilingual natural language processing capabilities. The city-state's procurement maturity enables vendors to compete on lifecycle service contracts rather than upfront hardware cost alone. Tourism infrastructure recovery is expanding hospitality robot deployment faster than regional peers.
Indonesia
Palm oil and rice cultivation operations remain dependent on manual labor despite terrain-compatible autonomous platform availability for agricultural automation. Labor cost arbitrage is narrowing as platform economics improve for uneven terrain navigation with RTK-GPS guidance. The agricultural automation gap represents latent demand as regional labor markets tighten.
Asia-Pacific Service Robotics Market Competitive Landscape
Global majors compete with regional champions across certification regimes and channel control dimensions in the Asia-Pacific service robotics market. The vendor base separates into three tiers: integrated conglomerates with captive component supply, specialized platform builders with dominant segment positions, and emerging challengers seeking scale through manufacturing partnerships. Two dominant competitive moves are reshaping positioning: backward integration into actuator and sensor production to defend margin structures, and geographic expansion through dual-certification strategies for Japan-South Korea healthcare convergence.
Among South Korean industrial automation specialists, Hanwha Robotics and Hyundai Robotics Co. Ltd. exemplify the captive supply archetype through in-house production capabilities. Chinese platform builders Ecovacs Robotics Co Ltd and UBTECH Robotics Inc. anchor the consumer-facing and humanoid segments respectively, while SIASUN Robot & Automation Co Ltd represents scale-driven manufacturing for heavy-payload logistics applications. These named entities occupy positions that reflect broader structural patterns in regional competitive dynamics rather than isolated strategic choices.
| Leading Market Players |
|---|
| Hanwha Robotics |
| SIASUN Robot & Automation Co Ltd |
| LG Electronics Inc. |
| SoftBank Corp. |
| Omron Corporation |
| UBTECH Robotics Inc. |
| Ecovacs Robotics Co Ltd |
| Milagrow HumanTech |
| Hyundai Robotics Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals gate both qualified component supply and premium-tier pricing access for autonomous systems, as efficiency-certified suppliers command material premiums while uncertified manufacturers face exclusion from Yangtze River Delta procurement programs. This environmental mandate reshapes buyer-seller power dynamics across the Asia-Pacific service robotics value chain.
Pricing Analysis
Input-cost pass-through from high-precision sensor modules concentrates in premium navigation system tiers, where multi-spectral fusion hardware commands margin pools that standard LIDAR configurations cannot match. Pricing stratifies across premium, standard, and economy tiers based on certification grade under Japan's METI JIS standards and volume scale for fleet deployments. Cost compression in mid-tier systems is intensifying because Chinese industrial buyers unbundle after-sales service contracts and demand transparent five-year total cost of ownership models. Healthcare procurement committees in Seoul and Busan exhibit the least price sensitivity, while Indonesian agricultural operators remain the most cost-constrained buyer segment.
Supply Chain Analysis
Single-source vulnerability sits with South Korean actuator production, where Hanwha Robotics and Hyundai Robotics maintain captive in-house capabilities that limit component access for smaller platform builders. Manufacturing concentration centers on China, South Korea, and Japan for LIDAR sensors, precision gearboxes, and edge AI processors. The supply chain rests on lithium-ion battery cells, aluminum alloy chassis materials, and multi-spectral camera modules. Tariff exposure between Japan and South Korea on precision components creates regulatory risk for cross-border healthcare robot architectures. Distribution runs through direct enterprise sales for industrial applications and dominant e-commerce platforms for China's consumer segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on lightweight aluminum alloy substitution reducing power consumption costs and extending operational range premiums for logistics fleet operators.
For Market Incumbents: Anchor market position through backward integration into sensor fusion module production, defending against emerging Chinese platform builders leveraging manufacturing scale. Deepen certification investments under evolving SAMR GB standards to preempt compliance-driven customer switching. Prioritize channel control in the Yangtze River Delta corridor where logistics operator procurement concentrates. For New Entrants and Emerging Players: Launch via hardware-as-a-service subscription models targeting Vietnamese electronics assembly facilities lacking automated material handling density. Exploit Indonesia's agricultural automation gap in palm oil and rice cultivation operations where terrain-compatible platforms face limited competition. Pursue dual-certification strategies for Japan-South Korea healthcare convergence to capture first-mover advantages in surgical support and rehabilitation platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier navigation system specialists lacking proprietary SLAM algorithm portfolios but holding established manufacturing partnerships. Long-term viability over the projection horizon favors targets with demonstrated SAMR or METI certification traction and recurring service revenue streams. Monitor GB standard threshold reductions from 100 kg to 50 kg rated payloads as the inflection signal for heavy-payload logistics platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | Accelerates market access across Japan's METI JIS and South Korea's MFDS regulatory regimes. |
| Actuator Production Integration | Defends margin structures against supply concentration at Hanwha Robotics and Hyundai Robotics. |
| GB Standard Pre-Compliance | Prevents retroactive platform modifications as SAMR tightens autonomous navigation requirements. |
| Hardware-as-a-Service Launch | Aligns with Seoul and Busan hospital networks unbundling after-sales service from hardware acquisition. |
| Indonesian Agricultural Partnership | Captures latent demand as palm oil labor cost arbitrage narrows against RTK-GPS platform economics. |
Research Methodology
Bottom-up healthcare and logistics end-use modeling reconciled against top-down component supply tracking forms the analytical core of this study. Primary interviews with robotics platform engineers, hospital procurement managers, industrial automation directors, and SAMR certification consultants combined with secondary validation from METI robotics roadmap disclosures, MFDS clinical validation databases, and Yangtze River Delta industrial park deployment records. Triangulation between demand-side operator interviews and supply-side manufacturer capacity assessments ensures segmentation integrity.
Input-output matrix framing connects sensor technology cost curves, battery energy density improvements, and regulatory recertification timelines to deployment volume projections across the analysis window. Segmentation dimensions modeled include service type, end-user industry, technology tier, and application terrain compatibility, with CAGRs derived from replacement cycle analysis and penetration rate benchmarking. Forecast inputs incorporate SLAM navigation engineer availability constraints and legacy warehouse management system integration friction coefficients.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated GB standard enforcement or sudden Japan-South Korea trade policy shifts. Assumptions regarding aluminum alloy cost trajectories and RTK-GPS module price erosion inform the projection sensitivity bands. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Soft Exoskeleton Market
Robotics and Automation
Singapore Cloud Robotics Market
Robotics and Automation
Social Robots Market
Robotics and Automation
Bionic Glove's Market
Robotics and Automation
Robot for Public Service Market
Robotics and Automation
Palletizing Robots Market
Robotics and Automation
Articulated Robots for Injection Molding Machine Market
Robotics and Automation
Robotics End of Arm Tooling Market
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
SLAM Robots Market
Robotics and Automation
Waste Sorting Robots Market
Robotics and Automation
Consumer and Office Robot Market
Robotics and Automation
Global All Terrain Robots Market
Robotics and Automation
Food Robotics Market
Robotics and Automation
Europe Warehouse Robotics Market
Robotics and Automation
Cyber-Physical System Market