
 Cloud Orchestration Market | 2026-2036
Cloud Orchestration Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Orchestration Market Intelligence
Financial services is consolidating its share of cloud orchestration spending as institutions replace fragmented point tools with unified control planes. Kubernetes anchors the container-native segment through its open-source ecosystem dominance and native integration with major hyperscalers. Red Hat Ansible competes in the configuration-management layer by sustaining enterprise adoption across regulated industries. Terraform differentiates through infrastructure-as-code standardization that spans public and private cloud boundaries.
Cloud orchestration denotes the automated coordination, provisioning, and lifecycle management of computing workloads across distributed cloud environments using policy-driven controllers and API abstraction layers. The technology enables enterprises to enforce cost governance, security posture, and performance SLAs without manual intervention across heterogeneous infrastructure. Hybrid Cloud deployments command the largest current allocation of enterprise budgets as organizations retain sensitive workloads on-premises while bursting to public capacity. Kubernetes-based orchestration represents the fastest-expanding technology segment, displacing legacy hypervisor-centric tools in greenfield deployments. Managed Services within the service-type dimension captures expanding margin pools as skills scarcity drives outsourcing of platform operations.
The EU AI Act, GDPR, and NIS2 Directive collectively mandate auditable workload placement, data-residency enforcement, and incident-response automation that only policy-aware orchestration platforms can satisfy. In the United States, FedRAMP and NIST SP 800-53 frameworks shape federal procurement specifications, filtering vendor eligibility for government contracts. Stakeholders must evaluate whether their orchestration architecture can absorb emerging sovereign-cloud requirements without fragmenting operational consistency.
Market Dynamics
The Cloud Orchestration Market is being fundamentally restructured by the collision of multi-cloud sprawl with mandatory compliance automation. Financial institutions, hyperscalers, and federal agencies are forcing vendors to embed policy engines directly into control planes rather than layering governance atop existing tools.
Growth Catalysts
- FedRAMP Authorization:Federal cloud mandates in the United States are filtering vendor eligibility and accelerating procurement of compliant orchestration platforms by defense and civilian agencies.
- EU AI Act workload auditing:The European Union's artificial intelligence regulation mandates automated data residency enforcement that only policy-aware orchestration can satisfy.
- Container-native migration:Kubernetes is displacing legacy hypervisor-centric tools in greenfield deployments as enterprises standardize on cloud-native infrastructure.
Market Restraints
- Skills scarcity premium:Platform engineering expertise concentrates in hyperscaler hubs, inflating implementation costs for enterprises outside Seattle, San Francisco, and Northern Virginia.
- Hyperscaler lock-in risk:Native orchestration tools from Amazon Web Services, Microsoft Azure, and Google Cloud Platform create switching friction that deters multi-cloud standardization.
- Legacy integration debt:Mainframe and bare-metal workloads resist API abstraction, forcing hybrid architectures that fragment operational consistency.
Strategic Opportunities
- Sovereign cloud requirements:Germany's Gaia-X initiative and France's Cloud de Confiance are creating demand for EU-controlled orchestration layers that exclude non-European infrastructure.
- Managed service arbitrage:Skills gaps are pushing enterprises toward outsourced platform operations, expanding margin pools for service providers.
- FinOps convergence:The integration of cost governance with orchestration control planes is creating new product categories for cloud financial management.
Industry Challenges
- Platform engineering talent deficit:Kubernetes, Terraform, and policy-as-code expertise remains scarce relative to deployment demand, elongating implementation timelines.
- Cross-cloud identity federation:Harmonizing authentication across heterogeneous environments requires complex service mesh architectures that strain operational teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Orchestration Market |
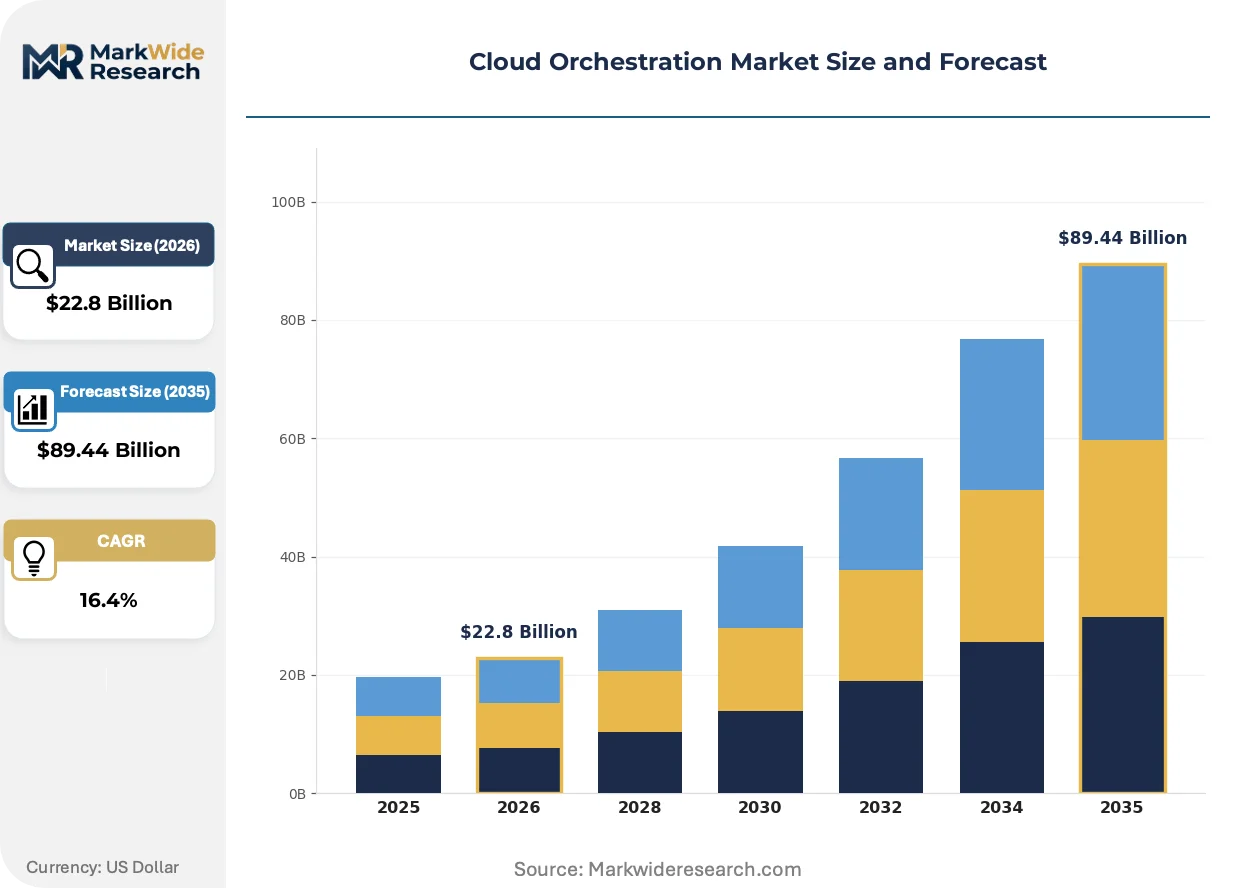
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $89.44 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Managed Services End User: Enterprises, Startups, Government Agencies, Educational Institutions Technology: Kubernetes, Docker, OpenStack, Apache Mesos |
| Companies Covered | Stonebranch, RunMyJobs, Kubernetes, CloudBolt, Morpheus Data, Red Hat Ansible, ActiveBatch, Turbonomic, Terraform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Orchestration Market Strategic Shifts & Innovations
Control plane unification is compressing the vendor stack as enterprises reject fragmented point tools. Three forces are actively reshaping product architecture, procurement patterns, and competitive positioning in cloud orchestration.
GitOps methodologies are unifying infrastructure state management with application deployment pipelines. Platform teams at regulated enterprises are adopting ArgoCD and Flux to enforce declarative configurations at scale. This convergence is collapsing the boundary between continuous delivery and infrastructure orchestration, forcing incumbent vendors to acquire or build GitOps capabilities.
The EU AI Act's risk-based classification system is mandating automated audit trails for high-risk AI workloads. Financial services and healthcare providers in the European Union must demonstrate data lineage and model provenance through orchestration-layer logging. German automotive manufacturers and French insurance groups are prioritizing vendors with built-in compliance evidence generation.
FinOps discipline is embedding cost accountability into engineering workflows through orchestration-integrated showback mechanisms. Cloud centers of excellence are replacing manual budget reviews with automated policy enforcement that blocks over-provisioning at deployment time. This behavioral shift is most visible in United States technology and media companies where usage-based pricing volatility has triggered C-level intervention.
Cloud Orchestration Market Segmentation
Cloud orchestration procurement patterns diverge sharply across deployment models, service tiers, and organizational maturity levels. Capital allocation decisions in this market hinge on compliance exposure, workload sensitivity, and in-house platform engineering depth rather than unit economics alone.
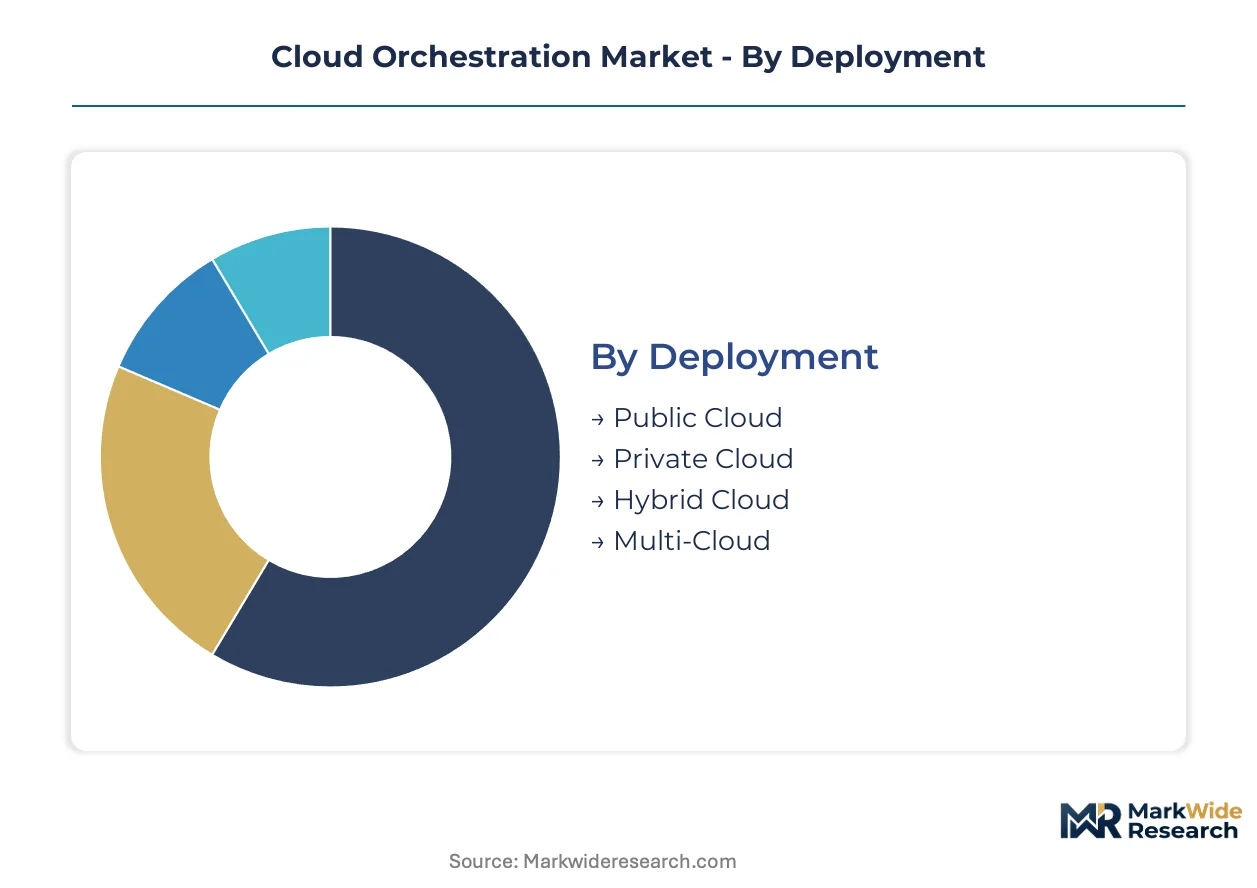
Deployment:
Hybrid Cloud configurations demand the heaviest upfront capital commitment due to dual-stack infrastructure requirements and specialized integration labor.
- Public Cloud:Delivers orchestration through hyperscaler-native control planes with consumption-based pricing. Financial services firms in the United States favor this model for non-sensitive workloads to satisfy FedRAMP authorization timelines without自建 infrastructure.
- Hybrid Cloud:Combines on-premises orchestration layers with public cloud bursting capacity via unified policy engines. German automotive manufacturers and French insurance groups prioritize this architecture to meet EU AI Act data residency mandates while retaining elastic compute access.
- Private Cloud:Restricts orchestration to dedicated infrastructure within organizational boundaries. Defense agencies and sovereign cloud initiatives absorb capacity here.
- Multi-Cloud:Distributes orchestration across two or more hyperscalers to mitigate concentration risk. Enterprises with mature platform engineering teams adopt this model despite operational complexity.
Hybrid Cloud absorbs the bulk of installed capacity; Multi-Cloud is expanding most quickly as vendor diversification becomes a board-level priority.
Service Type:
Margin structures in this category invert traditional software economics, with human-capital-intensive offerings commanding premium pricing over standardized infrastructure layers.
- Managed Services:Outsourced platform operations including 24/7 orchestration layer monitoring, patch management, and policy tuning. Skills scarcity in Seattle, San Francisco, and Northern Virginia has inflated pricing for these engagements as enterprises bypass internal hiring.
- Platform as a Service:Abstracted orchestration control planes with pre-integrated compliance tooling and CI/CD pipelines. Regulated industries in the European Union gravitate toward PaaS offerings with built-in GDPR and NIS2 Directive evidence generation.
- Infrastructure as a Service:Raw compute and storage resources with customer-managed orchestration tooling. Cost-conscious startups and mid-market enterprises dominate demand here.
- Software as a Service:Pre-configured orchestration applications delivered through browser interfaces with minimal customization. Educational institutions and small government agencies standardize on this consumption model.
Managed Services captures the steepest margin expansion; Platform as a Service is climbing the fastest as compliance automation becomes non-negotiable.
End User:
Procurement sophistication correlates directly with regulatory scrutiny exposure and available technical staffing budgets.
- Enterprises:Large organizations with dedicated cloud centers of excellence and multi-million-dollar annual orchestration budgets. United States technology and media companies drive FinOps-integrated tooling demand to curb usage-based pricing volatility.
- Government Agencies:Federal, state, and municipal entities with mandatory compliance frameworks and extended procurement cycles. FedRAMP authorization requirements filter vendor eligibility aggressively in this segment.
- Startups:Venture-backed and bootstrapped companies prioritizing speed-to-market over architectural control. Native hyperscaler tooling dominates here due to minimal upfront investment requirements.
- Educational Institutions:Universities and research organizations with episodic compute demand and constrained IT budgets. Grant-funded projects often dictate technology selection in this segment.
Enterprises command the largest absolute spending; Government Agencies are scaling fastest as federal cloud mandates accelerate procurement timelines.
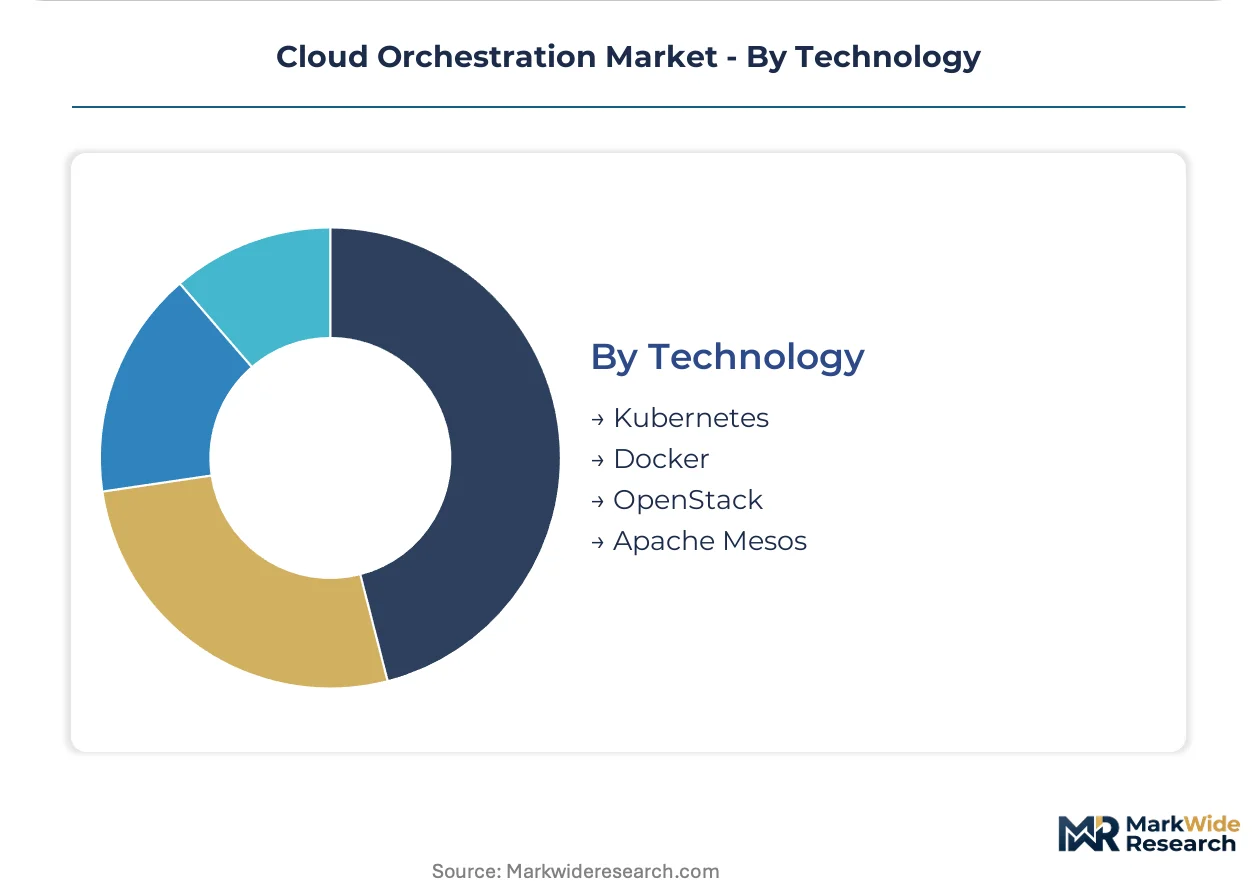
Technology:
Adoption trajectories in this category reflect ecosystem maturity, certification density, and hyperscaler integration depth rather than raw technical capability.
- Kubernetes:Container orchestration platform with native integration across Amazon Web Services, Microsoft Azure, and Google Cloud Platform. Greenfield deployments in financial services and healthcare increasingly standardize on Kubernetes-based control planes.
- Docker:Container runtime technology with simplified developer experience and broad IDE integration. Startups and mid-market enterprises favor Docker for rapid application packaging without platform engineering overhead.
- OpenStack:Open-source cloud operating system for private cloud orchestration with extensive customization options. Telecom operators and national research networks maintain significant deployments.
- Apache Mesos:Distributed systems kernel with two-level scheduling architecture for specialized workload types. Legacy installations persist in high-performance computing environments.
Kubernetes anchors the dominant share of new deployments; Docker maintains the broadest developer adoption despite narrower orchestration scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler concentration in Northern Virginia's data center corridor concentrates procurement authority for orchestration platforms. Federal cloud mandates and EU regulatory pressure are redistributing deployment patterns across national boundaries.
United States
Defense and civilian agencies drive FedRAMP-authorized platform procurement through extended federal cloud mandates. NIST SP 800-53 frameworks filter vendor eligibility aggressively for government contracts. The Northern Virginia cluster anchors hyperscaler density, with Seattle and San Francisco maintaining platform engineering talent pools.
Germany
Automotive manufacturers and industrial conglomerates prioritize hybrid architectures for EU AI Act data residency compliance. The Gaia-X initiative mandates EU-controlled orchestration layers excluding non-European infrastructure. Bavaria's industrial automation sector and Frankfurt's financial hub concentrate policy-aware platform demand.
France
Insurance groups and healthcare providers require automated audit trails for high-risk AI workload classification under EU AI Act risk tiers. The Cloud de Confiance initiative accelerates sovereign cloud procurement specifications. Paris-based financial institutions and Lyon healthcare clusters dominate compliance-embedded platform adoption.
United Kingdom
Financial services firms replace fragmented point tools with unified control planes amid post-Brexit regulatory divergence. The Financial Conduct Authority's operational resilience requirements shape procurement timelines for critical infrastructure. London's fintech corridor and Edinburgh banking centers drive Kubernetes-based orchestration standardization.
India
IT services exporters and domestic financial institutions expand multi-cloud deployments to satisfy data localization under RBI guidelines. The MeitY's cloud adoption framework for government departments creates public sector demand. Bangalore's technology parks and Mumbai's financial district concentrate platform engineering talent and procurement authority.
Cloud Orchestration Market Key Industry Players
Top-tier vendors anchor the hyperscaler-native layer, while independent orchestration specialists occupy the multi-cloud abstraction tier. The market structure stratifies across three distinct competitive planes: infrastructure control planes, configuration management engines, and policy governance overlays. Strategic archetypes include open-source ecosystem anchors, enterprise configuration managers, and compliance-embedded platform builders. Competitive moves concentrate on acquiring GitOps capabilities and embedding FinOps cost governance directly into control plane architectures.
Among open-source ecosystem anchors, Kubernetes exemplifies container-native orchestration dominance through hyperscaler integration depth. Red Hat Ansible occupies the configuration management tier with sustained enterprise adoption across regulated industries. Terraform represents infrastructure-as-code standardization that spans public and private cloud boundaries without vendor lock-in.
| Leading Market Players |
|---|
| Stonebranch |
| RunMyJobs |
| Kubernetes |
| CloudBolt |
| Morpheus Data |
| Red Hat Ansible |
| ActiveBatch |
| Turbonomic |
| Terraform |
| Others |
Cost & Logistics Intelligence
Platform engineering labor costs in Seattle, San Francisco, and Northern Virginia cascade through orchestration pricing tiers as enterprises absorb 40-60% implementation premiums for scarce Kubernetes and Terraform expertise. This human-capital bottleneck stratifies vendor offerings across premium managed services, standard platform subscriptions, and economy self-managed tiers.
Pricing Analysis
Short lead-time deployments command 25-35% premiums over standard provisioning cycles as enterprises pay for accelerated FedRAMP authorization pathways or EU AI Act compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with FedRAMP-authorized and GDPR-embedded platforms capturing the top tier. Pricing pressure stems from hyperscaler-native tool bundling that commoditizes basic orchestration layers. Startups exhibit highest price sensitivity; defense agencies and EU-regulated financial institutions demonstrate lowest sensitivity due to mandatory compliance requirements.
Supply Chain Analysis
Dual-sourcing requirements from United States federal procurement guidelines and EU sovereign cloud mandates force enterprises to qualify orchestration vendors across both hyperscaler-native and independent multi-cloud abstraction tiers. Supply concentrates in the United States, Germany, and India, with Northern Virginia hyperscaler density, Frankfurt financial infrastructure, and Bangalore platform engineering talent anchoring regional clusters. Raw material dependencies include open-source Kubernetes distributions, Terraform provider ecosystems, and policy-as-code enforcement engines. Single-source vulnerability risks emerge where enterprises rely exclusively on AWS, Azure, or Google Cloud native tooling without portable abstraction layers. Distribution runs through direct enterprise sales for regulated verticals, hyperscaler marketplaces for mid-market adoption, and systems integrators for complex hybrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cloud Orchestration Market functions as a cost-of-compliance arena where EU AI Act audit-trail mandates erect steep technical barriers that filter out undercapitalized entrants. This regulatory moat rewards vendors with pre-embedded governance engines and punishes point-tool assemblers.
For Market Incumbents: Acquire GitOps-native platform capabilities to collapse the boundary between continuous delivery and infrastructure orchestration. Consolidate position by embedding FinOps cost governance directly into control plane architectures before independent specialists capture this convergence. Threats include hyperscaler vertical integration into managed Kubernetes layers and emerging policy-as-code startups unseating configuration management incumbents. For New Entrants and Emerging Players: Channel partners specializing in EU sovereign cloud certification represent the most penetrable on-ramp for unproven orchestration vendors. Target Germany's Gaia-X initiative and France's Cloud de Confiance procurement pipelines where incumbent tooling lacks EU-controlled infrastructure exclusion capabilities. White-space opportunities concentrate in automated compliance evidence generation for high-risk AI workload classification and sovereign-cloud orchestration layers excluding non-European infrastructure. For Investors and Strategic Acquirers: FedRAMP authorization timelines compressing below historical averages is the leading indicator that federal procurement velocity is accelerating and compliant vendor valuations will detach from generalist comparables. Long-term viability favors platform builders with embedded policy engines over configuration-management tool vendors facing convergence pressure. Acquisition target archetype: mid-cap orchestration specialists with existing FedRAMP or EU AI Act certification infrastructure and recurring managed services revenue above 60% of total. Signal to watch: C-level intervention on cloud cost volatility triggering mandatory FinOps-integrated procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Policy Engine Acquisition | GitOps and policy-as-code capabilities collapse delivery-orchestration boundaries for regulated enterprises. |
| FedRAMP Fast-Track Investment | Compressed federal authorization timelines filter vendor eligibility and accelerate compliant platform procurement. |
| EU Sovereign Cloud Partnership | Gaia-X and Cloud de Confiance alignment excludes non-European infrastructure from sensitive workload placement. |
| FinOps Control Plane Integration | Automated cost governance at deployment time replaces manual budget reviews in United States technology enterprises. |
| Managed Services Margin Expansion | Skills scarcity in Seattle, San Francisco, and Northern Virginia inflates pricing for outsourced platform operations. |
Research Approach
Independent corroboration across platform engineering directors, cloud center-of-excellence leads, federal procurement officers, and systems integration architects underwrites the qualitative findings in this analysis. Primary fieldwork combined structured interviews with secondary validation through hyperscaler capex disclosures, FedRAMP authorization databases, EU regulatory filings, and SEC 10-K infrastructure software segments. Bottom-up deployment sizing and top-down vendor revenue triangulation anchored market estimates.
Comparable-period anchoring to historical orchestration adoption curves established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include deployment architecture, service tier, organization maturity, technology stack, and regional regulatory cluster. CAGRs derived from diffusion-rate analysis of Kubernetes displacement patterns and compliance-mandated procurement acceleration. Forecast inputs incorporated sovereign cloud initiative timelines and federal cloud mandate implementation velocity.
Caveats apply where EU AI Act enforcement intensity or FedRAMP authorization standard revisions could materially shift the outlook. Forecasts reflect assumptions about skills scarcity persistence and hyperscaler pricing discipline. A model refresh is warranted upon material change in federal procurement velocity or sovereign cloud mandate scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Managed Networking Market
Cloud Computing
Cloud Database Market
Cloud Computing
AI Platform Cloud Service Market
Cloud Computing
Cloud Systems Management Software Market
Cloud Computing
Healthcare Cloud Computing Software Market
Cloud Computing
Cloud Enterprise Content Management Market
Cloud Computing
Hybrid Cloud in BFSI Market
Cloud Computing
Government Cloud Computing Market
Cloud Computing
Multi-Cloud Architecture Market
Cloud Computing
VM Service Market
Cloud Computing
Asia-Pacific Mobile Cloud Market
Cloud Computing
Government Cloud Market
Cloud Computing
Cloud Directory Services Market
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Cloud ELN Service Market
Cloud Computing
Spain Cloud Computing Market