
 Global Robot Software Market | 2026-2036
Global Robot Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Robot Software Market Foresight
North American venture funding for robot software developers is hardening as capital flows toward production-ready platforms rather than early-stage concepts. ABB Robotics leverages its European industrial base to sustain leadership in control software for manufacturing environments. Amazon Robotics anchors logistics automation through proprietary fleet management systems, while FANUC competes via deep specialization in CNC-integrated robot programming for precision tasks.
Robot software encompasses the programs, algorithms, and middleware that govern perception, motion planning, task execution, and system coordination in robotic platforms, typically operating through real-time operating systems with sub-millisecond loop closure for safety-critical functions. Its primary purpose is to translate high-level operational commands into precise electromechanical actions across industrial, commercial, and field-deployed machines. Simulation software leads deployment volumes as manufacturers validate digital twins before physical commissioning, while artificial intelligence modules represent the fastest-expanding margin pool as machine learning replaces hard-coded heuristics. Cloud-based deployment models are gaining traction in logistics automation, though on-premise installations still dominate pharmaceutical production due to data sovereignty requirements.
The EU AI Act classifies autonomous robots by risk tier, directly shaping product development roadmaps for vendors seeking European market access. FDA guidance on software-as-a-medical-device and ISO 13482 for personal care robots create parallel compliance tracks in the United States and internationally. Japan's METI promotes next-generation robotics through JIS standards harmonization with IEC 61508 functional safety protocols. Stakeholders must monitor how divergent regulatory timelines across Washington, Brussels, and Tokyo fragment certification requirements and reshape competitive positioning.
Market Dynamics
The central structural force in robot software is the migration from deterministic control logic to probabilistic AI-driven architectures, driven by EU AI Act risk-tier classifications that mandate explainability for high-risk autonomous systems.
Growth Catalysts
- EU AI Act Risk Framework:Tiered compliance requirements for autonomous robots are accelerating investment in certified software stacks among manufacturers seeking European market access.
- Automotive Assembly Automation:German and Japanese manufacturers are deploying advanced motion planning algorithms for precision welding and component placement in electric vehicle production lines.
- Digital Twin Validation:Simulation software adoption is expanding as manufacturers reduce physical commissioning cycles through virtual environment testing before deployment.
Market Restraints
- Semiconductor Supply Concentration:Taiwan and South Korea dominate the advanced chip fabrication required for real-time robot controllers, creating vulnerability in hardware-software integration timelines.
- Data Sovereignty Requirements:Pharmaceutical production facilities in Switzerland and Germany mandate on-premise software installations, limiting cloud-based deployment scalability.
- Functional Safety Certification Costs:ISO 10218 and IEC 61508 compliance testing for safety-critical motion control extends product development cycles by 12-18 months.
Strategic Opportunities
- India Manufacturing Automation:PLI scheme incentives for electronics and automotive production are creating first-mover advantages for robot software vendors establishing localized support infrastructure.
- Edge-AI Convergence:Integration of embedded neural processing units with traditional PLC architectures enables real-time decision-making without cloud dependency in warehouse robotics.
- Subscription Licensing Models:Per-robot monthly software fees are displacing perpetual licenses in logistics automation, improving vendor recurring revenue predictability.
Industry Challenges
- Control Systems Engineering Talent:Shortage of engineers proficient in both real-time operating systems and machine learning deployment is constraining product development velocity.
- Legacy Equipment Integration:Retrofitting 1990s-era CNC machines with modern robot coordination software requires custom middleware development that erodes project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Robot Software Market |
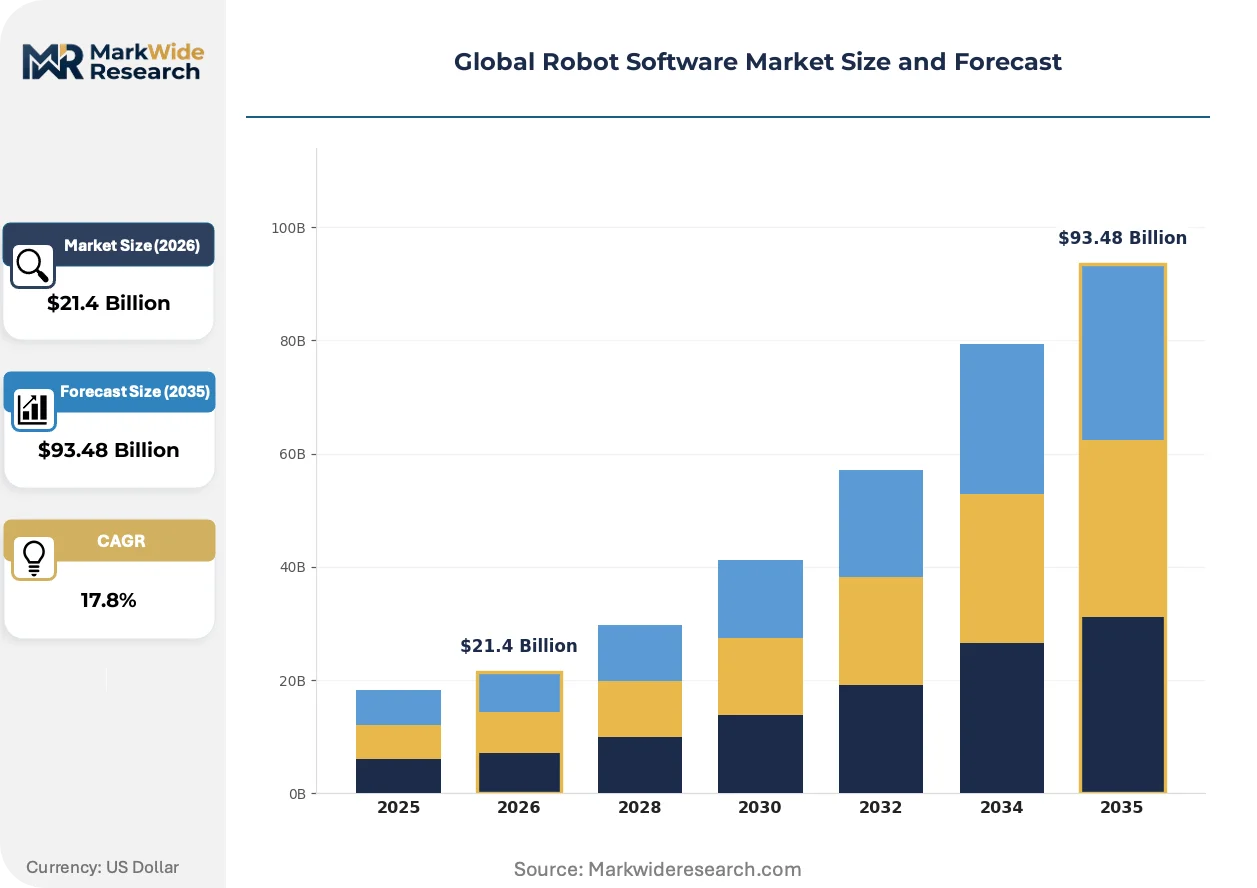
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $93.48 Billion |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Simulation, Control, Artificial Intelligence, Middleware, Programming, Analytics Deployment Model: Cloud-Based, On-Premise, Hybrid, Edge Computing, Subscription, Perpetual License Application: Assembly Automation, Logistics Automation, Precision Agriculture, Mining Operations, Inspection Tasks, Research & Development End User Industry: Consumer Electronics Manufacturers, Aerospace Engineering, Pharmaceutical Production, Food Processing Plants, Construction Firms, Telecommunications Equipment |
| Companies Covered | Amazon Robotics, Zebra Technologies, Skild AI, FANUC, ABB Robotics, Figure AI, Geek+, Universal Robots, Physical Intelligence, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Robot Software Market Shifts & Advancements
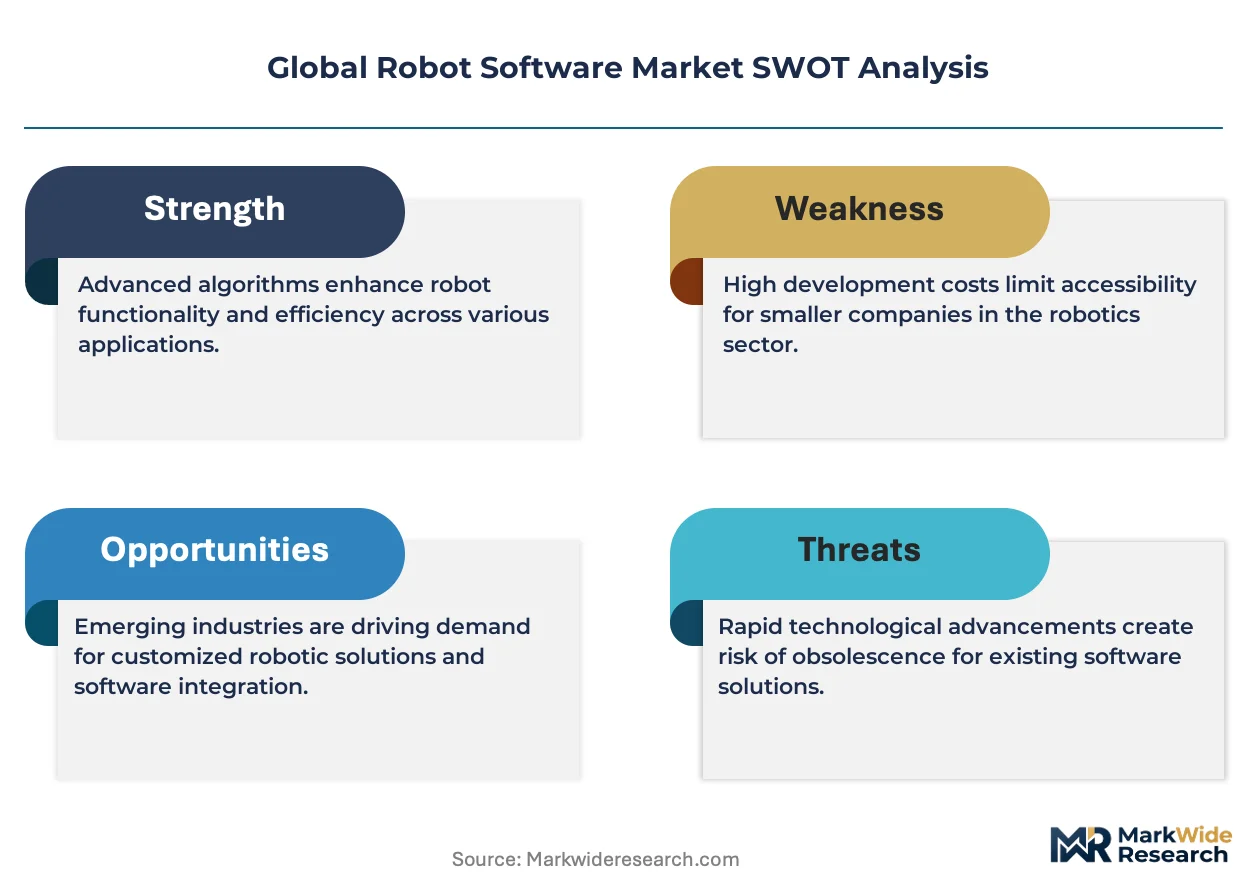
Robot software architecture is undergoing fundamental restructuring as deterministic control systems absorb probabilistic AI methods, while regulatory fragmentation across Washington, Brussels, and Tokyo forces vendors to maintain parallel compliance tracks.
Reinforcement learning-based motion planning is converging with traditional trajectory optimization in industrial robot controllers. Automotive manufacturers in Stuttgart and Toyota City are piloting these hybrid systems for adaptive assembly tasks. This convergence is compressing the competitive advantage window for pure-play simulation vendors as integrated platforms absorb their functionality.
The EU AI Act's high-risk classification for collaborative robots is mandating algorithmic audit trails and human oversight interfaces. Industrial software vendors must now embed logging capabilities that satisfy Brussels conformity assessment bodies. German automation suppliers are responding fastest, leveraging existing ISO 10218 safety documentation to streamline AI Act compliance.
Buyer procurement patterns are consolidating around platform vendors offering unified perception, planning, and execution stacks. Third-party point solution providers face displacement as end-users in Pittsburgh and Boston robotics clusters prioritize single-vendor accountability. This consolidation is most visible in warehouse automation, where Amazon Robotics' integrated fleet management has reshaped vendor selection criteria.
Global Robot Software Market Segmentation
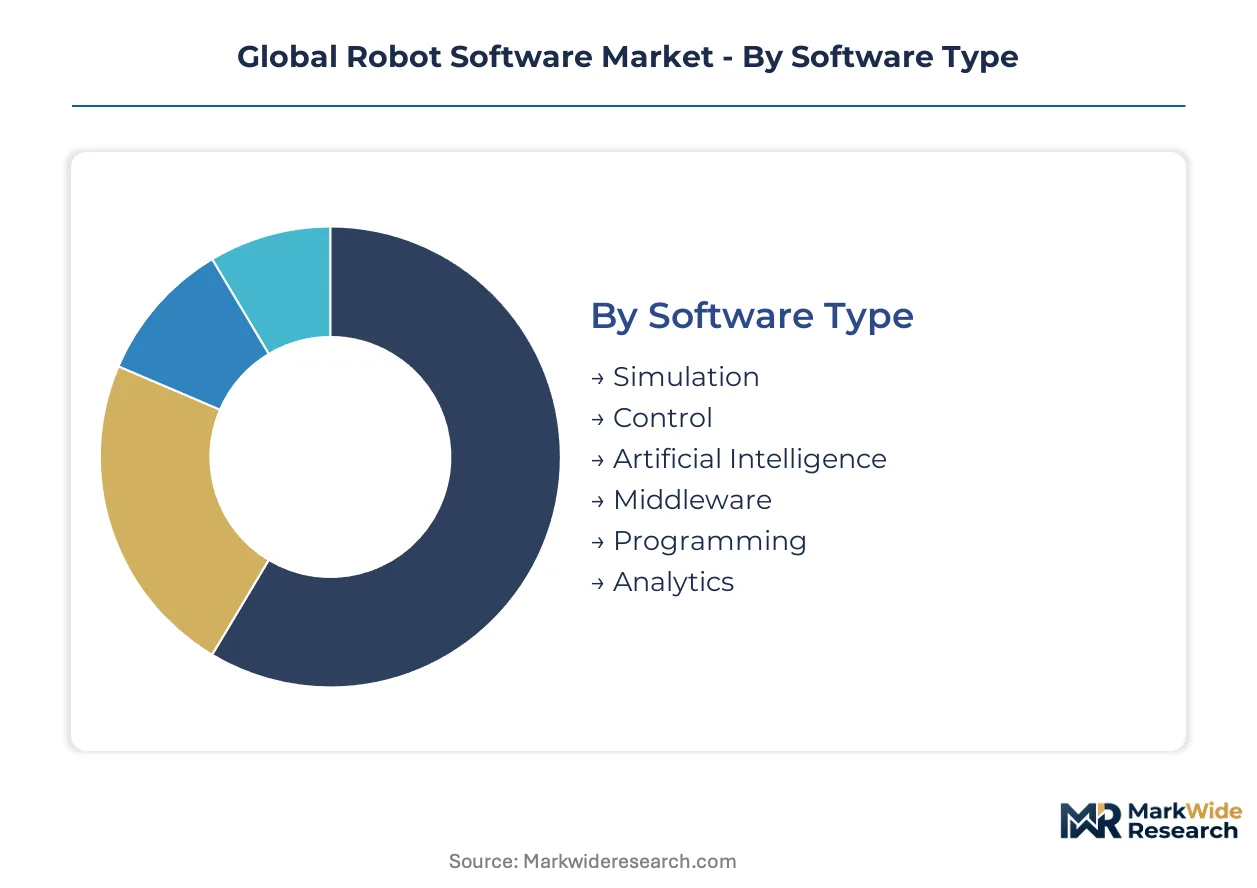
Robot software purchasing decisions hinge on deployment constraints, regulatory exposure, and integration complexity rather than feature lists alone. Buyers evaluate stacks through total cost of ownership lenses that weight certification overhead against operational flexibility.
Software Type:
Procurement teams prioritize certification velocity and integration risk when selecting software layers, with simulation and AI modules commanding premium evaluation cycles.
- Simulation:Digital twin platforms enable virtual commissioning of robot workcells before physical deployment. Automotive manufacturers in Germany and Japan rely on these tools to compress EV production line validation timelines. Volume sits with simulation; growth tilts toward artificial intelligence.
- Artificial Intelligence:Machine learning modules replace hard-coded heuristics for adaptive motion planning and perception tasks. EU AI Act explainability requirements are reshaping vendor development roadmaps for high-risk autonomous systems.
- Control:Real-time operating systems with sub-millisecond loop closure govern electromechanical execution in safety-critical functions.
- Middleware:Communication layers bridge heterogeneous hardware protocols and enterprise IT systems.
- Programming:Offline development environments and teach pendant interfaces reduce deployment engineering hours.
- Analytics:Performance monitoring and predictive maintenance dashboards extract operational intelligence from robot fleets.
Simulation dominates deployment volumes as manufacturers validate digital twins; AI modules capture the steepest expansion trajectory as probabilistic methods displace deterministic control.
Deployment Model:
Data sovereignty requirements and network latency tolerances split buyer preferences between cloud elasticity and local control.
- On-Premise:Installations within facility firewalls satisfy pharmaceutical production requirements in Switzerland and Germany. Swissmedic and national data protection authorities mandate local processing for sensitive manufacturing data.
- Cloud-Based:Centralized fleet management enables dynamic workload distribution across warehouse robotics operations. Logistics operators in the United States favor this model for scalability without capital intensity.
- Hybrid:Sensitive processing remains local while non-critical analytics flow to cloud infrastructure.
- Edge Computing:Embedded neural processing units enable real-time decision-making without network dependency.
- Subscription:Per-robot monthly fees improve vendor recurring revenue predictability in logistics automation.
- Perpetual License:One-time purchases with maintenance contracts dominate capital-intensive industrial deployments.
On-premise installations retain dominance in regulated manufacturing; cloud and edge configurations are expanding most quickly in warehouse automation.
Application:
Task complexity and safety certification burden determine software architecture selection across operational domains.
- Assembly Automation:Precision welding and component placement algorithms serve electric vehicle production lines. German automotive OEMs in Stuttgart deploy advanced motion planning for battery pack integration.
- Logistics Automation:Fleet coordination and path optimization manage high-throughput warehouse operations. Amazon Robotics anchors demand through proprietary systems in United States distribution centers.
- Precision Agriculture:Autonomous navigation and crop monitoring software reduce labor dependency in large-scale farming operations.
- Mining Operations:Harsh-environment durability requirements drive specialized middleware for remote equipment control.
- Inspection Tasks:Non-destructive testing and quality verification leverage computer vision pipelines.
- Research & Development:Academic and corporate labs prototype novel algorithms before commercial deployment.
Assembly automation commands the largest installed base; logistics applications are gaining share fastest as e-commerce fulfillment demands intensify.
End User Industry:
Regulatory exposure and production volume characteristics shape industry-specific software procurement patterns.
- Pharmaceutical Production:Batch traceability and cleanroom compliance requirements demand validated software stacks. FDA software-as-a-medical-device guidance and EU GMP Annex 11 create parallel compliance tracks for vendors.
- Consumer Electronics Manufacturers:High-mix, high-volume assembly drives demand for rapid reprogramming capabilities. Contract manufacturers in Shenzhen and Vietnam prioritize software flexibility for product changeovers.
- Aerospace Engineering:AS9100 quality standards and FAA traceability requirements extend certification timelines for specialized applications.
- Food Processing Plants:USDA and FDA sanitary design standards influence hardware-software integration specifications.
- Construction Firms:Outdoor positioning and safety perimeter management address unstructured environment challenges.
- Telecommunications Equipment:Precision fiber optic handling and small-batch customization require adaptive control algorithms.
Pharmaceutical and consumer electronics anchor current volumes; aerospace and telecommunications represent emerging demand concentrations as certification methodologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication in Taiwan and South Korea supplies the neural processing units embedded in robot controllers across Stuttgart, Boston, and Tokyo. German automotive OEMs consume precision motion planning algorithms for battery assembly. Japanese manufacturers integrate ISO 10218-compliant safety stacks into collaborative robot deployments.
United States
Logistics operators in Pittsburgh and Boston robotics clusters drive fleet management software procurement for warehouse automation. FDA software-as-a-medical-device guidance shapes compliance roadmaps for surgical robot developers. Amazon Robotics anchors proprietary demand through its distribution center network, while venture capital concentrates on production-ready platforms over early-stage concepts.
Germany
Automotive manufacturers in Stuttgart deploy advanced motion planning for electric vehicle battery pack integration. The EU AI Act's high-risk classification for collaborative robots mandates algorithmic audit trails and explainability features. ISO 10218 safety documentation from existing industrial deployments streamlines conformity assessment for German automation suppliers seeking Brussels market access.
Japan
Precision manufacturing in Toyota City and Nagoya drives CNC-integrated robot programming demand for assembly tasks. METI promotes next-generation robotics through JIS standards harmonization with IEC 61508 functional safety protocols. FANUC leverages deep specialization in motion control to sustain competitive positioning in automotive and electronics production lines.
China
Consumer electronics contract manufacturers in Shenzhen prioritize rapid reprogramming capabilities for high-mix assembly environments. MIIT industrial internet policies accelerate cloud-based fleet management adoption in logistics hubs. Domestic vendors compete with European and Japanese incumbents through localized support infrastructure and government-backed manufacturing automation incentives.
India
Electronics and automotive production incentives under the PLI scheme create first-mover opportunities for robot software vendors establishing localized engineering presence. BIS standards for industrial automation equipment shape certification requirements for imported control systems. Maharashtra and Gujarat manufacturing corridors concentrate demand for assembly automation in smartphone and component fabrication facilities.
Global Robot Software Market Competitive Landscape
Global majors compete with regional champions across certification velocity and integration risk dimensions. The vendor base organizes around three tiers: diversified industrial automation conglomerates with captive software stacks, pure-play robotics specialists, and emerging AI-native entrants. Two dominant competitive moves are reshaping positioning: strategic partnerships between hardware OEMs and cloud infrastructure providers, and portfolio diversification into subscription-based licensing models that displace perpetual sales.
Within the diversified industrial tier, ABB Robotics and FANUC exemplify European and Japanese incumbents leveraging manufacturing heritage to sustain control software leadership. Amazon Robotics occupies a position as the logistics automation anchor, reshaping procurement criteria through integrated fleet management systems. Among AI-native entrants, Figure AI and Physical Intelligence represent the emerging archetype of venture-backed developers targeting general-purpose robot intelligence architectures.
| Leading Market Players |
|---|
| Amazon Robotics |
| Zebra Technologies |
| Skild AI |
| FANUC |
| ABB Robotics |
| Figure AI |
| Geek+ |
| Universal Robots |
| Physical Intelligence |
| Others |
Supply & Pricing Matrix
Captive integration into semiconductor fabrication and safety-certified controller production anchors both supply security and pricing power for robot software vendors navigating EU AI Act compliance timelines. German and Japanese automation suppliers leverage in-house chip sourcing partnerships to sustain margin positions while independent software developers face cost compression from external hardware dependencies.
Pricing Analysis
Warranty and certification-bundling arrangements separate premium software tiers from unbundled entry-level offerings in procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10218 safety documentation completeness and algorithmic audit trail capabilities. Price differentiation centers on certification velocity and integration risk absorption, with pharmaceutical manufacturers showing lowest price sensitivity due to FDA software-as-a-medical-device validation requirements. Cost compression in logistics automation subscription tiers is intensifying because cloud infrastructure providers are commoditizing fleet management baseline functionality.
Supply Chain Analysis
Certification and qualification gating through IEC 61508 functional safety protocols constrains supplier eligibility for safety-critical motion control modules. Taiwan and South Korea dominate advanced neural processing unit fabrication, while Germany and Japan anchor precision controller assembly. Raw material dependencies span silicon wafers, rare earth magnets for servo motors, and specialized real-time operating system licenses. Single-source vulnerability concentrates in Taiwan semiconductor foundries serving Stuttgart and Boston robotics clusters. Distribution runs through direct OEM partnerships for industrial deployments and cloud marketplaces for logistics automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Robot Software Market operates as a cost-of-compliance story where EU AI Act risk-tier classifications erect barrier-to-entry moats favoring vendors with pre-existing ISO 10218 safety documentation and certified algorithmic audit trail capabilities.
For Market Incumbents: Acquire embedded neural processing unit design capabilities to secure hardware-software integration timelines against Taiwan foundry concentration risks. Consolidate certification assets by purchasing specialized functional safety consultancies in Germany and Japan to accelerate EU AI Act conformity assessment velocity. Defensive positioning requires backward integration into real-time operating system stacks as AI-native entrants threaten middleware abstraction layers. For New Entrants and Emerging Players: Capture India manufacturing automation white-space by establishing localized engineering presence in Maharashtra and Gujarat corridors before PLI scheme incentives mature. Target precision agriculture and construction robotics applications where safety certification burdens remain lighter than automotive or pharmaceutical verticals. Go-to-market leverage rests on edge-AI convergence offerings that bypass cloud dependency for warehouse operators facing data sovereignty constraints. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified industrial automation conglomerates seeking AI-native software capabilities to complement captive hardware stacks. Long-term viability favors vendors with demonstrated regulatory navigation across Washington, Brussels, and Tokyo parallel compliance tracks. Acquisition target archetype: pure-play simulation vendors facing displacement as integrated platforms absorb digital twin functionality. The signal to watch is FDA software-as-a-medical-device guidance expansion into surgical robotics, which would trigger certification investment spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Functional safety consultancies in Stuttgart accelerate EU AI Act compliance timelines for buyers. |
| Platform Integration | Unified perception-planning-execution stacks displace point solution providers in Boston robotics clusters. |
| Geographic Expansion | Localized engineering presence in Gujarat leverages PLI scheme incentives for smartphone assembly automation. |
| Strategic Partnership | Cloud infrastructure alliances enable subscription fleet management scalability for logistics operators. |
| Product Launch | Edge-AI controller modules with embedded neural processing units bypass network dependency in warehouse robotics. |
Research Methodology
Independent corroboration across automation engineering directors, regulatory affairs specialists at notified bodies, and cloud platform procurement officers underwrites the qualitative findings in this study. Primary interviews with control systems engineers, OEM software integration leads, and venture capital partners focused on robotics clusters in Pittsburgh and Boston were validated against secondary sources including SEC filings from industrial automation conglomerates, FDA software-as-a-medical-device guidance documents, and EU AI Act implementing act drafts. Bottom-up triangulation across deployment model segmentation and top-down cross-checks against regional manufacturing automation incentive programs ensure methodological rigor.
Rate-of-change decomposition across the analysis window separates baseline industrial automation growth from AI module expansion and cloud deployment acceleration. Segmentation dimensions modeled include software type, deployment model, application complexity, and regional regulatory cluster. CAGRs were derived from installed base evolution, replacement cycle compression, and pricing trajectory analysis. Industry-specific forecast inputs encompass EU AI Act implementation timelines and FDA software guidance expansion patterns.
The model holds under stable regulatory implementation schedules; deviation in EU AI Act conformity assessment body capacity or Taiwan semiconductor export restrictions would shift trajectory assumptions. Forecasts reflect documented assumptions regarding certification timeline standardization and cloud infrastructure cost curves. A model refresh is warranted upon material change in FDA software-as-a-medical-device enforcement posture or METI JIS standards harmonization announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Eldercare-Assistive Robots Market
Robotics and Automation
Europe Logistics Robotics Market
Robotics and Automation
South Korea Cloud Robotics Market
Robotics and Automation
United States Agricultural Robots Market
Robotics and Automation
Industrial Robotics Market
Robotics and Automation
Europe Educational Robot Market
Robotics and Automation
Global Educational Robots Market
Robotics and Automation
Motion Control Software in Robotics Market
Robotics and Automation
Global Automated Guided Vehicle (AGV) Software Market
Robotics and Automation
LAMEA Waste Sorting Robots Market
Robotics and Automation
Asia-Pacific Logistics Robotics Market
Robotics and Automation
Gantry (Cartesian) Robot Market
Robotics and Automation
Global Programmable Robots Market
Robotics and Automation
Personal Robots Market
Robotics and Automation
North America AUV and ROV Market
Robotics and Automation
Social Robots Market