
 Deep Sea Robot Market | 2026-2036
Deep Sea Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Deep Sea Robot Market Outlook
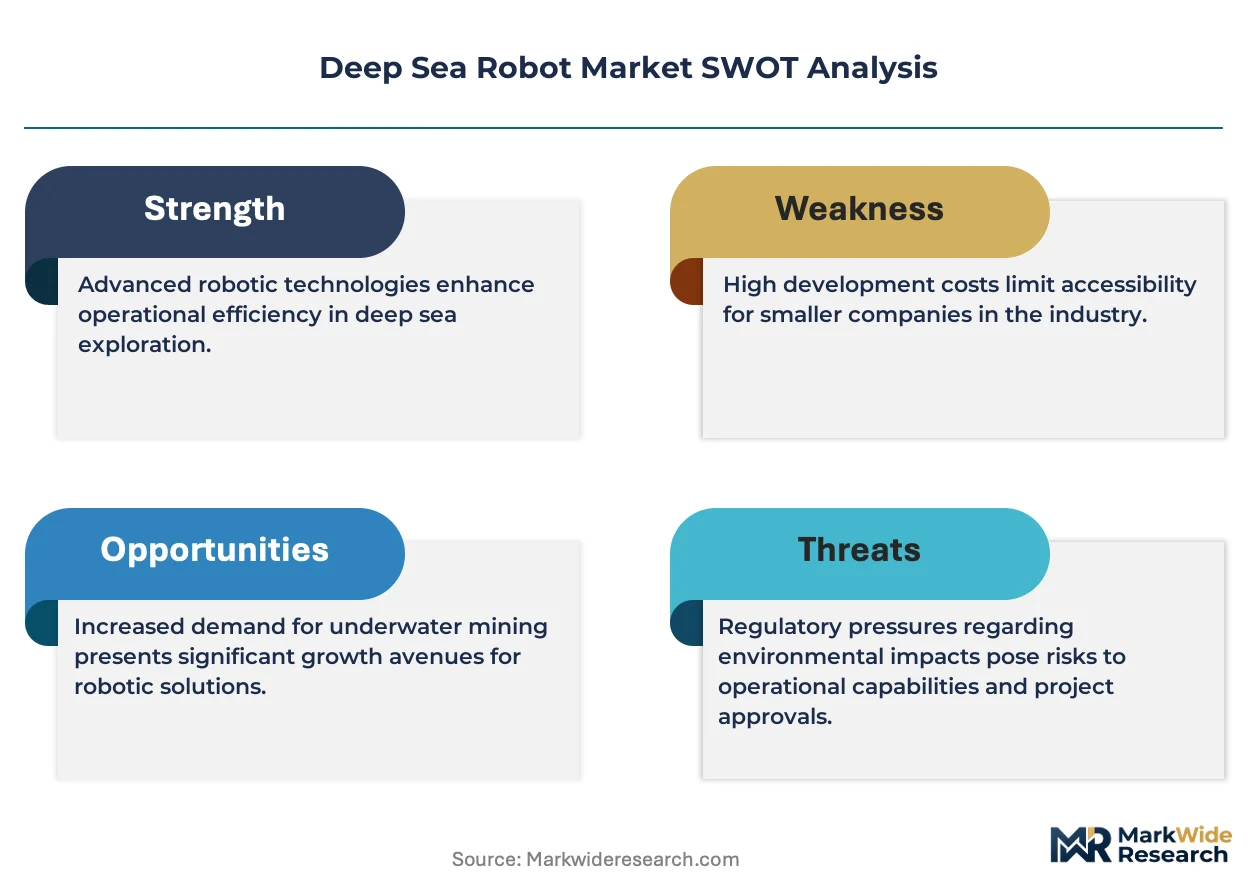
Project finance for vessel-mounted robot fleets is fragmenting the competitive landscape, allowing smaller service contractors to bid against integrated majors. Saab Seaeye leverages its compact electric thruster architecture to dominate shallow-to-mid depth inspection contracts. Oceaneering International sustains its position through captive hydraulic work-class systems and proprietary tether management. Fugro competes by operating the largest commercial fleet of autonomous underwater vehicles on a charter basis.
Deep sea robots are pressure-hardened electromechanical systems rated for operation below 200 meters, combining buoyancy-engineered hulls with acoustic positioning and real-time telemetry to perform tasks in environments beyond diver reach. Remotely operated vehicles anchor current revenue as mature work-class systems handle subsea construction and intervention for offshore energy clients. Autonomous underwater vehicles represent the fastest-expanding product category, with long-endurance gliders and hovering AUVs displacing tethered alternatives in seabed survey work where communication latency tolerances permit.
The International Maritime Organization's subsea cable protection guidelines and the International Seabed Authority's exploration contract terms shape robot certification requirements and operational boundaries for contractors. The US Coast Guard and Bureau of Safety and Environmental Enforcement enforce domestic standards for offshore robot deployment in federal waters. Stakeholders must monitor how seabed mining moratorium extensions and national security-driven cable surveillance mandates redirect procurement toward dual-use platforms with interchangeable sensor payloads.
Market Dynamics
The International Seabed Authority's exploration contract terms are compressing operational zones while simultaneously mandating precision mapping capabilities, forcing contractors to retool fleets for dual-use seabed survey and surveillance missions.
Growth Catalysts
- Subsea Infrastructure Aging:North Sea operators face replacement cycles for installations deployed in the 1990s, creating sustained demand for inspection-class systems rated to 3,000 meters.
- REACh Compliance Pressure:The EU's chemical substance restrictions on hydraulic fluids are accelerating electric thruster adoption in work-class vehicle designs.
- Acoustic Positioning Advances:Ultra-short baseline systems from Kongsberg Maritime enable autonomous docking with subsea structures, reducing surface vessel standby costs.
Market Restraints
- Titanium Alloy Supply Concentration:Pressure hull fabrication depends on Russian and Chinese sponge titanium, exposing Western manufacturers to export control volatility.
- ISA Licensing Bottlenecks:The International Seabed Authority's two-year environmental review timelines delay commercial mining robot deployment.
- Optical Fiber Tether Costs:Deep-rated fiber-optic cables represent 35-40% of work-class vehicle system costs, with limited qualified suppliers in Japan and Norway.
Strategic Opportunities
- Brazil Pre-Salt Expansion:Petrobras's Buzios and Mero field developments require resident autonomous systems for continuous well monitoring.
- Offshore Wind Foundation Inspection:Monopile scour assessment contracts in the UK and Germany are displacing diver-based methods with hovering AUVs.
- US Coast Guard Cable Surveillance Mandates:National security directives are creating dual-use procurement pools where seabed mapping robots gain intelligence application certifications.
Industry Challenges
- Subsea Robotics Engineering Talent Gap:Pressure vessel design and acoustic navigation expertise concentrates among retiring specialists from 1980s-era defense programs.
- ISO 13628-8 Certification Timelines:Subsea production control system integration testing extends delivery schedules by 8-12 months for new vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deep Sea Robot Market |
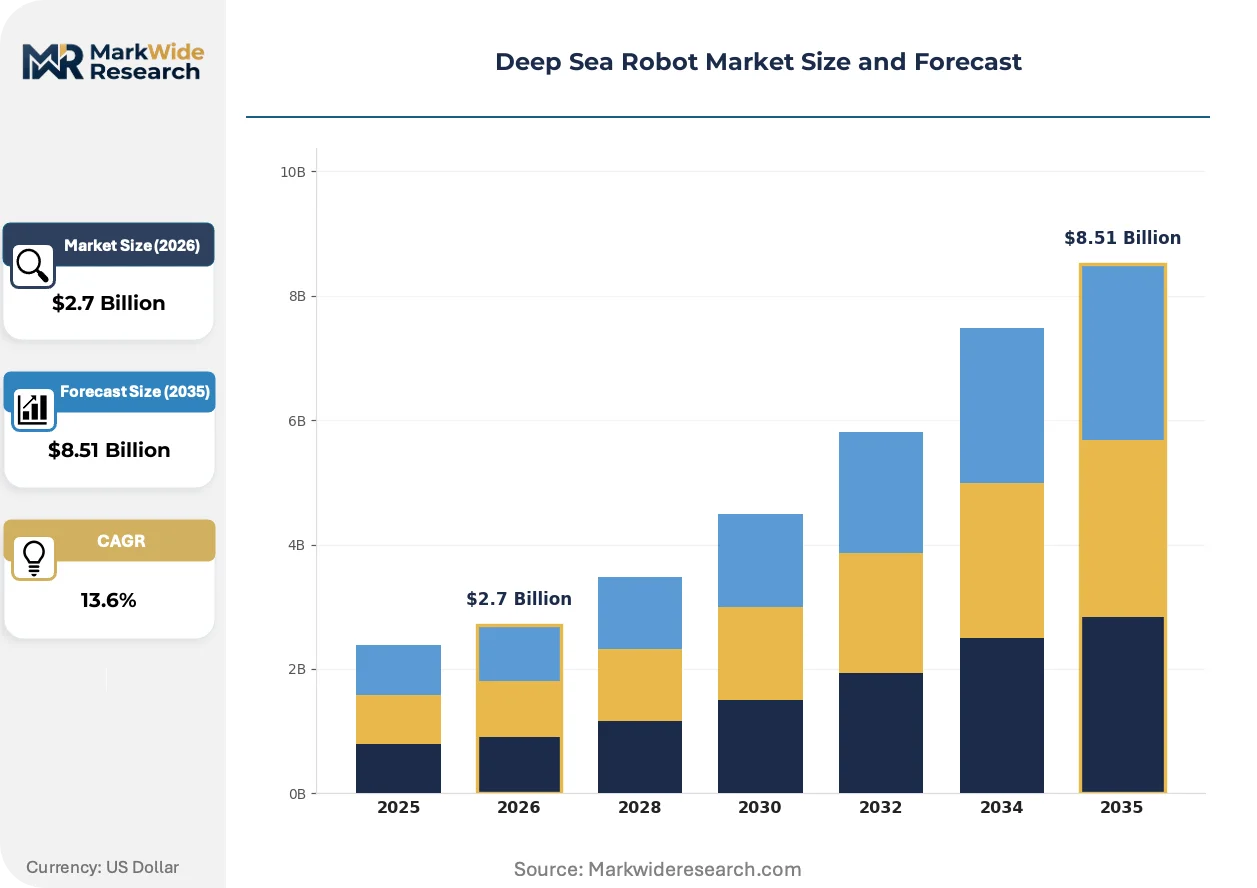
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $8.51 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Underwater Vehicles, Remotely Operated Vehicles, Surface Vehicles, Hybrid Vehicles End User: Oil & Gas Exploration, Marine Research, Defense, Environmental Monitoring Application: Underwater Inspection, Data Collection, Search and Rescue, Underwater Maintenance Technology: Sensor Technology, Communication Systems, Navigation Systems, Energy Management |
| Companies Covered | Saab Seaeye, TechnipFMC, Oceaneering International, ECA Group, Soil Machine Dynamics, Fugro, Forum Energy Technologies, Ocean Infinity, Kongsberg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deep Sea Robot Market Strategic Shifts
Digital twin architectures are virtualizing mission planning and post-processing workflows, compressing the boundary between physical deployment and simulated rehearsal for high-risk deepwater interventions.
Edge computing payloads with NVIDIA Jetson modules are virtualizing real-time object detection and anomaly classification aboard autonomous underwater vehicles. Offshore survey contractors in Norway and the UK are deploying these systems for live pipeline inspection without surface tether dependency. This virtualization of processing workloads is eliminating the bandwidth constraints that previously forced all data to surface vessels.
The International Seabed Authority's draft exploitation regulations are mandating continuous environmental baseline monitoring as a condition of commercial mining licenses. Contractors must now integrate biological sampling payloads and sediment plume sensors into seabed survey robots. The Clarion-Clipperton Zone contractors are responding by procuring long-endurance gliders with interchangeable sensor modules.
Charter-based fleet access is displacing capital purchase models among mid-tier offshore service companies. These operators now contract autonomous vehicle capacity from Fugro and Ocean Infinity on mission-specific terms rather than maintaining owned assets. The North Sea and Gulf of Mexico exhibit the strongest migration toward this operational expenditure model.
Deep Sea Robot Market Segmentation
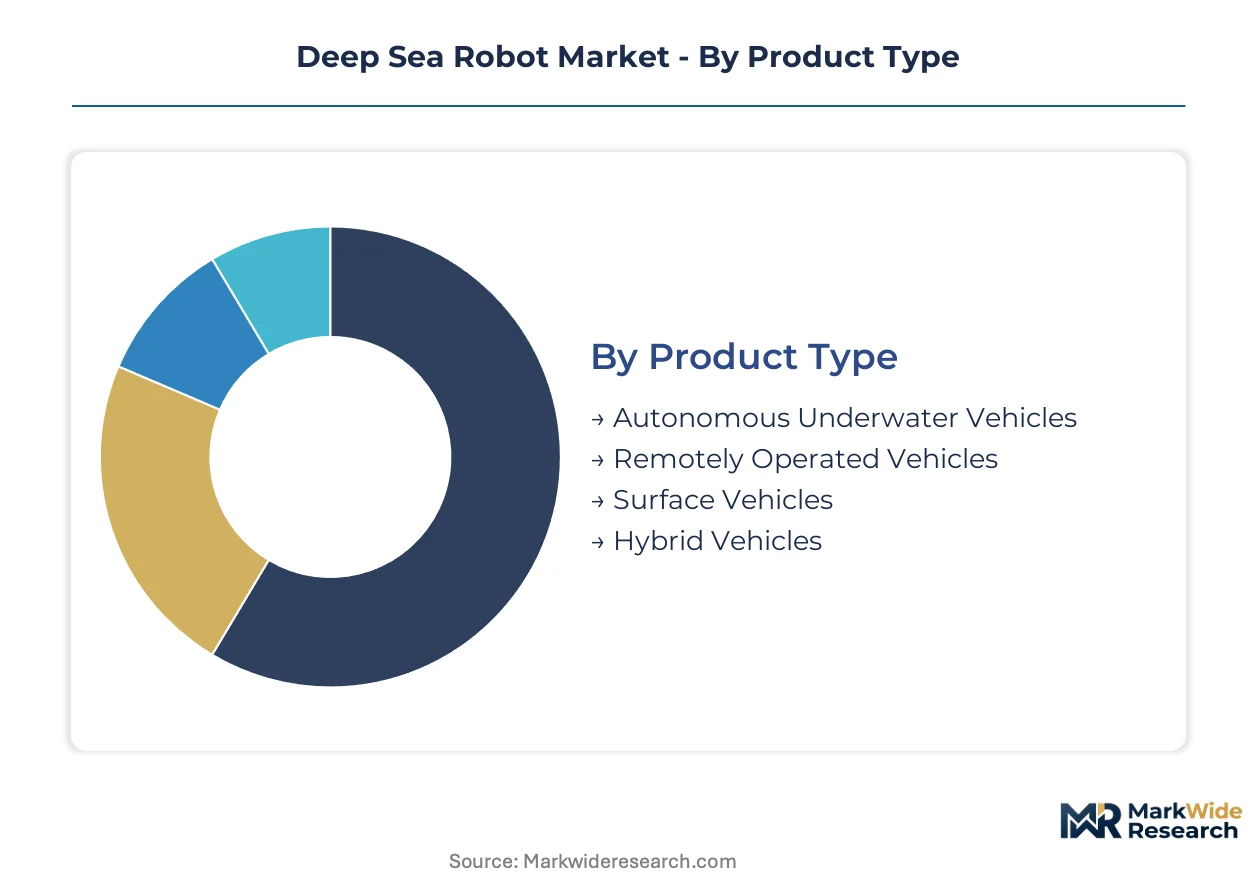
Deep sea robot procurement varies sharply by operational depth, autonomy level, and regulatory environment. Segment boundaries determine certification requirements, pricing tiers, and vendor selection criteria for offshore contractors.
Product Type:
Autonomous capability spans tethered workhorses to untethered survey platforms with divergent power architectures and mission endurance profiles.
- Autonomous Underwater Vehicles:Untethered battery-powered platforms with acoustic or inertial navigation executing pre-programmed survey grids. Demand concentrates in Norway's North Sea corridor for pipeline inspection where surface vessel day rates exceed $150,000. Long-endurance gliders and hovering AUVs are displacing tethered alternatives in seabed survey work where communication latency tolerances permit.
- Remotely Operated Vehicles:Tethered hydraulic or electric systems with real-time operator control via fiber-optic umbilicals rated to 6,000 meters. Petrobras and Equinor deploy work-class ROVs for subsea construction and intervention at Brazil's pre-salt fields and North Sea installations. These systems anchor current revenue as mature platforms handle heavy-lift tasks beyond AUV capability.
- Surface Vehicles:Unmanned surface vessels deploying towed sensors or serving as communication relays for submerged assets.
- Hybrid Vehicles:Dual-mode systems switching between autonomous survey and tethered intervention modes for flexible mission profiles.
Established volume favors Remotely Operated Vehicles; emerging adoption favors Autonomous Underwater Vehicles.
End User:
Customer procurement patterns split between capital-intensive energy majors and mission-funded institutional operators with divergent budget cycles and technical specifications.
- Oil & Gas Exploration:Integrated majors and national oil companies operating production assets requiring continuous inspection and intervention. Offshore oil and gas operators now deploy autonomous systems for subsea infrastructure inspection at depths exceeding 3,000 meters. North Sea replacement cycles for 1990s-era installations sustain demand for inspection-class systems.
- Marine Research:Academic institutions and oceanographic institutes procuring long-endurance platforms for climate and biodiversity studies. The International Seabed Authority's draft exploitation regulations mandate continuous environmental baseline monitoring, driving biological sampling payload integration.
- Defense:Naval programs and intelligence agencies procuring dual-use seabed mapping platforms with surveillance certifications.
- Environmental Monitoring:Regulatory compliance contractors and conservation organizations tracking sediment plumes and ecosystem impacts.
Capital expenditure concentration favors Oil & Gas Exploration; steepest expansion trajectory favors Environmental Monitoring.
Application:
Mission type determines sensor payload configuration, positioning accuracy requirements, and regulatory certification pathways.
- Underwater Inspection:Visual and ultrasonic assessment of subsea structures, pipelines, and foundations. Offshore wind monopile scour assessment contracts in the UK and Germany are displacing diver-based methods with hovering AUVs. REACh compliance pressure on hydraulic fluids accelerates electric thruster adoption in work-class vehicle designs.
- Data Collection:Bathymetric mapping, geophysical survey, and environmental baseline acquisition for seabed mining licensing. Stricter seabed mining regulations from the International Seabed Authority constrain operational zones but accelerate demand for precision mapping robots.
- Search and Rescue:Emergency response operations requiring rapid deployment and object detection capabilities.
- Underwater Maintenance:Subsea intervention including valve operation, cable burial, and equipment replacement.
Current contract volume favors Underwater Inspection; regulatory-driven procurement favors Data Collection.
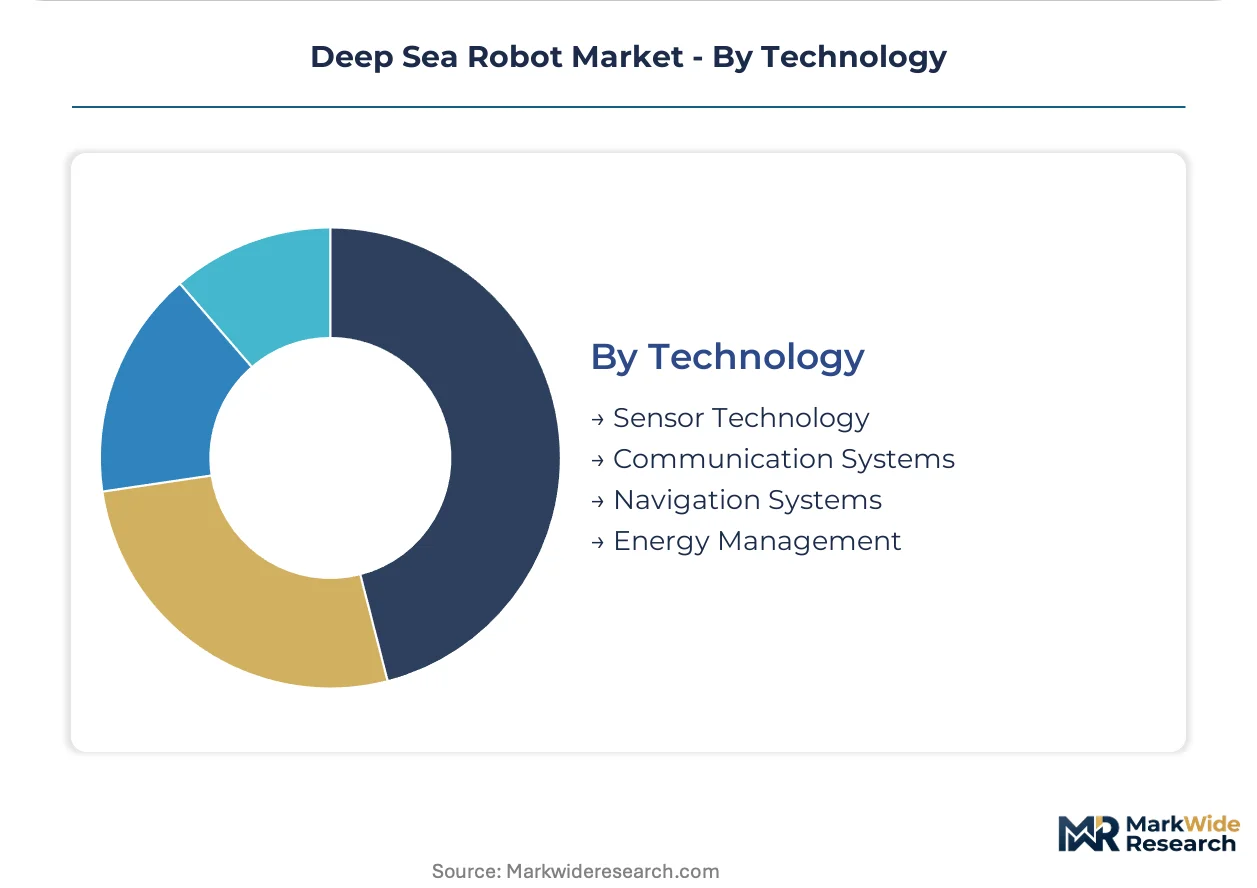
Technology:
Component-level capabilities determine mission endurance, positioning accuracy, and real-time decision autonomy.
- Sensor Technology:Multibeam sonar, sub-bottom profilers, and optical imaging systems for seabed characterization. Edge computing payloads with NVIDIA Jetson modules are virtualizing real-time object detection and anomaly classification aboard autonomous underwater vehicles in Norway and UK offshore survey operations.
- Communication Systems:Acoustic modems and optical links enabling data transmission between submerged assets and surface control. Optical fiber tether costs represent 35-40% of work-class vehicle system costs with supply concentration in Japan and Norway.
- Navigation Systems:Ultra-short baseline acoustic positioning and inertial measurement units for subsea localization. Kongsberg Maritime systems enable autonomous docking with subsea structures, reducing surface vessel standby costs.
- Energy Management:Battery chemistry, fuel cells, and inductive charging systems determining mission endurance.
Platform differentiation centers on Navigation Systems; procurement priority is shifting toward Sensor Technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in titanium sponge and pressure-rated optical components shape regional competitive positioning. Norway and Japan maintain net export positions in specialized subsea components, while Brazil and the United Kingdom remain import-dependent for work-class vehicle systems.
Norway
Equinor and Aker BP drive resident autonomous system procurement for North Sea infrastructure exceeding 3,000 meters depth. The Norwegian Maritime Authority enforces strict certification protocols for subsea intervention equipment. The Stavanger-to-Bergen corridor concentrates Europe's densest cluster of ROV service contractors and AUV charter operators.
United States
The US Coast Guard cable surveillance mandates and Bureau of Safety and Environmental Enforcement offshore standards sustain dual-use platform demand. Federal waters regulations require redundant acoustic positioning for autonomous operations below 500 meters. Gulf of Mexico operators in Louisiana and Texas charter AUV capacity from third-party fleets rather than owning assets.
Brazil
Petrobras pre-salt field developments at Buzios and Mero require continuous well monitoring through resident autonomous systems. The national petroleum regulator ANP mandates environmental baseline documentation for all subsea interventions. Rio de Janeiro anchors Latin America's largest concentration of work-class ROV deployment vessels.
United Kingdom
Offshore wind monopile scour assessment contracts displace diver-based methods with hovering AUVs in North Sea waters. The Health and Safety Executive enforces REACh-compliant hydraulic fluid restrictions on subsea equipment. Aberdeen maintains its position as a service hub despite capital expenditure migration toward charter models.
Japan
Deep-rated fiber-optic tether manufacturing concentrates among qualified suppliers serving work-class vehicle integrators. METI industrial standards govern pressure vessel certification for seabed mining exploration systems. Yokohama and Kobe host specialized component fabricators supplying titanium alloy hull fabricators globally.
Deep Sea Robot Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in acoustic positioning, pressure-rated optics, and buoyancy-engineered alloys. Market structure fragments across three tiers: integrated energy service majors with captive fleets, independent vehicle manufacturers selling to charter operators, and mission-specific contractors accessing capacity through operational expenditure models. Dominant competitive moves include fleet standardization around interchangeable sensor payloads and backward integration into pressure hull fabrication to secure titanium supply.
Among Nordic system integrators, Kongsberg and Saab Seaeye exemplify platform-specialist positioning, while Oceaneering International anchors the integrated service tier with captive hydraulic work-class deployment. These three entities represent divergent strategic archetypes: pure-play vehicle manufacturing, diversified maritime technology, and vertically integrated offshore contracting.
| Leading Market Players |
|---|
| Saab Seaeye |
| TechnipFMC |
| Oceaneering International |
| ECA Group |
| Soil Machine Dynamics |
| Fugro |
| Forum Energy Technologies |
| Ocean Infinity |
| Kongsberg |
| Others |
Value Chain & Pricing Dynamics
Titanium alloy export control volatility from Russian and Chinese sponge suppliers compresses margin structures across all three pricing tiers while simultaneously forcing Western manufacturers toward captive smelter investments or alternative alloy formulations. This single-source dependency creates a bifurcated market where integrated majors with long-term offtake contracts capture pricing power, and mid-tier charter operators absorb spot-market volatility.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by ISO 13628-8 certification status and pressure-depth ratings. Price erosion runs through the standard tier as charter-based fleet access displaces capital purchases among North Sea service contractors. National oil companies exhibit lowest price sensitivity due to resident system requirements for continuous well monitoring, while mid-tier environmental monitoring contractors face acute budget constraints.
Supply Chain Analysis
US and EU dual-use technology controls on acoustic positioning systems and pressure-rated fiber-optic components limit flows to qualified integrators in Norway, Japan, and the United Kingdom. Deep-rated optical tethers draw from Japanese and Norwegian qualified suppliers, while titanium sponge feeds from Russian and Chinese primary producers. Single-source vulnerability concentrates in pressure hull fabrication, where distribution runs through Stavanger and Yokohama component fabricators to system integrators globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat environment where International Seabed Authority licensing timelines and ISO certification requirements create switching costs that entrench incumbent positions. Network effects concentrate among charter fleet operators with established vessel relationships.
For Market Incumbents: Insulate market position through backward integration into titanium alloy hull fabrication and captive supply of pressure-rated optical components. Lock in charter fleet capacity through multi-year vessel alliances before emerging AUV specialists achieve scale. The priority threat is substitution by long-endurance glider platforms with modular payload architectures. For New Entrants and Emerging Players: Offshore wind foundation inspection contracts in the United Kingdom and Germany represent the most penetrable entry point, where diver-displacement mandates create procurement urgency without incumbent fleet entrenchment. Environmental baseline monitoring for seabed mining exploration licenses offers a second white-space target with regulatory-driven demand certainty. A go-to-market angle centered on interchangeable biological sampling payloads differentiates against integrated majors with fixed sensor configurations. For Investors and Strategic Acquirers: The market sits at a fleet-refreshment phase that favors autonomous vehicle specialists with proven ultra-short baseline navigation integration. Long-term viability over the next decade hinges on dual-use certification pathways that unlock defense and intelligence procurement pools. The signal to watch is International Seabed Authority exploitation regulation finalization, which would trigger commercial mining robot deployment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Titanium Smelter Investment | Secures pressure hull supply against Russian and Chinese export control volatility. |
| Dual-Use Platform Certification | Unlocks US Coast Guard cable surveillance procurement alongside commercial survey contracts. |
| Modular Payload Architecture | Enables rapid reconfiguration between seabed mining environmental monitoring and oilfield inspection missions. |
| Charter Fleet Alliance | Consolidates vessel access for mid-tier contractors migrating from capital purchase models. |
| Edge Computing Payload Integration | Eliminates surface tether dependency for real-time pipeline anomaly classification in Norwegian North Sea operations. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with ROV fleet managers, AUV charter operators, subsea engineering directors, and regulatory compliance officers at the International Seabed Authority; and secondary validation through SEC filings from listed offshore service contractors, Norwegian Maritime Authority certification registries, ANP environmental documentation, and Bureau of Safety and Environmental Enforcement incident databases. Bottom-up vessel deployment counts were triangulated against top-down energy major capital expenditure disclosures.
Forecast inputs incorporated autonomous system penetration rates by depth tier, charter fleet capacity expansion announcements, and regulatory timeline scenarios across the projection horizon. Segmentation dimensions modeled include product type autonomy level, end-user budget cycle archetype, application mission profile, and technology component tier. CAGRs were derived from S-curve adoption modeling calibrated to historical ROV fleet replacement cycles and AUV displacement patterns in North Sea pipeline inspection.
Stress conditions across titanium supply disruption severity, ISA licensing delay extensions, and offshore wind procurement acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about charter model migration velocity and electric thruster adoption curves. Material shifts in US Coast Guard cable surveillance mandate scope or ISA seabed mining moratorium extensions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Europe Logistics Robotics Market
Robotics and Automation
Professional Service Robots Market
Robotics and Automation
AI Assisted Robots Market
Robotics and Automation
Asia Pacific Industrial Robots Market
Robotics and Automation
Global Robotic Grippers Market
Robotics and Automation
Global Enterprise Robotic Process Automation Market
Robotics and Automation
Europe Data Center Robotics Market
Robotics and Automation
Global Soldering Robot Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Market
Robotics and Automation
Spain Cloud Robotics Market
Robotics and Automation
Robotic Welding Market
Robotics and Automation
Global Robot Kitchen Market
Robotics and Automation
High-Precision Truss Robot Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
Global Smart Robots Market
Robotics and Automation
US Cloud Robotics Market