
 Gantry (Cartesian) Robot Market | 2026-2036
Gantry (Cartesian) Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Gantry (Cartesian) Robot Market Analysis
Modular gantry configurations with swappable end-effector packages is pivoting buyer choice away from fixed-function systems. ABB leverages its electric drive expertise to dominate high-precision electronics assembly lines. FANUC anchors its position through captive supply of servo motors and controllers. Güdel Group specializes in heavy-payload material handling systems for automotive and aerospace clients.
A gantry (Cartesian) robot employs linear actuators mounted on perpendicular axes to achieve precise three-dimensional positioning, typically achieving repeatability within ±0.05 mm through ball-screw or linear-motor drive mechanisms. These systems execute pick-and-place, dispensing, and inspection tasks across continuous production cycles where rectilinear motion paths outperform articulated arm geometries. Electric drive technology leads installed capacity due to superior energy efficiency and programmability, while hybrid robots combining Cartesian bases with rotary wrist units represent the fastest-expanding product category as manufacturers seek flexible part orientation without sacrificing positional accuracy. Machine tending applications command the largest application share, though packaging lines are accelerating adoption as food and pharmaceutical producers retrofit for washdown-compatible automation.
FDA regulations on pharmaceutical manufacturing traceability and USDA requirements for meat and poultry processing equipment sanitation directly shape gantry robot specification requirements in North American food and drug plants. CE marking under the EU Machinery Directive and ISO 10218 safety standards for industrial robots govern market access across European manufacturing sectors. Stakeholders must monitor how China's evolving GB robot safety standards and the EU AI Act's risk-classification framework for autonomous systems will reshape certification burdens and design priorities for next-generation Cartesian platforms.
Market Dynamics
Modular gantry architectures with field-swappable end-effector packages are compressing replacement cycles as electronics fabs in Jiangsu province and automotive stamping plants in Stuttgart demand reconfigurable automation without line shutdowns.
Growth Catalysts
- MIIT GB Standard Tightening:China's revised industrial robot safety and electromagnetic compatibility mandates are accelerating fleet modernization among domestic electronics assemblers seeking export certification.
- Linear Motor Adoption:Direct-drive linear motors are displacing ball-screw mechanisms in high-throughput semiconductor test handlers, cutting cycle times and maintenance intervals.
- Pharmaceutical Traceability Mandates:FDA serialization requirements for drug packaging lines are forcing retrofits of legacy Cartesian systems with integrated vision and data-logging modules.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium sourcing dependency on Chinese processors creates input cost volatility for linear motor manufacturers.
- CE Machinery Directive Compliance Burden:Extended third-party certification timelines for multi-axis Cartesian systems delay revenue recognition for European system integrators.
- Articulated Robot Substitution:Six-axis collaborative robots with improved reach envelopes are capturing pick-and-place applications previously reserved for gantry geometries.
Strategic Opportunities
- India PLI Scheme Uptake:Production-linked incentives for electronics manufacturing are driving greenfield fab construction in Tamil Nadu and Karnataka with native automation specification.
- EU AI Act Risk Classification:Autonomous gantry systems with adaptive path planning face lighter compliance burdens than fully collaborative robots, creating a regulatory wedge for Cartesian platforms in European pharma.
- Battery Cell Stacking Automation:Lithium-ion electrode layer alignment requires micron-level repeatability that hybrid Cartesian-rotary systems deliver more cost-effectively than pure SCARA or six-axis alternatives.
Industry Challenges
- Mechatronics Skill Scarcity:Integration of linear encoders, servo drives, and kinematic controllers demands cross-trained technicians unavailable in most regional manufacturing clusters.
- Legacy PLC Integration Friction:Brownfield deployments require protocol bridging between modern EtherCAT gantry controllers and decades-old proprietary automation networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gantry (Cartesian) Robot Market |
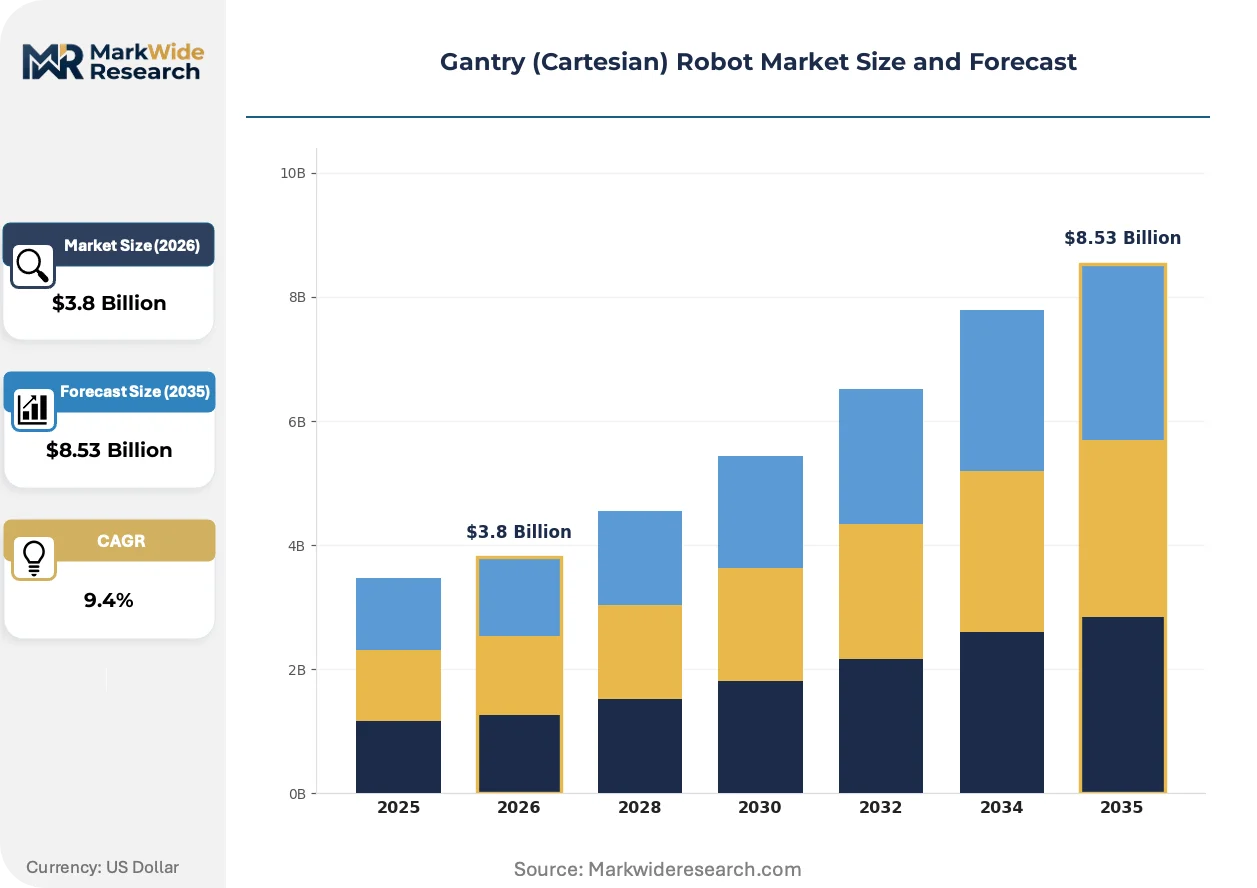
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
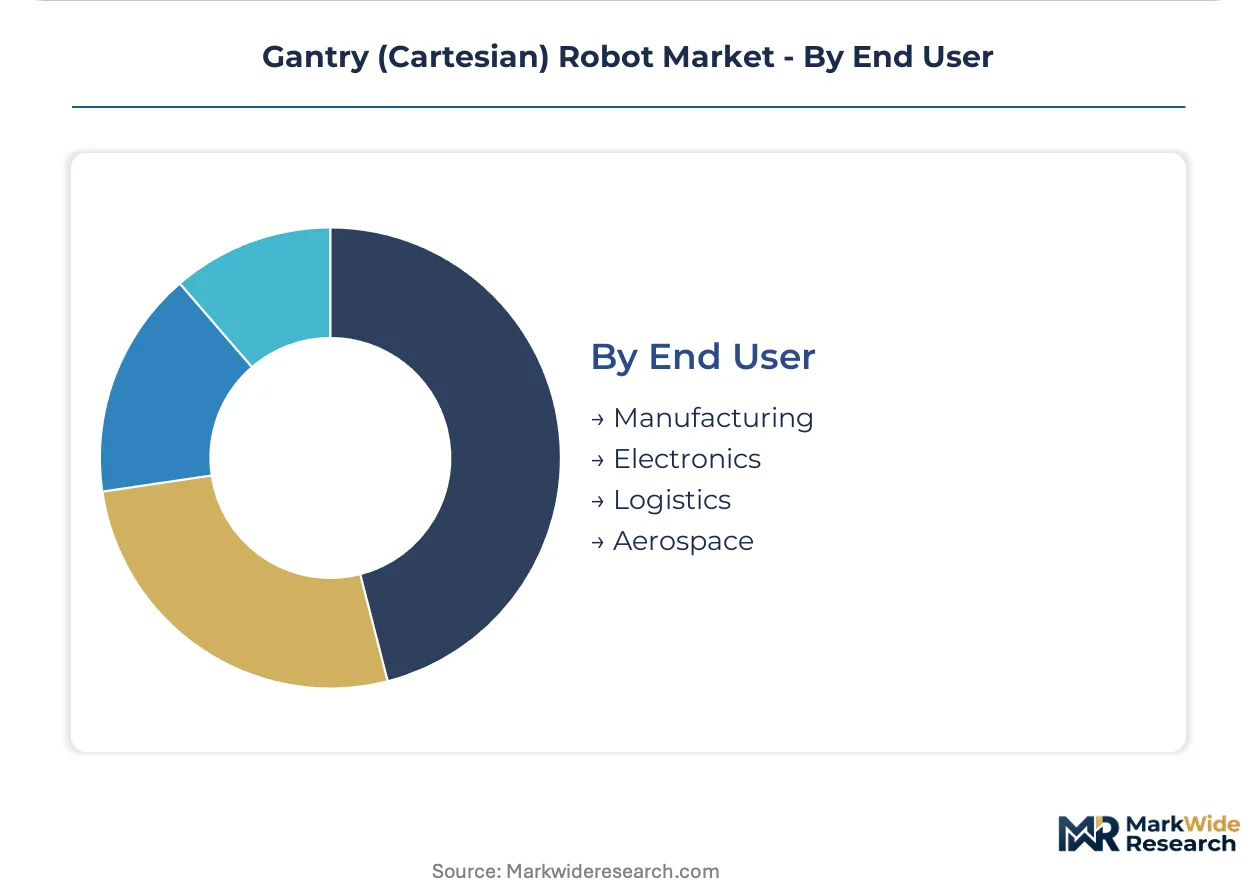
| Segmentation | Product Type: 2D Robots, 3D Robots, Hybrid Robots, Specialized Robots Technology: Electric Drive, Hydraulic Drive, Pneumatic Drive, Manual Drive Application: Material Handling, Machine Tending, Assembly, Packaging End User: Manufacturing, Electronics, Logistics, Aerospace |
| Companies Covered | ABB, Omron, FANUC, Bosch Rexroth, Yamaha Robotics, KUKA, Mitsubishi Electric, Güdel Group, Yaskawa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gantry (Cartesian) Robot Market Emerging Trajectories
Active vibration damping and real-time thermal compensation are elevating precision thresholds as semiconductor lithography and medical device manufacturers push gantry repeatability below ten-micron tolerances.
Magnetic levitation linear drives are overtaking mechanical bearing systems in wafer inspection and flat-panel display assembly. TSMC and Samsung Display have standardized on mag-lev gantries for Gen 10.5 OLED substrate handling. The elimination of mechanical contact points is compressing maintenance windows from quarterly to annual intervals while enabling sustained velocities above five meters per second.
The EU AI Act's risk-based classification framework is forcing recertification of autonomous Cartesian platforms with adaptive collision avoidance. Machine builders in Bavaria and Lombardy are embedding deterministic safety PLCs to maintain Category 3 compliance. Pharmaceutical packaging lines in Ireland and Denmark face the steepest redesign costs as their vision-guided pick systems trigger higher-risk thresholds under the Act's Annex III.
Buyer concentration among tier-one contract manufacturers is compressing vendor negotiation cycles. Foxconn and Luxshare are mandating open-architecture controllers and standardized mechanical interfaces across their global gantry fleets. This specification homogenization is visible most acutely in Kunshan and Shenzhen, where automation procurement teams now reject proprietary kinematic software stacks in favor of IEC 61131-3 programmable alternatives.
Gantry (Cartesian) Robot Market Segmentation
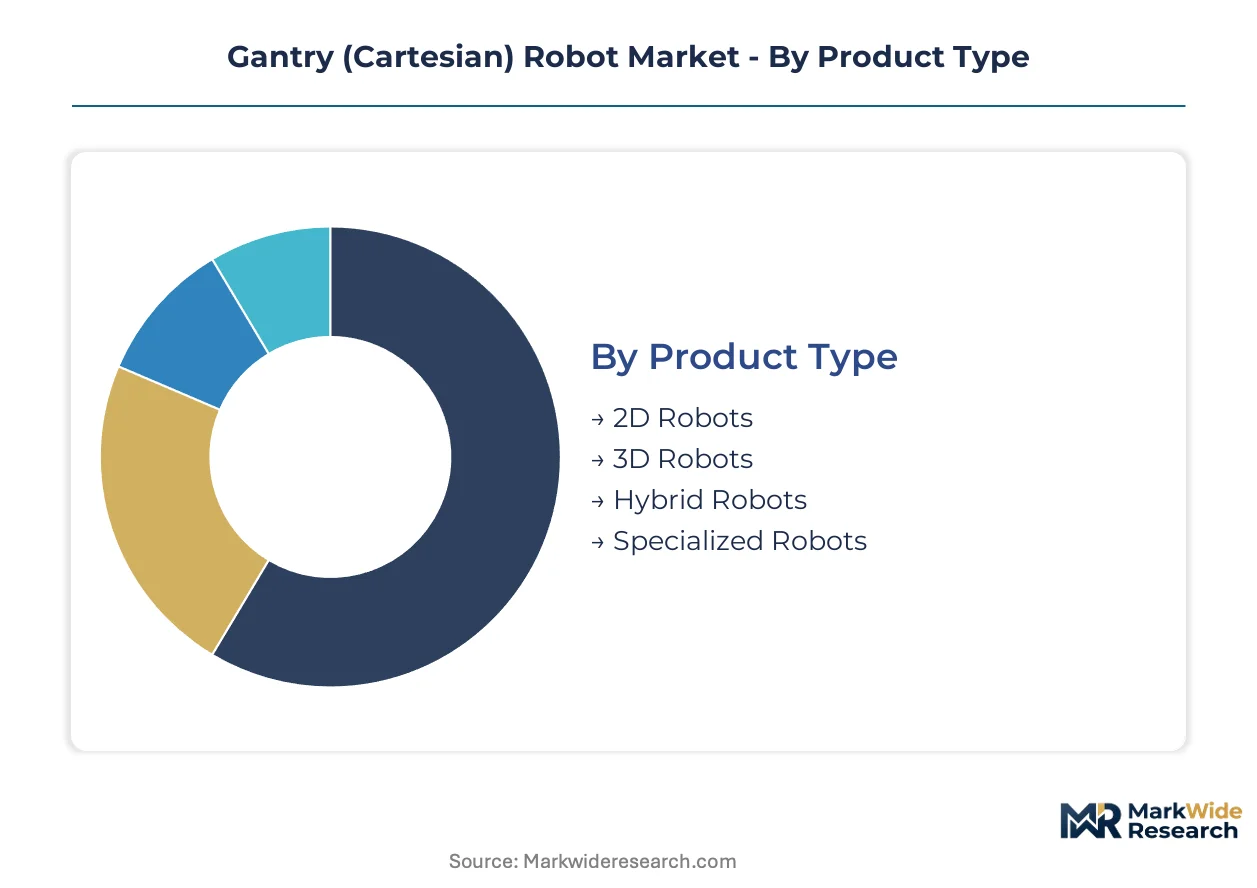
Gantry robot procurement decisions hinge on motion precision requirements, payload demands, and reconfiguration frequency across production environments. Segmentation reveals where technical specifications diverge from commercial priorities, exposing margin concentration points and substitution risks.
Product Type:
Buyers weigh footprint constraints against degrees of freedom when selecting gantry architectures for specific production tasks.
- 2D Robots:Planar systems operate on X-Y axes with fixed Z-height, delivering repeatability within ±0.05 mm for flat-panel display inspection and printed circuit board testing. Jiangsu province electronics fabs in Kunshan and Suzhou deploy these for wafer probing operations where vertical travel remains constant. Cost efficiency and simplified commissioning make these the default choice for high-volume, low-mix production lines.
- 3D Robots:Full Cartesian systems with independent Z-axis motion enable volumetric positioning for automotive powertrain assembly and battery module stacking. Stuttgart stamping plants specify these for die-changing operations where vertical clearance varies by tool geometry. The additional axis adds 40-60% to system cost but eliminates fixturing redundancy across mixed-model lines.
- Hybrid Robots:Cartesian bases integrated with rotary wrist units combine rectilinear precision with part orientation flexibility. Semiconductor test handlers in Hsinchu and Dresden standardize on these for device alignment during final packaging. The configuration bridges the gap between pure gantry and SCARA economics.
- Specialized Robots:Custom architectures for cleanroom wafer transport or explosive atmosphere material handling carry extended lead times and captive software dependencies. Aerospace composite layup systems in Toulouse and Wichita fall into this category.
Volume sits with 2D Robots; growth tilts toward Hybrid Robots.
Technology:
Energy efficiency mandates and maintenance cost accounting are reconfiguring drive technology preferences across end-user categories.
- Electric Drive:Servo motor and ball-screw or linear motor configurations dominate installed capacity due to programmability and energy recovery capabilities. FDA-regulated pharmaceutical packaging lines in New Jersey and North Carolina mandate electric systems for washdown compatibility and precise torque control during vial capping operations. MIIT GB electromagnetic compatibility standards in China are accelerating displacement of legacy alternatives.
- Hydraulic Drive:Fluid power systems persist in heavy-payload automotive stamping and forging applications where force density exceeds electric motor capabilities. Bavarian press automation retains hydraulic gantries for hot-forming operations despite higher energy consumption.
- Pneumatic Drive:Compressed air systems occupy niche positions in explosive atmosphere zones and food-grade washdown environments where electric motor sealing costs prove prohibitive. Meat processing facilities under USDA inspection in Nebraska and Iowa specify these for sanitary compliance.
- Manual Drive:Hand-cranked positioning systems survive in prototype shops and maintenance bays where automation economics fail; these represent declining share concentrated in low-wage manufacturing clusters.
Electric Drive commands current volume; expansion concentrates in linear motor variants displacing ball-screw mechanisms.
Application:
Cycle time requirements and part geometry complexity determine which motion architectures win specific production tasks.
- Machine Tending:Loading and unloading of CNC machining centers, injection molding presses, and stamping equipment constitutes the largest application segment by unit volume. Automotive suppliers in Wolfsburg and Toyota City deploy dedicated gantries for unattended overnight production. The application demands highest reliability metrics with mean time between failures exceeding 60,000 hours.
- Material Handling:Palletizing, depalletizing, and inter-process transport operations prioritize speed over precision, with velocities reaching five meters per second in mag-lev configurations. Logistics fulfillment centers in Rotterdam and Singapore specify these for carton sorting where path predictability simplifies safety zoning.
- Assembly:Precision part mating operations in electronics and medical device manufacturing require force-controlled insertion. FDA-regulated insulin pen assembly in Denmark and Switzerland employs vision-guided gantries for component alignment.
- Packaging:Primary and secondary packaging lines for food, pharmaceutical, and consumer goods are accelerating adoption as serialization mandates force retrofits. EU AI Act risk classifications are elevating compliance costs for autonomous pick systems in Irish and Danish facilities.
Machine Tending anchors current deployment; Packaging lines are expanding most quickly on regulatory compulsion.
End User:
Capital expenditure cycles and automation maturity vary sharply across buyer industries, fragmenting vendor sales motions.
- Electronics:Contract manufacturers in Shenzhen, Kunshan, and Chennai drive highest unit demand for precision assembly and test handling. Foxconn and Luxshare procurement standardization around open-architecture controllers is compressing vendor margins while accelerating replacement cycles.
- Manufacturing:General industrial automation spans automotive, metal fabrication, and plastics processing with diverse technical requirements. German Mittelstand machine builders favor modular gantries with field-swappable end-effectors to preserve line flexibility.
- Logistics:E-commerce fulfillment and warehouse automation are emerging demand centers as labor availability tightens in advanced economies. Amazon and JD.com specification of standardized mechanical interfaces is homogenizing procurement patterns.
- Aerospace:Composite layup, drilling, and inspection operations demand specialized configurations with extended reach and vibration damping. Boeing and Airbus tier-one suppliers in Toulouse, Hamburg, and Charleston accept 12-18 month lead times for custom systems.
Electronics concentrates current volume; Logistics investment is climbing the fastest on e-commerce infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of gantry robot systems while Germany and the United States absorb the highest-value precision deployments. East Asian electronics clusters drive volume consumption, though European automotive and pharmaceutical specifications set technical benchmarks for export-oriented production.
China
Domestic electronics contract manufacturers in Jiangsu province are scaling automated assembly lines for semiconductor test handling and battery cell stacking. MIIT's tightening GB standards for industrial robot safety and electromagnetic compatibility are accelerating fleet modernization among exporters seeking CE marking equivalence. Kunshan and Suzhou host concentrated gantry deployment for wafer probing and flat-panel display inspection operations.
Germany
Automotive stamping plants in Stuttgart and Wolfsburg specify 3D gantry systems for die-changing operations and powertrain assembly where vertical clearance varies by tool geometry. CE marking under the EU Machinery Directive and ISO 10218 safety standards govern all industrial robot deployments. Bavarian Mittelstand machine builders favor modular architectures with field-swappable end-effectors to preserve production line flexibility.
United States
FDA serialization requirements for pharmaceutical packaging are forcing retrofits of legacy Cartesian systems with integrated vision and data-logging modules in New Jersey and North Carolina facilities. USDA meat and poultry processing equipment sanitation rules shape specification requirements in Nebraska and Iowa plants. Amazon and JD.com fulfillment center specifications are homogenizing logistics automation procurement patterns.
Japan
Semiconductor test handlers in Hsinchu and Tokyo standardize on hybrid Cartesian-rotary systems for device alignment during final packaging. METI industrial policy supports precision manufacturing automation through JIS standards alignment. Kanto and Kansai manufacturing belts concentrate demand for machine tending applications with mean time between failure requirements exceeding sixty thousand hours.
South Korea
TSMC and Samsung Display have standardized on magnetic levitation gantries for Gen 10.5 OLED substrate handling in domestic fabrication facilities. MFDS pharmaceutical manufacturing traceability mandates parallel FDA serialization requirements for export-oriented drug packaging lines. Seoul Capital Area and Busan-Ulsan industrial corridors anchor precision electronics and shipbuilding automation demand.
Gantry (Cartesian) Robot Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive motion control component supply. Market concentration is moderate, with established robotics and automation specialists occupying distinct performance tiers rather than competing head-to-head on identical specifications. Three archetypes dominate: integrated electric drive specialists, heavy-payload material handling fabricators, and precision electronics assembly solution providers. Competitive dynamics center on backward integration into servo motor and controller manufacturing, alongside strategic partnerships for magnetic levitation linear drive technology licensing.
Within the diversified conglomerate tier, ABB leverages its electric drive expertise to anchor high-precision electronics assembly positioning, while FANUC exemplifies captive supply chain advantages through in-house servo motor and controller production. Güdel Group occupies a specialized position in heavy-payload material handling systems for automotive and aerospace applications. These three represent distinct competitive vectors rather than direct substitutes, with specification requirements determining vendor selection more than price positioning.
| Leading Market Players |
|---|
| ABB |
| Omron |
| FANUC |
| Bosch Rexroth |
| Yamaha Robotics |
| KUKA |
| Mitsubishi Electric |
| Güdel Group |
| Yaskawa |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Baden-Württemberg and Lombardy anchor supply-side discipline through generational capital allocation, insulating pricing power from quarterly earnings pressure while concentrating servo motor and linear encoder production in Germany, Italy, and Japan. Their long-horizon ownership structures sustain premium positioning for CE-certified precision systems even as contract manufacturers in Jiangsu province squeeze margins on standardized electronics assembly configurations.
Pricing Analysis
Price erosion across standard electric-drive gantries traces to Foxconn and Luxshare procurement standardization around open-architecture controllers, forcing vendor margin compression through specification homogenization. Three-tier pricing structure across precision-certified, standard-industrial, and economy-modular levels separates pharmaceutical packaging lines requiring FDA validation from logistics material handling systems. Cost-down pressure on economy-tier configurations accelerates because Chinese domestic brands exploit rare-earth magnet supply proximity to undercut European ball-screw mechanisms. Contract manufacturers in electronics assembly exhibit highest price sensitivity; aerospace composite layup systems in Toulouse and Wichita demonstrate lowest sensitivity due to captive specification and extended lead-time tolerance.
Supply Chain Analysis
Dual-sourcing mandates from TSMC and Samsung Display force qualification of redundant linear motor suppliers across Japan, Germany, and South Korea to mitigate single-source vulnerability in magnetic levitation substrate handling. Component sourcing draws from neodymium-dysprosium processors in China, precision ball-screw fabricators in Taiwan, and servo controller specialists in Bavaria. Tariff exposure on rare-earth magnet imports into European assembly plants constitutes the dominant structural risk. Distribution runs through authorized system integrators in regional manufacturing clusters, with direct OEM relationships reserved for high-volume electronics contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-side scarcity in mechatronics-qualified technicians and certified linear encoder fabricators props pricing for precision-tier systems, constraining volume expansion regardless of downstream demand acceleration.
For Market Incumbents: Deploy captive servo motor production to defend margin position against articulated robot substitution in pick-and-place applications. Consolidate software stacks around IEC 61131-3 programmable alternatives to neutralize Foxconn and Luxshare open-architecture procurement mandates. Prioritize certification investment for EU AI Act Category 3 deterministic safety compliance in pharmaceutical packaging lines. For New Entrants and Emerging Players: System integrators in Tamil Nadu and Karnataka represent the most penetrable channel partner type for PLI-scheme electronics manufacturing greenfield construction. Target battery cell stacking automation for lithium-ion electrode layer alignment where hybrid Cartesian-rotary economics beat pure SCARA alternatives. Pursue co-development partnerships with tier-one automotive suppliers seeking die-changing automation without incumbent switching costs. For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed mid-cap linear motor specialists in Baden-Württemberg with dormant CE certification infrastructure and established automotive supplier relationships. Long-term viability hinges on consolidation of fragmented encoder-controller integration capabilities. Watch for inflection in India's electronics manufacturing PLI scheme uptake as signal for greenfield automation specification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Levitation Drive Adoption | Eliminates mechanical contact points for TSMC and Samsung Display Gen 10.5 OLED handling. |
| Open-Architecture Controller Standardization | Enables Foxconn and Luxshare procurement homogenization across Kunshan and Shenzhen facilities. |
| EU AI Act Safety Certification | Determines Category 3 compliance burden for Bavarian and Lombardy machine builders. |
| Rare-Earth Magnet Supply Diversification | Reduces neodymium-dysprosium dependency on Chinese processors for linear motor manufacturers. |
| Mechatronics Technician Training Partnerships | Addresses integration skill scarcity in Jiangsu province electronics fabrication clusters. |
Methodological Framework
Independent corroboration across plant engineer interviews, OEM procurement director surveys, and aftermarket service head consultations underwrites the qualitative findings on specification standardization trends. Secondary validation draws from MIIT GB standard filings, CE Machinery Directive certification databases, FDA pharmaceutical equipment validation records, and SEC 10-K automation capital expenditure disclosures. Bottom-up unit demand modeling triangulates against top-down electronics manufacturing capacity expansion projections across the analysis window.
Rate-of-change decomposition separates volume effects from mix-shift and pricing components across the projection horizon. Segmentation dimensions span product architecture, drive technology, precision tier, application cycle time requirements, and end-user industry automation maturity. CAGRs derive from installed base replacement dynamics and greenfield capacity absorption rates, with semiconductor capital equipment cycles and automotive stamping press utilization serving as industry-specific forecast inputs.
Caveats apply where MIIT GB electromagnetic compatibility enforcement intensity or EU AI Act risk classification thresholds could materially shift the outlook. Deviation in rare-earth magnet export licensing from Chinese processors would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global IT Robotic Automation Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
Commercial Robots Market
Robotics and Automation
Piece Picking Robots Market
Robotics and Automation
GCC AUV Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Market
Robotics and Automation
Service Robotics Market
Robotics and Automation
Global All Terrain Robots Market
Robotics and Automation
Europe Automated Guided Vehicle (AGV) Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market
Robotics and Automation
Smart Lawn Robot Market
Robotics and Automation
Global Entertainment Robots Market
Robotics and Automation
Global Robotic Grippers Market
Robotics and Automation
Global Demolition Robots Market
Robotics and Automation
Robotics Actuators Market
Robotics and Automation
Medical Automation Technologies Market