
 Interference Mitigation Filters Market | 2026-2036
Interference Mitigation Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Interference Mitigation Filters Market Foresight
Ceramic dielectric materials is rebalancing cost-performance trade-offs in compact filter designs for millimeter-wave bands. Murata Manufacturing leverages proprietary ceramic formulations to sustain margin leadership in surface-mount device categories. TDK Corporation anchors high-volume supply through captive ferrite and ceramic powder operations. API Technologies competes in defense-qualified filter segments where ITAR-controlled manufacturing creates barrier positions.
Interference mitigation filters are frequency-selective networks constructed from lumped-element resonators, distributed transmission lines, or acoustic-wave structures, engineered to suppress unwanted signals while preserving desired passband characteristics with insertion loss typically below 3 dB and out-of-band rejection exceeding 40 dB; these devices enable coexistence of densely packed RF systems in shared spectrum environments. Band pass filters carry the largest revenue share where cellular infrastructure demands sharp roll-off and minimal passband ripple. Notch filters represent the fastest-expanding category as radar and satellite systems require deep nulls at specific interference frequencies. Digital filter implementations within software-defined radios are displacing analog counterparts in baseband processing chains, though RF front-ends retain passive filter dominance.
The FCC enforces Part 15 emission limits and Part 27 broadband equipment authorization standards that mandate minimum adjacent-channel rejection, directly dictating filter selectivity specifications for devices sold in the United States. ETSI harmonized standards under the Radio Equipment Directive impose comparable mask requirements across European Union member states, while China's MIIT issues type-approval rules for cellular base station RF performance. Stakeholders must monitor spectrum auction outcomes and corresponding band reassignments to anticipate filter redesign cycles and qualification timelines.

Market Dynamics
Spectrum congestion from 5G densification and satellite constellations is forcing filter architectures toward tighter selectivity and multi-band coexistence, compressing design cycles while elevating qualification burdens for RF component suppliers.
Growth Catalysts
- 5G Mid-Band Expansion:Base station deployments in the 3.5 GHz and 26-28 GHz ranges require ceramic cavity filters with temperature-stable dielectric constants, pulling demand from tower infrastructure providers.
- FCC Part 27 Mandates:Adjacent-channel rejection specifications for Citizens Broadband Radio Service devices mandate minimum 45 dB out-of-band suppression, accelerating redesign cycles for access point manufacturers.
- Satellite Constellation Proliferation:Low-earth orbit terminals for Ku- and Ka-band consumer broadband need compact interference filters to manage cross-polarization leakage from densely packed orbital planes.
Market Restraints
- Palladium Price Volatility:Electrode materials in multilayer ceramic capacitors and associated filter structures face input cost swings that compress margin predictability for passive component fabricators.
- Japanese Ferrite Concentration:High-permeability magnetic powders for EMI suppression filters source predominantly from Tohoku-region suppliers, creating geographic single-point vulnerability.
- Acoustic-Wave Temperature Drift:Surface acoustic wave devices exhibit frequency shift beyond ±30 ppm across military-specified temperature ranges, limiting deployment in aerospace-qualified hardware.
Strategic Opportunities
- India Telecom Infrastructure:Domestic 5G rollout under TRAI spectrum allocation rules creates demand for cost-optimized filter designs serving price-sensitive tower operators.
- Software-Defined Radio Convergence:Digital pre-distortion algorithms paired with reconfigurable analog front-ends enable single hardware platforms to address multiple regional band plans.
- EU Green Deal Procurement:Public sector RF equipment tenders increasingly embed RoHS-III and REACH SVHC compliance as weighted scoring criteria, favoring suppliers with certified material traceability.
Industry Challenges
- Electromagnetic Simulation Talent Scarcity:Finite-element method expertise for 3D electromagnetic field solver operation remains concentrated among legacy defense contractors, constraining design velocity at commercial entrants.
- ITAR-Controlled Test Facilities:Defense-qualified filter validation requires access to anechoic chambers and network analyzers under export-controlled access lists, extending qualification timelines for dual-use product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interference Mitigation Filters Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Pass Filters, High Pass Filters, Band Pass Filters, Notch Filters Technology: Passive Components, Active Components, Digital Filters, Analog Filters End User: Telecommunications, Aerospace, Healthcare, Automotive Application: Signal Processing, RF Transmission, Audio Devices, Precision Equipment |
| Companies Covered | Radio Frequency Systems, TTI, API Technologies, Radio Design UK, Filtronic, TDK Corporation, Murata Manufacturing, TE Connectivity, L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interference Mitigation Filters Market Shifts & Advancements
Material science breakthroughs in temperature-compensated ceramics and substrate-integrated waveguide topologies are compressing filter footprints while preserving insertion loss performance. These advances intersect with regulatory pressure for coexistence in crowded spectrum allocations.
Substrate-integrated waveguide implementations are electrifying millimeter-wave filter designs by embedding guided-wave structures within printed circuit board laminates. Automotive radar suppliers at 77-81 GHz are adopting these topologies to replace bulky metallic waveguide assemblies. The technology is electrifying cost structures in advanced driver-assistance systems by eliminating precision machining steps.
ETSI harmonized standards under the Radio Equipment Directive now mandate receiver blocking and spurious emission test cases that exceed legacy FCC Part 15 stringency for unlicensed devices. European market access requires filter architectures with steeper roll-off characteristics than those serving North American deployments. Module manufacturers are responding by qualifying dual-SKU designs or programmable filter banks with region-selectable response curves.
Defense prime contractors are consolidating supplier bases around qualified filter vendors holding AS9100 and ITAR registration, displacing fragmented procurement across commodity distributors. This concentration shifts bargaining power toward captive sourcing agreements with multi-year volume commitments. The behavioral shift is most pronounced in United States military satellite programs where single-source qualification locks persist across program lifecycles.
Interference Mitigation Filters Market Segmentation
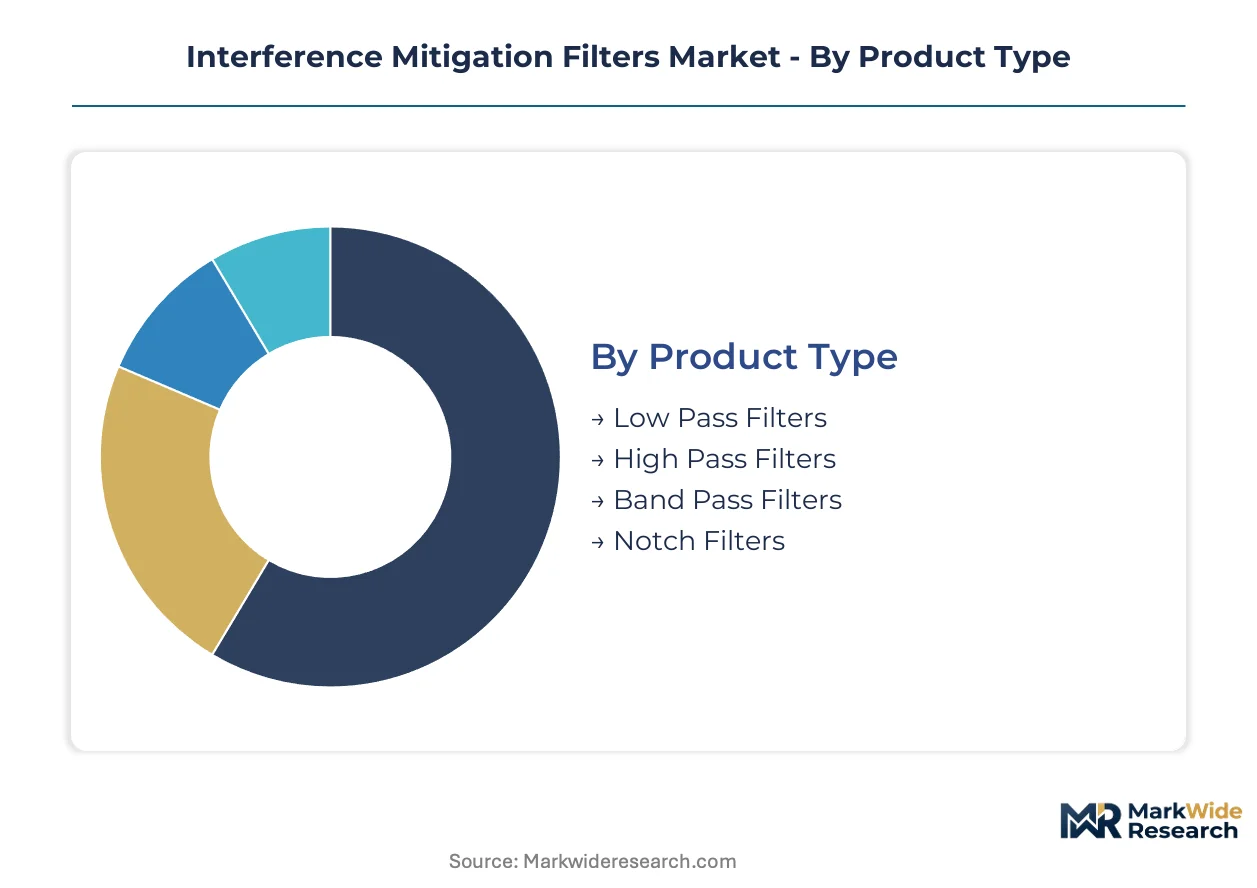
Filter architectures diverge sharply across deployment contexts, with telecommunications infrastructure demanding precision-engineered passive networks while automotive and healthcare sectors prioritize compact integration and electromagnetic compliance. Understanding these segment boundaries clarifies where technology investments concentrate and which qualification standards govern supplier selection.
Product Type:
Buyers in this category distinguish themselves by frequency selectivity requirements and insertion loss tolerance, with cellular infrastructure operators accepting higher unit costs for steep roll-off characteristics while consumer electronics manufacturers optimize for footprint minimization.
- Band Pass Filters:Frequency-selective networks constructed from ceramic resonators or acoustic-wave structures that preserve desired passband characteristics with minimal insertion loss. Demand concentrates in China where domestic 5G base station manufacturing scales rapidly, driven by MIIT type-approval rules mandating sharp adjacent-channel rejection for cellular infrastructure.
- Notch Filters:Deep-null architectures engineered to suppress specific interference frequencies while maintaining broadband signal integrity. Radar and satellite systems in the United States require these devices for cross-polarization leakage management, with FCC Part 27 mandates for CBRS devices accelerating qualification cycles.
- Low Pass Filters:Lumped-element or distributed designs that attenuate frequencies above a defined cutoff threshold. Audio processing chains and precision instrumentation deploy these for harmonic suppression.
- High Pass Filters:Networks blocking DC and low-frequency components while passing RF signals. Baseband processing applications favor these for DC offset removal in receiver front-ends.
Band pass filters lead volumes today; notch filters are gaining share fastest.
Technology:
Cost tier stratification separates this category, with premium-priced active and digital implementations commanding positions in software-defined radios while passive analog variants dominate high-volume cellular deployments.
- Passive Components:Surface-mount ceramic cavity filters and substrate-integrated waveguide assemblies requiring no external power. Tower infrastructure providers in India source these for cost-optimized 5G deployments under TRAI spectrum allocation rules.
- Digital Filters:Algorithmic implementations within software-defined radio baseband processors enabling reconfigurable response curves. These are displacing analog counterparts in multi-band military communications where ITAR-controlled test facilities govern qualification timelines.
- Active Components:Amplifier-integrated architectures providing gain compensation alongside frequency selectivity. Low-noise receiver applications favor these for sensitivity preservation.
- Analog Filters:Traditional LC and RC networks retaining dominance in RF front-ends where power consumption and latency constraints exclude digital alternatives.
Passive components anchor current procurement volumes; digital implementations show the steepest expansion trajectory.
End User:
Application maturity and electromagnetic compliance burden differentiate buyers, with aerospace and healthcare segments demanding AS9100 and FDA-aligned traceability while automotive and telecommunications prioritize volume scalability.
- Telecommunications:Base station OEMs and tower operators requiring temperature-stable dielectric constants for 3.5 GHz and 26-28 GHz deployments. FCC spectrum reallocation mandates in the United States force filter redesign cycles for access point manufacturers.
- Aerospace:Defense prime contractors and satellite operators specifying military-grade temperature stability beyond ±30 ppm across operational ranges. ITAR-controlled manufacturing creates barrier positions for qualified suppliers.
- Healthcare:Medical device manufacturers integrating interference suppression for MRI and patient monitoring equipment. FDA electromagnetic compatibility requirements govern filter selection for diagnostic imaging systems.
- Automotive:Advanced driver-assistance system suppliers adopting substrate-integrated waveguide topologies at 77-81 GHz to replace machined waveguide assemblies.
Telecommunications commands the largest procurement volumes; automotive applications are expanding most quickly.
Application:
Signal fidelity requirements and environmental exposure severity separate this category, with precision equipment and RF transmission applications demanding hermetic packaging while audio devices accept commercial-grade surface-mount alternatives.
- RF Transmission:Power amplifier output filtering and antenna duplexing in cellular base stations and satellite ground terminals. ETSI harmonized standards under the Radio Equipment Directive impose steeper roll-off requirements than FCC Part 15 for European market access.
- Precision Equipment:Test and measurement instrumentation requiring ultra-low phase noise and temperature drift compensation. Swiss and German metrology equipment manufacturers specify these for calibration-grade performance.
- Signal Processing:Baseband and intermediate frequency filtering in communications receivers and software-defined radio platforms.
- Audio Devices:Electromagnetic interference suppression for consumer electronics and professional sound equipment.
RF transmission dominates current demand; precision equipment shows the strongest share growth.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Pearl River Delta hosts the densest concentration of ceramic filter fabrication capacity serving global telecommunications infrastructure. Tower equipment manufacturers in Shenzhen and Dongguan source temperature-stable dielectric components for 3.5 GHz base station deployments. MIIT type-approval rules mandating sharp adjacent-channel rejection compress supplier qualification timelines.
United States
FCC spectrum reallocation mandates for Citizens Broadband Radio Service devices drive filter redesign cycles among access point manufacturers. Part 27 regulations require minimum 45 dB out-of-band suppression specifications. Defense prime contractors in the Washington-Baltimore corridor consolidate procurement around ITAR-registered suppliers for military satellite programs.
Germany
Automotive radar suppliers at 77-81 GHz adopt substrate-integrated waveguide topologies to replace machined assemblies in advanced driver-assistance systems. ETSI harmonized standards under the Radio Equipment Directive impose steeper roll-off requirements than FCC Part 15. Bavarian electronics clusters specialize in precision instrumentation filters for metrology equipment.
Japan
Tohoku-region suppliers dominate high-permeability magnetic powder production for EMI suppression filters. Murata Manufacturing leverages proprietary ceramic formulations to sustain margin leadership in surface-mount device categories. METI industrial policy supports captive ferrite operations through domestic supply chain resilience programs.
India
Domestic 5G rollout under TRAI spectrum allocation rules creates demand for cost-optimized filter designs serving price-sensitive tower operators. Passive component fabricators in Maharashtra and Gujarat scale surface-mount ceramic cavity production. BIS certification requirements for telecommunications equipment extend qualification timelines for imported subsystems.
Interference Mitigation Filters Market Competitive Landscape
Global majors compete with regional champions across qualification standards and supply chain proximity. The vendor base stratifies between defense-qualified specialists holding ITAR registration and high-volume passive component fabricators serving commercial telecommunications. Three archetypes dominate: ceramic formulation specialists with captive material operations, defense-aerospace integrators with AS9100 certification, and diversified electronics conglomerates with scale-driven cost positions. Competitive moves concentrate on backward integration into ferrite and ceramic powder production, plus geographic expansion into India's telecom infrastructure buildout.
Within the defense-qualified tier, API Technologies and L3Harris Technologies exemplify the ITAR-controlled manufacturing barrier position. Murata Manufacturing and TDK Corporation anchor the high-volume passive component segment with proprietary ceramic formulations and captive material operations. Radio Frequency Systems occupies a position between these poles, serving both commercial infrastructure and select defense applications.
| Leading Market Players |
|---|
| Radio Frequency Systems |
| TTI |
| API Technologies |
| Radio Design UK |
| Filtronic |
| TDK Corporation |
| Murata Manufacturing |
| TE Connectivity |
| L3Harris Technologies |
| Others |
Supply & Pricing Matrix
EU Green Deal procurement mandates now gate qualified supply access and premium-tier pricing eligibility for interference mitigation filter vendors serving European public sector RF equipment tenders. REACH SVHC compliance and RoHS-III certification function as weighted scoring criteria, effectively bifurcating the supplier base between traceability-certified premium tier and commodity-standard alternatives.
Pricing Analysis
Input-cost pass-through from palladium electrode materials and high-permeability ferrite powders directly shapes margin structures across passive component fabricators. Three-tier pricing structure across ITAR-registered defense-qualified, AS9100-certified aerospace, and commercial telecommunications tiers separates buyers by certification burden and volume scale. Cost compression in the commercial tier is intensifying as Chinese domestic base station manufacturers leverage local ceramic supply chains. Tower operators in India exhibit highest price sensitivity, while defense prime contractors in the United States demonstrate lowest elasticity due to single-source qualification locks.
Supply Chain Analysis
Freight cost escalation for ceramic powder and ferrite shipments from Japan's Tohoku region to filter fabrication facilities in China's Pearl River Delta compresses margin predictability for surface-mount device producers. Supply concentrates in China for ceramic resonator fabrication, Japan for high-permeability magnetic powders, and Germany for precision instrumentation substrates. Raw material dependencies span temperature-stable dielectric ceramics, palladium electrode pastes, and captive ferrite formulations. Single-source vulnerability from Japanese ferrite concentration creates geographic chokepoint exposure. Distribution runs through tower infrastructure providers, defense prime contractors, and automotive Tier 1 suppliers with divergent qualification timelines.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where 5G mid-band infrastructure specifications are tightening adjacent-channel rejection thresholds beyond legacy FCC Part 15 baselines, elevating premium-tier filter architectures.
For Market Incumbents: Anchor margin position through backward integration into captive ceramic powder operations following TDK Corporation's captive ferrite model. Defend against digital filter displacement in software-defined radio baseband processing by accelerating substrate-integrated waveguide qualification for millimeter-wave front-ends. ITAR-registered suppliers should consolidate defense procurement relationships through multi-year volume commitments before qualification windows close.
For New Entrants and Emerging Players: Capture white-space in India's domestic 5G rollout under TRAI spectrum allocation rules, where cost-optimized passive designs serve price-sensitive tower operators with shorter qualification cycles. Target automotive radar suppliers at 77-81 GHz adopting substrate-integrated waveguide topologies to displace machined waveguide assemblies. Lead with BIS certification pre-investment to bypass import subsystem delays.
For Investors and Strategic Acquirers: Roll-up economics work for ceramic formulation specialists with proprietary dielectric recipes because defense prime contractor consolidation around qualified vendor bases creates captive sourcing demand with decade-long program locks. Platform viability extends across the analysis window for AS9100-certified filter integrators serving military satellite programs. Watch FCC spectrum auction outcomes as inflection signals triggering redesign cycle velocity and qualification pipeline expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Operations | TDK Corporation's captive ferrite supply anchors margin leadership against palladium price volatility. |
| ITAR Registration and AS9100 Certification Investment | Defense prime contractor consolidation creates barrier positions for qualified military satellite suppliers. |
| Substrate-Integrated Waveguide Topology Adoption | Automotive radar suppliers at 77-81 GHz eliminate precision machining steps from advanced driver-assistance systems. |
| Digital Pre-Distortion Algorithm Development | Software-defined radio convergence enables single hardware platforms to address multiple regional band plans. |
| India Manufacturing Footprint Establishment | TRAI spectrum allocation rules create demand for cost-optimized designs serving domestic tower operators. |
Research Methodology
Bottom-up telecommunications infrastructure modeling reconciled against top-down ceramic filter supply tracking forms the analytical core of this study. Primary interviews with RF component procurement managers at tower operators, filter design engineers at defense contractors, ceramic materials specialists, and regulatory affairs leads at base station OEMs combined with secondary validation from FCC Part 27 equipment authorization databases, ETSI harmonized standards filings under the Radio Equipment Directive, MIIT type-approval records, and customs trade data for ferrite and ceramic powder shipments.
Input-output matrix framing connects base station deployment trajectories across 3.5 GHz and 26-28 GHz bands to ceramic resonator and acoustic-wave filter production capacities. Segmentation dimensions span product architecture, technology implementation, end-use sector, and application context across the projection horizon. CAGRs derive from unit economics modeling of filter content per base station, satellite terminal, and automotive radar assembly, cross-referenced against spectrum auction timelines and regulatory mandate effective dates.
Underlying measurement precision varies by segment; defense-qualified and aerospace-certified filters carry tighter precision than commercial telecommunications volumes due to visible program-level procurement data. Forecasts reflect assumptions regarding 5G densification velocity, satellite constellation deployment rates, and automotive radar adoption curves. Stakeholders should weight assumptions against their own operating context regarding qualification timeline exposure and geographic supply concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Food Fiber Market
Others
Semiconductor Gas Filters Market
Others
Drum Motor Market
Others
Molecular Spectroscopy Market
Others
North America Commercial Vehicles Lubricants Market
Others
Heat Treatment Furnace Market
Others
Smart Home Controller Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market
Others
Nanomedicine for Drug Delivery Market
Others
Mainframe Market
Others
Smart Card Market
Others
Halogen Free Flame Retardant Bopet Films Market
Others
India Foundry Market
Others
Global Process Equipment Market
Others
Folding Mobile Phone Market
Others
Smart Card Contactless Ticketing Market