
 Japan Smart Home Market | 2026-2036
Japan Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Smart Home Market Insights
Residential healthcare integration is shifting the center of gravity in Japanese smart home deployments. Panasonic Corporation leverages its long-standing eldercare appliance heritage to anchor connected wellness platforms in suburban Osaka and Nagoya markets. Sony Group Corporation competes through ambient sensing and entertainment convergence, while Mitsubishi Electric Corporation dominates climate-intelligent building management with proprietary heat-pump-to-grid communication protocols.
Smart home technology encompasses residential systems that network lighting, security, climate, and appliance controls through unified communication protocols such as Zigbee 3.0 and Matter-compatible Wi-Fi mesh, enabling automated energy optimization and occupant safety monitoring. Home Automation commands the deepest margin pools through whole-house integration contracts, while Smart Security records the fastest expansion as facial recognition entry systems and AI-enabled surveillance penetrate Tokyo condominium developments. Smart Lighting sustains volume leadership through LED retrofit cycles tied to building energy codes.
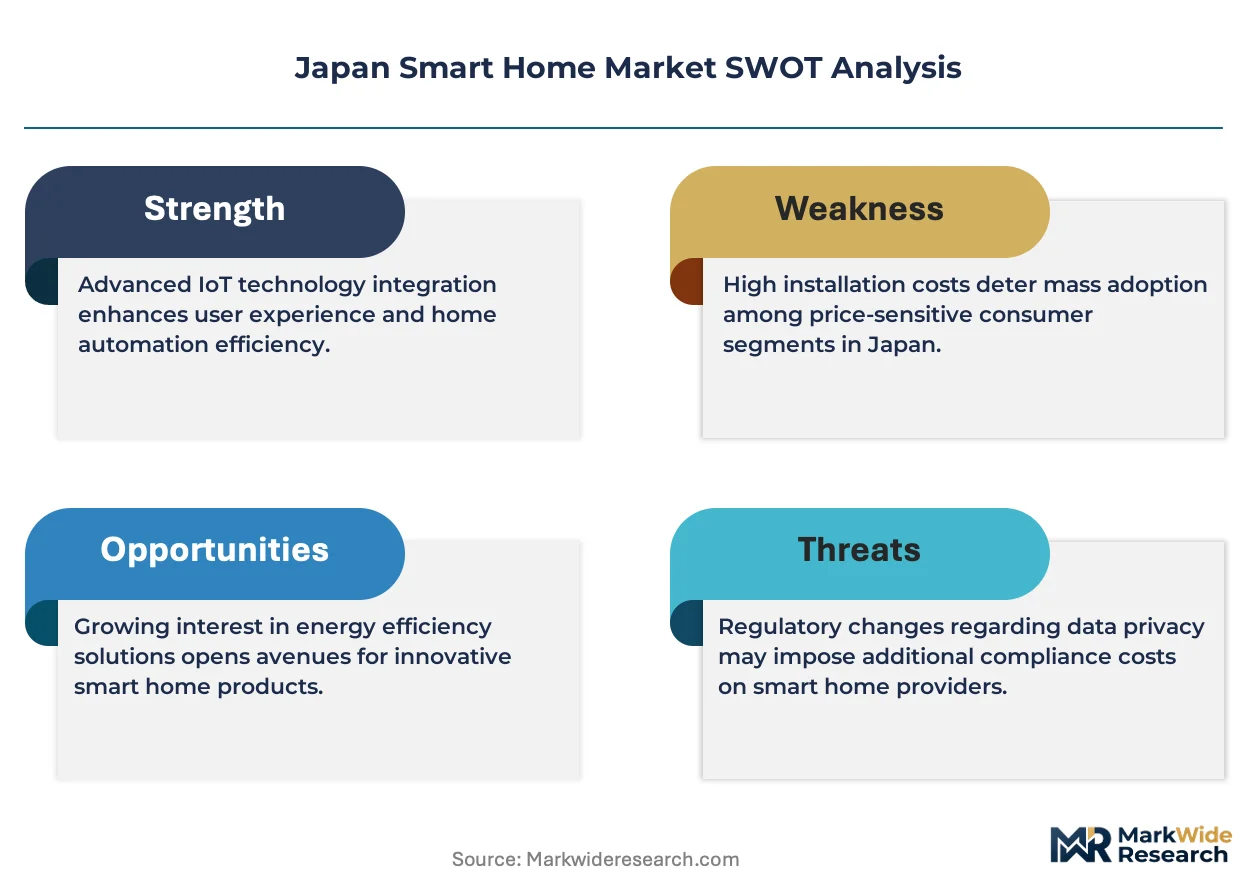
METI enforces interoperability standards under the Society 5.0 framework, while JIS standards govern device safety and electromagnetic compatibility for residential electrical equipment. PMDA oversight extends to connected medical devices that stream biometric data from smart home environments to clinical providers. Stakeholders must track how forthcoming amendments to Japan's Building Energy Efficiency Act will mandate smart meter integration in new construction and major renovations.
Market Dynamics
Japan's smart home sector pivots on METI's carbon-neutral housing mandates, which embed intelligent energy management into every major renovation and new construction project across the archipelago.
Growth Catalysts
- Society 5.0 Framework:METI's interoperability standards accelerate device-to-device communication across Zigbee 3.0 and Matter protocols, reducing integration friction for residential developers.
- Aging-in-place demand:Elderly homeowners in suburban Osaka and Nagoya drive connected health monitoring adoption, linking biometric sensors to clinical providers through PMDA-regulated data streams.
- Building Energy Efficiency Act amendments:Pending mandates for smart meter integration in major renovations create compulsory upgrade cycles across Greater Tokyo's dense condominium stock.
Market Restraints
- Semiconductor input volatility:Wi-Fi mesh and sensor chip supply concentrates in East Asian foundries, exposing Japanese OEMs to geopolitical disruption and input cost spikes.
- Legacy electrical infrastructure:Pre-1990s housing stock lacks neutral wiring required for intelligent load management, forcing expensive retrofitting before smart thermostat deployment.
- JIS certification timelines:Electromagnetic compatibility testing for residential electrical equipment extends product launch windows by 8-14 months versus unregulated markets.
Strategic Opportunities
- Rural Hokkaido penetration:Underconnected prefectures outside Kanto present first-mover advantage for solar-integrated smart home packages tied to agricultural property management.
- Healthcare-construction convergence:PMDA's expanding oversight of connected medical devices creates regulatory tailwind for platforms streaming fall-detection and medication-adherence data to insurers.
- Matter-Wi-Fi 6E convergence:Unified protocol stacks enable cross-brand automation previously fragmented by proprietary ecosystems, opening whole-house integration contracts to new entrants.
Industry Challenges
- Systems integration skill scarcity:Shortage of technicians certified in both electrical installation and network configuration slows deployment of whole-home automation in regional markets.
- Multi-protocol legacy entanglement:Existing ECHONET Lite installations resist seamless migration to Matter-compatible architectures, forcing parallel infrastructure maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Smart Home Market |
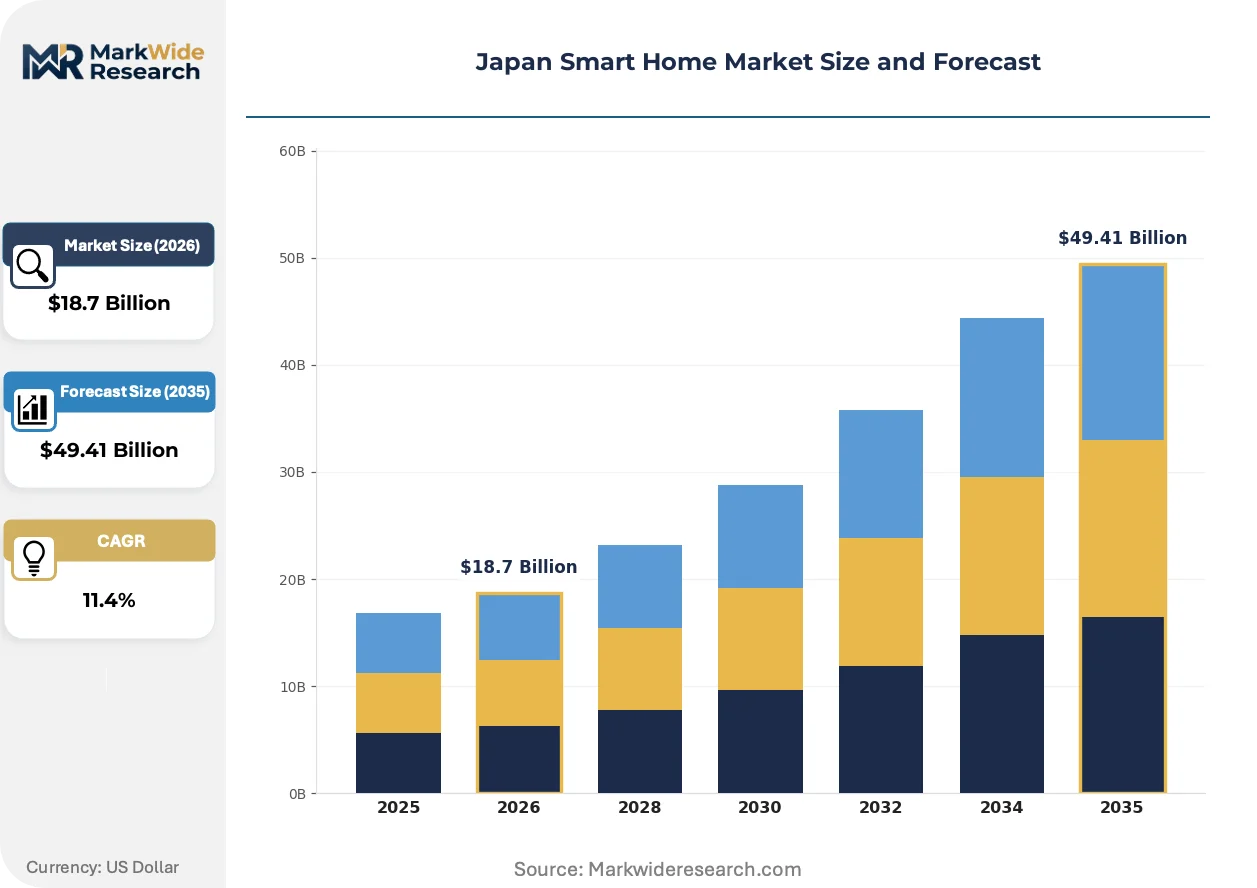
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Smart Security, Smart Appliances, Home Automation Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth End User: Homeowners, Renters, Property Managers, Real Estate Developers Installation: Self-Installed, Professional Installed, Hybrid, Smart Device Bundles |
| Companies Covered | Panasonic Corporation, Hitachi, Ltd., Sharp Corporation, Toshiba Corporation, Sony Group Corporation, Mitsubishi Electric Corporation, Fujitsu General, Schneider Electric SE, ABB Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Smart Home Market Trends and Innovations
Protocol convergence is collapsing the fragmentation that long segmented Japanese smart home deployments into incompatible vendor silos. Three developments dominate the current transformation.
Matter-compatible Wi-Fi mesh is unifying device communication across previously isolated lighting, security, and climate subsystems. Major Tokyo condominium developers now specify cross-brand interoperability as a procurement requirement. This unification compresses vendor lock-in and enables modular upgrades without ecosystem replacement.
METI's forthcoming Building Energy Efficiency Act amendments mandate smart meter integration in all new construction and major renovations. The regulation forces electrical contractors to acquire IoT commissioning capabilities. Prefecture-level building departments in Kanagawa and Saitama are already piloting automated compliance verification systems.
After-sales service unbundling is disrupting the traditional equipment-plus-installation bundle. Tokyo-area property management firms now procure smart security and climate systems through separate SaaS subscriptions rather than capital expenditure. This shift concentrates purchasing authority with facility managers rather than construction-phase specifiers.
Japan Smart Home Market Segmentation
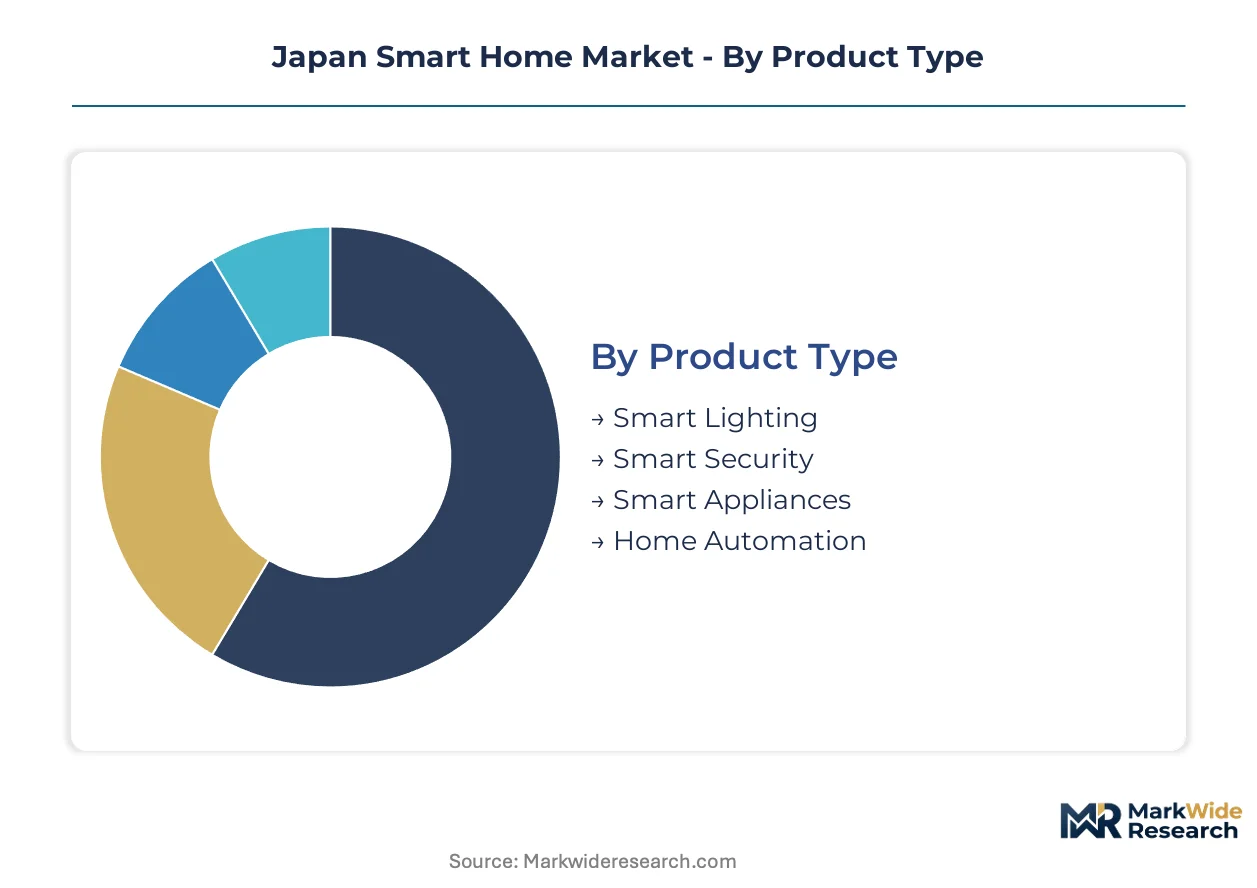
Segmentation in Japan's smart home market reveals how regulatory mandates, aging demographics, and housing stock characteristics shape purchasing patterns. METI's carbon-neutral housing requirements and PMDA's connected health oversight create distinct demand profiles across product categories and customer types. Understanding these divisions enables precise targeting of the Greater Tokyo Area's dense condominium stock versus suburban Osaka-Nagoya eldercare installations.
Product Type:
Standardization dominates entry-level categories while premium integration commands customization depth across this spectrum.
- Home Automation:Whole-house control systems integrate lighting, climate, security, and appliance management through unified dashboards. Demand concentrates in Greater Tokyo new construction where METI's Building Energy Efficiency Act amendments mandate intelligent load management, though systems integration skill scarcity slows regional deployment.
- Smart Security:Facial recognition entry systems and AI-enabled surveillance platforms protect residential assets. Tokyo condominium developers specify these as procurement requirements, with SaaS subscription models displacing capital expenditure purchases among property management firms.
- Smart Lighting:LED retrofit cycles tied to building energy codes sustain volume leadership through matter-compatible mesh networks.
- Smart Appliances:Connected refrigeration, laundry, and cooking equipment with remote diagnostics and energy optimization protocols.
Most installed capacity flows through Smart Lighting. Expansion is steepest in Smart Security.
Technology:
Protocol maturity determines deployment cost and interoperability reach across Japanese residential infrastructure.
- Wi-Fi:Matter-compatible Wi-Fi 6E mesh networks unify previously fragmented subsystems through cross-brand communication. Greater Tokyo developers now specify this as mandatory procurement criteria, collapsing vendor lock-in and enabling modular upgrades without ecosystem replacement.
- Zigbee:Zigbee 3.0 protocols power low-energy lighting and sensor networks with established JIS electromagnetic compatibility certification. Suburban Osaka and Nagoya eldercare installations favor this stable standard for connected health monitoring reliability.
- Bluetooth:Short-range device pairing for mobile-configured point solutions and wearable health integrations.
- Z-Wave:Sub-GHz mesh alternative for legacy installations requiring penetration through dense building materials.
Wi-Fi captures the greatest deployment volume. Zigbee maintains the steepest expansion trajectory in healthcare-construction convergence applications.
End User:
Purchasing authority shifts from construction-phase specifiers to operational facility managers across this customer hierarchy.
- Property Managers:Tokyo-area firms now procure smart security and climate through separate SaaS subscriptions rather than bundled capital expenditure. This unbundling concentrates ongoing purchasing authority with operational stakeholders managing Greater Tokyo's dense condominium stock.
- Homeowners:Aging-in-place demand among elderly homeowners in suburban Osaka and Nagoya drives connected health monitoring adoption, linking biometric sensors to clinical providers through PMDA-regulated data streams.
- Real Estate Developers:New construction specifiers integrating METI-mandated smart meter and energy management infrastructure.
- Renters:Mobile-configured point solutions requiring minimal installation and lease-friendly portability.
Homeowners represent the largest installed base. Property Managers are gaining share fastest through service unbundling.
Installation:
Technical complexity and legacy infrastructure constraints determine deployment methodology across housing vintages.
- Professional Installed:Certified technicians handle whole-home automation requiring neutral wiring upgrades in pre-1990s housing stock. Systems integration skill scarcity slows deployment in regional markets outside Greater Tokyo, forcing premium pricing for qualified electrical-network dual certification.
- Hybrid:Professional backbone installation with homeowner-configured device onboarding balances reliability and flexibility. This model dominates suburban Nagoya eldercare retrofits where PMDA-connected medical devices require certified commissioning.
- Self-Installed:Consumer-configured point solutions for Wi-Fi and Bluetooth devices in newer construction with existing neutral wiring.
- Smart Device Bundles:Pre-integrated packages from single vendors with simplified setup protocols.
Professional Installed channels handle the most complex deployments. Hybrid approaches are climbing the fastest as technical scarcity meets consumer configuration preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Tokyo Area concentrates Japan's smart home demand through dense condominium stock and high disposable incomes supporting premium installations. METI's carbon-neutral housing mandates and PMDA-connected health regulations shape deployment patterns across sub-regional markets.
Kanto/Tokyo
Tokyo condominium developers specify cross-brand Matter-compatible interoperability as mandatory procurement criteria. METI's Building Energy Efficiency Act amendments force smart meter integration into new construction and major renovations across Kanagawa and Saitama prefectures. Dense urban housing stock in central Tokyo and Yokohama sustains whole-house automation contracts through SaaS subscription models displacing capital expenditure.
Kansai/Osaka
Suburban Osaka eldercare installations drive connected health monitoring adoption linking biometric sensors to clinical providers. PMDA oversight of streaming medical devices creates regulatory tailwind for fall-detection and medication-adherence platforms. Panasonic Corporation leverages its eldercare appliance heritage to anchor connected wellness platforms in Osaka's aging homeowner districts.
Chubu/Nagoya
Nagoya's automotive supplier ecosystem generates demand for intelligent load management in company housing and executive residences. JIS electromagnetic compatibility certification requirements extend product launch windows for regional electrical contractors. Hybrid professional-consumer installation models dominate eldercare retrofits where certified commissioning meets consumer configuration preferences.
Kyushu
Fukuoka's technology startup concentration incubates smart home SaaS platforms targeting property management firms. Legacy ECHONET Lite installations resist seamless Matter migration, forcing parallel infrastructure maintenance. Regional systems integration skill scarcity slows whole-home automation deployment outside major metropolitan zones.
Hokkaido
Rural agricultural property management creates first-mover opportunity for solar-integrated smart home packages. Underconnected prefecture status outside Kanto reduces competition for qualified electrical-network dual certification technicians. Sapporo's colder climate intensifies demand for Mitsubishi Electric's climate-intelligent heat-pump-to-grid communication protocols.
Japan Smart Home Market Competitive Landscape
Portfolio diversification dominates the current landscape as established electronics conglomerates extend appliance heritage into connected platforms. The vendor base clusters around three strategic archetypes: diversified electronics conglomerates with eldercare legacies, climate-specialized industrial manufacturers, and entertainment-technology convergers. M&A activity concentrates on healthcare-construction convergence capabilities, while technology licensing partnerships accelerate Matter protocol adoption across proprietary legacy ecosystems.
Within the diversified electronics tier, Panasonic Corporation and Sony Group Corporation exemplify contrasting positioning strategies. Panasonic anchors suburban Osaka-Nagoya eldercare markets through connected wellness platforms leveraging decades of appliance heritage. Sony occupies the ambient sensing and entertainment convergence vector targeting Tokyo's premium condominium developments. Mitsubishi Electric Corporation represents the climate-specialized industrial archetype, dominating heat-pump-to-grid intelligence through proprietary communication protocols. These three players illustrate how divergent heritage assets—appliance manufacturing, entertainment technology, industrial climate systems—map onto distinct smart home sub-segments under METI's interoperability mandates.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Hitachi, Ltd. |
| Sharp Corporation |
| Toshiba Corporation |
| Sony Group Corporation |
| Mitsubishi Electric Corporation |
| Fujitsu General |
| Schneider Electric SE |
| ABB Ltd. |
| Others |
Pricing and Supply Chain Analysis
Matter-compatible Wi-Fi 6E mesh deployment simultaneously compresses integration costs and concentrates component sourcing among East Asian semiconductor foundries serving Japanese OEMs. METI's interoperability mandates accelerate protocol unification while tightening margin pressure on legacy proprietary ecosystem vendors.
Pricing Analysis
Input-cost pass-through from Wi-Fi mesh and sensor chip volatility shapes tiered pricing across installation categories. Three-tier pricing structure across premium whole-house automation, standard security-climate bundles, and economy point solutions differentiates by certification depth and after-sales service bundling. Pricing pressure stems from semiconductor input volatility exposing Japanese OEMs to geopolitical disruption. Property managers demonstrate highest price sensitivity through SaaS subscription procurement, while real estate developers absorb premium pricing for METI-compliant new construction.
Supply Chain Analysis
Japan's domestic-content alignment with METI's Society 5.0 framework reshapes sourcing toward JIS-certified component suppliers. Wi-Fi and Zigbee chip fabrication concentrates in Taiwan, South Korea, and mainland China. Japanese OEMs draw from East Asian foundries for sensor modules, communication chipsets, and LED driver components. Single-source vulnerability around advanced node semiconductor production creates structural risk. Distribution runs through electrical contractors acquiring IoT commissioning capabilities and Tokyo-area property management firms procuring through SaaS platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Protocol convergence and service unbundling expand margin pools for players capturing healthcare-construction convergence and SaaS recurring revenue. Cost compression in legacy proprietary ecosystems accelerates premium-tier shift toward whole-house integration contracts.
For Market Incumbents: Hedge against Matter protocol commoditization by deepening eldercare platform differentiation through PMDA-connected medical device certification. Acquire systems integration capabilities in regional markets outside Greater Tokyo to address skill scarcity. Defend margin position through captive supply of JIS-certified electromagnetic compatibility testing infrastructure. For New Entrants and Emerging Players: METI's Building Energy Efficiency Act amendments in Japan open a window for smart meter integration specialists targeting Kanagawa and Saitama prefecture pilot programs. Rural Hokkaido agricultural property management presents underpenetrated white-space for solar-integrated packages. Hybrid professional-consumer installation models penetrate suburban Nagoya eldercare retrofits fastest. For Investors and Strategic Acquirers: Valuations sit cheapest among regional systems integration specialists with electrical-network dual certification. Long-term viability centers on healthcare-construction convergence platforms streaming PMDA-regulated biometric data to insurers. Watch for PMDA expanding connected medical device oversight as inflection signal for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Certification Investment | Accelerates regulatory approval for fall-detection platforms streaming to clinical providers. |
| Matter Protocol Migration | Enables cross-brand automation contracts previously fragmented by proprietary ECHONET Lite ecosystems. |
| SaaS Service Unbundling | Captures recurring revenue from Tokyo property management firms displacing capital expenditure. |
| Regional Systems Integration Acquisition | Addresses skill scarcity slowing whole-home automation deployment outside Greater Tokyo. |
| Healthcare-Construction Convergence Platform | Links Panasonic's eldercare appliance heritage to PMDA-regulated medication-adherence data streams. |
Research Methodology
Direct dialogue with smart home platform engineers, electrical contractors, property management procurement officers, and PMDA regulatory affairs specialists grounded qualitative insights. Secondary validation drew from METI policy announcements, JIS certification databases, Building Energy Efficiency Act amendment drafts, and condominium developer procurement specifications. Bottom-up installation volume estimates triangulated with top-down energy management mandate penetration assumptions.
Market size and growth trajectory outputs calibrated segment-level expansion across home automation, smart security, smart lighting, and smart appliances through the projection horizon. Technology segmentation modeled Wi-Fi, Zigbee, Bluetooth, and Z-Wave protocol adoption curves. End-user dynamics incorporated property manager SaaS procurement shifts and aging-in-place homeowner demand patterns. CAGRs derived from regulatory mandate timing, housing stock renovation cycles, and semiconductor supply normalization assumptions.
Revisions become necessary when METI accelerates Building Energy Efficiency Act enforcement timelines, PMDA expands connected medical device oversight scope, or East Asian foundry capacity disruption intensifies. Forecasts reflect documented assumptions around protocol convergence speed and systems integration skill development. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Solar Lighting Tower Market
Others
Silicone Molding Machinery Market
Others
Dental Ceramics Market
Others
Smart Home and Office Market
Others
Video Paas Market
Others
Solar Animal Repeller Market
Others
Tripod Market
Others
Magnesite Market
Others
Moonstone Market
Others
Global Duty-Free Retailing Market
Others
Asia Pacific Foodservice Paper Packaging Market
Others
Storm Surge Barriers Market
Others
Tanned Fish Skin Leather Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market
Others
South Korea Automotive LED Lighting Market
Others
Global Contactless Biometrics Technology Market