
 Lepidolite Market | 2026-2036
Lepidolite Market Size, Share, and Industry Trends Forecast 2026-2036
Lepidolite Market Analysis
A capital-intensity divergence between integrated miners and downstream refiners is reorganizing competitive tiers in lepidolite processing. Albemarle Corporation leverages its Chilean brine expertise to benchmark lithium carbonate purity standards against hard-rock alternatives. Ganfeng Lithium anchors its cost position through captive mining rights in Jiangxi and vertical spodumene-lepidolite blending capabilities. Tianqi Lithium competes by sustaining dual-source supply flexibility across Australian spodumene and African lepidolite offtake.
Lepidolite is a phyllosilicate mineral of the mica group containing lithium, aluminum, and potassium in its crystalline structure, typically grading 1.5% to 5.5% lithium oxide content that requires calcination and acid roasting to liberate battery-grade lithium compounds. Its primary industrial purpose centers on lithium extraction for lithium-ion battery cathodes, with secondary applications in specialty glass fluxing and ceramic glaze formulations. Raw lepidolite concentrates command processing premiums due to elevated impurity levels versus spodumene, while lepidolite powder sales into ceramics and glass manufacturing represent mature margin pools with limited pricing volatility. Electronics applications through battery-grade lithium chemicals represent the fastest-expanding consumption vector, though jewelry and gemstone segments occupy stable niche positions among artisanal collectors.
China's MIIT sets mandatory lithium carbonate purity thresholds for domestic battery supply chain qualification, while the EU Critical Raw Materials Act imposes recycled content benchmarks and origin disclosure rules on imported lithium. The US Inflation Reduction Act ties clean vehicle tax credits to critical mineral sourcing from free-trade agreement partners, reshaping which lepidolite deposits qualify for North American battery supply chains. Stakeholders must monitor evolving FTA eligibility lists and carbon intensity accounting methodologies to determine which processing routes retain competitive access across major demand jurisdictions.
Market Dynamics
Battery-grade lithium carbonate extraction from lepidolite ore is accelerating as automakers diversify cathode supply chains beyond spodumene and brine sources, tightening purity standards and traceability requirements across major demand jurisdictions.
Growth Catalysts
- EU Critical Raw Materials Act:Mandatory recycled content benchmarks and origin disclosure rules for imported lithium are creating structured demand for traceable hard-rock feedstocks.
- Acid roasting efficiency gains:Integrated refiners in Jiangxi Province are achieving higher lithium recovery rates from low-grade lepidolite concentrates through optimized calcination sequences.
- Automaker cathode diversification:European and North American EV manufacturers are qualifying alternative lithium sources to reduce dependence on concentrated brine supply chains.
Market Restraints
- Impurity processing premiums:Elevated fluorine and rubidium content in lepidolite concentrates requires additional purification stages versus spodumene, compressing refiner margins.
- Jiangxi supply concentration:Over two-thirds of global lepidolite processing capacity sits within a single Chinese province, creating geographic vulnerability to environmental compliance disruptions.
- US Inflation Reduction Act FTA restrictions:Clean vehicle tax credit eligibility excludes non-free-trade-agreement lepidolite sources, disqualifying much of current Chinese supply from North American battery chains.
Strategic Opportunities
- Brazilian hard-rock development:Underexplored lepidolite-bearing pegmatite districts in Minas Gerais offer FTA-compliant feedstock potential for US-qualified supply chains.
- Direct shipping ore bypass:Emerging concentrator-to-refiner tolling arrangements allow asset-light processors to access captive mining rights without full vertical integration.
- MIIT battery material purity tiering:China's Ministry of Industry and Information Technology is creating premium qualification tracks for ultra-high-purity lithium carbonate, rewarding advanced refining investments.
Industry Challenges
- Pyrometallurgical engineering scarcity:Qualified technicians capable of optimizing rotary kiln parameters for variable lepidolite ore grades command premium wages across Jiangxi's processing corridor.
- Carbon intensity accounting complexity:Divergent methodologies between EU CBAM, US Treasury guidance, and Chinese provincial standards create compliance fragmentation for exported lithium chemicals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lepidolite Market |
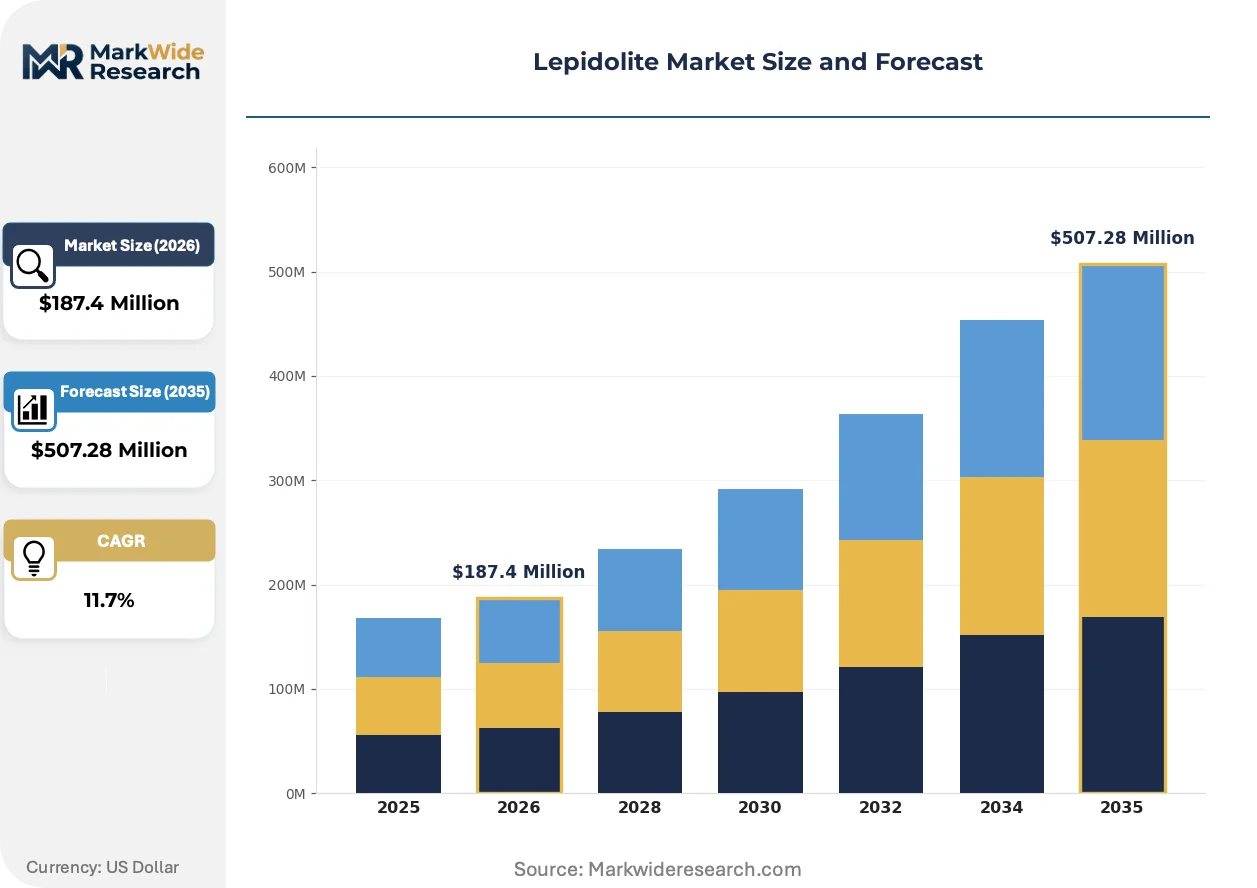
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Lepidolite, Lepidolite Powder, Lepidolite Crystal, Lepidolite Gemstone Application: Electronics, Glass Manufacturing, Ceramics, Jewelry End User: Mining Companies, Manufacturers, Retailers, Jewelry Designers Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | SQM, Mineral Resources Limited, Ganfeng Lithium, CATL, Lithium Americas Corp., Tianqi Lithium, Rio Tinto, Zijin Mining Group, Albemarle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lepidolite Market Emerging Trajectories
Processing technology is splitting into distinct efficiency tiers while regulatory jurisdictions compete to define acceptable carbon thresholds for battery material qualification.
Calcination-acid roasting integration is bifurcating competitive tiers in lepidolite refining. Advanced operators are achieving 85% plus lithium recovery rates through continuous kiln systems. This technology compression is marginalizing batch-processing facilities with legacy equipment configurations.
REACH authorization requirements for process chemicals are tightening solvent recovery mandates across EU-bound lithium chemical production. Refiners serving European cathode manufacturers must now demonstrate closed-loop acid management. German and French battery material importers are prioritizing suppliers with verified environmental management system certifications.
Long-term offtake contracting is displacing spot market purchasing among tier-one cathode producers. Korean and Japanese battery manufacturers are securing five-year minimum supply agreements with embedded price adjustment mechanisms. This procurement consolidation is visible across Jiangxi's integrated refiner negotiations with Seoul and Tokyo-based buyers.
Lepidolite Market Segmentation
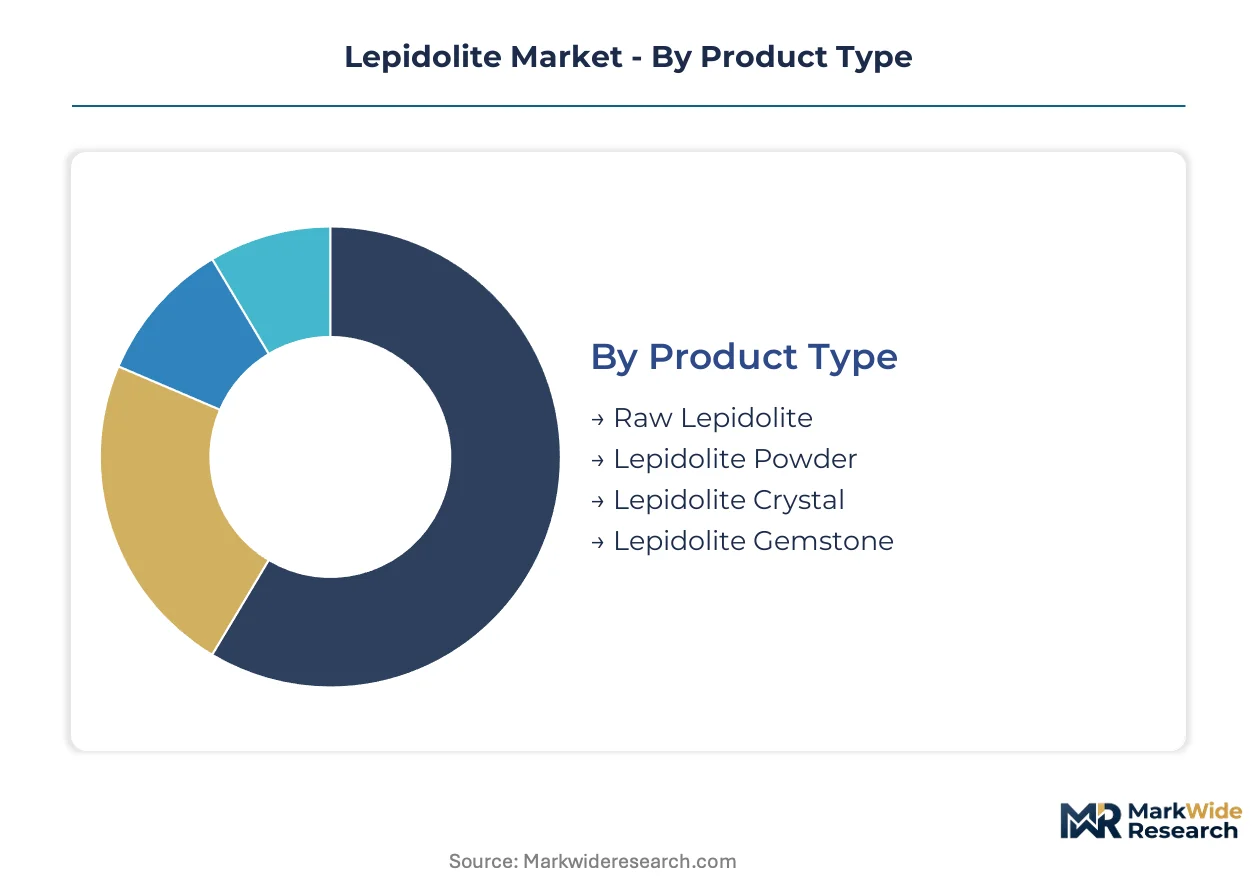
Lepidolite market segmentation reveals divergent margin structures across product forms and starkly different channel economics between industrial buyers and artisanal consumers. Understanding these segment boundaries clarifies where capital deployment generates sustainable returns versus commodity exposure.
Product Type:
Channel-mix patterns separate bulk industrial feedstocks from value-added processed forms, with raw material flows concentrating in long-term supply contracts while refined products fragment across spot and specialty purchasing.
- Raw Lepidolite:Unprocessed ore concentrates grading 1.5% to 5.5% lithium oxide content, shipped directly from mining operations to integrated refiners or toll processors. Demand concentrates in Jiangxi Province's processing corridor, where calcination and acid roasting facilities require consistent feedstock quality to maintain recovery rates above 85%.
- Lepidolite Powder:Finely milled material serving glass fluxing and ceramic glaze applications, with particle size distributions tailored to specific industrial specifications. European specialty glass manufacturers in Germany and France represent the primary demand concentration, driven by REACH-compliant sourcing requirements for process traceability.
- Lepidolite Crystal:Coarsely crushed or partially refined material for industrial mineral applications, including lithium chemical precursors and specialty ceramics. Chinese refractory manufacturers in Henan Province absorb significant volumes for high-temperature ceramic production.
- Lepidolite Gemstone:Selectively extracted and cut material for jewelry and collector markets, with color and clarity grading determining value tiers. Artisanal cutters in Jaipur and Bangkok process rough material for North American and European retail channels.
Raw lepidolite dominates installed base by tonnage. Lepidolite powder is where expansion concentrates as battery-grade lithium carbonate demand tightens hard-rock feedstock markets.
Application:
Cost-tier differentiation separates high-purity battery chemical pathways from mature industrial uses with limited pricing volatility and stable margin pools.
- Electronics:Battery-grade lithium carbonate and lithium hydroxide production for lithium-ion cathode manufacturing, requiring impurity levels below 20 ppm for nickel-cobalt-manganese formulations. Korean and Japanese battery manufacturers in Seoul and Tokyo metropolitan areas anchor demand concentration, with five-year offtake contracting displacing spot purchasing.
- Glass Manufacturing:Fluxing agent in specialty borosilicate and lithium-aluminosilicate glass production, lowering melting temperatures and improving thermal expansion coefficients. German optical glass producers in Schott's traditional manufacturing regions maintain steady demand for certified material batches.
- Ceramics:Glaze opacifier and body flux in sanitary ware, tableware, and technical ceramics, with rubidium and cesium byproduct recovery adding margin contribution. Italian ceramic tile manufacturers in Sassuolo and Spanish producers in Castellón represent established European demand centers.
- Jewelry:Cabochon and faceted gemstone production for artisanal collectors, with pink to purple coloration from manganese content driving aesthetic valuation. Bangkok's gemstone cutting district channels material to North American and European specialty retailers.
Electronics commands premium pricing tiers. Glass manufacturing and ceramics represent stable volume anchors with limited cyclicality.
End User:
Customer-type fragmentation creates distinct procurement patterns, with integrated miners negotiating long-term supply agreements while fragmented downstream buyers operate on shorter purchasing cycles.
- Mining Companies:Hard-rock lithium producers seeking lepidolite as supplementary feedstock to diversify beyond spodumene dependence, often through joint venture structures with Jiangxi-based processors. Ganfeng Lithium's captive mining rights exemplify upstream control strategies in this segment.
- Manufacturers:Glass, ceramic, and chemical processors requiring consistent mineral specifications and batch certification, with German and French importers prioritizing suppliers with verified environmental management system certifications.
- Retailers:Gemstone and mineral specimen vendors serving collector markets, with online platforms and specialty trade shows driving price discovery for aesthetic-grade material.
- Jewelry Designers:Artisanal creators sourcing cut stones for bespoke pieces, with Jaipur's cutting houses and Bangkok's gemstone district serving as primary supply intermediaries.
Manufacturers dominate procurement volume. Mining companies represent the steepest expansion trajectory as battery supply chain diversification accelerates.
Distribution Channel:
Supply concentration patterns favor direct relationships for industrial volumes while specialty and artisanal segments fragment across intermediated channels.
- Online Retail:E-commerce platforms serving gemstone collectors, mineral enthusiasts, and small-scale ceramic suppliers, with photographic grading and return policies addressing quality verification challenges for non-industrial buyers.
- Direct Sales:Long-term supply agreements between mining operations and integrated refiners, with embedded price adjustment mechanisms and volume commitments spanning three to five years. Korean and Japanese battery material importers favor this channel for critical feedstock security.
- Distributors:Regional intermediaries stocking processed powders and crystals for glass and ceramic manufacturers requiring just-in-time delivery and technical support, with German and Italian industrial mineral distributors maintaining specialized lithium mineral inventories.
- Specialty Stores:Physical retail outlets for gemstone and mineral specimens, with Tucson's annual gem and mineral show and Munich's mineralientage serving as critical price discovery and relationship-building venues.
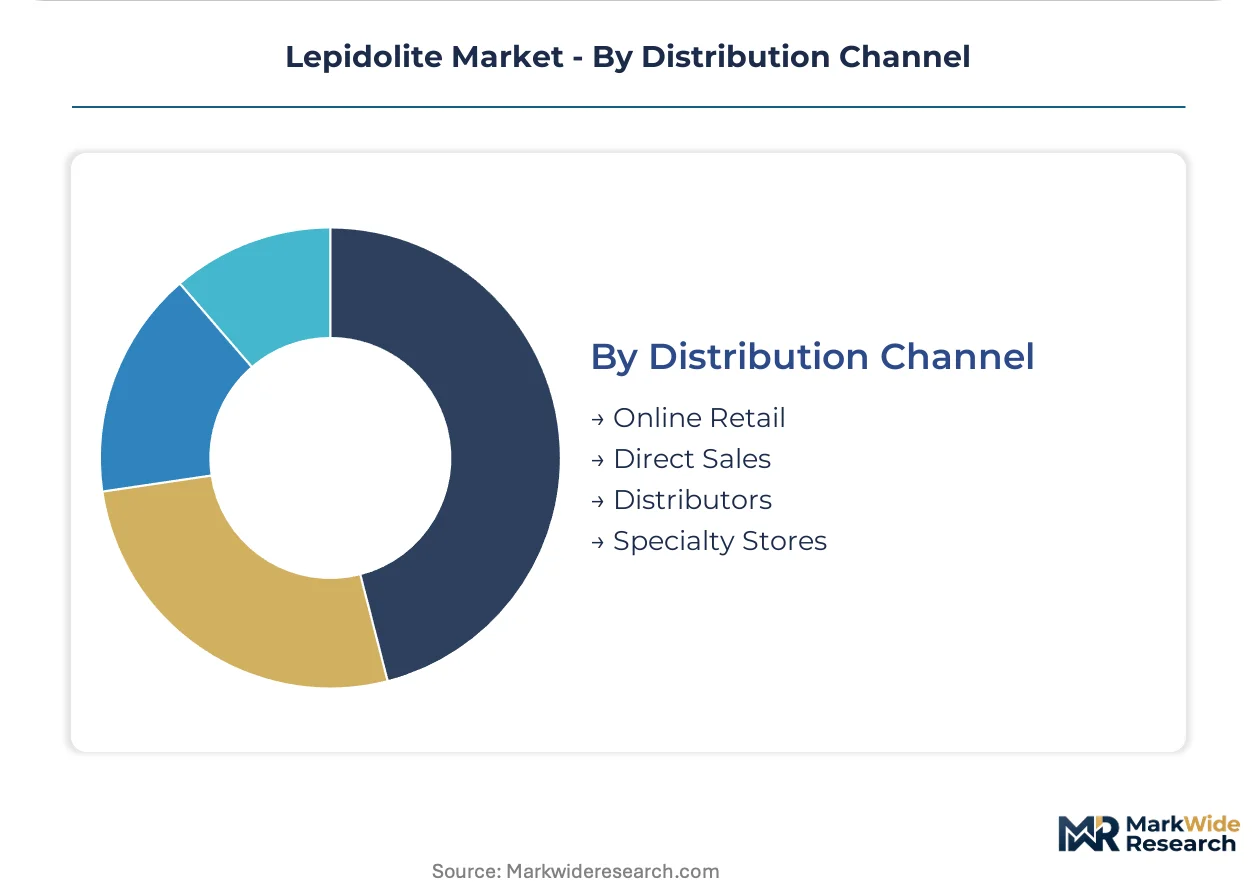
Direct sales dominate industrial value flows. Online retail is gaining share fastest in collector and artisanal segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates lepidolite processing capacity while import-dependent markets scramble for compliant supply alternatives. Export flows from Jiangxi Province feed battery material demand across Northeast Asia, yet regulatory fragmentation in the EU and US is forcing geographic diversification of hard-rock feedstock sourcing.
China
Jiangxi Province anchors global lepidolite refining through integrated calcination-acid roasting corridors serving Korean and Japanese battery manufacturers. MIIT battery material purity standards create tiered qualification tracks that reward advanced refining investments. Ganfeng Lithium's captive mining rights in Yichun exemplify upstream control strategies within this concentrated processing geography.
South Korea
Seoul-based cathode manufacturers source battery-grade lithium carbonate through five-year offtake agreements with Jiangxi refiners, prioritizing supply security over spot market flexibility. The country's national industrial regulator enforces traceability mandates aligned with EU Critical Raw Materials Act benchmarks. Busan-Ulsan port infrastructure handles bulk chemical imports bound for metropolitan manufacturing clusters.
Japan
Tokyo metropolitan area battery material importers favor direct sales channels with embedded price adjustment mechanisms for critical feedstock security. METI industrial standards emphasize carbon intensity disclosure requirements that complicate Chinese supply chain qualification. Osaka-Kansai ceramic manufacturers maintain steady demand for lepidolite powder in specialty glaze formulations.
Germany
Schott's traditional optical glass manufacturing regions in Bavaria and Baden-Württemberg source certified lepidolite batches under REACH-compliant traceability requirements. The KBA automotive regulator coordinates with ECHA on battery material origin disclosure rules affecting cathode supply chain qualification. Industrial mineral distributors in North Rhine-Westphalia maintain specialized lithium mineral inventories for just-in-time delivery.
Brazil
Minas Gerais pegmatite districts offer FTA-compliant feedstock potential for US-qualified battery supply chains under Inflation Reduction Act sourcing rules. The country's national mining regulator oversees exploration permits for hard-rock lithium development. Emerging concentrator projects in southeastern states target direct shipping ore arrangements with North American refiners.
Lepidolite Market Vendor Landscape
Concentration sits with integrated lithium majors possessing captive mining rights and vertical blending capabilities across multiple feedstock types. Tier-one cathode qualification requirements favor refiners with demonstrated battery-grade purity consistency, while asset-light toll processors exploit concentrator-to-refiner arrangements without full integration burdens. Strategic moves center on dual-source supply flexibility and five-year offtake contracting with Korean and Japanese buyers.
Among Chilean brine specialists, SQM exemplifies the purity-benchmarking archetype against hard-rock alternatives. Ganfeng Lithium anchors the integrated Chinese processor tier through Jiangxi-based captive supply. Albemarle Corporation occupies a position spanning both brine expertise and hard-rock qualification capabilities. These three represent divergent competitive vectors: brine-scale efficiency, integrated Chinese processing concentration, and dual-technology portfolio breadth.
| Leading Market Players |
|---|
| SQM |
| Mineral Resources Limited |
| Ganfeng Lithium |
| CATL |
| Lithium Americas Corp. |
| Tianqi Lithium |
| Rio Tinto |
| Zijin Mining Group |
| Albemarle Corporation |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day concentrate inventory cycles in Jiangxi Province processing corridors concentrate pricing power with integrated refiners holding captive mining rights, while spot market exposure for toll processors amplifies margin volatility during acid reagent cost spikes. Battery-grade lithium carbonate qualification premiums widen against technical-grade material as Korean and Japanese cathode manufacturers embed five-year offtake price adjustment mechanisms.
Pricing Analysis
Configured-to-order pricing for battery-grade lithium carbonate commands substantial premiums over standard technical-grade lepidolite powder shipments into European glass fluxing markets. Contract-based long-term offtake agreements dominate procurement between Jiangxi refiners and Seoul-Tokyo battery material importers, with price differentiation driven by MIIT purity tier certification and embedded carbon intensity disclosure. Cost compression in low-grade concentrate processing is intensifying because fluorine removal stages consume disproportionate acid reagent volumes. Artisanal gemstone collectors exhibit least price sensitivity, while ceramic glaze manufacturers in Italy and Spain represent the most price-elastic industrial segment.
Supply Chain Analysis
Inventory cycles stretching sixty-to-ninety days for raw concentrate feedstock reflect geographic supply concentration across China, Brazil, and Zimbabwe, with Jiangxi Province alone anchoring over two-thirds of global refining capacity. Acid reagents, rotary kiln refractories, and sulfuric acid recovery systems constitute critical input dependencies. Single-source vulnerability pervades the Jiangxi processing corridor, where environmental compliance disruptions propagate rapidly through integrated calcination-acid roasting facilities. Distribution runs through direct sales channels for industrial volumes, with German and Italian mineral distributors maintaining regional inventories for just-in-time ceramic and glass manufacturer delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent lepidolite processors face substitution defense imperatives against spodumene and direct-extraction brine technologies capturing cathode manufacturer qualification share. Brine-derived lithium carbonate threatens hard-rock feedstock positioning through superior purity consistency and lower carbon intensity profiles.
For Market Incumbents: Consolidate upstream control through captive mining rights acquisition in Minas Gerais FTA-compliant districts, insulating against US Inflation Reduction Act sourcing exclusions. Reinforce acid roasting recovery rates above eighty-five percent through continuous kiln technology deployment, defending margin position against batch-processing competitors facing fluorine impurity cost penalties. Dual-source spodumene-lepidolite blending capabilities anchor supply flexibility that Korean offtake partners prioritize.
For New Entrants and Emerging Players: Anchor in Brazilian hard-rock development where FTA status unlocks US-qualified battery supply chain participation absent from Chinese incumbent routes. Toll processing arrangements with existing concentrator infrastructure bypass capital-intensive vertical integration requirements. Target direct shipping ore qualification with North American refiners seeking origin-diversified feedstock alternatives to Jiangxi supply concentration.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory arbitrage play because FTA-compliant deposit control determines access to US and EU battery material procurement pools. Acquisition candidates holding Brazilian or African pegmatite exploration permits with demonstrated lithium oxide grades above three percent warrant priority evaluation. Watch for EU Critical Raw Materials Act recycled content benchmark implementation as inflection indicator for hard-rock feedstock demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Mining | Ganfeng Lithium's Jiangxi mining rights demonstrate upstream cost control essential for margin defense. |
| Continuous Kiln Technology Deployment | Advanced rotary kiln configurations achieving eighty-five percent recovery rates marginalize batch-processing competitors. |
| FTA-Compliant Feedstock Development | Brazilian Minas Gerais deposits unlock US Inflation Reduction Act qualified supply chain access. |
| Long-term Offtake Agreement Structuring | Five-year contracts with Seoul and Tokyo battery manufacturers displace spot market price exposure. |
| Carbon Intensity Certification Investment | Verified low-carbon processing routes qualify for EU CBAM preferential treatment and Korean METI disclosure requirements. |
Methodological Framework
Initial hypotheses were tested against primary input from lithium refinery operations managers, cathode manufacturer procurement directors, acid roasting process engineers, and Brazilian mining regulator officials, then refined through secondary validation. Customs trade data from Chinese export filings, Jiangxi provincial environmental compliance records, SEC 10-K disclosures from listed lithium majors, and EU Critical Raw Materials Act implementation guidance provided quantitative anchoring. Bottom-up concentrate throughput estimates and top-down battery material demand projections underwent iterative reconciliation.
Variance decomposition across product grade tiers, end-use applications spanning electronics through ceramics, geographic production clusters, and purity certification levels structured the analytical framework. CAGRs were derived through segmented growth rate aggregation and cross-validation against cathode manufacturing capacity expansion announcements. Acid roasting recovery rate trajectories and FTA eligibility list revisions constituted industry-specific forecast sensitivity inputs throughout the projection horizon.
Decision-makers should treat outputs as directional under assumptions of sustained battery-grade lithium carbonate demand growth and stable Jiangxi processing corridor operations; material deviation in spodumene price competitiveness or Brazilian project development timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Composite Copper Foil Production Equipment Market
Others
Wearable Translator Market
Others
Gas Radiators Market
Others
North America Medical Simulation Market
Others
Global Aircraft Lighting Systems Market
Others
Global Multi-Access Edge Computing Market
Others
Thermal Insulation Solution for LNG and LPG Market
Others
Security Bottles Market
Others
Asia-Pacific Military 4D Printing Market
Others
ASEAN Agricultural Logistics Market
Others
North America Automotive LED Lighting Market
Others
North America Forklift Truck Market
Others
Workstation Desktops Market
Others
Folding Smartphone Market
Others
South America Orange Market
Others
Smart Badge Market