
 Connected Living Room Market | 2026-2036
Connected Living Room Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Living Room Market Analysis
Embedded systems engineering talent is bifurcating the competitive landscape, with firms struggling to secure firmware developers who bridge hardware-software boundaries. Samsung Electronics leverages its semiconductor foundry relationships to sustain captive chip supply for its smart TV and hub portfolios. Apple dominates premium smart speaker and display segments through tight ecosystem control and proprietary silicon design.
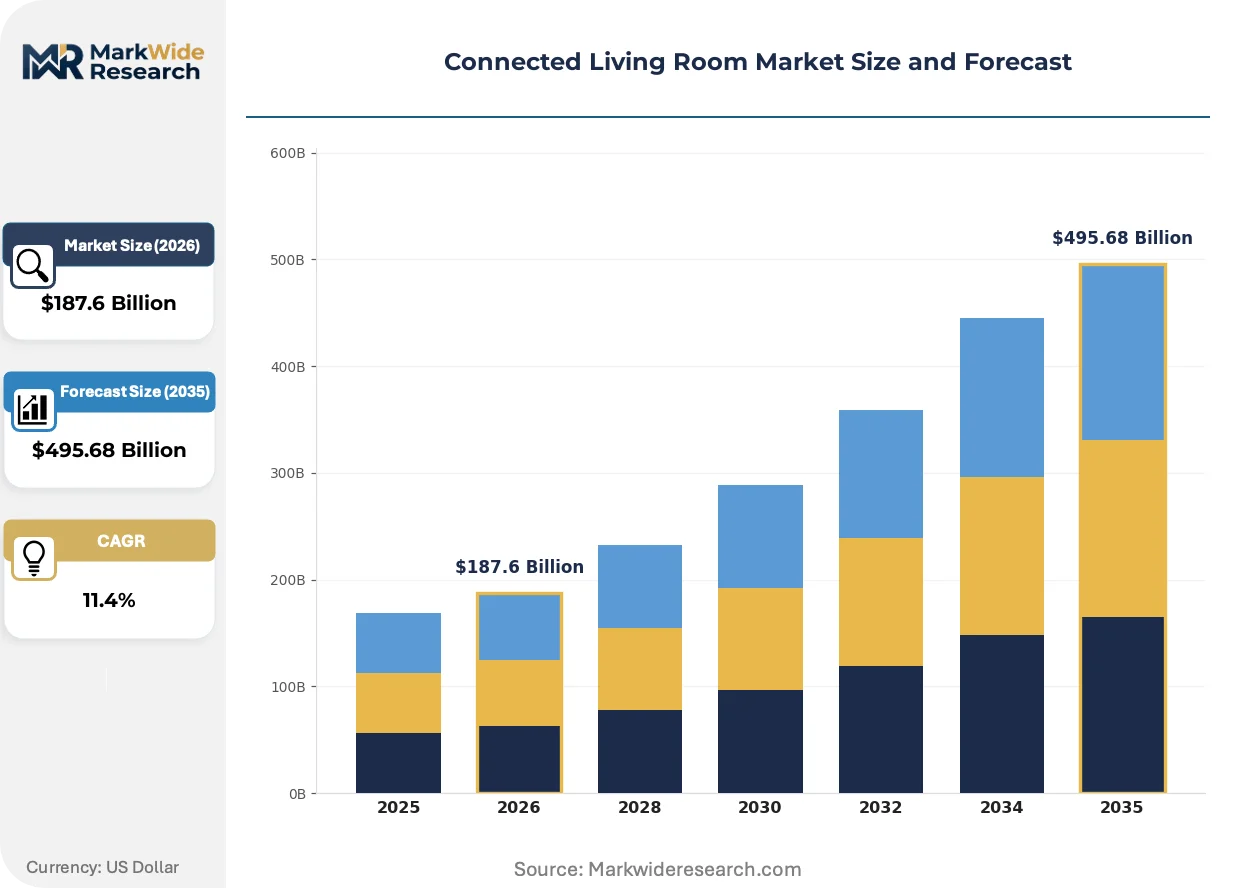
A connected living room integrates internet-enabled audiovisual, environmental control, and automation devices operating through unified communication protocols such as Matter over Thread or Wi-Fi 6E with sub-6 GHz and 6 GHz band support. Its primary purpose is to centralize entertainment, climate, lighting, and security management through voice or ambient computing interfaces. Streaming devices currently anchor the largest revenue pool given cord-cutting momentum and ad-supported tier expansion, while home automation hubs represent the fastest-growing category as multi-protocol interoperability reduces consumer friction. Smart displays capture disproportionate margin concentration through recurring subscription attach and visual commerce integration.
The FCC mandates SAR testing and equipment authorization under Title 47 for all radio-emitting living room devices entering the US market, while the EU Cyber Resilience Act imposes mandatory vulnerability disclosure and update lifecycles for IoT products sold in member states. ETSI EN 303 645 cybersecurity standards further constrain product design choices for European market access. Stakeholders must monitor regulatory divergence between California's SB-327 IoT security law and emerging federal baseline requirements to determine certification sequencing and geographic rollout priority.
Market Dynamics
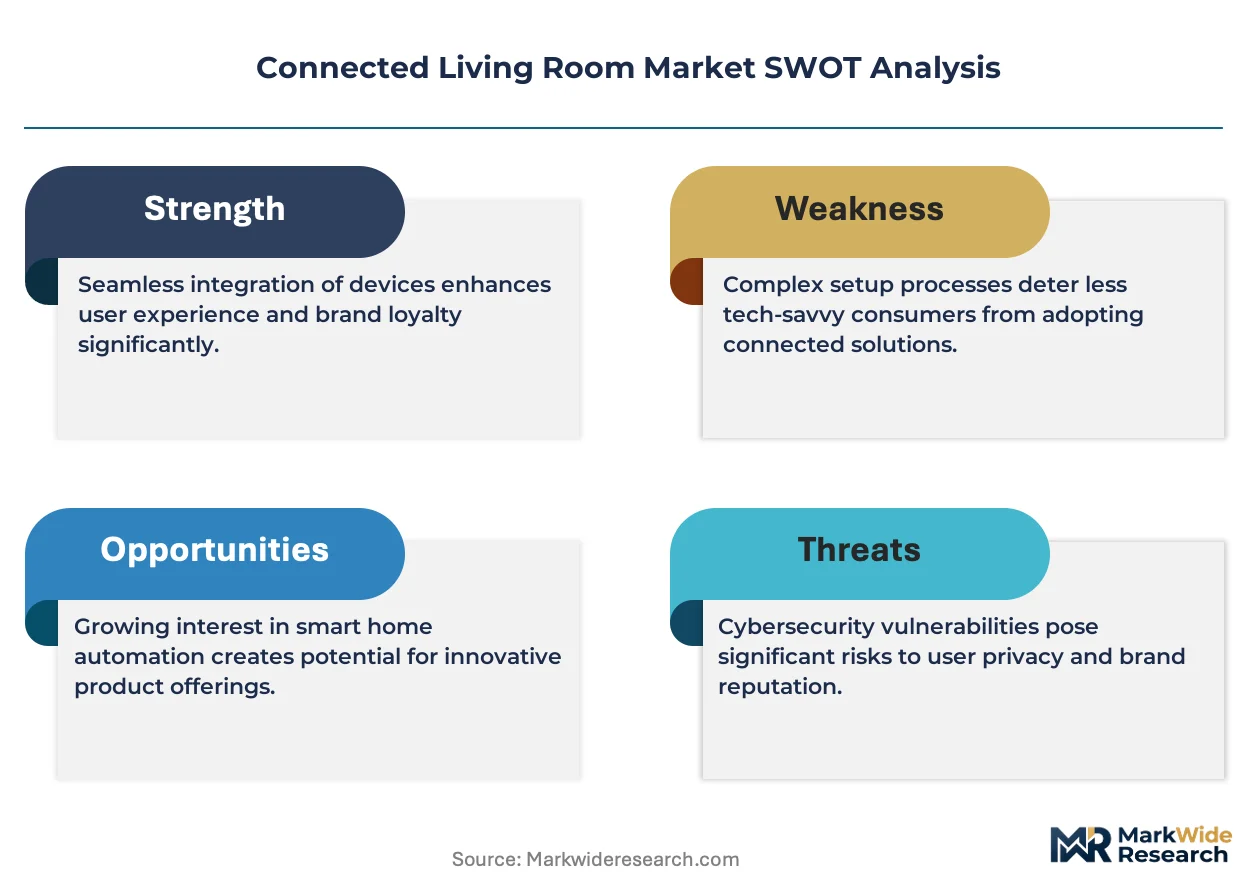
Protocol unification around Matter and Thread is compressing vendor lock-in advantages while forcing incumbent ecosystem operators to open interoperability layers previously guarded as competitive moats.
Growth Catalysts
- EU Cyber Resilience Act:Mandatory security update lifecycles and vulnerability disclosure requirements are accelerating firmware investment cycles, creating upgrade revenue streams for hub and display manufacturers serving European households.
- Wi-Fi 6E spectrum allocation:The 6 GHz band expansion in the United States, Germany, and South Korea enables low-latency 4K/8K streaming and multi-device concurrency without mesh degradation.
- Cord-cutting acceleration:Streaming device penetration among broadband households is pulling companion smart speaker and display purchases as consumers rebuild entertainment stacks around IP-based delivery.
Market Restraints
- Semiconductor supply concentration:Advanced SoC fabrication for smart displays and speakers remains concentrated among Taiwan-based foundries, exposing living room OEMs to geopolitical disruption and allocation priority shifts.
- FCC equipment authorization timelines:SAR testing and modular approval procedures for Wi-Fi 6E and Thread radio modules extend product launch windows by 4-6 months, compressing competitive response windows.
- Legacy infrared ecosystem persistence:Existing AV receiver and set-top box installed bases resist IP-native control, forcing hybrid hardware architectures that inflate BOM costs.
Strategic Opportunities
- India smart home penetration:Sub-15% connected device adoption among urban households creates first-mover positioning for Matter-certified hub and lighting bundles as broadband infrastructure expands.
- Health and wellness integration:Ambient sensing for air quality, sleep monitoring, and fall detection is converging with entertainment hubs, opening subscription revenue attach in aging-population households.
- Utility demand-response programs:California and Texas grid operators are incentivizing thermostat and EV charger integration through living room control interfaces, creating utility-funded customer acquisition channels.
Industry Challenges
- Firmware engineering scarcity:Embedded systems talent capable of bridging real-time OS constraints with cloud-native update pipelines commands premium compensation, constraining mid-tier vendor R&D scaling.
- Multi-protocol certification complexity:Simultaneous Matter, Thread, Zigbee, and proprietary stack validation extends QA cycles and requires specialized test lab partnerships.
- Interoperability regression testing:Each Matter revision mandates backward compatibility verification across third-party device ecosystems, inflating sustained engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Living Room Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Speakers, Smart Displays, Streaming Devices, Home Automation Hubs Technology: Wi-Fi, Bluetooth, Zigbee, Z-Wave End User: Homeowners, Renters, Hospitality Providers, Commercial Spaces Distribution Channel: Online Retail, Brick-and-Mortar Stores, Direct Sales, Specialty Shops |
| Companies Covered | Samsung Electronics Co., Ltd., Apple Inc., Sony Corporation, Google LLC, LG Electronics, Amazon.com, Inc., Panasonic Corporation, Roku, Inc., Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Living Room Market Emerging Trajectories
Computational offloading from edge devices to cloud inference services is redistributing hardware requirements while enabling software-defined feature upgrades that extend hardware replacement cycles.
Edge AI accelerators in smart displays and speakers is bifurcating the processing architecture landscape. Premium devices now embed NPU silicon for local voice recognition and computer vision, while cost-optimized SKUs rely entirely on cloud inference. This split is forcing OEMs to maintain dual software stacks and fragmenting developer targeting for ambient computing applications.
ETSI EN 303 645 cybersecurity standards implementation deadlines across EU member states are mandating password prohibition, vulnerability disclosure procedures, and encryption baselines for all radio-emitting living room devices. Manufacturers serving European markets must re-engineer legacy product lines or face market exclusion, with smart cameras and voice assistants facing the steepest compliance redesign requirements.
Subscription unbundling from hardware purchases is reshaping channel economics in North America and Western Europe. Retailers increasingly demand recurring revenue participation through smart display app store commissions and streaming service affiliate arrangements, compressing upfront hardware margins while extending customer lifetime value capture for ecosystem operators who control content and service layers.
Connected Living Room Market Segmentation
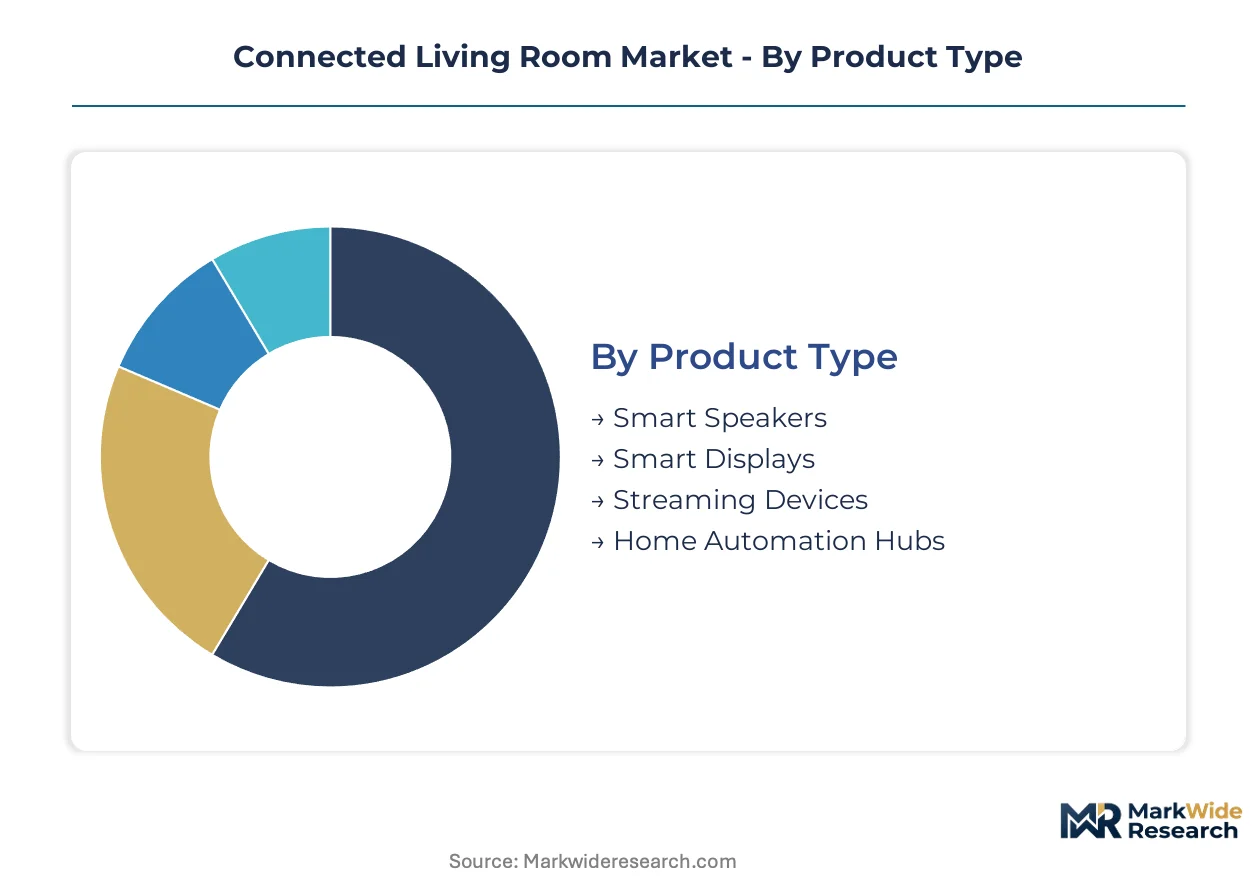
Segmentation in the connected living room market reveals how protocol choices and channel economics shape vendor strategies. Product type and technology selections determine certification burdens and margin structures, while end-user and distribution splits expose where interoperability investments convert to revenue.
Product Type:
Channel economics vary sharply across product categories, with streaming devices dominating mass retail velocity while smart displays concentrate in direct-to-consumer and premium electronics channels.
- Streaming Devices:HDMI-native hardware delivering IP-based video and audio content to legacy television displays. Demand clusters among broadband households in the United States and Germany where cord-cutting has accelerated most aggressively, constrained by FCC equipment authorization timelines that extend launch windows.
- Smart Displays:Touchscreen-enabled hubs combining visual interfaces with voice control and camera systems for video calling and ambient computing. Hospitality providers in China and commercial co-working operators in South Korea are deploying these for guest service automation, driving above-average margin capture through software subscription attach.
- Smart Speakers:Audio-first voice assistant endpoints with microphone arrays for far-field recognition.
- Home Automation Hubs:Multi-protocol controllers bridging Matter, Thread, Zigbee, and proprietary device ecosystems.
By volume, streaming devices lead. By expansion trajectory, home automation hubs are climbing the fastest as Matter protocol unification reduces consumer friction.
Technology:
Cost tier stratification separates premium whole-home deployments from entry-level point solutions, with silicon integration decisions driving BOM differentials.
- Wi-Fi:Backbone connectivity supporting high-bandwidth video streaming and cloud-dependent voice processing. Homeowners in the United States and Germany prioritize Wi-Fi 6E-enabled devices for 4K/8K streaming concurrency, though 6 GHz module certification adds 4-6 months to product development cycles.
- Bluetooth:Low-energy pairing protocol for initial device setup and audio streaming to peripherals. Renters in urban India and Brazil favor Bluetooth-first configurations for apartment-scale deployments where infrastructure investment is limited, constrained by range limitations that resist whole-home coverage.
- Zigbee:Mesh networking stack for battery-powered sensors and lighting controls.
- Z-Wave:Sub-GHz proprietary protocol with strong presence in security-focused installations.
By installed base, Wi-Fi dominates. By share gain velocity, Thread-enabled Matter devices are expanding most quickly as interoperability becomes a purchase criterion.
End User:
Application context dictates feature prioritization, with residential users emphasizing entertainment integration while commercial deployments prioritize centralized management and SLA guarantees.
- Homeowners:Permanent residents investing in whole-home automation with multi-year upgrade horizons. Demand concentrates in the United States, China, and Germany where broadband penetration and disposable income support premium ecosystem adoption, though legacy infrared AV equipment persists as an integration friction point.
- Hospitality Providers:Hotels and short-term rental operators deploying guest-facing controls for climate, lighting, and entertainment. Operators in Dubai and Singapore are retrofitting properties with Matter-certified hub systems to reduce front-desk service calls and enable mobile check-in workflows.
- Renters:Transient residents requiring portable, non-invasive solutions with minimal installation.
- Commercial Spaces:Corporate campuses and co-working facilities integrating living room technologies for employee amenity zones.
By absolute spending, homeowners lead. By deployment velocity, hospitality providers are gaining share fastest as guest experience differentiation becomes a competitive priority.
Distribution Channel:
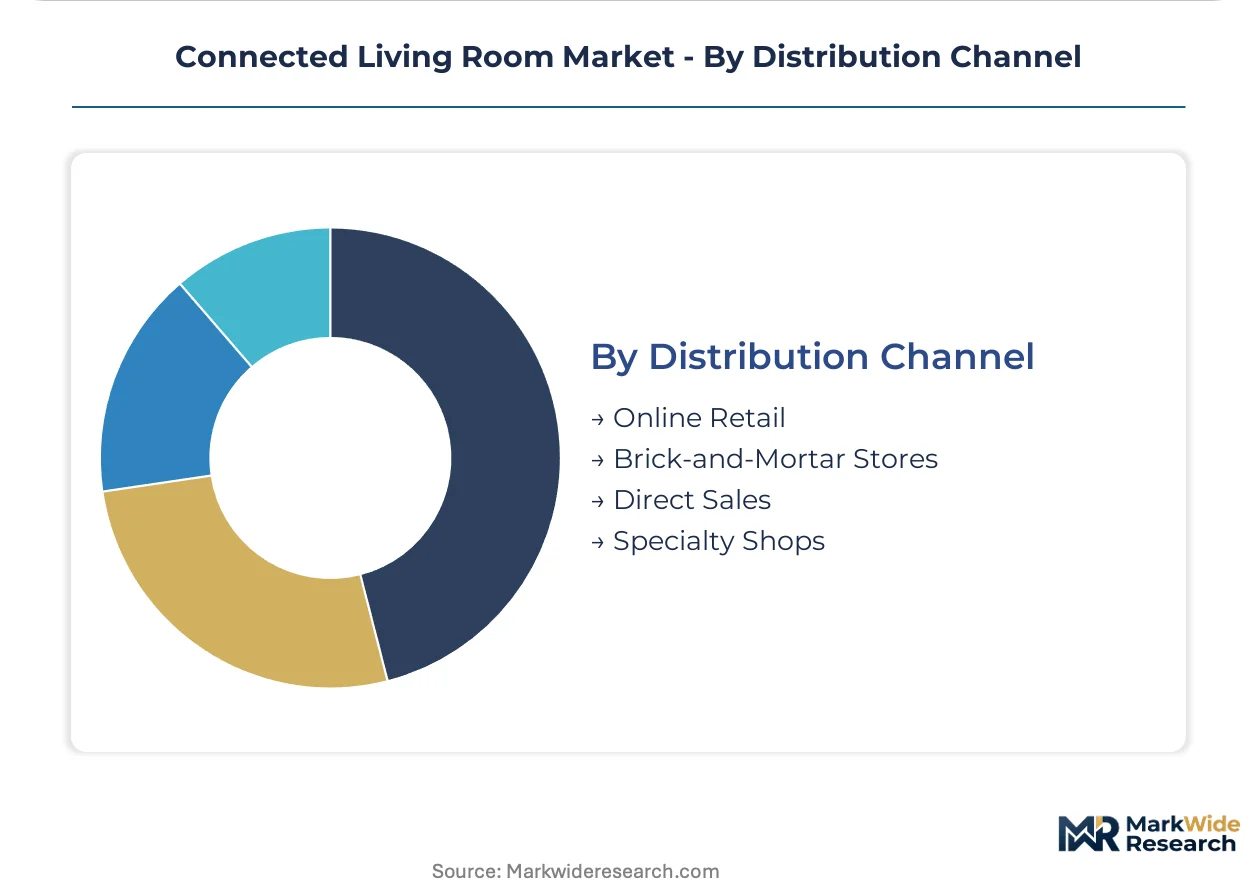
Geographic concentration of purchasing behavior separates markets where e-commerce dominates from those where tactile evaluation remains essential.
- Online Retail:E-commerce platforms capturing subscription-bundled hardware sales with streaming service affiliate economics. The United States and United Kingdom show highest online penetration for smart speaker and display purchases, though return rates for complex multi-device bundles exceed brick-and-mortar averages.
- Brick-and-Mortar Stores:Big-box electronics and home improvement retailers enabling protocol interoperability demonstrations. German and Japanese consumers rely heavily on in-store Matter compatibility testing before hub purchases, extending sales cycles but reducing post-purchase support burdens.
- Direct Sales:Manufacturer-owned channels for premium ecosystem lock-in.
- Specialty Shops:Custom integrator and AV specialist channels for high-complexity installations.
By transaction volume, online retail leads. By margin retention, direct sales are expanding most quickly as ecosystem operators capture service revenue without retail margin sharing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies. German households prioritize Matter-certified interoperability and energy-efficient climate control integration, while US consumers emphasize streaming device density and voice assistant penetration. Chinese buyers concentrate spending on smart displays with localized content ecosystems and visual commerce features.
United States
FCC equipment authorization timelines and Wi-Fi 6E spectrum allocation are accelerating hub and display refresh cycles. California's SB-327 IoT security law mandates unique default passwords and vulnerability disclosure, pressuring firmware engineering investments. Silicon Valley and Austin clusters concentrate embedded systems talent for voice processing and edge AI development.
China
Smart display adoption for visual commerce and elderly care monitoring is outpacing speaker-only deployments. MIIT radio transmission equipment certification and GB standards for cybersecurity impose multi-month approval windows. Shenzhen and Hangzhou manufacturing corridors dominate Matter module production and Thread radio silicon packaging.
Germany
EU Cyber Resilience Act compliance and ETSI EN 303 645 cybersecurity standards are elevating product development costs for hub manufacturers. BSI federal cybersecurity guidance shapes procurement specifications for hospitality and commercial deployments. Munich and Berlin host integrator networks specializing in whole-home Matter retrofits for energy-conscious homeowners.
India
Sub-15% connected device penetration among urban households creates first-mover positioning for Matter-certified bundles as broadband infrastructure expands. TRAI data localization requirements and BIS electronics certification add regulatory sequencing complexity. Bangalore and Hyderabad engineering centers supply firmware development for cost-optimized Wi-Fi and Bluetooth-first product lines.
South Korea
Wi-Fi 6E device density for 4K/8K streaming concurrency is highest globally among broadband households. MFDS and RRA radio equipment certification align with EU cybersecurity disclosure timelines, smoothing export pathways. Seoul metropolitan area clusters concentrate smart display manufacturing and edge AI accelerator integration for premium hospitality deployments.
Connected Living Room Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive silicon supply and ecosystem lock-in defining competitive separation. Consolidation pressure concentrates around semiconductor fabrication access and multi-protocol firmware engineering capacity. Three archetypes dominate: vertically integrated consumer electronics conglomerates with foundry relationships, cloud-native platform operators monetizing service layers, and streaming-specialized hardware vendors dependent on content affiliate economics. Dominant competitive moves include strategic silicon sourcing partnerships and Matter certification acceleration to compress interoperability gaps.
Within the integrated tier, Samsung Electronics Co., Ltd. and Apple Inc. exemplify divergent ecosystem strategies—Samsung leveraging semiconductor captive supply across display and hub portfolios, Apple enforcing proprietary silicon and tight software-hardware integration. Amazon.com, Inc. anchors the service-layer monetization archetype, using speaker and display hardware as conduits for subscription and commerce revenue attach. These three occupy positions that reshape margin capture rules for mid-tier specialists lacking comparable vertical control or cloud infrastructure scale.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Apple Inc. |
| Sony Corporation |
| Google LLC |
| LG Electronics |
| Amazon.com, Inc. |
| Panasonic Corporation |
| Roku, Inc. |
| Microsoft Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation agreements with Taiwan-based foundries lock in both NPU silicon allocation and cost visibility for smart display OEMs serving European and North American markets. These contractual structures insulate tier-one manufacturers from spot-market volatility while binding them to minimum volume commitments that reshape inventory risk distribution across the value chain.
Pricing Analysis
Long-term offtake contracts dominate component procurement for Wi-Fi 6E radio modules and edge AI accelerators, though spot-market exposure persists for legacy Bluetooth and Zigbee silicon. Price differentiation hinges on Matter certification tier and firmware customization depth, with premium SKUs commanding substantial uplifts for multi-protocol interoperability. Cost compression in entry-level streaming devices is intensifying because retail margin participation demands are squeezing hardware economics. Renters in urban India exhibit highest price sensitivity, while hospitality providers in Dubai and Singapore prioritize SLA guarantees over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites the majority of Thread radio module and smart display panel shipments from Shenzhen and Hangzhou manufacturing corridors to European distribution hubs. Taiwan, South Korea, and China concentrate advanced SoC fabrication for voice processing and computer vision workloads, with raw material dependencies spanning 6 GHz RF front-end components, NPU inference silicon, and high-brightness display substrates. Single-source vulnerability in Taiwan-based foundry relationships exposes living room OEMs to geopolitical disruption. Distribution runs through big-box electronics retailers in Germany and Japan, where in-store Matter compatibility testing extends sales cycles but reduces return rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from cloud-native platform operators monetizing service layers without hardware margin exposure, forcing defensive repositioning around captive silicon and ecosystem lock-in.
For Market Incumbents: Secure semiconductor foundry allocation priority through multi-year capacity reservations, insulating smart display and hub portfolios from Taiwan-based supply concentration risks. Deepen backward integration into Thread radio module design to compress certification timelines and defend margin position against streaming-specialized hardware vendors dependent on content affiliate economics.
For New Entrants and Emerging Players: Anchor in India's sub-15% connected device penetration among urban households, where broadband infrastructure expansion creates first-mover positioning for Matter-certified hub and lighting bundles. Target hospitality providers in Dubai and Singapore retrofitting properties for guest service automation, leveraging direct sales channels to capture software subscription attach without retail margin sharing.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated consumer electronics conglomerates with foundry relationships and multi-protocol firmware engineering capacity, as these archetypes reshape margin capture rules for mid-tier specialists lacking comparable vertical control. The signal to watch is EU Cyber Resilience Act compliance acceleration, which will bifurcate vendor viability based on firmware update lifecycle capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Certification Acceleration | Compresses interoperability gaps against proprietary ecosystem lock-in from Apple and Amazon. |
| Edge AI Accelerator Integration | Enables local voice recognition for premium smart displays serving aging-population households. |
| Foundry Capacity Reservation | Insulates NPU silicon supply from Taiwan-based fabrication concentration risks. |
| Utility Demand-Response Partnership | Creates California and Texas grid operator-funded customer acquisition channels for thermostat OEMs. |
| Health and Wellness Feature Attach | Opens subscription revenue from ambient sensing for air quality and fall detection in smart hubs. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FCC equipment authorization databases, MIIT radio transmission certifications, and ETSI cybersecurity standard implementation timelines. Interviews with firmware engineering directors, smart home platform architects, hospitality technology procurement leads, and semiconductor supply chain managers informed demand-side and supply-side validation. Secondary sources include customs records for Thread module trade flows, SEC filings from streaming device vendors, and hyperscaler smart speaker capex disclosures. Bottom-up unit economics triangulate against top-down broadband household penetration models.
Segmentation dimensions modeled include product type, connectivity protocol, end-user application context, and distribution channel structure across the projection horizon. CAGRs derive from installed base growth rates, replacement cycle compression, and subscription attach velocity. Forecast inputs incorporate Wi-Fi 6E spectrum allocation timelines, Matter protocol adoption curves, and EU Cyber Resilience Act compliance deadlines.
Decision-makers should treat outputs as directional under assumptions of sustained broadband infrastructure investment and regulatory harmonization around ETSI EN 303 645 baselines; material deviation in Taiwan foundry allocation priority or FCC equipment authorization timelines would warrant model refresh. Practitioners should keep alternative scenarios live as EU Cyber Resilience Act enforcement intensity and India TRAI data localization requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Animal Feed Alternative Protein Market
Others
Balsa Wood Market
Others
Palatants Market
Others
ASEAN Smart Homes Market
Others
Internet Protocol Television (IPTV) Market
Others
India Data Center Physical Security Market
Others
Coloring Apps Market
Others
Hookah Tobacco Market
Others
Thailand Commercial Vehicles Lubricants Market
Others
Fresh Apples Market
Others
India Home Automation Market
Others
Global Mica Market
Others
Global Smart Kitchen Market
Others
Global Military Wearable Sensors Market
Others
Global Human Augmentation Market
Others
Spain Automotive LED Lighting Market