
 Wearable Solar Devices Market | 2026-2036
Wearable Solar Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Solar Devices Market Analytics
A capital-intensity divergence between thin-film photovoltaic specialists and conventional electronics assemblers is rotating competitive advantage toward upstream materials control. Voltaic Systems leverages captive solar cell sourcing to sustain margin structures that downstream-only competitors cannot match. Casio Computer anchors its position through decades of low-power watch engineering that now extends into solar-integrated timepieces. Lumos competes on optical expertise, navigating the intersection of wearable illumination and photovoltaic charging.
Wearable solar devices integrate photovoltaic energy conversion into garments, accessories, and body-worn electronics, typically employing amorphous silicon or copper indium gallium selenide cells on flexible polymer substrates to harvest ambient light for continuous trickle charging. The primary commercial purpose is eliminating battery anxiety for users in off-grid or mobile environments where conventional charging infrastructure is unavailable. Smartwatches and fitness bands dominate current revenue as established consumer electronics categories absorb solar augmentation, while solar backpacks lead absolute growth by addressing power-hungry device charging for extended outdoor use. Photovoltaic cell technology anchors the value chain, though hybrid systems combining solar with kinetic and thermal harvesting represent the fastest-expanding margin pool as manufacturers pursue uninterrupted power across variable lighting conditions.
FCC certification requirements in the United States govern electromagnetic emissions from solar-integrated communication wearables, while REACH compliance in Europe restricts hazardous substances in flexible photovoltaic laminates that contact skin. Japan's METI enforces JIS standards for portable power device safety, shaping product design for export-oriented manufacturers. ECEEN and BirkSun position around these regulatory moats, specializing in certification-heavy segments where smaller entrants face compliance barriers. Stakeholders must monitor whether emerging energy-harvesting efficiency standards in major economies consolidate testing protocols or fragment market access requirements.
Market Dynamics
Flexible photovoltaic cell technology is displacing rigid substrates across next-generation wearable designs, compressing supply chain tiers and forcing assemblers to secure captive thin-film sourcing or face margin erosion.
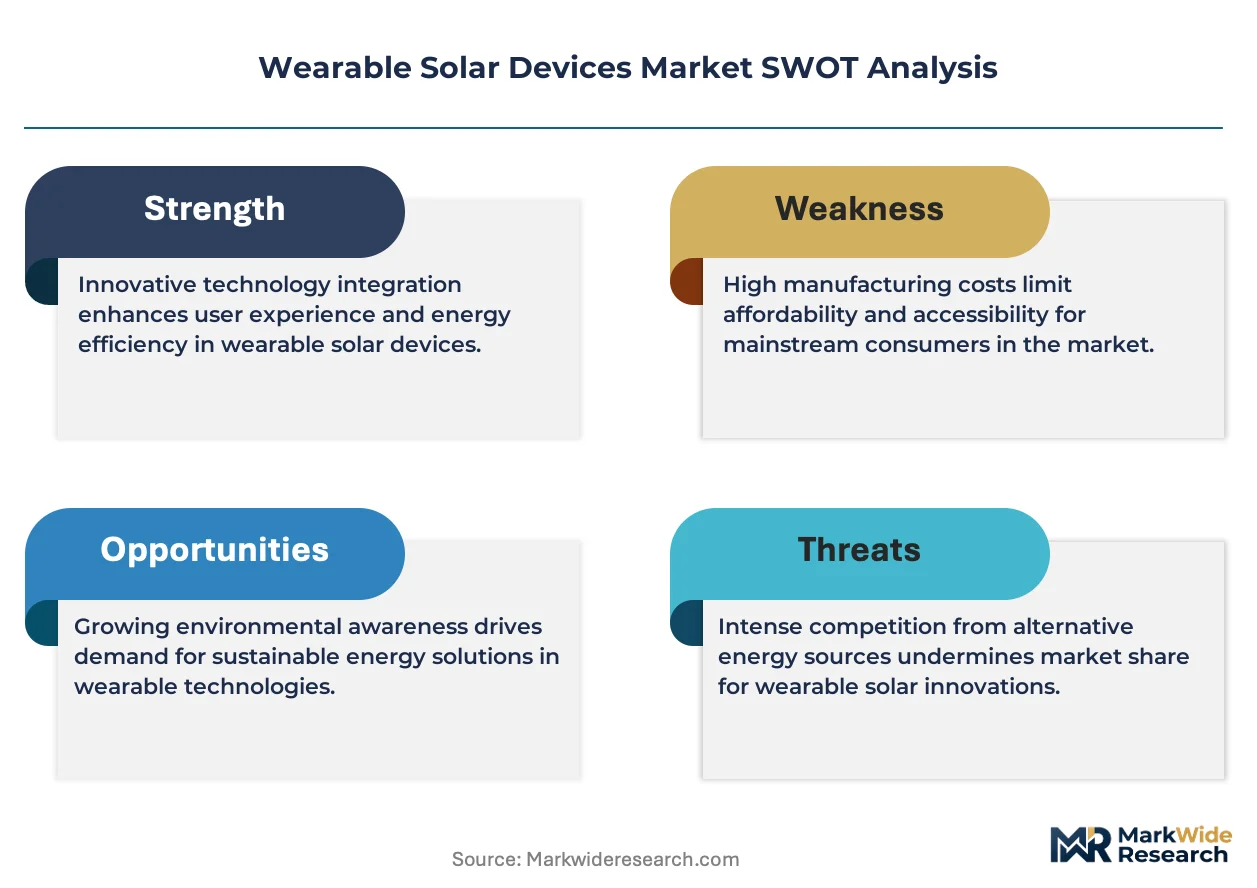
Growth Catalysts
- Outdoor enthusiast demand:Backpackers, trekkers, and remote workers require continuous off-grid power for GPS devices, smartphones, and emergency beacons, creating durable pull for solar-integrated garments and accessories.
- Japan's METI JIS standards:Rigorous portable power safety certification accelerates consumer trust and enables premium positioning for compliant manufacturers exporting to Japanese electronics retailers.
- Copper indium gallium selenide efficiency gains:CIGS cells achieve superior energy conversion in low-light conditions compared to amorphous silicon, expanding viable use cases from direct sunlight to indoor ambient harvesting.
Market Restraints
- Indium supply concentration:CIGS cell production depends on indium refining concentrated in Chinese smelters, exposing manufacturers to geopolitical supply disruptions and price volatility.
- REACH compliance costs:European hazardous substance restrictions on flexible photovoltaic laminates require expensive third-party testing and material reformulation for skin-contact wearables.
- Kinetic harvesting substitution:Piezoelectric and triboelectric nanogenerators compete for wrist-worn and footwear-integrated applications where motion energy exceeds ambient light availability.
Strategic Opportunities
- German portable energy standards advancement:Berlin's federal environment agency is drafting efficiency mandates for personal power devices that would create first-mover advantages for solar-integrated designs meeting draft thresholds.
- Medical wearable convergence:Continuous glucose monitors and cardiac patches require uninterrupted power in variable lighting conditions, opening hybrid solar-thermal harvesting applications in clinical and home health settings.
- Direct-to-outfitter distribution:Bypassing consumer electronics retail to supply REI, Decathlon, and specialized expedition outfitters reduces channel margin capture and builds brand authenticity with core outdoor segments.
Industry Challenges
- FCC certification timelines:Solar-integrated communication wearables face 12-18 month electromagnetic emissions approval processes that delay product launches and compress revenue recognition windows.
- Flexible substrate lamination expertise:The intersection of polymer chemistry and photovoltaic cell handling requires rare interdisciplinary talent that commands premium compensation and experiences high turnover.
- Hybrid system integration complexity:Combining solar with kinetic and thermal harvesting demands proprietary power management firmware that fragments R&D resources and extends development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Solar Devices Market |
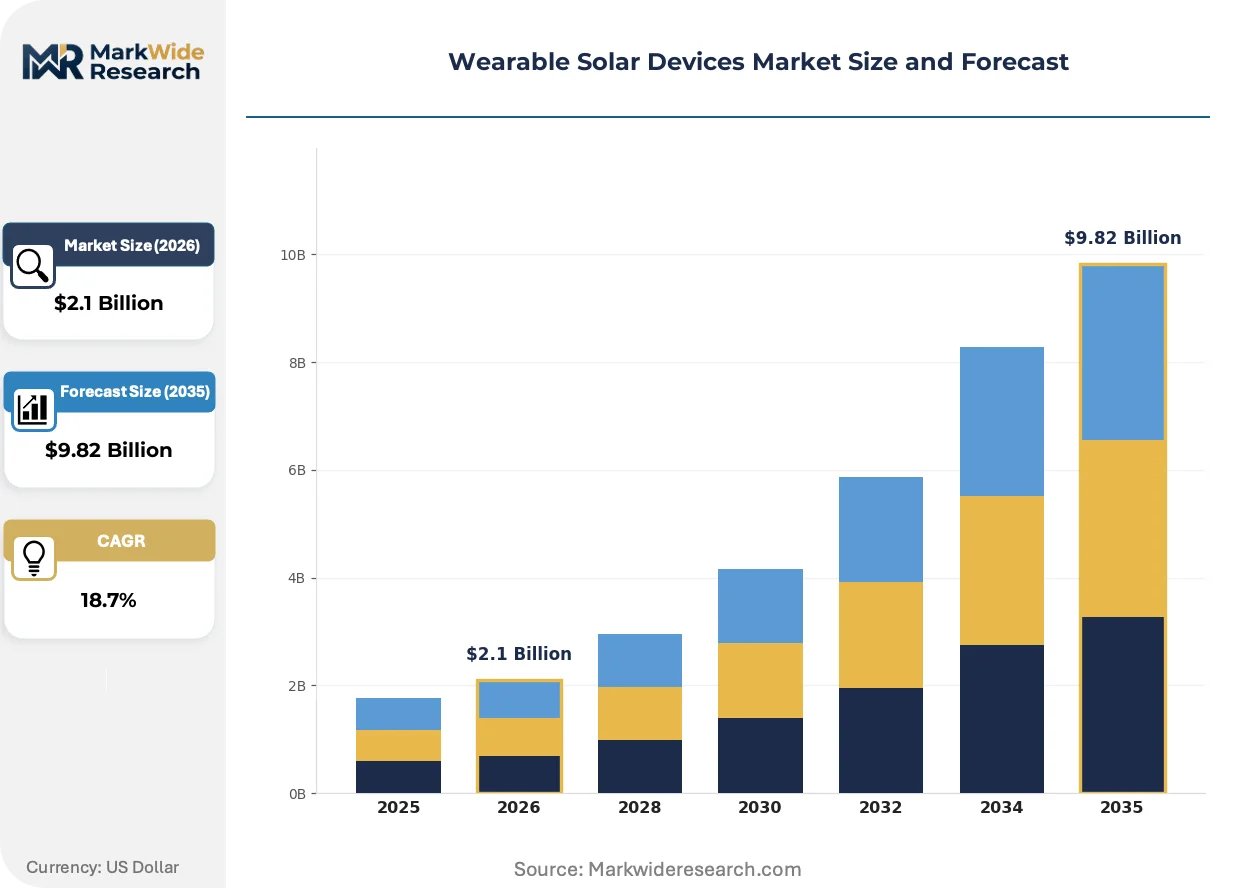
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.82 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Bands, Solar Backpacks, Solar Clothing End User: Athletes, Outdoor Enthusiasts, Commuters, Students Technology: Photovoltaic Cells, Flexible Solar Panels, Hybrid Systems, Energy Harvesting Application: Health Monitoring, Navigation, Communication, Charging Devices |
| Companies Covered | Voltaic Systems, Colorado Instruments (Solar Made), e5solar, BirkSun, SolarGoPack, Tommy Hilfiger Licensing, ECEEN, Lumos, Casio Computer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Solar Devices Market Evolving Landscape
Photovoltaic integration is evolving from novelty feature to core power architecture, with material science breakthroughs and regulatory pressure converging to redefine competitive advantage around energy autonomy rather than battery capacity.
Copper indium gallium selenide thin-film technology is displacing amorphous silicon in premium wearable segments due to superior low-light performance and mechanical flexibility. Outdoor equipment manufacturers are adopting CIGS for solar backpacks and tent-integrated charging panels where weight-to-power ratios determine purchasing decisions. This material shift is displacing incumbent silicon suppliers from high-margin product tiers and concentrating value capture with specialized thin-film deposition equipment vendors.
REACH restrictions on hazardous substances in skin-contact electronics are forcing reformulation of flexible photovoltaic encapsulants across European-bound product lines. Manufacturers must eliminate specific plasticizers and flame retardants previously standard in polymer substrates, adding 8-12 months to product development cycles. Fitness band and smartwatch segments face the steepest compliance burden as these devices maintain prolonged skin contact during exercise.
Expedition outfitters and professional guides are consolidating procurement around certified off-grid power systems that bundle solar wearables with satellite communicators and GPS units. This bundled purchasing replaces discrete component acquisition and shifts vendor selection criteria toward system integration capabilities and field-repair support networks. The United States and German alpine guiding associations are driving this consolidation through endorsed equipment lists that exclude non-integrated power solutions.
Wearable Solar Devices Market Segmentation
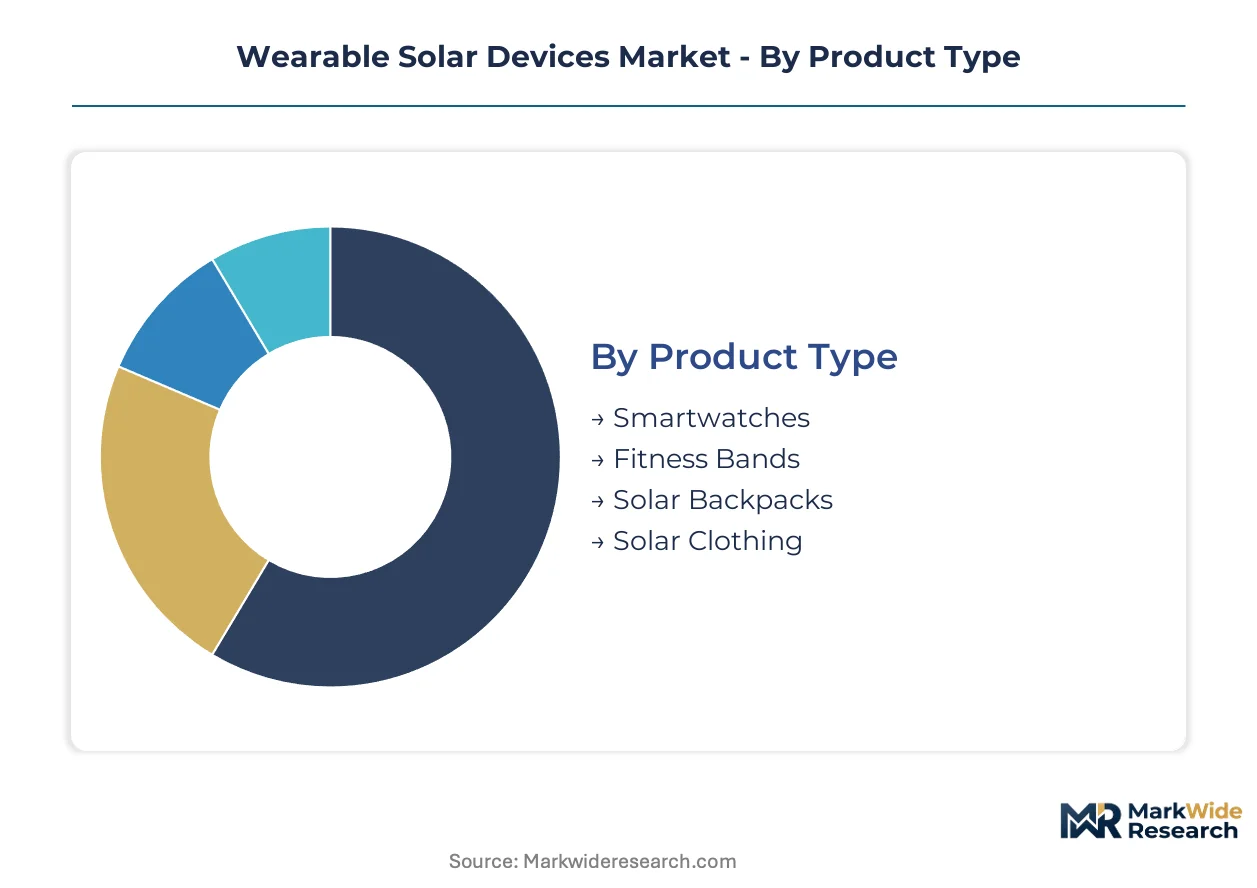
Wearable solar devices fragment across four intersecting dimensions that determine power output, form factor constraints, and regulatory exposure. Product type and technology choices anchor manufacturing investment, while end user and application segments dictate channel strategy and certification requirements.
Product Type:
FCC electromagnetic emissions rules govern smartwatch and fitness band certification timelines, while solar backpacks and clothing face REACH substance restrictions for skin-contact laminates.
- Smartwatches:Amorphous silicon cells integrated into watch faces and bezels deliver trickle charging for low-power displays and sensors. Demand concentrates in Japan where METI JIS standards validate safety claims for electronics retailers.
- Fitness Bands:Flexible CIGS deposition on polymer substrates enables curved form factors with superior low-light harvesting during indoor training sessions. Athletes in Germany's federal environment agency certification zones drive premium positioning for efficiency-compliant designs.
- Solar Backpacks:Rigid and flexible panel arrays on expedition-grade fabrics target off-grid power for GPS and satellite communicators.
- Solar Clothing:Photovoltaic thread integration into jackets and vests serves professional guides requiring hands-free charging during multi-day treks.
Smartwatches handle the majority of throughput; solar backpacks are expanding most quickly on share.
End User:
Cost tier stratification separates professional-grade purchasers from mass-market consumers across certification and durability specifications.
- Athletes:Continuous heart rate and GPS tracking demands drive adoption of hybrid solar-kinetic systems in performance wearables.
- Outdoor Enthusiasts:Backpackers and trekkers require weather-sealed solar backpacks with integrated battery storage for extended off-grid expeditions in United States national parks and German alpine zones.
- Commuters:Urban cyclists and transit riders in Japanese metropolitan areas favor solar-integrated bags and accessories for smartphone charging during variable lighting conditions.
- Students:Campus-bound users prioritize cost-optimized fitness bands with basic solar augmentation for device charging between classes.
Outdoor enthusiasts command the highest average selling prices; students represent the volume entry point for manufacturer ecosystems.
Technology:
Application environment determines cell chemistry selection, with indoor-dominant use cases favoring CIGS efficiency and outdoor exposure accommodating broader technology mixes.
- Photovoltaic Cells:Amorphous silicon and CIGS thin-film deposition on glass or polymer substrates convert ambient light to electrical current. Japanese electronics assemblers concentrate procurement around METI-certified cell suppliers for domestic retail distribution.
- Flexible Solar Panels:Bendable CIGS and organic photovoltaic laminates enable integration into curved surfaces and textile substrates. German portable energy standards advancement creates first-mover certification advantages for compliant manufacturers.
- Hybrid Systems:Solar combined with kinetic and thermal harvesting demands proprietary power management firmware for uninterrupted operation across variable conditions.
- Energy Harvesting:Piezoelectric and triboelectric nanogenerators compete for wrist-worn applications where motion energy exceeds light availability.
Photovoltaic cells anchor current manufacturing scale; hybrid systems are gaining share fastest as manufacturers pursue energy autonomy.
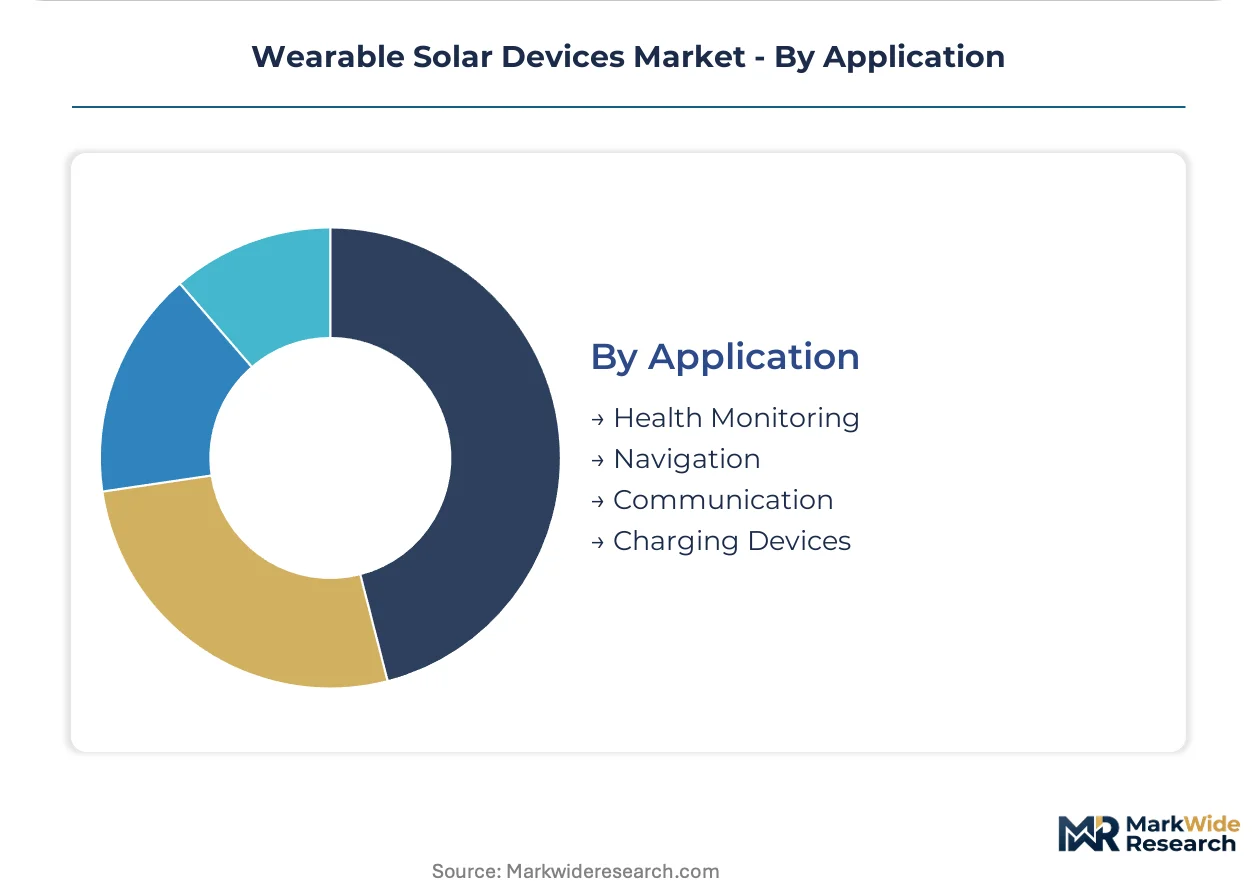
Application:
Volume concentration in consumer electronics retail channels versus specialized outdoor outfitter distribution shapes margin structures and brand positioning.
- Health Monitoring:Continuous glucose monitors and cardiac patches require uninterrupted power in variable lighting, opening clinical applications for solar-thermal hybrid designs.
- Navigation:GPS units and satellite communicators for backcountry use drive solar backpack adoption among United States and German alpine guiding associations with endorsed equipment lists.
- Communication:Solar-integrated wearables with cellular or satellite connectivity face 12-18 month FCC certification timelines that delay revenue recognition.
- Charging Devices:Direct USB and wireless power delivery for smartphones and emergency beacons dominates solar backpack and clothing utility claims.
Charging devices captures the broadest addressable base; health monitoring shows the steepest expansion trajectory as clinical wearables converge with consumer form factors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Japan and Germany where METI JIS standards and federal efficiency mandates validate safety claims, while volume manufacturing gravitates toward Chinese thin-film deposition clusters serving cost-optimized export markets.
United States
Backcountry expedition outfitters in Colorado and Utah drive procurement of solar-integrated backpacks for GPS and satellite communicator charging. FCC electromagnetic emissions certification governs solar wearables with cellular connectivity, creating 12-18 month approval timelines that favor established vendors. The Pacific Northwest hosts flexible photovoltaic R&D clusters where polymer chemistry specialists collaborate with outdoor equipment manufacturers on textile-integrated designs.
Germany
Alpine guiding associations in Bavaria endorse certified off-grid power systems bundling solar wearables with navigation equipment. The federal environment agency drafts portable energy efficiency mandates that reward first-mover solar designs meeting draft thresholds. Baden-Württemberg concentrates CIGS thin-film research facilities supplying deposition equipment to wearable manufacturers across Europe.
Japan
Electronics retailers in Tokyo and Osaka prioritize METI JIS-certified solar timepieces and fitness bands for domestic consumers. METI enforces rigorous portable power safety standards that accelerate consumer trust and enable premium positioning. The Kansai region houses amorphous silicon cell assemblers serving watchmakers integrating photovoltaic faces and bezels.
China
Indium refining concentration in southern smelters supplies CIGS cell production for flexible wearable substrates. GB standards for portable electronics shape export-bound product specifications. The Yangtze River Delta clusters thin-film deposition equipment vendors and polymer substrate laminators serving global wearable brands.
Australia
Remote mining and agricultural workers in Western Australia and Queensland generate demand for rugged solar charging solutions in off-grid environments. The country's national communications regulator governs electromagnetic emissions from wearable communication devices. Sydney hosts expedition equipment distributors bundling solar wearables with satellite connectivity for Outback operations.
Wearable Solar Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with thin-film photovoltaic specialists commanding upstream margins while downstream assemblers compete on certification speed and channel access. The vendor base organizes around three strategic archetypes: captive solar cell producers securing material supply, heritage electronics manufacturers leveraging low-power engineering expertise, and outdoor equipment specialists bundling integrated power systems. Dominant competitive moves include backward integration into thin-film deposition capacity and geographic expansion through direct-to-outfitter distribution bypassing consumer electronics retail.
Among upstream material specialists, Voltaic Systems exemplifies the captive sourcing archetype, while Casio Computer anchors the heritage electronics tier through decades of low-power instrument engineering. Lumos occupies a position at the intersection of optical expertise and photovoltaic integration, representing specialists navigating wearable illumination and energy harvesting convergence. These three companies illustrate the structural segmentation between material control, manufacturing legacy, and application-specific engineering that defines competitive positioning.
| Leading Market Players |
|---|
| Voltaic Systems |
| Colorado Instruments (Solar Made) |
| e5solar |
| BirkSun |
| SolarGoPack |
| Tommy Hilfiger Licensing |
| ECEEN |
| Lumos |
| Casio Computer |
| Others |
Value Network & Pricing Analysis
Flexible CIGS cell substitution for rigid amorphous silicon modules is simultaneously relocating manufacturing gravity toward Chinese thin-film deposition clusters and compressing margin structures for assemblers lacking captive cell sourcing. This displacement dynamic concentrates pricing power with upstream materials controllers while forcing downstream brands to absorb certification and reformulation costs.
Pricing Analysis
The customization-premium spread separates expedition-grade solar backpacks configured for alpine guiding associations from mass-market fitness bands. Three-tier pricing structure across premium, standard, and economy levels tracks certification tier and captive sourcing status. Cost compression in the standard tier is intensifying because REACH compliance mandates 8-12 month reformulation cycles for European-bound skin-contact laminates. Students exhibit highest price sensitivity, while professional outdoor guides prioritize field-repair support networks over unit economics.
Supply Chain Analysis
Strategic stockpiling of indium feedstock distinguishes CIGS cell manufacturers from just-in-time assemblers exposed to Chinese smelter concentration. Indium refining centers on Chinese smelters, polymer substrate lamination clusters in the Yangtze River Delta, and CIGS deposition equipment vendors in Baden-Württemberg. Raw material flows draw from indium concentrates, copper foil substrates, and specialized polymer encapsulants. Single-source vulnerability in indium supply exposes manufacturers to geopolitical disruption. Distribution runs through direct-to-outfitter channels bypassing consumer electronics retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of interdisciplinary talent bridging polymer chemistry and photovoltaic cell handling is constraining product development velocity and inflating compensation costs for qualified engineers. This capability gap favors incumbents with established training pipelines and captive R&D infrastructure.
For Market Incumbents: Secure backward integration into thin-film deposition capacity to defend margin structures against indium price volatility and Chinese supply concentration. Lock in long-term indium offtake agreements before federal efficiency mandates in Germany tighten procurement competition. Prioritize certification speed investments to compress FCC electromagnetic emissions timelines that currently delay revenue recognition.
For New Entrants and Emerging Players: Lead with hybrid solar-thermal harvesting systems for continuous glucose monitors and cardiac patches where uninterrupted power requirements outstrip incumbent capabilities. Target medical wearable convergence as the most penetrable application segment, exploiting regulatory fragmentation between consumer electronics and clinical device pathways. Deploy direct-to-outfitter distribution through REI and Decathlon to build authenticity with core outdoor segments before scaling consumer retail.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed outdoor equipment specialists bundling integrated power systems for expedition outfitters. Long-term viability hinges on whether hybrid energy harvesting achieves clinical validation for FDA-cleared wearables. Monitor German federal environment agency efficiency mandate drafts as inflection indicator for first-mover certification advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Thin-Film Deposition Capacity | Backward integration into CIGS cell production insulates margin structures from indium price volatility and Chinese supply concentration. |
| REACH-Compliant Encapsulant Reformulation | Eight-to-twelve month development cycles for skin-contact laminates create regulatory moats against smaller entrants lacking testing resources. |
| Direct-to-Outfitter Distribution | Bypassing consumer electronics retail reduces channel margin capture and builds brand authenticity with alpine guiding associations. |
| Hybrid Energy Harvesting R&D | Proprietary power management firmware for solar-thermal-kinetic integration addresses clinical wearable requirements for uninterrupted operation. |
| METI JIS Certification Investment | Rigorous Japanese portable power safety standards validate premium positioning and accelerate consumer trust in domestic electronics retail. |
Research Methodology
Operator-level perspectives from thin-film deposition equipment vendors, polymer substrate laminators, alpine guiding association procurement officers, and METI certification consultants anchored the qualitative base. Primary interview data combined with secondary validation from FCC electromagnetic emissions filings, REACH substance restriction databases, Japanese industrial standards documentation, and customs trade records for indium concentrate flows. Bottom-up unit economics triangulated against top-down market sizing across photovoltaic cell, flexible panel, and hybrid system technology tiers.
Sensitivity analysis tested forecast robustness against indium price volatility scenarios and REACH compliance timeline variations throughout the forecast period. Segmentation dimensions modeled include product type, cell chemistry, end-user archetype, application environment, and regional regulatory cluster. CAGRs derived from weighted average of historical capacity expansion rates and projected technology substitution curves. Industry-specific inputs incorporated CIGS efficiency improvement trajectories and kinetic harvesting substitution elasticities.
Underlying assumptions cover stable indium supply from Chinese smelters and gradual harmonization of portable energy efficiency standards, with deviation risk concentrated in geopolitical trade restrictions and accelerated kinetic harvesting performance breakthroughs. Revision becomes warranted when indium price volatility exceeds historical bands or when German efficiency mandates advance faster than draft timelines indicate.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Construction Wearables Market
Others
5G Enabled Healthcare Services Market
Others
Roasted Wheat Market
Others
North America Automotive LED Lighting Market
Others
Asia-Pacific Intercom Devices Market
Others
Thiamethoxam Market
Others
China Smart Home Market
Others
Global Mobile Video Optimization Market
Others
Global Optical Coordinate Measuring Machine Market
Others
Bamboo Straws Market
Others
France Automotive LED Lighting Market
Others
North America Industrial Wearable Devices Market
Others
Asia-Pacific B2B Legal Services Market
Others
Asia-Pacific Road Safety Market
Others
North America Forklift Truck Market
Others
Global Aircraft Lighting Systems Market