
 Over the Top Devices and Services Market | 2026-2036
Over the Top Devices and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Over the Top Devices and Services Market Intelligence
Silicon-based system-on-chip architectures in entry-level streaming sticks is rebalancing cost structures across the OTT hardware stack. Netflix leverages exclusive content production to sustain subscriber retention in saturated North American markets. Amazon anchors its Prime Video ecosystem through backward integration into cloud infrastructure and logistics. Roku competes aggressively on advertising-supported tier economics, differentiating its platform through data-driven audience segmentation tools.
Over the Top Devices and Services encompasses internet-delivered audio, video, and interactive content accessed without traditional broadcast, cable, or satellite distribution infrastructure, relying on IP-based transmission protocols with adaptive bitrate streaming typically operating between 2-25 Mbps depending on resolution tier. The primary commercial purpose centers on disintermediating legacy distribution gatekeepers while enabling direct-to-consumer monetization through subscription, advertising, or transactional models. Smart TVs and streaming sticks together capture the dominant hardware volume, though gaming consoles represent the fastest-growing access point for cloud gaming services. Subscription services generate the deepest margin pools through recurring revenue predictability, while advertising-supported tiers expand addressable reach into price-sensitive user segments.
FCC net neutrality frameworks in the United States, GDPR data governance requirements across Europe, and India's TRAI OTT consultation mechanisms collectively shape platform liability, content moderation obligations, and cross-border data flow restrictions. These regulatory layers directly influence product design decisions around encryption standards, regional content caching, and parental control feature sets. Stakeholders must monitor evolving spectrum allocation policies and local content quota mandates as determinants of market entry sequencing and capital deployment priorities.
Market Dynamics
Fiber-optic infrastructure replacement of copper last-mile delivery across India, Brazil, and Germany is compressing latency thresholds and expanding addressable broadband households for 4K and cloud-gaming workloads.
Growth Catalysts
- TRAI OTT Consultation Mechanisms:India's regulatory framework clarifies platform liability boundaries, reducing compliance uncertainty for international entrants deploying regional content caching infrastructure.
- Silicon-based SoC Architectures:Entry-level streaming stick manufacturers capture cost efficiencies through die-shrink roadmaps, lowering hardware barriers for price-sensitive market penetration.
- Residential Broadband Households:Fiber-to-the-home deployment in São Paulo and Mumbai accelerates smart TV adoption rates, creating concentrated demand pockets for subscription video bundles.
Market Restraints
- Content Licensing Fragmentation:Territory-exclusive distribution agreements force platform operators to maintain redundant content libraries, inflating per-subscriber acquisition costs without commensurate retention gains.
- GDPR Data Governance Requirements:Cross-border data flow restrictions mandate localized encryption standards and regional server deployment, extending capital deployment timelines for European market entry.
- Copper Infrastructure Persistence:Rural and semi-urban zones in target markets remain tethered to legacy DSL delivery, capping streaming quality at sub-HD thresholds and limiting addressable premium-tier demand.
Strategic Opportunities
- Gaming Console Access Points:Cloud gaming service integration into PlayStation and Xbox ecosystems represents the fastest-growing hardware channel for interactive content delivery, bypassing traditional streaming stick saturation.
- Advertising-Supported Tier Economics:Data-driven audience segmentation tools unlock price-sensitive user segments previously excluded from subscription models, expanding total addressable reach.
- FCC Net Neutrality Frameworks:Evolving platform liability standards in the United States create first-mover advantages for operators investing in transparent encryption and parental control feature sets.
Industry Challenges
- Adaptive Bitrate Streaming Engineering:Maintaining seamless 2-25 Mbps quality transitions across heterogeneous network conditions demands specialized codec optimization talent scarce in emerging markets.
- Local Content Quota Mandates:Regulatory compliance timelines for domestic production requirements compress content commissioning cycles, straining creative financing structures.
- Legacy Broadcast Integration:Hybrid households maintaining linear cable subscriptions create fragmented user experience expectations, complicating unified interface design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Over the Top Devices and Services Market |
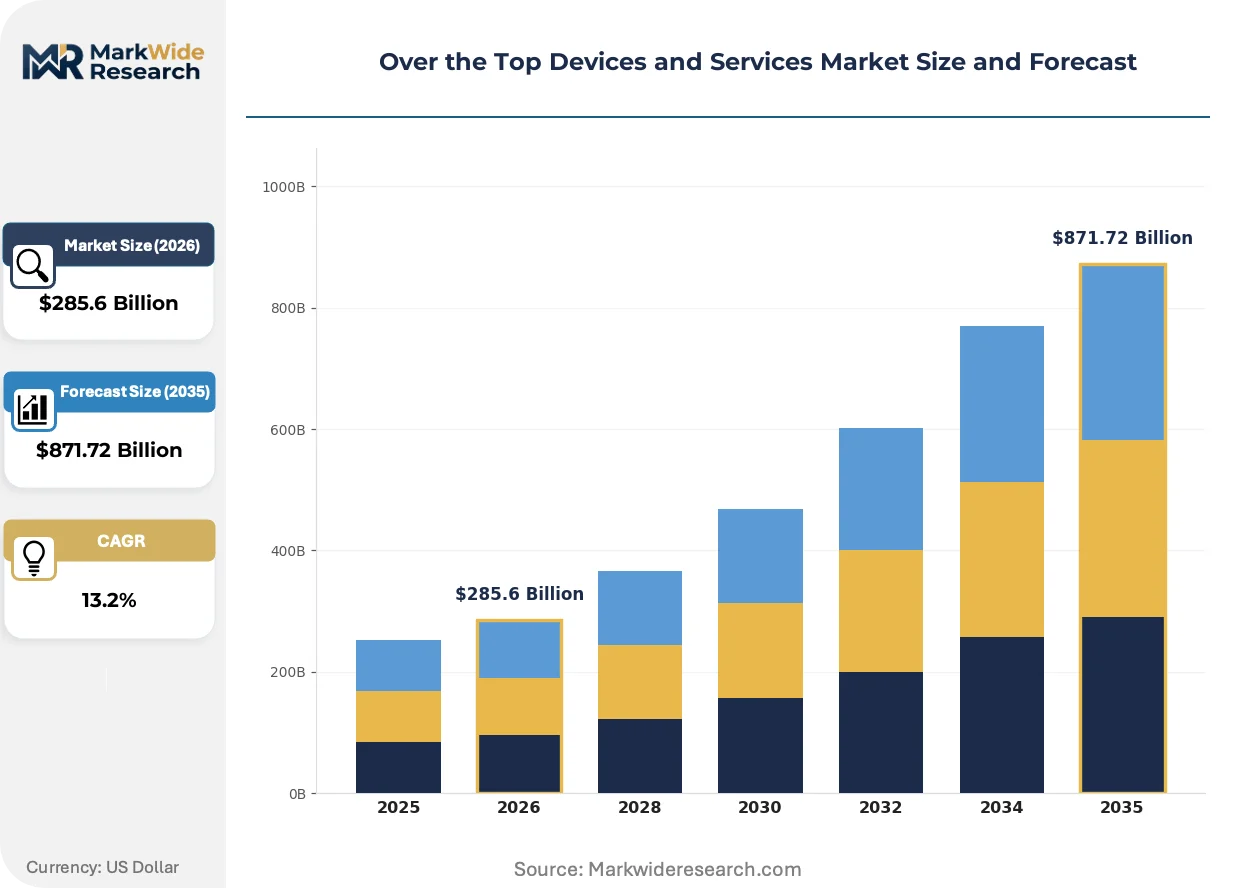
| Market Size in 2026 | $285.6 Billion |
| Market Size in 2035 | $871.72 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Streaming Sticks, Smart TVs, Set-Top Boxes, Gaming Consoles Service Type: Video Streaming, Music Streaming, Cloud Gaming, Subscription Services End User: Households, Educational Institutions, Businesses, Content Providers Content Type: Movies, TV Shows, Live Sports, Documentaries |
| Companies Covered | Netflix, Inc., Amazon.com, Inc., Roku, Inc., Google LLC, Apple, Inc., The Walt Disney Company, Hulu, LLC, Tencent Holdings Ltd., Akamai Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Over the Top Devices and Services Market Strategic Shifts & Innovations
IP-based transmission protocols and edge computing architectures are compressing the distance between content origin and consumption endpoint, reshaping infrastructure deployment priorities across the value chain.
AV1 codec deployment is unifying compression efficiency across smart TV and mobile endpoints, enabling equivalent visual quality at 30% lower bitrates than H.264 baselines. Streaming platform engineering teams in Seoul and San Francisco have accelerated adoption timelines, targeting 2025 for default enablement. This bitrate reduction is unifying addressable market expansion into bandwidth-constrained geographies previously excluded from premium-tier service delivery.
GDPR Article 17 right-to-erasure mandates are forcing platform operators to rearchitect recommendation engines around ephemeral data processing, eliminating persistent viewing history storage. European OTT providers face 72-hour compliance windows for user deletion requests, compressing database infrastructure design cycles. Germany's Federal Data Protection Authority has issued specific guidance on anonymization thresholds, pushing vendors toward differential privacy implementations.
Households are consolidating around bundled subscription management, with third-party aggregators capturing payment and discovery interfaces previously owned by individual platforms. This disintermediation compresses direct customer relationships, forcing original content producers to negotiate placement fees within aggregator storefronts. The phenomenon is most visible in Nordic markets where Telenet and Telia have integrated 15+ streaming services into unified billing portals.
Over the Top Devices and Services Market Segmentation
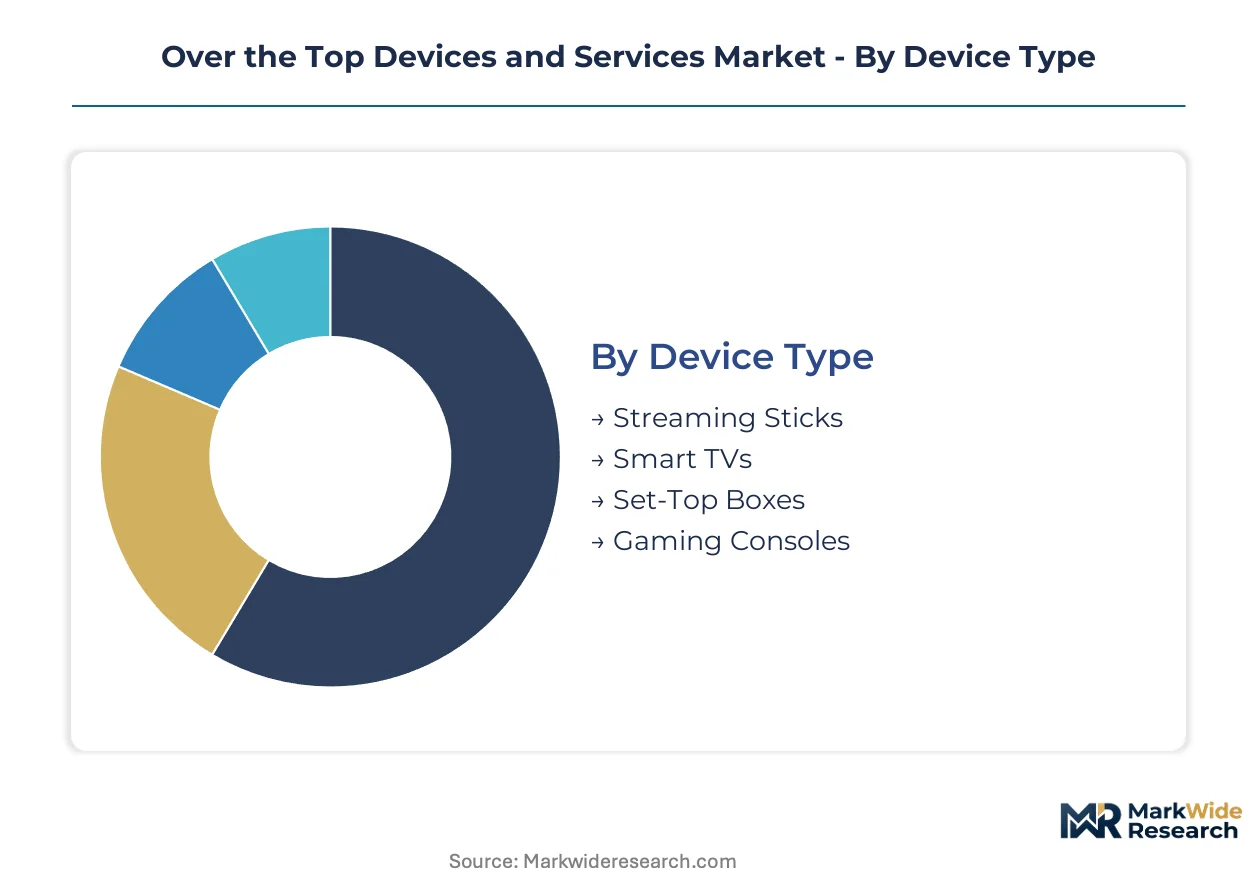
Device refresh cycles and service bundling strategies fragment addressable demand across hardware generations and content consumption patterns. Upgrade timelines vary dramatically between residential broadband households replacing aging streaming sticks and enterprises provisioning unified video conferencing infrastructure.
Device Type:
Replacement velocity accelerates as fiber-to-the-home deployment renders legacy hardware incapable of 4K adaptive bitrate streaming workloads.
- Streaming Sticks:Silicon-based SoC architectures enable die-shrink cost efficiencies for entry-level HDMI dongles. Demand concentrates in price-sensitive households across São Paulo and Mumbai where smart TV penetration remains incomplete.
- Smart TVs:Integrated IP-based transmission protocols eliminate external hardware dependencies while supporting AV1 codec default enablement. Residential broadband households in Germany and Brazil drive volume as fiber-optic infrastructure replaces copper last-mile delivery.
- Set-Top Boxes:Hybrid devices bridge legacy broadcast integration requirements for cable-maintaining households.
- Gaming Consoles:Cloud gaming service integration positions PlayStation and Xbox as the fastest-expanding interactive content access channel.
Smart TVs sit at the top of the volume ranking, with gaming consoles climbing the fastest.
Service Type:
Margin structure varies sharply between recurring subscription predictability and advertising-supported tier economics.
- Video Streaming:Subscription-based bundles displace linear broadcast consumption through direct-to-consumer monetization. North American saturation compels Netflix and Amazon toward exclusive content production for retention.
- Music Streaming:Lower per-user revenue pools rely on scale economics and family plan penetration.
- Cloud Gaming:Latency-sensitive interactive workloads demand edge computing deployment, compressing infrastructure distance between origin and endpoint. Seoul and San Francisco engineering teams target default enablement timelines.
- Subscription Services:Recurring revenue predictability generates the deepest margin pools across residential and enterprise segments.
Video streaming dominates installed base, while cloud gaming gains share fastest.
End User:
Procurement authority and content licensing complexity diverge between consumer discretion and institutional compliance requirements.
- Households:Aggregator bundling consolidates payment interfaces, compressing direct platform relationships. Nordic markets exhibit concentrated third-party integration through Telenet and Telia unified billing portals.
- Educational Institutions:GDPR Article 17 mandates force ephemeral data processing architectures for student privacy compliance.
- Businesses:Enterprise video conferencing and training content delivery require localized encryption standards under cross-border data flow restrictions.
- Content Providers:Original production houses negotiate placement fees within aggregator storefronts as disintermediation advances.
Households anchor volume concentration, with educational institutions expanding most quickly.
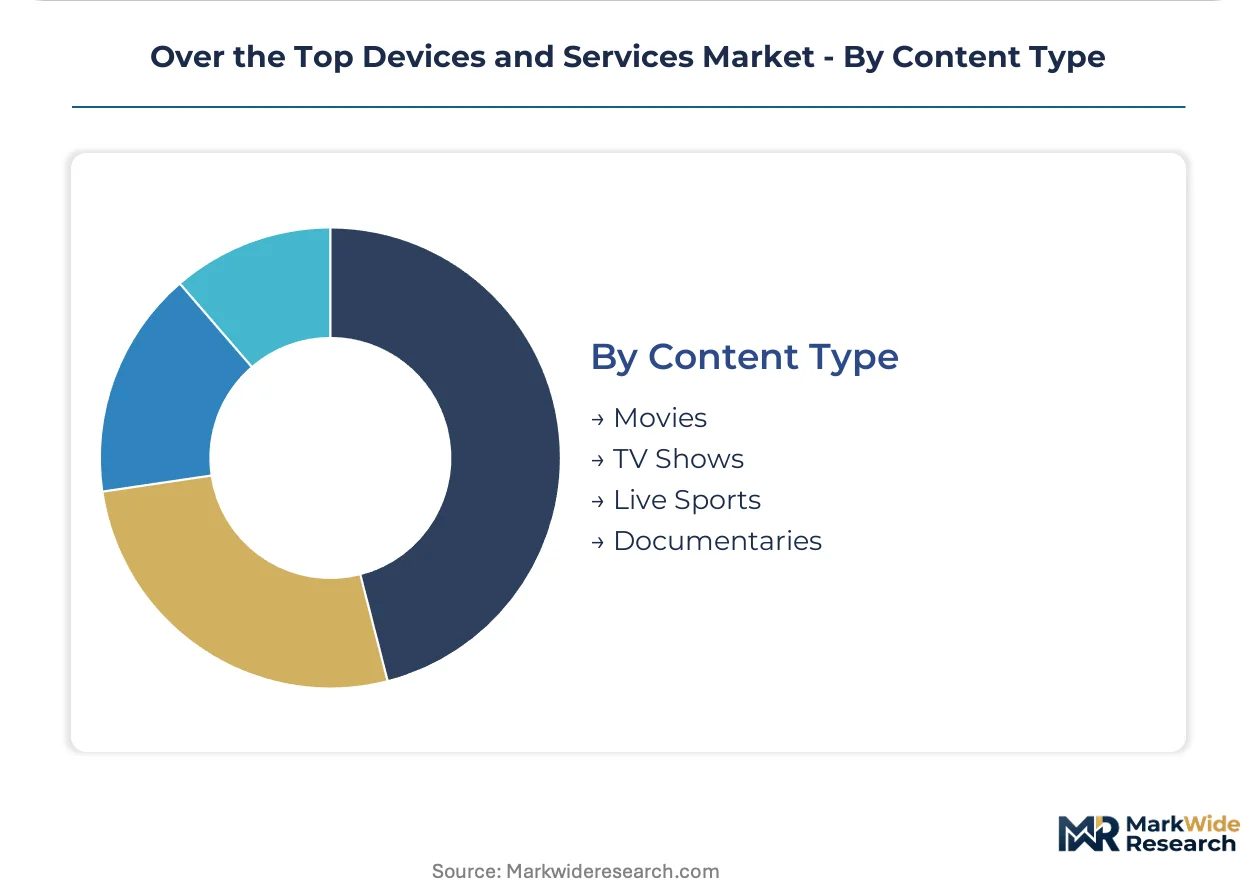
Content Type:
Production financing structures and territorial licensing fragmentation shape commissioning cycles differently across format categories.
- Movies:Territory-exclusive distribution agreements inflate per-subscriber acquisition costs through redundant library maintenance.
- TV Shows:Serialized content drives binge-consumption patterns and subscription retention metrics.
- Live Sports:Real-time delivery demands specialized adaptive bitrate engineering across heterogeneous network conditions.
- Documentaries:Local content quota mandates compress commissioning timelines for domestic production requirements in India and Germany.
TV shows command the largest addressable base, with live sports showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's cloud gaming engineering clusters anchor IP-based transmission protocol development across the Asia-Pacific, while San Francisco's streaming platform headquarters drive adaptive bitrate codec optimization roadmaps.
United States
FCC net neutrality frameworks govern platform liability standards for encryption and parental control feature sets. Residential broadband households in Austin and Denver accelerate fiber-to-the-home replacement of copper infrastructure. Netflix and Amazon anchor exclusive content production in Los Angeles to sustain subscriber retention metrics.
India
TRAI OTT consultation mechanisms clarify cross-border data flow restrictions for international entrants deploying regional content caching. Mumbai and São Paulo fiber deployment accelerates smart TV adoption among price-sensitive households. Silicon-based SoC architectures in entry-level streaming sticks penetrate semi-urban zones previously capped at sub-HD delivery.
Germany
Germany's Federal Data Protection Authority enforces GDPR Article 17 right-to-erasure mandates with 72-hour compliance windows for recommendation engine rearchitecture. Berlin and Munich engineering teams accelerate AV1 codec default enablement timelines. Local content quota mandates compress documentary commissioning cycles for domestic production requirements.
Brazil
ANVISA and national telecommunications regulators shape spectrum allocation policies for 4K streaming quality thresholds. São Paulo's fiber-optic infrastructure replacement creates concentrated demand pockets for subscription video bundles. Copper infrastructure persistence in rural zones caps addressable premium-tier demand despite metropolitan deployment.
South Korea
MFDS and national broadcast regulators coordinate latency-sensitive interactive workload standards for cloud gaming service integration. Seoul engineering teams target 2025 default enablement for edge computing architectures compressing origin-to-endpoint distance. PlayStation and Xbox ecosystems represent the fastest-expanding hardware channel for gaming console access points.
Over the Top Devices and Services Market Key Industry Players
Global majors compete with regional champions across content production and cloud infrastructure dimensions. The vendor base stratifies between vertically integrated streaming platforms, advertising-supported tier specialists, and hardware-agnostic software distributors. Three archetypes dominate: exclusive content producers sustaining retention through original programming, advertising technology platforms monetizing data-driven audience segmentation, and cloud infrastructure operators anchoring delivery networks. Competitive moves concentrate on backward integration into content libraries and strategic partnerships for aggregator bundling.
Among US-based technology conglomerates, Netflix, Inc. and Amazon.com, Inc. occupy positions exemplifying the exclusive content production archetype, while Roku, Inc. represents the advertising-supported tier specialist model. These three entities anchor distinct competitive vectors within the subscription and advertising monetization landscape.
| Leading Market Players |
|---|
| Netflix, Inc. |
| Amazon.com, Inc. |
| Roku, Inc. |
| Google LLC |
| Apple, Inc. |
| The Walt Disney Company |
| Hulu, LLC |
| Tencent Holdings Ltd. |
| Akamai Technologies |
| Others |
Cost & Logistics Intelligence
Residential broadband households in price-sensitive emerging markets anchor demand concentration for entry-level streaming hardware, locking the dominant pricing model around silicon-based SoC cost-down roadmaps that compress hardware margins while expanding addressable reach.
Pricing Analysis
Input-cost pass-through from semiconductor foundry capacity constraints shapes subscription tier economics across hardware and service bundles. Three-tier pricing structure across premium, standard, and economy levels differentiates by resolution tier and advertising load, with AV1 codec deployment enabling quality parity at lower bitrates. Pricing pressure stems from advertising-supported tier proliferation as Roku and regional challengers compete for price-sensitive segments. Households in São Paulo and Mumbai exhibit highest price sensitivity, while enterprise video conferencing clients in Germany and the United States absorb premium tiers with minimal elasticity.
Supply Chain Analysis
GDPR Article 17 compliance certification gates European market entry, forcing localized server deployment and encryption standard verification before revenue recognition. Semiconductor fabrication concentrates in Taiwan and South Korea, while final assembly of streaming sticks clusters in China and Vietnam. Supply chains draw from specialized codec optimization talent pools in Seoul and San Francisco, with single-source vulnerability in edge computing infrastructure for cloud gaming workloads. Distribution runs through third-party aggregator portals in Nordic markets and direct platform relationships in North American households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a geographic-arbitrage play where fiber-to-the-home deployment timelines in São Paulo and Mumbai compress hardware refresh cycles faster than GDPR-mandated infrastructure investments in Berlin and Munich.
For Market Incumbents: Deepen backward integration into exclusive content production to defend against advertising-supported tier erosion from regional challengers. Incumbents should expand regional content caching infrastructure in India under TRAI consultation clarity to reduce compliance uncertainty for international entrants. Priority investment in AV1 codec optimization talent pools anchors technical differentiation against emerging platform competitors.
For New Entrants and Emerging Players: Rural households tethered to copper DSL infrastructure represent the most penetrable buyer archetype for entry-level streaming sticks with sub-HD optimization. New entrants should target semi-urban zones in Brazil and India where silicon-based SoC die-shrink roadmaps enable price points below smart TV replacement thresholds. Go-to-market execution through mobile carrier bundling bypasses saturated aggregator portals.
For Investors and Strategic Acquirers: Cloud infrastructure operators are the most active acquirer in this space, consolidating edge computing assets for latency-sensitive interactive workloads. Long-term viability centers on captive supply of fiber-to-the-home deployment partnerships and exclusive content libraries with territorial licensing leverage. Signal to monitor: TRAI OTT consultation outcome clarity as inflection trigger for India market entry capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Content Caching Deployment | TRAI consultation mechanisms in India reduce compliance uncertainty for international platform entrants. |
| AV1 Codec Default Enablement | Seoul and San Francisco engineering teams target bandwidth-constrained geographies previously excluded from premium tiers. |
| Advertising-Supported Tier Launch | Roku's data-driven audience segmentation tools unlock price-sensitive user segments beyond subscription saturation. |
| Cloud Gaming Service Integration | PlayStation and Xbox ecosystems represent fastest-expanding hardware channel bypassing streaming stick saturation. |
| Aggregator Bundling Partnership | Telenet and Telia unified billing portals in Nordic markets consolidate payment interfaces compressing direct platform relationships. |
Research Approach
Bottom-up residential broadband household modeling reconciled against top-down fiber-to-the-home deployment tracking forms the analytical core of this study. Primary interviews with streaming platform engineering directors, content licensing executives, regulatory affairs leads at TRAI and GDPR compliance officers, and smart TV procurement managers at major OEMs combined with secondary validation from FCC spectrum allocation filings, ANVISA telecommunications regulations, and hyperscaler capex disclosures. Top-down and bottom-up triangulation cross-validates hardware shipment estimates against service subscriber metrics.
Input-output matrices map silicon-based SoC die-shrink roadmaps to streaming stick unit economics across price-sensitive market tiers. Segmentation dimensions modeled include device type, service monetization model, end-user procurement authority, and content format category across the analysis window. CAGRs derive from adaptive bitrate streaming bandwidth demand curves intersecting fiber deployment timelines. Forecast inputs incorporate GDPR Article 17 compliance cost structures and TRAI consultation mechanism outcome probabilities.
Underlying measurement precision varies by segment; subscription service revenue pools carry tighter precision than advertising-supported tier economics due to disclosure transparency differentials. Forecasts reflect assumptions around fiber-optic infrastructure replacement velocity and regulatory consultation timelines. A model refresh is warranted upon material change in TRAI OTT consultation final guidelines or FCC net neutrality framework revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Data Center CPU Market
Others
Europe Air Separation Unit Market
Others
Snus Market
Others
Fiberglass Storage Tanks Market
Others
Military Sensors Software Market
Others
India Smart Home Market
Others
Brazil Cane Sugar Market
Others
Level Measuring Instrument Market
Others
AI in Precision Medicine Market
Others
Edible Insects for Animal Feed Market
Others
Global Retail Media Networks Market
Others
Industrial Tablet PC Market
Others
Shear Testing Equipment Market
Others
Smart TV Platforms Market
Others
Paraffin Physical Therapy Market
Others
Latin America IT Device Market