
 US Air Quality Analyzers Market | 2026-2036
US Air Quality Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
US Air Quality Analyzers Market Intelligence
Buyer concentration across US industrial facilities is broadening as mid-sized refineries and chemical plants deploy analyzers previously limited to major emitters. Thermo Fisher Scientific Inc. leverages its mass spectrometry depth to anchor the high-end compliance segment. TSI Incorporated specializes in portable particulate monitors for field teams navigating OSHA workplace air rules. Aeroqual competes on cost-efficient optical sensor arrays suited for community-scale networks.
Air quality analyzers are instruments that detect and quantify gaseous pollutants, particulate matter, and aerosol compositions through calibrated sensing technologies, typically achieving detection thresholds in parts per billion for criteria pollutants such as ozone, nitrogen dioxide, and sulfur dioxide. These systems serve industrial operators, environmental agencies, and health researchers by providing legally defensible data for regulatory reporting and public health alerts. Optical sensors occupy the largest installed base due to their reliability in continuous ambient monitoring, while mass spectrometry commands premium positioning in research institutions requiring molecular-level speciation. Electrochemical sensors extend into indoor air quality applications where lower capital outlays match commercial building budgets.
EPA enforcement under the Clean Air Act, OSHA permissible exposure limits, and state-level California Air Resources Board protocols collectively mandate analyzer accuracy, calibration frequency, and data transparency. The Inflation Reduction Act channels procurement dollars toward environmental justice communities, reshaping demand geography toward fence-line monitoring near disadvantaged neighborhoods. Stakeholders must weigh instrument interoperability against emerging EPA requirements for real-time data streaming to federal repositories.
Market Dynamics
The US air quality analyzers market is experiencing structural pressure from the EPA's tightened National Ambient Air Quality Standards, which compel industrial operators to expand continuous monitoring networks beyond traditional stack emissions into fence-line and community-scale deployments.
Growth Catalysts
- Inflation Reduction Act funding:Federal procurement dollars flowing toward environmental justice communities are accelerating hyperlocal monitoring network buildouts in disadvantaged neighborhoods adjacent to refineries and chemical plants.
- Midwest industrial corridor expansion:Mid-sized refineries and chemical processors across Ohio, Indiana, and Illinois are deploying analyzers previously limited to major emitters, broadening the buyer base beyond historical concentration.
- Optical sensor maturation:Cost-efficient photoelectric arrays now achieve detection thresholds sufficient for regulatory reporting, enabling community-scale networks that were economically unfeasible under legacy mass spectrometry systems.
Market Restraints
- Calibration consumables volatility:Certified reference gas cylinders and zero-air generators face supply concentration among specialty chemical suppliers, creating input cost unpredictability for continuous monitoring operations.
- Mass spectrometry import dependence:High-end molecular speciation instruments rely heavily on European and Asian component sourcing, exposing compliance timelines to transatlantic logistics friction.
- Electrochemical sensor drift limitations:Lower-cost indoor air quality monitors suffer calibration degradation in high-humidity environments, constraining deployment reliability in Gulf Coast petrochemical corridors.
Strategic Opportunities
- Texas Permian Basin oilfield emissions:Unconventional production growth in West Texas and southeastern New Mexico is generating demand for portable methane and particulate monitors among midstream operators lacking permanent infrastructure.
- California Central Valley agricultural dust:PM10 and PM2.5 monitoring requirements tied to San Joaquin Valley Air Pollution Control District rules are creating sustained replacement cycles for aging nephelometer networks.
- Real-time data streaming mandates:Emerging EPA requirements for direct instrument-to-repository data transmission are opening integration service opportunities for systems integrators capable of API-compliant middleware development.
Industry Challenges
- Metrologist talent scarcity:Qualified technicians capable of executing EPA Method 40 CFR Part 58 calibration protocols are concentrated among legacy environmental consulting firms, constraining operator self-sufficiency.
- Legacy system interoperability:Decades-old data acquisition systems at Department of Defense and utility installations resist seamless integration with modern IoT-enabled analyzers, prolonging deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Air Quality Analyzers Market |
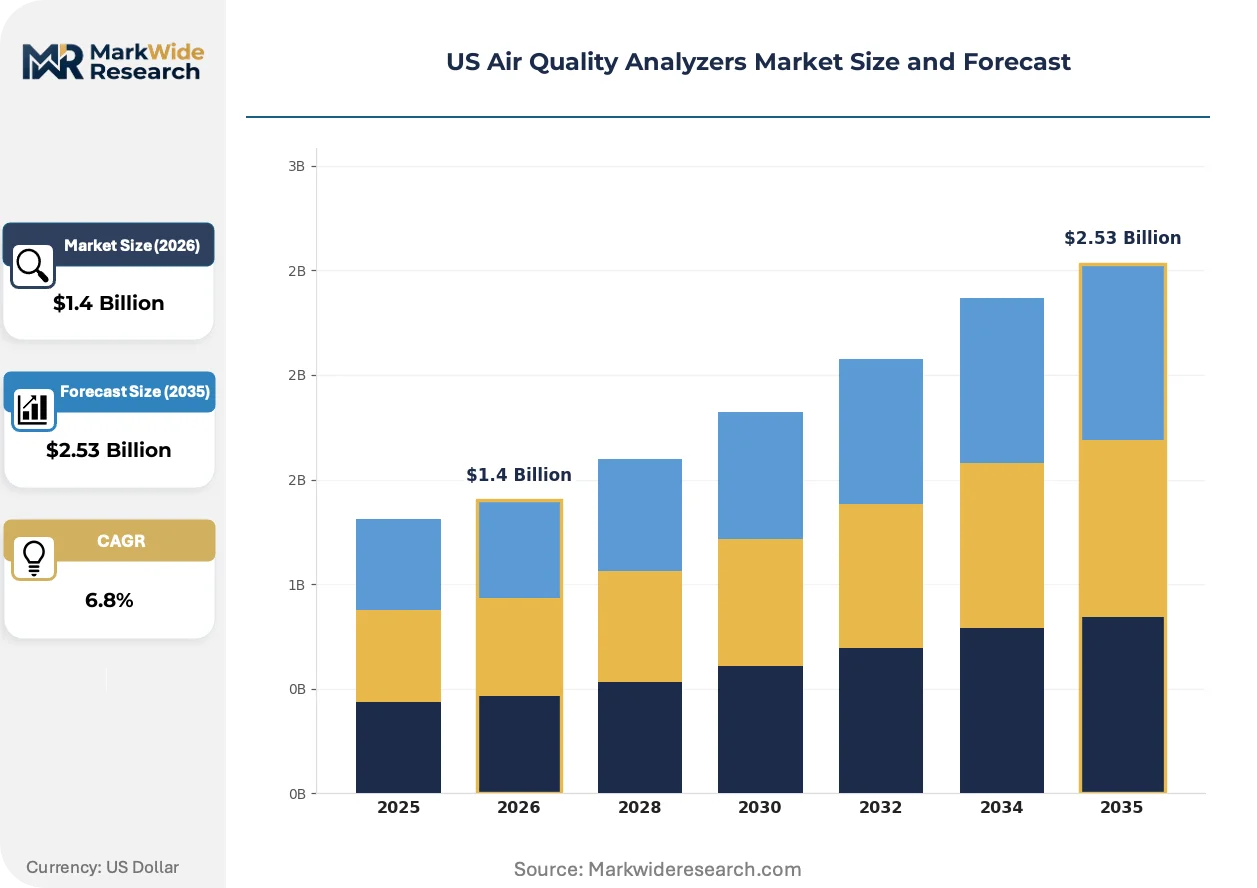
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Sensors, Optical Sensors, Electrochemical Sensors, Particulate Matter Sensors Technology: Remote Sensing, Laser-Induced Breakdown Spectroscopy, Gas Chromatography, Mass Spectrometry End User: Environmental Agencies, Research Institutions, Industrial Facilities, Smart Cities Application: Aerosol Monitoring, Emissions Detection, Indoor Air Quality, Compliance Monitoring |
| Companies Covered | Thermo Fisher Scientific Inc., Teledyne Technologies Inc., Siemens AG, Honeywell International Inc., Emerson Electric Co., 3M Company, TSI Incorporated, Aeroqual, Horiba Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Air Quality Analyzers Market Strategic Shifts & Innovations
Sensor miniaturization and edge computing are redistributing analytical capability from central laboratories to distributed field nodes, compressing the latency between pollutant detection and public health alert issuance.
Low-cost optical particulate sensors paired with cellular telemetry are decentralizing air quality monitoring authority from federal reference stations to municipal health departments and community organizations. Cities including Houston and Los Angeles are deploying hundred-node networks that stream data directly to public dashboards. This topology is compressing the traditional three-tier hierarchy of federal, state, and local monitoring into flatter, more responsive architectures.
EPA enforcement under revised ozone and particulate matter NAAQS is tightening allowable measurement uncertainty margins, compelling instrument manufacturers to enhance photodetector stability and temperature compensation algorithms. Refineries along the Gulf Coast are retrofitting existing shelters with chilled mirror hygrometers to meet enhanced data quality objectives. The compliance segment is responding by extending warranty periods and embedding predictive maintenance analytics to defend service contract renewals.
Municipal procurement offices are unbundling analyzer hardware from multiyear service agreements, favoring competitive bidding for calibration and repair functions. State environmental agencies in Pennsylvania and Michigan are piloting performance-based contracts where payment ties to uptime percentage rather than scheduled maintenance visits. This shift is most visible in the Great Lakes region, where budget-constrained air quality districts seek to reduce total cost of ownership through vendor diversification.
US Air Quality Analyzers Market Segmentation
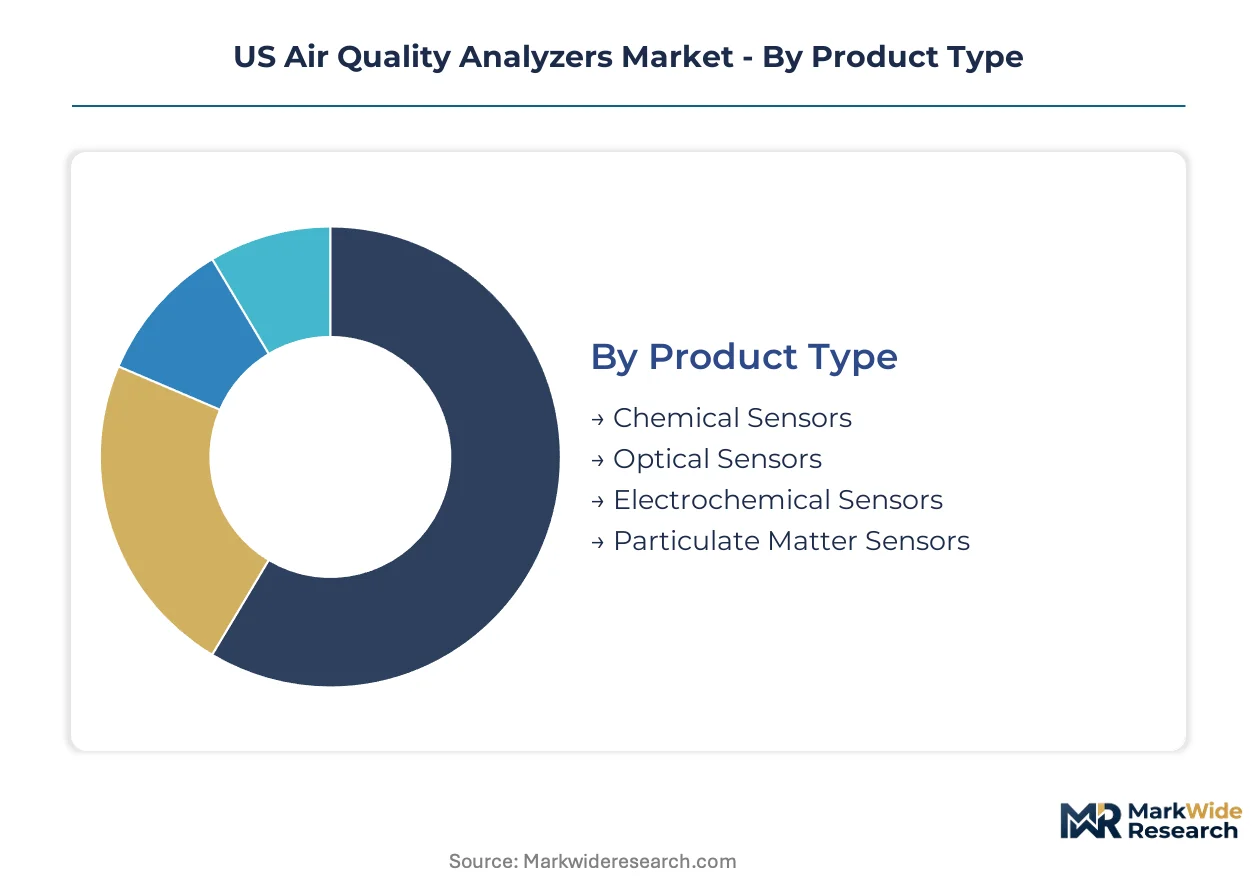
Analyzer segmentation reveals how detection physics, deployment context, and regulatory pressure intersect to shape procurement patterns. Buyers select instrument architectures based on whether data serves courtroom evidence, research publication, or operational alarms.
Product Type:
Detection chemistry determines capital outlay, calibration burden, and environmental tolerance.
- Optical Sensors:Photoelectric arrays exploit light scattering and absorption spectra to quantify particulate mass and gas concentrations. These instruments anchor California Central Valley agricultural dust networks where PM10 compliance demands continuous nephelometer uptime under extreme temperature swings.
- Chemical Sensors:Metal oxide semiconductor films react with target gases to produce conductivity changes proportional to concentration. Refineries along the Texas Gulf Coast deploy these for fence-line benzene detection where drift tolerance matters less than rapid alarm response.
- Electrochemical Sensors:Amperometric cells consume electrolyte through redox reactions with pollutants like nitrogen dioxide and sulfur dioxide.
- Particulate Matter Sensors:Compact optical modules sized for IoT nodes sacrifice precision for density in community-scale deployments.
Optical sensors lead on scale; particulate matter sensors lead on momentum.
Technology:
Resolution depth separates laboratory-grade molecular speciation from field-deployable screening.
- Mass Spectrometry:Ionization and mass-to-charge ratio separation deliver molecular-level compound identification at parts-per-trillion sensitivity. EPA compliance laboratories in Research Triangle Park and Denver rely on these systems for 40 CFR Part 58 equivalency demonstrations where legal defensibility demands documented uncertainty budgets.
- Gas Chromatography:Volatile organic compound separation through capillary columns enables speciated hydrocarbon quantification. Petrochemical complexes in Louisiana's Cancer Alley deploy GC-FID configurations for flare monitoring where BTEX reporting triggers operational shutdowns.
- Remote Sensing:Open-path infrared and ultraviolet differential optical absorption spectroscopy measures column-integrated concentrations across facility perimeters.
- Laser-Induced Breakdown Spectroscopy:Pulsed laser ablation creates plasma emissions for elemental analysis of aerosol filter deposits.
Mass spectrometry leads on scale; gas chromatography leads on momentum.
End User:
Procurement authority reflects funding source, technical staff depth, and liability exposure.
- Environmental Agencies:State and federal monitoring stations operate reference-grade networks with federally prescribed quality assurance. The California Air Resources Board maintains the nation's densest regulatory grid, with San Joaquin Valley stations achieving 95% data capture rates through rigorous preventive maintenance protocols.
- Industrial Facilities:Refineries, chemical plants, and power generators purchase analyzers to satisfy Title V permit conditions and consent decree obligations. Ohio River Valley steel mills are expanding continuous emissions monitoring systems ahead of tightened ozone NAAQS designations.
- Research Institutions:Universities and national laboratories acquire instruments for atmospheric chemistry and exposure science investigations.
- Smart Cities:Municipal health departments deploy dense sensor grids for hyperlocal pollution mapping and public dashboard transparency.
Environmental agencies lead on scale; smart cities lead on momentum.
Application:
Use case dictates detection threshold, data latency, and archival requirements.
- Compliance Monitoring:Legally defensible measurement for regulatory reporting and enforcement defense demands EPA-equivalent methods with documented uncertainty. Gulf Coast petrochemical corridors are retrofitting shelters with chilled mirror hygrometers to meet enhanced data quality objectives under revised ozone standards.
- Emissions Detection:Fugitive and stack emission quantification supports leak repair programs and trading scheme participation. Permian Basin midstream operators deploy portable methane analyzers for LDAR surveys across sprawling infrastructure lacking permanent monitoring.
- Aerosol Monitoring:Size-fractionated particulate measurement serves health studies and visibility protection programs.
- Indoor Air Quality:Commercial building ventilation control and occupant comfort management utilize lower-cost sensors with relaxed accuracy specifications.
Compliance monitoring leads on scale; emissions detection leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's oil sands monitoring networks operate at lower deployment density than US industrial corridors, while Mexico's emerging regulatory framework accelerates demand for cost-efficient sensor arrays near border manufacturing zones.
California
San Joaquin Valley agricultural dust drives sustained nephelometer replacement cycles under Air Resources Board PM10 mandates. The Central Valley Air Pollution Control District enforces continuous monitoring for fugitive emissions from dairy operations and diesel transport corridors. Bakersfield and Fresno anchor the nation's densest regulatory grid outside Los Angeles Basin, with stations achieving mandated data capture thresholds through rigorous preventive maintenance protocols.
Texas
Permian Basin oilfield methane and volatile organic compound detection dominates procurement from midstream operators lacking permanent infrastructure. EPA Region 6 enforcement under tightened ozone NAAQS compels fence-line monitoring expansion near Corpus Christi and Houston Ship Channel refineries. The Gulf Coast petrochemical corridor from Beaumont to Baytown represents the nation's largest concentration of Title V permit-driven analyzer deployment.
Ohio River Valley
Mid-sized refineries and chemical processors across Ohio, Indiana, and Illinois deploy analyzers previously limited to major emitters under tightened regional ozone designations. EPA's 2015 ozone NAAQS revision and subsequent reclassification of counties as non-attainment zones accelerate continuous emissions monitoring system upgrades. Pittsburgh-to-Cincinnati industrial corridor steel mills expand monitoring footprints ahead of anticipated particulate matter standard tightening.
Mid-Atlantic
Environmental justice community funding through Inflation Reduction Act channels procurement toward fence-line monitoring in disadvantaged neighborhoods adjacent to Philadelphia and Baltimore port facilities. Pennsylvania Department of Environmental Protection pilots performance-based service contracts where payment ties to instrument uptime percentage. Delaware River petrochemical complexes retrofit existing shelters with enhanced data quality objectives under state implementation plan revisions.
Pacific Northwest
Wildfire smoke monitoring networks drive demand for portable particulate analyzers across Oregon and Washington state health departments. EPA Region 10 collaborates with tribal air quality programs to deploy reference-grade stations in rural areas lacking historical monitoring infrastructure. Seattle-Tacoma metropolitan area expands hyperlocal sensor grids for real-time public health alert issuance during summer smoke intrusion events.
US Air Quality Analyzers Market Key Industry Players
US-based producers anchor the compliance-grade instrument tier; European and Asian specialists hold positions in portable and research-grade segments. The vendor base organizes around three strategic archetypes: diversified laboratory conglomerates with mass spectrometry depth, dedicated environmental instrumentation firms with regional service networks, and sensor technology specialists competing on cost-efficient optical arrays. Competitive moves concentrate on calibration service contract unbundling and predictive maintenance analytics embedding to defend renewal rates.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Teledyne Technologies Inc. exemplify positioning anchored in analytical instrument portfolios spanning life sciences and environmental applications. Honeywell International Inc. and Emerson Electric Co. represent industrial automation specialists extending process control expertise into emissions monitoring integration. Siemens AG occupies a position bridging European engineering heritage with North American regulatory compliance requirements. Among dedicated environmental specialists, TSI Incorporated and Aeroqual exemplify contrasting approaches to field-deployable and community-scale monitoring architectures respectively.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Teledyne Technologies Inc. |
| Siemens AG |
| Honeywell International Inc. |
| Emerson Electric Co. |
| 3M Company |
| TSI Incorporated |
| Aeroqual |
| Horiba Ltd. |
| Others |
Cost & Logistics Intelligence
Metrologist talent concentration across the Ohio River Valley and Gulf Coast petrochemical corridors creates labor-cost differentials that widen pricing-tier spreads between premium compliance-grade instruments and field-service-dependent economy offerings. EPA calibration protocol expertise scarcity in rural monitoring districts forces buyers toward bundled service contracts that inflate total cost of ownership beyond hardware sticker prices.
Pricing Analysis
Capacity additions in Southeast Asian optical component manufacturing are reshaping price floors for photoelectric sensor arrays deployed in community-scale networks. Three-tier pricing structure across premium, standard, and economy levels separates mass spectrometry systems with documented uncertainty budgets from electrochemical sensors with relaxed accuracy specifications. Cost compression in economy-tier particulate monitors is intensifying because municipal procurement offices unbundle hardware from multiyear service agreements. Environmental justice community grant recipients exhibit highest price sensitivity; EPA reference laboratories demonstrate lowest.
Supply Chain Analysis
Photodetector and laser diode supply rests on Japanese, German, and Taiwanese specialty component producers with limited alternative sourcing. Raw material dependencies span precision optical glass, rare-earth-doped crystals, and certified reference gas mixtures. Single-source vulnerability concentrates in chilled mirror hygrometer assemblies for enhanced data quality objectives. Distribution runs through environmental instrumentation distributors with regional service technician networks, though direct manufacturer relationships dominate high-end compliance segment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US air quality analyzers market functions as a stable compounder underpinned by EPA National Ambient Air Quality Standards enforcement that mandates continuous monitoring infrastructure regardless of economic cycles.
For Market Incumbents: Lock in calibration service contract renewals by embedding predictive maintenance analytics that reduce unplanned downtime for fence-line monitoring networks. Deepen backward integration into zero-air generator production to offset certified reference gas cylinder supply concentration. Counter optical sensor commoditization through EPA-equivalent method certification investments that preserve premium positioning.
For New Entrants and Emerging Players: Launch via municipal health department procurement channels targeting hundred-node hyperlocal sensor grids in Inflation Reduction Act-funded environmental justice communities. Exploit white-space in Texas Permian Basin portable methane analyzer deployment where midstream operators lack permanent infrastructure. Differentiate through API-compliant middleware development for emerging EPA real-time data streaming mandates.
For Investors and Strategic Acquirers: Industrial automation conglomerates with process control expertise represent the most active acquirer category in this space. Long-term viability centers on recurring calibration service revenue streams rather than hardware shipment cyclicality. Target acquisition candidates with established EPA Method 40 CFR Part 58 equivalency demonstrations and dense regional technician networks. Watch EPA ozone NAAQS designation reclassifications as volume inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Contract Unbundling | Municipal procurement offices in Pennsylvania and Michigan pilot performance-based payment tied to instrument uptime percentage. |
| Predictive Maintenance Analytics Embedding | Compliance-grade manufacturers defend renewal rates through machine learning models anticipating photodetector drift failures. |
| Hyperlocal Sensor Grid Deployment | Houston and Los Angeles municipal health departments deploy hundred-node networks streaming data to public dashboards. |
| EPA Real-Time Data Streaming Integration | Systems integrators develop API-compliant middleware for direct instrument-to-repository transmission under emerging requirements. |
| Optical Sensor Miniaturization | Edge computing redistribution enables distributed field nodes that compress pollutant detection-to-alert latency intervals. |
Research Approach
Multiple input streams — primary interviews with environmental agency station managers, industrial facility compliance officers, and instrument manufacturer product directors; secondary validation through EPA enforcement databases, state air quality annual reports, and Clean Air Act consent decree filings; plus customs records for mass spectrometry component imports — were reconciled through bottom-up installation base enumeration and top-down procurement budget triangulation.
Historical deployment trajectories were cross-referenced against expert panel assessments of NAAQS tightening timelines. Segmentation modeling spanned detection chemistry, resolution depth, procurement authority, and application use case across the projection horizon. CAGR derivation incorporated instrument replacement cycle analysis, regulatory mandate phase-in schedules, and federal funding appropriation trajectories for environmental justice community monitoring.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged EPA equivalency method approval delays or accelerated optical sensor commoditization. A small set of named triggers — Inflation Reduction Act funding reauthorization, regional ozone non-attainment reclassifications, and mass spectrometry import logistics disruptions — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Air Pollution Control Systems Market
Air Quality Control Systems
Singapore Air Purifier Market
Air Quality Control Systems
Middle-East and Africa Industrial Air Quality Control Systems Market
Air Quality Control Systems
Asia-Pacific Indoor Air Purification Market
Air Quality Control Systems
Green Emissions Analyzers Market
Air Quality Control Systems
Environmental Control System (ECS) Market
Air Quality Control Systems
North America Industrial Air Quality Control Systems Market
Air Quality Control Systems
Air Pollution Control Equipment Market
Air Quality Control Systems
Environment Controllers Market
Air Quality Control Systems
Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Global Mist Eliminator Market
Air Quality Control Systems
Asia Pacific Air Filtration Market
Air Quality Control Systems
Air Scrubber Market
Air Quality Control Systems
Ozone Generation Market
Air Quality Control Systems
Europe Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Asia-Pacific Air Quality Control System Market