
 Indoor Air Quality Service Market | 2026-2036
Indoor Air Quality Service Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor Air Quality Service Market Insights
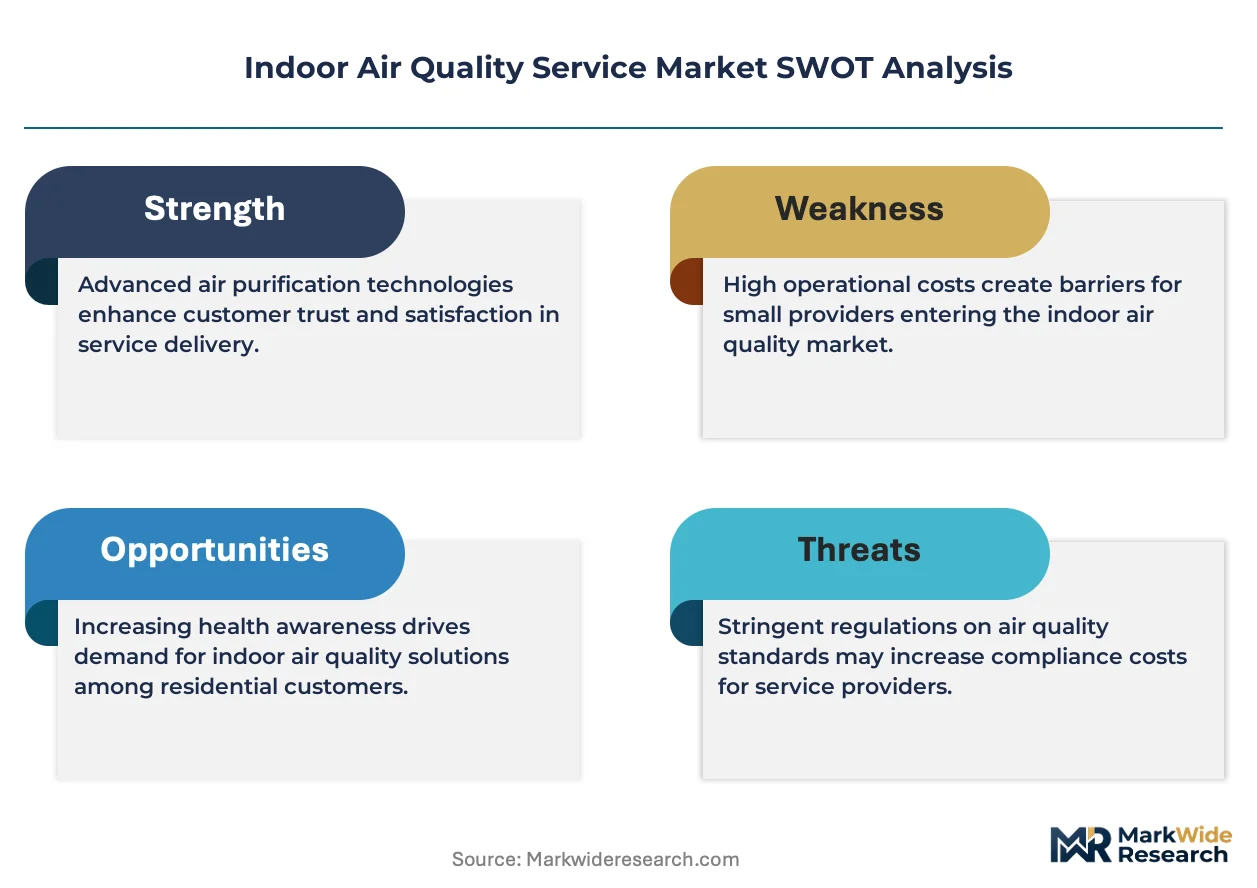
The United States is rewriting competitive dynamics in indoor air quality services as federal school infrastructure grants and ASHRAE guideline revisions expand the addressable market for testing and remediation contracts. Honeywell International Inc. leverages its building automation portfolio to bundle air quality monitoring with climate control systems, while Trane Technologies sustains technical credibility through deep HVAC integration and energy-recovery ventilation expertise. Johnson Controls anchors its position in the commercial segment with facility management platforms that embed real-time pollutant tracking.
Indoor air quality service encompasses the assessment, treatment, and ongoing management of airborne contaminants within enclosed environments, typically measuring particulate matter, volatile organic compounds, carbon dioxide, and biological pollutants against established exposure thresholds. The primary purpose is to protect occupant health, ensure regulatory compliance, and optimize building system performance. Air filtration services command the largest share of current revenue as commercial buildings face escalating filter replacement and upgrade cycles, while ventilation optimization represents the fastest-expanding segment driven by post-pandemic fresh air delivery mandates. Sensor-based monitoring is maturing rapidly as IoT hardware costs decline and facility managers shift from episodic testing to continuous diagnostics.
The US EPA sets baseline ambient and indoor air quality benchmarks that shape service scope and certification requirements for contractors, while OSHA enforces workplace exposure limits that directly trigger employer procurement of professional monitoring. ASHRAE standards 62.1 and 62.2 provide the technical architecture most jurisdictions adopt for ventilation adequacy, creating a standardized compliance pathway that benefits national service providers. Stakeholders must weigh whether to build in-house diagnostic capabilities or partner with specialized firms as regulatory granularity intensifies and liability exposure for building operators expands.
Market Dynamics
Post-pandemic ventilation mandates are forcing building operators to recontract maintenance relationships around continuous monitoring rather than episodic inspection cycles, compressing procurement timelines and elevating technical certification requirements for service providers.
Growth Catalysts
- Healthcare Infrastructure Modernization:Hospital systems are embedding real-time particulate tracking into facility management platforms to satisfy Joint Commission accreditation standards and reduce nosocomial infection liability.
- EPA Clean Air Act Enforcement:Tightened ventilation benchmarks for commercial buildings are triggering mandatory professional assessment contracts where self-certification previously sufficed.
- IoT Sensor Cost Decline:Hardware price compression below fifty dollars per node is enabling district-wide school deployments that were economically unfeasible for aging public infrastructure.
Market Restraints
- Specialized Labor Scarcity:Certified industrial hygienists and building systems diagnosticians command wage premiums that inflate project delivery costs by twenty to forty percent in secondary metropolitan markets.
- Filter Media Supply Concentration:High-efficiency particulate arrestance media production clusters in East Asian manufacturing corridors, exposing service contractors to shipping volatility and tariff exposure.
- ASHRAE Standard Revision Lag:The three-to-five-year cycle for guideline updates creates compliance ambiguity for contractors advising clients on pre-standard versus post-standard system configurations.
Strategic Opportunities
- Remote Monitoring Platforms:Cloud-based dashboard services enable recurring revenue streams through subscription air quality management rather than transactional testing engagements.
- Green Building Certification Integration:LEED and WELL standard compliance pathways are bundling indoor environmental quality metrics with energy performance, expanding service scope for commercial property portfolios.
- K-12 Infrastructure Grants:Federal school facility modernization allocations are creating dedicated procurement channels for ventilation assessment and remediation in districts with historically deferred maintenance.
Industry Challenges
- Cross-Disciplinary Talent Integration:Effective service delivery requires synthesis of HVAC mechanical expertise, environmental health science, and data analytics capabilities that rarely coexist in single hiring pools.
- Legacy Building System Interoperability:Decades-old pneumatic controls and proprietary building automation protocols obstruct seamless sensor network deployment without costly infrastructure overlays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor Air Quality Service Market |
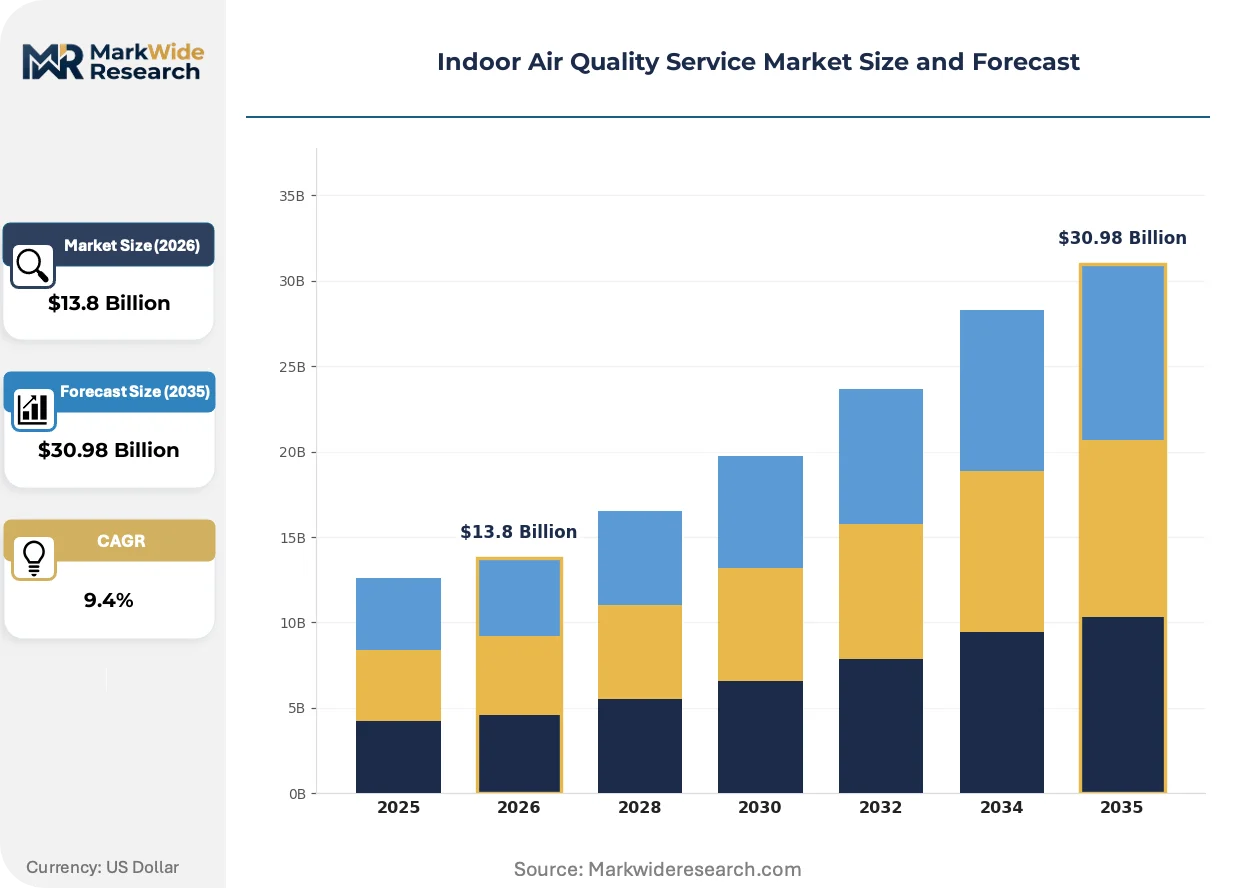
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $30.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Testing, Air Filtration, Ventilation Optimization, Mold Remediation Technology: HVAC, Air Purifiers, Sensors, Dehumidifiers Application: Residential, Commercial, Education, Healthcare End User: Homeowners, Facility Managers, Schools, Hospitals |
| Companies Covered | Honeywell International Inc., Trane Technologies, Johnson Controls, Daikin Industries, Carrier, Camfil, Emerson Electric, Thermo Fisher Scientific, Lennox International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor Air Quality Service Market Trends and Innovations
Sensor miniaturization and edge computing are collapsing the cost structure of distributed air quality networks, enabling building-scale deployments that previously required centralized laboratory analysis and extended turnaround intervals.
Photoelectric particulate sensors paired with metal-oxide volatile organic compound detectors are collapsing the distinction between professional-grade and consumer-grade monitoring hardware. School districts and small commercial property managers are adopting these integrated units for continuous corridor and classroom surveillance. The technology is collapsing service provider margins on baseline assessment contracts while compressing the sales cycle for premium remediation and system optimization engagements.
Revisions to ASHRAE Standard 62.1 are mandating enhanced outdoor air delivery rates and demand-controlled ventilation based on real-time occupancy sensing. The regulation is accelerating mechanical system retrofit cycles in Class B office inventory and triggering reinspection requirements for previously grandfathered installations. Building operators in California and New York are responding with multi-year service agreements that embed compliance documentation and automated reporting to local air quality districts.
Facility managers are unbundling air quality monitoring from bundled mechanical service contracts and contracting directly with specialized diagnostic firms. This disintermediation is disrupting traditional HVAC service relationships and elevating transparency requirements around data ownership and third-party platform access. The pattern is most pronounced in healthcare and pharmaceutical manufacturing verticals where audit trails carry regulatory weight.
Indoor Air Quality Service Market Segmentation
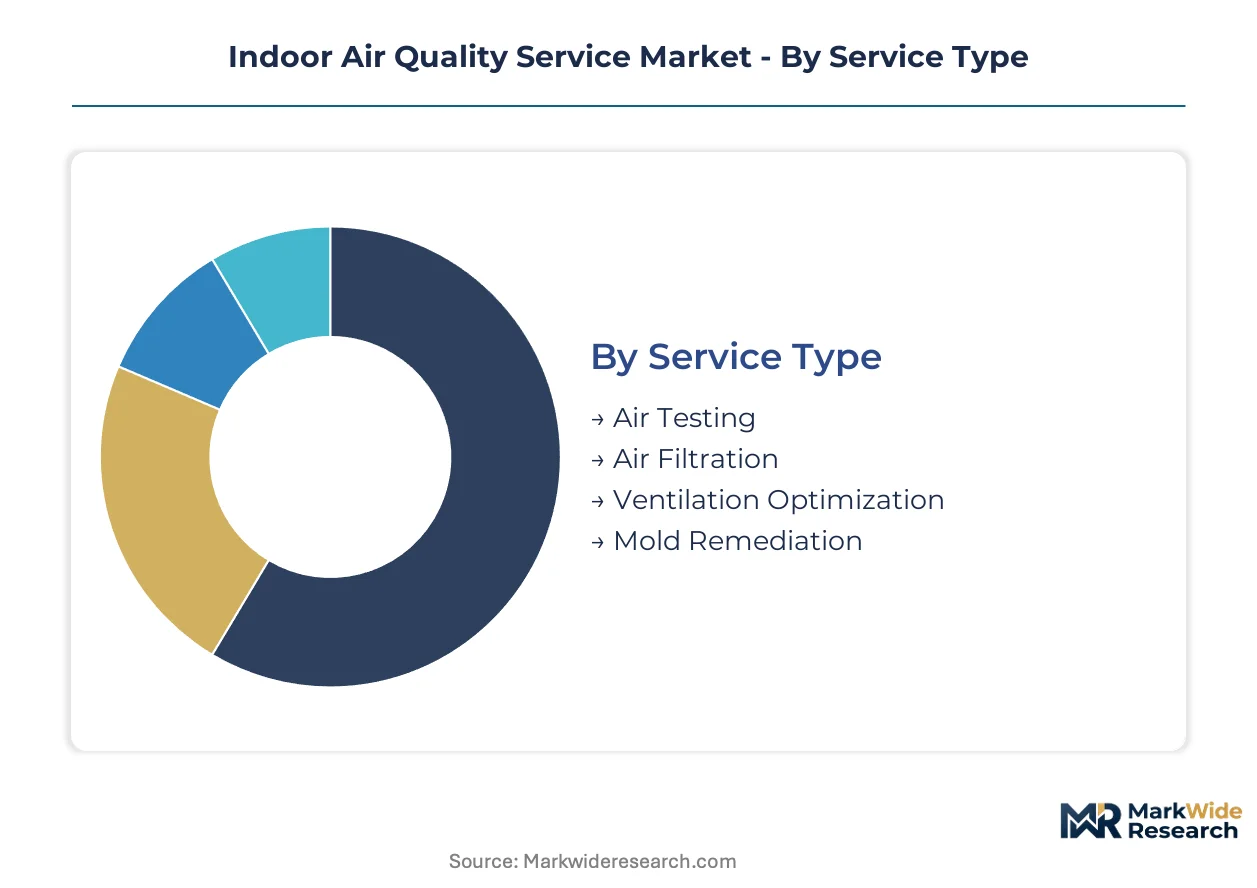
Indoor air quality service procurement patterns diverge sharply across building typologies and technical intervention types. Service providers must align capability portfolios with distinct compliance pressures, equipment lifecycles, and buyer sophistication levels that characterize each segment boundary.
Service Type:
Cost tier stratification separates commoditized testing from high-margin remediation engagements requiring specialized labor and recurring monitoring infrastructure.
- Air Testing:Baseline contaminant assessment protocols measure particulate matter, VOCs, and biological agents against EPA and OSHA exposure thresholds. Demand concentrates in commercial real estate transactions and pre-occupancy certification where documentation carries liability weight. Price compression from low-cost sensor proliferation is eroding margins on single-visit engagements.
- Air Filtration:Filter specification, installation, and maintenance cycles constitute the largest revenue pool as commercial buildings face accelerated replacement schedules under tightened ASHRAE guidelines. Healthcare facilities and K-12 districts in the United States are driving volume through federal infrastructure grants that mandate MERV-13 minimum upgrades.
- Ventilation Optimization:Mechanical system rebalancing and outdoor air delivery enhancement. Post-pandemic code revisions are expanding the addressable market for demand-controlled ventilation retrofits.
- Mold Remediation:Moisture source elimination and spore containment protocols. Insurance claim documentation requirements sustain professional service demand in humid climate zones.
Air filtration holds installed capacity. Ventilation optimization is rotating up the share rankings.
Technology:
Application context determines hardware selection—centralized mechanical integration versus distributed point-source treatment creates divergent procurement pathways.
- HVAC:Building-scale climate and ventilation systems that embed air quality management within mechanical infrastructure. Facility managers in Class A commercial properties favor integrated approaches that minimize redundant equipment footprints.
- Air Purifiers:Standalone filtration units deployed for localized contaminant control. Portable HEPA deployments surged in United States school districts during federal emergency funding windows.
- Sensors:IoT-enabled particulate and gas detection networks enabling continuous monitoring. Hardware costs below fifty dollars per node are collapsing deployment economics for multi-building portfolios.
- Dehumidifiers:Moisture control equipment preventing mold proliferation and VOC off-gassing. Baseline humidity management sustures steady replacement demand in coastal and riverine geographies.
Sensor deployments are climbing the fastest. HVAC integration maintains the deepest revenue per contract.
Application:
Building typology dictates regulatory exposure, occupancy density, and budget availability for air quality interventions.
- Residential:Single-family and multi-family dwelling units where consumer-grade detection and retail filtration dominate. Homeowner awareness campaigns from EPA and public health agencies are expanding professional assessment demand in high-radon and high-allergen regions.
- Commercial:Office, retail, and hospitality properties where tenant expectations and lease documentation drive service procurement. Class B inventory in the United States faces compressed retrofit timelines under revised ventilation mandates.
- Education:K-12 and higher education facilities with elevated occupancy density and aging mechanical systems. Federal facility modernization grants are creating dedicated procurement channels for ventilation assessment in historically underfunded districts.
- Healthcare:Hospitals, clinics, and long-term care facilities where Joint Commission accreditation and infection control protocols mandate continuous environmental monitoring. Real-time particulate tracking is embedding into facility management platforms to reduce nosocomial liability exposure.
Healthcare commands premium pricing. Education is gaining share fastest through federal grant deployment.
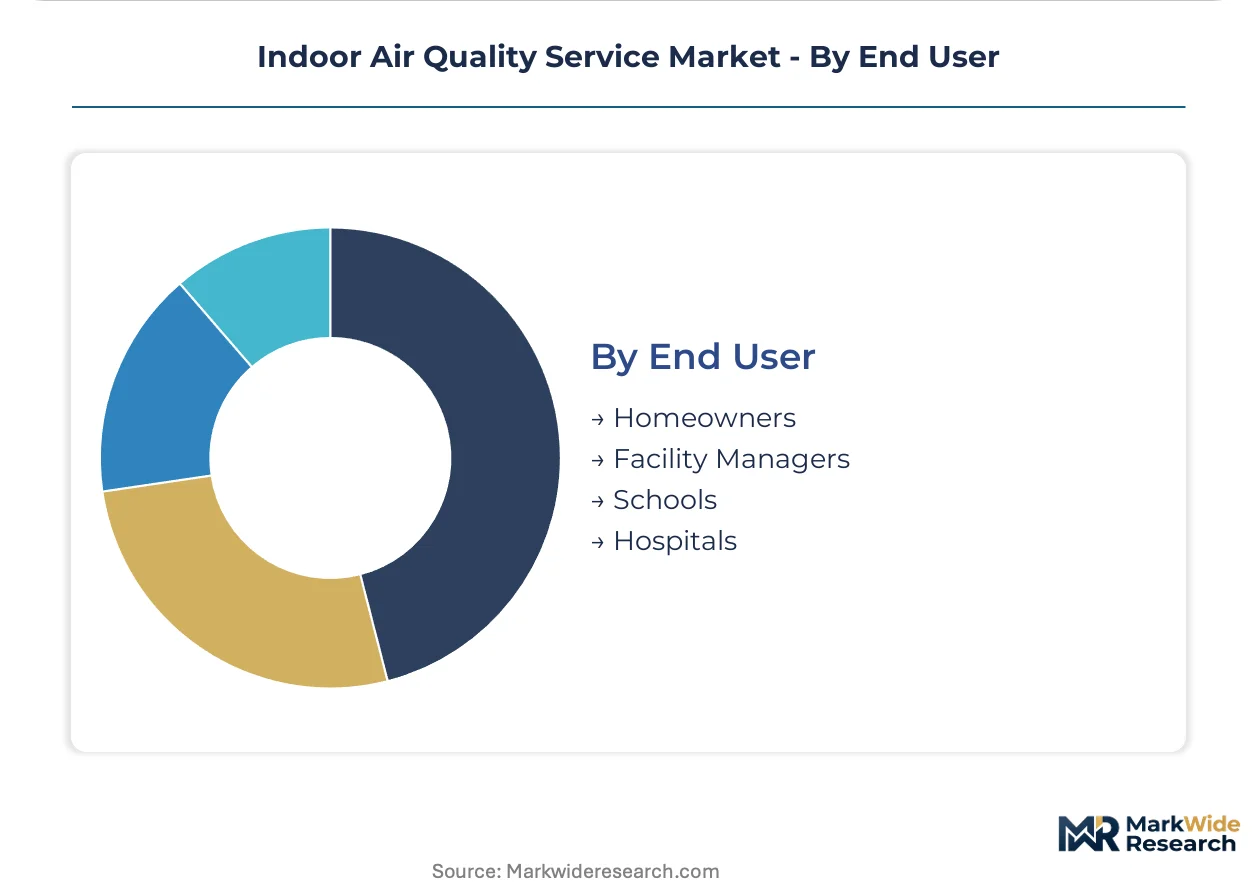
End User:
Buyer sophistication and procurement authority separate transactional retail purchases from multi-year service agreements with embedded compliance documentation.
- Homeowners:Individual residential occupants purchasing testing kits, portable purifiers, or point-source remediation. Retail channel dominance limits professional service penetration outside regulatory trigger events.
- Facility Managers:Commercial property professionals responsible for building system performance and tenant satisfaction. This cohort is disintermediating traditional HVAC service relationships to contract directly with specialized diagnostic firms.
- Schools:K-12 district administrators navigating federal infrastructure grants and state-level ventilation mandates. Procurement is consolidating around vendors offering district-wide deployment capabilities with automated reporting to local air quality districts.
- Hospitals:Healthcare system environmental services directors accountable to accreditation bodies and infection control committees. Audit trail requirements favor platform-based monitoring with third-party data verification.
Facility managers control the largest contract value. Schools are rotating up fastest through dedicated federal funding streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service provider networks concentrate where building stock density intersects with stringent ventilation codes. Regulatory enforcement intensity varies sharply across jurisdictions, fragmenting competitive positioning by geography.
United States
Federal school infrastructure grants and ASHRAE guideline revisions are expanding procurement channels for testing and remediation contracts. EPA Clean Air Act enforcement has tightened ventilation benchmarks, triggering mandatory professional assessments where self-certification previously sufficed. Aging K-12 districts in the Midwest and Northeast are deploying district-wide sensor networks with automated reporting to state environmental agencies.
Germany
Commercial property portfolios are embedding indoor environmental quality metrics into energy performance certifications under the EU Green Deal framework. The country's national building regulator enforces ventilation adequacy standards that align with DIN technical specifications, creating compliance pathways for integrated service providers. Industrial clusters in North Rhine-Westphalia are retrofitting Class B office inventory with demand-controlled ventilation systems.
China
Dual carbon goals are accelerating mechanical system retrofit cycles in commercial and educational facilities. The Ministry of Ecology and Environment sets baseline indoor air quality benchmarks that shape service scope for contractors in major metropolitan areas. Building operators in the Yangtze River Delta are adopting continuous monitoring platforms to satisfy municipal environmental disclosure requirements.
Japan
Healthcare facility modernization is embedding real-time particulate tracking into facility management platforms to reduce nosocomial infection liability. METI guidelines on building energy performance create standardized compliance pathways that benefit national service providers. Hospital systems in the Kanto region are consolidating procurement around vendors offering audit trail documentation for accreditation bodies.
United Kingdom
Post-pandemic building code revisions are compressing procurement timelines for ventilation assessment in commercial real estate transactions. The Health and Safety Executive enforces workplace exposure limits that directly trigger employer procurement of professional monitoring. Property managers in London and the Southeast are disintermediating traditional HVAC service relationships to contract directly with specialized diagnostic firms.
Indoor Air Quality Service Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in filtration media and sensor hardware. The vendor base separates into three distinct strata: multinational building automation conglomerates with bundled climate control portfolios, dedicated HVAC OEMs with deep mechanical integration capabilities, and emerging diagnostic specialists with cloud-native monitoring platforms. Consolidation pressure is intensifying as facility managers demand single-source accountability for compliance documentation. Strategic moves center on backward integration into sensor manufacturing and geographic expansion through certified contractor networks.
Among diversified technology conglomerates, Honeywell International Inc. and Johnson Controls occupy positions that exemplify platform-centric bundling of air quality monitoring with broader building management systems. Trane Technologies anchors the mechanical-system-native archetype, representing the competitive vector where HVAC integration depth substitutes for standalone software sophistication. These three entities collectively illustrate how technical credibility migrates toward either data platform dominance or energy-recovery ventilation expertise.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Trane Technologies |
| Johnson Controls |
| Daikin Industries |
| Carrier |
| Camfil |
| Emerson Electric |
| Thermo Fisher Scientific |
| Lennox International |
| Others |
Pricing and Supply Chain Analysis
East Asian filter media concentration exposes service contractors to tariff volatility that simultaneously compresses economy-tier margins and accelerates premium-tier certification investments. This supply chokepoint forces pricing stratification across three levels: commodity replacement cycles, integrated monitoring subscriptions, and bespoke remediation engagements with embedded compliance documentation.
Pricing Analysis
ASHRAE Standard 62.1 revisions dictate the pricing tier structure across the Indoor Air Quality Service Market. Three-tier pricing separates certified industrial hygienist engagements from standard maintenance contracts and economy sensor deployments. Price differentiation rests on technician certification grade and volume scale, with district-wide school procurements commanding volume discounts absent in one-off healthcare assessments. Cost compression in consumer-grade sensor hardware is intensifying because photoelectric particulate detectors now retail below fifty dollars per node. Facility managers in K-12 districts exhibit highest price sensitivity; hospital environmental services directors show least sensitivity due to Joint Commission liability exposure.
Supply Chain Analysis
Contract manufacturing for IoT sensor nodes concentrates with Foxconn, Pegatron, and Jabil in Greater China and Southeast Asia assembly corridors. High-efficiency filter media production draws from South Korea, Japan, and coastal Chinese manufacturing zones. Raw material dependencies include borosilicate microfibers, activated carbon substrates, and MEMS gas detection chips. Single-source vulnerability concentrates in East Asian logistics chokepoints subject to shipping volatility. Distribution runs through certified contractor networks that anchor national service provider expansion strategies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Indoor Air Quality Service Market faces substitution pressure from building automation conglomerates bundling monitoring into climate control platforms. Incumbents must defend against disintermediation as facility managers bypass traditional HVAC relationships.
For Market Incumbents: Entrench platform stickiness through backward integration into sensor manufacturing and exclusive data platform access. Consolidate certified contractor networks in Midwest and Northeast school districts where federal infrastructure grants concentrate procurement. The bundled building automation threat demands vertical integration into cloud-native monitoring infrastructure. For New Entrants and Emerging Players: Build out white-space presence in Class B commercial office retrofit cycles triggered by ASHRAE 62.1 enforcement. Target underpenetrated secondary metropolitan markets where certified industrial hygienist scarcity inflates incumbent delivery costs. A district-wide sensor deployment capability with automated state reporting offers the sharpest go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-integrated specialists over pure-play testing firms. Long-term viability hinges on recurring revenue density rather than transactional project volume. Acquisition targets should demonstrate embedded compliance documentation workflows for healthcare and education verticals. Watch sensor hardware cost trajectories as the inflection signal; sub-thirty-dollar nodes would collapse assessment margins and accelerate subscription model adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Hardware Backward Integration | In-house MEMS production insulates margins from East Asian tariff exposure and supply volatility. |
| Cloud-Native Platform Development | Recurring SaaS revenue displaces episodic testing contracts in facility manager procurement cycles. |
| Certified Contractor Network Expansion | Geographic density in grant-heavy K-12 districts captures federal infrastructure allocation flows. |
| Healthcare Accreditation Partnership | Joint Commission audit trail integration locks in hospital system multi-year agreements. |
| LEED/WELL Certification Bundling | Green building compliance pathways expand service scope beyond standalone air quality metrics. |
Research Methodology
Cross-validation between facility manager interviews and regulatory filing analysis anchors the qualitative findings. Primary fieldwork engaged HVAC service directors, school district procurement officers, hospital environmental services leads, and industrial hygienist practitioners. Secondary sources included EPA enforcement databases, ASHRAE guideline documentation, OSHA workplace exposure records, and federal school infrastructure grant disbursement reports. Bottom-up service provider revenue estimates triangulated against top-down building stock penetration models.
Calibration against historical ASHRAE adoption curves and pandemic-era ventilation mandate implementation timelines shaped the projection framework. Segmentation modeling spanned service type, technology deployment, building application, and end-user procurement authority. CAGRs derived from elasticity-adjusted replacement cycle compression and sensor cost decline trajectories. Industry-specific inputs incorporated filter media shipping volatility indices and certified technician wage premium spreads across metropolitan markets.
The forecast holds incumbent behavior within observed patterns; aggressive platform bundling moves by building automation conglomerates would shift outcomes beyond modeled ranges. Quarterly review of federal school infrastructure grant allocation rates and ASHRAE standard revision timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
North America Emission Monitoring System Market
Environmental Monitoring
Global Environmental Remediation Market
Environmental Monitoring
Quality Monitoring Sensor for Water Market
Environmental Monitoring
Latin America Cloud Seeding Market
Environmental Monitoring
Carbon Monoxide Analyzers Market
Environmental Monitoring
Water Quality Analyzer Market
Environmental Monitoring
Cloud Seeding System Market
Environmental Monitoring
Asia-Pacific Food and Environment Manual Testing Market
Environmental Monitoring
Radon Gas Test Kits Market
Environmental Monitoring
Weather Modification Equipment Market
Environmental Monitoring
Asia-Pacific Cloud Seeding Market
Environmental Monitoring
Asia Pacific Air Quality Monitoring Market
Environmental Monitoring
Water Testing Market
Environmental Monitoring
Environmental Radiation Monitor Market
Environmental Monitoring
Smart Water Monitoring Market
Environmental Monitoring
Environmental Test Equipment Market