
 Asia-Pacific Indoor Air Purification Market | 2026-2036
Asia-Pacific Indoor Air Purification Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Indoor Air Purification Market Outlook
China's GB/T 18883 indoor air quality standard is hardening enforcement timelines for commercial buildings, compelling facility managers to upgrade legacy HVAC systems. Daikin Industries leverages its captive refrigeration technology to integrate purification into climate-control packages across East Asian markets. Panasonic anchors its position through photocatalytic oxidation R&D pipelines concentrated in Japanese and Australian operations. Xiaomi competes on channel density, using direct-to-consumer platforms to displace traditional appliance retail in India and Indonesia.
Asia-Pacific indoor air purification encompasses electromechanical systems designed to remove particulate matter, volatile organic compounds, and biological contaminants from enclosed environments, typically achieving CADR ratings between 200-600 cubic meters per hour for residential units. HEPA filtration dominates installed base value due to established efficacy against PM2.5, the primary pollutant across Chinese and Indian urban centers. Activated carbon filters command premium placement in commercial and healthcare settings where formaldehyde and benzene abatement carries regulatory weight. UV light purifiers represent the fastest-growing product category as hospitals in Thailand and Vietnam adopt upper-room germicidal irradiation protocols.
China's SAMR enforces GB standards compliance through market surveillance campaigns that delist non-conforming products from e-commerce channels. India's BIS mandates ISI marking for electronic air purifiers sold domestically, creating a two-year lag for uncertified imports. Japan's METI promotes JIS-standard energy efficiency labeling that shapes procurement criteria for municipal buildings. Stakeholders must monitor divergence between national certification regimes and the interoperability demands of multinational facility operators expanding across ASEAN markets.
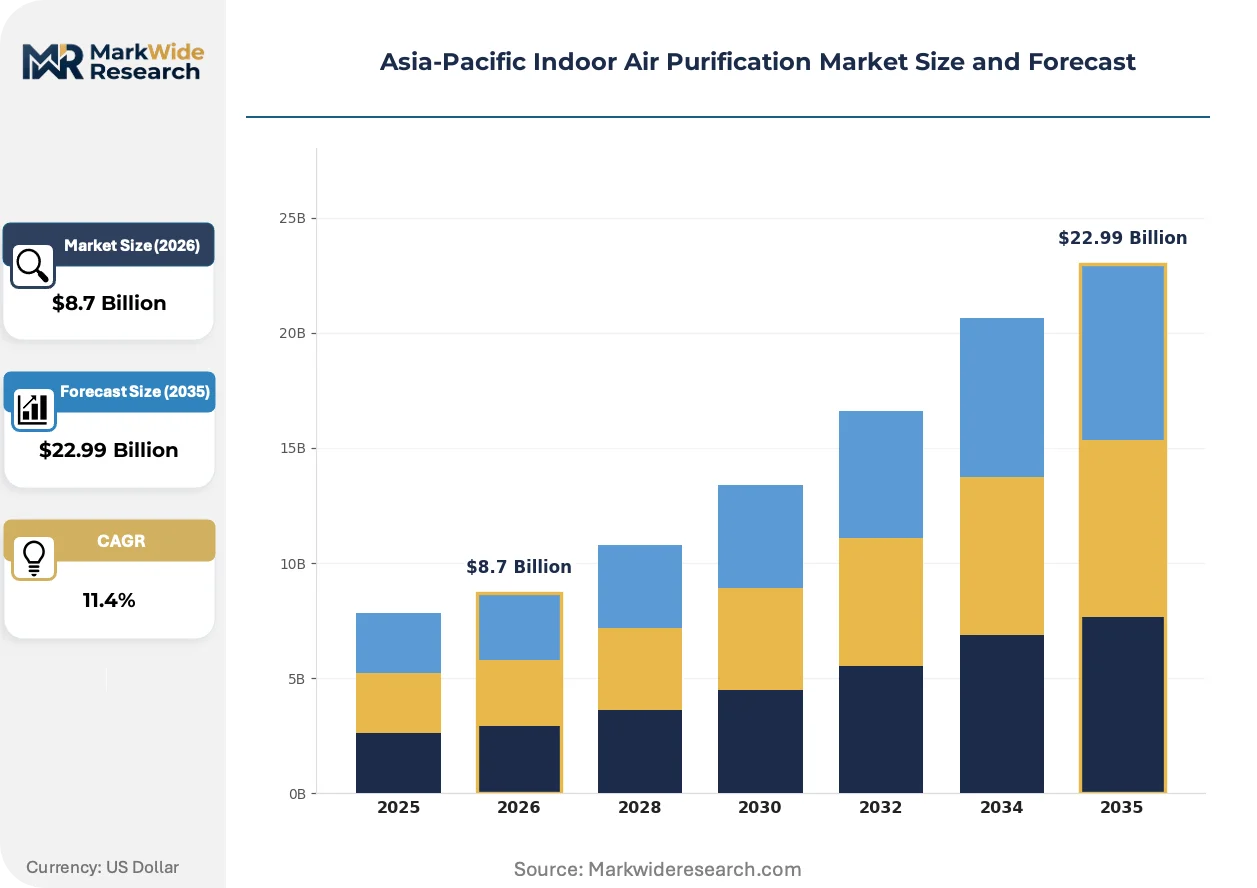
Market Dynamics
China's SAMR market surveillance campaigns are systematically delisting non-conforming air purifiers from e-commerce channels, forcing manufacturers to accelerate GB standards compliance investments ahead of hardening enforcement timelines across commercial building portfolios.
Growth Catalysts
- Healthcare Infrastructure Expansion:Hospitals in Thailand and Vietnam are adopting upper-room germicidal irradiation protocols, creating institutional demand for UV light purification systems.
- Commercial Real Estate Specification:Developers in China's tier-one cities and India's National Capital Region now mandate built-in purification systems as standard amenity packages.
- India's BIS Certification Mandate:ISI marking requirements for electronic air purifiers are filtering out uncertified imports and consolidating domestic manufacturing capacity.
Market Restraints
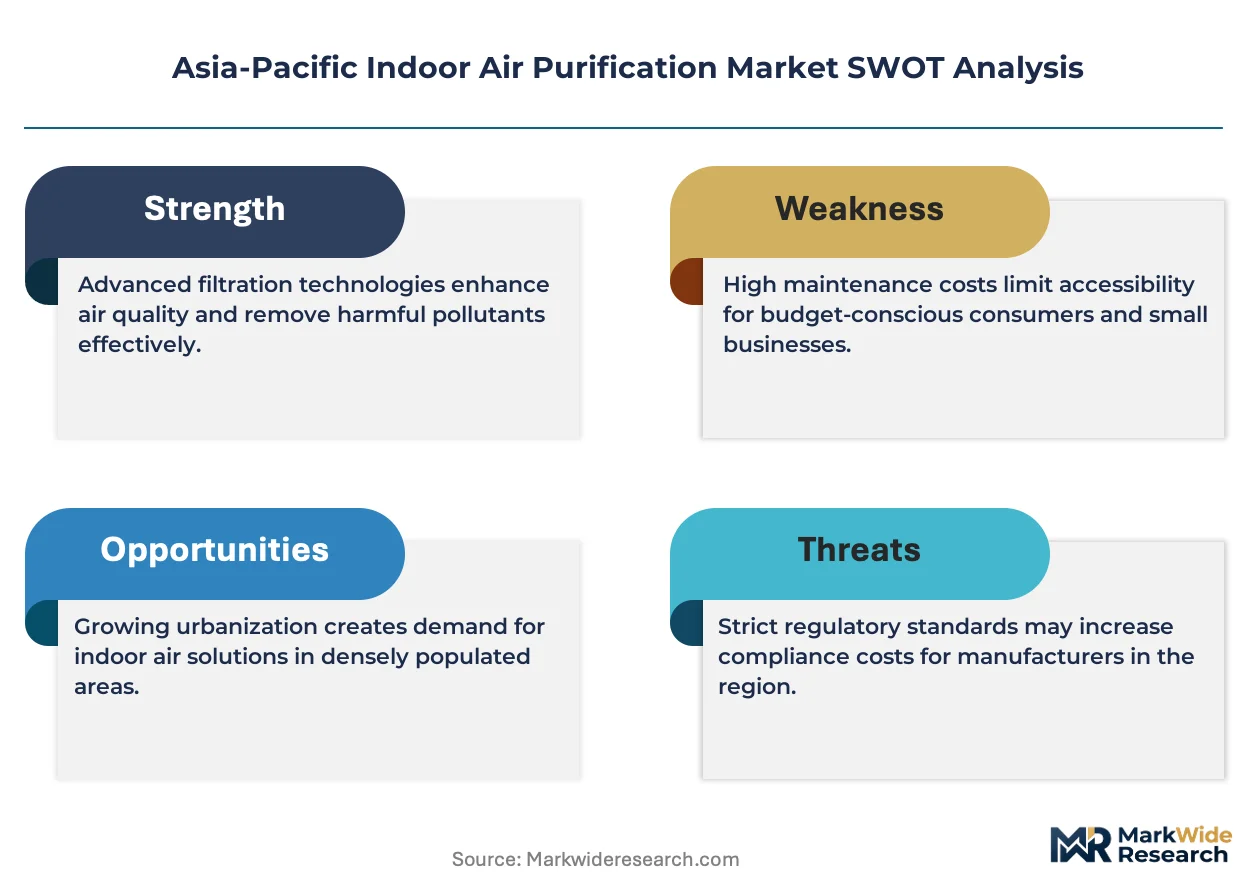
- Filter Replacement Cost Burden:HEPA and activated carbon consumables impose recurring operational expenses that compress adoption in price-sensitive residential segments.
- Certification Timeline Friction:India's two-year BIS compliance lag for uncertified imports delays market entry and ties up working capital for foreign manufacturers.
- Technical Efficacy Ceiling:CADR ratings plateau between 200-600 cubic meters per hour for residential units, limiting performance differentiation in crowded product tiers.
Strategic Opportunities
- Photocatalytic Oxidation Convergence:Integration of photocatalytic materials with HVAC climate-control packages opens premium positioning in Japanese and Australian commercial markets.
- Direct-to-Consumer Channel Penetration:Platform-based distribution models are compressing traditional appliance retail margins in Indonesia's archipelago markets.
- ASEAN Interoperability Gap:Divergence between national certification regimes creates white space for modular purification systems designed to multinational facility operator specifications.
Industry Challenges
- HVAC Retrofit Integration Complexity:Facility managers in aging Chinese commercial buildings face structural constraints when upgrading legacy climate systems to accommodate medical-grade purification.
- Photocatalytic Talent Scarcity:R&D pipelines for advanced oxidation technologies require specialized material science expertise concentrated in Japanese research clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Indoor Air Purification Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filters, Activated Carbon Filters, UV Light Purifiers, Ionizers End User: Residential, Commercial, Healthcare Facilities, Educational Institutions Technology: Filtration, Electrostatic Precipitation, Photocatalytic Oxidation, Ozone Generation Application: Dust Removal, VOC Reduction, Odor Control, Allergy Relief |
| Companies Covered | Daikin Industries Ltd, Koninklijke Philips NV, LG Electronics Inc., Panasonic Corporation, Dyson Ltd, Xiaomi Corporation, Honeywell International Inc., Sharp Corporation, IQAir, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Indoor Air Purification Market Strategic Shifts
Photocatalytic oxidation systems are converging with climate-control infrastructure, while regulatory enforcement hardens compliance thresholds and procurement patterns fragment across platform-based and traditional channels.
Photocatalytic oxidation technology employs titanium dioxide catalysts activated by UV light to decompose volatile organic compounds at the molecular level. Hospital procurement departments in Thailand are piloting these systems for formaldehyde abatement in surgical suites. This performance tier is overtaking activated carbon filtration in premium healthcare specifications where benzene and formaldehyde compliance carries regulatory weight.
China's GB/T 18883 indoor air quality standard is tightening particulate matter thresholds for commercial buildings through SAMR enforcement campaigns. Facility managers must document HVAC upgrade timelines or face operational restrictions. Medical-grade purification specifications in Beijing and Shanghai commercial towers are responding with integrated electromechanical systems rather than standalone portable units.
Platform-based distribution models are compressing traditional appliance retail networks across Southeast Asian markets. Xiaomi's direct-to-consumer infrastructure in Indonesia reaches secondary cities that lack dedicated electronics retail presence. This channel rotation is most visible in India's tier-two urban clusters where smartphone penetration enables specification comparison and price transparency ahead of purchase decisions.
Asia-Pacific Indoor Air Purification Market Segmentation
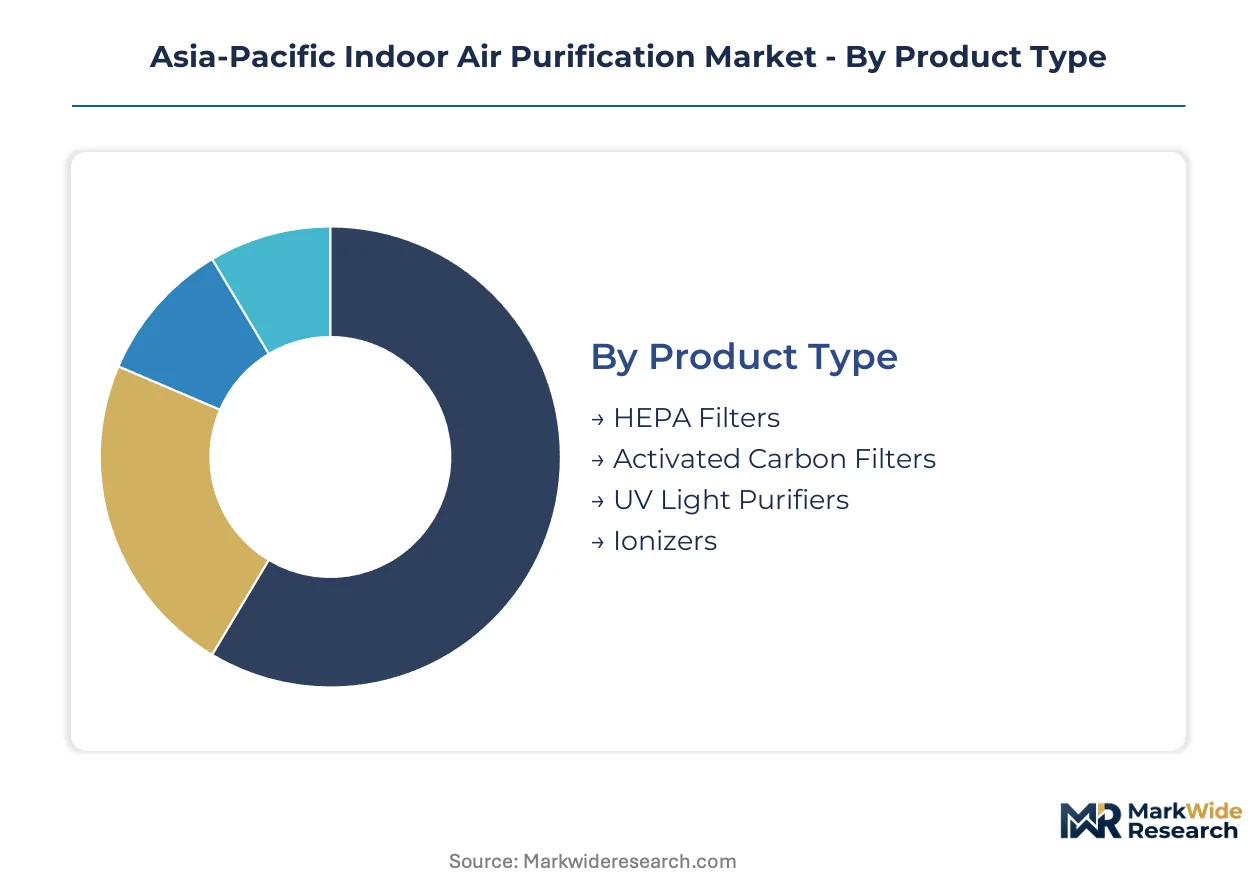
Asia-Pacific indoor air purification segments fracture across technical performance tiers, regulatory compliance thresholds, and buyer procurement sophistication. Manufacturers must align R&D pipelines and certification strategies to the divergent specifications of residential consumers, healthcare procurement departments, and commercial facility managers.
Product Type:
Buyers in this category differentiate primarily by contaminant removal efficacy against specific pollutant profiles prevalent across Chinese and Indian urban centers.
- HEPA Filters:High-efficiency particulate air media constructed from interlaced glass fibers capture 99.97% of particles 0.3 microns and larger. Demand concentrates in Beijing and Delhi residential towers where PM2.5 levels drive replacement cycles. China's SAMR enforcement of GB standards hardens performance documentation requirements for commercial specifications.
- Activated Carbon Filters:Porous carbon substrates adsorb formaldehyde, benzene, and volatile organic compounds through physisorption mechanisms. Procurement in Thailand and Vietnam healthcare facilities prioritizes these units for surgical suite air quality compliance. Filter replacement logistics create recurring revenue concentration for aftermarket suppliers.
- UV Light Purifiers:Germicidal irradiation at 254 nanometers deactivates airborne pathogens. Upper-room installations in Bangkok and Ho Chi Minh City hospitals follow WHO tuberculosis control guidelines.
- Ionizers:Corona discharge generates charged particles that agglomerate contaminants for collection. Smaller footprint drives adoption in Tokyo and Osaka compact residential units.
Volume sits with HEPA filtration; growth tilts toward UV light systems.
End User:
Procurement sophistication escalates from individual consumer decision-making to institutional tender processes with documented compliance requirements.
- Residential:Individual purchasers prioritize CADR-per-watt efficiency and filter replacement cost transparency. China's tier-one cities and India's National Capital Region concentrate unit shipments through platform-based channels.
- Commercial:Facility managers in Shanghai and Mumbai commercial towers specify built-in HVAC integration. GB/T 18883 enforcement timelines accelerate upgrade cycles.
- Healthcare Facilities:Infection control departments mandate medical-grade specifications with bacterial removal documentation. Thai and Vietnamese hospital construction pipelines anchor institutional demand.
- Educational Institutions:Municipal procurement in Japan and South Korea prioritizes energy efficiency labeling under METI and KEMCO frameworks. Classroom density specifications drive unit sizing decisions.
Commercial installations generate the highest per-unit value; healthcare facilities are expanding most quickly.
Technology:
Intellectual property concentration and material science expertise determine competitive positioning across performance tiers.
- Filtration:Mechanical particle capture through fibrous or membrane media dominates installed base value. HEPA and activated carbon configurations anchor this category.
- Electrostatic Precipitation:Charged collection plates remove particulate without pressure-drop penalties. Industrial applications in Chinese manufacturing zones favor washable components.
- Photocatalytic Oxidation:Titanium dioxide catalysts activated by UV light mineralize organic pollutants at the molecular level. Japanese and Australian R&D clusters concentrate patent filings.
- Ozone Generation:Reactive oxygen species oxidize contaminants in unoccupied spaces. Commercial remediation in Australian and New Zealand facilities follows occupational exposure limits.
Filtration commands current volume; photocatalytic oxidation claims the steepest expansion trajectory.
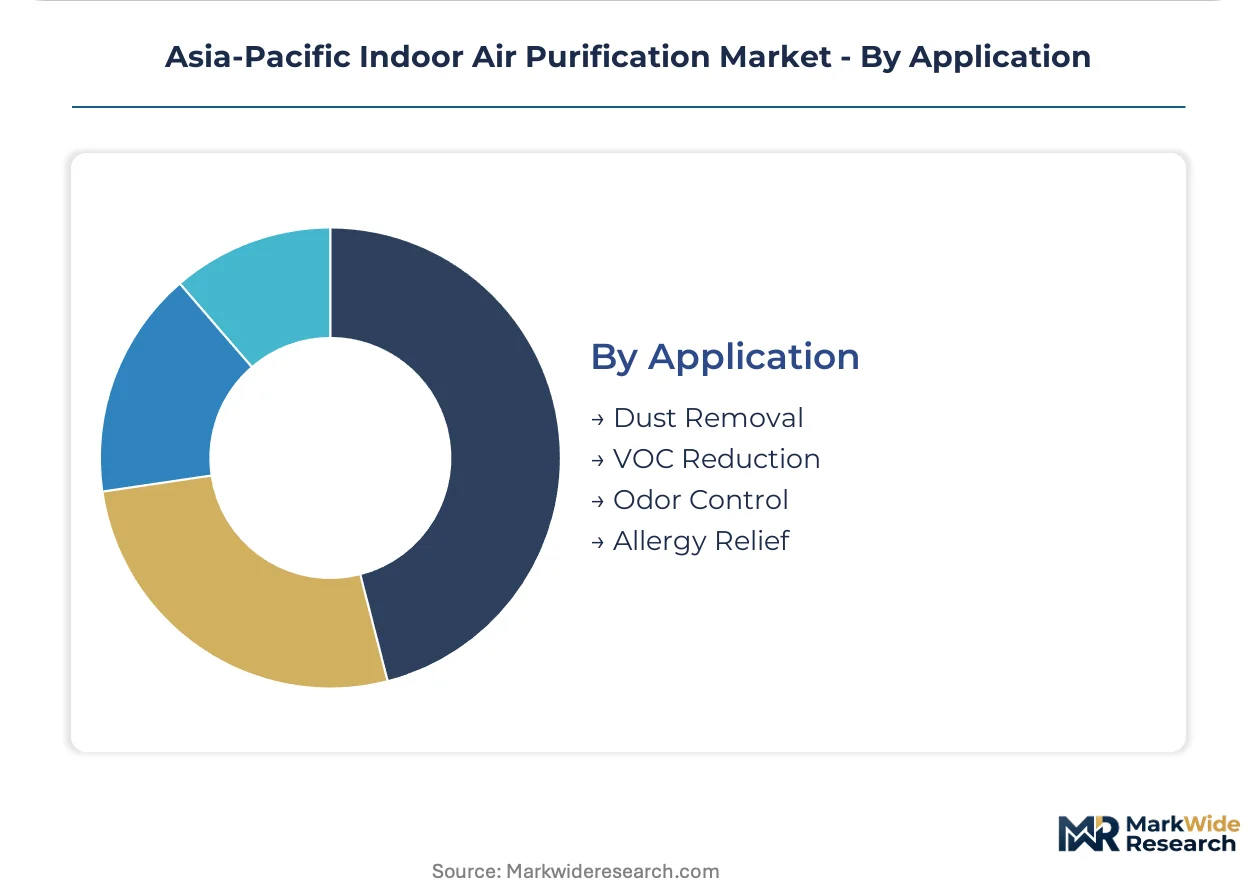
Application:
Specific contaminant targets shape filter media selection and system architecture decisions.
- Dust Removal:Particulate filtration for PM2.5 and PM10 dominates residential specifications across Chinese and Indian markets.
- VOC Reduction:Formaldehyde and benzene abatement drives activated carbon and photocatalytic specifications in healthcare and commercial new construction.
- Odor Control:Adsorption and oxidation technologies address hospitality and food service environments in Southeast Asian urban centers.
- Allergy Relief:HEPA configurations targeting pollen and pet dander serve Japanese and Australian consumer segments with high atopic sensitivity prevalence.
Dust removal anchors shipment volumes; VOC reduction specifications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates manufacturing capacity for filtration media and electromechanical components, while consumption clusters in polluted urban corridors across East and South Asia. Japan and South Korea import Chinese-made HEPA substrates for domestic assembly of premium units. Southeast Asian markets rely on imported finished goods, with local distribution networks controlling channel access.
China
Beijing and Shanghai commercial towers drive demand for medical-grade HVAC-integrated systems as facility managers respond to SAMR enforcement of GB/T 18883 particulate thresholds. The MIIT promotes domestic filter media production through industrial clustering in Jiangsu and Zhejiang provinces. Daikin Industries leverages captive refrigeration technology to bundle purification into climate-control packages across East Asian markets.
India
Delhi-NCR residential towers and Mumbai commercial developments anchor unit shipments as BIS ISI marking requirements filter out uncertified imports. The two-year certification lag for foreign manufacturers consolidates domestic assembly capacity in Tamil Nadu and Karnataka. Xiaomi deploys direct-to-consumer platforms to displace traditional appliance retail in tier-two urban clusters.
Japan
Tokyo and Osaka compact residential units favor ionizer configurations with smaller footprints suited to dense urban housing. METI's JIS-standard energy efficiency labeling shapes procurement criteria for municipal building tenders. Panasonic anchors market position through photocatalytic oxidation R&D pipelines concentrated in domestic and Australian operations.
South Korea
Seoul Capital Area educational institutions drive institutional demand under KEMCO energy efficiency frameworks for classroom density specifications. The country's national environmental regulator enforces indoor air quality standards that accelerate replacement cycles in aging school infrastructure. Busan-Ulsan industrial zones generate secondary demand for electrostatic precipitation units in manufacturing facilities.
Thailand
Bangkok hospital construction pipelines anchor institutional demand for UV light upper-room germicidal irradiation systems following WHO tuberculosis control protocols. The Ministry of Public Health mandates formaldehyde abatement specifications in new surgical suite construction. Healthcare procurement departments in Ho Chi Minh City and Hanoi mirror these protocols, creating cross-border demand clustering in the Greater Mekong sub-region.
Asia-Pacific Indoor Air Purification Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with captive climate-control technology. Japanese and Korean electronics groups dominate premium tiers through integrated HVAC-purification bundles, while Chinese platform companies compress margins in mass-market residential segments. Three archetypes define positioning: refrigeration-integrated system suppliers, direct-to-consumer platform operators, and specialized healthcare filtration vendors. Capacity expansion and certification compliance investments constitute the dominant competitive moves as national regulators harden market entry barriers.
Among Japanese diversified manufacturers, Panasonic Corporation and Sharp Corporation exemplify the refrigeration-integrated archetype, leveraging domestic material science expertise for photocatalytic oxidation development. Daikin Industries Ltd anchors the climate-control bundling strategy across East Asian commercial markets. Xiaomi Corporation represents the platform-native challenger, using smartphone ecosystem penetration to bypass traditional appliance retail in Southeast Asian archipelago markets. These three players illustrate the divergence between premium integrated systems and mass-market channel disruption.
| Leading Market Players |
|---|
| Daikin Industries Ltd |
| Koninklijke Philips NV |
| LG Electronics Inc. |
| Panasonic Corporation |
| Dyson Ltd |
| Xiaomi Corporation |
| Honeywell International Inc. |
| Sharp Corporation |
| IQAir |
| Others |
Value Chain & Pricing Dynamics
Material science expertise concentrated in Japanese research clusters widens labor-cost differentials between premium photocatalytic oxidation systems and mass-market filtration units, compressing mid-tier pricing spreads across the Asia-Pacific region.
Pricing Analysis
Margin tightening in residential tiers reflects Xiaomi's direct-to-consumer platform compression against traditional appliance retail networks. Three-tier pricing structure across premium HVAC-integrated, standard standalone HEPA, and economy ionizer levels separates buyers by certification grade and after-sales bundling intensity. Cost-down pressure on activated carbon configurations accelerates because India's BIS ISI marking mandates extend compliance timelines for import-dependent suppliers. Healthcare procurement departments exhibit the least price sensitivity, while tier-two residential consumers in Indonesia and Vietnam drive aggressive specification comparison.
Supply Chain Analysis
India's phased domestic-content requirements for BIS-certified assembly are reshaping sourcing patterns away from finished-goods import dependence toward Tamil Nadu and Karnataka manufacturing clusters. Filter media production concentrates in China's Jiangsu and Zhejiang provinces, while Japanese and Korean manufacturers draw from Chinese HEPA substrates for domestic premium assembly. Supply chain risk centers on single-source vulnerability for titanium dioxide catalysts feeding photocatalytic oxidation R&D pipelines. Distribution runs through platform-based direct-to-consumer channels in archipelago markets alongside traditional HVAC contractor networks in commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over filter media production and refrigerant-compatible system architecture determines margin sustainability against platform-native challengers.
For Market Incumbents: Hedge against Xiaomi's channel disruption by securing exclusive HVAC contractor relationships in China's tier-one commercial towers and accelerating GB/T 18883 pre-certification for integrated climate-control bundles. Daikin Industries exemplifies this defensive posture through captive refrigeration technology leverage. Prioritize backward integration into activated carbon substrate production to offset India's two-year BIS compliance lag for imported components.
For New Entrants and Emerging Players: E-commerce platform operators in Indonesia's secondary cities represent the most penetrable channel white space, bypassing electronics retail infrastructure gaps that constrain incumbent reach. Target UV light upper-room germicidal systems for Thai and Vietnamese hospital construction pipelines where WHO tuberculosis protocols create specification demand without entrenched supplier relationships. Pursue modular certification strategies that bridge China's GB standards with India's BIS requirements for ASEAN interoperability.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized healthcare filtration vendors given Thailand's Ministry of Public Health formaldehyde abatement mandates and Vietnam's parallel surgical suite specifications. Long-term viability hinges on R&D pipelines converging photocatalytic oxidation with climate-control infrastructure rather than standalone unit commoditization. Monitor BIS certification timeline compression as the inflection signal for domestic manufacturing capacity consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Media | Captive HEPA substrate production insulates against China's SAMR enforcement-driven supply disruptions. |
| Photocatalytic Oxidation R&D Expansion | Japanese material science clusters anchor patent concentration for VOC mineralization in healthcare specifications. |
| Platform-Based Distribution Buildout | Direct-to-consumer infrastructure in Indonesia and India compresses traditional appliance retail margins. |
| BIS Certification Pre-Investment | Early ISI marking compliance avoids India's two-year import lag and consolidates domestic assembly positioning. |
| HVAC Integration Partnership | Climate-control bundling with Daikin-style refrigeration technology locks in commercial real estate specification demand. |
Study Parameters
Multi-period observation of CADR rating trajectories, filter replacement cycle frequencies, and certification timeline divergences anchored the trend analysis, supplemented by interviews with facility managers in Shanghai and Mumbai commercial towers, hospital infection control departments in Bangkok and Ho Chi Minh City, and procurement leads at Indian BIS-registered assembly operations. Secondary validation drew from China's SAMR market surveillance disclosure databases, India's BIS product registration records, Japan's METI energy efficiency labeling archives, and Thailand Ministry of Public Health surgical suite construction tenders. Bottom-up shipment estimates triangulated against top-down healthcare infrastructure investment flows.
Segment-weighting across product type, end user, technology, and application dimensions shaped the analytical framework throughout the projection horizon. CAGRs derived from installed base replacement cycles, regulatory enforcement phase-in schedules, and platform penetration trajectories in archipelago markets. Industry-specific forecast inputs incorporated GB/T 18883 particulate threshold tightening timelines and WHO tuberculosis control protocol adoption rates across Southeast Asian hospital systems.
Several conditions sit outside the modeled scope, including potential harmonization between China's GB standards and India's BIS regimes, breakthrough advances in non-filtration purification modalities, and macroeconomic disruptions to commercial real estate development pipelines. Forecasts reflect assumptions documented in primary stakeholder interviews and secondary regulatory filings. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Global Mist Eliminator Market
Air Quality Control Systems
Indoor Air Purification Market
Air Quality Control Systems
Ozone Generation Market
Air Quality Control Systems
Desiccant Air Breather Market
Air Quality Control Systems
North America Industrial Air Quality Control Systems Market
Air Quality Control Systems
United States Pollution Mask Market
Air Quality Control Systems
Sustainable Air Filter Market
Air Quality Control Systems
Green Emissions Analyzers Market
Air Quality Control Systems
Asia Pacific Air Filtration Market
Air Quality Control Systems
Air Quality Control Systems Market
Air Quality Control Systems
Asia-Pacific Air Quality Control System Market
Air Quality Control Systems
Europe Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Anti-Pollution Mask Market
Air Quality Control Systems
Environment Controllers Market
Air Quality Control Systems
Southeast Asia Air Purifier Market
Air Quality Control Systems
Ozone Analyzer Market