
 Environment Controllers Market | 2026-2036
Environment Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Environment Controllers Market Foresight
Modular sensor-controller bundles is decoupling hardware procurement from installation services, giving facility managers flexibility to upgrade components without full system replacement. Daikin Industries leverages its captive compressor manufacturing to bundle climate controllers with refrigeration hardware. Honeywell International anchors its position through building management software that locks in controller ecosystems. Johnson Controls competes by extending service contracts that embed controller refresh cycles.
Environment controllers are electromechanical or digital devices that regulate temperature, humidity, air quality, and ventilation parameters through sensor feedback loops and actuator commands, typically operating within 0.1°C precision for critical applications. Their primary purpose is maintaining defined environmental setpoints to protect equipment, preserve biological materials, or ensure occupant comfort and safety. Smart Control technology leads the technology dimension as IoT-enabled predictive algorithms reduce energy waste in commercial buildings. Agricultural application represents the fastest-growing segment as greenhouse operators deploy precision humidistat networks to optimize crop yields. Thermostats remain the most mature product category with compressed margins, while air quality monitors command premium pricing amid post-pandemic indoor air mandates.
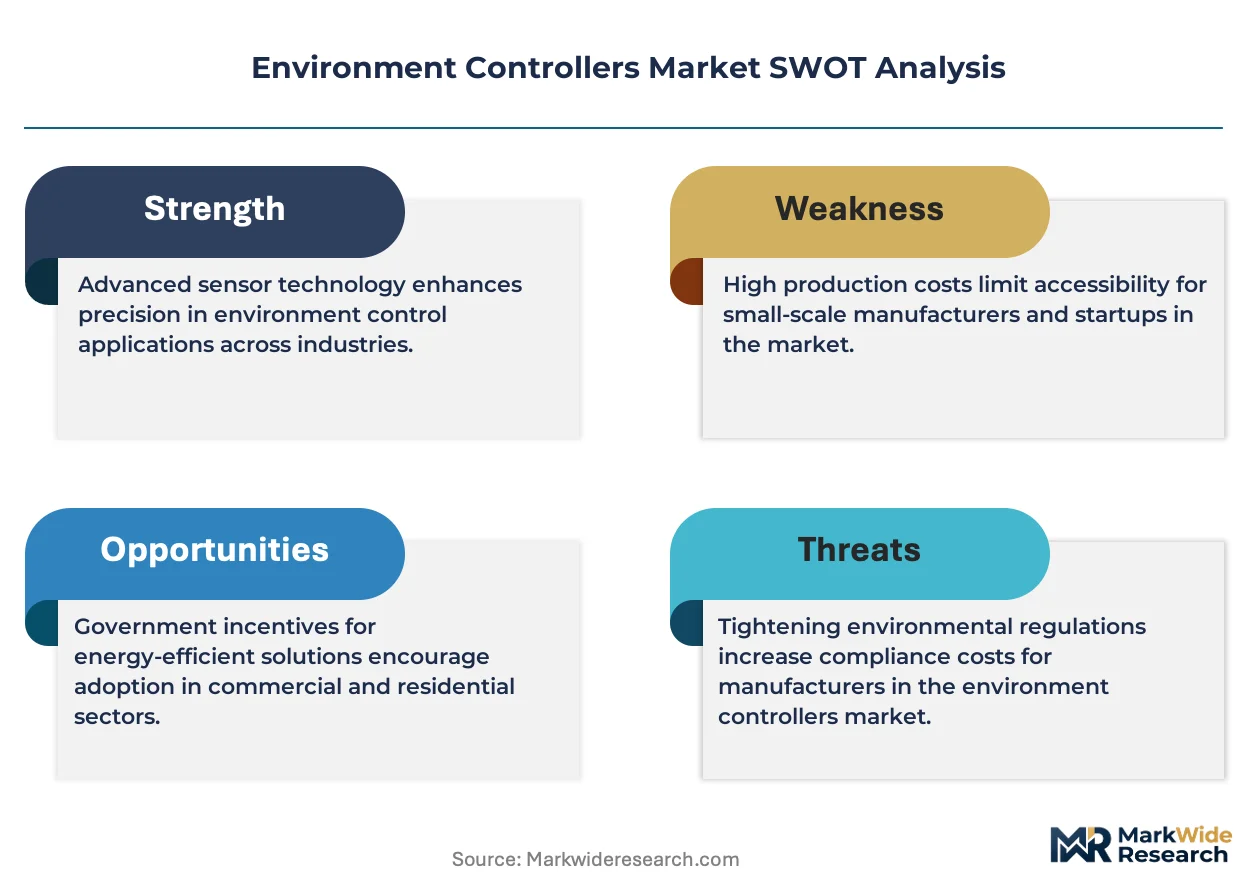
EPA regulations under the Clean Air Act and ENERGY STAR certification requirements shape product standards by mandating minimum efficiency thresholds and emissions reporting capabilities for installed controller systems. The EU Green Deal and F-Gas Regulation are accelerating demand for controllers compatible with low-global-warming-potential refrigerant transitions across European commercial refrigeration. Stakeholders must monitor how building electrification mandates in multiple jurisdictions redefine controller interoperability standards and procurement specifications.
Market Dynamics
Building electrification mandates across multiple jurisdictions are forcing wholesale replacement of gas-fired heating controllers with electric heat pump-compatible systems, compressing replacement cycles from fifteen years to under eight.
Growth Catalysts
- Clean Air Act amendments:EPA mandates for integrated air quality reporting in commercial facilities above 25,000 square feet require sensor-controller bundles with real-time emissions tracking capabilities.
- Precision agriculture:Greenhouse operators in the Netherlands and Spain deploy networked humidistat arrays to optimize crop yields through sub-degree climate control.
- Smart HVAC retrofits:Building operators replace standalone thermostats with IoT-enabled predictive systems that reduce energy waste through algorithmic load balancing.
Market Restraints
- Semiconductor supply concentration:Controller manufacturers depend on Taiwanese and South Korean foundries for sensor microcontrollers, exposing procurement to geopolitical disruption.
- Copper and rare earth volatility:Actuator motors and magnetic components face input cost swings that compress hardware margins.
- Refrigerant transition friction:EU F-Gas Regulation timelines force premature controller replacement for systems incompatible with low-global-warming-potential alternatives.
Strategic Opportunities
- India building automation:Bureau of Energy Efficiency mandates for commercial cooling load management create first-mover advantage for integrated controller-platform vendors.
- Edge AI convergence:On-device machine learning chips enable predictive maintenance without cloud dependency, opening rural and secure-facility segments.
- Subscription software attach:Controller hardware margins collapse while recurring platform revenue from building analytics software expands addressable spend per installation.
Industry Challenges
- Controls engineering talent scarcity:Facilities management departments lack personnel trained in BACnet and Modbus protocol integration, slowing smart retrofit deployment.
- Multi-protocol certification delays:Products must clear separate compliance paths for UL, CE, and GB standards before market entry, extending launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Environment Controllers Market |
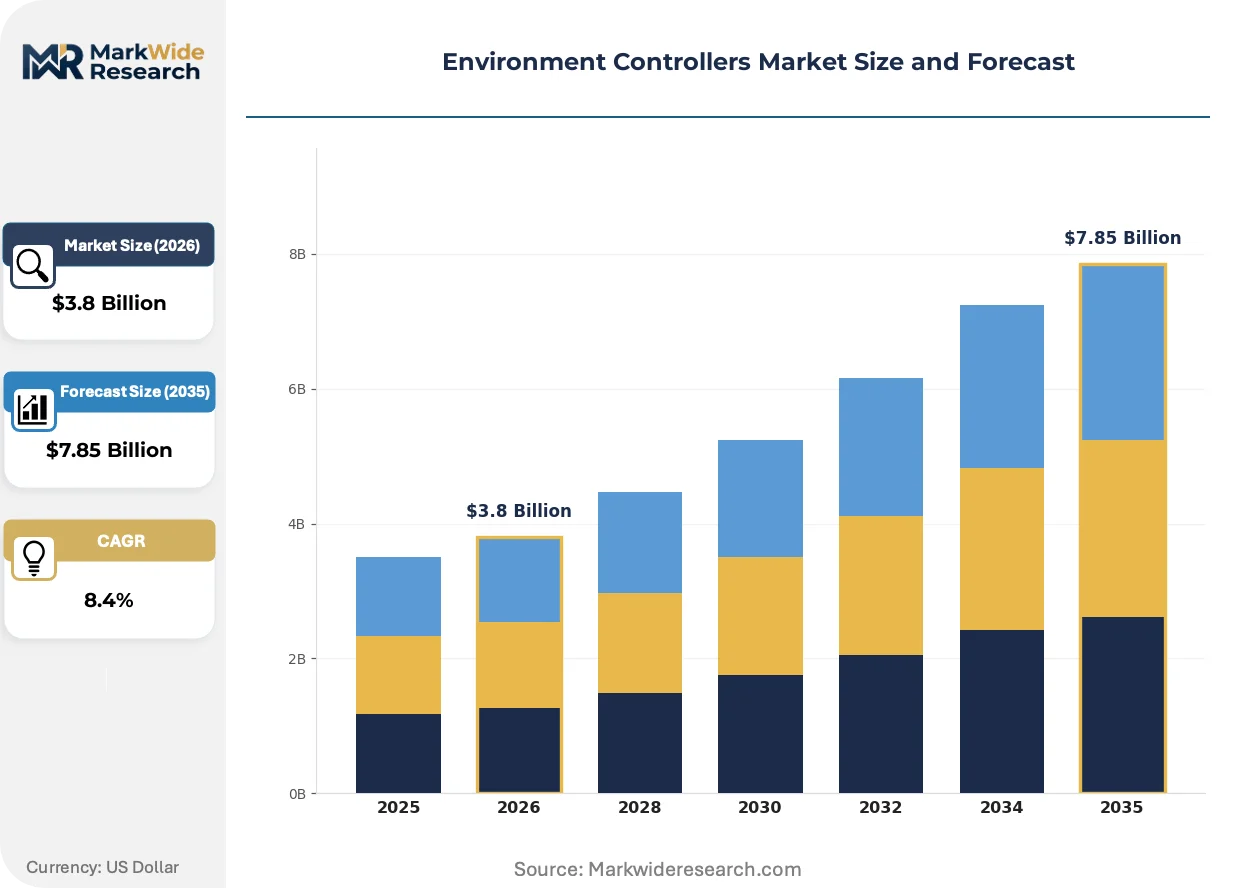
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermostats, Humidistats, Air Quality Monitors, Temperature Sensors Technology: Smart Control, Manual Control, IoT Integration, Wireless Control Application: Residential, Commercial, Industrial, Agricultural End User: Homeowners, Facility Managers, Farmers, Business Owners |
| Companies Covered | Daikin Industries, Trane Technologies, Honeywell International, Collins Aerospace, Carrier Global Corporation, Siemens AG, Johnson Controls, Thermo Fisher Scientific Inc., Liebherr International AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Environment Controllers Market Shifts & Advancements
Digital twin architectures are redefining how environmental parameters are monitored and adjusted, shifting competitive advantage from hardware precision to software prediction accuracy.
Edge-based predictive algorithms are overtaking cloud-dependent controller architectures in commercial building deployments. These systems process sensor data locally to issue actuator commands within milliseconds. Large facility operators in Germany and Japan prioritize latency reduction for critical equipment protection. The shift is compressing demand for always-connected controllers while elevating on-chip AI accelerator specifications.
EU Green Deal implementation timelines are accelerating refrigerant transition roadmaps across European commercial refrigeration. The F-Gas Regulation mandates phasedown of hydrofluorocarbon-based systems by 2030. Controller suppliers must redesign expansion valve drivers and pressure sensors for CO2 and ammonia compatibility. Cold storage operators in France and Italy face forced controller replacement regardless of equipment age.
Outcome-based performance contracts are displacing capital expenditure procurement for large commercial installations. Building owners pay per degree-hour of maintained climate rather than purchasing hardware outright. Energy service companies assume controller refresh and maintenance obligations. This model concentrates fastest in US healthcare and data center verticals where uptime guarantees carry penalty clauses.
Environment Controllers Market Segmentation
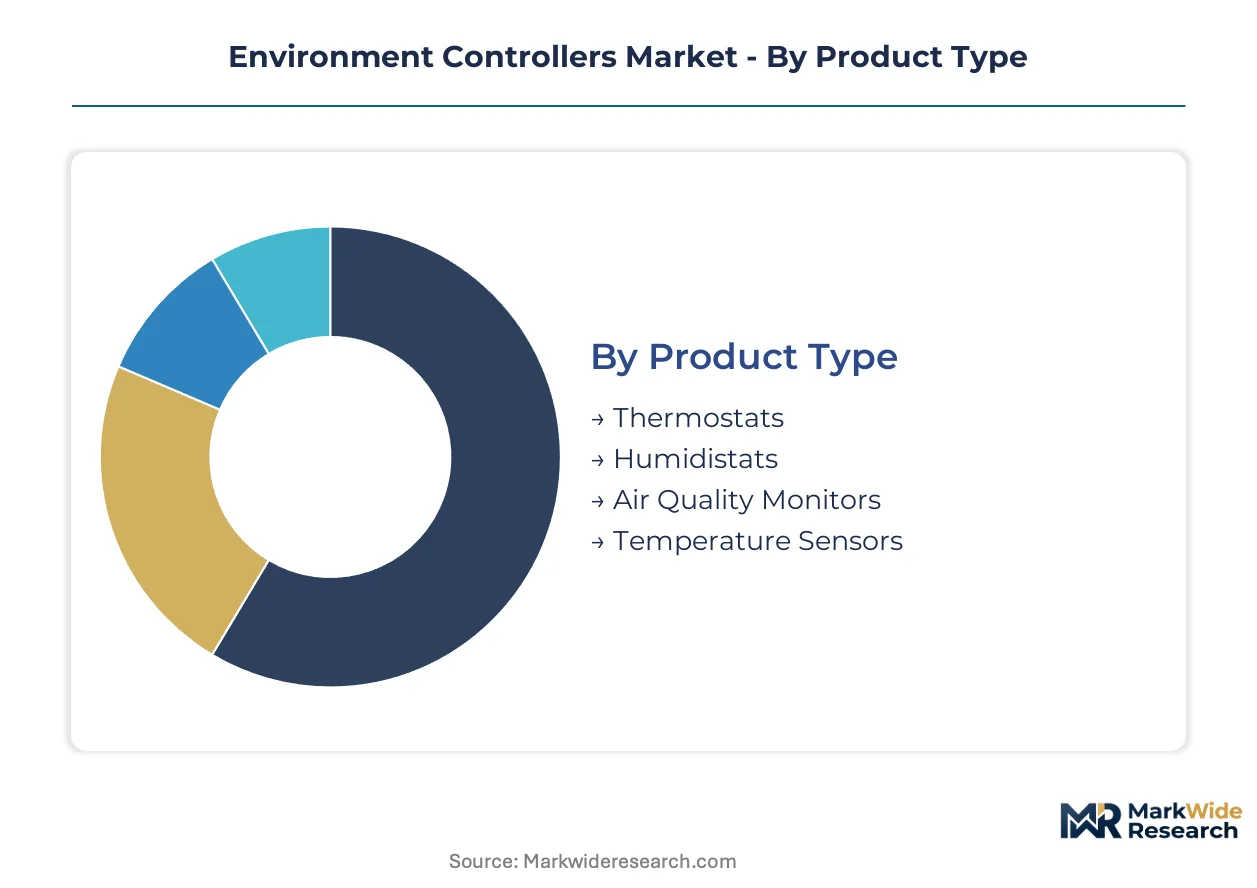
Environment controllers serve distinct operational contexts that demand specification-aligned procurement. Each segment axis reflects different buyer priorities: precision tolerances, connectivity protocols, regulatory compliance thresholds, or lifecycle cost structures.
Product Type:
Thermal regulation hardware differentiates by measurement precision and actuator integration depth.
- Thermostats:Electromechanical or digital temperature regulation devices with setpoint programming and HVAC system command interfaces. Facility managers in US commercial buildings deploy these for ENERGY STAR compliance, though margins compress amid commoditization of basic programmable units.
- Humidistats:Moisture-sensing controllers that activate humidification or dehumidification equipment through relay outputs or digital signals. Dutch and Spanish greenhouse operators drive precision-grade demand as sub-degree humidity control directly correlates with crop yield metrics.
- Air Quality Monitors:Multi-parameter sensors tracking particulates, VOCs, and CO2 concentrations with controller-integrated ventilation triggers.
- Temperature Sensors:Discrete thermal measurement elements providing analog or digital feedback to central control systems.
Mature deployment sits with thermostats. Newer deployment is concentrated in air quality monitors.
Technology:
Control architecture selection determines energy optimization potential and cybersecurity exposure.
- Smart Control:Algorithm-driven systems with predictive load balancing, occupancy sensing, and automated setpoint adjustment. German and Japanese large facility operators prioritize these for millisecond-latency equipment protection and cloud-independent edge processing.
- IoT Integration:Networked controllers with API connectivity to building management platforms and remote monitoring dashboards. US healthcare and data center verticals adopt these under outcome-based performance contracts where uptime guarantees carry financial penalties.
- Manual Control:Direct user-adjustable setpoint interfaces without automated feedback loops.
- Wireless Control:RF or mesh-networked actuators eliminating hardwired infrastructure in retrofit applications.
Established building stock relies on manual control. Wireless control is gaining share fastest in retrofit-heavy markets.
Application:
Environmental risk profiles and regulatory intensity vary sharply across installation contexts.
- Commercial:Integrated HVAC and air quality management in offices, retail, and institutional buildings. EPA Clean Air Act amendments mandate real-time emissions tracking for facilities above 25,000 square feet, forcing sensor-controller bundle upgrades.
- Agricultural:Precision climate systems for greenhouse cultivation and livestock environments. Netherlands operators deploy networked humidistat arrays to optimize yield through sub-degree control, representing the steepest expansion trajectory across application segments.
- Residential:Single-family and multi-unit dwelling climate regulation with occupant comfort prioritization.
- Industrial:Process-critical environmental maintenance for manufacturing, warehousing, and cold storage.
Volume concentration remains in commercial. Agricultural applications show the sharpest growth acceleration.
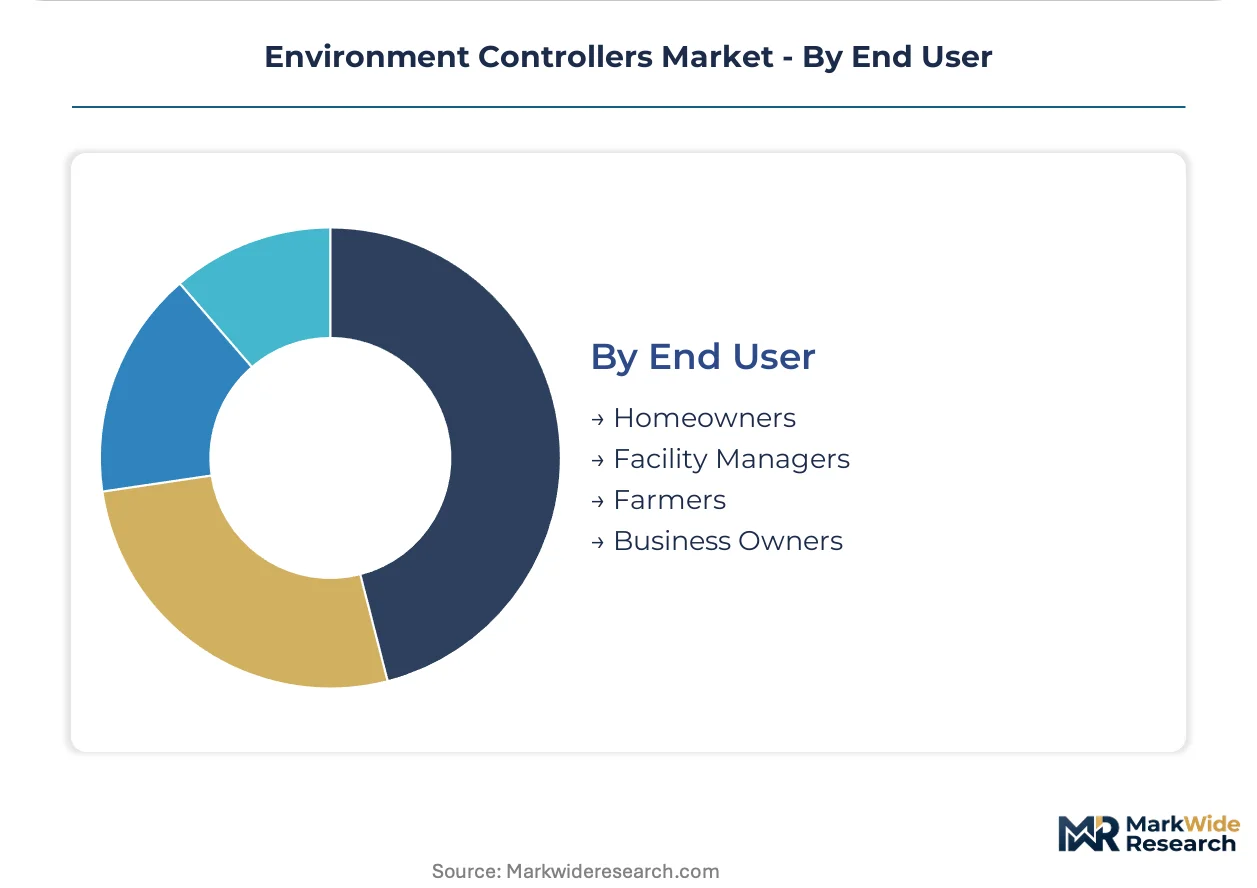
End User:
Procurement authority and technical sophistication shape controller specification requirements.
- Facility Managers:Professional building operations personnel responsible for multi-system integration, regulatory compliance documentation, and energy performance reporting. These buyers prioritize BACnet and Modbus protocol compatibility for centralized management platform integration.
- Farmers:Agricultural operators seeking yield optimization through environmental parameter control. Greenhouse specialists in Spain and the Netherlands invest in precision humidistat networks where climate stability directly affects revenue.
- Homeowners:Individual residential purchasers selecting standalone or smart home-integrated climate control.
- Business Owners:Small commercial proprietors with limited facilities staff making direct procurement decisions.
Facility managers anchor premium segment procurement. Farmers represent the fastest-emerging specification influencer category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in the Yangtze River Delta and Pearl River Delta concentrate controller manufacturing capacity. Shenzhen's Qianhai zone offers 15% corporate tax rates for smart building technology investments. These incentives attract sensor foundries and assembly operations serving domestic and export markets.
China
Greenhouse operators in Shandong Province deploy precision humidistat networks for vegetable cultivation. MIIT mandates IoT interoperability standards under GB/T protocols for building automation systems. Shenzhen and Shanghai host the densest clusters of controller R&D facilities serving Asia-Pacific retrofit demand.
United States
Healthcare facilities in Texas and data centers in Virginia drive demand for millisecond-latency climate protection. EPA Clean Air Act amendments require real-time emissions tracking for commercial buildings exceeding 25,000 square feet. The Dallas-Fort Worth metroplex anchors distribution infrastructure for North American HVAC controller deployment.
Germany
Industrial cold storage operators face forced controller replacement under EU F-Gas Regulation timelines. The EU Green Deal accelerates refrigerant transitions requiring CO2-compatible expansion valve drivers. Bavaria and Baden-Württemberg concentrate precision engineering firms supplying sensor-controller bundles to European markets.
Netherlands
Greenhouse clusters in Westland and Aalsmeer deploy sub-degree humidity control for ornamental flower production. REACH compliance requirements shape material specifications for agricultural controller housings. Wageningen University partnerships drive precision agriculture technology adoption among Dutch growers.
India
Commercial cooling mandates from the Bureau of Energy Efficiency create first-mover opportunities for integrated platform vendors. BIS certification requirements for electronic control devices extend product launch timelines. Maharashtra and Gujarat host the fastest-growing deployment of building automation systems in South Asia.
Environment Controllers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the controller value chain. The market structures into three tiers: captive compressor manufacturers bundling climate hardware, software-anchored building management platforms, and component-focused sensor specialists. Consolidation pressure intensifies as building electrification mandates compress replacement cycles. Dominant competitive moves include backward integration into semiconductor sourcing and strategic partnerships for edge AI chip development.
Among diversified industrial conglomerates, Daikin Industries exemplifies the captive-manufacturing archetype through compressor-controller bundling. Honeywell International occupies a position anchoring building management software ecosystems. Johnson Controls represents the service-embedded refresh model extending controller lifecycle contracts. These three patterns illustrate how scale, software lock-in, and recurring revenue each defend market position against margin compression in hardware.
| Leading Market Players |
|---|
| Daikin Industries |
| Trane Technologies |
| Honeywell International |
| Collins Aerospace |
| Carrier Global Corporation |
| Siemens AG |
| Johnson Controls |
| Thermo Fisher Scientific Inc. |
| Liebherr International AG |
| Others |
Supply & Pricing Matrix
Copper and rare earth volatility in actuator motors traces through controller hardware margins into tiered pricing structures, compressing standard-grade unit economics while premium sensor-controller bundles absorb input swings through software attach revenue.
Pricing Analysis
Margin tightening in standard thermostats reflects commoditization of basic programmable units as smart HVAC retrofits displace standalone installations. Three-tier pricing structure across premium, standard, and economy levels differentiates by connectivity protocol certification and predictive algorithm capability. Cost-down pressure on economy-tier hardware accelerates because Taiwanese foundry concentration exposes procurement to geopolitical disruption. Facility managers in commercial buildings show highest price sensitivity for standalone thermostat replacements, while greenhouse operators in the Netherlands accept premium humidistat pricing tied to yield optimization outcomes.
Supply Chain Analysis
Controller refurbishment flows from commercial building retrofits feed secondary markets in Southeast Asia, extending component lifecycles outside warranty channels. Manufacturing concentration in China, South Korea, and Taiwan draws from sensor microcontroller foundries and magnetic component suppliers. Single-source vulnerability in 28nm sensor chip fabrication rests on two Taiwanese facilities. Distribution runs through HVAC OEM captive channels and independent building automation integrators serving retrofit-heavy European and North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The environment controllers market has become a vertical-integration race where captive semiconductor sourcing and edge AI chip development determine margin survival against compressed hardware replacement cycles.
For Market Incumbents: Anticipate margin collapse in standalone thermostat hardware by securing long-term foundry allocation agreements with Taiwanese and South Korean suppliers. Extend software platform lock-in through BACnet and Modbus protocol certification investments that raise switching costs for facility managers. Counter emerging pure-play sensor specialists by embedding controller refresh cycles into outcome-based performance contracts. For New Entrants and Emerging Players: Enter via India's Bureau of Energy Efficiency commercial cooling mandates, where integrated platform vendors face limited incumbent saturation. Target agricultural precision-climate segments in Spain and the Netherlands, where sub-degree humidity control specifications favor specialized humidistat arrays over bundled HVAC systems. Pursue edge AI convergence partnerships with on-device machine learning chip developers to differentiate latency performance. For Investors and Strategic Acquirers: Building electrification mandate announcements in multiple US states are the leading indicator that electric heat pump-compatible controller demand will displace gas-fired heating controller installed bases. Long-term viability favors acquirers of sensor-controller bundle specialists with EPA Clean Air Act emissions tracking certification and EU F-Gas Regulation CO2 compatibility roadmaps. Monitor EU Green Deal refrigerant transition timeline acceleration as forced replacement trigger for cold storage controller refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Reduces exposure to Taiwanese foundry concentration for sensor microcontrollers. |
| Edge AI Chip Development Partnership | Enables predictive maintenance without cloud dependency for secure-facility segments. |
| Sensor-Controller Bundle Certification Investment | Secures EPA Clean Air Act and EU F-Gas Regulation compliance for commercial retrofits. |
| Outcome-Based Performance Contract Expansion | Concentrates fastest in US healthcare and data center verticals with uptime penalty clauses. |
| Precision Agriculture Platform Launch | Captures Netherlands and Spain greenhouse operator demand for sub-degree humidity control. |
Research Methodology
Document review covered SEC 10-K filings, EPA Clean Air Act regulatory dockets, EU F-Gas Regulation implementation timelines, and building automation trade association technical standards, complemented by interviews with HVAC controls engineering directors, facilities management procurement leads, greenhouse operator technology adopters, and building automation system integrators. Secondary validation drew from MIIT GB protocol documentation, Bureau of Energy Efficiency cooling mandate circulars, and semiconductor foundry capacity disclosures. Bottom-up unit shipment estimates triangulated against top-down construction spending and agricultural investment data.
Market size outputs across the projection horizon reflect segmented modeling by product type, technology architecture, application vertical, and end-user procurement authority, with cross-validation against regional regulatory implementation schedules. CAGRs were derived from trend extrapolation of smart HVAC retrofit penetration rates, precision agriculture technology adoption curves, and building electrification mandate compliance timelines. Industry-specific forecast inputs included ENERGY STAR certification requirement phase-ins, EU Green Deal refrigerant transition roadmaps, and edge AI chip cost decline trajectories.
Revisions become necessary when semiconductor supply concentration disruptions, copper and rare earth commodity price spikes, or accelerated building electrification timelines materialize outside baseline assumptions. Forecasts reflect documented regulatory implementation schedules and technology cost curves. Practitioners should monitor EPA Clean Air Act amendment enforcement patterns, EU F-Gas Regulation timeline acceleration signals, and Taiwanese foundry capacity expansion announcements for early indicators of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Anti-Pollution Toner Market
Air Quality Control Systems
Anti-Pollution Mask Market
Air Quality Control Systems
Southeast Asia Air Purifier Market
Air Quality Control Systems
Asia-Pacific Air Quality Control System Market
Air Quality Control Systems
UV Air Purifiers Market
Air Quality Control Systems
Global Mist Eliminator Market
Air Quality Control Systems
US Air Quality Analyzers Market
Air Quality Control Systems
Sustainable Air Filter Market
Air Quality Control Systems
Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Europe Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Emission Management Software Market
Air Quality Control Systems
Desiccant Air Breather Market
Air Quality Control Systems
Air Scrubber Market
Air Quality Control Systems
Middle-East and Africa Industrial Air Quality Control Systems Market
Air Quality Control Systems
Asia-Pacific Indoor Air Purification Market
Air Quality Control Systems
Indoor Air Purification Market