
 North America Industrial Air Quality Control Systems Market | 2026-2036
North America Industrial Air Quality Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Air Quality Control Systems Market Analytics
Activated carbon fiber is pivoting toward pleated filter media in coal-fired plant retrofits, cutting pressure drop while maintaining mercury capture efficiency. Babcock & Wilcox Enterprises leverages its scrubber rebuild expertise to anchor utility upgrade cycles across the Midwest. CECO Environmental Corporation specializes in custom engineered ventilation for pharmaceutical cleanrooms, sustaining premium positioning through application-specific design.
Industrial air quality control systems encompass engineered equipment that removes, monitors, or neutralizes particulate matter, volatile organic compounds, acid gases, and other contaminants from industrial process streams and facility environments, typically operating at filtration efficiencies from MERV 11 to HEPA H14 and temperature tolerances exceeding 350°F in heavy manufacturing settings. These systems serve to maintain occupational exposure limits, prevent equipment corrosion, and ensure regulatory compliance across continuous process industries. Filters represent the most mature revenue pool with replacement cycles driving recurring demand, while sensors are capturing the fastest growth as facilities shift from periodic manual sampling to continuous emissions monitoring systems. Electrostatic technology dominates in power sector precipitator applications, whereas HEPA filtration commands the highest margins in pharmaceutical and biotechnology end-user segments where product contamination carries severe financial consequences.
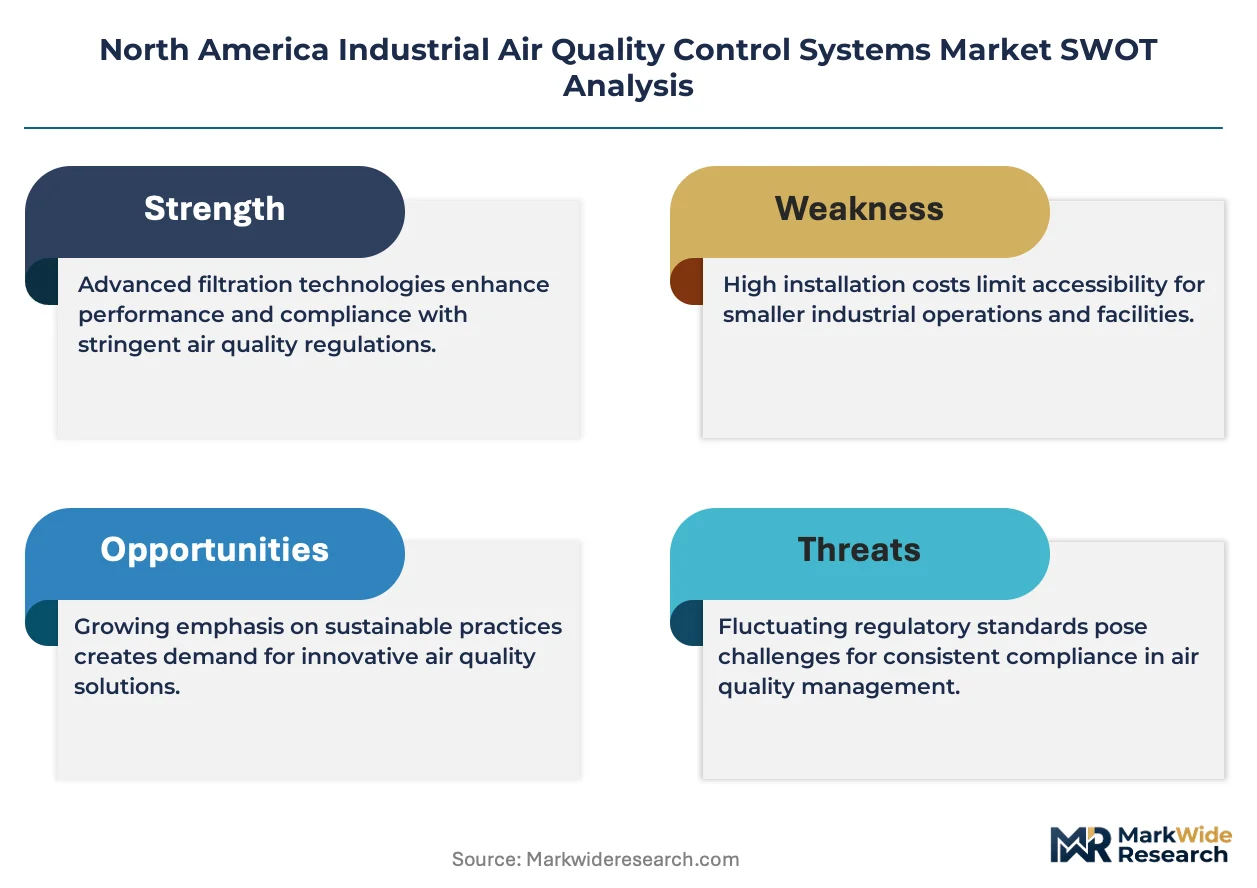
EPA enforcement of National Ambient Air Quality Standards under the Clean Air Act compels manufacturing and energy facilities to install certified control equipment or face operational penalties. OSHA permissible exposure limits for respirable crystalline silica and hexavalent chromium further tighten indoor air quality requirements in metal fabrication and chemical processing plants. Stakeholders must weigh the capital efficiency of upgrading existing precipitator infrastructure against complete system replacement as mercury and particulate regulations tighten without grandfathering relief.
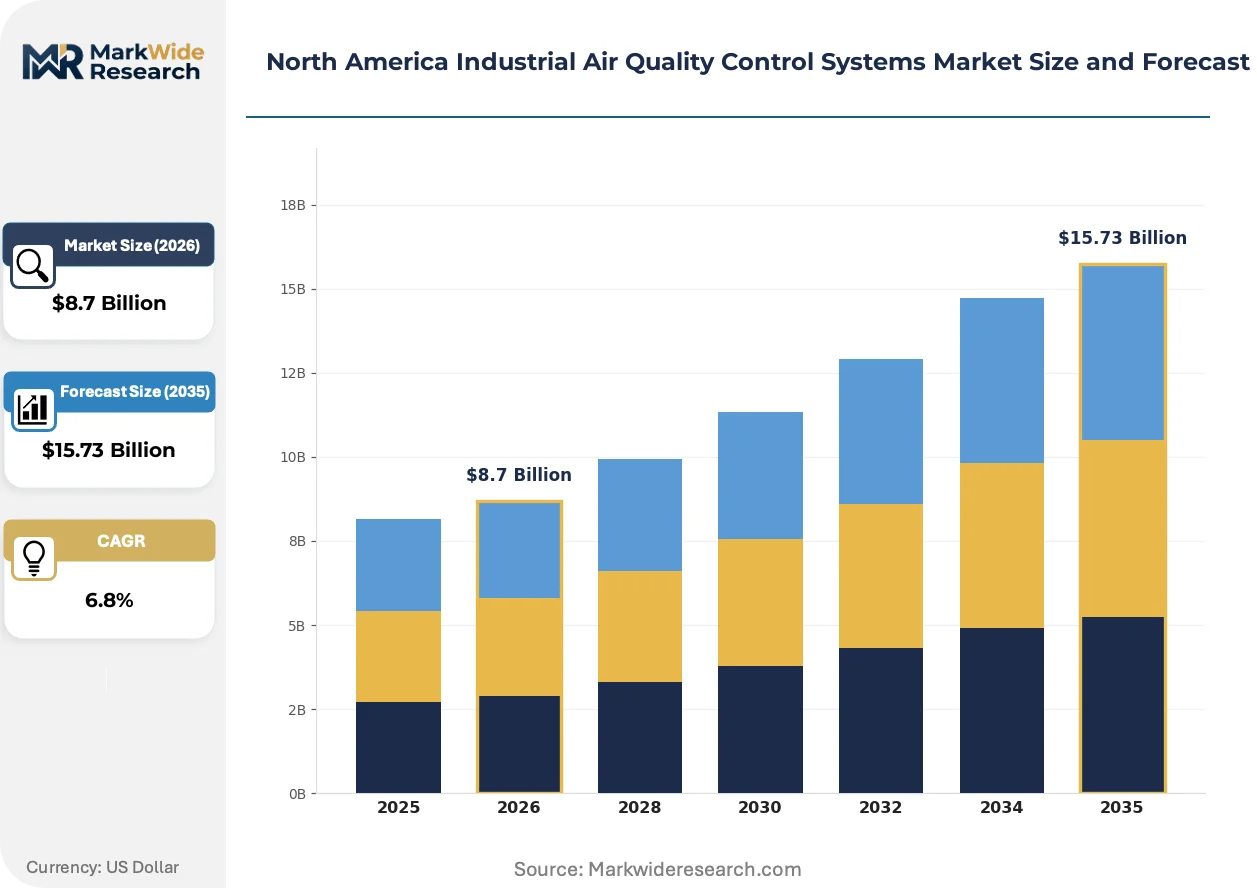
Market Dynamics
Coal-fired plant retrofits across the Ohio River Valley are compressing upgrade timelines as utilities race to meet EPA Mercury and Air Toxics Standards compliance deadlines without triggering operational shutdowns.
Growth Catalysts
- EPA Mercury and Air Toxics Standards:Power generation utilities face mandatory scrubber and baghouse installations, creating sustained equipment demand through 2035.
- Activated carbon fiber pleating:This material innovation cuts pressure drop while maintaining mercury capture efficiency, accelerating retrofit economics in coal-heavy states.
- Ohio River Valley manufacturing corridor:Electrostatic precipitator upgrades concentrate capital allocation here, anchoring regional equipment demand cycles.
Market Restraints
- Specialty ceramic fiber supply:Domestic production capacity for high-temperature filtration media remains concentrated among three US-based suppliers, creating input bottlenecks.
- Legacy precipitator infrastructure:Capital efficiency calculations favor upgrades over replacement, limiting total addressable market expansion for greenfield system sales.
- Silica gel desiccant substitution:Alternative moisture control technologies threaten rotary dehumidifier demand in pharmaceutical cleanroom applications.
Strategic Opportunities
- Mexico nearshoring expansion:Automotive and electronics manufacturing growth in Baja California and Querétaro creates demand for ventilation systems meeting OSHA-equivalent standards.
- Continuous emissions monitoring convergence:Integration of optical sensors with predictive maintenance software opens service revenue streams beyond hardware sales.
- Inflation Reduction Act clean energy incentives:Hydrogen hub development in Texas and California requires novel contaminant control for electrolyzer feedstock purification.
Industry Challenges
- PEM electrolyzer integration:Air quality systems for hydrogen production must achieve sub-ppb contaminant levels unfamiliar to conventional industrial filtration engineers.
- HEPA certification timelines:Pharmaceutical cleanroom projects face 14-18 month validation cycles that compress installation windows and strain project cash flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Air Quality Control Systems Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filters, Sensors, Monitors, Ventilation Systems End User: Manufacturing, Energy, Pharmaceuticals, Food Processing Technology: Active Carbon, Ionic, Electrostatic, HEPA Application: Emission Control, Indoor Air Quality, Industrial Hygiene, Pollution Control |
| Companies Covered | General Electric Company, Babcock & Wilcox Enterprises, CECO Environmental Corporation, Thermo Fisher Scientific, Ducon Technologies, Donaldson Company, Camfil, Parker Hannifin Corporation, AAF International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Air Quality Control Systems Market Evolving Landscape
Digital sensor networks are displacing manual stack testing protocols while membrane filtration advances challenge conventional packed-bed scrubber economics in acid gas applications.
Pulse-jet cleaning systems with piezoelectric actuators are electrifying baghouse maintenance cycles. Cement plants in the Great Lakes region adopt these retrofits to cut compressed air consumption by half. The technology is electrifying competitive dynamics between established fabric filter suppliers and industrial automation specialists entering environmental equipment.
EPA enforcement of National Ambient Air Quality Standards tightens continuously without grandfathering relief for existing sources. Manufacturing facilities in the Los Angeles basin and Houston Ship Channel face accelerated compliance timelines. Metal fabrication plants respond by front-loading electrostatic precipitator rebuilds ahead of permit renewal deadlines.
Buyer consolidation among North American pharmaceutical contract manufacturers concentrates specification authority with fewer procurement teams. These buyers now unbundle after-sales service contracts from initial equipment purchases, forcing original equipment manufacturers to compete with independent service providers on maintenance pricing. The shift is most visible in Massachusetts and North Carolina biotech clusters where facility expansion outpaces vendor service capacity.
North America Industrial Air Quality Control Systems Market Segmentation
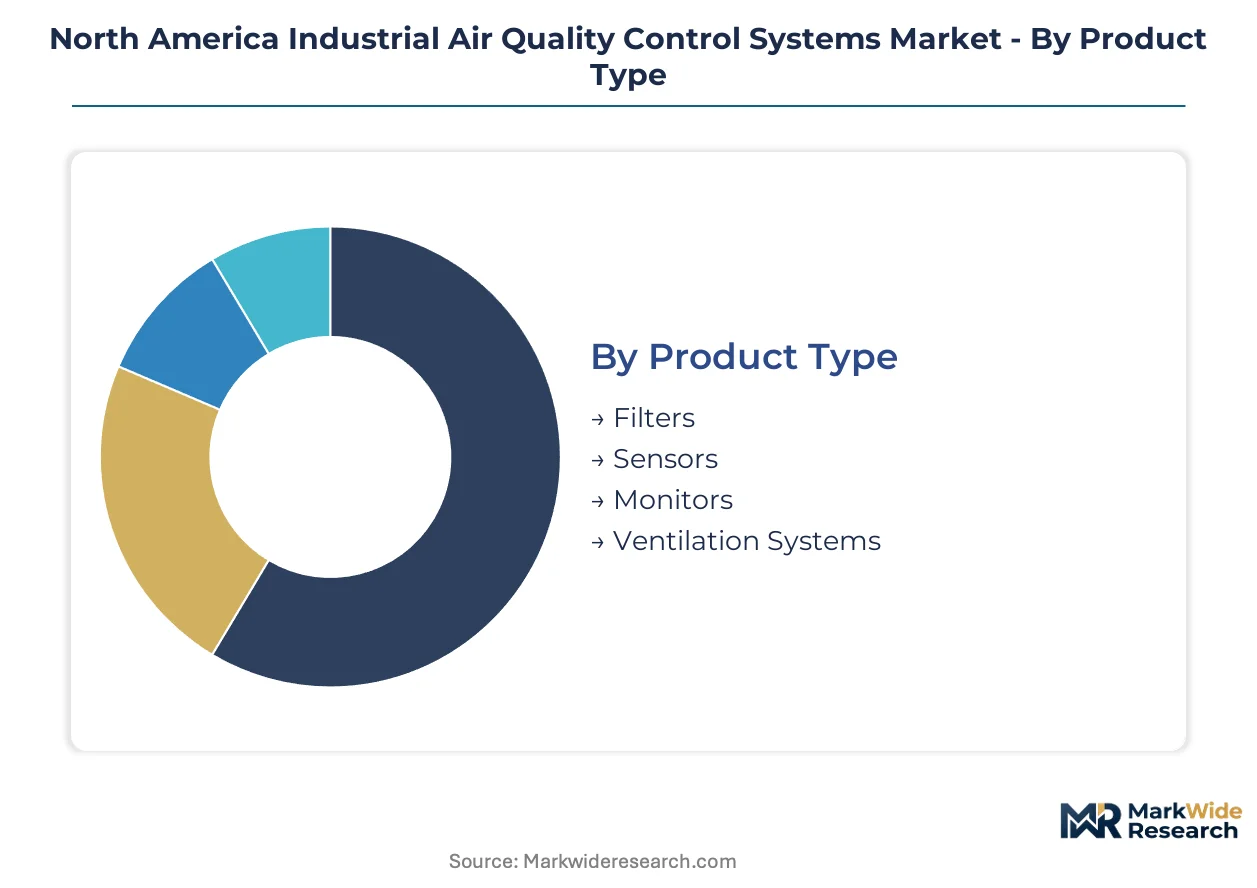
Equipment specification in North American industrial air quality control diverges sharply between standardized commodity components and engineered-to-order systems. Procurement teams balance capital efficiency against compliance certainty, with technology selection often predetermined by contaminant chemistry and operating temperature rather than cost optimization alone.
Product Type:
Standardization intensity varies from commodity replacement parts to fully custom integrated systems, with aftermarket service economics pulling toward modular designs.
- Filters:Pleated media, activated carbon beds, and ceramic fiber elements dominate consumable spend. Coal-fired utilities in the Ohio River Valley drive replacement cycles for mercury capture cartridges. Baghouse fabric filters face compressed lead times as cement plants accelerate compliance retrofits.
- Sensors:Optical particulate monitors and electrochemical gas detectors capture the steepest expansion trajectory. Continuous emissions monitoring mandates from EPA push power generation facilities toward networked sensor architectures that displace manual stack testing protocols.
- Monitors:Centralized data acquisition systems aggregate multi-point readings for regulatory reporting. Pharmaceutical cleanrooms in Massachusetts and North Carolina demand validated software platforms with 21 CFR Part 11 compliance.
- Ventilation Systems:Engineered air handling units with HEPA terminal filtration serve biotechnology manufacturing. Custom ductwork and pressure cascade designs command premium pricing over standardized HVAC equipment.
Most installed capacity flows through Filters. Expansion is steepest in Sensors.
End User:
Compliance cost sensitivity separates price-driven commodity buyers from specification-locked premium segments where contamination risk carries catastrophic financial consequences.
- Manufacturing:Metal fabrication plants across the Great Lakes region deploy electrostatic precipitators to meet OSHA silica exposure limits. Automotive stamping operations in Michigan and Ohio prioritize respirable dust control over volatile organic compound recovery.
- Energy:Coal-fired power generation utilities face the most stringent regulatory pressure under EPA Mercury and Air Toxics Standards. Scrubber rebuilds and activated carbon injection systems concentrate capital deployment in the Ohio River Valley.
- Pharmaceuticals:Sterile fill-finish operations and bioreactor suites require HEPA H14 terminal filtration with documented integrity testing. Contract manufacturing organization consolidation concentrates specification authority with fewer procurement teams in Massachusetts and North Carolina clusters.
- Food Processing:Dust collection for grain handling and thermal process ventilation for snack manufacturing dominate equipment demand. USDA food safety regulations drive hygienic design specifications for filter housings and ductwork materials.
Energy commands the largest equipment revenue pool. Pharmaceuticals deliver the highest margin realization per installed dollar.
Technology:
Maturity curves separate established incumbent platforms from emerging material innovations competing on total cost of ownership rather than capital expenditure alone.
- Active Carbon:Impregnated and non-impregnated granular and fiber forms capture mercury and acid gases. Pleated carbon fiber configurations cut pressure drop while maintaining capture efficiency, accelerating retrofit economics in coal-heavy states.
- Ionic:Bipolar ionization and plasma-based systems target odor and volatile organic compound reduction. Commercial building retrofits in California and Texas adopt these technologies for energy recovery ventilation integration.
- Electrostatic:Dry and wet precipitator configurations dominate particulate control in power generation and heavy manufacturing. Upgrade cycles concentrate in the Ohio River Valley manufacturing corridor where legacy infrastructure requires rebuild rather than replacement.
- HEPA:H13 and H14 efficiency ratings command specification in pharmaceutical aseptic processing and biotechnology containment. Validation timelines of 14-18 months compress installation windows and strain project cash flows for cleanroom construction.
Electrostatic technology anchors the largest installed base. Active Carbon fiber configurations are gaining share fastest in mercury control retrofits.
Application:
Regulatory enforcement intensity and penalty exposure determine capital allocation priority across ambient emission, occupational exposure, and product protection use cases.
- Emission Control:Stack-mounted scrubbers, precipitators, and carbon injection systems address EPA National Ambient Air Quality Standards. Enforcement without grandfathering relief forces manufacturing facilities in the Los Angeles basin and Houston Ship Channel into accelerated compliance timelines.
- Indoor Air Quality:Ventilation and filtration systems maintain OSHA permissible exposure limits for respirable crystalline silica and hexavalent chromium. Metal fabrication and chemical processing plants face tightening indoor requirements alongside ambient mandates.
- Industrial Hygiene:Source capture ventilation and personal protective equipment integration protect workers from welding fume and solvent vapor. Automotive assembly plants in Mexico nearshoring zones adopt OSHA-equivalent standards to support US customer qualification.
- Pollution Control:Fugitive dust suppression and accidental release mitigation systems serve mining, bulk handling, and chemical storage operations. Texas and California hydrogen hub development requires novel contaminant control for electrolyzer feedstock purification.
Emission Control absorbs the majority of utility capital expenditure. Indoor Air Quality is climbing the fastest as OSHA enforcement tightens manufacturing facility requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ohio River Valley manufacturing corridor anchors North American industrial air quality control demand through concentrated power generation and heavy manufacturing activity. EPA Mercury and Air Toxics Standards compliance deadlines compress retrofit timelines across this region. Three national markets and two cross-border industrial zones shape equipment deployment patterns.
United States
Coal-fired utilities in the Ohio River Valley drive scrubber and electrostatic precipitator upgrade cycles. EPA enforcement of National Ambient Air Quality Standards forces accelerated compliance in the Los Angeles basin and Houston Ship Channel. Metal fabrication plants across the Great Lakes region deploy source capture systems to meet OSHA silica exposure limits.
Canada
Oil sands operations in Alberta sustain demand for high-temperature filtration and fugitive dust suppression systems. Environment and Climate Change Canada regulations align with EPA standards for cross-border airshed management. Ontario's automotive manufacturing corridor around Windsor and Oshawa prioritizes welding fume control for occupational compliance.
Mexico
Nearshoring expansion in Baja California and Querétaro creates demand for ventilation systems meeting OSHA-equivalent standards. Automotive and electronics manufacturing growth supports US customer qualification requirements. The Mexico City metropolitan area faces compressed timelines for ambient particulate reduction under federal environmental programs.
Great Lakes Cross-Border Manufacturing Zone
Cement plants throughout Michigan, Ohio, and Ontario adopt pulse-jet cleaning retrofits to cut compressed air consumption. Regulatory harmonization between EPA and Environment and Climate Change Canada enables standardized equipment specifications. Regional supplier networks serve rebuild cycles across this integrated industrial corridor.
Southwest Industrial Corridor
Hydrogen hub development in Texas requires novel contaminant control for electrolyzer feedstock purification. Inflation Reduction Act incentives accelerate project timelines for PEM electrolyzer integration. Semiconductor fabrication growth in Arizona and New Mexico drives HEPA filtration demand for cleanroom construction.
North America Industrial Air Quality Control Systems Market Competitive Landscape
Global majors compete with regional champions across technology specialization and service proximity dimensions. The vendor base organizes around three tiers: diversified industrial conglomerates with environmental divisions, dedicated air quality equipment specialists, and regional fabricators serving aftermarket rebuild cycles. Two strategic archetypes dominate competitive positioning: technology licensors leveraging proprietary designs and service-intensive operators capturing recurring maintenance revenue. Consolidation pressure concentrates among mid-scale fabricators lacking differentiation in standardized filter media.
Among diversified industrial conglomerates, General Electric Company and Parker Hannifin Corporation exemplify scale-driven positioning through integrated manufacturing and distribution infrastructure. Babcock & Wilcox Enterprises and CECO Environmental Corporation represent the dedicated specialist archetype, anchoring premium positioning through application-specific engineering capabilities. Donaldson Company and Camfil occupy positions between these tiers, balancing standardized product platforms with sector-focused technical support.
| Leading Market Players |
|---|
| General Electric Company |
| Babcock & Wilcox Enterprises |
| CECO Environmental Corporation |
| Thermo Fisher Scientific |
| Ducon Technologies |
| Donaldson Company |
| Camfil |
| Parker Hannifin Corporation |
| AAF International |
| Others |
Value Network & Pricing Analysis
Activated carbon fiber spot prices cascade through North American industrial air quality control equipment tiers, compressing margins on standard baghouse retrofits while reinforcing premium capture for mercury-specific engineered systems. Specialty ceramic fiber supply concentration among three domestic producers anchors input cost pass-through mechanics across the Ohio River Valley manufacturing corridor.
Pricing Analysis
Input-cost pass-through dominates pricing mechanics as activated carbon fiber and ceramic media tariffs transmit directly to utility procurement teams. Three-tier pricing structure across premium engineered systems, standard modular retrofits, and commodity replacement filters separates EPA-compliant mercury capture configurations from basic particulate control. Cost compression in standard electrostatic precipitator rebuilds intensifies because buyer consolidation among Midwest utilities concentrates volume leverage. Pharmaceutical cleanroom specifications demonstrate least price sensitivity, whereas cement plant baghouse retrofits exhibit acute cost responsiveness.
Supply Chain Analysis
Regional distribution centers in Ohio, Texas, and Ontario coordinate hub-and-spoke fulfillment patterns for high-temperature filtration media and replacement cartridge inventory. Manufacturing concentrates in the United States, Mexico, and Canada, with specialty ceramic fiber production anchored domestically. Raw material dependencies include activated carbon feedstock, fiberglass matting, and piezoelectric actuator components. Single-source vulnerability in specialty ceramic fiber creates structural exposure to input bottlenecks. Distribution runs through authorized service networks and direct OEM channels to utility and pharmaceutical end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EPA Mercury and Air Toxics Standards enforcement shifts procurement authority toward specification-engineered systems over commodity alternatives.
For Market Incumbents: Anticipate pulse-jet cleaning electrification and membrane filtration advances threatening conventional packed-bed scrubber economics. Defend position by deepening backward integration into activated carbon fiber pleating capabilities and securing exclusive service contracts with Ohio River Valley utilities before permit renewal deadlines compress vendor selection windows. For New Entrants and Emerging Players: Mid-scale pharmaceutical contract manufacturers in North Carolina and Massachusetts represent an underserved buyer archetype as facility expansion outpaces established vendor service capacity. Penetrate this segment through validated 21 CFR Part 11 software platforms unbundled from hardware procurement, leveraging compressed HEPA certification timelines as competitive wedge against integrated incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with regional fabricators possessing rebuild expertise in legacy precipitator infrastructure rather than greenfield system manufacturers. Long-term viability favors service-intensive operators capturing recurring maintenance revenue streams. Monitor EPA enforcement acceleration in the Los Angeles basin and Houston Ship Channel as inflection signal for compliance-driven capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Activated Carbon Fiber | Captive supply of pleated media secures margin capture in mercury control retrofits across coal-heavy states. |
| Continuous Emissions Monitoring Convergence | Optical sensor integration with predictive maintenance software opens service revenue beyond hardware sales. |
| Mexico Nearshoring Service Network Expansion | OSHA-equivalent ventilation demand in Baja California and Querétaro supports US customer qualification requirements. |
| PEM Electrolyzer Contaminant Control Development | Sub-ppb purification capabilities for hydrogen hub projects in Texas and California create first-mover positioning. |
| Pharmaceutical Cleanroom Validation Acceleration | Compressed 14-18 month HEPA certification cycles strain project cash flows and favor service-contract bundling. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, plant engineers at cement and metal fabrication facilities, pharmaceutical facility directors, and aftermarket service heads with secondary validation against EPA enforcement databases, EIA power generation statistics, SEC equipment manufacturer filings, and OSHA compliance inspection records. Bottom-up equipment deployment estimates triangulated against top-down market sizing derived from capital expenditure disclosures across the analysis window.
Comparable-period anchoring linked projection assumptions to historical retrofit cycle patterns and regulatory compliance deadline clustering. Segmentation modeling incorporated product type, end-user industry, technology platform, and geographic regulatory intensity dimensions across the projection horizon. CAGRs were derived from equipment replacement cycle frequencies, regulatory enforcement trajectory, and technology substitution elasticity. Industry-specific inputs included scrubber rebuild backlog data and pharmaceutical cleanroom construction pipeline tracking.
Underlying measurement precision varies by segment; sensor and monitor categories carry tighter precision than custom ventilation systems given standardization intensity differences. Forecasts reflect documented assumptions regarding EPA enforcement continuity, ceramic fiber supply stability, and hydrogen hub development pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Air Pollution Control Equipment Market
Air Quality Control Systems
Europe Industrial Air Quality Control Systems Market
Air Quality Control Systems
UV Air Purifiers Market
Air Quality Control Systems
Emission Management Software Market
Air Quality Control Systems
Industrial Air Quality Control Systems Market
Air Quality Control Systems
Oxygen Filters Market
Air Quality Control Systems
Environment Controllers Market
Air Quality Control Systems
Desiccant Air Breather Market
Air Quality Control Systems
Air Scrubber Market
Air Quality Control Systems
Europe Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Global Mist Eliminator Market
Air Quality Control Systems
Environmental Control System (ECS) Market
Air Quality Control Systems
Singapore Air Purifier Market
Air Quality Control Systems
Air Quality Monitoring Software Market
Air Quality Control Systems
Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Ozone Generation Market