
 Europe Nitrogen Oxide Control Systems Market | 2026-2036
Europe Nitrogen Oxide Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nitrogen Oxide Control Systems Market Analytics
German engineering firms and Nordic catalyst producers is rebalancing supply chains toward localized urea and ammonia dosing component manufacturing. Siemens AG leverages its automation portfolio to dominate digital integration for SCR process control. BASF SE sustains catalyst formulation leadership through continuous R&D on vanadium-titanium and zeolite-based substrates. Mitsubishi Heavy Industries Ltd. anchors large-scale installation capacity for utility boiler retrofits across Central Europe.
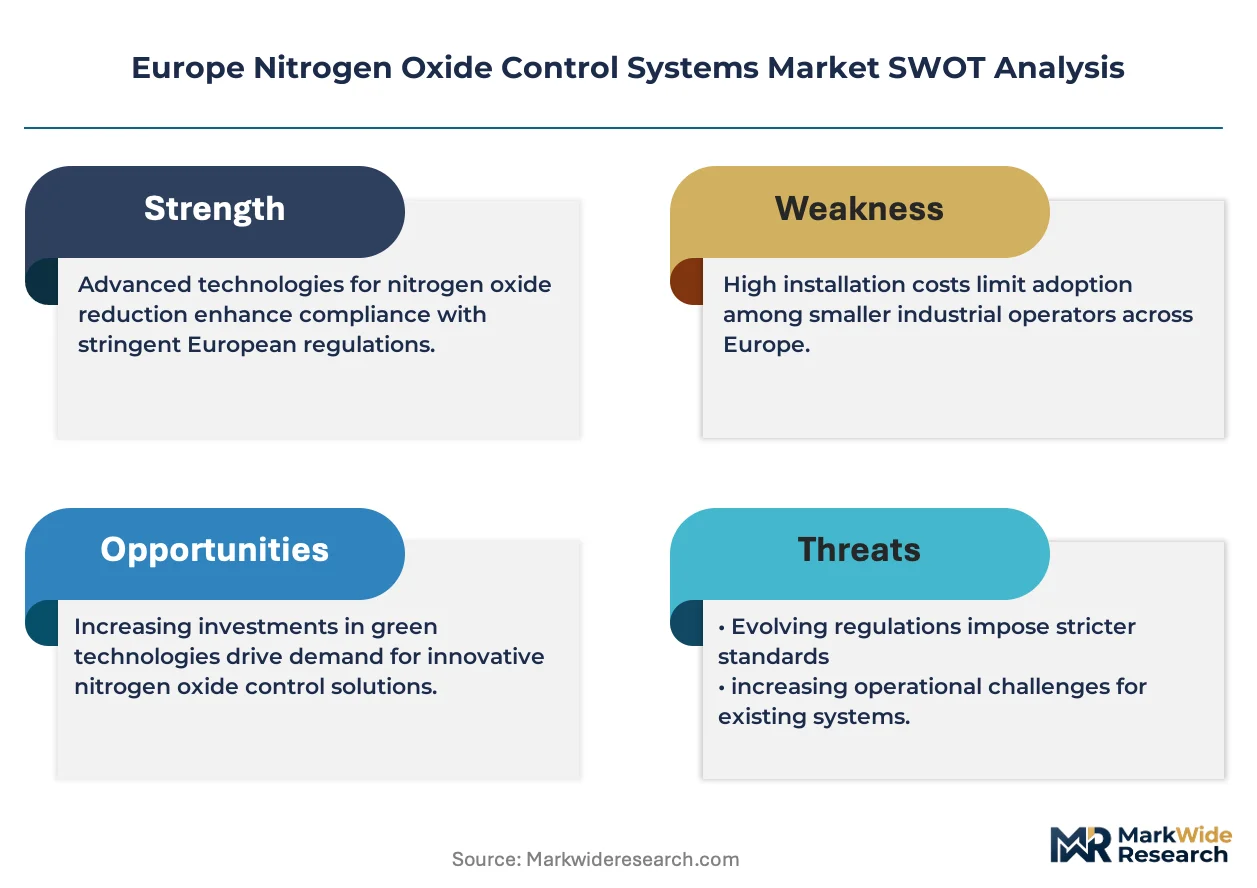
Europe nitrogen oxide control systems encompass selective catalytic reduction (SCR), selective non-catalytic reduction (SNCR), and adsorption technologies designed to chemically convert NOx into nitrogen and water vapor, typically operating at flue gas temperatures between 300°C and 400°C for SCR and 850°C to 1100°C for SNCR. These systems serve power generation, marine propulsion, and industrial combustion facilities to meet enforceable emission limits. SCR systems capture the dominant value share due to their efficiency in high-volume continuous operations, while marine applications represent the fastest-growing end user segment as International Maritime Organization Tier III standards tighten in European ports. Retrofit installations command premium margins relative to new construction given engineering complexity and downtime constraints at existing facilities.
The EU Green Deal, Industrial Emissions Directive, and F-Gas Regulation collectively mandate stepwise NOx reduction timelines and ban certain fluorinated greenhouse gases used in precursor manufacturing. ECHA substance restrictions and CE marking requirements shape product certification pathways and cross-border market access for equipment suppliers. Stakeholders must monitor upcoming BAT reference document revisions and carbon border adjustment mechanism alignment to anticipate compliance cost shifts and procurement timing.
Market Dynamics
The EU Green Deal's tightened emission ceilings are compressing technology replacement cycles across European industrial corridors, forcing power generators and marine operators into simultaneous compliance retrofits.
Growth Catalysts
- Selective Catalytic Reduction Retrofits:Germany's Rhine-Ruhr industrial corridor is driving concentrated demand for SCR system upgrades at aging coal and gas-fired facilities to meet Industrial Emissions Directive benchmarks.
- Marine Propulsion Compliance:International Maritime Organization Tier III standards in European ports are mandating exhaust after-treatment installations on vessels calling at Rotterdam, Hamburg, and Antwerp.
- F-Gas Regulation Phase-Out:The ban on certain fluorinated greenhouse gases in precursor manufacturing is accelerating catalyst substrate innovation toward zeolite-based alternatives.
Market Restraints
- Urea Supply Concentration:Baltic and Black Sea sourcing corridors for ammonia-derived reagents expose dosing system operators to input cost volatility and geopolitical disruption.
- Catalyst Degradation Rates:Vanadium-titanium formulations suffer accelerated poisoning from sulfur and alkali metals in biomass co-firing applications, shortening replacement intervals.
- CE Marking Complexity:ECHA substance restrictions and evolving BAT reference documents create certification friction for cross-border equipment shipments.
Strategic Opportunities
- Polish Industrial Corridor Expansion:Silesian steel and cement clusters remain underpenetrated for SNCR installations relative to German and French benchmarks.
- Digital Twin Integration:Convergence of predictive maintenance software with SCR process control is creating premium service attach rates at utility boiler operators.
- Carbon Border Adjustment Alignment:Importers into the EU face embedded emission accounting requirements that favor certified NOx control technology procurement.
Industry Challenges
- Cross-Border Technician Mobility:Specialized catalyst replacement crews face work permit and safety certification fragmentation across Schengen and non-Schengen EU members.
- Legacy DCS Integration:Retrofit installations at 1980s-era power plants require custom protocol bridging to modern ammonia dosing control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nitrogen Oxide Control Systems Market |
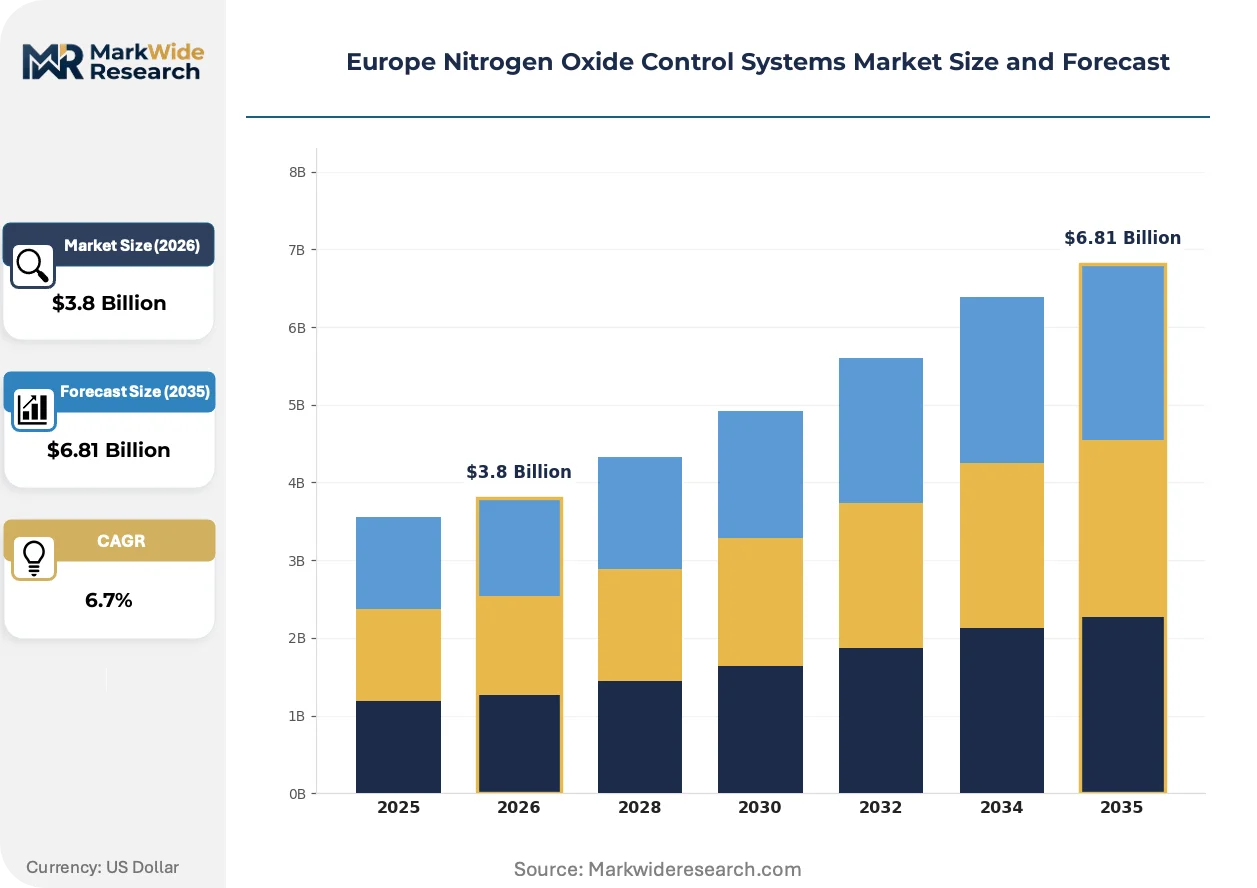
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
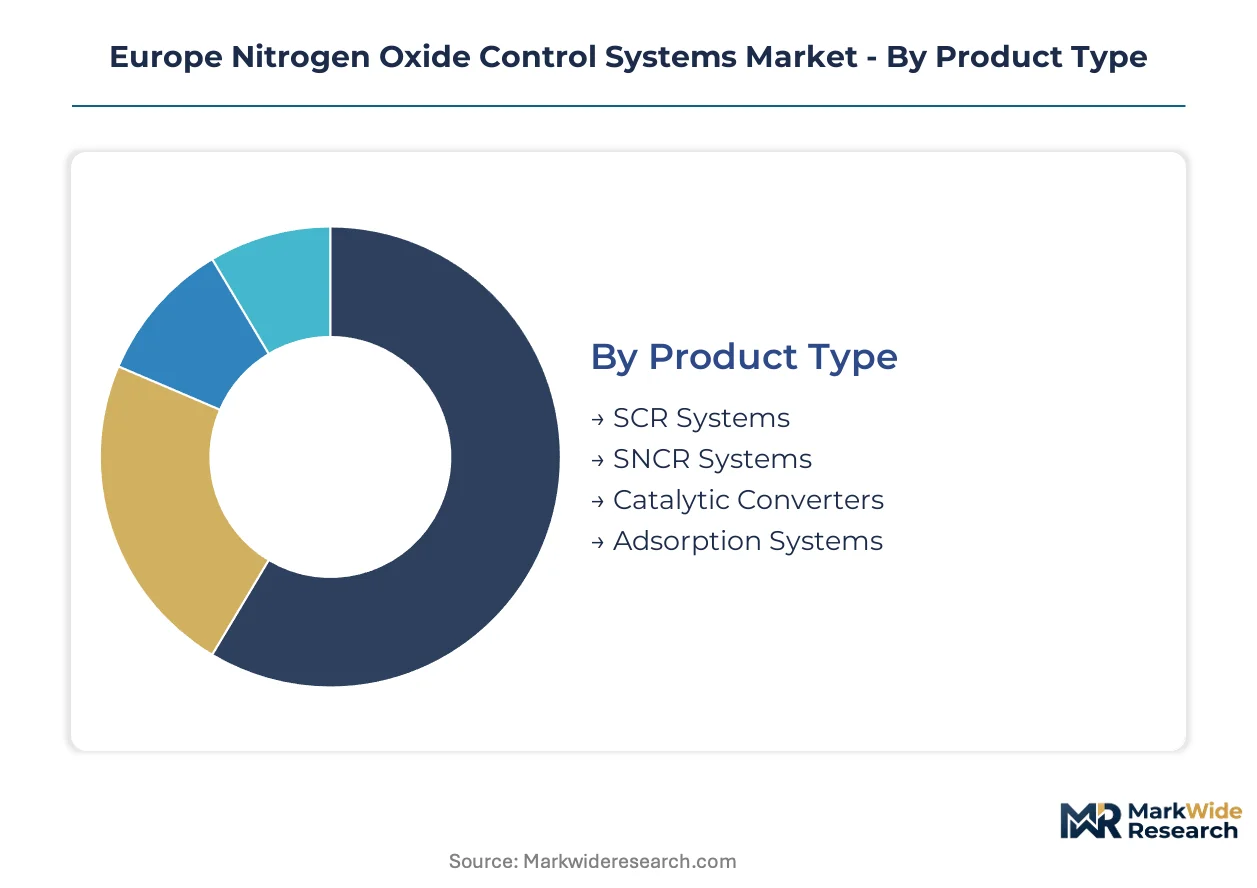
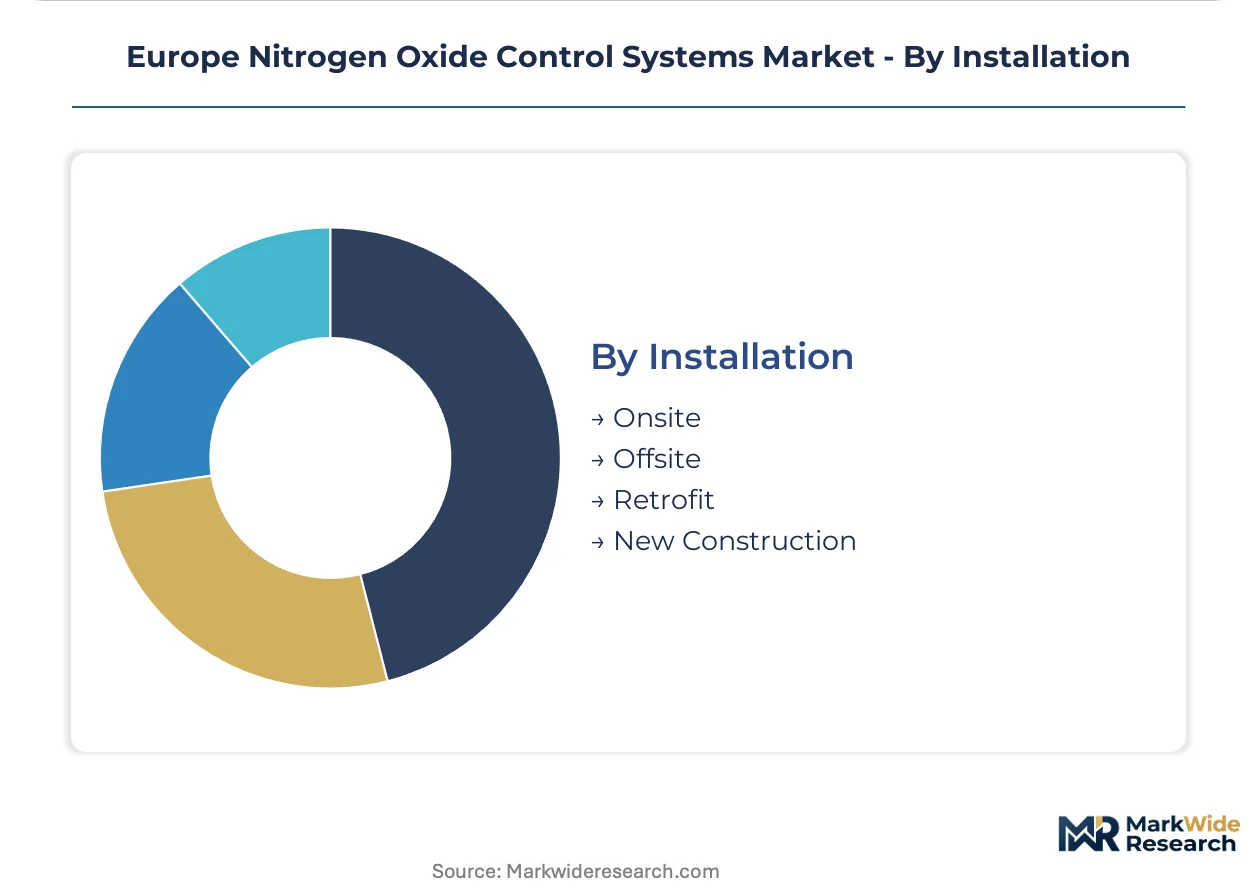
| Segmentation | Product Type: SCR Systems, SNCR Systems, Catalytic Converters, Adsorption Systems Technology: Chemical Reduction, Thermal Decomposition, Oxidation, Adsorption End User: Power Plants, Automotive Industry, Industrial Boilers, Marine Applications Installation: Onsite, Offsite, Retrofit, New Construction |
| Companies Covered | Siemens AG, Mitsubishi Heavy Industries Ltd., Babcock & Wilcox Enterprises Inc., Honeywell International Inc., John Wood Group plc, Haldor Topsoe A/S, BASF SE, Hamon Group, CECO Environmental Corp., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nitrogen Oxide Control Systems Market Evolving Landscape
Equipment architecture and service delivery models are fragmenting as modular designs meet tightened environmental enforcement and compressed project timelines.
Containerized SCR skids with pre-engineered catalyst beds and integrated urea storage are modularizing project delivery for mid-scale industrial boilers. Food processing and chemical manufacturers in the Netherlands and Belgium are adopting these units to avoid extended production shutdowns. The shift is compressing engineering-procurement-construction timelines from 18 months to 8-12 weeks for sub-50 MW applications.
Revised BAT reference documents under the Industrial Emissions Directive are mandating lower NOx concentration ceilings for large combustion plants. Germany's Federal Environment Agency is enforcing these limits through enhanced stack monitoring requirements. Cement and lime producers in Bavaria and North Rhine-Westphalia are responding with hybrid SCR-SNCR configurations to bridge compliance gaps.
Long-term catalyst performance guarantees are displacing upfront equipment sales at European power utilities. RWE and Uniper are unbundling capital expenditure from operations through 10-year service agreements with penalty clauses for emission exceedance. This model is concentrating in Germany and France where utility balance sheets face stranded asset pressure from renewable transition timelines.
Europe Nitrogen Oxide Control Systems Market Segmentation
Technology choice in European NOx control hinges on flue gas temperature profiles, reagent availability, and the regulatory stringency of specific industrial corridors. Segmentation reveals where capital deployment concentrates and which compliance pathways offer margin protection for equipment suppliers.
Product Type:
Supply concentration for catalyst substrates and ammonia dosing hardware varies sharply across product categories, with German and Dutch engineering firms dominating SCR system integration while SNCR remains more fragmented.
- SCR Systems:These units deploy vanadium-titanium or zeolite-based catalyst beds to reduce NOx at 300°C to 400°C operating temperatures. Demand clusters at coal and gas-fired power stations in Germany's Rhine-Ruhr corridor, where the Industrial Emissions Directive mandates continuous compliance monitoring and the tightest emission ceilings.
- SNCR Systems:Urea or ammonia injection without catalyst substrates operates at 850°C to 1100°C, suited to smaller industrial boilers and cement kilns. Polish Silesian steel and cement clusters represent underpenetrated demand relative to German benchmarks, with lower capital barriers driving adoption.
- Catalytic Converters:Compact oxidation catalysts serve diesel engine exhaust streams in automotive and marine propulsion applications.
- Adsorption Systems:Activated carbon or zeolite capture units handle low-temperature exhaust where thermal activation is impractical.
SCR Systems absorb the bulk of installed capacity; Catalytic Converters are expanding most quickly under International Maritime Organization Tier III mandates.
Technology:
Cost tier differentiation separates mature chemical reduction methods from emerging thermal and adsorption approaches, with oxidation technologies commanding premium pricing in marine certification pathways.
- Chemical Reduction:Ammonia-urea reactions with NOx represent the dominant commercial pathway, with process control automation from Siemens AG and similar firms enabling precise dosing at German utility installations.
- Thermal Decomposition:High-temperature NOx breakdown without reagent injection suits specific cement kiln configurations in Bavaria and North Rhine-Westphalia.
- Oxidation:Platinum-group catalysts convert NOx to nitrogen dioxide for subsequent absorption, climbing the fastest in European port marine applications facing Tier III enforcement.
- Adsorption:Physical capture on porous substrates serves intermittent-duty industrial boilers where thermal cycling degrades catalytic performance.
Chemical Reduction retains the deepest installed base; Oxidation is gaining share fastest among new marine installations.
End User:
Application-specific emission profiles and downtime tolerance reshape procurement patterns, with continuous-duty power generation demanding redundancy that intermittent industrial users reject.
- Power Plants:Baseload coal and gas facilities require redundant SCR trains and 24/7 reagent supply chains, with RWE and Uniper transitioning to long-term service contracts that unbundle capital from operations.
- Marine Applications:Exhaust after-treatment on vessels calling at Rotterdam, Hamburg, and Antwerp faces mandatory Tier III compliance, with containerized retrofit skids compressing installation windows to avoid charter penalties.
- Industrial Boilers:Mid-scale process heat applications in Dutch and Belgian food processing favor modular containerized units with pre-engineered catalyst beds.
- Automotive Industry:Heavy-duty diesel and emerging hydrogen combustion engines drive catalyst formulation refinement at BASF SE and similar suppliers.
Power Plants anchor the largest committed capital; Marine Applications show the steepest expansion trajectory.
Installation:
Customer type and margin structure diverge sharply between greenfield project timelines and the engineering complexity of retrofitting active industrial facilities.
- Retrofit:Installation at operating power plants and marine vessels commands premium margins due to downtime constraints, custom protocol bridging to legacy DCS systems, and confined-space catalyst replacement logistics.
- New Construction:Greenfield utility and industrial projects allow integrated SCR design from commissioning, with standardized specifications compressing procurement cycles in Poland's expanding industrial corridor.
- Onsite:Field-erected systems with local civil works dominate large combustion plant applications.
- Offsite:Pre-fabricated skids with factory-tested catalyst beds reduce commissioning risk for sub-50 MW industrial users.
Retrofit captures the highest margin per installed megawatt; New Construction offers volume scale in Poland and southeastern Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urea supply corridors from the Baltic and Black Sea regions anchor reagent procurement economics across European NOx control installations, with dosing system operators managing input cost exposure through diversified sourcing strategies.
Germany
The Rhine-Ruhr industrial corridor sustains the densest concentration of SCR retrofits at aging coal and gas-fired facilities. The Federal Environment Agency enforces Industrial Emissions Directive limits through enhanced stack monitoring requirements. Bavarian cement and lime producers deploy hybrid SCR-SNCR configurations to bridge compliance gaps under tightening BAT reference documents.
Poland
Silesian steel and cement clusters generate underpenetrated demand for SNCR installations relative to German benchmarks, with lower capital barriers accelerating adoption. The country's national environmental regulator aligns implementation timelines with EU Green Deal stepwise reduction schedules. Warsaw-based engineering procurement is standardizing specifications for greenfield utility projects in the expanding industrial corridor.
France
Utility operators including EDF transition to long-term service agreements that unbundle capital expenditure from operations through performance-guaranteed contracts. The French national environmental agency enforces emission ceilings through continuous compliance monitoring at baseload power stations. Île-de-France process heat applications favor modular containerized SCR units to minimize production shutdowns.
Netherlands
Rotterdam port marine operators face mandatory International Maritime Organization Tier III compliance for exhaust after-treatment on vessels. The Dutch national environmental agency coordinates with EU F-Gas Regulation phase-out timelines for catalyst precursor manufacturing. Food processing manufacturers in the Randstad adopt containerized SCR skids with pre-engineered catalyst beds.
Italy
Lombard and Piedmont industrial boiler operators concentrate procurement for mid-scale selective catalytic reduction upgrades. The Italian Ministry of Environment implements Industrial Emissions Directive benchmarks through regional enforcement delegations. Milan-area chemical manufacturers compress engineering-procurement-construction timelines through standardized sub-50 MW equipment specifications.
Europe Nitrogen Oxide Control Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital integration and modular fabrication as differentiation vectors. The vendor base stratifies across German engineering integrators, Nordic catalyst specialists, and Japanese installation contractors. Three archetypes dominate: automation-anchored system integrators, substrate-focused chemical formulators, and project-scale field erection specialists. Competitive moves concentrate on long-term service contract unbundling and pre-fabricated skid standardization.
Among German-based industrial conglomerates, Siemens AG occupies a position exemplifying automation-anchored integration for SCR process control. Japanese heavy engineering specialists including Mitsubishi Heavy Industries Ltd. anchor the large-scale installation archetype for utility boiler retrofits. BASF SE, a German chemical producer, sits within the catalyst formulation tier through continuous R&D on vanadium-titanium and zeolite-based substrates.
| Leading Market Players |
|---|
| Siemens AG |
| Mitsubishi Heavy Industries Ltd. |
| Babcock & Wilcox Enterprises Inc. |
| Honeywell International Inc. |
| John Wood Group plc |
| Haldor Topsoe A/S |
| BASF SE |
| Hamon Group |
| CECO Environmental Corp. |
| Others |
Value Network & Pricing Analysis
German family-owned mid-cap engineering specialists, consolidated through private-equity rollups in the Rhine-Ruhr corridor, anchor catalyst substrate production and enforce disciplined pricing through captive urea dosing component manufacturing. Their ownership structure limits external financing pressure, allowing sustained margin protection against Baltic ammonia cost volatility while concentrating procurement leverage over utility retrofit buyers.
Pricing Analysis
Warranty and catalyst performance guarantee bundling separates capital-light equipment sales from premium service contracts at RWE and Uniper installations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under ECHA substance restrictions and BAT reference document alignment. Pricing pressure stems from containerized skid standardization compressing engineering margins for sub-50 MW industrial applications. Polish Silesian cement operators exhibit highest price sensitivity due to lower capital barriers, while German utility retrofits accept premium positioning for emission exceedance penalty protection.
Supply Chain Analysis
CE marking and ECHA substance qualification gating restrict catalyst substrate sourcing to German, Dutch, and Danish engineering integrators with established certification pathways. Urea reagent supply draws from Baltic and Black Sea ammonia corridors, with vanadium-titanium and zeolite-based catalyst formulations resting on specialized precursor manufacturing concentrated in the Rhine-Ruhr industrial belt. Single-source vulnerability runs through geopolitically exposed ammonia shipping routes. Distribution runs through project-scale field erection specialists and modular skid fabricators serving mid-scale industrial boiler operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized catalyst replacement crew capacity constraints across Schengen and non-Schengen EU members prop pricing discipline for retrofit installations, compressing availability windows and sustaining premium margin capture.
For Market Incumbents: To counter containerized skid commoditization from Dutch and Belgian food processing adopters, BASF SE and Siemens AG should deepen backward integration into localized urea dosing component manufacturing and secure exclusive long-term service agreements with penalty clauses for emission exceedance. Certification investment in zeolite-based substrate pathways ahead of F-Gas Regulation phase-out timelines reinforces defensible positioning. For New Entrants and Emerging Players: The EU Green Deal's tightened emission ceilings in Poland open a window for SNCR system penetration in Silesian steel and cement clusters where German benchmark penetration remains unmet. Targeting modular containerized SCR skids for mid-scale industrial boilers in the Netherlands and Belgium leverages compressed engineering-procurement-construction timeline demand. A digital twin integration go-to-market angle captures premium service attach rates at utility boiler operators seeking predictive maintenance convergence. For Investors and Strategic Acquirers: Distressed-cycle entries favor automation-anchored system integrators with established SCR process control platforms in Germany and France, where utility balance sheet pressure from renewable transition timelines creates acquisition opportunity. Long-term viability across the energy transition window hinges on service contract unbundling capabilities and catalyst formulation R&D depth. The signal to watch is carbon border adjustment mechanism alignment triggering certified technology procurement preference shifts among EU importers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Urea Dosing Components | German engineering firms reduce Baltic ammonia corridor exposure through localized manufacturing capacity. |
| Zeolite-Based Catalyst R&D Acceleration | BASF SE and Nordic producers preempt F-Gas Regulation precursor bans with alternative substrate pathways. |
| Digital Twin Platform Development | Siemens AG captures predictive maintenance premiums through SCR process control software convergence. |
| Containerized Skid Standardization | Mid-scale industrial boiler operators in the Netherlands compress installation timelines from 18 months to 8-12 weeks. |
| Long-Term Service Contract Unbundling | RWE and Uniper separate capital expenditure from operations through 10-year performance-guaranteed agreements. |
Research Methodology
Independent corroboration across plant engineers at German utility operators, procurement leads at Silesian steel and cement clusters, catalyst R&D directors at BASF SE and Haldor Topsoe A/S, marine compliance officers at Rotterdam port authorities, and ECHA regulatory affairs specialists underwrites the qualitative findings. Secondary validation drew from Industrial Emissions Directive BAT reference documents, EU F-Gas Regulation implementation timelines, SEC filings of listed engineering conglomerates, and customs data tracking urea reagent import corridors. Bottom-up installation capacity estimates triangulated against top-down market value reconstructions.
Comparable-period anchoring to historical retrofit cycle timing and greenfield utility commissioning schedules established the forecast window baseline. Across the analysis window, segmentation dimensions modeled include technology type, flue gas temperature profile, installation mode, and regulatory compliance tier alignment with EU Green Deal stepwise reduction timelines. CAGRs derived from unit economics analysis of SCR versus SNCR system deployment costs, catalyst replacement intervals under sulfur and alkali metal exposure, and reagent pricing sensitivity to Baltic ammonia supply disruptions. Marine propulsion compliance acceleration under International Maritime Organization Tier III enforcement shaped trajectory assumptions.
The model assumes a particular technology adoption path; alternative pathways for hybrid SCR-SNCR configurations or thermal decomposition approaches in Bavarian cement applications would alter the outlook. Forecasts reflect assumptions regarding ECHA substance restriction implementation pacing and carbon border adjustment mechanism procurement preference effects. A model refresh is warranted upon material change in EU Green Deal emission ceiling enforcement intensity or Baltic-Black Sea ammonia corridor stability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Green Emissions Analyzers Market
Air Quality Control Systems
Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Global Mist Eliminator Market
Air Quality Control Systems
Southeast Asia Air Purifier Market
Air Quality Control Systems
Industrial Air Quality Control Systems Market
Air Quality Control Systems
Desiccant Air Breather Market
Air Quality Control Systems
Anti-Pollution Toner Market
Air Quality Control Systems
Environment Controllers Market
Air Quality Control Systems
United States Pollution Mask Market
Air Quality Control Systems
Ozone Analyzer Market
Air Quality Control Systems
Air Pollution Control Equipment Market
Air Quality Control Systems
Air Quality Control Systems Market
Air Quality Control Systems
Indoor Air Purification Market
Air Quality Control Systems
Anti-Pollution Mask Market
Air Quality Control Systems
Emission Management Software Market
Air Quality Control Systems
North America Industrial Air Quality Control Systems Market