
 Nitrogen Oxide Control Systems Market | 2026-2036
Nitrogen Oxide Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Nitrogen Oxide Control Systems Market Analysis
Zeolite-based catalyst formulations is restructuring procurement economics for selective catalytic reduction units, trimming replacement cycles and reducing vanadium price exposure. Mitsubishi Heavy Industries leverages integrated engineering capabilities to anchor large power-plant retrofit programs across East Asia. Johnson Matthey plc specializes in advanced catalytic coatings that differentiate its offerings in marine and industrial exhaust applications. BASF SE controls upstream zeolite supply chains, extending cost advantages to OEM partners in the transportation segment.
Nitrogen oxide control systems are engineered exhaust-gas treatment assemblies that inject reductants such as ammonia or urea into flue streams, using catalyst beds or thermal processes to convert NO and NO₂ into nitrogen and water vapor at operating temperatures between 150°C and 450°C. Selective catalytic reduction dominates installed capacity due to its efficiency above 90% in heavy-duty diesel and stationary power applications, while exhaust gas recirculation commands the fastest growth in marine propulsion as IMO Tier III standards tighten. Retrofit systems capture concentrated margin pools in aging coal and industrial boiler fleets where space constraints and downtime windows favor modular, skid-mounted designs over greenfield integrated solutions.
The US EPA enforces NOx emission caps under the Clean Air Act, mandating continuous emissions monitoring and best available control technology for utilities and industrial boilers, while the EU F-Gas Regulation and Industrial Emissions Directive tighten catalyst leakage and ammonia slip standards across member states. China's MEE administers ultra-low emission standards for thermal power that require SCR upgrades on units above 65 MW, directly shaping procurement volumes for domestic and foreign suppliers. Stakeholders must monitor evolving catalyst disposal regulations and ammonia supply security as dual constraints on project returns and operational continuity.
Market Dynamics
The transition from vanadium-based to zeolite-based selective catalytic reduction catalysts is compressing replacement cycles and decoupling operating costs from volatile vanadium markets, fundamentally restructuring procurement economics for power utilities and industrial operators.
Growth Catalysts
- China's MEE ultra-low emission standards:Thermal power units above 65 MW face mandatory SCR upgrades, generating sustained procurement volumes for catalyst suppliers and system integrators.
- IMO Tier III marine standards:Exhaust gas recirculation installations are accelerating across oceangoing vessels as shipyards retrofit propulsion systems to meet nitrogen oxide limits in emission control areas.
- Industrial boiler oversight expansion:Indonesia and India are tightening stack-monitoring requirements for cement, steel, and chemical facilities, forcing adoption of continuous emissions monitoring paired with SCR or SNCR systems.
Market Restraints
- Vanadium price volatility:Legacy catalyst formulations remain exposed to ferrovanadium supply disruptions from South African and Russian mining operations, creating margin pressure for operators delaying zeolite transitions.
- Ammonia supply security:Urea-to-ammonia conversion infrastructure concentrates in agricultural demand centers, leaving power utilities vulnerable to seasonal pricing spikes and transport bottlenecks.
- Catalyst disposal regulations:The EU F-Gas Regulation and emerging national frameworks classify spent zeolite and vanadium catalysts as hazardous waste, adding compliance costs and landfill restrictions.
Strategic Opportunities
- Modular skid-mounted retrofits:Aging coal fleets in Poland and Germany face space-constrained installation windows, favoring pre-assembled SCR units over integrated greenfield designs.
- Green hydrogen-ammonia convergence:Electrolyzer-produced ammonia for power sector denitrification is attracting pilot investments in Denmark and the Netherlands as carbon border adjustments tighten.
- Marine dual-fuel engines:LNG-propelled vessels operating on high-pressure injection cycles require specialized low-temperature SCR catalysts, opening premium product tiers.
Industry Challenges
- Catalyst engineering specialization:Zeolite formulation expertise concentrates among materials scientists with rare earth and molecular sieve backgrounds, creating recruitment bottlenecks for OEMs.
- Continuous emissions monitoring integration:Retrofitting CEMS hardware onto legacy boiler architectures demands custom ductwork and control system interfaces, extending commissioning timelines.
- Cross-border catalyst transport:Basel Convention hazardous waste classifications complicate international returns of spent catalyst cores for precious metal recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitrogen Oxide Control Systems Market |
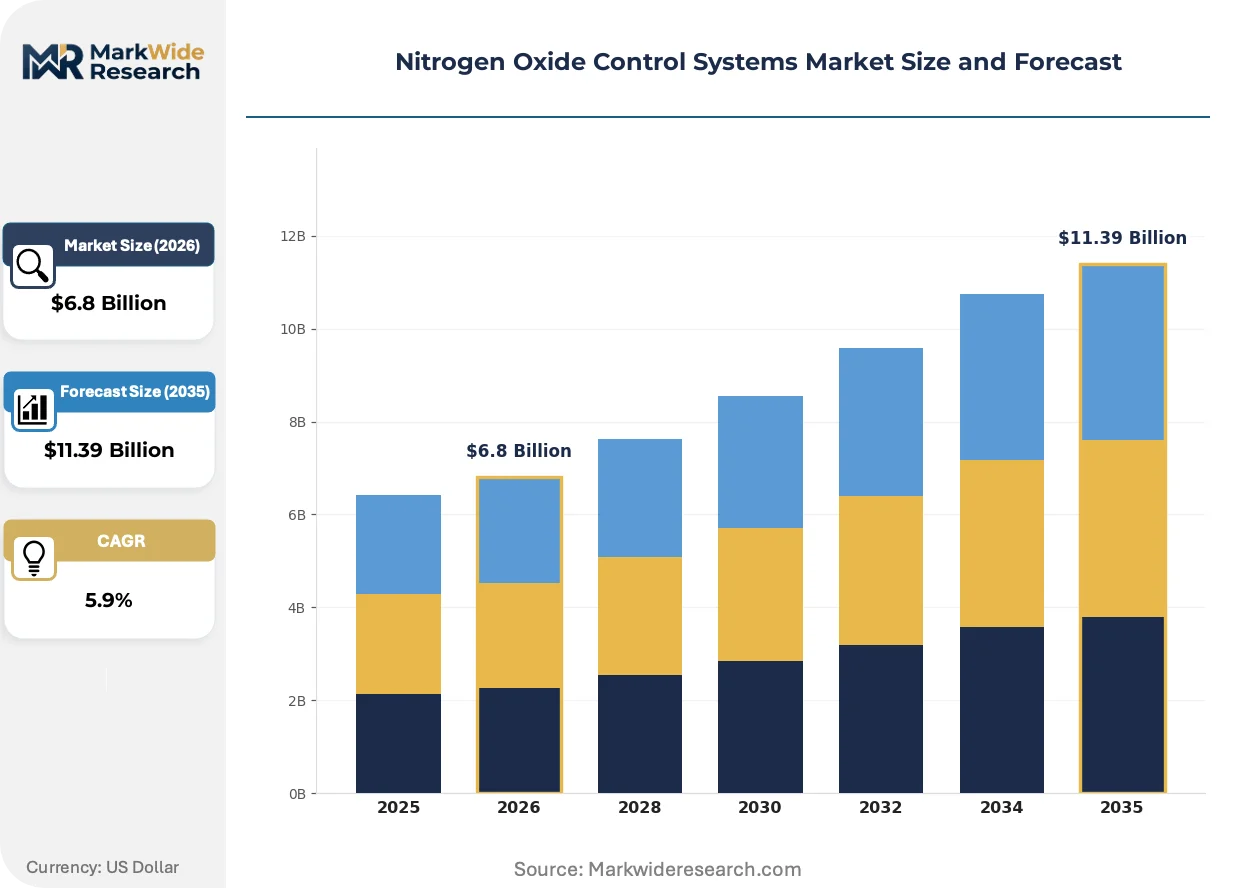
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Selective Catalytic Reduction, Non-Catalytic Reduction, Oxidation Catalyst, Exhaust Gas Recirculation End User: Industrial, Transportation, Power Generation, Marine Product Type: Standalone Systems, Integrated Solutions, Retrofit Systems, Testing Equipment Application: Automotive, Industrial Processes, Energy Production, Aerospace |
| Companies Covered | Mitsubishi Heavy Industries, Ltd., Hitachi Zosen Corporation, Johnson Matthey plc, CECO Environmental, Siemens AG, BASF SE, Babcock & Wilcox Enterprises, Inc., Fuel Tech, Haldor Topsoe A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitrogen Oxide Control Systems Market Emerging Trajectories
Zeolite-based catalyst formulations, modular retrofit architectures, and ammonia supply chain diversification are converging to compress total cost of ownership and expand addressable markets beyond traditional utility procurement.
Ceramic honeycomb substrates with copper-CHA zeolite coatings are decentralizing the supplier base for selective catalytic reduction units. Industrial boiler operators and smaller power generators are sourcing these catalysts from regional manufacturers rather than integrated OEMs, fragmenting procurement patterns and compressing replacement service margins for incumbent system providers.
The EU F-Gas Regulation is tightening leakage standards for fluorinated greenhouse gases used in catalyst manufacturing processes. This industrial consequence is forcing reformulation of binder chemistries and accelerating REACH-compliant alternatives, with marine SCR suppliers facing the steepest compliance timelines due to IMO alignment pressures.
Long-term catalyst management contracts are displacing spot replacement purchases among European power utilities. These performance-guaranteed arrangements bundle monitoring, replacement scheduling, and spent catalyst logistics, concentrating buyer leverage with integrated service providers and squeezing standalone catalyst merchants in Germany and the United Kingdom.
Nitrogen Oxide Control Systems Market Segmentation
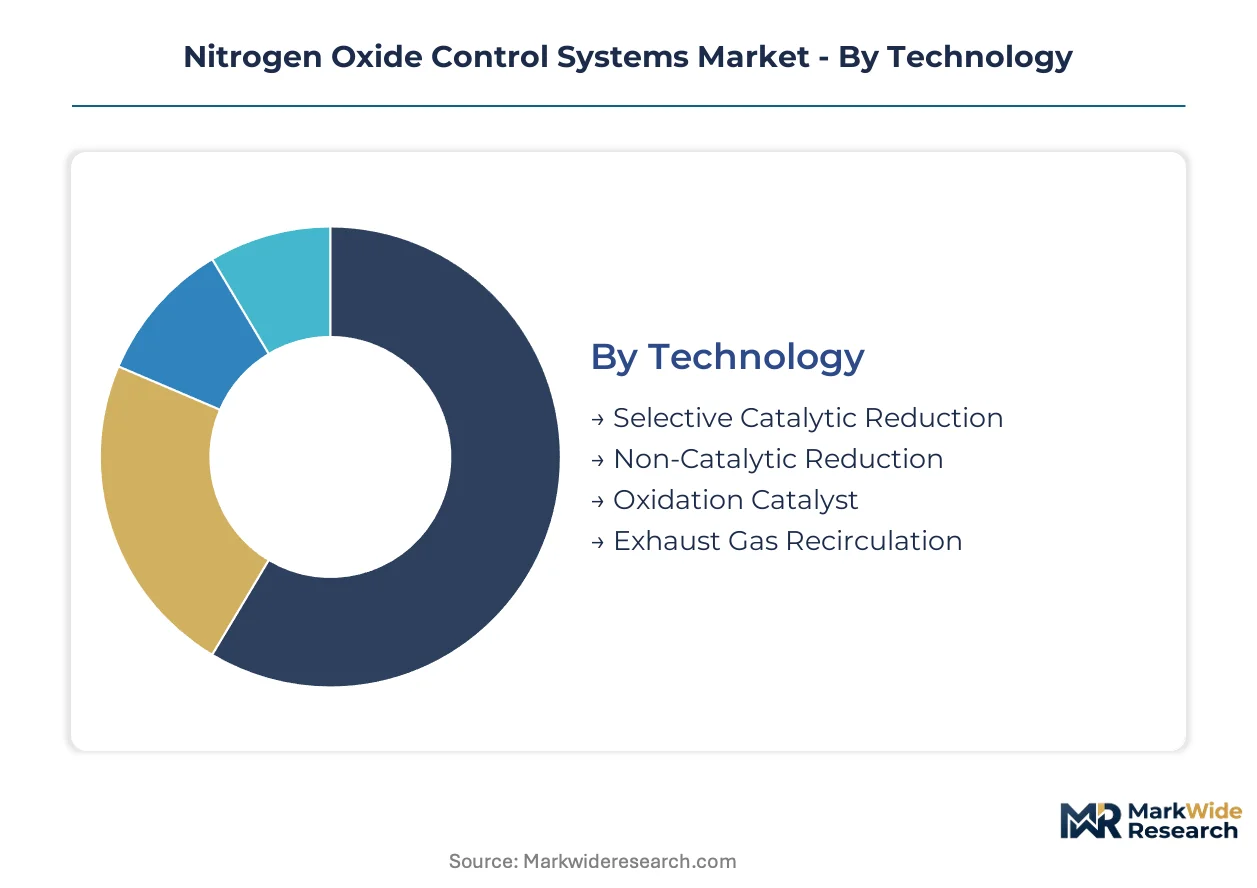
Technology choices in nitrogen oxide control systems dictate replacement cycles, catalyst procurement patterns, and total cost of ownership across power utilities, marine operators, and industrial facilities. Segment-specific engineering requirements create divergent margin structures and vendor selection criteria that reshape competitive positioning in each vertical.
Technology:
Upgrade and replacement-cycle dynamics vary dramatically across catalytic and non-catalytic approaches, with catalyst formulation shifts compressing maintenance intervals for some operators while extending asset life for others.
- Selective Catalytic Reduction:Zeolite-based formulations operating between 150°C and 450°C achieve conversion efficiencies above 90% in heavy-duty diesel and stationary power applications. Power generation utilities across China and India dominate procurement volumes as MEE ultra-low emission standards mandate retrofits on thermal units above 65 MW.
- Exhaust Gas Recirculation:Thermal management systems redirect cooled exhaust gases into combustion chambers to suppress NOx formation at source temperatures. Marine propulsion installations are accelerating fastest as IMO Tier III standards tighten in emission control areas, with shipyards in South Korea and Japan retrofitting oceangoing vessels.
- Non-Catalytic Reduction:Urea or ammonia injection without catalyst beds operates at 850°C to 1100°C, suited to cement and steel kilns where particulate loads poison SCR catalysts.
- Oxidation Catalyst:Platinum-group metal coatings convert NO to NO₂ upstream of particulate filters in diesel aftertreatment trains.
Selective Catalytic Reduction sits at the top of the volume ranking, with Exhaust Gas Recirculation climbing the fastest.
End User:
Cost tier differentiation separates capital-intensive greenfield installations from modular retrofit approaches, with procurement authority concentrating differently across utility procurement offices, marine technical departments, and industrial facility managers.
- Power Generation:Coal and gas-fired utilities operate continuous-duty SCR systems with 5-7 year catalyst replacement cycles. Procurement concentrates among integrated engineering firms capable of delivering turnkey flue-gas treatment islands.
- Marine:Dual-fuel LNG vessels require specialized low-temperature catalyst formulations for high-pressure injection cycles. Shipowners face compressed installation windows in drydock schedules.
- Industrial:Cement, steel, and chemical facilities deploy SNCR for high-dust environments where catalyst poisoning risks outweigh efficiency gains.
- Transportation:Heavy-duty diesel OEMs specify compact SCR assemblies meeting EPA and EU Stage V emission limits.
Power Generation commands the largest installed base, while Marine applications are expanding most quickly.
Product Type:
Application context determines whether operators favor pre-engineered modular units or custom-integrated architectures, with aging infrastructure and space constraints driving format selection.
- Retrofit Systems:Skid-mounted SCR units designed for constrained installation windows in aging coal fleets. Space limitations and downtime restrictions in Poland and Germany favor pre-assembled designs over field-constructed alternatives.
- Integrated Solutions:Greenfield power plants specify SCR reactors, ammonia storage, and CEMS hardware as unified procurement packages. System integrators capture long-term service contracts bundling catalyst management and emissions compliance.
- Standalone Systems:Smaller industrial boilers source catalyst cartridges and injection skids separately from regional suppliers.
- Testing Equipment:Continuous emissions monitoring hardware and portable analyzers support regulatory compliance verification.
Integrated Solutions dominate new-build procurement, with Retrofit Systems gaining share fastest in European and Asian coal fleet upgrades.
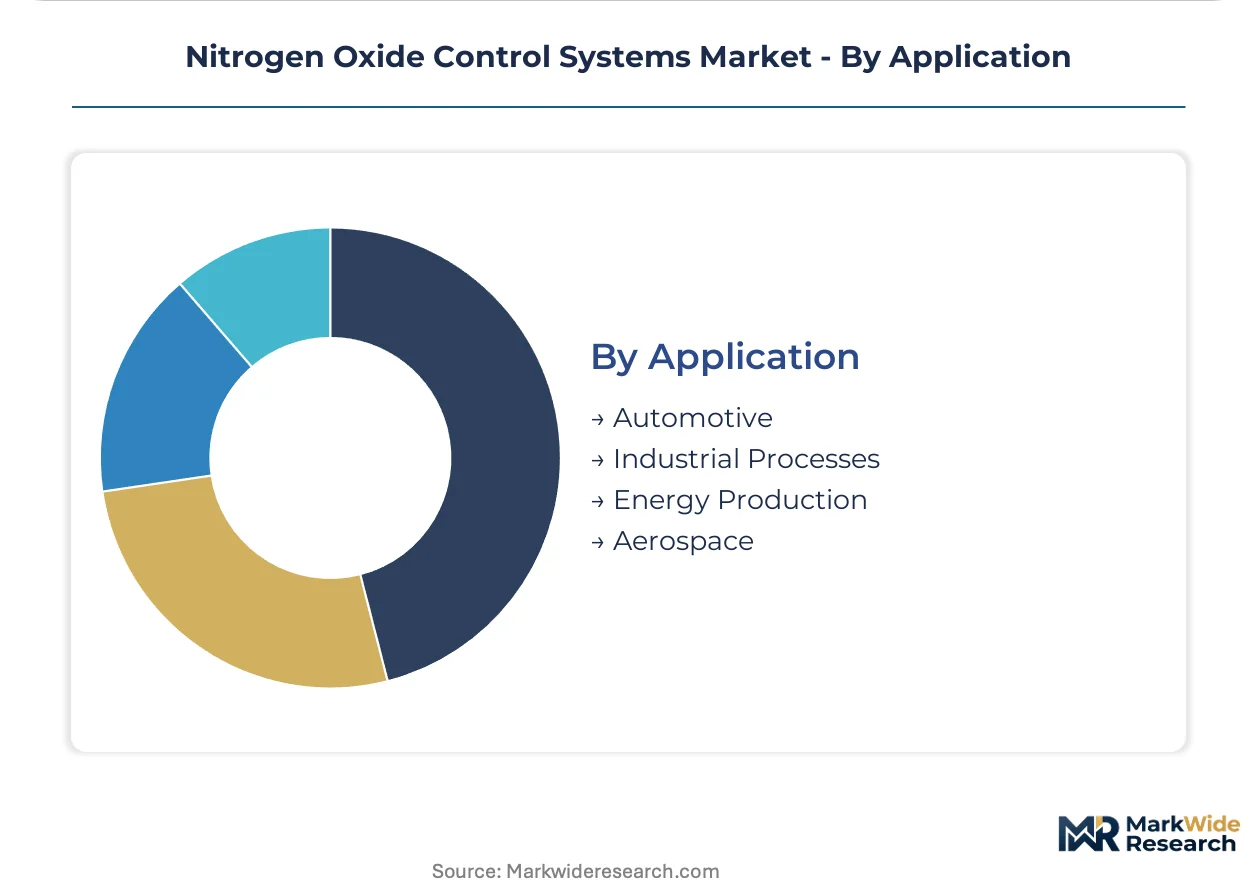
Application:
Customer type and operational intensity create divergent performance requirements, with automotive volume scale contrasting against aerospace specification exactitude.
- Energy Production:Utility-scale thermal power plants operate the largest individual SCR installations, with catalyst volumes measured in hundreds of cubic meters per unit. China's MEE enforcement drives sustained replacement demand.
- Industrial Processes:Cement kilns, glass furnaces, and chemical crackers face unique temperature and particulate profiles requiring customized injection grid designs.
- Automotive:On-road and off-road diesel engines specify compact, vibration-resistant SCR assemblies with urea dosing integrated into engine control modules.
- Aerospace:Auxiliary power units and ground support equipment face stringent weight and volume constraints.
Energy Production leads by installed capacity, with Industrial Processes showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors procurement volumes as China's MEE enforces ultra-low emission retrofits on thermal units above 65 MW. Catalyst suppliers and system integrators concentrate engineering resources in Shanghai and Jiangsu province to capture replacement demand from aging coal fleets.
China
Power generation utilities in Jiangsu and Shandong provinces drive zeolite-based SCR catalyst procurement as MEE ultra-low emission standards mandate stack upgrades. The country's national environmental regulator enforces continuous emissions monitoring on units above 65 MW. Shanghai-based engineering clusters coordinate turnkey flue-gas treatment installations for domestic coal-fired fleets.
United States
Midwestern coal utilities and Gulf Coast petrochemical complexes sustain demand for modular retrofit SCR systems. The EPA enforces NOx emission caps under the Clean Air Act, requiring best available control technology for utilities and industrial boilers. Houston and Chicago industrial corridors host concentrated procurement activity for catalyst replacement and ammonia storage infrastructure.
Germany
Aging lignite and hard coal fleets in North Rhine-Westphalia favor skid-mounted SCR retrofits constrained by limited outage windows. The EU F-Gas Regulation tightens catalyst leakage and ammonia slip standards across member states. The Rhine-Ruhr industrial cluster generates concentrated demand for continuous emissions monitoring integration onto legacy boiler architectures.
India
Thermal power stations in Gujarat and Maharashtra expand flue-gas treatment capacity to meet tightened stack-emission limits. The Central Electricity Authority mandates emission control upgrades for coal units in designated critically polluted areas. The Mundra and Trombay generation clusters anchor procurement volumes for domestic and foreign catalyst suppliers.
Indonesia
Cement and steel facilities in Java face expanding stack-monitoring requirements forcing adoption of SNCR and SCR systems. The country's national environmental ministry tightens industrial boiler oversight for heavy industry sectors. The Cilegon industrial estate on Banten Bay concentrates demand for continuous emissions monitoring paired with reductant injection systems.
Nitrogen Oxide Control Systems Market Vendor Landscape
Strategic partnerships dominate the current landscape as catalyst formulators align with system integrators to bundle hardware and chemistry procurement. The vendor base concentrates among integrated engineering conglomerates, specialized materials scientists, and regional fabrication specialists. Three archetypes define positioning: upstream zeolite suppliers controlling molecular sieve supply chains, turnkey system integrators delivering flue-gas treatment islands, and standalone catalyst merchants facing margin compression from long-term management contracts. Geographic expansion and technology licensing represent the dominant competitive vectors as Asian demand outpaces European replacement cycles.
Within the integrated engineering tier, Mitsubishi Heavy Industries and Hitachi Zosen exemplify conglomerates leveraging captive construction capabilities to anchor large power-plant retrofit programs. Johnson Matthey plc occupies a position representing specialized materials science expertise in advanced catalytic formulations. BASF SE anchors the upstream chemical supply tier through zeolite production scale. These three demonstrate how competitive positioning separates conglomerate project execution, materials specialization, and supply chain control into distinct value-capture layers.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries, Ltd. |
| Hitachi Zosen Corporation |
| Johnson Matthey plc |
| CECO Environmental |
| Siemens AG |
| BASF SE |
| Babcock & Wilcox Enterprises, Inc. |
| Fuel Tech |
| Haldor Topsoe A/S |
| Others |
Supply Flow & Price Mechanics
Captive zeolite production by BASF SE and Johnson Matthey plc anchors both supply security and pricing power for premium catalyst formulations, insulating integrated suppliers from ferrovanadium volatility while compressing margins for standalone merchants dependent on spot molecular sieve procurement.
Pricing Analysis
Input-cost pass-through from rare earth and molecular sieve markets shapes contract structures for SCR catalyst procurement. Three-tier pricing structure across premium, standard, and economy levels separates copper-CHA zeolite coatings from legacy vanadium formulations and basic ceramic honeycomb substrates. Pricing pressure stems from regional manufacturers in China fragmenting procurement patterns for industrial boiler operators. Cement and steel facilities exhibit highest price sensitivity due to SNCR workarounds, while marine dual-fuel engine operators accept premium tiers for IMO Tier III compliance.
Supply Chain Analysis
REACH and EU F-Gas Regulation certification requirements gate catalyst manufacturing access, concentrating qualified production among German, Japanese, and Chinese facilities with molecular sieve synthesis capabilities. Supply chains draw from South African and Russian ferrovanadium, Chinese rare earth processing, and German specialty chemical binders. Single-source vulnerability concentrates in zeolite precursor supply, with limited qualified alternatives for copper-CHA formulations. Distribution runs through integrated engineering conglomerates for power utility procurement and regional fabricators for smaller industrial boiler operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zeolite formulation transitions compress replacement cycles and extend catalyst life, expanding service margins for suppliers capturing long-term management contracts while squeezing spot-market merchants.
For Market Incumbents: Anchor market position through backward integration into zeolite synthesis and captive ammonia storage infrastructure. Mitsubishi Heavy Industries demonstrates project execution leverage across East Asian power retrofits. Defend against regional Chinese manufacturers by bundling continuous emissions monitoring with catalyst replacement scheduling under performance-guaranteed arrangements. For New Entrants and Emerging Players: The price-point gap between premium marine SCR systems and economy industrial boiler cartridges opens white-space targets in mid-tier cement and steel SNCR conversions. Indonesia's Cilegon industrial estate and India's Mundra cluster present penetrable geographies with tightening stack-monitoring requirements. Pursue licensing partnerships with established zeolite formulators rather than greenfield R&D investment. For Investors and Strategic Acquirers: Roll-up economics work for regional catalyst service providers because long-term management contracts concentrate buyer leverage and squeeze standalone merchants. Five-to-ten year viability hinges on ammonia supply chain diversification and green hydrogen convergence pilots. Watch Denmark and Netherlands electrolyzer-to-ammonia investments as inflection indicators for power sector denitrification cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zeolite Synthesis | BASF SE's molecular sieve control extends cost advantages to OEM partners in transportation. |
| Modular Skid-Mounted Retrofit Deployment | Pre-assembled SCR units capture margin pools in Poland and Germany's space-constrained coal fleets. |
| Long-Term Catalyst Management Contracts | Performance-guaranteed bundles displace spot purchases among European power utilities. |
| Green Hydrogen-Ammonia Convergence Pilots | Electrolyzer-produced ammonia attracts investment as EU carbon border adjustments tighten. |
| Marine Dual-Fuel Engine Specialization | LNG-propelled vessels require low-temperature SCR catalysts opening premium product tiers. |
Methodological Framework
Bottom-up power utility and marine operator modeling reconciled against top-down catalyst production tracking forms the analytical core of this study. Primary interviews with plant engineers, SCR system procurement leads, EPC contractors, and aftermarket service heads combine with secondary validation from EPA enforcement databases, China MEE emission standard filings, IMO technical circulars, and customs trade records for zeolite and ferrovanadium flows. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of replacement cycles, retrofit installation rates, and catalyst formulation shifts informs projection mechanics across the modeling period. Segmentation dimensions include technology type, end-user vertical, product format, and regional regulatory cluster. CAGRs derive from regression against enforcement timeline intensity and fleet age demographics. Forecast inputs incorporate China's MEE unit-by-unit retrofit mandates and IMO Tier III emission control area expansion schedules.
Caveats apply where vanadium price volatility, ammonia supply disruptions, or catalyst disposal regulation tightening could materially shift the outlook. Forecasts reflect assumptions around enforcement consistency and technology transition rates. A model refresh is warranted upon material change in EU F-Gas Regulation implementation timelines or China MEE inspection intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Air Quality Control Systems Market
Air Quality Control Systems
Global Mist Eliminator Market
Air Quality Control Systems
Asia Pacific Air Filtration Market
Air Quality Control Systems
Green Emissions Analyzers Market
Air Quality Control Systems
Desiccant Air Breather Market
Air Quality Control Systems
Ozone Generation Market
Air Quality Control Systems
Southeast Asia Air Purifier Market
Air Quality Control Systems
Anti-Pollution Toner Market
Air Quality Control Systems
Anti-Pollution Mask Market
Air Quality Control Systems
Europe Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Environment Controllers Market
Air Quality Control Systems
Europe Industrial Air Quality Control Systems Market
Air Quality Control Systems
UV Air Purifiers Market
Air Quality Control Systems
Ozone Analyzer Market
Air Quality Control Systems
Asia-Pacific Indoor Air Purification Market
Air Quality Control Systems
Air Pollution Control Systems Market