
 Air Scrubber Market | 2026-2036
Air Scrubber Market Size, Share, and Industry Trends Forecast 2026-2036
Air Scrubber Market Outlook
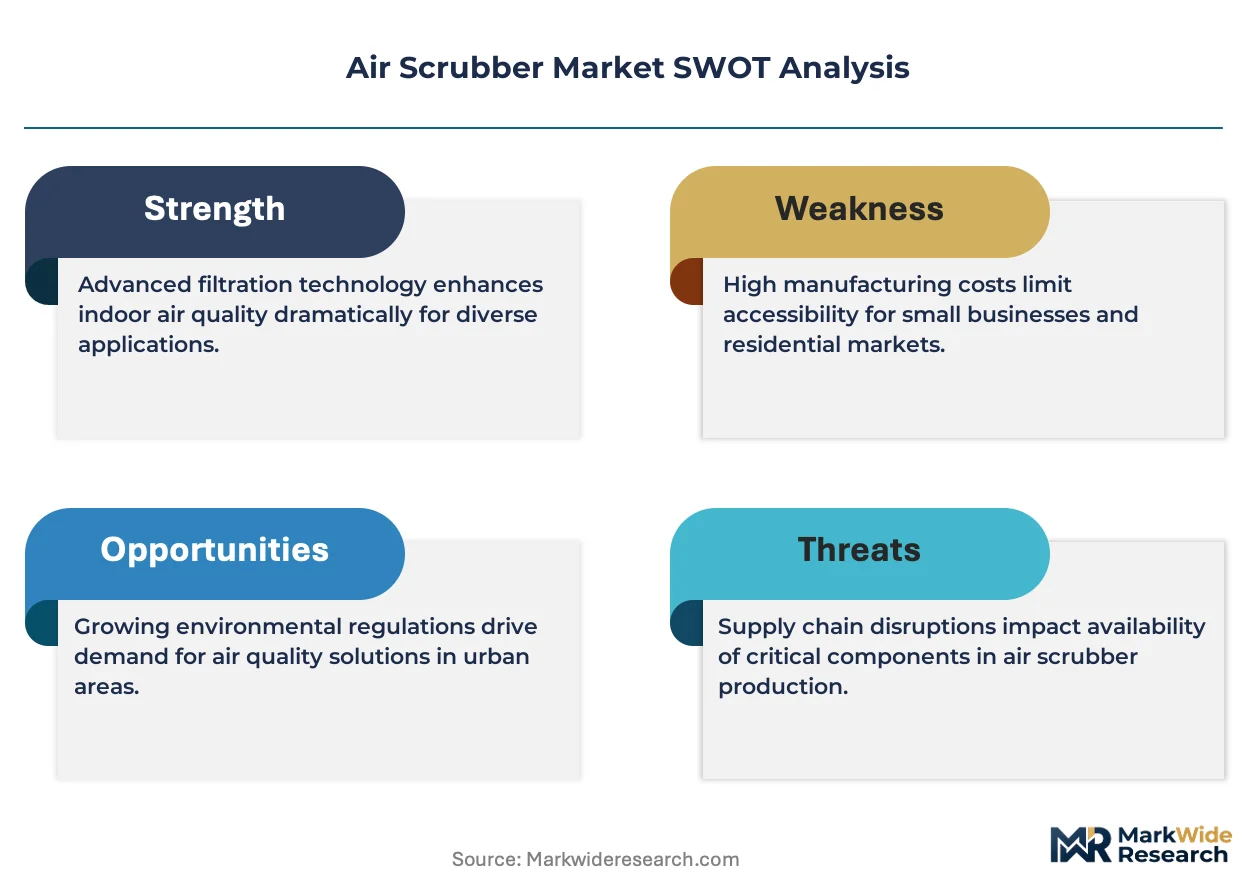
The EPA's National Emission Standards for Hazardous Air Pollutants is restructuring compliance timelines for American industrial operators, forcing accelerated capital deployment into scrubber infrastructure. Honeywell International, Inc. leverages its building automation integration to bundle air scrubbers with HVAC controls, while Daikin Industries, Ltd. anchors its position through captive compressor technology that reduces system footprint. Camfil AB specializes in filter media manufacturing, giving it upstream control over replacement revenue cycles.
An air scrubber is a mechanical air purification device that forces contaminated air through filtration media—typically HEPA filters rated at 99.97% efficiency for 0.3-micron particles—or chemical absorption beds to remove particulates, gases, or biological contaminants from enclosed environments. The primary purpose spans industrial emissions control, indoor air quality management, and pathogen containment in sensitive facilities. Portable air scrubbers command premium pricing in remediation and construction verticals where mobility outweighs throughput, while ducted systems dominate healthcare facilities because centralized infrastructure amortizes maintenance across larger square footage. HEPA filtration technology leads volume but UV-C light integration is capturing margin pools in hospital-grade specifications.
OSHA ventilation requirements for general industry workplaces, EPA NESHAP enforcement for hazardous air pollutants, and the EU F-Gas Regulation restricting fluorinated greenhouse gases collectively tighten product certification thresholds and expand addressable market scope. The EU AI Act's building management system provisions will eventually require scrubber-integrated sensor networks to document air quality compliance automatically. Stakeholders must monitor how overlapping EPA, OSHA, and state-level mandates fragment procurement specifications and whether filter standard harmonization emerges across North American and European certification bodies.
Market Dynamics
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is compressing compliance timelines for American industrial operators, forcing capital redeployment into scrubber infrastructure ahead of scheduled facility reviews. This regulatory pressure cascades through procurement specifications, filter certification thresholds, and aftermarket service contracts.
Growth Catalysts
- Healthcare ventilation mandates:Joint Commission standards for hospital air changes per hour are expanding HEPA system procurement across United States acute care facilities.
- MEE provincial directives:China's Ministry of Ecology and Environment mandates scrubber installations at chemical and electronics manufacturing plants in Jiangsu and Guangdong provinces.
- Filter media innovation:Nanofiber-coated substrates are extending HEPA replacement cycles while maintaining 99.97% efficiency ratings at 0.3-micron capture.
Market Restraints
- Specialized filter supply concentration:Glass microfiber media production concentrates among a limited set of European and Japanese substrate manufacturers.
- Fluorinated gas restrictions:EU F-Gas Regulation is phasing out refrigerants used in certain scrubber-integrated HVAC systems, complicating retrofit compatibility.
- Activated carbon cost volatility:Bituminous coal and coconut shell feedstock prices fluctuate with energy commodity cycles, pressuring chemical absorption bed economics.
Strategic Opportunities
- EU AI Act building provisions:Automated air quality documentation requirements will mandate scrubber-integrated sensor networks across European commercial real estate.
- UV-C convergence:Ultraviolet germicidal irradiation modules are merging with HEPA filtration to capture margin pools in hospital-grade specifications.
- Portable remediation demand:Construction and mold remediation contractors in the United States are expanding rental fleets for mobile air scrubbing units.
Industry Challenges
- Certification timeline compression:Overlapping EPA, OSHA, and state-level mandates fragment product testing requirements, extending time-to-market for new scrubber models.
- Legacy HVAC integration friction:Ducted scrubber retrofits require pressure-drop calculations and fan capacity upgrades in aging United States commercial building stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Scrubber Market |
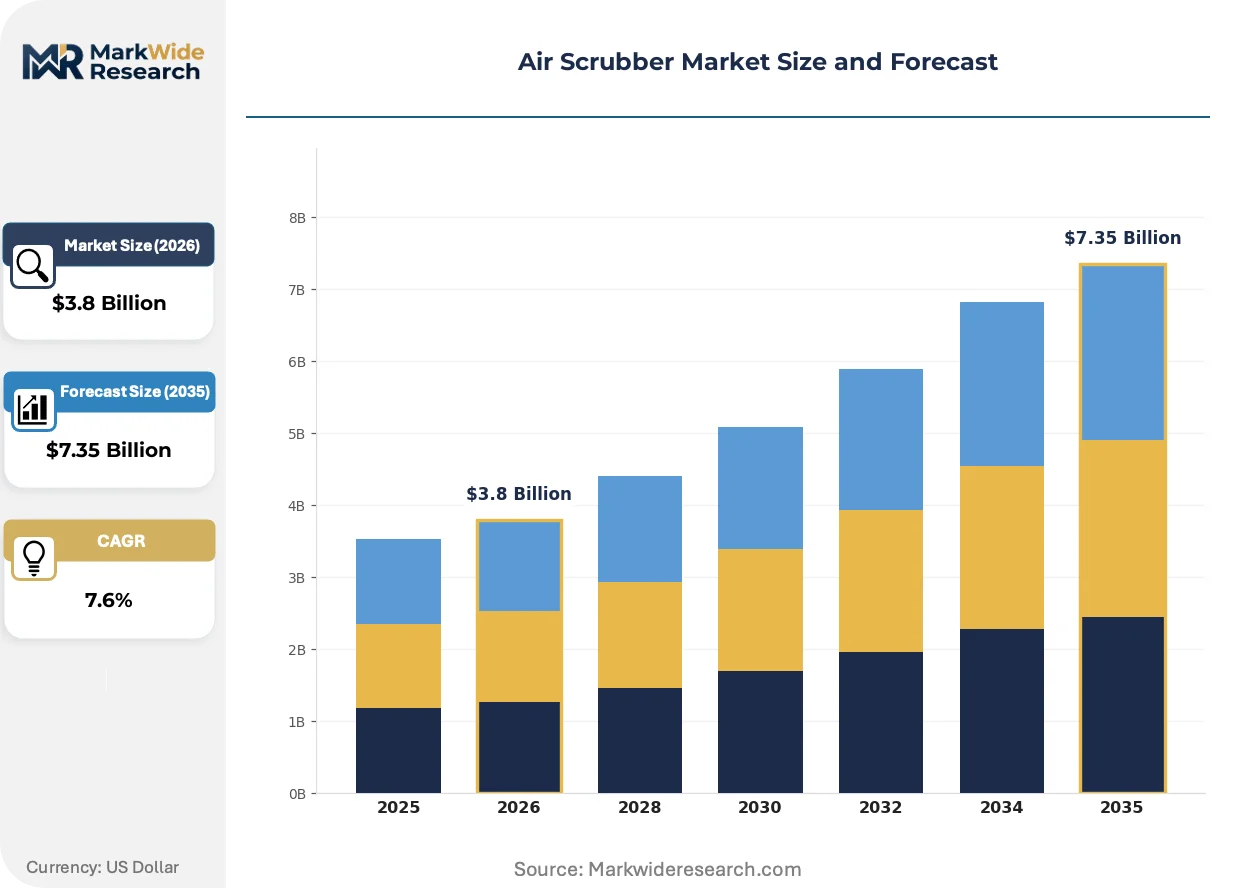
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Air Scrubbers, Wall-Mounted Units, Ducted Systems, Standalone Units Technology: HEPA Filtration, Activated Carbon, UV-C Light, Electrostatic Precipitation Application: Industrial Use, Residential Use, Commercial Spaces, Healthcare Facilities End User: Manufacturers, Homeowners, Office Buildings, Hospitals |
| Companies Covered | Camfil AB, Honeywell International, Inc., Daikin Industries, Ltd., Novatek Corporation, Amaircare Corporation, Advanced Air Technologies Inc., Croll Reynolds, Inc., Abatement Technologies, Parker Hannifin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Scrubber Market Strategic Shifts
Electrochemical and catalytic oxidation technologies are expanding into industrial emissions applications previously served by thermal oxidizers. Filter media chemistry, sensor integration, and service contract structures are all shifting in response.
Photocatalytic oxidation is expanding into volatile organic compound destruction at semiconductor fabrication facilities. Taiwan and South Korea fabs are piloting titanium dioxide-coated reactors for formaldehyde and isopropyl alcohol abatement. This technology is expanding into applications where thermal oxidizer fuel costs and carbon intensity create displacement pressure.
REACH authorization procedures for chromium compounds are restricting hexavalent chromium use in certain scrubber corrosion-resistant coatings. European manufacturers are reformulating with trivalent alternatives or nickel-based alloys. The metal finishing and chemical processing verticals face accelerated coating replacement cycles and supplier qualification burdens.
Hospital procurement departments are unbundling filter replacement service contracts from initial equipment purchases. United States health systems now separately negotiate multi-year filter supply agreements with specialized distributors. This shift compresses OEM aftermarket margins while expanding addressable market scope for independent filter media specialists.
Air Scrubber Market Segmentation
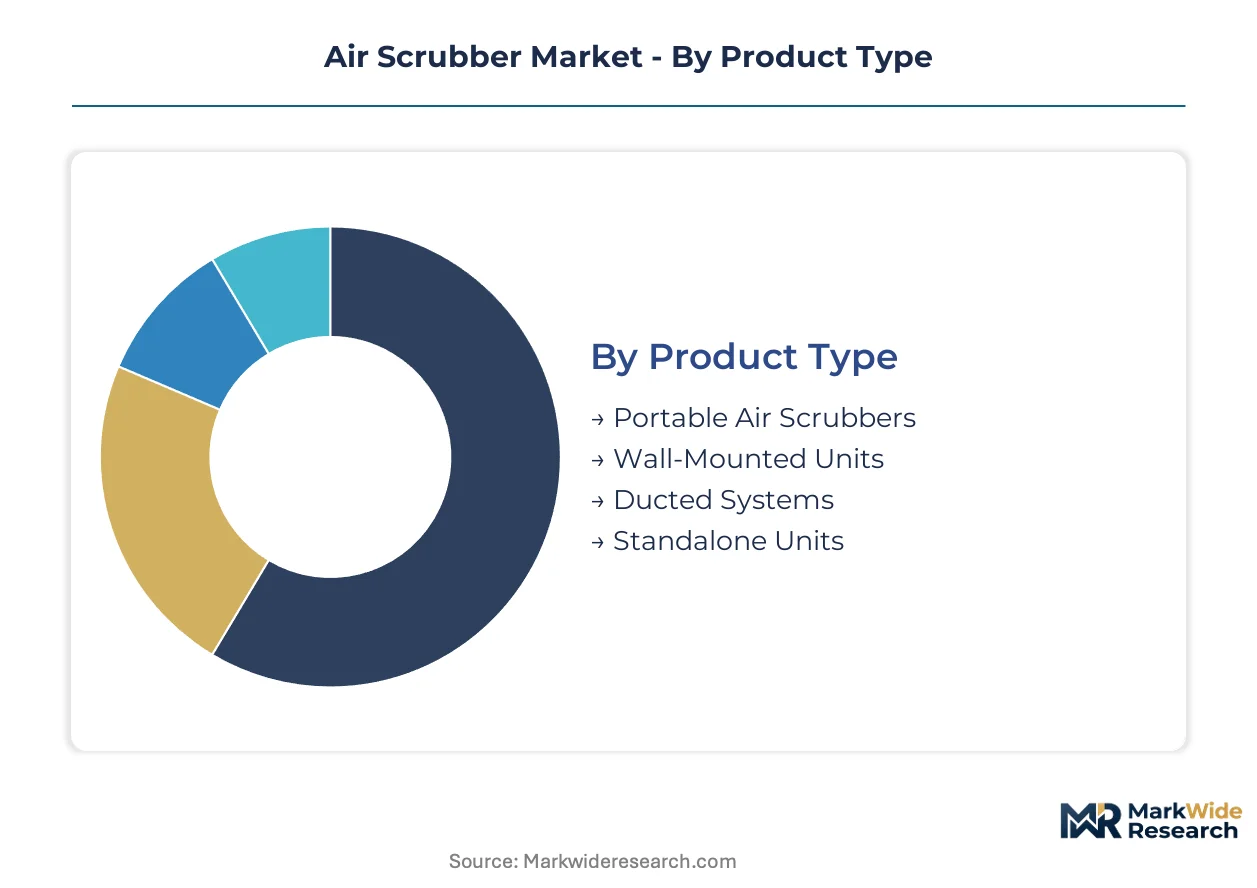
Air scrubber procurement patterns diverge sharply across installation formats and contamination targets. Replacement cycles, spatial constraints, and regulatory compliance thresholds reshape how buyers evaluate product categories and technology tiers.
Product Type:
Upgrade trajectories hinge on whether facilities need mobility for episodic remediation or permanent infrastructure for continuous air changes.
- Ducted Systems:Centralized units integrate with HVAC infrastructure to distribute filtered air across large square footage. United States hospital systems prioritize these for Joint Commission compliance, amortizing maintenance costs across entire wings rather than room-by-room deployments.
- Portable Air Scrubbers:Mobile units on casters or skids serve remediation contractors and construction sites where contamination sources shift. United States mold abatement specialists and disaster restoration firms expand rental fleets to avoid capital deployment on short-duration projects.
- Wall-Mounted Units:Semi-permanent installations suit classrooms, small offices, and clinic waiting areas with limited floor space. These bridge the gap between portable flexibility and ducted permanence.
- Standalone Units:Self-contained floor models target residential and light commercial settings without existing ductwork. Retail channels and direct-to-consumer distribution dominate this tier.
Volume placements concentrate in ducted systems; the faster expansion belongs to portable air scrubbers.
Technology:
Filter media chemistry and energy consumption patterns separate premium specifications from commodity tiers.
- HEPA Filtration:Glass microfiber media rated at 99.97% efficiency for 0.3-micron particles remains the clinical standard. China's Jiangsu province electronics fabs and United States acute care facilities mandate this grade for particulate control, driving replacement revenue through scheduled media swaps.
- UV-C Light:Ultraviolet germicidal irradiation at 254 nanometers destroys viral and bacterial nucleic acids. Hospital procurement departments in the United States increasingly specify UV-C modules as add-ons to HEPA bases, capturing margin pools in infection control budgets.
- Activated Carbon:Bituminous coal or coconut shell substrates adsorb volatile organic compounds and odorous gases. Chemical processing plants and cannabis cultivation facilities deploy these beds for molecular contamination.
- Electrostatic Precipitation:Charged plates capture particles without pressure drop penalties of dense media. Industrial metalworking and welding operations favor these for high-dust loads where filter replacement costs would escalate.
Revenue concentrates in HEPA-plus-UV-C configurations; activated carbon applications climb fastest on chemical emissions enforcement.
Application:
Contamination source intensity and occupant vulnerability dictate specification stringency and service contract structures.
- Healthcare Facilities:Operating rooms, isolation wards, and compounding pharmacies require continuous HEPA filtration with documented air changes per hour. The Joint Commission and CMS conditions of participation enforce these standards across United States acute care networks.
- Industrial Use:Semiconductor fabrication, chemical synthesis, and metal finishing generate concentrated hazardous emissions. EPA NESHAP enforcement and China's MEE provincial directives compel scrubber retrofits at existing plants.
- Commercial Spaces:Offices, retail, and hospitality venues prioritize occupant comfort and liability reduction over clinical-grade specifications. Post-pandemic lease negotiations increasingly include air quality clauses.
- Residential Use:Single-family homes and apartments represent price-sensitive demand with minimal regulatory drivers. Wildfire smoke events in western United States states periodically spike portable unit sales.
Capital deployment concentrates in industrial compliance; healthcare upgrades show the steepest specification escalation.
End User:
Procurement sophistication and total cost of ownership horizons vary dramatically across buyer types.
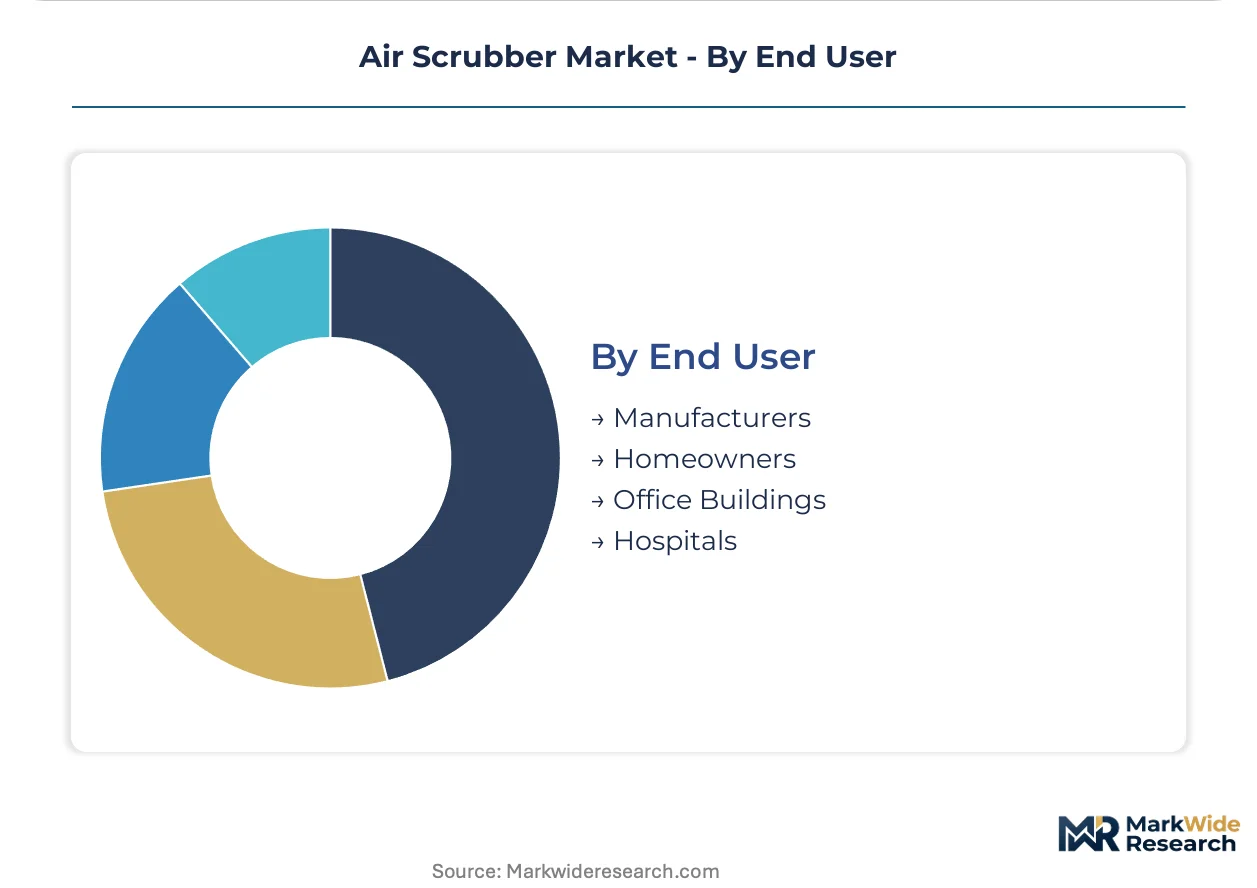
- Hospitals:Health system supply chains negotiate multi-year filter replacement contracts separately from equipment purchases, compressing OEM aftermarket margins while expanding independent distributor scope.
- Manufacturers:Chemical, electronics, and automotive plants face EPA and MEE enforcement timelines that accelerate capital approval cycles for emissions control infrastructure.
- Office Buildings:Property managers weigh tenant retention against energy costs, often selecting mid-tier specifications unless Class A positioning demands premium systems.
- Homeowners:Individual purchasers respond to episodic triggers—wildfires, pandemic waves, allergy seasons—rather than systematic replacement schedules.
Contract value concentrates in hospital and manufacturing accounts; homeowner volume fluctuates with environmental events.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangtze River Delta electronics corridor drives scrubber procurement as semiconductor fabs expand cleanroom capacity. Chemical processing clusters in Germany's Ruhr region and automotive paint shops in Detroit-Windsor accelerate HEPA system deployment. Healthcare construction booms in Riyadh and São Paulo reshape ventilation specifications across mid-market hospital networks.
United States
Hospital systems in Texas and Florida expand HEPA infrastructure to meet Joint Commission air-change mandates. EPA NESHAP enforcement compresses retrofit timelines at chemical plants along the Gulf Coast. Semiconductor fabrication growth in Phoenix and Austin drives cleanroom-grade scrubber procurement for particulate control.
China
Jiangsu and Guangdong provincial environmental bureaus mandate scrubber installations at electronics and chemical manufacturing facilities. MEE directives tighten emissions thresholds for volatile organic compounds at Shenzhen and Suzhou industrial parks. Yangtze River Delta pharmaceutical clusters upgrade filtration systems for GMP compliance.
Germany
Ruhr Valley chemical processors retrofit scrubber trains to satisfy REACH authorization timelines for hazardous emissions. EU F-Gas Regulation phases out refrigerants in HVAC-integrated systems, forcing compatibility upgrades. Bavarian automotive paint shops deploy activated carbon beds for solvent abatement.
Saudi Arabia
NEOM construction and Riyadh hospital expansion projects specify hospital-grade HEPA configurations. The central environmental regulator enforces ambient air quality standards at Jubail Industrial City petrochemical complexes. Western Region healthcare construction accelerates procurement of ducted ventilation systems.
Brazil
São Paulo state environmental agencies mandate scrubber retrofits at Osasco metal finishing plants. ANVISA pharmaceutical manufacturing rules tighten cleanroom air quality documentation. Rio de Janeiro oil refinery maintenance cycles drive demand for portable remediation units during turnaround periods.
Air Scrubber Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with captive HVAC integration capabilities. Filter media specialists and building automation vendors occupy distinct tier positions. Three archetypes dominate: integrated climate-control conglomerates, specialized filtration component suppliers, and regional fabrication houses serving remediation contractors. Consolidation pressure concentrates in the mid-tier, while technology licensing agreements proliferate between media manufacturers and equipment assemblers.
Among diversified technology conglomerates, Honeywell International, Inc. and Daikin Industries, Ltd. exemplify the integrated-systems archetype through building automation and compressor technology positioning. Camfil AB occupies the specialized filtration tier with upstream media manufacturing focus. These three anchors illustrate how competitive positioning diverges between full-system integration and component supply strategies.
| Leading Market Players |
|---|
| Camfil AB |
| Honeywell International, Inc. |
| Daikin Industries, Ltd. |
| Novatek Corporation |
| Amaircare Corporation |
| Advanced Air Technologies Inc. |
| Croll Reynolds, Inc. |
| Abatement Technologies |
| Parker Hannifin Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive compressor technology anchors both supply position and pricing power for integrated climate-control conglomerates, while specialized filter media manufacturers exert upstream control through glass microfiber substrate production concentrated in Germany and Japan. This bifurcation creates divergent margin structures across equipment assemblers and component suppliers.
Pricing Analysis
Uptime guarantees and documented air-change compliance anchor value-based pricing for hospital-grade HEPA-UV-C configurations. Three-tier pricing structure across premium, standard, and economy levels separates Joint Commission-certified systems from commercial specifications and residential portable units. Cost compression in mid-tier commercial installations intensifies because property managers prioritize tenant retention over clinical-grade performance. Homeowners exhibit highest price sensitivity, responding episodically to wildfire events rather than systematic replacement schedules.
Supply Chain Analysis
Glass microfiber media supply rests on German and Japanese specialty substrate manufacturers, with activated carbon feedstock drawing from bituminous coal and coconut shell producers in Indonesia and India. HEPA filter frames, UV-C lamp assemblies, and corrosion-resistant coatings constitute critical component tiers. Single-source vulnerability concentrates in nanofiber coating chemistry for extended-replacement-cycle media. Distribution runs through specialized HVAC distributors serving hospital systems and industrial procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure concentrates in the mid-tier equipment assembly segment as filter media specialists and building automation conglomerates squeeze standalone fabricators. EPA NESHAP enforcement timelines and MEE provincial mandates accelerate capital deployment requirements that weaker capitalized players cannot meet.
For Market Incumbents: To counter independent filter distributors unbundling replacement contracts from equipment sales, Honeywell and Daikin should deepen captive supply of nanofiber-coated media and secure multi-year GPO agreements with United States health systems. Certification investment in EU AI Act-compliant sensor networks will preempt European commercial real estate procurement specifications. For New Entrants and Emerging Players: Photocatalytic oxidation modules for semiconductor VOC abatement represent the most penetrable white-space target, with Taiwan and South Korea fabs piloting titanium dioxide reactors. Portable remediation rental fleets serving United States mold abatement contractors offer asset-light entry with recurring revenue potential. Go-to-market positioning should emphasize mobility and episodic deployment rather than permanent infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in technology licensing agreements between media manufacturers and regional equipment assemblers, with strategic value accruing to filter chemistry IP holders. Long-term viability favors specialists with backward integration into substrate production or forward integration into building automation platforms. Watch MEE provincial enforcement intensity in Jiangsu and Guangdong as inflection indicator for Chinese manufacturing demand.| Strategic Initiative | Industry Significance |
|---|---|
| Filter Media Backward Integration | Captive glass microfiber production secures replacement revenue cycles against distributor unbundling. |
| UV-C Module Convergence | Ultraviolet germicidal irradiation add-ons capture infection control budgets in United States hospital procurement. |
| Photocatalytic Oxidation Licensing | Titanium dioxide reactor technology displaces thermal oxidizers at Taiwan semiconductor fabrication facilities. |
| Portable Rental Fleet Expansion | Mobile scrubber units serve United States disaster restoration and mold remediation contractor demand. |
| EU AI Act Sensor Integration | Automated air quality documentation networks preempt European commercial real estate compliance mandates. |
Study Parameters
Multi-period observation of EPA NESHAP enforcement timelines, MEE provincial directive issuance patterns, and hospital procurement contract structures anchored the trend analysis, supplemented by interviews with plant engineers at chemical processing facilities, biomedical engineers at United States acute care networks, HVAC distribution channel partners, and aftermarket service heads. Secondary validation drew from EPA enforcement databases, SEC 10-K filings of diversified conglomerates, customs trade data on filter media imports, and Joint Commission accreditation records. Bottom-up equipment shipment tracking and top-down emissions compliance spending estimates were triangulated against facility-level retrofit announcements.
The input-output matrix framed volume projections across product type, technology tier, application intensity, and end-user procurement sophistication dimensions. Segment-level CAGRs were derived from regulatory deadline clustering and replacement cycle elasticity modeling. Forecast inputs incorporated semiconductor fab construction pipelines in Phoenix and Austin, Yangtze River Delta pharmaceutical GMP upgrade schedules, and REACH authorization timelines affecting hexavalent chromium coating formulations.
Several conditions sit outside the modeled scope, including abrupt tariff restructuring on Chinese HVAC components, unscheduled revisions to EU F-Gas Regulation phase-out calendars, and pandemic-scale disruption to hospital construction financing. Forecasts reflect documented assumptions about enforcement consistency and commodity feedstock price bands. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
US Air Quality Analyzers Market
Air Quality Control Systems
United States Pollution Mask Market
Air Quality Control Systems
Asia Pacific Air Filtration Market
Air Quality Control Systems
Middle-East and Africa Industrial Air Quality Control Systems Market
Air Quality Control Systems
Air Quality Control Systems Market
Air Quality Control Systems
Air Pollution Control Systems Market
Air Quality Control Systems
Air Pollution Control Equipment Market
Air Quality Control Systems
Green Emissions Analyzers Market
Air Quality Control Systems
Southeast Asia Air Purifier Market
Air Quality Control Systems
UV Air Purifiers Market
Air Quality Control Systems
Singapore Air Purifier Market
Air Quality Control Systems
Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Indoor Air Purification Market
Air Quality Control Systems
Asia-Pacific Indoor Air Purification Market
Air Quality Control Systems
Anti-Pollution Toner Market
Air Quality Control Systems
Ozone Analyzer Market