
 Green Emissions Analyzers Market | 2026-2036
Green Emissions Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Green Emissions Analyzers Market Insights
Utility buyer consolidation around integrated power producers is recalibrating procurement criteria toward long-term service contracts and data analytics integration. ABB leverages its distributed control systems footprint to bundle analyzer sales with plant automation upgrades. Siemens anchors its position through digital twin platforms that embed emissions data into predictive maintenance workflows. Emerson Electric competes by extending its Rosemount gas analysis portfolio into hydrogen-ready measurement architectures.
Green emissions analyzers are precision instruments that quantify pollutant concentrations—typically CO, NOx, SO2, particulate matter, and volatile organic compounds—in exhaust streams using optical, electrochemical, or chromatographic detection methods, with sensitivity thresholds reaching parts-per-billion for regulatory-grade certification. Their primary purpose is to verify compliance with environmental permits and enable real-time process optimization in combustion and chemical operations. Stationary analyzers dominate installed base value due to capital intensity and integration with distributed control systems, while portable analyzers represent the fastest-growing product category as field audit requirements multiply across industrial sites. Infrared sensing technology leads unit shipments for stack gas applications, though optical sensing platforms are displacing legacy electrochemical cells in ambient air monitoring networks where drift tolerance and calibration intervals determine total cost of ownership.
The EPA enforces Continuous Emission Monitoring System rules under the Clean Air Act, mandating certified analyzers for major source categories and driving replacement cycles when protocols tighten. China's MEE administers emission permit systems that require real-time data transmission to provincial monitoring platforms, creating demand for analyzers with embedded IoT connectivity and tamper-evident data logging. The EU Green Deal's Industrial Emissions Directive revision will expand measurement scope to methane and hydrogen leakage, compelling technology refreshes across European process industries. Stakeholders must evaluate whether their analyzer portfolios can accommodate emerging pollutant categories and blockchain-verified reporting standards without full hardware replacement.
Market Dynamics
Utility procurement consolidation is compressing vendor margins while accelerating demand for integrated service contracts that bundle hardware with predictive analytics and remote calibration support.
Growth Catalysts
- China's MEE emission permit systems:Real-time data transmission mandates to provincial monitoring platforms are forcing industrial clusters to upgrade legacy analyzers with IoT-enabled, tamper-evident architectures.
- Power generation utilities:Coal-to-gas transitions and hydrogen blending trials across Asia-Pacific are expanding the addressable base for multi-species measurement systems.
- Infrared sensing platforms:Drift tolerance improvements and extended calibration intervals are displacing electrochemical cells in ambient air networks, lowering total cost of ownership for municipal buyers.
Market Restraints
- Optical component supply concentration:German and Japanese laser source manufacturers control critical photonics supply, exposing analyzer OEMs to lead-time volatility and input cost spikes.
- Certification timeline friction:EPA's 40 CFR Part 75 and EN 15267-3 testing protocols require 12-18 month validation cycles, delaying product launches and freezing R&D budgets.
- Portable analyzer substitution pressure:Lower-cost electrochemical handhelds from Chinese manufacturers are capturing spot-check applications, eroding margin pools for premium stationary systems.
Strategic Opportunities
- India's industrial corridor expansion:Gujarat and Tamil Nadu state pollution control boards are mandating continuous monitoring for cement and steel installations, creating first-mover advantages for certified suppliers.
- Hydrogen leakage detection:The EU Green Deal's Industrial Emissions Directive revision will expand measurement scope beyond conventional pollutants, compelling technology refreshes across European process industries.
- Blockchain-verified reporting:Emerging standards for immutable emissions data are opening service revenue streams around data integrity verification and third-party audit trails.
Industry Challenges
- Embedded systems engineering scarcity:Firmware developers with expertise in edge computing and industrial IoT security command premium compensation, constraining product roadmap velocity.
- Distributed control system integration complexity:Analyzer vendors must maintain backward compatibility with 1990s-era DCS protocols while modernizing data architectures, fragmenting engineering resources.
- Cross-border calibration standard divergence:Misalignment between EPA reference methods and China's GB standards forces dual product configurations, inflating inventory and compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Emissions Analyzers Market |
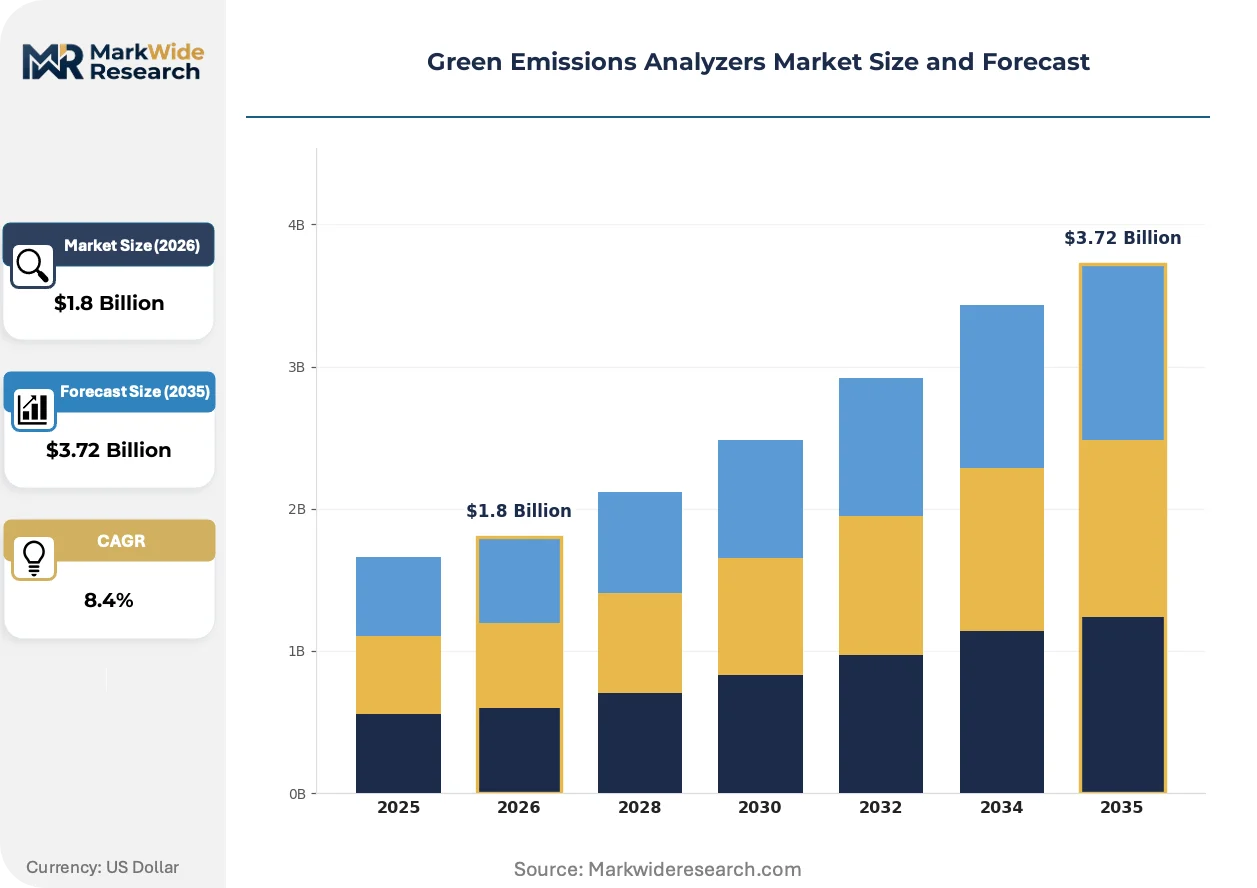
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Stationary Analyzers, Fixed-Point Analyzers, Vehicle Emission Monitors Technology: Infrared Sensors, Gas Chromatography, Chemical Sensors, Optical Sensing End User: Environmental Agencies, Manufacturing Plants, Research Institutions, Automotive Industry Application: Air Quality Monitoring, Industrial Emission Testing, Vehicle Emission Testing, Compliance Reporting |
| Companies Covered | ABB, Siemens, Emerson Electric, Yokogawa Electric, Shimadzu Corporation, Horiba, Fuji Electric, Testo SE & Co. KGaA, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Emissions Analyzers Market Trends and Innovations
Optical sensing architectures are overtaking legacy detection methods while regulatory scope expansion and buyer consolidation are rewriting competitive rules across the value chain.
Quantum cascade laser absorption spectroscopy is decentralizing emissions monitoring by enabling field-deployable, laboratory-grade precision without extractive sampling infrastructure. Chemical refineries in the US Gulf Coast and Rotterdam port complexes are piloting these systems for fence-line monitoring. The technology is decentralizing measurement authority from central labs to plant operators, compressing response times from days to minutes.
The EU Green Deal's Industrial Emissions Directive revision will mandate methane and hydrogen leakage quantification across chemical, waste, and energy installations. This regulatory expansion is compelling analyzer vendors to extend detection libraries and recalibrate sensitivity thresholds. European process industries are responding by pre-qualifying multi-species platforms that accommodate anticipated pollutant categories without hardware replacement.
Integrated power producers are unbundling after-sales service contracts from initial equipment sales, creating standalone revenue pools for calibration, remote diagnostics, and predictive maintenance. This procurement model evolution is disrupting traditional distributor channels that historically captured service margins. The shift is most visible in China's Yangtze River Delta industrial clusters, where state-owned utilities are consolidating vendor panels around long-term performance agreements.
Green Emissions Analyzers Market Segmentation
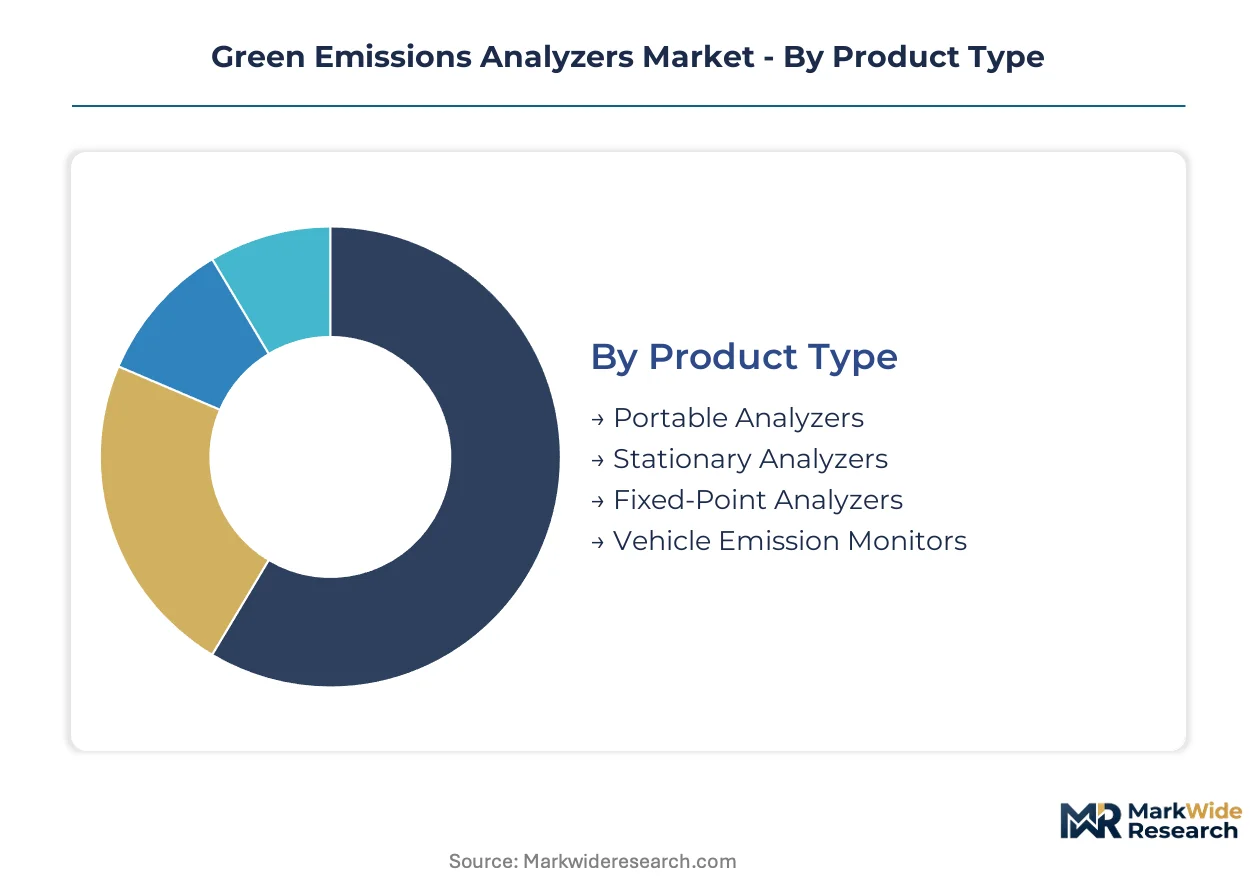
Segmentation in the Green Emissions Analyzers Market reflects divergent integration architectures across industrial environments. Procurement patterns split between embedded systems requiring DCS compatibility and standalone units for field audit deployment. Technology selection increasingly hinges on calibration interval economics and connectivity mandates from regulators.
Product Type:
Stationary analyzers anchor capital budgets through deep integration with plant automation infrastructure, while portable units serve spot-check protocols and mobile compliance verification.
- Portable Analyzers:Battery-powered units with electrochemical or optical detection cores enable fence-line audits and emergency response deployment. Demand concentrates in China's Pearl River Delta manufacturing clusters where MEE inspectors mandate unannounced facility checks, though lower-cost Chinese handhelds compress margins for premium suppliers.
- Stationary Analyzers:Rack-mounted systems with extractive sampling infrastructure and tamper-evident data logging dominate utility procurement. Power generation installations across India and China specify these units for continuous stack monitoring with real-time transmission to provincial platforms.
- Fixed-Point Analyzers:Permanently installed ambient air monitors with meteorological sensors populate urban monitoring networks.
- Vehicle Emission Monitors:Tailpipe testing equipment for inspection and maintenance programs.
Stationary analyzers lead volumes today; portable analyzers are gaining share fastest.
Technology:
Detection method selection determines total cost of ownership through calibration frequency, drift tolerance, and species coverage breadth.
- Infrared Sensors:Non-dispersive and tunable diode laser platforms measure CO, NOx, and SO2 through absorption spectroscopy with minimal maintenance. Municipal buyers in Germany and Japan specify these for ambient networks where 6-month calibration intervals slash operational burden versus electrochemical alternatives.
- Optical Sensing:UV-DOAS and FTIR architectures enable multi-species quantification without consumable reagents. European process industries pre-qualify these systems for anticipated methane and hydrogen leakage mandates under revised EU Green Deal directives.
- Gas Chromatography:Laboratory-grade separation for speciated VOC analysis in research and forensic applications.
- Chemical Sensors:Electrochemical cells and metal oxide semiconductors serve cost-sensitive spot-check applications.
Infrared sensors dominate current installations; optical sensing platforms show steepest expansion trajectory.
End User:
Buyer sophistication varies sharply between regulatory enforcement bodies and industrial self-monitoring operations.
- Environmental Agencies:Government monitoring networks require certified reference-grade instrumentation with documented traceability chains. China's MEE provincial platforms and the EPA's state implementation plans drive procurement of networked analyzer arrays with centralized data validation.
- Manufacturing Plants:Industrial facilities balance compliance verification against process optimization objectives. Cement and steel installations in India's Gujarat and Tamil Nadu industrial corridors are newly mandated for continuous monitoring, creating first-mover certification races.
- Research Institutions:Academic and government laboratories require speciated measurement capabilities for atmospheric chemistry studies.
- Automotive Industry:Engine test cells and assembly line quality control deploy analyzers for R&D and production validation.
Manufacturing plants anchor revenue today; environmental agencies are expanding procurement most rapidly.
Application:
Use case specificity dictates sensitivity thresholds, response time requirements, and data reporting formats.
- Industrial Emission Testing:Stack and duct monitoring for permit compliance demands continuous measurement with 15-minute rolling averages. Power utilities across Asia-Pacific specify these systems for coal-to-gas transition projects and hydrogen blending trials requiring multi-species flexibility.
- Compliance Reporting:Automated data submission to regulatory platforms requires embedded IoT architectures with blockchain-ready audit trails. China's real-time transmission mandates and emerging EU verification standards favor analyzers with tamper-evident logging and third-party audit capabilities.
- Air Quality Monitoring:Ambient network stations track regional pollutant levels for public health alerts.
- Vehicle Emission Testing:Chassis dynamometer and roadside inspection protocols measure tailpipe output against type-approval limits.
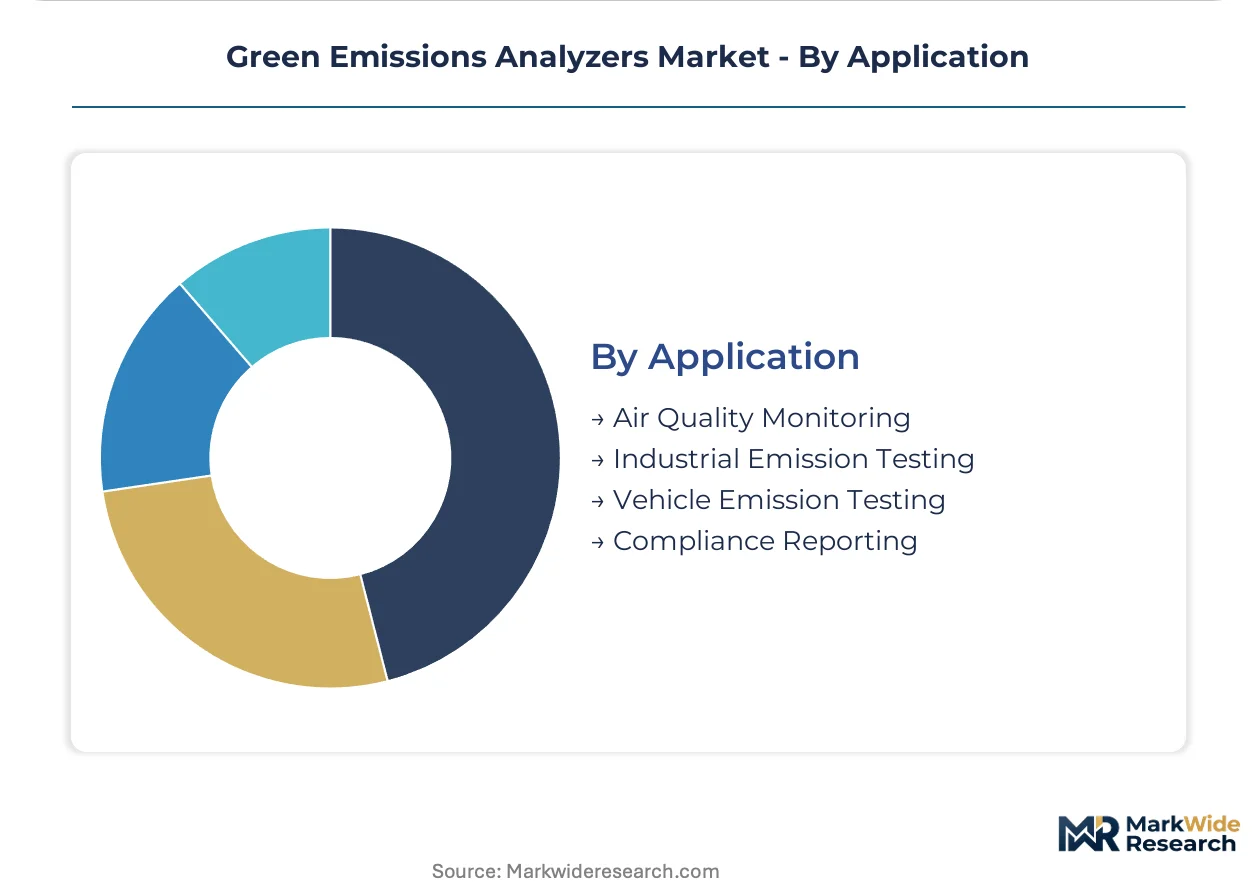
Industrial emission testing generates the largest revenue pool; compliance reporting applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE-driven procurement outpaces Germany's EU Green Deal compliance cycles by roughly eighteen months, creating divergent technology refresh timelines across the two largest analyzer markets.
China
Power generation utilities and steel conglomerates drive analyzer deployment across the Yangtze River Delta and Pearl River Delta industrial clusters. The MEE's real-time data transmission mandates force cement and chemical installations to upgrade legacy systems with IoT-enabled architectures. Shanghai's Pudong district hosts the densest concentration of continuous emissions monitoring installations.
United States
Coal-to-gas transition projects and hydrogen blending trials at Gulf Coast refineries expand demand for multi-species measurement platforms. The EPA's 40 CFR Part 75 enforcement drives replacement cycles when protocols tighten. Houston's petrochemical corridor and Louisiana's industrial zone anchor stationary analyzer procurement.
Germany
Chemical refineries and automotive test facilities specify optical sensing platforms for fence-line monitoring and R&D validation. The EU Green Deal's Industrial Emissions Directive revision compels pre-qualification of methane-capable systems. The Ruhr industrial region and Bavaria's manufacturing belt concentrate analyzer installations.
India
Cement and steel installations across Gujarat and Tamil Nadu face new continuous monitoring mandates from state pollution control boards. The CEA's emission norms for thermal power plants create certification races among suppliers. The Delhi-Mumbai Industrial Corridor and Chennai's manufacturing cluster drive portable analyzer demand for field audits.
Japan
Precision manufacturing and semiconductor fabrication facilities deploy reference-grade instrumentation for process control and environmental compliance. METI's carbon neutrality roadmap accelerates hydrogen leakage detection requirements. The Keihin industrial zone and Osaka's chemical complex anchor high-sensitivity analyzer procurement.
Green Emissions Analyzers Market Competitive Landscape
German and Swiss producers anchor the premium-tier segment; Japanese specialists hold position in precision instrumentation. The vendor base splits between consolidated automation conglomerates with distributed control system integration capabilities and focused sensor technology firms. Three archetypes dominate: full-stack automation providers bundling analyzers with plant control systems, standalone gas analysis specialists competing on detection sensitivity, and emerging optical technology firms commercializing quantum cascade laser platforms. Strategic moves concentrate on backward integration into photonics supply and geographic expansion through certification racing in India's newly regulated states.
Among automation conglomerates, ABB and Siemens exemplify the full-stack archetype through their embedded positions in power generation control infrastructure. Shimadzu Corporation occupies a position within the precision instrumentation tier, representing Japanese engineering standards in optical detection platforms. These anchors illustrate how competitive positioning increasingly depends on backward integration into laser source supply and pre-certification for emerging pollutant categories under revised EU and Chinese regulations.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Emerson Electric |
| Yokogawa Electric |
| Shimadzu Corporation |
| Horiba |
| Fuji Electric |
| Testo SE & Co. KGaA |
| Thermo Fisher Scientific |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in Germany and Japan anchor premium-tier production, enabling disciplined pricing through captive photonics supply and long-term utility service contracts that resist commoditization pressure from Chinese handheld entrants.
Pricing Analysis
Capacity additions in China are reshaping price floors for portable analyzers, compressing margins for premium suppliers while reinforcing three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade—EPA 40 CFR Part 75 versus China's GB standards—and after-sales bundling depth. Cost compression in the portable tier is intensifying because MEE inspectors in the Pearl River Delta favor lower-cost electrochemical handhelds for spot-check protocols. Municipal buyers in Germany and Japan show lowest price sensitivity due to calibration interval economics, while cement and steel installations in India's Gujarat corridor exhibit highest sensitivity.
Supply Chain Analysis
Certification timelines under EPA 40 CFR Part 75 and EN 15267-3 function as supply-side gating mechanisms, freezing inventory positions for 12-18 month validation cycles. German and Japanese laser source manufacturers concentrate critical photonics supply, drawing from specialized foundries in Bavaria and Osaka. Analyzer OEMs source tunable diode lasers, quantum cascade substrates, and optical detectors from these concentrated nodes. Single-source vulnerability in laser source supply exposes producers to lead-time volatility when provincial monitoring mandates in China spike demand. Distribution runs through certified system integrators with DCS compatibility expertise and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Green Emissions Analyzers Market represents a late-cycle quality story as buyer consolidation around integrated power producers shifts procurement criteria toward predictive analytics integration and blockchain-verified reporting standards.
For Market Incumbents: Anchor defensive positioning through backward integration into photonics supply and pre-certification for methane-capable platforms under revised EU Green Deal directives. Threat substitution from quantum cascade laser startups demands firmware investment in edge computing architectures. Certification investment in India's newly regulated states—Gujarat and Tamil Nadu—secures channel control against emerging optical technology firms. For New Entrants and Emerging Players: The price-point gap between premium stationary systems and economy handhelds opens white-space targeting for mid-tier portable units with IoT-enabled data logging. India's industrial corridor expansion presents the most penetrable geography, with state pollution control boards mandating continuous monitoring for first-time installations. A calibration-service-first go-to-market angle bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone gas analysis specialists lacking DCS integration capabilities, though these assets carry platform obsolescence risk. Long-term viability over a decade horizon favors full-stack automation providers with captive utility relationships. Watch MEE protocol tightening frequency as the inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photonics Supply | German and Japanese laser source manufacturers reduce lead-time exposure for analyzer OEMs serving MEE-mandated upgrades. |
| Pre-Certification for Methane Detection | EU Green Deal Industrial Emissions Directive revision compels technology refreshes across Rotterdam and Ruhr chemical complexes. |
| Calibration-First Service Contracts | China's Yangtze River Delta utilities unbundle after-sales service, creating standalone revenue pools for predictive maintenance. |
| Blockchain-Verified Data Architectures | Tamper-evident logging with third-party audit trails meets emerging EU verification standards and MEE real-time transmission mandates. |
| Quantum Cascade Laser Platform Launch | US Gulf Coast and Rotterdam refineries pilot fence-line monitoring, decentralizing measurement authority from central laboratories. |
Research Methodology
Direct dialogue with plant automation engineers, utility procurement officers, environmental compliance managers, and photonics component suppliers grounded qualitative findings, cross-referenced against EPA enforcement databases, MEE provincial monitoring platform disclosures, EU ETS verification reports, and customs trade records for optical detection equipment. Bottom-up and top-down triangulation validated segment-level estimates.
Bottom-up modeling anchored installed base quantification by technology type and end-user sector, while top-down approaches cross-checked aggregate market evolution against regulatory enforcement budgets and utility capital expenditure patterns across the projection horizon. Segmentation dimensions included product architecture, detection method, certification tier, and regional regulatory cluster. CAGRs derived from replacement cycle analysis tied to protocol tightening schedules and industrial capacity expansion trajectories. Hydrogen blending trial momentum and coal-to-gas transition velocity served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for quantum cascade laser absorption spectroscopy would alter the outlook if field-deployable precision achieves cost parity with extractive sampling infrastructure. Forecasts reflect assumptions around MEE mandate enforcement consistency and EU Green Deal implementation timelines. A model refresh is warranted upon material change in provincial monitoring platform data transmission requirements or photonics supply concentration shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Asia Pacific Air Filtration Market
Air Quality Control Systems
Asia-Pacific Indoor Air Purification Market
Air Quality Control Systems
Anti-Pollution Mask Market
Air Quality Control Systems
Emission Management Software Market
Air Quality Control Systems
UV Air Purifiers Market
Air Quality Control Systems
US Air Quality Analyzers Market
Air Quality Control Systems
North America Industrial Air Quality Control Systems Market
Air Quality Control Systems
Anti-Pollution Toner Market
Air Quality Control Systems
Desiccant Air Breather Market
Air Quality Control Systems
Air Pollution Control Systems Market
Air Quality Control Systems
Sustainable Air Filter Market
Air Quality Control Systems
Air Pollution Control Equipment Market
Air Quality Control Systems
Environment Controllers Market
Air Quality Control Systems
Global Mist Eliminator Market
Air Quality Control Systems
Middle-East and Africa Industrial Air Quality Control Systems Market
Air Quality Control Systems
Environmental Control System (ECS) Market