
 Global Mist Eliminator Market | 2026-2036
Global Mist Eliminator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mist Eliminator Market Intelligence
Asian specialty metals producers is broadening fabrication capacity for corrosion-resistant mist elimination media. Sulzer Ltd. leverages vertical integration across alloy wire drawing and knitted mesh assembly to control lead times. Munters Group AB sustains technology leadership in polymer vane geometries for coastal desalination. Koch-Glitsch LP anchors its position through dominance in structured packing derivatives for refinery sulfur recovery trains.
Mist eliminators are mechanical separation devices engineered from interlaced wire mesh, corrugated vanes, or packed beds to capture liquid droplets entrained in gas streams, typically achieving removal efficiencies above 99% for particles larger than 3-5 microns. Their primary purpose is protecting downstream equipment, reducing product loss, and ensuring compliance with stack emission limits in continuous process industries. Wire mesh and vane configurations occupy the mature core of the product mix, while cyclonic and blade designs represent faster-growing niches where high-velocity gas streams demand lower pressure drop. Stainless steel and polypropylene materials lead volume, though PTFE and alloy steel command premium positioning in acid gas and elevated-temperature applications.
The EPA enforces Maximum Achievable Control Technology standards that mandate particulate capture efficiency thresholds across chemical processing and power generation stacks. EMA industrial emissions guidelines and REACH material compliance obligations in Europe restrict certain polymer formulations while driving substitution toward certified stainless steel constructions. Stakeholders must monitor evolving MEE enforcement trajectories in China and pending F-Gas Regulation amendments, as these will reshape material qualification requirements and retrofit investment timing across the installed base.
Market Dynamics
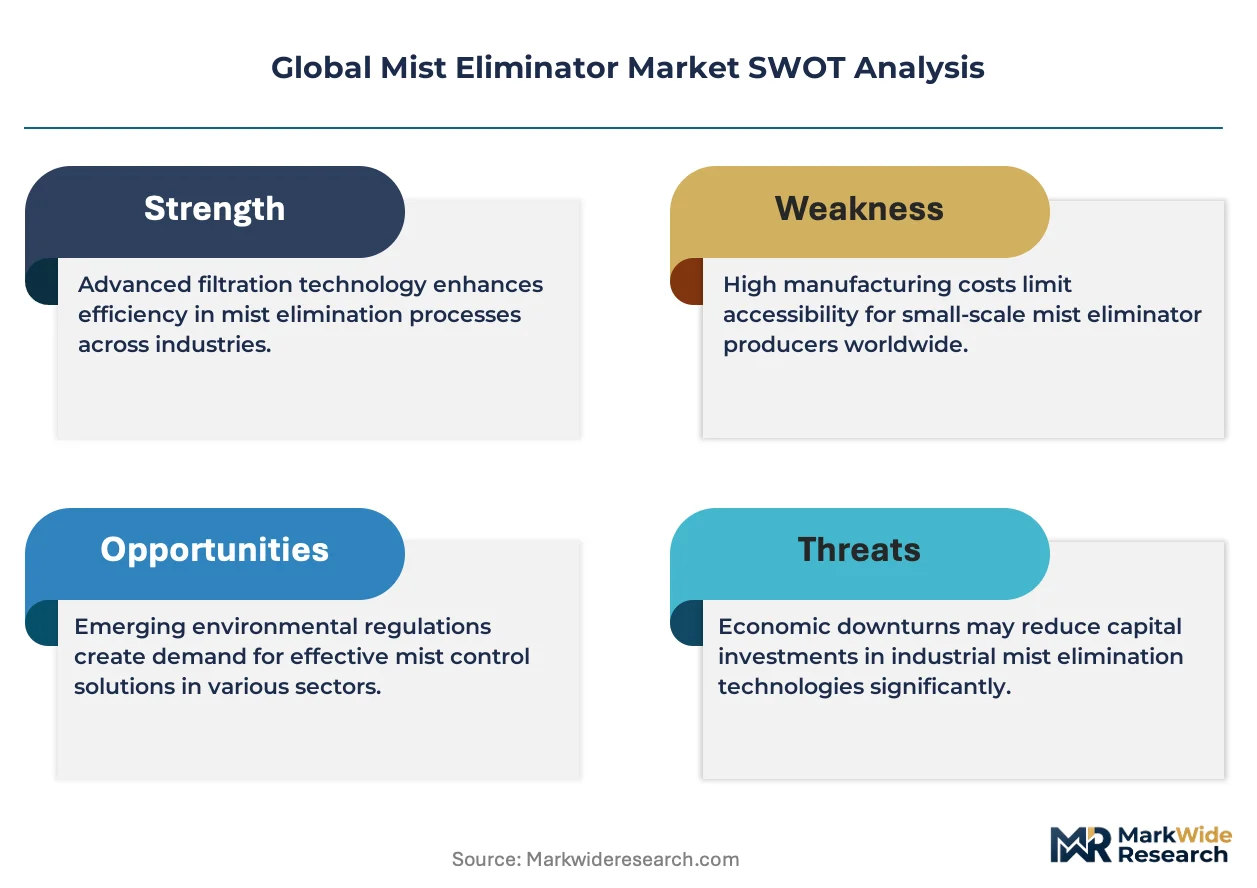
Stringent emissions protocols are compressing replacement cycles across process industries, compelling facility operators to upgrade from legacy wire-mesh configurations to higher-efficiency vane and cyclonic designs that satisfy tightening particulate discharge thresholds.
Growth Catalysts
- EPA Maximum Achievable Control Technology:Mandated capture efficiency thresholds across chemical processing stacks drive systematic retrofit investments in stainless steel mist elimination trains.
- Petrochemical capacity expansion:New buildouts in ethylene and aromatics complexes generate greenfield demand for corrosion-resistant separation media in acid gas service.
- China MEE enforcement trajectories:Accelerated inspection schedules in industrial clusters force state-owned refineries to replace degraded installed units ahead of scheduled maintenance windows.
Market Restraints
- Nickel price volatility:Stainless steel alloy feedstock cost swings compress fabrication margins and destabilize project quoting for extended-lead-time refinery contracts.
- Specialty polymer supply concentration:PTFE and fluoropolymer resin production concentrates among limited chemical compounders, exposing mist eliminator assemblers to allocation risk during semiconductor industry demand surges.
- Pressure-drop limitations in wire-mesh designs:Conventional knitted mesh configurations face technical ceilings in high-velocity gas streams above 15 meters per second, restricting applicability in compressor suction service.
Strategic Opportunities
- India petrochemical corridor development:Gujarat and Maharashtra industrial zones lack mature emissions control infrastructure, creating first-mover positioning for packaged mist elimination systems in upcoming integrated complexes.
- EU F-Gas Regulation amendments:Pending restrictions on fluorinated greenhouse gases incentivize substitution toward certified stainless steel constructions in refrigeration and chemical processing applications.
- Digital twin integration:Convergence of computational fluid dynamics modeling with IoT pressure-drop monitoring enables predictive maintenance contracts that extend equipment lifecycle revenue.
Industry Challenges
- Corrosion-resistant welding certification:Qualified technicians for alloy mesh-to-support-ring fabrication remain scarce, extending delivery timelines for superduplex and Hastelloy specifications.
- Legacy system integration complexity:Retrofitting high-efficiency vanes into existing vessel footprints requires custom engineering that strains project engineering bandwidth at mid-cap fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mist Eliminator Market |
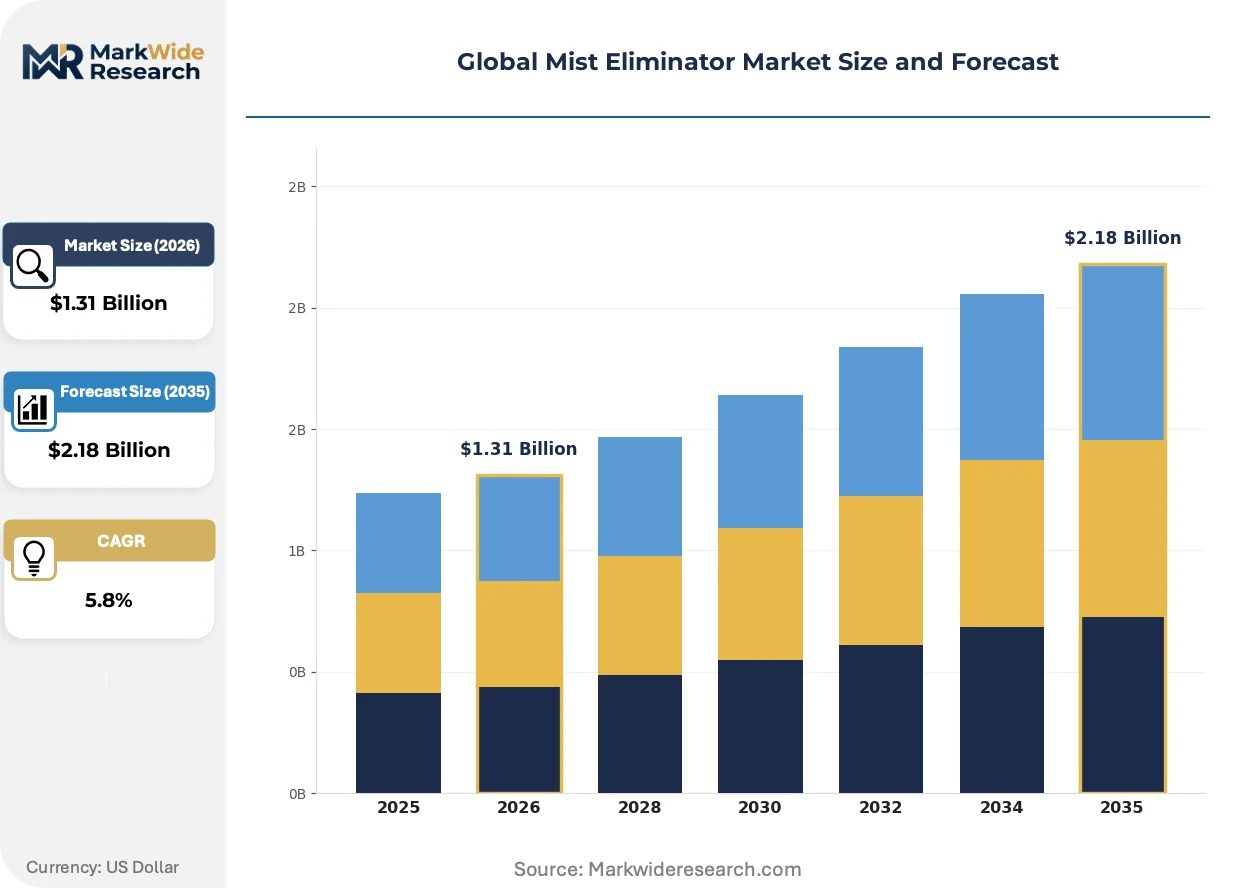
| Market Size in 2026 | $1.31 Billion |
| Market Size in 2035 | $2.18 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
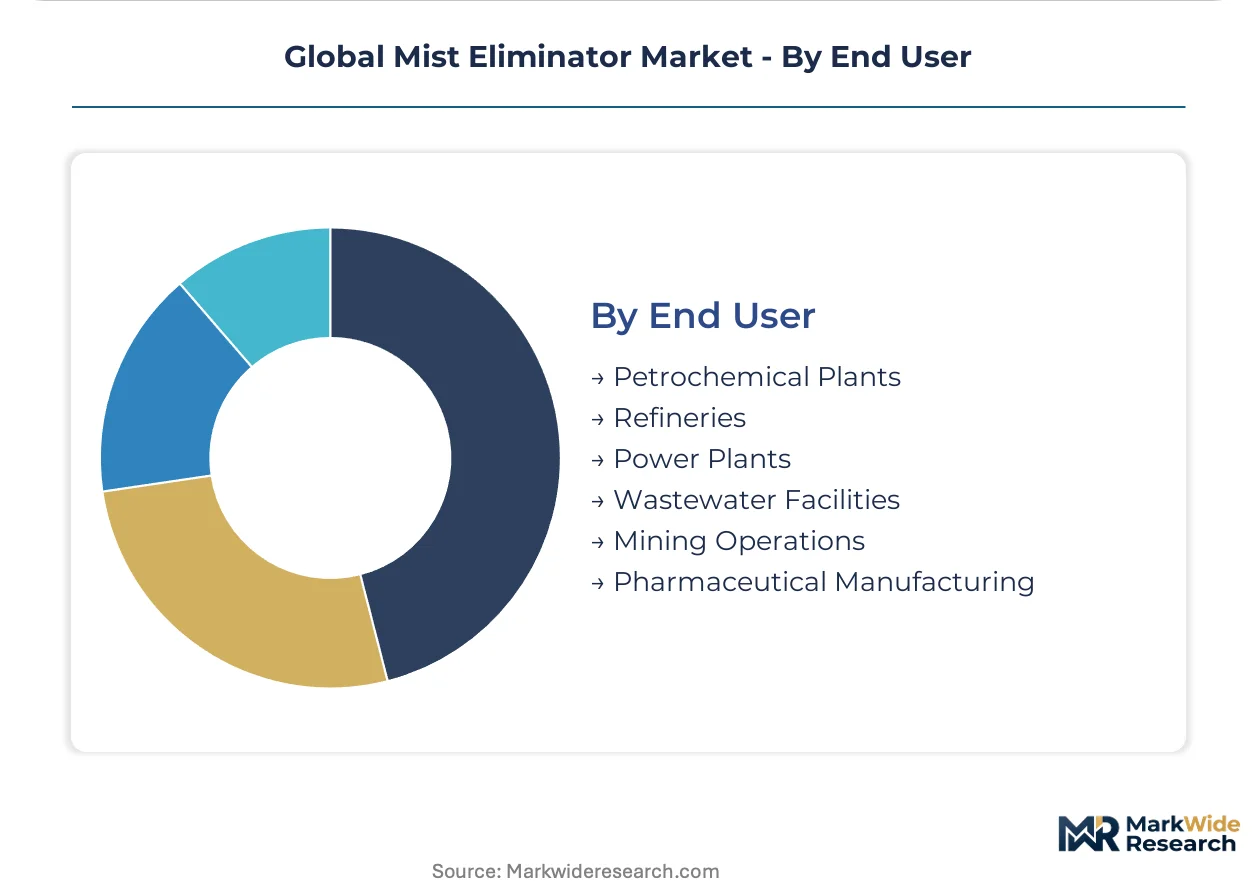
| Segmentation | Product Type: Chevron, Wire Mesh, Packed Bed, Cyclonic, Vane, Blade Material: Stainless Steel, Polypropylene, PVC, Fiberglass, PTFE, Alloy Steel Application: Chemical Processing, Power Generation, Water Treatment, Oil Extraction, Gas Processing, Metal Refining End User: Petrochemical Plants, Refineries, Power Plants, Wastewater Facilities, Mining Operations, Pharmaceutical Manufacturing |
| Companies Covered | Sulzer Ltd., Munters Group AB, Koch-Glitsch LP, DuPont de Nemours, Inc., CECO Environmental Corp., Kimre, Inc., Hilliard Corporation, AMACS Process Towers Internals, Air Quality Engineering, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mist Eliminator Market Strategic Shifts & Innovations
Computational modeling and advanced materials are reconfiguring product architectures, shifting competitive advantage from pure manufacturing scale toward simulation-backed customization and alloy specification expertise.
Multi-stage cyclonic mist eliminators are overtaking conventional wire-mesh configurations in offshore gas processing and high-pressure compressor applications. Operators in the North Sea and Gulf of Mexico deploy these units to achieve sub-3-micron capture at face velocities exceeding 25 meters per second. The technology is overtaking legacy designs by eliminating flooding risk in slug-catching service and reducing vessel diameter requirements by 30-40 percent.
The EU Green Deal Industrial Emissions Directive tightens particulate discharge limits for large combustion plants and chemical manufacturing facilities. Member state permitting authorities now require continuous opacity monitoring downstream of mist elimination stages. Refinery operators in Rotterdam and Antwerp respond by specifying vane packs with integrated drainage channels that prevent re-entrainment during upset conditions.
Buyer preference is consolidating around performance-guaranteed supply contracts that bundle equipment, installation supervision, and predictive maintenance subscriptions. EPC firms executing lump-sum turnkey projects now demand outcome-based agreements where vendors absorb efficiency shortfall risk. This model penetrates fastest in Middle Eastern desalination and petrochemical complexes, where owner-operators prioritize operational expenditure certainty over capital cost minimization.
Global Mist Eliminator Market Segmentation
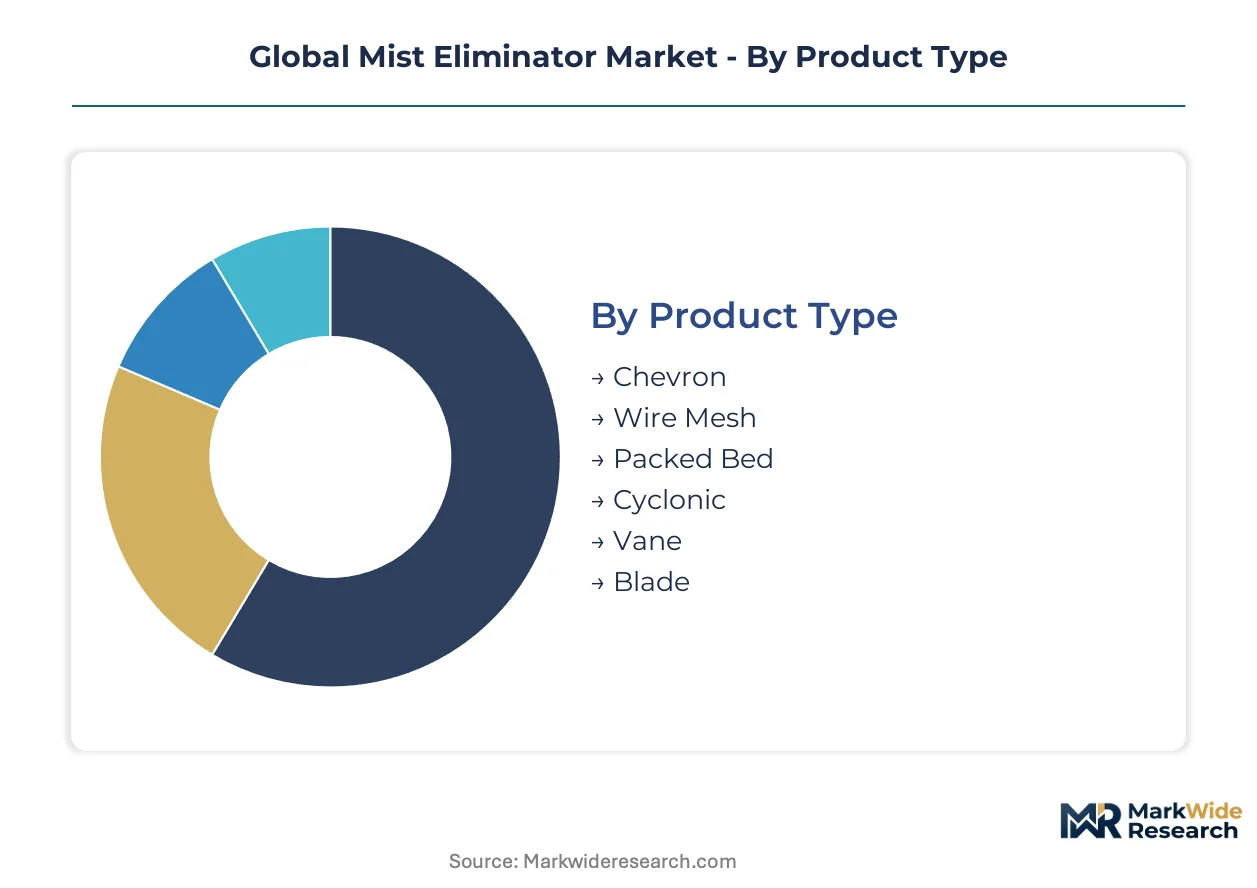
Segmentation in mist eliminators determines material qualification pathways, pressure-drop specifications, and retrofit compatibility with existing vessel footprints. Product architecture and material selection drive certification requirements under EPA MACT, EU F-Gas Regulation, and China MEE standards. Application context dictates whether stainless steel constructions or fluoropolymer alternatives satisfy corrosion resistance and temperature thresholds.
Product Type:
Certification burdens cluster around vane and cyclonic designs where EPA MACT mandates continuous opacity monitoring downstream, while wire-mesh configurations face lighter documentation under legacy grandfathering provisions.
- Wire Mesh:Knitted stainless steel or polymer filaments interlaced into layered pads achieve 99% capture efficiency for droplets above 3-5 microns. Petrochemical operators in Texas and Louisiana specify these for standard refinery sulfur recovery trains where gas velocities remain below 15 meters per second.
- Vane:Corrugated plate geometries with integrated drainage channels prevent re-entrainment during upset conditions. Rotterdam and Antwerp refineries deploy these under EU Green Deal Industrial Emissions Directive requirements for continuous monitoring compliance in large combustion plants.
- Cyclonic:Tangential inlet designs generate centrifugal separation without flooding risk in slug-catching service. North Sea offshore platforms favor these for high-velocity applications exceeding 25 meters per second.
- Blade:Aerodynamic profiles optimized for low pressure-drop in compressor suction lines. Gulf of Mexico gas processing facilities specify these where energy consumption constraints dominate.
- Chevron:Zigzag plate arrangements with impingement surfaces for moderate-velocity streams. Wastewater treatment plants in Germany deploy these for biogas purification under ECHA REACH material compliance.
- Packed Bed:Structured or random media configurations for simultaneous mass transfer and droplet capture. Specialty chemical producers in Switzerland specify these where multi-function separation trains reduce vessel count.
Wire mesh sits at the top of the volume ranking, with cyclonic climbing the fastest as offshore gas processing demands higher face velocities.
Material:
Cost tiers separate commodity stainless steel from premium alloy specifications, with fluoropolymer resins occupying a mid-tier position constrained by semiconductor industry allocation competition.
- Stainless Steel:304 and 316 grades dominate refinery and power generation applications. EPA MACT standards systematically drive retrofit demand for these certified constructions across US chemical processing stacks.
- PTFE:Fluoropolymer resin with exceptional acid gas resistance and temperature stability to 260°C. Semiconductor demand surges periodically constrain supply availability for chemical processing orders.
- Alloy Steel:Superduplex and Hastelloy specifications for extreme chloride and sour gas service. North Sea operators specify these where seawater exposure and hydrogen sulfide concentrations converge.
- Polypropylene:Injection-molded vanes and mesh for water treatment and moderate-temperature chemical service. Indian wastewater facilities favor these for cost-sensitive procurement in Gujarat industrial corridors.
- PVC:Rigid construction for low-temperature, non-oxidizing environments. Cooling tower applications in Saudi desalination plants specify these where chloride levels remain controlled.
- Fiberglass: Reinforced polymer composites for coastal and marine atmospheric exposure. UAE petrochemical complexes deploy these where salt spray accelerates metallic corrosion.
Stainless steel commands the largest volume position, with alloy steel expanding most quickly as sour gas processing intensifies.
Application:
Customer type segmentation reveals divergent procurement patterns: lump-sum turnkey EPCs demand performance guarantees while owner-operators prioritize operational expenditure certainty.
- Chemical Processing:Acid gas separation, solvent recovery, and emissions control in continuous reactors. China MEE enforcement trajectories accelerate replacement cycles for state-owned ethylene producers.
- Power Generation:Flue gas desulfurization and cooling tower drift elimination. EU Green Deal Industrial Emissions Directive tightens particulate limits for coal and biomass combustion plants.
- Oil Extraction:Production separator mist control and compressor suction protection. Permian Basin operators specify cyclonic designs for high-pressure associated gas streams.
- Gas Processing:Dehydration unit glycol recovery and amine treating. Qatar and UAE integrated complexes drive demand for superduplex specifications in acid gas service.
- Water Treatment:Desalination evaporator drift elimination and biogas upgrading. Saudi Arabia's Ras Al-Khair complex represents concentrated procurement for polymer vane technologies.
- Metal Refining:Sulfuric acid plant mist control and electrowinning tankhouse ventilation. Chilean copper producers specify PTFE constructions for aggressive electrolyte environments.
Chemical processing anchors volume demand, with gas processing gaining share fastest as LNG infrastructure expands.
End User:
Maturity gradients separate petrochemical and refinery segments with established specification standards from pharmaceutical and mining applications where mist elimination penetration remains uneven.
- Petrochemical Plants:Ethylene, aromatics, and derivatives complexes with acid gas and process solvent recovery requirements. China industrial cluster expansion generates greenfield demand for corrosion-resistant separation media.
- Refineries:Fluid catalytic cracking, coking, and hydroprocessing units with sulfur recovery train integration. US Gulf Coast operators face EPA MACT compliance deadlines for particulate capture upgrades.
- Power Plants:Fossil and biomass combustion with flue gas treatment and cooling systems. Germany's lignite phase-out creates retrofit urgency for remaining units under EU emissions standards.
- Wastewater Facilities:Anaerobic digester biogas purification and odor control. India's Namami Gange program drives municipal procurement for packaged mist elimination systems.
- Mining Operations:Acid mine drainage treatment and hydrometallurgical process ventilation. Peruvian copper concentrators specify alloy constructions for high-altitude sulfuric acid exposure.
- Pharmaceutical Manufacturing:Cleanroom air handling and solvent recovery with strict particulate limits. Swiss and Irish API producers demand FDA-validated stainless steel constructions.
Petrochemical plants occupy the top volume tier, with pharmaceutical manufacturing ascending fastest as containment regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping fabrication footprints as producers migrate toward jurisdictions with narrower cost-of-compliance gaps between legacy wire-mesh and advanced vane systems. China, the United States, Germany, India, and Saudi Arabia concentrate divergent enforcement timelines that fragment procurement patterns.
China
Industrial cluster expansion around Ningbo and Dalian generates replacement demand as MEE inspection schedules compress maintenance windows. The Ministry of Ecology and Environment enforces opacity limits that disqualify degraded knitted-mesh installations in state-owned refinery sulfur recovery trains. Shandong Province ethylene producers accelerate retrofit procurement ahead of quarterly compliance audits.
United States
Permian Basin gas processing capacity additions specify cyclonic designs for high-pressure associated gas streams above 15 meters per second. EPA Maximum Achievable Control Technology mandates drive systematic stainless steel upgrades across Gulf Coast chemical processing stacks. Texas and Louisiana refineries face particulate capture deadlines that strain qualified welding technician availability.
Germany
Lignite phase-out urgency concentrates retrofit investment in remaining coal and biomass combustion units under EU Green Deal Industrial Emissions Directive. ECHA REACH obligations restrict certain fluoropolymer formulations while steering specification toward certified stainless steel constructions. The Rhine-Ruhr chemical corridor deploys vane packs with integrated drainage channels for continuous monitoring compliance.
India
Gujarat and Maharashtra petrochemical corridors lack mature emissions control infrastructure, creating first-mover positioning for packaged systems in upcoming integrated complexes. The Namami Gange program drives municipal wastewater procurement for biogas purification applications. Reliance Industries' Jamnagar refinery expansion generates demand for corrosion-resistant separation media in acid gas service.
Saudi Arabia
Ras Al-Khair desalination complex represents concentrated procurement for polymer vane technologies in evaporator drift elimination. The Saudi Food and Drug Authority and national environmental regulator tighten industrial discharge protocols for Red Sea coastal protection. Jubail industrial city operators specify fiberglass-reinforced composites where salt spray accelerates metallic corrosion.
Global Mist Eliminator Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue digital-twin integration and predictive maintenance contracting. The vendor base stratifies across three maturity levels: integrated alloy specialists controlling upstream wire drawing, mid-cap fabricators with regional installation capabilities, and technology licensors monetizing computational fluid dynamics platforms. Dominant competitive moves include backward integration into specialty alloy supply and outcome-based performance guarantees that absorb efficiency shortfall risk.
Within the integrated-specialist tier, Sulzer Ltd. and Munters Group AB exemplify divergent material strategies—Sulzer through captive stainless steel mesh production, Munters through polymer vane geometry leadership. Koch-Glitsch LP anchors the structured-packing derivative segment for refinery sulfur recovery applications. These three entities represent distinct archetypes: alloy verticalization, polymer innovation, and mass-transfer integration.
| Leading Market Players |
|---|
| Sulzer Ltd. |
| Munters Group AB |
| Koch-Glitsch LP |
| DuPont de Nemours, Inc. |
| CECO Environmental Corp. |
| Kimre, Inc. |
| Hilliard Corporation |
| AMACS Process Towers Internals |
| Air Quality Engineering, Inc. |
| Others |
Cost & Logistics Intelligence
Certified welders for superduplex and Hastelloy mesh-to-support-ring fabrication concentrate in Germany's Rhine-Ruhr corridor and Texas's Gulf Coast, creating labor-cost differentials that widen spreads between premium alloy specifications and standard stainless steel tiers. EPA MACT compliance deadlines in the United States and EU Green Deal enforcement trajectories in Europe amplify these cost gaps as buyers face accelerated replacement schedules.
Pricing Analysis
Distributor margins compress standard stainless steel wire-mesh configurations while direct-to-OEM contracts for cyclonic and vane systems command project-based pricing with performance guarantees. Three-tier pricing structure across premium, standard, and economy levels separates superduplex alloy specifications from 316-grade stainless steel and polypropylene alternatives. Cost compression in the standard tier is intensifying because nickel price volatility destabilizes fabrication margins for extended-lead-time refinery contracts. Municipal wastewater facilities in India exhibit highest price sensitivity, while Middle Eastern petrochemical complexes prioritize operational expenditure certainty over capital cost minimization.
Supply Chain Analysis
Dual-sourcing requirements for PTFE resin qualification mandate multi-supplier relationships among chemical compounders in the United States, Germany, and Japan to mitigate allocation risk during semiconductor demand surges. Raw material dependencies center on nickel-bearing stainless steel feedstock, fluoropolymer resins, and specialty alloy wire drawing capacity concentrated among integrated producers. Single-source vulnerability persists in superduplex welding certification where qualified technicians remain scarce. Distribution runs through EPC contractors executing lump-sum turnkey projects and direct OEM relationships for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as regulatory enforcement compresses replacement cycles and buyer preference consolidates around performance-guaranteed supply contracts bundling equipment, installation supervision, and predictive maintenance subscriptions.
For Market Incumbents: To counter nickel price volatility and qualified welding technician scarcity, secure captive supply of specialty alloy wire drawing capacity and expand in-house certification programs for superduplex and Hastelloy fabrication. Deepen backward integration into corrosion-resistant alloy production to control lead times and stabilize project quoting for extended-lead-time refinery contracts. For New Entrants and Emerging Players: Begin with digital-twin integration and computational fluid dynamics modeling services as a wedge into predictive maintenance contracting, where incumbent engineering bandwidth constraints create white-space opportunity. Target India's Gujarat and Maharashtra petrochemical corridors where mature emissions control infrastructure remains underdeveloped and packaged system demand is ascending. For Investors and Strategic Acquirers: Specialty chemical producers with captive mist elimination fabrication capabilities are the most active acquirer in this space, seeking mass-transfer integration synergies. The long-term viability window favors targets with alloy specification expertise and IoT-enabled service revenue streams. Watch China MEE enforcement trajectories as the signal indicating inflection in replacement cycle velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive wire drawing capacity insulates against nickel volatility and secures EPA MACT-compliant certification timelines. |
| Predictive Maintenance Subscription Launch | CFD modeling convergence with IoT pressure-drop monitoring extends equipment lifecycle revenue beyond initial equipment sale. |
| India Manufacturing Footprint Establishment | Gujarat and Maharashtra corridor positioning captures first-mover advantage in greenfield petrochemical complex procurement. |
| Superduplex Welding Certification Program | In-house technician training alleviates scarcity constraints and accelerates delivery timelines for North Sea sour gas specifications. |
| EU F-Gas Regulation Compliance Transition | Stainless steel construction substitution captures retrofit demand as fluoropolymer formulations face REACH restriction risk. |
Research Approach
Bottom-up chemical processing and power generation modeling reconciled against top-down alloy wire drawing and fabrication capacity tracking forms the analytical core of this study. Primary interviews with plant engineers at petrochemical facilities, procurement leads at EPC contractors, aftermarket service heads, and technical R&D directors at specialty metal producers combined with secondary validation from EPA enforcement databases, ECHA REACH substance restrictions, China MEE opacity monitoring records, and SEC filings from publicly traded separation technology providers.
Historical trendline analysis across installed base replacement cycles, regulatory compliance deadline clustering, and capacity expansion announcements informed projection methodology. Segmentation dimensions modeled include product architecture, material specification grade, application context, and end-user industry vertical. CAGRs were derived from elasticity-adjusted demand curves and supply-side capacity constraints. Forecast inputs incorporated China MEE inspection schedule acceleration and EU F-Gas Regulation amendment timelines.
Several conditions sit outside the modeled scope, including abrupt nickel price dislocations exceeding historical volatility bands, unanticipated semiconductor demand surges absorbing PTFE resin allocation, and geopolitical disruptions to alloy feedstock trade flows. Deviation in EPA MACT enforcement intensity or China MEE audit frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Air Quality Monitoring Software Market
Air Quality Control Systems
Green Emissions Analyzers Market
Air Quality Control Systems
Desiccant Air Breather Market
Air Quality Control Systems
Air Scrubber Market
Air Quality Control Systems
Oxygen Filters Market
Air Quality Control Systems
UV Air Purifiers Market
Air Quality Control Systems
Asia-Pacific Indoor Air Purification Market
Air Quality Control Systems
Europe Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Environmental Control System (ECS) Market
Air Quality Control Systems
Ozone Analyzer Market
Air Quality Control Systems
Asia Pacific Air Filtration Market
Air Quality Control Systems
Southeast Asia Air Purifier Market
Air Quality Control Systems
United States Pollution Mask Market
Air Quality Control Systems
Europe Industrial Air Quality Control Systems Market
Air Quality Control Systems
Asia-Pacific Air Quality Control System Market
Air Quality Control Systems
Industrial Air Quality Control Systems Market