
 Asia-Pacific Air Quality Control System Market | 2026-2036
Asia-Pacific Air Quality Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Air Quality Control System Market Outlook
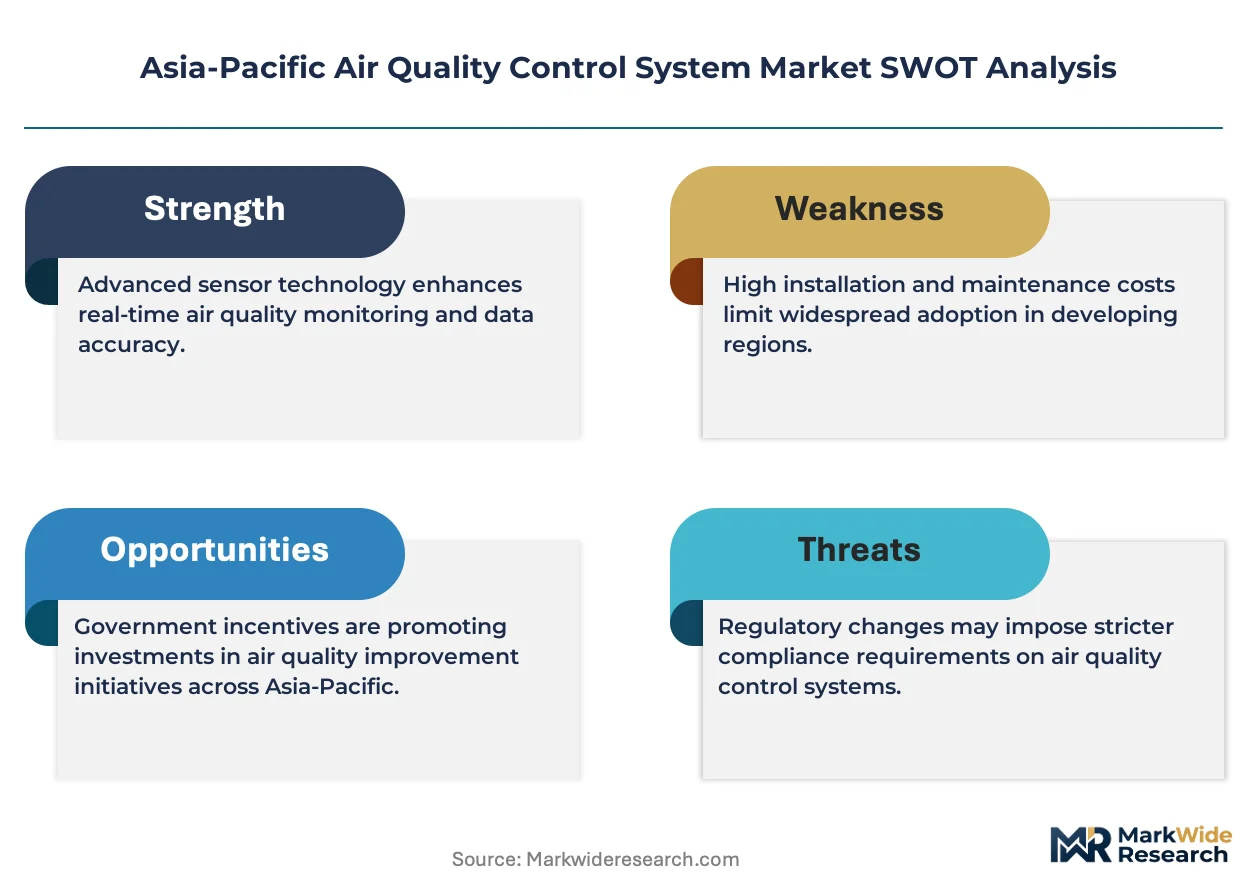
Scarce instrumentation engineers with cross-training in IoT analytics is reorganizing project timelines across the Asia-Pacific Air Quality Control System Market. Fujian Longking leverages its captive manufacturing base in Fujian Province to dominate domestic flue-gas desulfurization tenders. Mitsubishi Heavy Industries anchors its regional position through specialized large-scale electrostatic precipitator systems for utility boilers. Siemens competes on digital twin integration for predictive maintenance of continuous emission monitoring networks.
Asia-Pacific air quality control systems encompass engineered equipment and sensor networks designed to capture, neutralize, or monitor airborne contaminants across industrial, commercial, and ambient environments. Electrostatic precipitators operate at collection efficiencies exceeding 99 percent for particulate matter down to one micron, while wet scrubbers neutralize acid gases through liquid-phase absorption chemistry. Indoor systems and continuous emission monitoring systems command the deepest margin pools, with the former benefiting from post-pandemic building ventilation upgrades and the latter tied to mandatory stack-monitoring regulations. Optical sensors and electrochemical sensors represent the fastest-expanding technology pairing, as distributed monitoring grids replace centralized analyzer stations.
China's Ministry of Ecology and Environment enforces ultra-low emission standards for thermal power and steel, while India's Central Pollution Control Board mandates online continuous emission monitoring for seventeen highly polluting industrial categories. Japan's METI coordinates national air quality management through its Environmental Quality Standards for nitrogen dioxide and particulate matter, creating certified product requirements for monitoring equipment. Stakeholders must weigh localization commitments against technology transfer costs as procurement rules in China and India harden domestic content thresholds.
Market Dynamics
Ultra-low emission mandates from China's Ministry of Ecology and Environment are forcing steel and thermal power operators to retrofit legacy stacks with multi-pollutant capture systems, compressing project timelines and redrawing supplier qualification criteria across the regional value chain.
Growth Catalysts
- MEE Ultra-Low Standards:China's thermal power and steel sectors must achieve particulate matter concentrations below 10 mg per cubic meter, triggering scrubber and electrostatic precipitator procurement waves across the Yangtze River Delta and Hebei Province.
- India's CEMS Mandate:The Central Pollution Control Board requires online continuous emission monitoring across seventeen highly polluting industrial categories, creating installed base expansion for analyzer networks in cement, aluminum, and fertilizer clusters.
- Electrochemical Sensor Diffusion:Distributed monitoring grids around Japan's Nagoya industrial corridor are replacing centralized analyzer stations, cutting per-node capital costs while expanding spatial coverage for fugitive emission detection.
Market Restraints
- Specialized Talent Scarcity:Cross-trained instrumentation engineers capable of integrating IoT analytics with legacy DCS architectures command premium compensation, extending system commissioning timelines by four to eight months in secondary Chinese cities.
- Domestic Content Thresholds:Hardening localization rules in China and India require foreign suppliers to establish captive manufacturing or joint ventures, elevating technology transfer costs and complicating intellectual property protection.
- Reagent Supply Concentration:Wet scrubber operations depend on limestone and caustic soda inputs sourced from concentrated mining and chemical processing clusters, exposing operating cost volatility to regional logistics disruptions.
Strategic Opportunities
- Indonesia's Industrial Corridor Buildout:New nickel smelting and coal-fired generation capacity in Sulawesi and Kalimantan lacks mature emission control infrastructure, creating first-mover advantage for integrated system providers.
- Digital Twin Convergence:Predictive maintenance platforms combining continuous emission data with boiler combustion modeling are penetrating utility boiler segments, unbundling traditional hardware-service pricing.
- Vietnam's Power Development Plan:Coal-fired capacity additions through 2030 must comply with tightening stack emission limits, generating demand for flue-gas desulfurization and denitrification systems in the Mekong Delta region.
Industry Challenges
- Legacy Stack Retrofit Complexity:Integrating multi-pollutant capture systems with existing electrostatic precipitator footprints requires custom ductwork and control system reconfiguration, elevating engineering risk and cost overruns.
- Certification Timeline Compression:Japan's METI certified product requirements for nitrogen dioxide and particulate matter monitoring equipment demand extended validation cycles, delaying commercial deployment of new sensor technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Air Quality Control System Market |
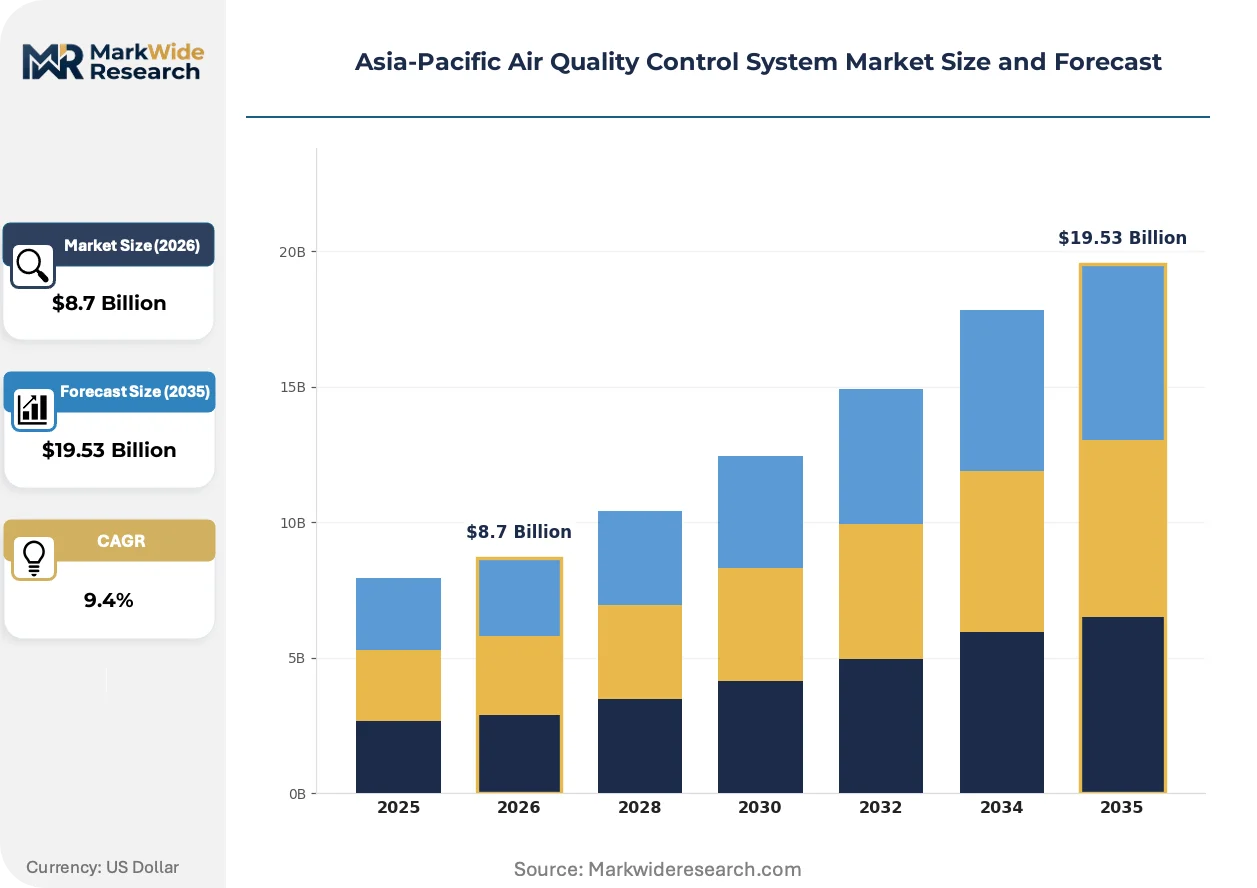
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Systems, Outdoor Systems, Portable Monitors, Continuous Emission Monitoring Systems Technology: Active Sampling, Passive Sampling, Optical Sensors, Electrochemical Sensors End User: Industrial, Residential, Commercial, Government Application: Pollution Monitoring, Ventilation Control, Compliance Reporting, Health Assessment |
| Companies Covered | Fujian Longking, Siemens, Mitsubishi Heavy Industries, Hamon Corporation, Babcock & Wilcox Enterprises, Thermax, Hitachi, John Wood Group, General Electric Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Air Quality Control System Market Strategic Shifts
Sensor architecture and regulatory enforcement modalities are diverging sharply across the Asia-Pacific region, creating technology adoption patterns that vary by industrial maturity and ambient air quality priority.
Optical sensing paired with electrochemical detection is bifurcating the continuous emission monitoring landscape. Steel mills in China's Hebei Province are deploying hybrid sensor arrays for real-time multi-pollutant tracking. This convergence is compressing demand for centralized analyzer stations while expanding the addressable market for distributed node networks.
India's Central Pollution Control Board has mandated third-party data validation for all online continuous emission monitoring systems, effective across cement, power, and aluminum installations. This requirement is elevating demand for tamper-proof data acquisition and transmission hardware. System integrators are responding by embedding blockchain-anchored logging capabilities in new analyzer deployments.
Steel producers in the Yangtze River Delta are unbundling hardware procurement from long-term service agreements, compressing initial capital outlays while shifting lifecycle value toward performance-based maintenance contracts. This transition is displacing traditional turnkey project structures. Equipment vendors are restructuring sales organizations to capture recurring revenue from sensor calibration and reagent supply.
Asia-Pacific Air Quality Control System Market Segmentation
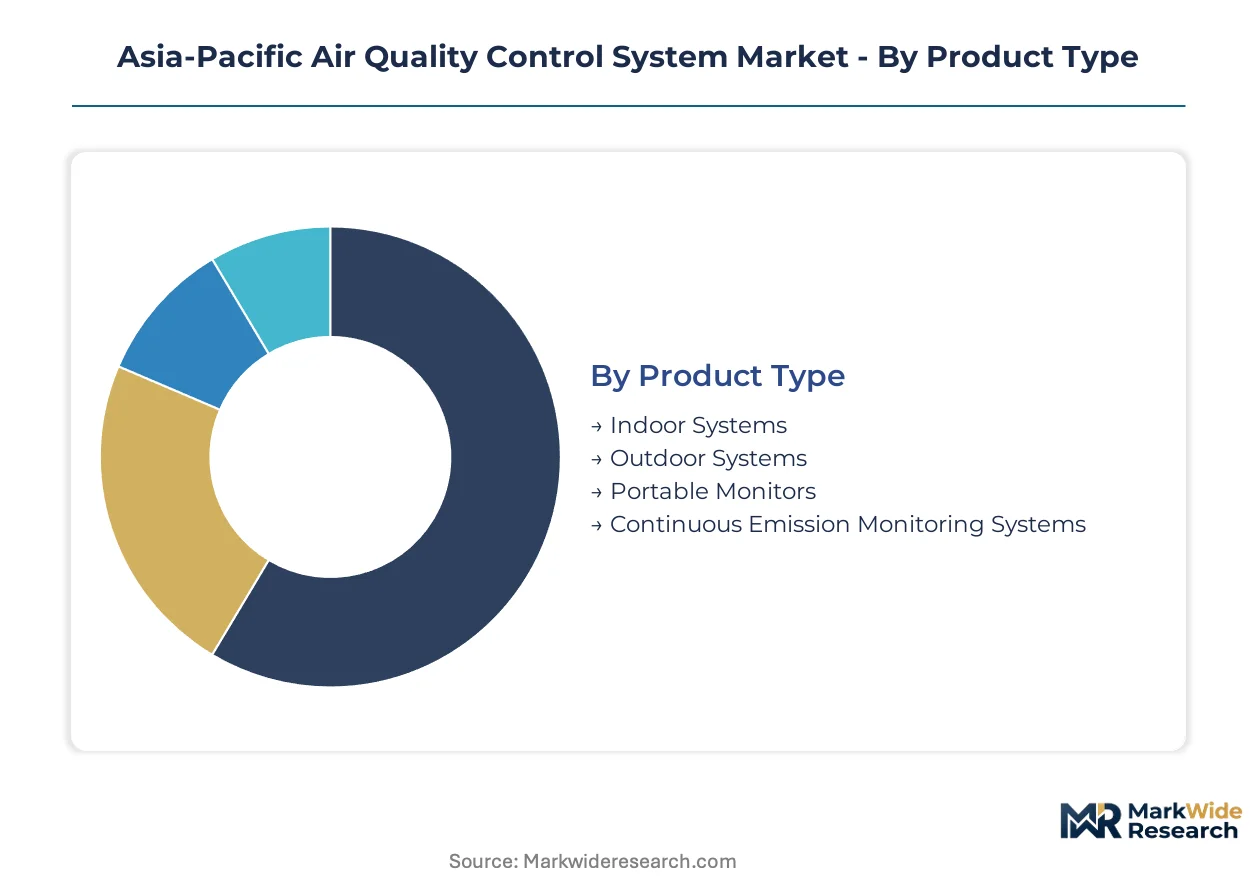
Asia-Pacific air quality control procurement patterns diverge sharply between export-oriented industrial clusters and domestically focused building ventilation markets. Segment performance tracks regulatory enforcement intensity, with continuous emission monitoring and electrochemical sensing gaining disproportionate share in China's ultra-low emission zones and Japan's industrial corridors.
Product Type:
Domestic demand concentrates in indoor and portable systems across Southeast Asian building stock, while export-led manufacturing in China and Japan drives continuous emission monitoring and outdoor infrastructure procurement.
- Indoor Systems:Building-integrated filtration and ventilation units with HEPA and activated carbon stages. Post-pandemic building codes in Singapore and South Korea mandate upgraded air exchange rates in commercial towers, compressing replacement cycles.
- Continuous Emission Monitoring Systems:Stack-mounted analyzer networks with data acquisition and transmission hardware for regulatory reporting. China's MEE ultra-low standards and India's CPCB online mandate are forcing retrofit waves across thermal power and steel installations in the Yangtze River Delta and Chhattisgarh.
- Outdoor Systems:Ambient monitoring stations with meteorological sensors for urban airshed management.
- Portable Monitors:Handheld electrochemical and optical units for spot-checking and field audits.
Continuous Emission Monitoring Systems holds the largest share; momentum sits with Indoor Systems.
Technology:
Cost tier stratification separates high-precision optical systems for utility compliance from electrochemical nodes for distributed industrial monitoring.
- Electrochemical Sensors:Gas-specific amperometric cells measuring nitrogen oxides, sulfur dioxide, and ozone at parts-per-billion sensitivity. Japan's Nagoya industrial corridor is replacing centralized analyzers with distributed electrochemical grids, cutting capital cost per monitoring node while expanding spatial coverage.
- Optical Sensors:Non-dispersive infrared and ultraviolet absorption spectroscopy for multi-gas quantification. Steel mills in Hebei Province deploy hybrid optical-electrochemical arrays for real-time multi-pollutant tracking, compressing demand for legacy centralized stations.
- Active Sampling:Pump-driven collection with pre-concentration for trace-level analysis.
- Passive Sampling:Diffusion-based collection without power requirements for long-term trend monitoring.
Optical Sensors command the premium tier; Electrochemical Sensors are climbing the fastest.
End User:
Application maturity varies by customer type, with industrial procurement driven by mandatory compliance and residential demand responding to health awareness and building certification programs.
- Industrial:Heavy manufacturing, power generation, and mineral processing operators deploying multi-pollutant capture and monitoring infrastructure. China's steel sector in Jiangsu and Shanxi provinces accounts for concentrated scrubber and precipitator procurement under MEE enforcement.
- Government:Environmental protection bureaus and municipal air quality authorities operating reference-grade monitoring networks. India's Central Pollution Control Board is expanding its national ambient monitoring program across tier-2 cities, creating analyzer procurement pipelines.
- Commercial:Office complexes, retail, and hospitality operators upgrading ventilation filtration.
- Residential:Individual households purchasing standalone purifiers and personal monitors.
Industrial end users dominate volume; Government procurement shows the steepest expansion trajectory.
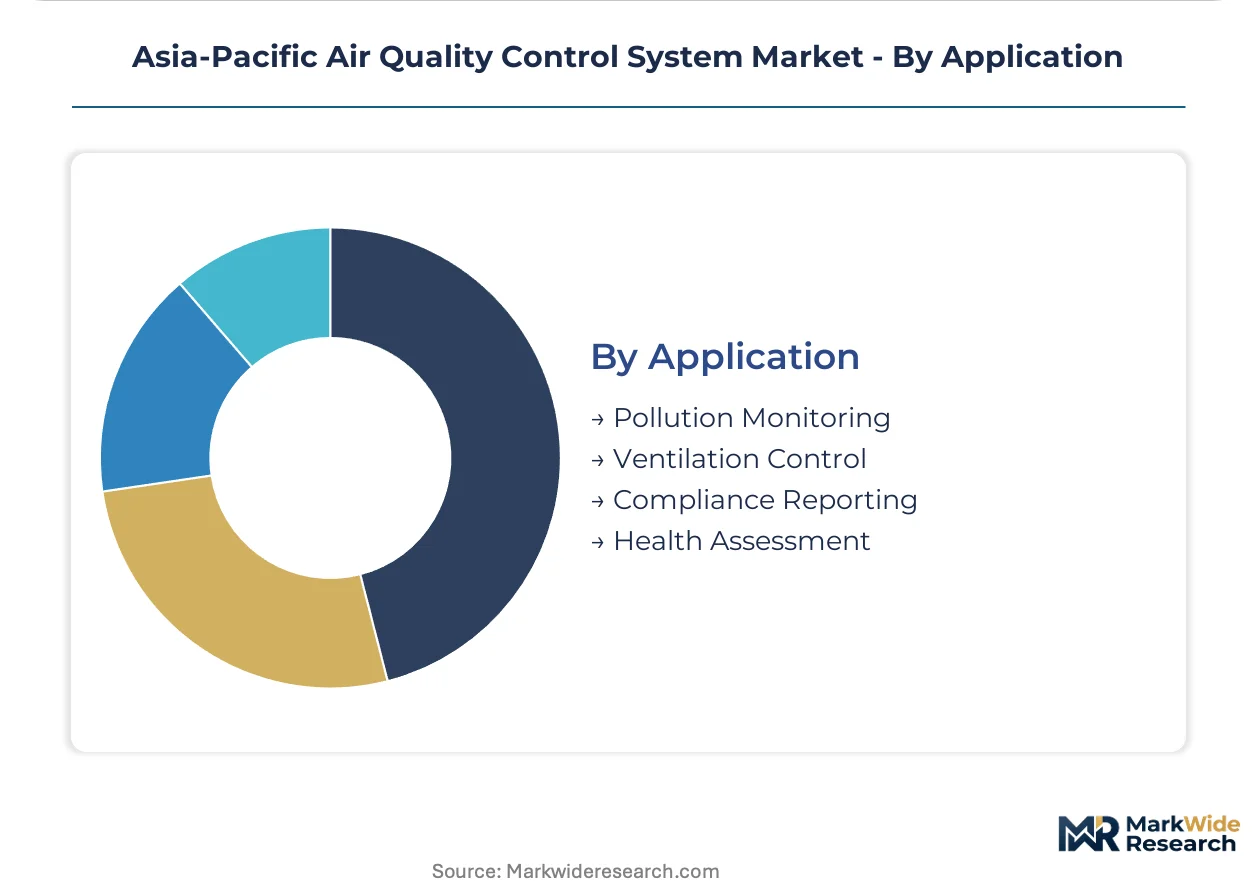
Application:
Supply concentration aligns with compliance reporting infrastructure in China and India, while health assessment applications diffuse across higher-income markets with established certification schemes.
- Compliance Reporting:Automated data transmission to environmental regulators with tamper-proof logging and third-party validation. India's CPCB mandate for blockchain-anchored data acquisition is elevating hardware specifications across cement, aluminum, and fertilizer installations.
- Pollution Monitoring:Real-time measurement of particulate matter, nitrogen dioxide, and ozone for regulatory and public information purposes. Urban airshed management in Jakarta, Bangkok, and Ho Chi Minh City is driving densification of reference-grade station networks.
- Ventilation Control:Demand-controlled fresh air systems responding to indoor contaminant levels.
- Health Assessment:Exposure quantification for occupational safety and epidemiological studies.
Compliance Reporting anchors the installed base; Pollution Monitoring is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ministry of Ecology and Environment anchors regulatory momentum across the Asia-Pacific air quality control landscape, with ultra-low emission mandates cascading through industrial corridors from Hebei to Jiangsu provinces.
China
Steel mills and thermal power operators in the Yangtze River Delta and Hebei Province are retrofitting legacy stacks with multi-pollutant capture systems under MEE enforcement. The ultra-low emission standards mandate particulate matter concentrations below 10 mg per cubic meter. Provincial environmental bureaus in Jiangsu are compressing supplier qualification timelines for scrubber and electrostatic precipitator procurement.
India
Cement, aluminum, and fertilizer clusters in Chhattisgarh and Gujarat are expanding analyzer network installations. The Central Pollution Control Board mandates online continuous emission monitoring across seventeen highly polluting industrial categories. Third-party data validation requirements are elevating demand for tamper-proof hardware in the National Capital Region industrial belt.
Japan
Distributed electrochemical sensor grids are displacing centralized analyzer stations in the Nagoya industrial corridor. METI coordinates national air quality management through Environmental Quality Standards for nitrogen dioxide and particulate matter. Certified product requirements for monitoring equipment are extending validation cycles for new sensor commercialization in the Chubu region.
Indonesia
Nickel smelting and coal-fired generation capacity in Sulawesi and Kalimantan lacks mature emission control infrastructure. National regulations are tightening stack emission limits for new industrial investments. First-mover system providers are securing integrated procurement contracts in the Morowali industrial park.
Vietnam
Coal-fired capacity additions through 2030 under the Power Development Plan must comply with tightening emission standards. Flue-gas desulfurization demand is concentrating in the Mekong Delta region. Domestic engineering firms are partnering with foreign technology licensors to meet localization thresholds for utility boiler projects.
Asia-Pacific Air Quality Control System Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with market structure stratifying between captive manufacturing advantages and digital service capabilities. The vendor landscape organizes around three archetypes: integrated industrial conglomerates with captive production bases, precision engineering specialists focused on large-scale utility applications, and digital-technology providers bundling predictive maintenance platforms. Competitive dynamics center on localization commitments through joint ventures and captive manufacturing, alongside unbundling of hardware procurement from long-term service agreements.
Within the integrated industrial tier, Fujian Longking exemplifies the captive manufacturing archetype through its Fujian Province production base. Mitsubishi Heavy Industries anchors the precision engineering segment with specialized electrostatic precipitator systems. Siemens occupies a position at the digital convergence vector, competing on predictive maintenance integration for emission monitoring networks.
| Leading Market Players |
|---|
| Fujian Longking |
| Siemens |
| Mitsubishi Heavy Industries |
| Hamon Corporation |
| Babcock & Wilcox Enterprises |
| Thermax |
| Hitachi |
| John Wood Group |
| General Electric Company |
| Others |
Value Chain & Pricing Dynamics
Fourteen-week lead times for electrostatic precipitator transformer-rectifier sets concentrate pricing power with Fujian-based manufacturers serving China's Yangtze River Delta retrofit wave, while limestone reagent inventory cycles of twenty-one days expose scrubber operators to input cost volatility during supply disruptions.
Pricing Analysis
Price spreads between Japanese-certified electrochemical sensor modules and Indian-assembled analyzer networks exceed three-to-one across comparable specification bands. Three-tier pricing structure across premium, standard, and economy levels separates METI-validated optical systems from utility-grade continuous emission monitoring hardware and basic portable electrochemical units. Cost compression in economy-tier portable monitors is intensifying because Southeast Asian procurement offices prioritize upfront capital savings over calibration accuracy. Government environmental bureaus in China and India exhibit lowest price sensitivity due to mandatory compliance deadlines, while Indonesian nickel smelter developers negotiate hardest on total installed cost.
Supply Chain Analysis
Port congestion at Shanghai and Ningbo elevates inbound logistics costs for German-sourced ultraviolet spectrometer components destined for Hebei Province steel mill installations. Manufacturing concentration in China, Japan, and South Korea anchors production of optical sensor arrays and electrostatic precipitator internals. Wet scrubber operations draw from limestone deposits in Vietnam and caustic soda from Chinese chemical processing clusters. Single-source vulnerability for high-purity optical gratings creates procurement risk for precision analyzer manufacturers. Distribution runs through systems integrators with regional service capabilities rather than direct equipment vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among China's provincial environmental bureaus and India's Central Pollution Control Board as consolidated procurement frameworks displace fragmented plant-level purchasing.
For Market Incumbents: Shield installed base positions in China's ultra-low emission zones by embedding predictive maintenance platforms that raise switching costs for steel and power operators facing MEE enforcement deadlines. Deepen backward integration into electrochemical sensor cell production to offset technology transfer pressures from hardening domestic content rules. Prioritize certification investment for METI-validated equipment to maintain premium positioning in Japan's replacement cycles. For New Entrants and Emerging Players: Aftermarket calibration services for India's CPCB-mandated continuous emission monitoring networks represent the most penetrable white-space target, as incumbent hardware vendors under-serve tier-2 industrial clusters in Chhattisgarh and Gujarat with responsive technical support. Target Vietnam's Mekong Delta power development corridor with flue-gas desulfurization system packages bundled with localization partnerships to satisfy domestic engineering requirements. Lead with performance-based maintenance contracts rather than turnkey capital sales to bypass entrenched supplier relationships. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because emission monitoring mandates are hardening across industrializing economies with limited reversal probability. Acquisition targets should emphasize electrochemical sensor specialists with software-layer capabilities and existing certification in multiple Asia-Pacific jurisdictions. Watch for inflection when Indonesia's Morowali industrial park mandates online stack monitoring for nickel processing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture with Local Engineering Partner | Meets China's domestic content thresholds for Yangtze River Delta scrubber tenders. |
| Digital Twin Platform Integration | Captures recurring revenue from predictive maintenance of MEE-mandated analyzer networks. |
| Backward Integration into Sensor Cell Production | Reduces exposure to technology transfer costs under India's hardening localization rules. |
| Long-term Service Agreement Unbundling | Aligns vendor economics with steel mill performance-based procurement restructuring. |
| Certification Investment for METI Validation | Extends commercialization runway for electrochemical sensor commercialization in Japan. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with environmental compliance officers at steel and power operators, instrumentation procurement leads at provincial environmental bureaus, systems integration engineers, and aftermarket service heads. Secondary validation drew from MEE enforcement bulletins, CPCB online monitoring mandates, METI certified product registries, customs data on analyzer component trade flows, and equipment vendor SEC disclosures. Bottom-up installed base estimates were triangulated against top-down regulatory mandate coverage projections.
Across the analysis window, volume and value outputs reflect segmentation modeling across product type, technology tier, end-user category, and application purpose, with additional dimensioning by provincial regulatory enforcement intensity in China and industrial cluster maturity in India. CAGRs were derived from regression against historical procurement waves tied to MEE ultra-low standard phase-ins and CPCB online mandate rollouts. Forecast inputs incorporated scrubber retrofit pipeline data from Hebei and Jiangsu provinces and electrochemical sensor deployment trajectories in Japan's Nagoya corridor.
Underlying assumptions cover sustained enforcement of particulate matter limits below ten milligrams per cubic meter, with deviation risk concentrated in provincial implementation timeline delays or relaxation of domestic content thresholds. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Ozone Analyzer Market
Air Quality Control Systems
Industrial Air Quality Control Systems Market
Air Quality Control Systems
North America Industrial Air Quality Control Systems Market
Air Quality Control Systems
Anti-Pollution Mask Market
Air Quality Control Systems
Air Quality Control Systems Market
Air Quality Control Systems
Air Pollution Control Equipment Market
Air Quality Control Systems
Anti-Pollution Toner Market
Air Quality Control Systems
Indoor Air Purification Market
Air Quality Control Systems
UV Air Purifiers Market
Air Quality Control Systems
Europe Industrial Air Quality Control Systems Market
Air Quality Control Systems
Air Quality Monitoring Software Market
Air Quality Control Systems
US Air Quality Analyzers Market
Air Quality Control Systems
Desiccant Air Breather Market
Air Quality Control Systems
Europe Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Asia Pacific Air Filtration Market
Air Quality Control Systems
Air Scrubber Market