
 Europe Air Quality Monitoring Market | 2026-2036
Europe Air Quality Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Air Quality Monitoring Market Insights
Project finance and municipal leasing arrangements for sensor networks is narrowing the competitive field to vendors with balance-sheet capacity for multi-year service contracts. Honeywell International Inc. leverages its building automation footprint to bundle indoor air quality systems with climate controls. Horiba Ltd. anchors its position through optical analyzer specialization for regulatory-grade measurements. Siemens AG competes by integrating monitoring hardware with grid-scale digital twins for industrial clients.
Europe air quality monitoring encompasses instruments that detect particulate matter, nitrogen oxides, sulfur dioxide, ozone, and volatile organic compounds through electrochemical reaction, light scattering, or gravimetric collection, with detection thresholds typically calibrated to EU reference methods for ambient air directive compliance. These systems serve environmental agencies, industrial operators, and urban planners by generating legally defensible emissions data and triggering automated alerts when pollutant thresholds breach permitted levels. Fixed outdoor monitors dominate capital deployment due to permanent regulatory station mandates, while portable units represent the fastest-expanding category as workplace safety inspectors and construction firms adopt handheld electrochemical devices for spot-check flexibility. Cloud-based deployment architectures are displacing on-premise data logging as environmental agencies centralize real-time dashboards across distributed sensor grids.
The EU Green Deal and F-Gas Regulation establish binding emission reduction trajectories that mandate continuous monitoring verification, while EEA reporting standards require member states to maintain harmonized measurement protocols for cross-border airshed management. CE marking under the MDR and EMC directives constrains hardware design, creating compliance barriers for non-European suppliers lacking notified body relationships. Stakeholders must weigh the trade-off between capital-intensive reference-grade installations and denser networks of lower-cost sensors when designing monitoring strategies for emerging pollutant categories.
Market Dynamics
EU Green Deal emission reduction mandates are compressing replacement cycles for legacy monitoring infrastructure across municipal networks and industrial facilities, while project finance arrangements for multi-year sensor deployments favor vendors with balance-sheet capacity for service contracting.
Growth Catalysts
- EU Green Deal binding trajectories:Member states must verify continuous emission reductions through certified monitoring networks, accelerating capital deployment for reference-grade stations in urban corridors.
- Electrochemical handheld devices:Workplace safety inspectors and construction firms adopt portable units for spot-check flexibility, expanding the fastest-growing product category beyond fixed installations.
- Netherlands-Belgium-Northern Italy industrial corridor:Dense manufacturing concentration creates concentrated demand for regulatory-grade monitoring at facility perimeters and fence-line communities.
Market Restraints
- CE marking compliance barriers:MDR and EMC directive requirements constrain hardware design, excluding non-European suppliers lacking notified body relationships and extending time-to-market.
- Optical analyzer component concentration:Specialized photodetector and laser sources concentrate among limited precision optics suppliers, creating input vulnerability for regulatory-grade instrument manufacturers.
- Gravimetric reference method persistence:EU ambient air directive mandates gravimetric collection for legal defensibility, limiting full substitution by faster electrochemical alternatives despite operational advantages.
Strategic Opportunities
- Eastern European municipal networks:Poland, Romania, and Bulgaria maintain sparse monitoring density relative to Western counterparts, presenting whitespace for EU-funded infrastructure expansion under cohesion policy allocations.
- Cloud-based data logging architectures:Environmental agencies centralize real-time dashboards across distributed sensor grids, displacing on-premise systems and opening recurring SaaS revenue streams for platform vendors.
- F-Gas Regulation verification mandates:Synthetic fluorinated gas monitoring requirements for industrial refrigeration and semiconductor manufacturing create incremental sensor demand beyond traditional pollutant categories.
Industry Challenges
- Metrology calibration technician scarcity:Reference-grade analyzer maintenance requires specialized skills in gravimetric calibration and optical alignment that outpace vocational training pipeline output.
- Cross-border airshed data harmonization:EEA reporting standards demand protocol alignment between member states with divergent legacy infrastructure, complicating integrated modeling for transboundary pollution events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Air Quality Monitoring Market |
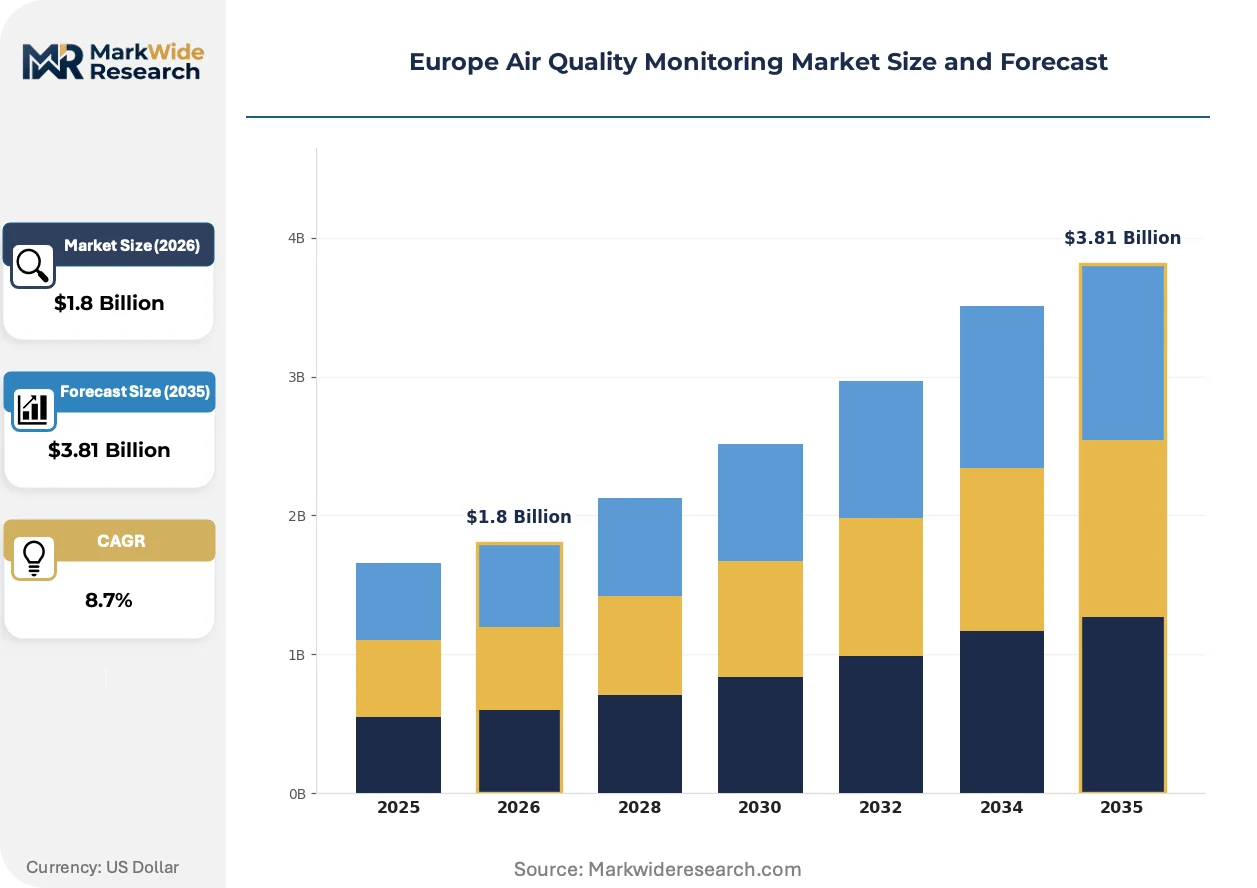
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Fixed Monitors, Indoor Monitors, Outdoor Monitors Technology: Electrochemical, Optical, Laser, Gravimetric End User: Public Sector, Private Companies, Research Institutions, Environmental Agencies Deployment: On-Premise, Cloud-Based, Hybrid, Remote Monitoring |
| Companies Covered | Honeywell International Inc., Horiba Ltd., 3M Company, Thermo Fisher Scientific Inc., Siemens AG, Emerson Electric Co., Teledyne Technologies Inc., TSI Inc., Aeroqual Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Air Quality Monitoring Market Trends and Innovations
Sensor miniaturization and edge computing integration are restructuring how environmental agencies architect monitoring networks, shifting capital allocation from fewer high-cost stations toward denser grids of lower-unit-cost devices with centralized analytics.
Low-cost particulate matter sensors employing light scattering detection are digitizing field data collection at municipal scale. German and French urban authorities deploy hundreds of nodes per city for hyperlocal pollution mapping. Cloud aggregation platforms compress the cost per data point while maintaining correlation to reference-grade instruments through machine-learned calibration models.
EU F-Gas Regulation phase-down schedules tighten verification requirements for synthetic fluorinated gas emissions from industrial refrigeration and electronics manufacturing. Facilities must install continuous monitoring for compounds previously unregulated. Northern Italian semiconductor clusters and Belgian chemical processors face the steepest compliance timelines, driving analyzer procurement for compounds with no historical measurement infrastructure.
Service unbundling from hardware procurement is altering municipal acquisition patterns. French and Dutch environmental agencies now separate sensor capital purchase from multi-year data management contracts, enabling specialized analytics firms to compete without manufacturing assets. This bifurcation concentrates in urban deployments where real-time public dashboards require dedicated platform operations rather than traditional instrument vendor support.
Europe Air Quality Monitoring Market Segmentation
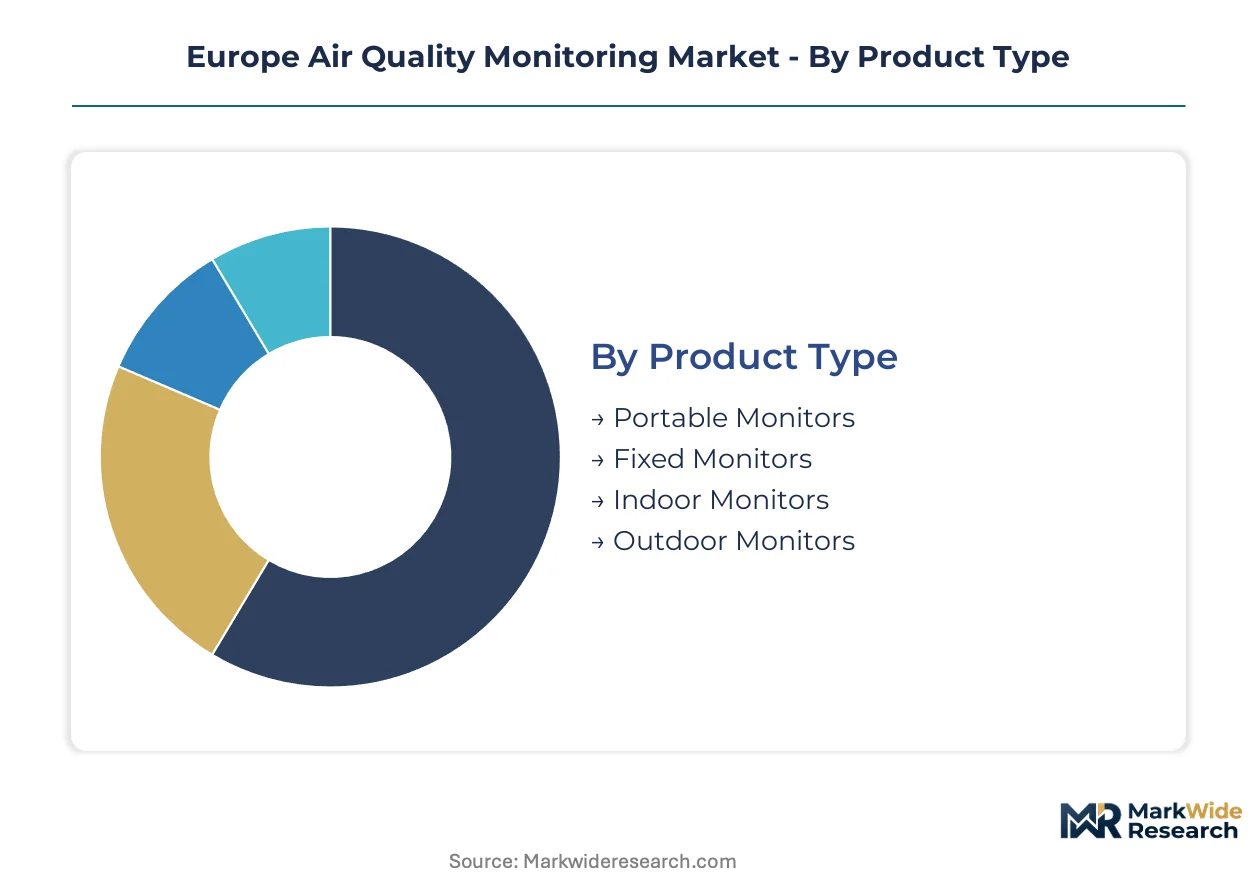
Product configuration, sensing technology, and deployment architecture determine procurement economics and compliance pathways across European air quality monitoring. Segment selection shapes capital intensity, recurring revenue potential, and regulatory defensibility for vendors and buyers alike.
Product Type:
Cost tier separates permanent infrastructure investments from flexible, lower-unit-cost alternatives suitable for spot-check or supplemental deployment.
- Fixed Monitors:Permanent installations employ reference-grade analyzers calibrated to EU ambient air directive methods for legal defensibility. Municipal networks across Germany and France anchor procurement volume as legacy station replacement cycles compress under Green Deal timelines.
- Portable Monitors:Handheld electrochemical units enable workplace safety inspectors and construction firms to conduct spot-check measurements without permanent infrastructure. Belgian and Dutch industrial corridor demand concentrates here for fence-line community verification.
- Indoor Monitors:Compact sensors track particulate matter and volatile organic compounds within commercial buildings and residential complexes. Building automation integrators bundle these with climate control systems for facility managers.
- Outdoor Monitors:Weather-hardened enclosures house multi-parameter analyzers for continuous ambient surveillance. Urban authorities deploy these at traffic intersections and industrial perimeters for regulatory station density.
Fixed monitors command the established base. The steepest expansion runs through portable units.
Technology:
Detection principle governs accuracy thresholds, maintenance burden, and alignment with EU reference method requirements for regulatory-grade measurements.
- Electrochemical:Gas-specific electrodes generate current proportional to target analyte concentration, enabling compact, lower-power designs. Portable device manufacturers favor this approach for nitrogen oxide and sulfur dioxide detection in field applications.
- Gravimetric:Filter-based mass collection provides the sole legally defensible method for particulate matter under EU ambient air directive mandates. Reference station operators must maintain these despite operational complexity and slower data turnaround.
- Optical:Light scattering and absorption techniques deliver real-time particulate sizing with lower maintenance than gravimetric alternatives. Municipal sensor networks across Italian urban centers adopt these for hyperlocal pollution mapping density.
- Laser:Cavity ring-down and tunable diode absorption achieve parts-per-trillion sensitivity for emerging pollutant categories. F-Gas Regulation verification for synthetic fluorinated compounds drives analyzer procurement from northern Italian semiconductor clusters.
Gravimetric methods anchor regulatory compliance. Optical platforms are climbing the fastest for network density expansion.
End User:
Customer type determines procurement authority, contract structure, and technical specification stringency across the value chain.
- Environmental Agencies:National and regional authorities operate reference-grade networks with mandatory EEA reporting obligations. These buyers specify full EU method compliance and centralized data aggregation platforms.
- Public Sector:Municipal governments deploy urban sensor grids for public health dashboards and traffic management integration. French and Dutch authorities increasingly unbundle hardware procurement from multi-year data service contracts.
- Private Companies:Industrial operators install perimeter monitoring for license-to-operate compliance and community relations. Belgian chemical processors and Dutch manufacturing facilities drive demand for continuous emission verification.
- Research Institutions:Universities and national laboratories procure specialized analyzers for atmospheric chemistry studies and sensor validation. These buyers prioritize measurement precision over regulatory certification speed.
Environmental agencies command the established base. Private sector procurement is gaining share fastest as industrial permit conditions tighten.
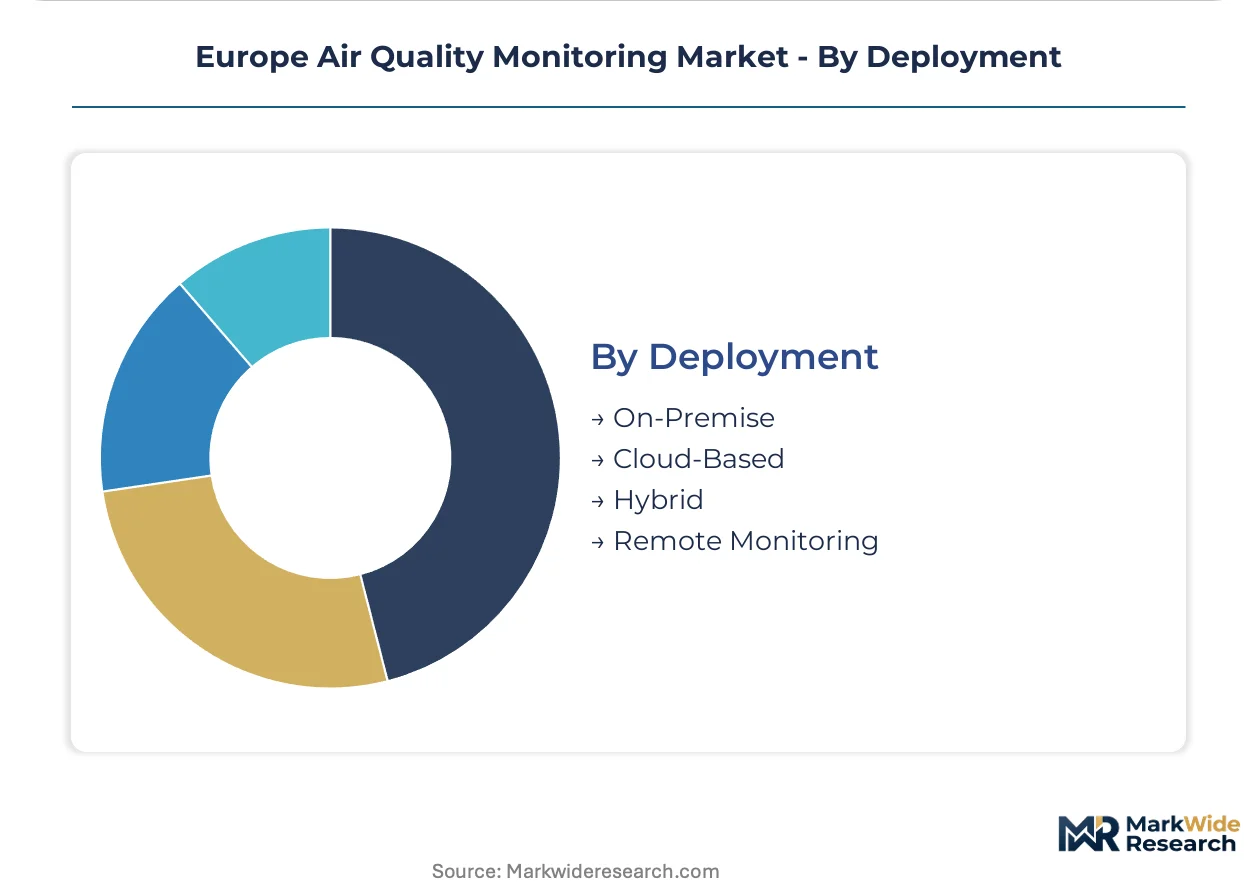
Deployment:
Architecture choice between localized and centralized data management reshapes vendor competitive position and customer switching costs.
- Cloud-Based:Real-time data streaming to centralized platforms enables cross-jurisdictional dashboard integration and machine-learned calibration. Environmental agencies across France and Germany displace legacy on-premise logging for distributed sensor grid management.
- On-Premise:Local data retention meets cybersecurity requirements for critical infrastructure operators and satisfies institutional data sovereignty preferences. Some German municipal networks retain this architecture for air quality control center operations.
- Hybrid:Edge preprocessing with cloud aggregation balances latency-sensitive alerting with centralized analytics. Industrial facilities in the Netherlands-Belgium corridor adopt this for perimeter monitoring with automated threshold breach notifications.
- Remote Monitoring:Satellite telemetry and cellular backhaul extend coverage to rural stations and mobile measurement campaigns. Eastern European cohesion fund projects specify this for sparse network expansion in Poland and Romania.
On-premise systems command the installed base. Cloud architectures are expanding most quickly as agencies centralize distributed grid management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's air quality monitoring sector runs a modest trade surplus in high-precision instrumentation, with German and French manufacturers exporting reference-grade analyzers to Eastern European cohesion fund projects while importing specialized optical components from Swiss and Japanese suppliers.
Germany
Municipal governments in North Rhine-Westphalia and Bavaria are replacing legacy monitoring stations at accelerated cycles under EU Green Deal timelines. The Federal Environment Agency mandates continuous emission verification through certified reference methods. Industrial clusters around the Rhine-Ruhr corridor deploy perimeter monitoring for fence-line community protection.
France
Airparif and regional air quality networks in Île-de-France are unbundling hardware procurement from multi-year data service contracts. The French Environment Code transposes EU ambient air directive requirements into national enforcement protocols. Lyon and Marseille authorities deploy hyperlocal sensor grids for traffic-related pollution mapping.
Netherlands
The Port of Rotterdam and Eindhoven manufacturing belt drive concentrated demand for F-Gas Regulation compliance monitoring. RIVM national standards require harmonized measurement protocols for transboundary airshed management. Dutch environmental agencies centralize real-time dashboards across distributed sensor grids through cloud-based architectures.
Italy
Northern Italian semiconductor clusters in Lombardy face steep F-Gas Regulation timelines for synthetic fluorinated compound verification. ARPA regional agencies maintain reference-grade networks for EEA reporting obligations. The Po Valley industrial corridor generates sustained procurement for continuous emission monitoring at chemical processing facilities.
Poland
Warsaw and Krakow municipal authorities leverage EU cohesion policy allocations to expand sparse monitoring density relative to Western counterparts. The Chief Inspectorate of Environmental Protection enforces transposed ambient air quality standards. Silesian industrial basins drive demand for regulatory-grade perimeter monitoring at coal-to-gas transition facilities.
Europe Air Quality Monitoring Market Competitive Landscape
On the supply side, the industry is consolidating around vendors with balance-sheet capacity for multi-year municipal service contracts. Tiered competitive dynamics separate reference-grade instrument specialists from building automation integrators and portable device manufacturers. Dominant competitive moves include strategic partnerships for cloud platform integration and portfolio diversification into indoor air quality systems.
Among diversified industrial conglomerates, Honeywell International Inc., Siemens AG, and Emerson Electric Co. occupy positions that leverage existing building automation and industrial control footprints to bundle monitoring hardware with broader facility management systems. These players exemplify the scale-driven tier where cross-selling opportunities and project finance capacity create defensive positioning against specialized instrument pure-plays.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Horiba Ltd. |
| 3M Company |
| Thermo Fisher Scientific Inc. |
| Siemens AG |
| Emerson Electric Co. |
| Teledyne Technologies Inc. |
| TSI Inc. |
| Aeroqual Limited |
| Others |
Pricing and Supply Chain Analysis
Swiss precision optics manufacturers around Zurich and Neuchâtel constrain photodetector availability for laser-based analyzers, concentrating upstream bargaining power and compressing margins for regulatory-grade instrument assemblers serving Dutch and Belgian industrial corridors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with premium tiers commanding certification to EU reference methods and CE marking under MDR directives. Price differentiation hinges on calibration traceability and after-sales service bundling, while cost compression in economy tiers intensifies as municipal leasing arrangements favor multi-year service contracts over capital purchase. Environmental agencies exhibit lowest price sensitivity due to legal defensibility requirements, whereas construction firms deploying portable units demonstrate highest elasticity.
Supply Chain Analysis
Photodetector arrays and laser sources draw from Switzerland, Japan, and Germany, while electrochemical sensor membranes and gravimetric filter substrates rest on specialty chemical suppliers in the Netherlands and France. Single-source vulnerability concentrates in tunable diode laser components for F-Gas Regulation analyzers. Distribution runs through authorized instrumentation distributors serving environmental agencies and industrial facility managers across the Netherlands-Belgium-Northern Italy corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based data aggregation platforms are restructuring Europe air quality monitoring toward ecosystem economics, where interoperability with municipal digital infrastructure determines vendor survival beyond hardware specifications.
For Market Incumbents: Build switching-cost moats through backward integration into calibration gas production and captive metrology technician training pipelines. Consolidate position by acquiring specialized analytics firms in France and Germany before platform unbundling accelerates. Counter emerging pure-play SaaS entrants by bundling reference-grade hardware with multi-year data management contracts.
For New Entrants and Emerging Players: Pursue whitespace in Eastern European municipal networks across Poland, Romania, and Bulgaria where EU cohesion fund allocations outpace established vendor coverage. Target portable electrochemical devices for Belgian and Dutch workplace safety inspectors as the most penetrable segment. Enter through channel partnerships with construction equipment distributors rather than direct environmental agency sales cycles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-integrated vendors with recurring SaaS revenue over pure hardware manufacturers facing replacement cycle compression. Five-to-ten year viability concentrates in firms controlling cloud data aggregation layers and machine-learned calibration IP. Watch F-Gas Regulation enforcement intensity in northern Italian semiconductor clusters as inflection indicator for synthetic fluorinated gas analyzer demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Cloud aggregation partnerships with French Airparif and German UBA centralize municipal data dashboards. |
| Acquisition of Specialist Firm | Pure-play analytics vendors in Lyon and Munich capture unbundled data service contracts from hardware incumbents. |
| Geographic Expansion | Eastern European cohesion fund projects in Warsaw and Krakow present whitespace for reference-grade station deployment. |
| Strategic Partnership | Swiss photonics suppliers secure long-term laser component allocation for F-Gas Regulation analyzer manufacturers. |
| Product Launch | Handheld electrochemical devices for Belgian construction firms address fastest-expanding portable monitor category. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EEA air quality reports, EU Green Deal implementation documents, and CE marking directive databases. Interviews with environmental agency procurement officers, municipal network operators, industrial facility compliance managers, and precision optics manufacturing executives informed demand-side and supply-side validation. Secondary sources included RIVM measurement protocol publications, ARPA regional monitoring disclosures, and customs trade data for analyzer component flows. Bottom-up sensor deployment counts triangulated against top-down market value estimates.
Forecast inputs considered product type segmentation across fixed, portable, indoor, and outdoor monitors; technology differentiation between gravimetric, optical, and electrochemical detection; and deployment architecture shifts from on-premise to cloud-based data logging. End-user segmentation modeled environmental agency, public sector, private company, and research institution procurement patterns across Germany, France, Netherlands, Italy, and Poland. CAGRs derived from replacement cycle compression under EU Green Deal timelines and F-Gas Regulation compliance mandates across the analysis window.
Sensitivities concentrate around EU Green Deal enforcement intensity, F-Gas Regulation phase-down acceleration, and metrology technician training pipeline expansion. Forecasts embed assumptions regarding municipal leasing arrangement adoption and cloud platform interoperability standardization. Cross-checking against EEA official air quality statistics and national environment agency capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
End-Of-Pipe Air Pollution Control Equipment Market
Environmental Monitoring
Asia Pacific Air Quality Monitoring Market
Environmental Monitoring
India Cloud Seeding Market
Environmental Monitoring
Testing, Inspection, and Certification for Natural Resources Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
North America Emission Monitoring System Market
Environmental Monitoring
Water Quality Monitoring Equipment Market
Environmental Monitoring
Green Mining Market
Environmental Monitoring
Emission Monitoring Systems Market
Environmental Monitoring
Middle East and Africa Air Quality Monitoring Market
Environmental Monitoring
Industrial Site Carbon Footprint Verification and Metering Test Equipment Market
Environmental Monitoring
United States Erosion Sediment Control Market
Environmental Monitoring
Global on-Line Total Organic Carbon (TOC) Analyzer Market
Environmental Monitoring
Indoor Air Quality Service Market
Environmental Monitoring
Continuous Emission Monitoring Systems (CEMS) Market
Environmental Monitoring
Global Environmental Sensor Market