
 Environmental Control System (ECS) Market | 2026-2036
Environmental Control System (ECS) Market Size, Share, and Industry Trends Forecast 2026-2036
Environmental Control System (ECS) Market Foresight
Multi-source procurement for thermal management components is shifting toward captive production among tier-one aerospace suppliers. Honeywell International leverages its avionics integration expertise to bundle ECS with flight-control architectures. Liebherr-International AG anchors European narrowbody programs through vertically stabilized landing-gear and air-conditioning units. Collins Aerospace competes on bleedless-system technology leadership for next-generation platforms.
An environmental control system regulates cabin pressure, temperature, humidity, and air quality through pneumatic, electronic, and thermal subsystems operating across altitude differentials exceeding eight psi. The system maintains habitable conditions for crew and passengers while managing avionics cooling loads and cargo-bay climate. HVAC equipment dominates product-type value pools given its integration with aircraft bleed-air architectures and electric compressor alternatives. Smart Controls and IoT Integration represent the fastest-expanding technology segment as predictive maintenance algorithms reduce unscheduled removal rates. Marine applications lag aviation in unit volume but command premium pricing due to salt-corrosion specifications and redundant-pack requirements.
FAA airworthiness directives and EASA certification specifications govern fire-suppression, smoke-detection, and ozone-conversion standards for commercial transport ECS. EPA regulations on refrigerant global-warming potential are forcing transitions from R-134a to lower-GWP working fluids in ground-based test equipment and aftermarket servicing. China's CAAC implements harmonized validation procedures with FAA-EASA baselines but adds domestic content requirements for state-airline procurement. Stakeholders must monitor electric-aircraft thermal-management roadmaps and corresponding certification-rule evolution to align R&D portfolios with propulsion-system transitions.
Market Dynamics
Bleedless electric compressor technology is compressing pneumatic subsystem demand while forcing thermal management architectures toward higher-voltage distribution networks. OEMs now spec integrated power electronics that merge ECS with electric propulsion cooling loops.
Growth Catalysts
- FAA-EASA harmonized certification:Unified airworthiness standards for electric thermal management systems accelerate platform approvals across the United States and European Union, reducing duplicate testing burdens for suppliers.
- More-electric aircraft programs:Boeing's 787 and Airbus A350 bleedless architectures validate high-voltage ECS designs, creating reference specifications for next-generation narrowbody development.
- Fleet renewal cycles:United States, China, and Germany account for the densest concentrations of aging widebody replacements requiring modern cabin pressure and humidity control suites.
Market Restraints
- Specialized alloy supply concentration:Nickel-titanium shape-memory actuators for valve control depend on a limited supplier base concentrated in Western Europe, exposing tier-one integrators to input volatility.
- EPA refrigerant phase-down:Ground-based test equipment servicing commercial fleets faces forced transitions from R-134a to lower-GWP alternatives, inflating aftermarket infrastructure retrofit costs.
- Technical limitation in thermal density:Current heat exchanger geometries cannot dissipate avionics loads above 50 kW without exceeding wing-sweep packaging constraints on single-aisle platforms.
Strategic Opportunities
- Urban air mobility thermal management:Electric vertical takeoff and landing platforms require compact, high-cycle ECS packs with no bleed-air access, opening design contracts for purpose-built compressor modules.
- China CAAC domestic content mandates:State-airline procurement rules incentivize joint ventures with local suppliers for cabin pressure controllers, creating captive production pathways for foreign tier-one entrants.
- Marine superyacht climate systems:Salt-corrosion specifications and redundant-pack requirements in Mediterranean and Middle Eastern leisure vessel construction command pricing multiples above aviation equivalents.
Industry Challenges
- Multiphysics simulation talent scarcity:Coupled thermal-fluid-structural modeling for heat exchanger optimization requires specialized aerospace engineers concentrated at a handful of German and United States research clusters.
- Certification timeline compression:FAA changed product rule updates for lithium-ion thermal runaway protection are extending validation schedules for electric ECS architectures by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Environmental Control System (ECS) Market |
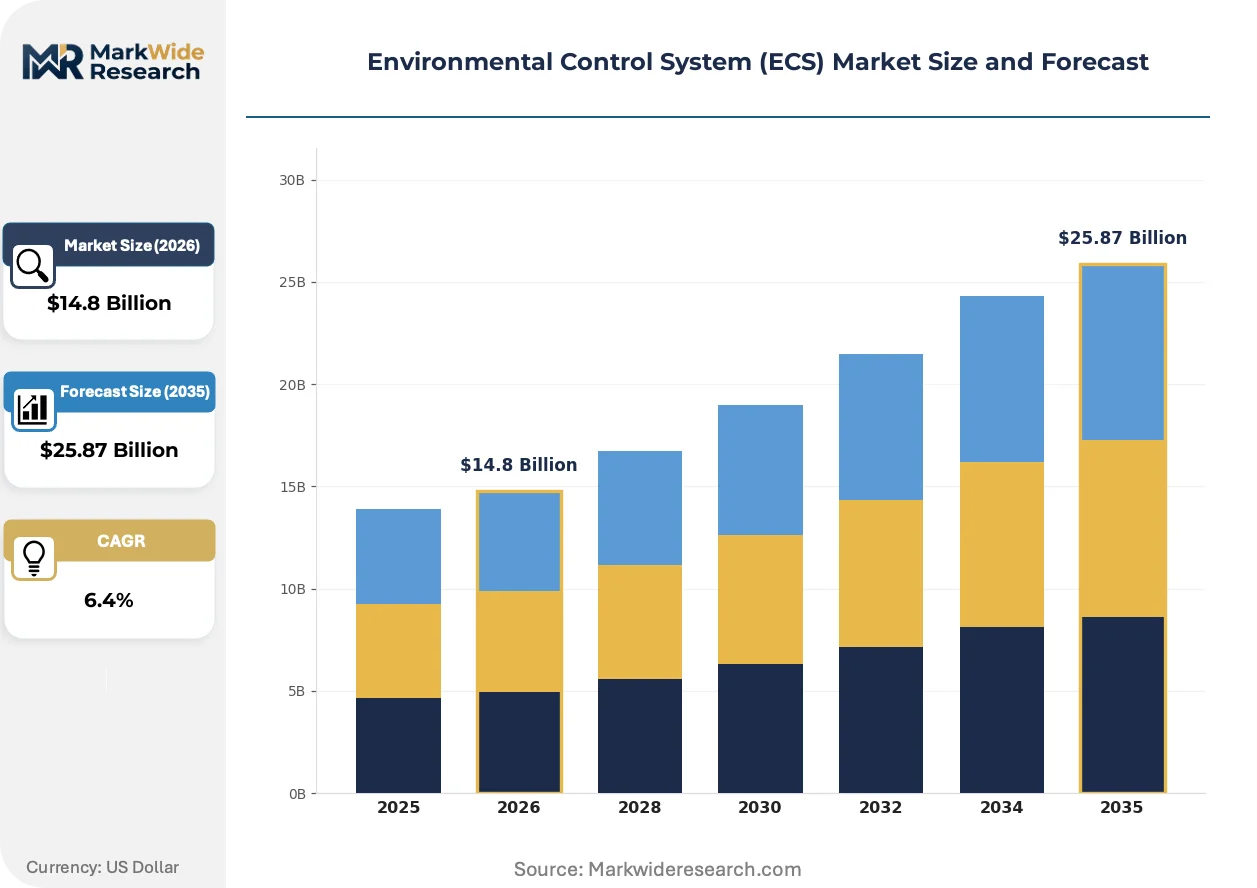
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HVAC, Humidifiers, Air Purifiers, Dehumidifiers Technology: Smart Controls, IoT Integration, Zoning Systems, Variable Refrigerant Flow Application: Residential, Commercial, Industrial, Marine End User: Homeowners, Facility Managers, Contractors, OEMs |
| Companies Covered | Honeywell International, Liebherr-International AG, Collins Aerospace, Safran SA, Curtiss-Wright Corporation, Mecaer Aviation Group, Jormac Aerospace, Mitsubishi Electric Corporation, Daikin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Environmental Control System (ECS) Market Shifts & Advancements
Electrification of pneumatic subsystems is collapsing traditional bleed-air hierarchies while predictive algorithms rewrite maintenance economics. Material science advances and regulatory chemistry mandates are simultaneously reshaping component specifications and supplier qualifications.
High-voltage electric compressors are electrifying thermal management architectures across next-generation platforms. These solid-state systems eliminate engine bleed extraction, reducing fuel burn penalties associated with pneumatic distribution losses. Narrowbody OEMs in the United States and Europe are now specifying 270V DC distribution as baseline for new programs, compressing demand for legacy air-cycle machines and rewiring supplier competitive sets toward power electronics specialists.
EPA regulations on refrigerant global-warming potential are forcing transitions from R-134a to hydrofluoroolefin alternatives in ground-based test equipment and aftermarket servicing infrastructure. This chemistry shift inflates capital requirements for MRO facilities while disqualifying legacy charging equipment from compliance. United States-based service networks are responding by consolidating regional test-cell investments to amortize retrofit costs across higher throughput volumes.
Airlines are unbundling long-term ECS maintenance contracts from airframe purchase agreements, opting instead for flight-hour-based service subscriptions with guaranteed availability clauses. This performance contracting model displaces traditional spares-provisioning arrangements and concentrates aftermarket revenue at OEMs with diagnostic data infrastructure. Lufthansa Technik and United Airlines maintenance subsidiaries are most visible in piloting these outcome-based arrangements for widebody thermal management fleets.
Environmental Control System (ECS) Market Segmentation
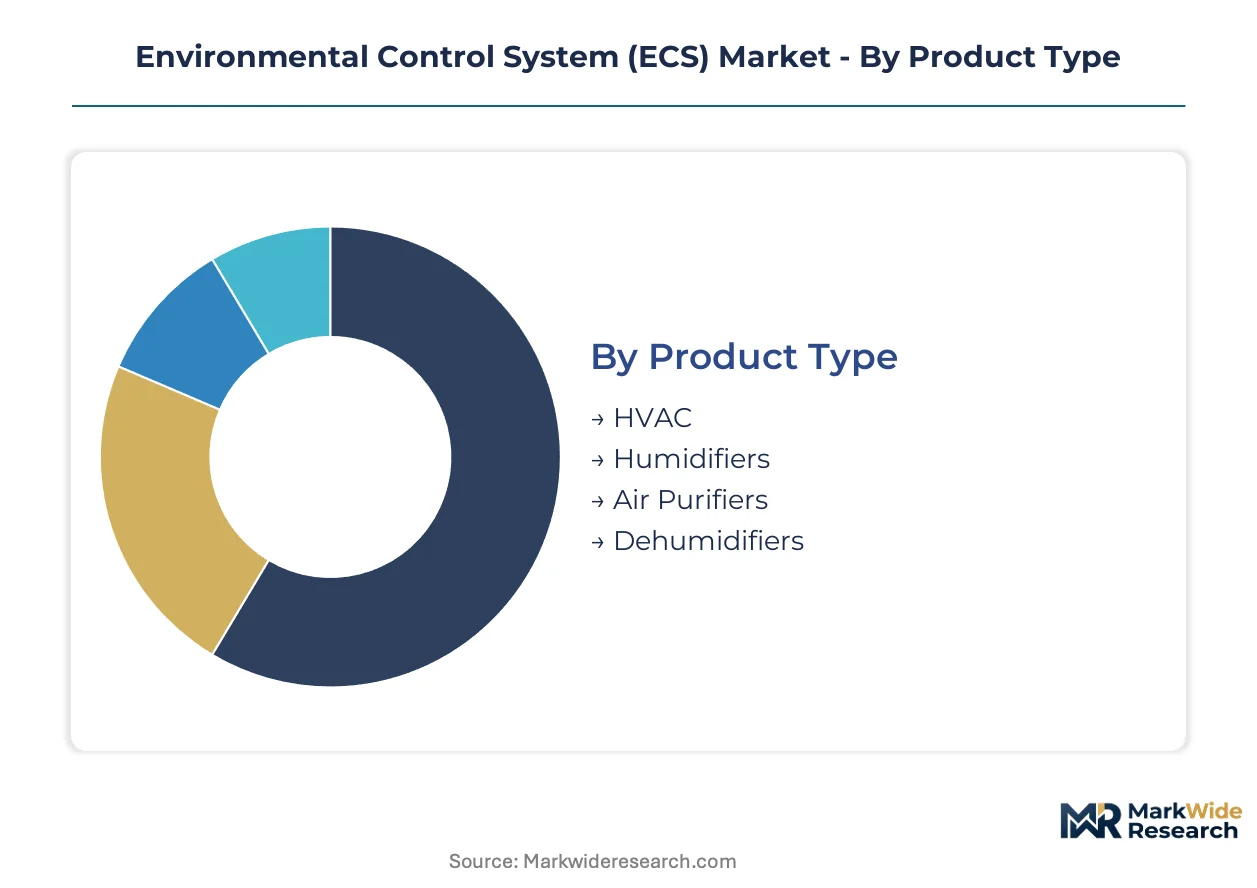
ECS procurement patterns diverge sharply across product architectures and customer workflows. Certification pathways from FAA, EASA, and China's CAAC create tiered compliance burdens that reshape supplier qualification requirements by segment.
Product Type:
FAA airworthiness directives and EASA CS-25 certification specifications impose distinct material and performance standards on each product category, with pneumatic subsystems facing the most stringent fire-suppression and smoke-detection protocols.
- HVAC:Thermal management units integrate with aircraft bleed-air architectures or electric compressor alternatives to regulate cabin pressure and temperature across altitude differentials exceeding eight psi. United States, China, and Germany concentrate demand as major OEMs and tier-one suppliers maintain integrated manufacturing and testing facilities for next-generation narrowbody and widebody platforms.
- Humidifiers:Cabin humidity control suites maintain passenger comfort and reduce dehydration on long-haul flights, with fleet renewal cycles in the United States and Germany driving replacements of aging widebody systems. EPA regulations on refrigerant global-warming potential force transitions from R-134a to lower-GWP working fluids in ground-based test equipment.
- Air Purifiers:Ozone-conversion and particulate filtration systems comply with EASA cabin air quality standards.
- Dehumidifiers:Cargo-bay climate control units prevent moisture damage to sensitive freight.
HVAC sits at the top of the volume ranking, with humidifiers climbing the fastest as passenger experience specifications tighten on premium routes.
Technology:
Development cost tiers separate legacy pneumatic architectures from emerging electric systems, with power electronics specialists commanding premium pricing for high-voltage distribution networks.
- Smart Controls:Predictive maintenance algorithms reduce unscheduled removal rates by monitoring thermal management performance in real time. Airlines unbundle long-term maintenance contracts from airframe purchases, opting for flight-hour-based subscriptions with guaranteed availability clauses.
- IoT Integration:Connected sensor networks enable diagnostic data infrastructure that concentrates aftermarket revenue at OEMs with fleet-wide monitoring capabilities. Lufthansa Technik and United Airlines maintenance subsidiaries pilot these outcome-based arrangements.
- Zoning Systems:Distributed temperature control allows independent climate management across cabin sections.
- Variable Refrigerant Flow:Optimized compressor modulation improves energy efficiency in ground-based applications.
Smart Controls dominates current deployment, while IoT Integration gains share fastest as performance contracting models displace traditional spares-provisioning arrangements.
Application:
Marine and aviation applications command pricing multiples above terrestrial equivalents due to salt-corrosion specifications, redundant-pack requirements, and extended certification timelines.
- Residential:Compact climate units for private aviation and luxury yacht segments face less stringent certification burdens than commercial transport, enabling faster product iteration cycles.
- Commercial:Narrowbody and widebody airline fleets drive the densest concentration of bleedless electric compressor adoption, with Boeing's 787 and Airbus A350 validating high-voltage ECS designs as reference specifications.
- Industrial:Ground-based test equipment servicing commercial fleets faces forced transitions from R-134a to hydrofluoroolefin alternatives, inflating MRO infrastructure retrofit costs.
- Marine:Superyacht climate systems in Mediterranean and Middle Eastern leisure vessel construction command premium pricing due to redundant-pack requirements and salt-corrosion specifications.
Commercial aviation anchors absolute volume, with Marine applications expanding most quickly on per-unit value metrics despite lower shipment counts.
End User:
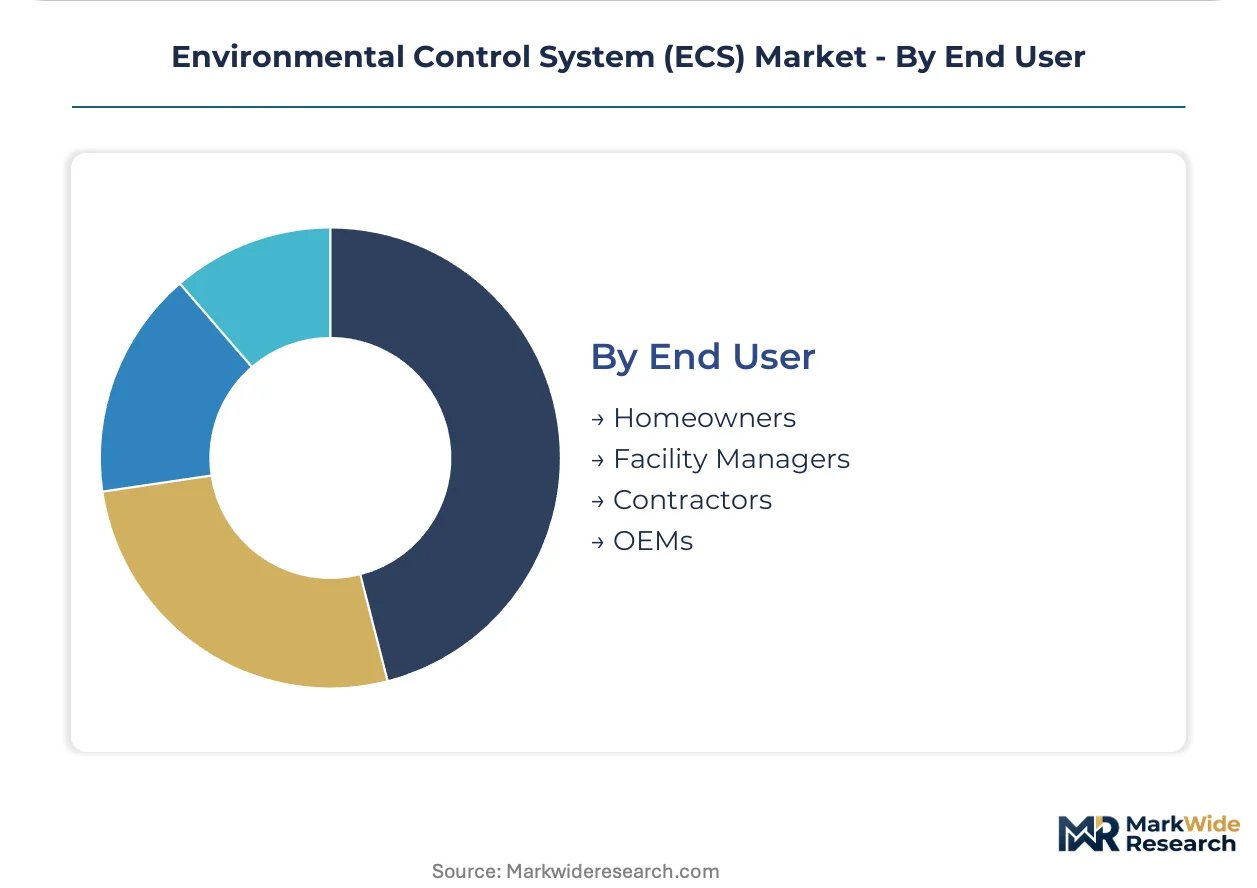
Procurement authority concentration determines contract structure, with OEMs and facility managers driving integrated system specifications while homeowners and contractors focus on aftermarket replacement cycles.
- Homeowners:Private aviation operators and individual yacht owners purchase through dealer networks with limited technical integration requirements.
- Facility Managers:Airport terminals and hangar operations specify ground-based HVAC with EPA refrigerant compliance mandates.
- Contractors:MRO service networks consolidate regional test-cell investments to amortize retrofit costs across higher throughput volumes.
- OEMs:Boeing and Airbus anchor demand for integrated thermal management architectures, with tier-one suppliers bundling ECS with flight-control and landing-gear systems.
OEMs sit at the top of the volume ranking, with facility managers climbing the fastest as EPA refrigerant phase-downs force infrastructure upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Seattle-Tacoma-Bellevue aerospace corridor anchors global ECS manufacturing density, concentrating Boeing integration facilities and tier-one thermal management suppliers across Washington state. United States, China, and Germany concentrate procurement authority through OEM final assembly lines and state-airline fleet renewal programs. Regulatory harmonization between FAA, EASA, and CAAC creates tiered compliance burdens that reshape supplier qualification requirements by geography.
United States
Commercial aviation fleet renewal cycles drive widebody replacement demand for modern cabin pressure and humidity control suites. FAA airworthiness directives govern fire-suppression and smoke-detection standards for bleed-air systems, tightening material specifications. The Seattle-Tacoma-Bellevue corridor hosts Boeing integration facilities and Honeywell thermal management manufacturing.
China
State-airline procurement rules incentivize joint ventures with local suppliers for cabin pressure controllers under fleet expansion programs. CAAC implements harmonized validation procedures with FAA-EASA baselines while adding domestic content requirements. The Yangtze River Delta concentrates tier-one supplier joint ventures and CAAC certification testing infrastructure.
Germany
Narrowbody program integration anchors European demand for vertically stabilized landing-gear and air-conditioning units. EASA CS-25 certification specifications impose distinct material and performance standards on pneumatic subsystems. Bavaria hosts Liebherr-International manufacturing and multiphysics simulation research clusters for heat exchanger optimization.
France
Bleedless-system technology leadership for next-generation platforms concentrates engineering talent around Toulouse aerospace corridors. EASA cabin air quality standards govern ozone-conversion and particulate filtration system approvals. The Occitanie region anchors Safran thermal management research and Airbus A350 integration facilities.
Japan
Electric compressor module development for urban air mobility platforms attracts purpose-built design contracts from domestic eVTOL manufacturers. METI industrial policy supports high-voltage thermal management R&D for more-electric aircraft architectures. The Nagoya aerospace cluster concentrates Mitsubishi Electric power electronics manufacturing.
Environmental Control System (ECS) Market Competitive Landscape
Global majors compete with regional champions across certification access and OEM integration relationships. The vendor base organizes around three tiers: integrated system architects bundling ECS with flight-control architectures, component specialists dominating bleedless electric compressor technology, and regional fabricators serving aftermarket MRO networks. Consolidation pressure intensifies as predictive maintenance algorithms concentrate aftermarket revenue at OEMs with diagnostic data infrastructure. Strategic moves center on backward integration into power electronics and captive supply of nickel-titanium actuators.
Within the integrated system architect tier, Honeywell International and Collins Aerospace exemplify global-scale positioning through avionics bundling and bleedless technology leadership respectively. Liebherr-International AG occupies a position anchoring European narrowbody programs through vertically integrated manufacturing. Safran SA and Curtiss-Wright Corporation represent the specialist tier, with Mitsubishi Electric Corporation exemplifying Asia-Pacific power electronics capability. These anchors illustrate how competitive positioning stratifies across certification access, OEM integration depth, and high-voltage distribution expertise.
| Leading Market Players |
|---|
| Honeywell International |
| Liebherr-International AG |
| Collins Aerospace |
| Safran SA |
| Curtiss-Wright Corporation |
| Mecaer Aviation Group |
| Jormac Aerospace |
| Mitsubishi Electric Corporation |
| Daikin Industries |
| Others |
Supply & Pricing Matrix
OEM procurement teams at Boeing and Airbus anchor pricing power through multi-year thermal management contracts that bundle ECS with flight-control architectures. This buyer concentration forces suppliers toward performance-based subscription models with guaranteed availability clauses rather than traditional unit-transaction pricing.
Pricing Analysis
Input-cost pass-through from nickel-titanium shape-memory alloys and high-voltage power electronics drives pricing stratification across certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates FAA-EASA dual-certified systems from single-jurisdiction alternatives and uncertified aftermarket components. Pricing pressure stems from EPA refrigerant phase-downs inflating MRO infrastructure retrofit costs. Tier-one integrators show least price sensitivity given bundled avionics contracts, while regional MRO networks face acute cost compression.
Supply Chain Analysis
Specialized aerospace engineering talent shortages in Washington state and Bavaria constrain heat exchanger manufacturing expansion despite order backlogs. Supply concentrates in the United States, Germany, and China, with nickel-titanium actuators drawing from Western European foundries and electric compressor modules resting on Japanese power electronics. Single-source vulnerability around shape-memory alloy suppliers exposes tier-one integrators to input volatility. Distribution runs through OEM direct procurement for original equipment and consolidated regional service networks for aftermarket servicing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Environmental Control System market compounds steadily as commercial aviation fleet renewal cycles sustain replacement demand for cabin pressure and thermal management units across narrowbody and widebody platforms.
For Market Incumbents: Lock in diagnostic data infrastructure to capture flight-hour-based maintenance subscriptions before airlines complete contract unbundling. Deepen backward integration into nickel-titanium actuator supply to offset Western European foundry concentration risk. Prioritize certification investment for 270V DC electric compressor architectures as Boeing and Airbus finalize next-generation narrowbody specifications. For New Entrants and Emerging Players: The premium-to-economy price gap in marine superyacht climate systems offers white-space entry with less stringent aviation certification burdens. Target Mediterranean and Middle Eastern leisure vessel construction where redundant-pack requirements command pricing multiples above aviation equivalents. Pursue joint venture structures with Chinese tier-one suppliers to satisfy CAAC domestic content mandates for state-airline procurement. For Investors and Strategic Acquirers: Power electronics specialists are the most active acquirer in this space as bleedless architectures displace pneumatic subsystem demand. Long-term viability hinges on high-voltage distribution expertise and predictive maintenance algorithm development. Watch FAA-EASA harmonization progress on electric thermal management certification as the inflection signal for platform approval velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Captive supply of 270V DC compressor modules secures positioning for next-generation narrowbody programs at Boeing and Airbus. |
| Predictive Maintenance Platform Development | Diagnostic data infrastructure concentrates aftermarket revenue as Lufthansa Technik and United Airlines pilot outcome-based service contracts. |
| CAAC Joint Venture Formation | Domestic content compliance unlocks state-airline procurement channels under China's fleet expansion programs. |
| Marine Superyacht Segment Entry | Salt-corrosion specifications and redundant-pack requirements in Mediterranean construction command premium pricing multiples. |
| Multiphysics Simulation Capability Buildout | Coupled thermal-fluid-structural modeling talent scarcity in German and United States research clusters creates competitive moat. |
Research Methodology
Direct dialogue with ECS program directors at tier-one suppliers, thermal management engineers at OEM integration facilities, MRO service network managers, and CAAC certification specialists grounded qualitative findings. Secondary validation drew from FAA airworthiness directive filings, EASA CS-25 certification specifications, EPA refrigerant phase-down schedules, and customs trade data for nickel-titanium alloy imports. Bottom-up and top-down triangulation cross-checked unit shipment estimates against OEM production forecasts and supplier revenue disclosures.
Bottom-up modeling aggregated segment-level volume and value outputs across the projection horizon by product type, technology, application, and end user. Analytical frameworks incorporated electric aircraft thermal-management roadmaps, fleet renewal cycle timing, and regulatory rule evolution as industry-specific forecast inputs. CAGRs were derived from fitted growth curves calibrated to historical replacement patterns and announced platform development schedules.
Caveats apply where FAA-EASA harmonization delays, nickel-titanium supply disruptions, or electric propulsion certification timeline extensions could materially shift the outlook. Forecasts reflect assumptions about bleedless architecture adoption velocity and refrigerant chemistry transition compliance. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Industrial Air Quality Control Systems Market
Air Quality Control Systems
Anti-Pollution Toner Market
Air Quality Control Systems
Environment Controllers Market
Air Quality Control Systems
Air Quality Control Systems Market
Air Quality Control Systems
Air Pollution Control Equipment Market
Air Quality Control Systems
Europe Industrial Air Quality Control Systems Market
Air Quality Control Systems
United States Pollution Mask Market
Air Quality Control Systems
North America Industrial Air Quality Control Systems Market
Air Quality Control Systems
Indoor Air Purification Market
Air Quality Control Systems
Europe Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Anti-Pollution Mask Market
Air Quality Control Systems
Southeast Asia Air Purifier Market
Air Quality Control Systems
Air Pollution Control Systems Market
Air Quality Control Systems
Desiccant Air Breather Market
Air Quality Control Systems
Middle-East and Africa Industrial Air Quality Control Systems Market
Air Quality Control Systems
UV Air Purifiers Market