
 Tiller Machine Market | 2026-2036
Tiller Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Tiller Machine Market Intelligence
The rise of equipment-as-a-service and leasing models for agricultural machinery is reconfiguring the competitive landscape for smaller farming operations. This shift allows smaller end-users to access advanced equipment without large capital outlays. Deere & Company leverages its extensive dealer network to offer such financing solutions. Meanwhile, Husqvarna AB specializes in compact and battery-powered models suited for professional landscaping lease packages.
A tiller machine is a mechanized cultivator that uses rotating tines or blades to churn and aerate soil for planting. These machines vary in power, with engine displacements ranging from 50cc for mini tillers to over 200cc for larger rotary models. While rotary tillers remain the dominant product type for large-scale soil preparation, battery-operated mini tillers represent the fastest-growing segment. Demand from commercial growers is shifting toward models that offer precise depth control for specialized seedbed preparation.
Engine emission regulations directly influence product design and market access for petrol and diesel-powered tillers. Manufacturers must comply with frameworks like the EPA's Tier 4 standards in the United States and the EU's Stage V norms. These regulations are accelerating the industry's transition toward electric and battery-operated power sources. Consequently, a manufacturer's strategic choice between internal combustion and electric powertrain development will define its future market position.
Market Dynamics
The fundamental transition from internal combustion engines to electric powertrains, driven by tightening global emissions regulations, is the central force reconfiguring product development priorities, supply chain structures, and market access for all tiller machine manufacturers.
Growth Catalysts
- Government Initiatives:India's Production Linked Incentive (PLI) scheme for farm equipment manufacturing is stimulating domestic production and lowering costs, making mechanized cultivation more accessible to small and medium-sized farms.
- Professional Landscaping Demand:Adoption by horticulturists and commercial landscapers is expanding for precision soil preparation in garden beds and turf installation, favoring compact and maneuverable models.
- Battery Technology Advancement:Continuous improvements in the energy density and cost-effectiveness of lithium-ion batteries are enabling the development of more powerful and longer-running cordless electric tillers.
Market Restraints
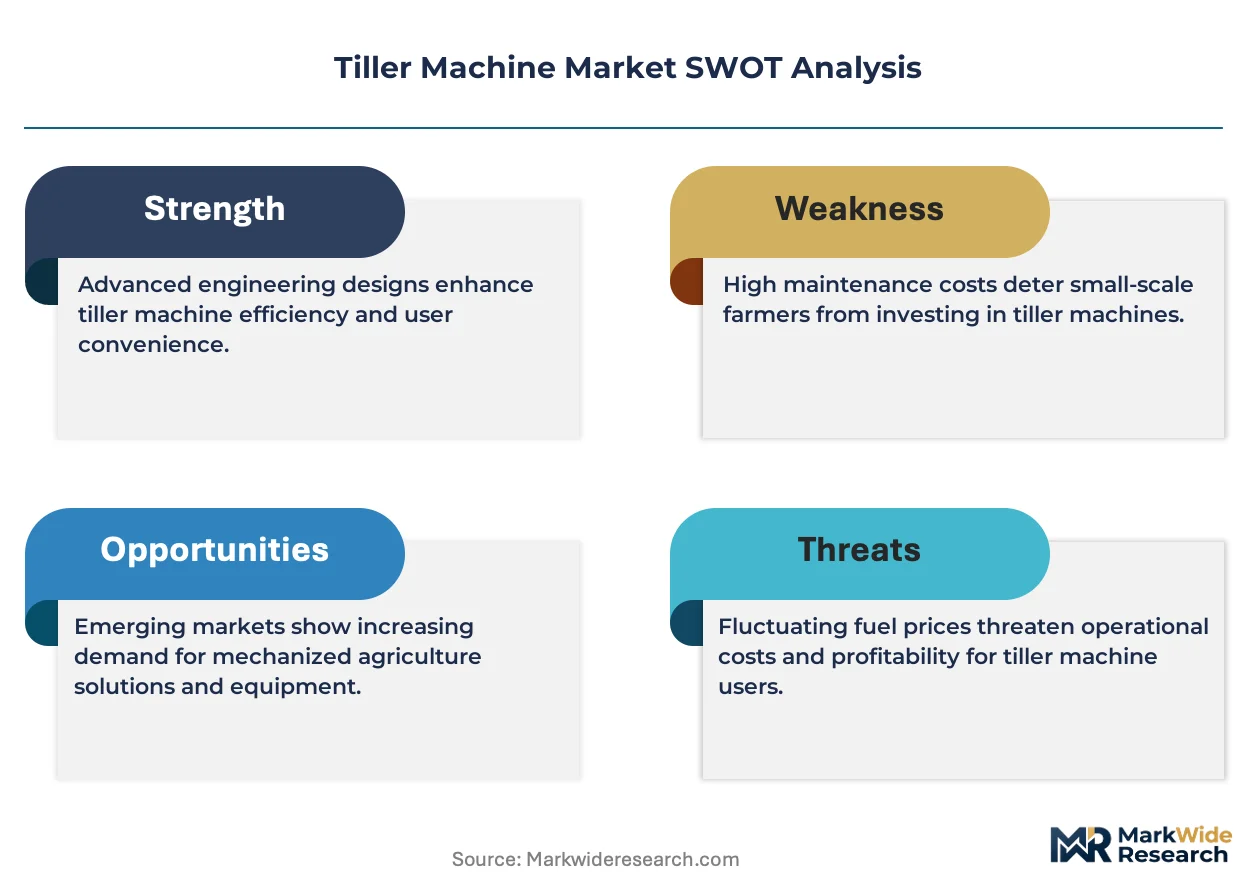
- High Upfront Cost:The initial purchase price of advanced, battery-powered tillers remains significantly higher than their petrol-powered counterparts, presenting a barrier for budget-conscious consumers and small-scale operators.
- Performance Limitations:Current battery technology still imposes constraints on runtime and power output, limiting the suitability of electric models for heavy-duty, large-acreage soil cultivation tasks.
- Regulatory Compliance Burden:The significant research and development costs required to meet disparate emissions standards, such as the EPA's Tier 4 and the EU's Stage V, increase production costs for combustion-engine models.
Strategic Opportunities
- Autonomous Systems:Developing small, autonomous tillers guided by GPS and IoT sensors for precision agriculture applications in vineyards and high-value specialty crop fields presents a significant growth avenue.
- Channel Expansion:Establishing direct-to-consumer (D2C) e-commerce platforms for mini tillers and accessories can bypass traditional dealer networks, reaching a broader base of residential and semi-professional users.
- Service Model Innovation:Creating subscription-based equipment-as-a-service packages, bundling the tiller with maintenance and battery-swapping services, offers a recurring revenue stream from commercial landscaping clients.
Industry Challenges
- Technician Skill Gaps:A shortage of service technicians trained to diagnose and repair the complex electronics, software, and battery management systems of modern electric tillers creates a support bottleneck.
- Dual Supply Chain Complexity:Managing parallel supply chains for legacy internal combustion engine parts and new electric powertrain components increases inventory costs and logistical challenges for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tiller Machine Market |
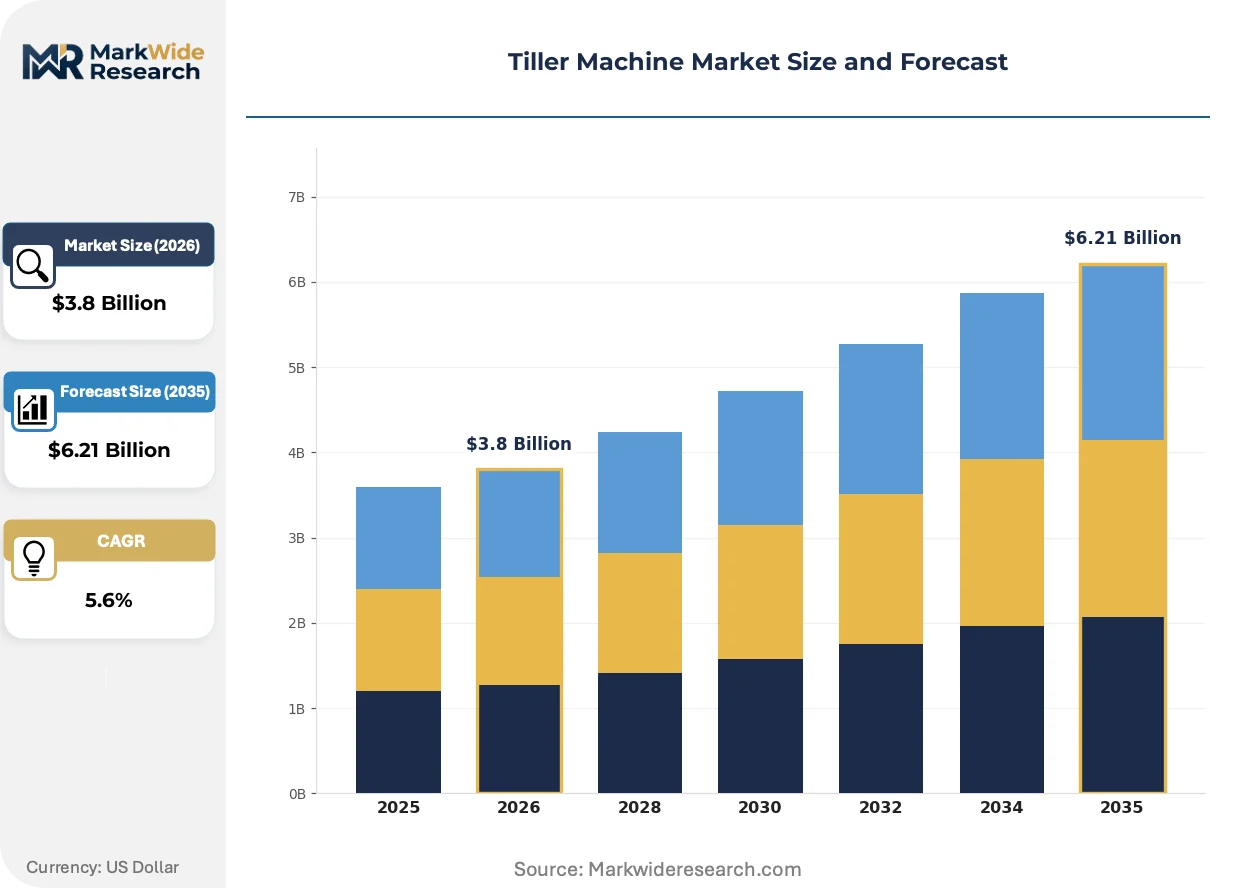
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Tillers, Mounted Tillers, Mini Tillers, Walking Tillers, Forward Tiller Power Source: Electric, Petrol, Diesel, Battery-Operated, Gasoline Application: Soil Preparation, Weed Control, Seedbed Preparation, Furrow Making, Cultivation End User: Smallholder Farmers, Commercial Growers, Landscaping Professionals, Horticulturists |
| Companies Covered | Deere & Company, Kubota Corporation, AGCO Corp, Yanmar Co., Ltd., Mahindra & Mahindra Ltd., CLAAS KGaA mbH, Husqvarna AB, ISEKI & Co., Ltd., CNH Industrial N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tiller Machine Market Strategic Shifts & Innovations
Product design is converging with digital services, moving beyond hardware performance to alter how end-users access equipment and how manufacturers capture value. This shift emphasizes lifecycle management and data-driven operational efficiency for commercial customers.
Advancements in IoT sensors and onboard telematics allow for real-time monitoring of tiller performance, soil conditions, and operational hours. Commercial fleet operators and equipment-as-a-service providers are rapidly adopting this technology to optimize asset utilization and maintenance schedules. This data-centric approach is virtualizing fleet management, replacing reactive repairs with predictive, subscription-based service models.
Global emissions standards, including the EU's Stage V norms and the EPA's Tier 4 regulations, mandate significant reductions in pollutants from diesel and petrol engines. This regulatory pressure is forcing substantial investment in after-treatment systems for internal combustion engines or a complete pivot to electric powertrains. Manufacturers of larger, professional-grade rotary tillers are most affected, facing increased production costs and engineering complexity.
The rise of short-term rental and leasing models is displacing traditional outright ownership, particularly for small-scale farmers and landscaping contractors. This changes the purchasing decision from a capital expenditure to an operational expense, managed through dealer networks or specialized rental firms. This trend is most pronounced in North American and European markets where access to financing facilitates such service models.
Tiller Machine Market Segmentation
The tiller machine market's segmentation reflects diverse user needs, power requirements, and operational scales. Understanding these distinct segments is critical for manufacturers to align product development with specific end-user demands and regulatory shifts. This granular analysis identifies areas of concentrated demand and emerging growth trajectories across the global landscape.
Product Type:
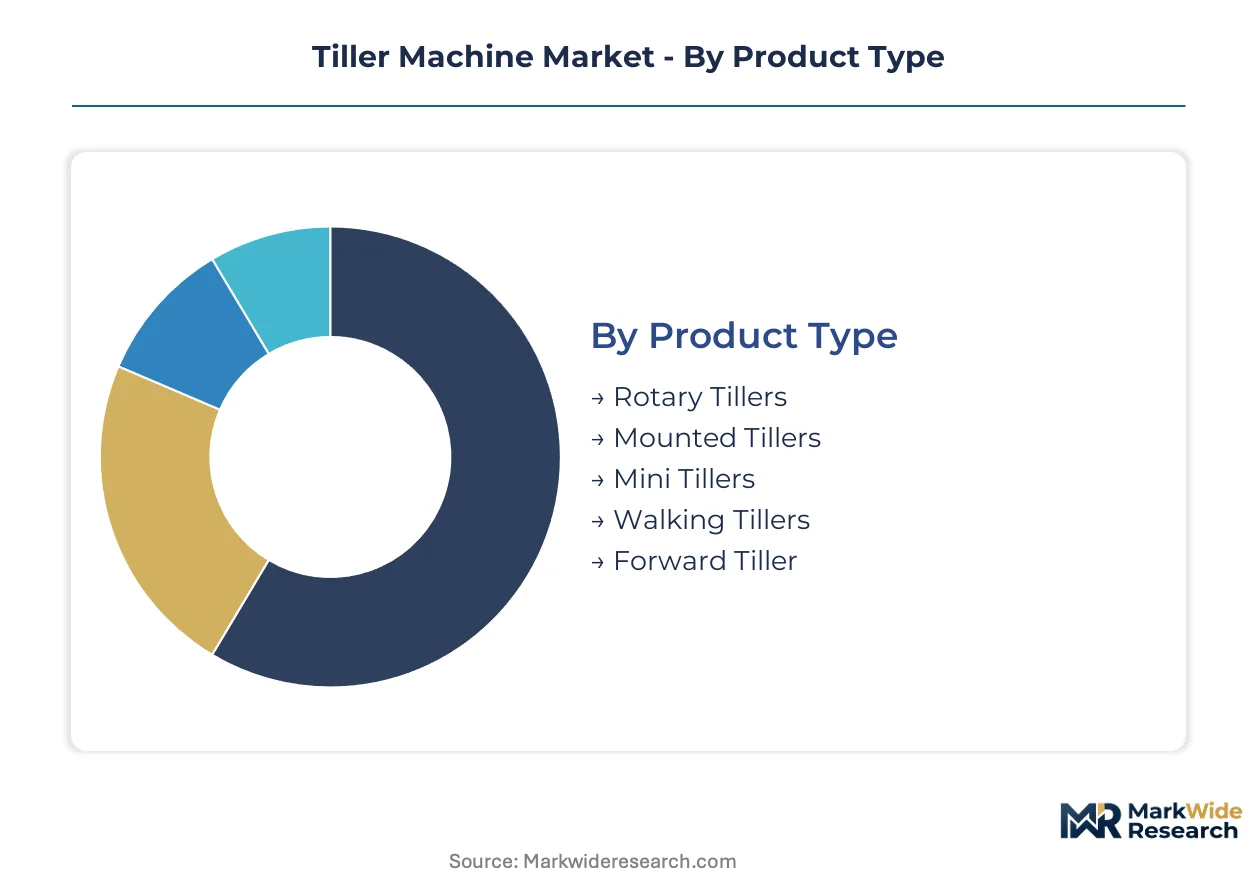
The product type dimension categorizes tiller machines based on their design and operational characteristics, ranging from robust industrial models to compact, specialized units.
- Rotary Tillers:These machines utilize power-driven rotating blades or tines to break up and pulverize soil effectively, making them indispensable for primary and secondary tillage operations. Demand concentrates among large-scale agricultural enterprises in regions like India, driven by the need for efficient soil preparation across extensive land areas.
- Mini Tillers:Characterized by their smaller size and lighter weight, mini tillers are highly maneuverable and suitable for cultivating small plots, gardens, and inter-row weeding. This segment is expanding most quickly among professional horticulturists seeking precision and ease of use in confined spaces.
- Mounted Tillers:Designed to attach to tractors, these tillers offer significant power and width for large-area cultivation, optimizing efficiency for commercial farming operations.
- Walking Tillers:Operated by a user walking behind the machine, these tillers are versatile for various soil conditions and popular with smallholder farmers and residential users.
- Forward Tiller:These models have rotating tines positioned to pull the machine forward, providing aggressive soil penetration for challenging ground conditions.
Rotary Tillers handle the majority of throughput; Mini Tillers represent the fastest-growing trajectory on share.
Power Source:
The power source segmentation highlights the industry's transition from traditional combustion engines to electric and battery-powered alternatives, driven by environmental regulations and technological advancements.
- Battery-Operated:These tillers rely on rechargeable lithium-ion batteries, offering cordless operation, reduced emissions, and lower noise levels, making them ideal for residential and professional landscaping. Demand is concentrating in European markets due to stringent EU Stage V emission norms and increasing consumer preference for sustainable tools.
- Petrol:Powered by gasoline engines, these tillers provide robust power and extended runtimes, suitable for medium to heavy-duty tasks in diverse agricultural settings. The US market continues to show strong demand for petrol models, particularly for larger property maintenance where battery limitations still exist.
- Electric:Corded electric tillers offer consistent power without emissions, primarily used in smaller garden plots where access to an electrical outlet is readily available.
- Diesel:Diesel-powered tillers are known for their high torque and fuel efficiency, typically employed in heavy-duty agricultural applications and large-scale land preparation.
- Gasoline:Similar to petrol, gasoline tillers provide reliable performance for a wide range of tilling activities, appealing to both professional and residential users.
The shift towards cleaner energy sources drives innovation in this category, with battery technology gaining significant traction.
Application:
This category delineates the primary uses of tiller machines, showcasing their versatility in various agricultural and horticultural practices.
- Soil Preparation:This application involves breaking up compacted soil, aerating it, and creating a fine tilth suitable for planting, forming the foundational use for most tiller machines. Commercial growers globally require precise soil preparation for optimal crop yields, driving demand for advanced rotary tillers.
- Seedbed Preparation:Focused on creating an ideal, finely textured and level surface for seed germination, this application demands precise depth control and consistent soil conditioning. Horticulturists increasingly specify tillers with specialized attachments for uniform seedbed creation in high-value crops.
- Weed Control:Tillers are used to mechanically remove weeds and incorporate them into the soil, reducing the need for chemical herbicides in sustainable farming practices.
- Furrow Making:This application involves creating trenches or furrows in the soil for planting seeds, irrigation, or drainage, commonly used in row cropping.
- Cultivation:General cultivation encompasses a range of activities including mixing soil amendments, breaking up crusts, and maintaining soil structure throughout the growing season.
Soil Preparation remains the largest application segment, while Seedbed Preparation is experiencing rapid expansion due fueled by precision agriculture trends.
End User:
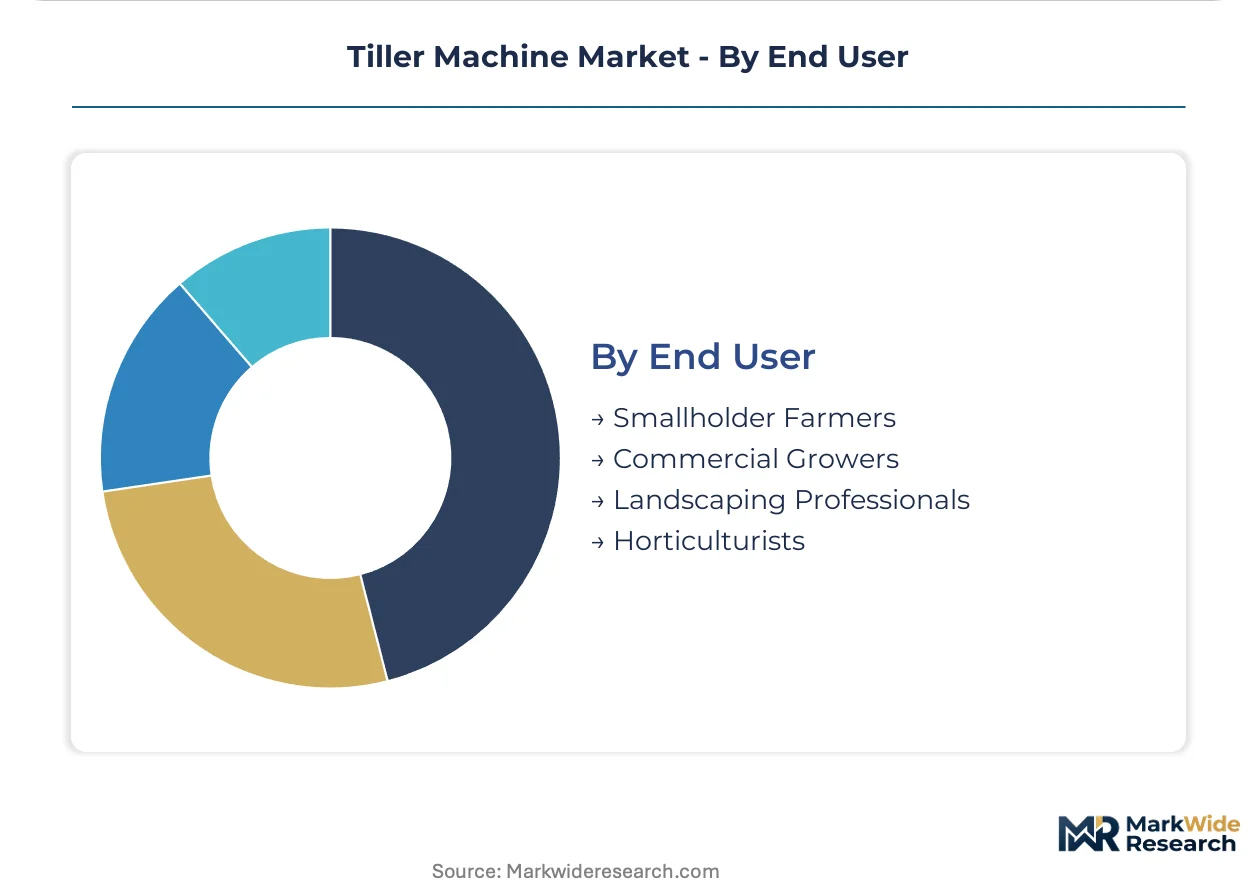
The end-user segmentation classifies tiller machine consumers based on their operational scale and specific needs, from individual gardeners to large commercial entities.
- Commercial Growers:These users operate on a large scale, demanding robust, high-performance tillers capable of extensive land cultivation and continuous operation. Their purchasing decisions are often influenced by equipment-as-a-service models and total cost of ownership.
- Landscaping Professionals:This segment includes businesses that provide services for garden maintenance, turf installation, and landscape development, requiring versatile and often compact tillers for precision work. Demand for battery-powered models is high among this group in urban areas due to noise restrictions and emission concerns.
- Smallholder Farmers:Operating smaller land parcels, these farmers prioritize affordability, ease of maintenance, and suitability for diverse crop types. Government initiatives like India's PLI scheme are making mechanized options more accessible to this demographic.
- Horticulturists:Specialists in garden cultivation and management, horticulturists often require precision tillers for delicate plant beds, nurseries, and specialized soil conditioning.
Commercial Growers represent the largest purchasing power; Landscaping Professionals are rapidly adopting newer, specialized models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive (PLI) scheme for farm equipment manufacturing is stimulating domestic production, making mechanized cultivation more accessible across various farm sizes. This initiative, coupled with a global drive towards sustainable agriculture, influences regional demand patterns and product development. Different regions exhibit unique preferences for tiller types and power sources.
India
Small and medium-sized farms in India are increasingly adopting mechanized cultivation for improved efficiency and yield. The Indian government's Production Linked Incentive (PLI) scheme directly supports domestic farm equipment manufacturing, lowering costs for local consumers. The Punjab region, a major agricultural hub, sees significant demand for robust rotary tillers and localized production facilities.
United States
Demand for tiller machines in the United States stems from large property maintenance operations and commercial growers requiring powerful equipment. The Environmental Protection Agency's (EPA) Tier 4 standards mandate lower emissions from internal combustion engines, pushing manufacturers towards cleaner designs. Agricultural regions in the Midwest prioritize large-scale rotary tillers for extensive soil preparation across vast farmlands.
Germany
Professional landscaping and horticultural businesses in Germany show strong demand for compact and battery-powered tillers, driven by sustainability preferences. The European Union's (EU) Stage V emission norms significantly restrict pollutants from diesel and petrol engines, accelerating the shift to electric models. Bavaria, a region known for advanced machinery manufacturing, actively develops and produces innovative electric tiller solutions.
Japan
Smallholder farmers and horticulturists in Japan require precision soil work and compact, maneuverable tiller machines for diverse applications. The Ministry of Economy, Trade and Industry (METI) supports agricultural machinery innovation, fostering the development of advanced tilling technologies. Hokkaido, a prominent agricultural prefecture, exhibits high adoption rates for specialized tillers in its diverse farming landscape.
China
China's agricultural sector drives substantial demand for tiller machines, particularly for large-scale soil preparation and increasing mechanization efforts. The nation's dual carbon goals encourage the adoption of electric and more efficient agricultural machinery. Shandong Province, a key agricultural and machinery manufacturing hub, focuses on producing and deploying efficient rotary tillers for its extensive farmlands.
Tiller Machine Market Key Industry Players
On the supply side, the industry is transitioning from a traditional, established base of combustion engine manufacturers to a more diversified landscape. This market structure features a tiered approach, encompassing global agricultural machinery giants and specialized compact/electric tool makers. Strategic archetypes include diversified agricultural solution providers, specialized battery-powered equipment manufacturers, and regional manufacturers. Dominant competitive moves involve portfolio diversification into electric models and strategic partnerships for battery technology development.
At the scale-driven end, Deere & Company and Kubota Corporation represent established agricultural machinery corporations. These companies exemplify extensive dealer networks and financing solutions for larger equipment. Husqvarna AB, an AB-structured company, anchors the specialized segment with compact and battery-powered models. These players collectively illustrate the dual market focus on heavy-duty agricultural solutions and precision landscaping tools.
| Leading Market Players |
|---|
| Deere & Company |
| Kubota Corporation |
| AGCO Corp |
| Yanmar Co., Ltd. |
| Mahindra & Mahindra Ltd. |
| CLAAS KGaA mbH |
| Husqvarna AB |
| ISEKI & Co., Ltd. |
| CNH Industrial N.V. |
| Others |
Cost & Logistics Intelligence
Lithium-ion battery manufacturing concentration in Asian economies directly impacts cost structures for electric tiller producers and their ability to offer competitive equipment-as-a-service packages. This upstream dynamic influences downstream profitability.
Pricing Analysis
Performance capabilities and power source technology create the primary pricing spread in the tiller machine market. A hybrid model combines per-unit transactional sales for traditional units with subscription-based equipment-as-a-service for advanced electric models. Price differentiation stems from battery capacity and specialized precision depth control features. Cost compression on petrol models intensifies due to emission regulation compliance expenses, while smallholder farmers remain highly price-sensitive compared to commercial growers who prioritize total cost of ownership.
Supply Chain Analysis
Major agricultural machinery OEMs and specialized electric tool manufacturers hold significant contract manufacturing capacity, particularly in China and India. The supply chain draws from critical raw materials like lithium for batteries, specialized electric motors, and high-grade steel for tines. Dual supply chain complexity, managing both internal combustion engine parts and electric powertrain components, presents a structural risk. Distribution runs through established dealer networks for heavy-duty models, complemented by direct-to-consumer e-commerce platforms for mini tillers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tiller machine market is undergoing a significant buyer-power shift as smallholder farmers, supported by government initiatives like India's PLI scheme, increasingly fragment the demand for accessible mechanized solutions. This dynamic reconfigures traditional purchasing patterns.
For Market Incumbents: Build end-to-end service ecosystems around advanced electric tillers, leveraging existing dealer networks for maintenance and support. Incumbents should expand equipment-as-a-service offerings to counter the threat from specialized battery-powered manufacturers. Investing in predictive maintenance platforms and battery-swapping infrastructure provides a critical lever. This strategy secures recurring revenue streams and reinforces customer loyalty against emerging competitive pressures.
For New Entrants and Emerging Players: Build out specialized autonomous mini tillers integrated with IoT sensors for precision agriculture applications. New entrants should target professional horticulturists requiring precise depth control in high-value specialty crops. Leveraging direct-to-consumer e-commerce platforms can bypass established dealer networks, offering a cost-effective go-to-market angle. Deep integration of advanced battery technology will differentiate offerings in this niche.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric powertrain development and battery technology integration within the tiller market. The market demonstrates robust long-term viability over the next 5-10 years, driven by electrification and precision agriculture. Acquisition targets should focus on vertically integrated specialists in advanced battery management systems or IoT-enabled precision tools. The increasing commercial adoption rates of autonomous tilling solutions serve as a key inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop autonomous mini tillers | Enables precision agriculture for specialty crops, reducing labor costs for commercial growers. |
| Expand equipment-as-a-service models | Lowers upfront capital outlay for smallholder farmers and landscaping professionals, expanding market access. |
| Invest in advanced battery technology | Improves runtime and power output for cordless electric tillers, addressing performance limitations. |
| Establish direct-to-consumer e-commerce | Reaches residential and semi-professional users, bypassing traditional dealer networks for mini tillers. |
| Form strategic partnerships for IoT integration | Enhances real-time monitoring of tiller performance and optimizes maintenance schedules for commercial fleets. |
Research Approach
Initial hypotheses were tested against primary input from agricultural equipment engineers, commercial growers, landscaping professionals, and government policy advisors, then refined through iterative analysis. This involved combining insights from in-depth interviews with extensive secondary validation. Data sources included EPA Tier 4 standards, EU Stage V norms, India's PLI scheme documents, and company annual reports. Both bottom-up and top-down triangulation methods ensured robust market sizing and forecast accuracy.
Demand-supply balance informed the analytical framework across the modeling period, integrating market dynamics and technological advancements. Segmentation dimensions modeled included product type, power source, application, end user, and regional demand patterns. Compound annual growth rates were derived through regression analysis of historical trends and projected growth catalysts. Key industry-specific forecast inputs included battery energy density improvements and global emissions regulation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by major agricultural machinery corporations or specialized electric tool manufacturers would shift outcomes. Forecasts reflect current assumptions, yet regulatory shifts or raw material supply disruptions are key risk factors. Quarterly review of battery technology breakthroughs and government incentive programs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Asia-Pacific Agricultural Tractors Market
Agricultural Machinery
Global Autonomous Tractor Market
Agricultural Machinery
Germany Agricultural Tractor Machinery Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
Farm Tractor Market
Agricultural Machinery
Agricultural Unit Heaters Market
Agricultural Machinery
Germany Agricultural Machinery Market
Agricultural Machinery
North America Agricultural Tractors Market
Agricultural Machinery
Wheat Milling Machine Market
Agricultural Machinery
Two-Wheeler Tractors Market
Agricultural Machinery
Cow Milking Machine Market
Agricultural Machinery
Australia Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
Electric Tractors Market