
 United States Agricultural Machinery Market | 2026-2036
United States Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
United States Agricultural Machinery Market Analytics
Modular equipment bundling is realigning how Midwestern grain operations configure capital outlays. Deere & Company leverages its integrated technology stack to control premium positioning in precision planting systems. AGCO Corporation differentiates through open-architecture telemetry that competes with proprietary platforms. Kubota Corporation anchors its expansion in sub-100 horsepower utility segments where smaller diversified farms sustain replacement cycles.
United States Agricultural Machinery encompasses self-propelled and trailed equipment engineered for soil cultivation, crop establishment, harvesting, and residue management, with power ratings spanning 20 to 600+ horsepower and precision guidance accuracy below 2.5 centimeters. This equipment serves the mechanization of crop and livestock operations across commercial farms, contractor fleets, and government research stations. Tractors and harvesters occupy the dominant share of manufacturer revenue pools, while precision agriculture technology represents the fastest-expanding margin layer as subscription-based agronomy services displace pure hardware sales. Autonomous equipment development concentrates R&D investment, though regulatory ambiguity around unmanned field operations limits near-term commercial deployment. IoT integration across tillage and seeding platforms is maturing into standard factory fitment rather than aftermarket add-on.
The EPA regulates nonroad diesel emissions under Tier 4 Final standards, while OSHA governs operator safety in agricultural equipment design, and USDA conservation programs indirectly steer demand toward no-till and reduced-tillage machinery configurations. These frameworks elevate engineering costs but create compliance barriers that favor scaled manufacturers with dedicated regulatory affairs capacity. Stakeholders must monitor state-level right-to-repair legislation progression, as pending laws in multiple farm states threaten to unlock proprietary diagnostic protocols and redistribute aftermarket service revenue across dealer networks and independent repair channels.
Market Dynamics
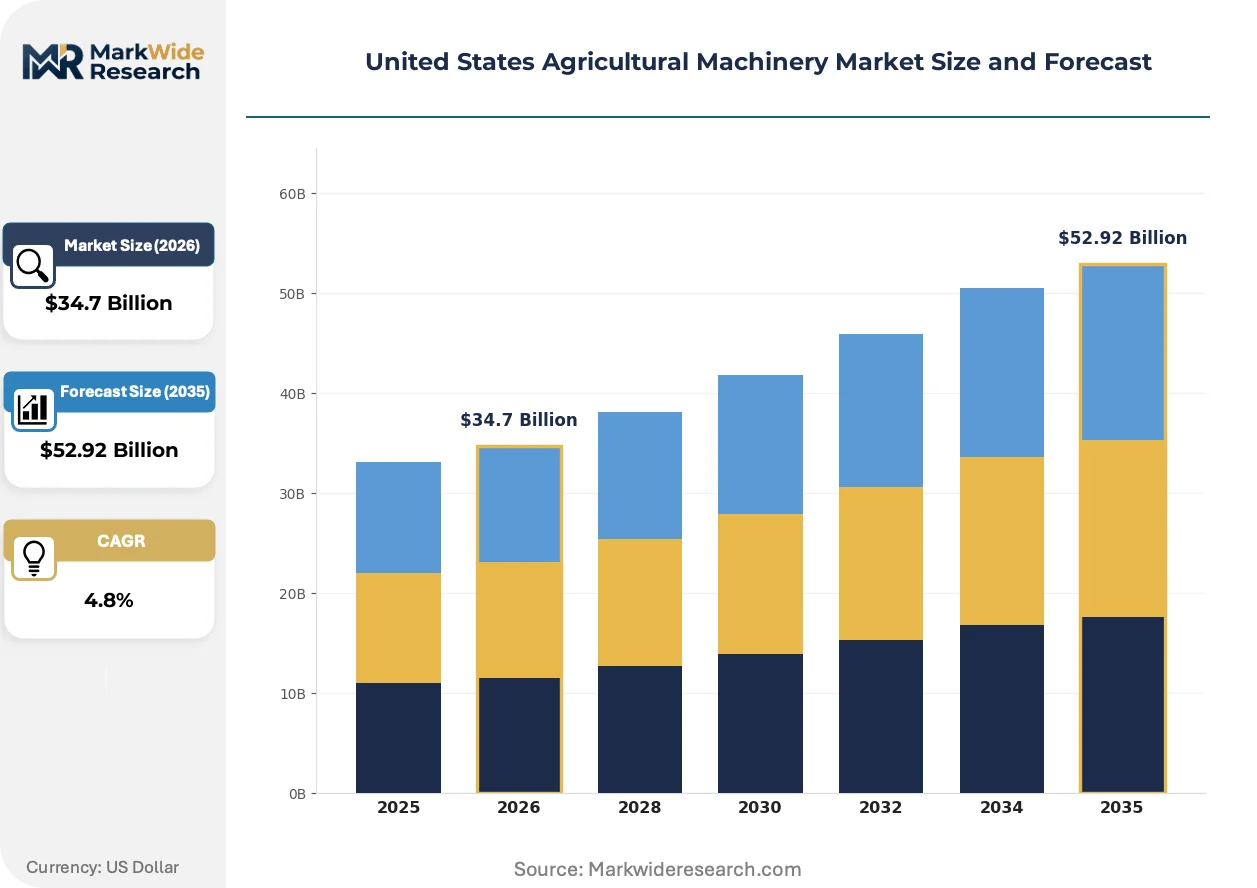
Farm consolidation across the Corn Belt and Great Plains is compressing equipment replacement cycles while elevating performance requirements for precision-guided, high-horsepower machinery. This structural concentration favors manufacturers with integrated technology stacks capable of bundling hardware, software, and subscription agronomy services.
Growth Catalysts
- EPA Tier 4 Final compliance:Off-road diesel emissions standards are accelerating powertrain redesigns toward electrified and alternative-fuel platforms, opening replacement demand across Midwestern row-crop fleets.
- Autonomous tillage systems:Labor scarcity in rural counties is pulling investment into self-propelled cultivators with sub-2.5 centimeter guidance accuracy, particularly in Nebraska and Kansas wheat operations.
- USDA conservation incentives:Cost-share programs for no-till and cover-crop adoption are redirecting capital toward specialized planting and residue management equipment configurations.
Market Restraints
- Steel and semiconductor input volatility:Fluctuations in commodity-grade steel and automotive-grade chip availability are compressing manufacturer margins and extending order-to-delivery timelines.
- Proprietary telemetry lock-in:Closed-architecture data platforms from dominant OEMs are creating switching costs that delay fleet standardization decisions among mid-scale operators.
- Right-to-repair legislative friction:Pending state-level repair access bills threaten to unlock diagnostic protocols and redistribute aftermarket service revenue across dealer and independent channels.
Strategic Opportunities
- Sub-100 horsepower utility segments:Smaller diversified farms in the Northeast and Pacific Northwest sustain replacement cycles where Kubota and regional brands maintain penetration gaps.
- Subscription agronomy services:Precision agriculture platforms are displacing pure hardware sales with recurring-revenue models tied to yield optimization and input prescription.
- Autonomous regulatory clarity:OSHA and state department of agriculture rulemaking on unmanned field operations will unlock commercial deployment timelines for robotic harvesters.
Industry Challenges
- Electrification engineering talent scarcity:Power electronics and battery thermal management expertise concentrates in automotive and aerospace sectors, forcing agricultural OEMs to compete for specialized hires.
- Legacy fleet integration complexity:Retrofitting IoT telemetry onto 10-15 year old tractors requires protocol bridging that fragments data coherence across mixed-vintage operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Agricultural Machinery Market |
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $52.92 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Plows, Harvesters, Seeders Application: Crop Production, Livestock Management, Soil Preparation, Post-Harvest End User: Farmers, Agricultural Contractors, Government Agencies, Research Institutions Technology: Precision Agriculture, Autonomous Equipment, IoT Integration, Biopesticides |
| Companies Covered | Deere & Company, CNH Industrial, AGCO Corporation, Kubota Corporation, Mahindra & Mahindra, Trimble Inc., CLAAS Group, Alamo Group Inc., Lindsay Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Agricultural Machinery Market Evolving Landscape
Telematics integration is maturing from aftermarket add-on to factory-standard fitment, compressing the value capture window for independent precision agriculture vendors. This shift is redistributing margin toward OEMs with captive data infrastructure and subscription service capabilities.
Variable-rate seeding and fertilizer application technology is consolidating control over input optimization decisions that were previously dispersed across agronomists and equipment operators. Large-scale Iowa and Illinois corn operations are adopting these systems at replacement-cycle pace, compressing the addressable market for standalone precision agriculture specialists into narrow retrofit niches.
EPA enforcement of Tier 4 Final standards is forcing accelerated R&D allocation toward electrified powertrains and alternative fuels in the 150-400 horsepower range. California Air Resources Board alignment with federal standards is creating a unified compliance perimeter that favors scaled manufacturers with dedicated regulatory affairs capacity over smaller competitors.
Equipment-as-a-service contracting is displacing traditional loan-and-lease procurement among contractor fleets and large integrated operations. This shift concentrates credit risk with manufacturers while transferring operational and maintenance responsibility to OEM service networks, most visible in Texas and Florida vegetable production regions where seasonal cash flow volatility favors subscription models.
United States Agricultural Machinery Market Segmentation
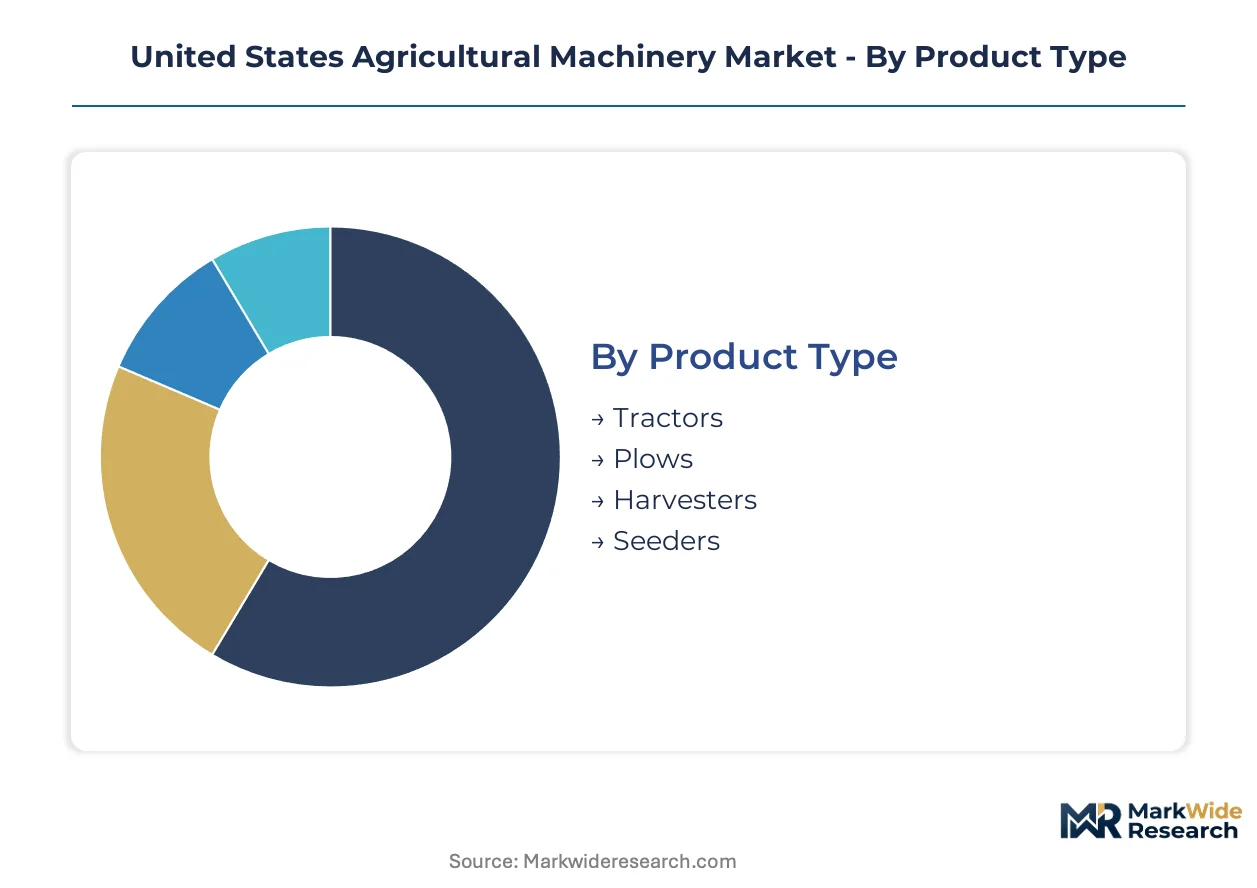
Equipment procurement patterns across the Corn Belt and Great Plains diverge sharply by operational scale and technology adoption stage. Understanding these splits enables manufacturers to align R&D investment with replacement-cycle timing and regional consolidation trajectories.
Product Type:
Volume concentration sits with mid-horsepower tractors serving 500-2,000 acre grain operations, while premium capture concentrates in harvester automation and precision planting systems.
- Tractors:Power ratings from 40 to 600+ horsepower dominate capital allocation across Midwestern row-crop fleets. EPA Tier 4 Final compliance costs are compressing margins in the sub-150 horsepower range where price sensitivity is highest among smaller diversified operations.
- Harvesters:Self-propelled combines with integrated yield mapping and moisture sensing command premium positioning in Iowa and Illinois corn-soy rotations. Labor scarcity in rural counties is accelerating autonomous header control development, though regulatory ambiguity limits near-term deployment.
- Plows:Trailed and mounted tillage equipment faces demand pressure from USDA conservation incentives favoring no-till configurations. Residue management attachments are gaining specification share in wheat-heavy Kansas and Nebraska operations.
- Seeders:Precision planting systems with sub-2.5 centimeter guidance accuracy represent the fastest-expanding margin layer as subscription agronomy services displace pure hardware sales.
Mature deployment sits with tractors. Newer deployment is concentrated in precision seeders and autonomous harvester prototypes.
Application:
Margin capture follows the input optimization value chain, with highest software attach rates in crop production and soil preparation versus commodity equipment sales in post-harvest handling.
- Crop Production:Variable-rate seeding and fertilizer application technology consolidates control over agronomic decisions previously dispersed across operators and consultants. Large-scale Iowa and Illinois operations adopt these systems at replacement-cycle pace.
- Soil Preparation:Reduced-tillage and no-till configurations are redirecting capital from conventional plows toward specialized planting equipment. USDA cost-share programs accelerate this shift in the Dakotas and western Minnesota.
- Livestock Management:Feeding and waste handling equipment sustains replacement cycles in Texas and Florida integrated operations where seasonal cash flow volatility favors equipment-as-a-service contracting.
- Post-Harvest:Grain handling and drying systems face elongated replacement timelines as on-farm storage consolidation reduces unit demand per bushel handled.
Equipment-as-a-service penetration is deepest in livestock management. Straight procurement persists in post-harvest where capital cycles track elevator infrastructure investment.
End User:
Consolidation dynamics split the customer base between fewer, larger farms demanding bundled technology stacks and fragmented smaller operations sustaining utility-segment replacement.
- Farmers:Commercial grain operations above 2,000 acres concentrate demand for integrated precision agriculture platforms. Sub-500 acre diversified farms in the Northeast and Pacific Northwest sustain Kubota and regional brand penetration in sub-100 horsepower segments.
- Agricultural Contractors:Custom harvest and planting fleets prioritize uptime guarantees and seasonal flexibility, driving equipment-as-a-service adoption in Texas and Florida vegetable regions.
- Government Agencies:Conservation equipment procurement through USDA programs channels demand toward no-till and cover-crop machinery configurations.
- Research Institutions:University extension and USDA stations drive early-stage autonomous equipment validation, though commercial deployment timelines remain uncertain.
Technology bundling is most advanced with large commercial farmers. Service-based contracting is expanding fastest among agricultural contractors.
Technology:
Factory-standard integration is displacing aftermarket fitment, redistributing margin toward OEMs with captive data infrastructure and recurring-revenue service capabilities.
- Precision Agriculture:Telematics and yield optimization platforms are climbing the fastest as subscription agronomy services replace standalone hardware sales. Deere's integrated technology stack controls premium positioning in this segment.
- Autonomous Equipment:Self-propelled cultivators with sub-2.5 centimeter guidance accuracy address labor scarcity in Nebraska and Kansas wheat operations. OSHA and state department of agriculture rulemaking will determine commercial deployment timelines.
- IoT Integration:Protocol standardization is maturing from aftermarket add-on to factory fitment, compressing value capture for independent precision agriculture vendors.
- Biopesticides:Application equipment modifications for biological crop protection inputs remain nascent, with demand concentrated in organic-certified operations and specialty crop regions.
IoT integration represents the most mature technology layer. Autonomous equipment holds the steepest expansion trajectory pending regulatory clarity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production capacity concentrates in the Midwestern manufacturing belt while consumption patterns track farm consolidation across the Corn Belt and Great Plains. The regional distribution reflects proximity to both assembly infrastructure and the largest commercial grain operations.
Corn Belt
Iowa and Illinois corn-soy rotations drive demand for high-horsepower tractors and precision planting systems. EPA Tier 4 Final enforcement accelerates fleet turnover in this densest concentration of row-crop acreage. Deere's Waterloo, Iowa manufacturing complex anchors regional supply chain integration for harvester and tractor platforms.
Great Plains
Nebraska and Kansas wheat operations prioritize autonomous tillage systems addressing acute rural labor scarcity. USDA conservation cost-share programs redirect capital toward no-till seeding configurations across the Dakotas. AGCO's Hesston, Kansas facility supports regional specialization in self-propelled windrowers and hay equipment.
Pacific Northwest
Washington and Oregon diversified farms sustain replacement cycles in sub-100 horsepower utility segments where smaller operations resist consolidation pressures. OSHA agricultural safety inspections elevate equipment specification requirements in this specialty crop region. Kubota maintains distribution density through Portland-Seattle corridor dealer networks.
Southeast
Florida and Georgia vegetable production regions favor equipment-as-a-service contracting models accommodating seasonal cash flow volatility. State-level right-to-repair legislative activity in Florida threatens proprietary diagnostic protocol lock-in. Lindsay Corporation's irrigation systems penetrate the Florida sugarcane and Georgia peanut belts.
Southwest
Texas cotton and cattle operations blend row-crop automation with livestock management equipment procurement. The Texas Department of Agriculture coordinates with OSHA on autonomous field operation pilot programs. CNH Industrial's Grand Island, Nebraska and Fargo, North Dakota facilities extend service coverage into the Texas Panhandle through regional distribution hubs.
United States Agricultural Machinery Market Competitive Landscape
The competitive structure tilts toward integrated technology stacks bundling hardware, software, and subscription services. Tier 1 manufacturers with dedicated regulatory affairs capacity capture premium positioning under EPA compliance frameworks. Three archetypes dominate: diversified full-line OEMs with captive precision agriculture platforms, specialized harvester and planting equipment fabricators, and utility-segment specialists serving sub-500 acre operations. Consolidation through strategic technology licensing and geographic distribution expansion constitutes the primary competitive vector.
Among diversified full-line OEMs, Deere & Company and CNH Industrial exemplify the integrated technology stack archetype controlling premium market tiers. AGCO Corporation represents the open-architecture challenger positioning against proprietary telemetry lock-in. Kubota Corporation anchors the utility-segment specialization archetype where sub-100 horsepower replacement cycles sustain penetration in fragmented smaller-farm markets.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial |
| AGCO Corporation |
| Kubota Corporation |
| Mahindra & Mahindra |
| Trimble Inc. |
| CLAAS Group |
| Alamo Group Inc. |
| Lindsay Corporation |
| Others |
Value Network & Pricing Analysis
Commodity-grade steel and automotive-grade semiconductor inputs cascade through three-tier pricing structures across Midwestern row-crop equipment procurement, with EPA Tier 4 Final compliance costs compressing margins most acutely in sub-150 horsepower segments where smaller diversified operations exhibit acute price sensitivity.
Pricing Analysis
Margin tightening in sub-150 horsepower utility segments reflects semiconductor input volatility and steel commodity fluctuations, while premium capture concentrates in harvester automation and precision planting systems where Deere's integrated technology stack commands brand premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by horsepower rating and telemetry bundling, with large-scale Corn Belt operations least sensitive to upfront capital outlays and sub-500 acre Northeast farms most responsive to financing terms.
Supply Chain Analysis
Automotive-grade chip supply rests on Taiwanese foundry capacity and South Korean memory producers, while commodity steel feeds from domestic mills in Indiana and Ohio. Hydraulic system components draw from German and Japanese precision engineering suppliers, creating tariff exposure on specialty valves and pumps. Distribution runs through manufacturer-captive dealer networks anchored in Iowa and Illinois, with independent aftermarket channels fragmenting service parts availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Agricultural Machinery Market is consolidating around integrated technology stacks, with EPA compliance costs and proprietary telemetry investments forcing smaller fabricators toward exit or acquisition.
For Market Incumbents: To counter proprietary telemetry lock-in challenges from open-architecture competitors, Deere and CNH Industrial should deepen backward integration into precision agriculture software development while expanding captive dealer service capacity in Nebraska and Kansas autonomous tillage corridors. Regulatory affairs investment represents a critical lever given EPA Tier 4 Final enforcement timelines. For New Entrants and Emerging Players: Regional dealer networks in the Pacific Northwest offer the most penetrable channel structure, where Kubota's distribution density leaves white space for sub-100 horsepower utility specialists targeting diversified Washington and Oregon operations. A go-to-market angle anchored in right-to-repair legislative alignment can unlock independent service channel partnerships. For Investors and Strategic Acquirers: OSHA rulemaking clarity on unmanned field operations is the leading indicator that autonomous equipment commercialization timelines will compress, signaling long-term viability for precision agriculture platform investments. Acquisition targets should emphasize mid-cap specialists with EPA certification capacity and telemetry protocol expertise. A small set of regulatory triggers warrants ongoing watch.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Platform Integration | Deere's technology stack consolidates subscription agronomy revenue across Iowa and Illinois corn operations. |
| Autonomous Equipment Regulatory Engagement | OSHA and state agriculture department coordination determines commercial deployment timelines for robotic harvesters. |
| Sub-100 Horsepower Segment Expansion | Kubota's Pacific Northwest dealer density captures replacement cycles in diversified smaller farm markets. |
| Equipment-as-a-Service Contracting | CNH Industrial's seasonal subscription models address cash flow volatility in Texas and Florida vegetable regions. |
| Right-to-Repair Legislative Alignment | Independent service channel partnerships in Florida and farm-state corridors redistribute aftermarket revenue streams. |
Research Methodology
Multi-period observation of EPA enforcement timelines, farm consolidation trajectories, and equipment replacement cycles anchored the trend analysis, supplemented by interviews with OEM product strategy directors, Midwestern dealer network managers, agricultural contractor fleet operators, and USDA conservation program administrators. Secondary validation drew from EPA regulatory filings, SEC 10-K equipment revenue disclosures, USDA Census of Agriculture data, and Association of Equipment Manufacturers shipment reports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segment-weighting across product type, application, end user, and technology dimensions structured the analytical framework, with horsepower tier and telemetry integration level providing additional granularity specific to agricultural equipment procurement patterns. CAGRs were derived from replacement-cycle timing models and consolidation-driven demand concentration across the projection horizon. Input cost volatility indices and regulatory compliance cost curves informed margin compression assumptions.
Caveats apply where OSHA autonomous operation rulemaking delays, right-to-repair legislative outcomes, or semiconductor supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions about farm consolidation pace and EPA enforcement consistency. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Argentina Agricultural Machinery Market
Agricultural Machinery
Italy Agricultural Machinery Market
Agricultural Machinery
Autonomous Farm Equipment Market
Agricultural Machinery
Milking Robots Market
Agricultural Machinery
Spain Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
Tractor Implements Market
Agricultural Machinery
Power Tiller Market
Agricultural Machinery
Sickle Bar Mower Market
Agricultural Machinery
Global Agricultural Sprayer Market
Agricultural Machinery
Germany Agricultural Tractor Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
North America Agricultural Tractors Machinery Market
Agricultural Machinery
North America Plowing and Cultivating Machinery Market
Agricultural Machinery
Autonomous Electric Tractor Market
Agricultural Machinery
Europe Agricultural Tractors Market