
 Milking Robots Market | 2026-2036
Milking Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Milking Robots Market Intelligence
Stainless steel composites are repositioning chassis and arm construction in milking robots, trimming unit weight while extending wash-cycle durability against acid and alkaline cleaning protocols. DeLaval leverages its vertically integrated supply chain to control component quality from sensor modules to milk metering electronics. GEA Group AG anchors its competitive stance through intensive R&D spending on vision-guided teat-cup attachment systems. Lely differentiates via proprietary herd-management software that integrates feeding, milking, and health monitoring into unified farm data layers.
Milking robots constitute electromechanical systems that autonomously identify individual cows, sanitize teats, attach milking clusters, monitor milk flow and quality parameters, and release animals without human intervention; core specifications include milking frequencies of two to three times daily per animal, teat-detection accuracy thresholds above 99%, and throughput rates ranging from 60 to 120 cows per robot unit depending on barn configuration and animal traffic design. Robotic Milking Systems capture the dominant share of product-type revenue as farm operators prioritize fully autonomous units over semi-automated retrofits that retain substantial manual intervention. Vision Systems and Sensor Technologies command expanding technology budgets as producers demand real-time mastitis detection, somatic cell count alerts, and automated sort-gate routing based on individual animal health signals.
The EU Machinery Directive and CE marking requirements govern safety interlocks and electromagnetic compatibility for robotic installations across member states, while FDA Grade A Pasteurized Milk Ordinance provisions in the United States dictate sanitary design standards for milk contact surfaces and cleaning validation protocols. ISO 5707 and ISO 6690 standards establish international benchmarks for milking machine performance and cleaning system efficacy, shaping procurement specifications for export-oriented manufacturers. Stakeholders must monitor evolving animal welfare regulations in Germany and the Netherlands, where pending rule changes on cow traffic freedom and resting time minimums could mandate hardware retrofits or accelerate replacement demand for systems that restrict natural movement patterns.
Market Dynamics
Labor scarcity across rural dairy economies is compressing replacement cycles for conventional milking parlors, pushing capital allocation toward autonomous systems that reduce hourly labor requirements by over sixty percent.
Growth Catalysts
- EU F-Gas Regulation:Mandatory phase-down of hydrofluorocarbons in cooling systems accelerates equipment turnover toward electrically efficient robotic installations.
- Stainless steel composites:Advanced chassis materials extend wash-cycle durability against acid and alkaline protocols, reducing maintenance downtime and replacement frequency.
- Netherlands procurement clusters:Dense dairy infrastructure and early robotics adoption create concentrated demand hubs that validate system performance for export markets.
Market Restraints
- Copper and rare-earth magnet costs:Servo motor supply chains face input volatility that compresses hardware margins and extends quote validity periods.
- Vision system technical limitations:Teat-detection accuracy thresholds above ninety-nine percent remain difficult to maintain in soiled or low-light barn conditions.
- German animal welfare code revisions:Pending rule changes on cow traffic freedom could mandate expensive hardware retrofits for existing installations.
Strategic Opportunities
- Mid-scale farm segment:Herds between one hundred and three hundred cows remain underpenetrated by fully autonomous systems relative to large-scale operations.
- Vision-guided teat-cup attachment:Convergence of machine vision with pneumatic positioning creates differentiation potential for precision attachment in irregular udder conformations.
- US Grade A Pasteurized Milk Ordinance:Sanitary design standards for milk contact surfaces create certification-driven preference shifts toward validated cleaning protocols.
Industry Challenges
- Electromechanical technician scarcity:Farm-level maintenance of sensor arrays and pneumatic clusters requires skills absent in traditional dairy labor pools.
- ISO 5707 certification timelines:International performance benchmarking for milking machine efficacy extends product validation cycles and delays market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milking Robots Market |
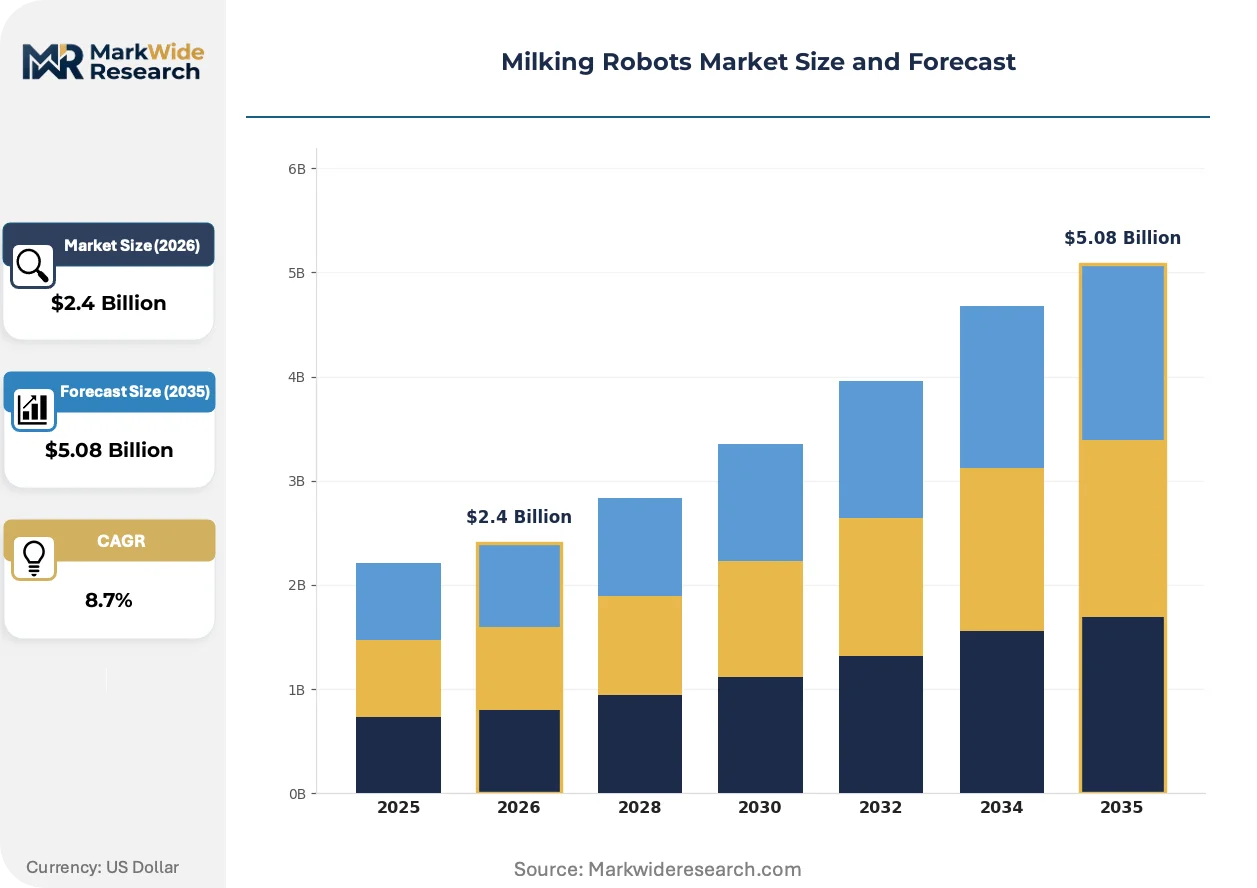
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Milking Systems, Automated Milking Parlors, Semi-Automated Systems, Dairy Herd Management Systems End User: Dairy Farms, Agricultural Cooperatives, Large Scale Operations, Smallholder Farms Technology: Vision Systems, Machine Learning, IoT Integration, Sensor Technologies Deployment: On-Farm Installation, Remote Monitoring, Cloud-Based Solutions, Plug-and-Play Systems |
| Companies Covered | Nedap Livestock Management, Fullwood JOZ, DeLaval, System Happel GmbH, Milkomax solutions laiteres inc., GEA Group AG, BouMatic, Dairymaster, Lely, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milking Robots Market Strategic Shifts & Innovations
Hardware-software integration is redefining competitive moats in milking robotics, with proprietary data layers emerging as the primary retention mechanism beyond mechanical reliability.
Machine vision for real-time mastitis detection is converging with automated sort-gate routing, enabling immediate animal segregation based on somatic cell count alerts. Large herd operators in the Netherlands and Denmark are deploying these integrated health-monitoring layers at scale. The structural consequence is compressing veterinary response times from days to hours while generating proprietary herd datasets that lock in equipment replacement decisions.
REACH chemical restrictions and EU Machinery Directive safety interlocks are mandating redesigned electromagnetic compatibility for robotic installations across member states. Manufacturers must recertify control systems for CE marking compliance, extending engineering timelines. Dairy cooperatives in Germany and France are responding by consolidating procurement specifications to pre-validated platform configurations that reduce site-specific engineering.
Service contract unbundling is fragmenting traditional bundled maintenance models into component-level subscriptions covering software updates, spare parts, and remote diagnostics separately. Dealer networks in North America are losing exclusivity on aftermarket revenue as direct manufacturer telemetry enables predictive intervention. This shift is most visible among Wisconsin and California operations with multi-site deployments negotiating enterprise service agreements.
Milking Robots Market Segmentation
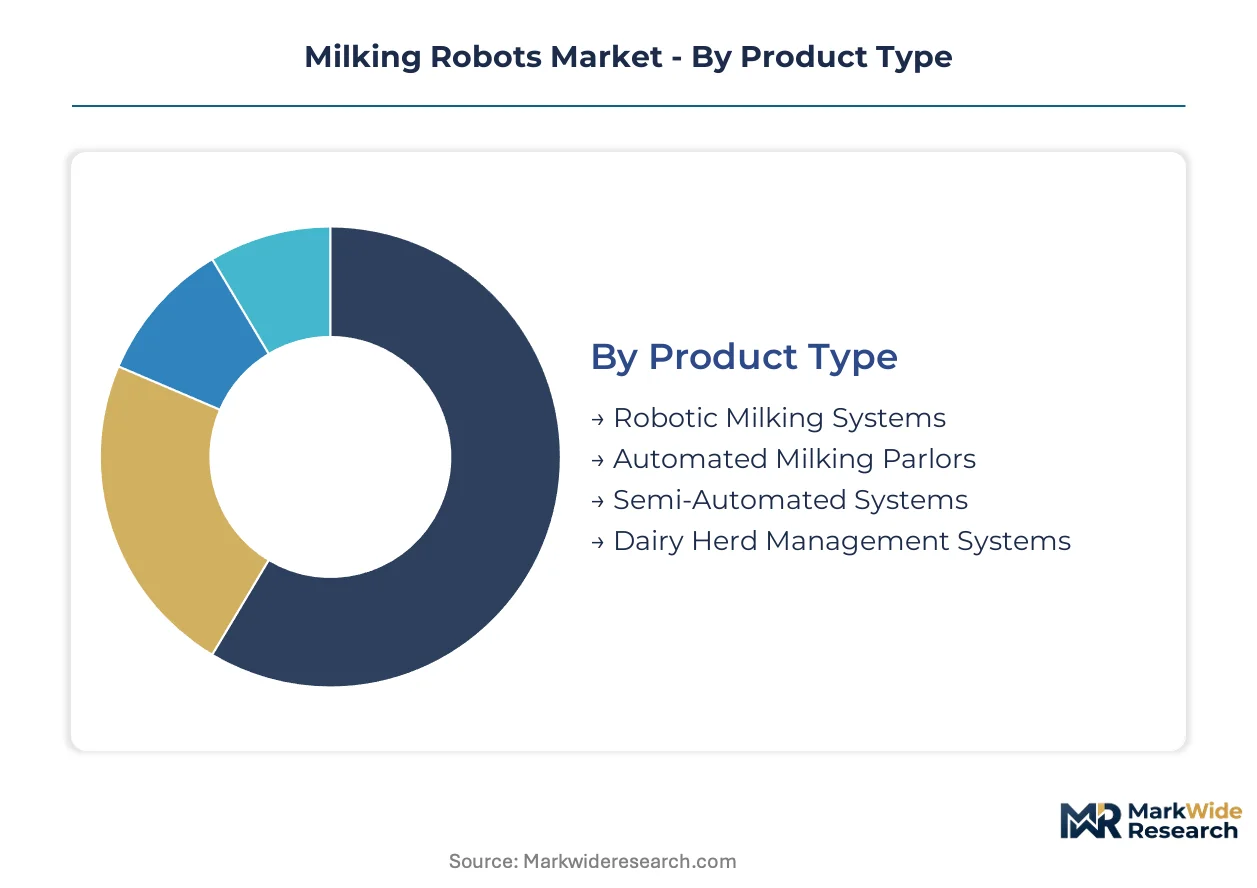
Milking robot procurement patterns diverge sharply between capital-intensive autonomous units and retrofit-compatible semi-automated configurations. Equipment specification varies by herd scale, barn infrastructure age, and regulatory compliance timelines across dairy-producing regions.
Product Type:
Volume deployment concentrates in fully autonomous units, while premium positioning attaches to integrated herd-management platforms.
- Robotic Milking Systems:Electromechanical units with autonomous teat identification, cluster attachment, and milk flow monitoring deliver throughput rates of 60 to 120 cows per unit. Demand clusters in the Netherlands and Denmark where labor scarcity and dense dairy infrastructure validate capital recovery models.
- Automated Milking Parlors:Batch-processing configurations retain rotary or parallel architecture while automating cluster attachment and detachment sequences. Large-scale operations in Wisconsin and California deploy these for herds exceeding 500 head where throughput efficiency outweighs per-cow customization.
- Semi-Automated Systems:Retrofit-compatible units preserve existing parlor infrastructure while automating select functions.
- Dairy Herd Management Systems:Software-centric platforms integrating feeding, milking, and health data layers.
Mature deployment sits with Robotic Milking Systems. Newer deployment is concentrated in Dairy Herd Management Systems.
End User:
Customer segmentation tracks capital access, technical staffing capacity, and procurement aggregation mechanisms.
- Large Scale Operations:Herds above 500 cows drive autonomous system adoption where labor reduction economics justify capital intensity. These operators in the Netherlands and Germany negotiate enterprise service agreements and validate performance data for export market reference.
- Dairy Farms:Mid-scale independent operators between 100 and 300 cows represent the most contested segment. Equipment vendors target this group with financing packages and dealer-supported maintenance to offset electromechanical technician scarcity.
- Agricultural Cooperatives:Pooled procurement entities consolidating demand across member farms.
- Smallholder Farms:Sub-100 cow operations where capital constraints and barn retrofit costs limit penetration.
Procurement sophistication peaks with Large Scale Operations. Equipment financing innovation targets Dairy Farms.
Technology:
Technology budgets are reallocating from mechanical reliability toward data-generating sensor layers and predictive analytics.
- Vision Systems:Camera arrays with machine vision algorithms achieve teat-detection accuracy thresholds above 99% under controlled lighting. GEA Group AG directs intensive R&D spending here to differentiate precision attachment in irregular udder conformations.
- Sensor Technologies:Multi-parameter arrays monitoring milk conductivity, flow rate, and temperature enable real-time mastitis detection. Large herd operators deploy these with automated sort-gate routing to compress veterinary response intervals.
- Machine Learning:Predictive models for yield optimization and health anomaly detection.
- IoT Integration:Telemetry infrastructure connecting distributed equipment to centralized monitoring platforms.
Hardware differentiation now depends on Vision Systems. Data monetization potential concentrates in Sensor Technologies.
Deployment:
Installation and service models are fragmenting from bundled dealer contracts toward component-level subscription structures.
- On-Farm Installation:Permanent electromechanical integration requiring site-specific civil works, electrical infrastructure, and barn reconfiguration. This remains the dominant deployment mode in established dairy regions with purpose-built facilities.
- Cloud-Based Solutions:Software and analytics layers delivered via remote infrastructure, enabling centralized herd management across dispersed locations. North American multi-site operators in Wisconsin and California negotiate these for enterprise visibility.
- Remote Monitoring:Manufacturer-direct telemetry replacing dealer exclusivity on diagnostics and intervention.
- Plug-and-Play Systems:Modular units with minimized site preparation requirements.
Service revenue retention is strongest with On-Farm Installation. Expansion trajectory is steepest for Cloud-Based Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the Netherlands, where dense dairy infrastructure and early robotics adoption validate system performance for export markets. Labor scarcity across rural economies accelerates procurement timelines in Northern European markets. Regulatory pressure from Brussels shapes equipment replacement cycles continent-wide.
Netherlands
Farms with herd sizes above 500 cows drive autonomous system adoption where labor reduction economics justify capital intensity. The EU F-Gas Regulation accelerates turnover toward electrically efficient robotic installations. Dairy clusters around Friesland and Gelderland validate integrated health-monitoring layers at scale.
Germany
Pending revisions to the national animal welfare code on cow traffic freedom could mandate expensive hardware retrofits for existing installations. The EU Machinery Directive governs safety interlocks and electromagnetic compatibility for robotic installations. Bavarian and Lower Saxony cooperatives consolidate procurement specifications to pre-validated platform configurations.
United States
Large-scale operations in Wisconsin and California deploy automated milking parlors for herds exceeding 500 head where throughput efficiency outweighs per-cow customization. FDA Grade A Pasteurized Milk Ordinance provisions dictate sanitary design standards for milk contact surfaces. Multi-site operators in the Upper Midwest negotiate enterprise service agreements for telemetry infrastructure.
Denmark
Large herd operators deploy vision-guided systems with automated sort-gate routing to compress veterinary response intervals. REACH chemical restrictions mandate redesigned electromagnetic compatibility for control systems. Jutland dairy infrastructure generates proprietary herd datasets that lock in equipment replacement decisions.
France
Dairy cooperatives respond to regulatory recertification requirements by consolidating procurement to pre-validated configurations. The EU Green Deal accelerates capital allocation toward energy-efficient installations. Brittany and Normandy farming collectives pilot cloud-based herd management across dispersed locations.
Milking Robots Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated solution providers commanding premium positioning against component suppliers. The vendor base organizes around three strategic archetypes: full-stack system integrators with proprietary software layers, electromechanical hardware specialists with modular retrofit compatibility, and data-centric platform operators monetizing telemetry subscriptions. Consolidation pressure intensifies as service contract unbundling fragments traditional bundled maintenance models. Geographic expansion and technology licensing represent the dominant competitive vectors as manufacturers seek validated reference sites for export market entry.
Among European-anchored full-stack integrators, DeLaval and GEA Group AG occupy positions defined by upstream control over sensor modules and milk metering electronics. Lely exemplifies the data-centric archetype through proprietary herd-management software that unifies feeding, milking, and health monitoring into consolidated farm data layers. These three entities represent the competitive tension between hardware reliability and software-driven retention mechanisms.
| Leading Market Players |
|---|
| Nedap Livestock Management |
| Fullwood JOZ |
| DeLaval |
| System Happel GmbH |
| Milkomax solutions laiteres inc. |
| GEA Group AG |
| BouMatic |
| Dairymaster |
| Lely |
| Others |
Cost & Logistics Intelligence
Stainless steel composite adoption in chassis and arm construction simultaneously trims unit weight and concentrates procurement leverage among vertically integrated manufacturers controlling sensor-to-metering electronics production. This materials transition feeds cost economics toward scale players while fragmenting component sourcing for modular retrofit specialists.
Pricing Analysis
Volume deployment concentrates in fully autonomous units commanding premium positioning, while margins compress in semi-automated retrofit tiers where standardization limits differentiation. Pricing stratifies across premium, standard, and economy tiers based on teat-detection accuracy certification and bundled after-sales service intensity. Cost compression in economy-tier hardware is intensifying because copper and rare-earth magnet input volatility squeezes servo motor margins. Mid-scale dairy farms between 100 and 300 cows exhibit acute price sensitivity, whereas large-scale operations above 500 cows prioritize throughput efficiency and data integration over unit cost.
Supply Chain Analysis
Electromechanical technician scarcity in the Netherlands, Germany, and Denmark constrains final assembly capacity expansion despite component availability. Servo motor production draws from rare-earth magnet supply chains anchored in China, while stainless steel composite fabrication rests on specialized European metallurgy. Single-source vulnerability in vision system camera arrays creates procurement risk for manufacturers pursuing 99% teat-detection accuracy thresholds. Distribution runs through dealer networks losing exclusivity as manufacturer-direct telemetry enables predictive service intervention.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation creates a cost-of-compliance moat that favors incumbent manufacturers with established CE marking pathways and recertification engineering capacity, disadvantaging new entrants lacking validated platform configurations.
For Market Incumbents: Hedge against service contract unbundling by consolidating proprietary data layers into unified herd-management platforms that lock in replacement decisions. Invest in backward integration into sensor module production to control quality from teat detection through milk metering. Counter emerging data-centric platform operators by embedding predictive health analytics into baseline hardware offerings. For New Entrants and Emerging Players: Capture the underpenetrated mid-scale farm segment between 100 and 300 cows through financing packages and dealer-supported maintenance that offset electromechanical technician scarcity. Target Wisconsin and California multi-site operators negotiating enterprise telemetry agreements as reference sites for export market validation. Deploy plug-and-play modular units with minimized site preparation requirements to reduce barn retrofit barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by full-stack system integrators seeking proprietary software layers and validated reference sites in the Netherlands or Denmark. Long-term viability favors data-centric platform operators monetizing telemetry subscriptions over hardware-dependent electromechanical specialists. Watch pending German animal welfare code revisions on cow traffic freedom as an inflection indicator mandating hardware retrofit demand or replacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Vision-Guided Teat-Cup Attachment R&D | GEA Group AG directs spending here to differentiate precision in irregular udder conformations. |
| Proprietary Herd-Management Software Integration | Lely unifies feeding, milking, and health data layers to drive equipment replacement lock-in. |
| CE Marking Recertification Investment | REACH chemical restrictions mandate redesigned electromagnetic compatibility for EU market access. |
| Enterprise Service Agreement Expansion | Wisconsin and California multi-site operators negotiate manufacturer-direct telemetry infrastructure. |
| Mid-Scale Farm Financing Program Launch | Equipment vendors target 100-300 cow operations with dealer-supported maintenance packages. |
Research Approach
Independent corroboration across dairy farm operators, electromechanical maintenance directors, and cooperative procurement managers underwrites the qualitative findings. Primary interviews with equipment vendor sales engineers and aftermarket service heads combined with secondary validation from EU Machinery Directive filings, ISO 5707 certification databases, and FDA Grade A Pasteurized Milk Ordinance provisions establish empirical grounding. Bottom-up installation data triangulates against top-down capital expenditure tracking across the analysis window.
Rate-of-change decomposition separates hardware replacement cycles from software subscription adoption velocities across the projection horizon. Segmentation dimensions modeled include product type autonomy level, herd scale tier, technology layer priority, and deployment model configuration. CAGRs derive from installed base growth rates overlaid with average selling price evolution by tier. Forecast inputs incorporate labor scarcity indices in rural dairy economies and regulatory compliance timeline acceleration under EU F-Gas phase-down mandates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to German animal welfare code revisions and copper/rare-earth magnet commodity volatility. Forecasts reflect documented assumptions regarding barn infrastructure age distribution and technician training pipeline capacity. A small set of triggers warrants ongoing watch: pending cow traffic freedom mandates, REACH chemical restriction expansions, and vision system accuracy degradation in soiled barn conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Farm Tractor Market
Agricultural Machinery
Global Tractor Market
Agricultural Machinery
Global Agricultural Sprayer Market
Agricultural Machinery
Europe Agricultural Tractors Market
Agricultural Machinery
Utility Tractor Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
Vietnam Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Irrigation Machinery Market
Agricultural Machinery
Tractor Implements Market
Agricultural Machinery
Asia-Pacific Utility Tractor Market
Agricultural Machinery
South America Agricultural Tractors Market
Agricultural Machinery
Compact Tractor Market
Agricultural Machinery
Driverless Tractor Market
Agricultural Machinery
Agricultural Tractor Robots Market
Agricultural Machinery
Forestry Machinery Market
Agricultural Machinery
Agricultural Spray Drone Market