
 Agricultural Tractor Market | 2026-2036
Agricultural Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Tractor Market Analysis
Multi-source engine supply is consolidating as OEMs reduce supplier counts to secure emissions-compliant powertrain volumes. John Deere leverages captive engine manufacturing to control certification timelines. CNH Industrial anchors its European and North American output through vertically integrated powertrain facilities. AGCO Corporation competes via a mixed model, blending in-house FPT Industrial supply with selective outsourcing for regional variants.
An agricultural tractor is a self-propelled vehicle delivering mechanical power through a diesel or alternative-fuel engine, typically rated between 15 and 600 horsepower, designed to pull or power implements for tillage, planting, and material handling. Its primary commercial purpose is to replace animal and human labor in field operations, improving throughput and operational consistency across seasonal windows. Utility tractors dominate volume in mature markets where diversified small-to-mid farms require flexible horsepower platforms. GPS guidance and automated steering represent the fastest-expanding technology tier, as precision agriculture commands premium positioning and repeat hardware upgrades. Electric propulsion remains nascent but occupies strategic R&D bandwidth among manufacturers preparing for future powertrain shifts.
The EPA governs off-road diesel emissions through Tier 4 Final mandates in the United States, while the European Union enforces Stage V limits via the European Commission's Non-Road Mobile Machinery framework; both regimes elevate engine costs and filter maintenance burdens for fleet operators. India's Central Pollution Control Board implements Bharat Stage norms that progressively tighten particulate thresholds, compelling localized engine calibration by manufacturers serving South Asian markets. Stakeholders must monitor regulatory divergence between established and emerging economies when allocating product development budgets and factory certification investments.
Market Dynamics
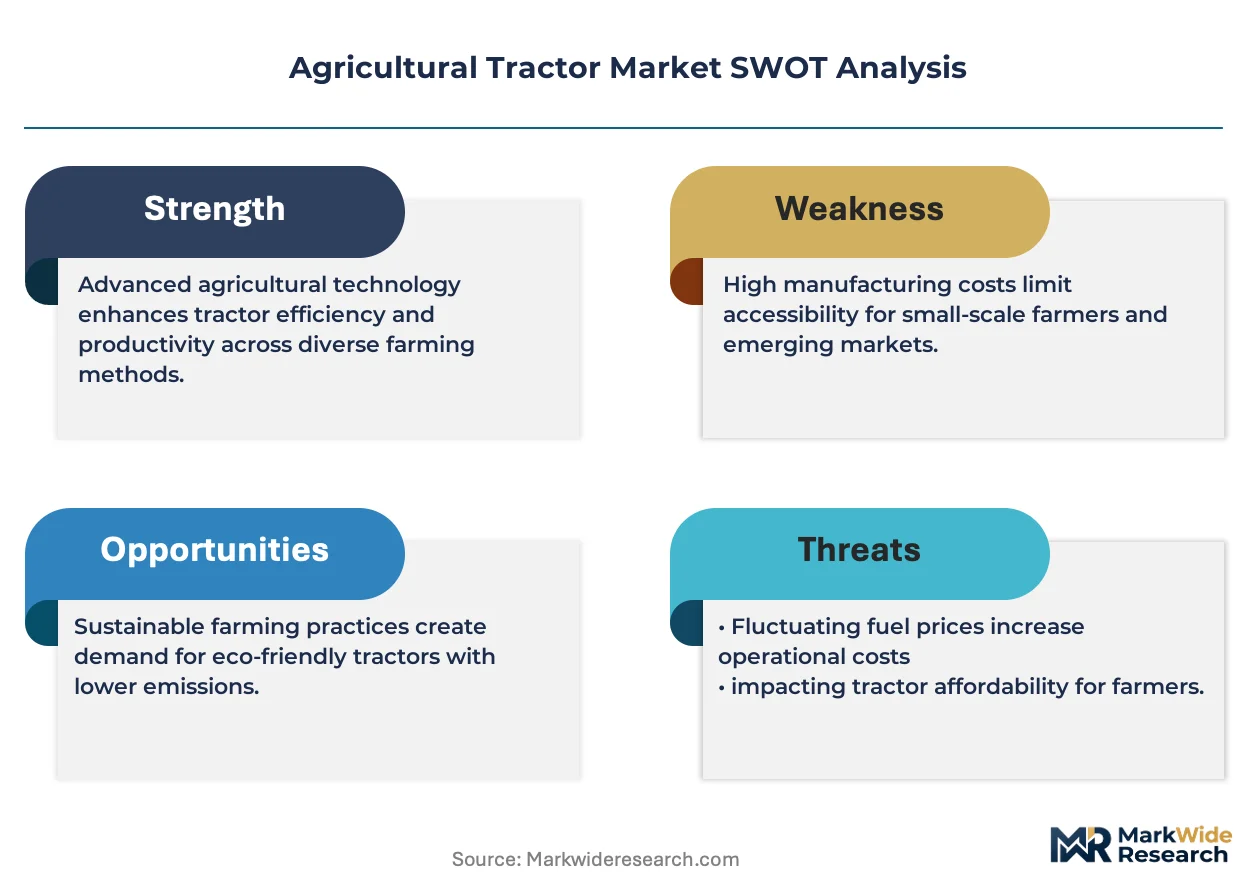
Tier 4 Final and Stage V emissions standards are compressing engine supplier margins while forcing OEMs to consolidate powertrain sourcing around certified volumes. This regulatory pressure is reshaping competitive positioning between vertically integrated manufacturers and assembly-dependent competitors.
Growth Catalysts
- Precision Agriculture Hardware:GPS guidance and automated steering systems command premium positioning as large-scale commercial farming operations in Brazil and India expand mechanized fleets to maximize seasonal throughput windows.
- Bharat Stage Regulatory Trajectory:India's Central Pollution Control Board progressively tightens particulate thresholds, compelling localized engine calibration that locks in manufacturer commitment to South Asian supply chains.
- Soybean Frontier Mechanization:Mato Grosso's expanding commercial acreage generates sustained demand for high-horsepower platforms capable of pulling heavy tillage and planting implements across extended field operations.
Market Restraints
- Diesel After-Treatment Cost Burden:Diesel particulate filters and selective catalytic reduction systems add material cost and maintenance complexity, elevating total cost of ownership for fleet operators in price-sensitive segments.
- Supplier Consolidation Risk:OEM reduction of engine supplier counts concentrates volume risk among fewer Tier 1 powertrain manufacturers, exposing procurement to single-source disruption.
- Battery Energy Density Limitation:Current lithium-ion cell chemistry cannot deliver the sustained high-torque output required for heavy draft applications, constraining electric platform viability to sub-100 horsepower utility segments.
Strategic Opportunities
- Underpenetrated Smallholder Mechanization:India's Punjab-Haryana belt contains substantial acreage still dependent on animal traction, representing conversion potential for affordable 15-35 horsepower utility tractors with localized financing structures.
- Telematics-Enabled Fleet Management:Convergence of machine connectivity with predictive maintenance algorithms creates recurring revenue streams through software subscriptions and remote diagnostics services.
- EU Green Deal Agricultural Transition:Carbon reduction incentives and sustainable farming mandates accelerate interest in alternative fuel trials, positioning early movers for preferential treatment in European public procurement.
Industry Challenges
- Emissions Certification Timeline Compression:EPA and European Commission testing protocols require extended validation cycles, delaying product launches and freezing engineering resources on compliance rather than feature innovation.
- Electronics-Hydraulics Integration Complexity:Precision agriculture systems demand seamless coordination between ISOBUS implement controls, variable-rate application hardware, and autonomous steering actuators, stretching field service technician capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Tractor Market |
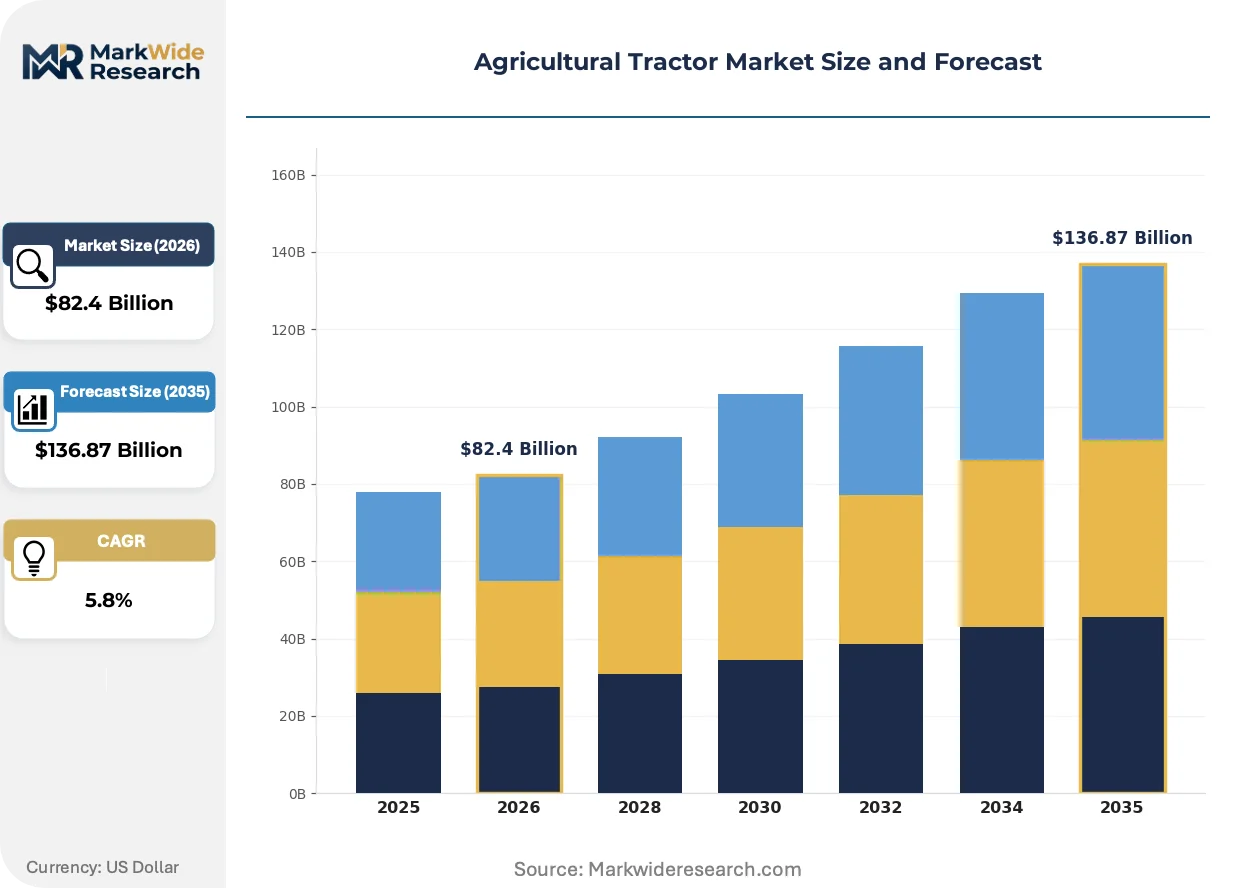
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $136.87 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Tractors, Utility Tractors, Row Crop Tractors, Orchard Tractors Application: Farming, Landscaping, Soil Preparation, Harvesting End User: Farmers, Agricultural Contractors, Cooperative Societies, Government Agencies Technology: GPS Guidance, Automated Steering, Electric Propulsion, Telemetry Systems |
| Companies Covered | John Deere, CNH Industrial, AGCO Corporation, Kubota Corporation, Mahindra & Mahindra, Claas Group, SDF Group, TurkTraktor, Yanmar Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Tractor Market Emerging Trajectories
Powertrain diversification and digital connectivity are converging to redefine tractor architecture and ownership economics. Manufacturers are repositioning around hardware-software integration rather than horsepower displacement alone.
Electric propulsion systems are electrifying the sub-100 horsepower utility segment through battery-electric and hybrid architectures designed for light tillage and material handling. European vineyard and orchard operators are piloting these platforms for their zero-emission compliance and reduced noise profiles. This transition is compressing the traditional diesel engine value chain while opening aftermarket opportunities for charging infrastructure and energy management services.
The European Commission's Stage V framework via its Non-Road Mobile Machinery regulation mandates real-driving emissions monitoring and onboard diagnostics, elevating software certification burdens alongside hardware compliance. Engine manufacturers must now validate control algorithms across variable load cycles, not just steady-state laboratory conditions. High-horsepower agricultural platforms face the steepest compliance cost escalation, accelerating consolidation among European OEMs with captive calibration capabilities.
Equipment-as-a-service contracting is displacing traditional ownership models among North American row-crop operators seeking to transfer residual value risk and maintenance liability to manufacturers. John Deere and CNH Industrial are expanding managed fleet programs that bundle hardware, telemetry, and seasonal uptime guarantees into per-acre pricing. This shift is most visible in the Corn Belt, where margin pressure and capital discipline favor operational expenditure over balance-sheet asset accumulation.
Agricultural Tractor Market Segmentation
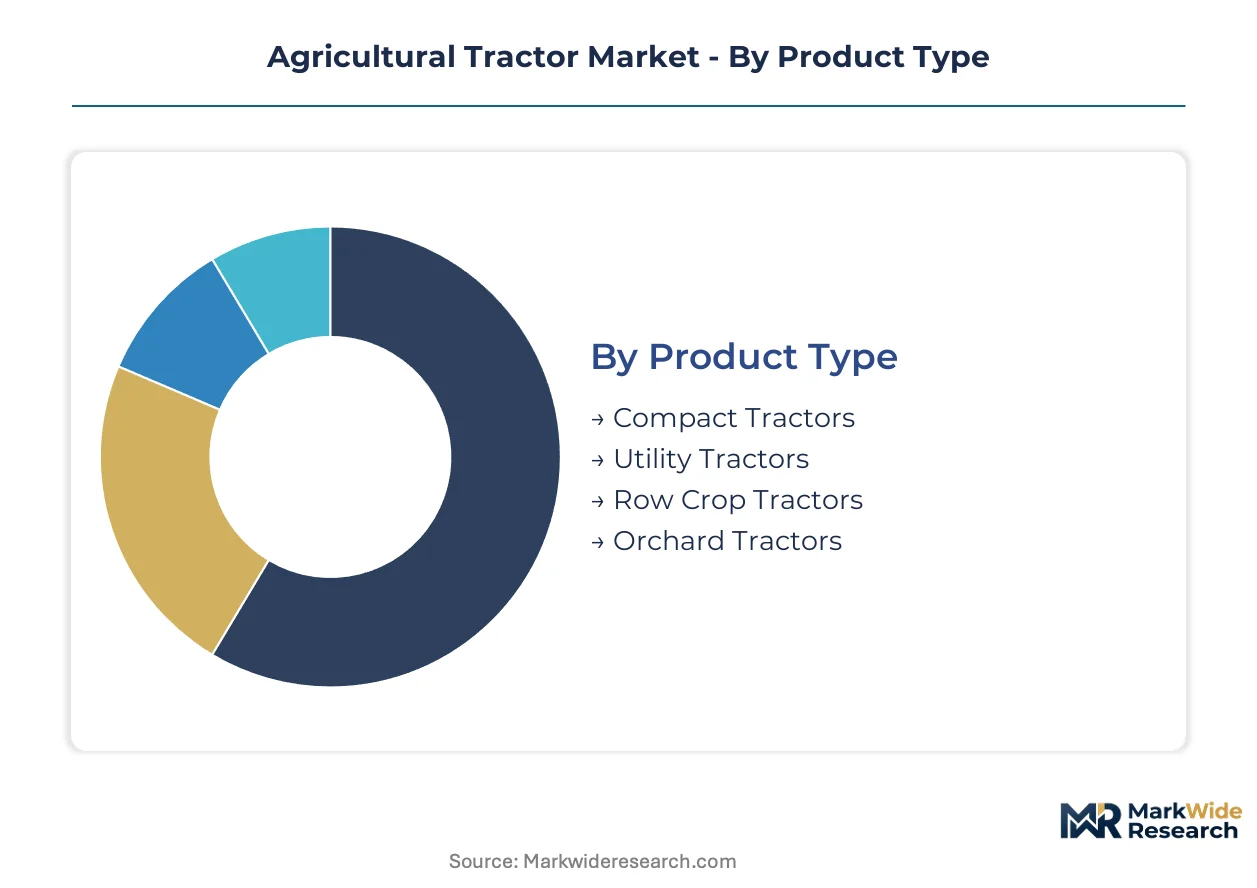
Tractor segmentation reveals divergent engineering priorities across horsepower bands and duty cycles. Product architecture, application intensity, and operator sophistication create distinct commercial territories with varying margin profiles and technology adoption rates.
Product Type:
Customization intensity spans from standardized mass-market platforms to specialized low-volume configurations engineered for confined spaces or premium crop handling.
- Utility Tractors:These 40-100 horsepower platforms balance draft capability with maneuverability for diversified operations. Demand concentrates in India's Punjab-Haryana belt where small-to-mid farms require flexible machines for tillage, planting, and transport. The segment locks in manufacturer commitment through Bharat Stage calibration requirements and localized financing structures.
- Row Crop Tractors:High-horsepower platforms exceeding 150 horsepower deliver sustained torque for heavy tillage and precision planting implements. Brazil's Mato Grosso soybean frontier generates concentrated demand as commercial operators maximize seasonal throughput windows. EPA Tier 4 Final and EU Stage V compliance costs escalate steeply in this bracket, favoring OEMs with captive engine manufacturing.
- Compact Tractors:Sub-40 horsepower units serve hobby farms and municipal maintenance with standardized diesel or emerging electric powertrains.
- Orchard Tractors:Narrow-profile designs with protective frames navigate vineyard and tree-fruit operations where clearance and crop safety override raw power metrics.
Leading the category by volume: Utility Tractors. Expanding most quickly: Row Crop Tractors.
Application:
Operational intensity and seasonal timing compress create divergent equipment utilization patterns across use cases.
- Farming:Core field operations including tillage, planting, cultivation, and transport account for the majority of tractor operating hours. Brazil and India drive volume as large-scale commercial operations expand mechanized fleets to replace animal and human labor.
- Soil Preparation:Primary and secondary tillage demand sustained high-torque output across variable soil conditions. Current lithium-ion energy density constraints limit electric platform viability here, preserving diesel dominance in heavy draft applications.
- Landscaping:Municipal parks, golf courses, and estate maintenance favor compact and utility platforms with attachment versatility.
- Harvesting:Trailer towing and in-field material handling require power take-off engagement and hydraulic capacity for implement coordination.
Dominant by equipment count: Farming. Steepest technology upgrade trajectory: Soil Preparation.
End User:
Capital access and technical sophistication stratify purchasing behavior across operator categories.
- Farmers:Owner-operators ranging from smallholders to commercial enterprises represent the foundational demand base. India's Central Pollution Control Board tightening of particulate thresholds compels localized engine calibration that shapes product availability.
- Agricultural Contractors:Custom service providers operating across multiple client properties prioritize uptime guarantees and rapid field service response. Equipment-as-a-service contracting models gain traction here as operators transfer residual value risk to manufacturers.
- Cooperative Societies:Pooled ownership structures in South Asian markets aggregate demand for shared utility platforms with simplified maintenance protocols.
- Government Agencies:Public procurement for demonstration farms, research stations, and subsidy programs favors standardized specifications with transparent pricing.
Largest installed base: Farmers. Fastest adoption of telemetry-enabled fleet management: Agricultural Contractors.
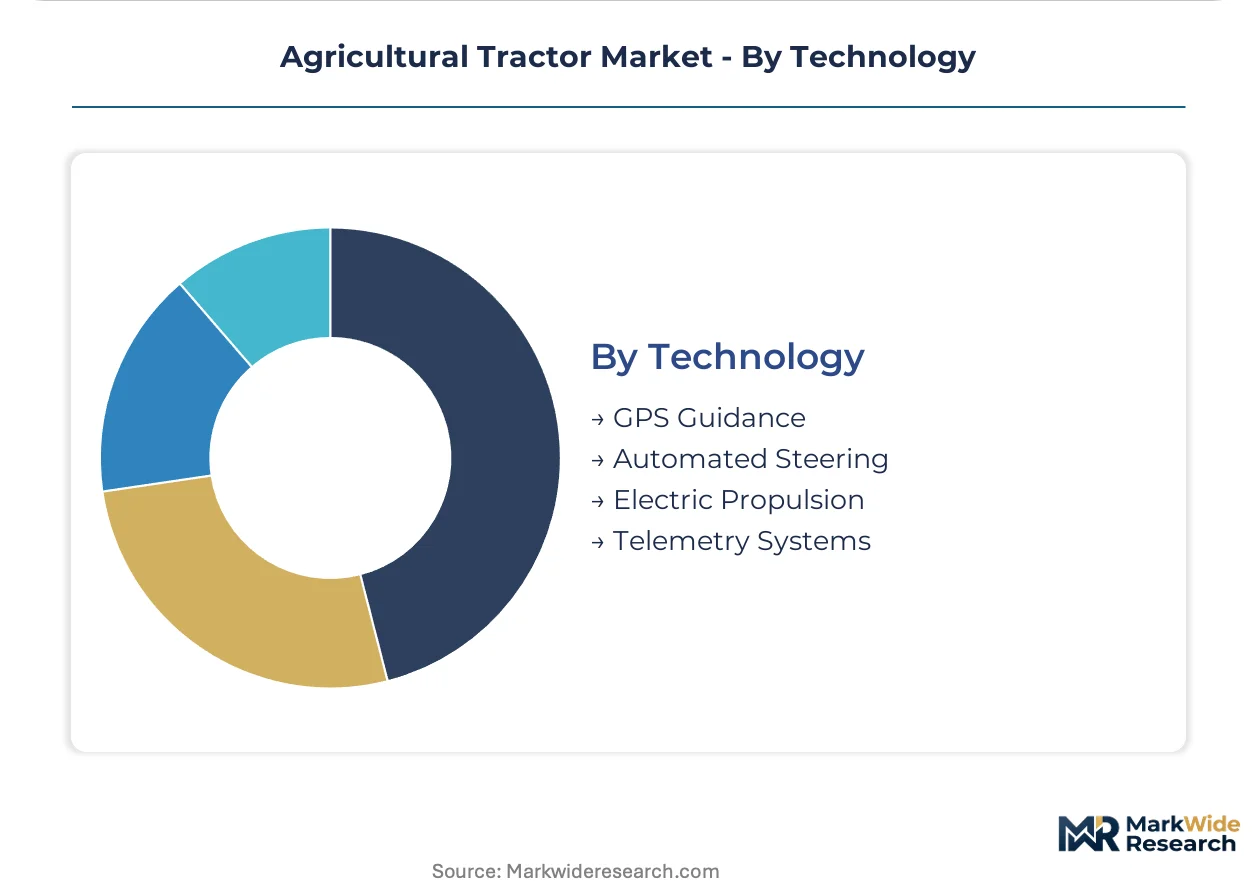
Technology:
Hardware-software integration intensity separates premium positioning from commodity volume.
- GPS Guidance:Satellite-based positioning enables sub-inch accuracy for planting and input application, reducing overlap and input waste. European vineyard operators pilot these systems alongside automated steering for zero-emission compliance.
- Automated Steering:Hands-free field operation reduces operator fatigue and extends daily productive hours during compressed seasonal windows. The European Commission's Stage V framework mandates onboard diagnostics that elevate software certification burdens alongside hardware compliance.
- Electric Propulsion:Battery-electric and hybrid architectures penetrate sub-100 horsepower utility segments for light tillage and material handling.
- Telemetry Systems:Machine connectivity enables predictive maintenance algorithms and remote diagnostics services creating recurring revenue streams.
Widest penetration: GPS Guidance. Climbing the fastest: Automated Steering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soybean belt soils and Indo-Gangetic alluvial plains anchor tractor demand geography. Diesel engine supply chains concentrate around these agricultural heartlands. Regulatory divergence between EPA Tier 4 Final, EU Stage V, and Bharat Stage norms fragments product availability across borders.
United States
Corn Belt operators drive replacement cycles for high-horsepower row crop platforms. EPA Tier 4 Final mandates compress emissions certification timelines for engine manufacturers. Illinois and Iowa field operations favor GPS-guided automated steering systems that maximize seasonal throughput during compressed planting windows.
Brazil
Mato Grosso's soybean frontier generates concentrated demand for 200+ horsepower tractors capable of heavy tillage across extended acreage. ANVISA coordinates with environmental regulators on agricultural machinery import standards. Campo Grande and Rondonópolis serve as equipment distribution hubs where commercial operators expand mechanized fleets to replace seasonal labor.
India
Punjab-Haryana belt smallholders convert from animal traction to 15-35 horsepower utility tractors. The Central Pollution Control Board tightens Bharat Stage particulate thresholds, compelling localized engine calibration. Ludhiana's manufacturing cluster supplies affordable platforms with simplified maintenance protocols for cooperative ownership structures.
Germany
Bavarian and Lower Saxony farms adopt precision agriculture hardware for vineyard and arable operations. The European Commission's Stage V framework mandates real-driving emissions monitoring through its Non-Road Mobile Machinery regulation. Munich-area OEMs integrate captive engine manufacturing to control certification timelines and software validation burdens.
China
Heilongjiang and Inner Mongolia state farms mechanize grain production at scale. MIIT oversees off-road diesel emissions standards that progressively align with international norms. Harbin equipment manufacturers blend domestic engine supply with licensed technology transfers for high-horsepower platforms serving northeastern corn and soybean belts.
Agricultural Tractor Market Vendor Landscape
Global majors compete with regional champions across emissions compliance capabilities and localized financing structures. Market structure tilts toward consolidated Tier 1 OEMs with captive powertrain manufacturing, while assembly-dependent competitors face margin compression from supplier consolidation. Three archetypes dominate: vertically integrated engine manufacturers, mixed-model assemblers blending in-house and outsourced supply, and regional specialists serving price-sensitive smallholder segments. Competitive moves concentrate on M&A for technology access and strategic partnerships for localized engine calibration.
Within the vertically integrated tier, Deere & Company and CNH Industrial occupy positions defined by captive engine manufacturing and controlled certification timelines. AGCO Corporation sits within a mixed-model archetype, blending in-house FPT Industrial supply with selective outsourcing for regional variants. Kubota Corporation anchors the compact and utility tractor specialist position, particularly in Asian and North American sub-100 horsepower segments where maneuverability commands premium positioning.
| Leading Market Players |
|---|
| John Deere |
| CNH Industrial |
| AGCO Corporation |
| Kubota Corporation |
| Mahindra & Mahindra |
| Claas Group |
| SDF Group |
| TurkTraktor |
| Yanmar Holdings |
| Others |
Supply Flow & Price Mechanics
EU Stage V emissions mandates gate qualified engine supply and premium-tier pricing access, compressing margins for assemblers lacking captive powertrain manufacturing while rewarding vertically integrated OEMs with controlled certification timelines and service-bundled positioning.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium tractor tiers from unbundled economy offerings. John Deere and CNH Industrial anchor premium-mid-economy pricing differentiation through multi-year uptime guarantees and telemetry-enabled service contracts, while price erosion runs through sub-100 horsepower utility segments where Mahindra and regional Indian manufacturers compete on capital cost alone. Fleet operators in Brazil's Mato Grosso soybean belt show least price sensitivity for high-horsepower platforms with precision agriculture integration, whereas Punjab-Haryana smallholders remain acutely cost-conscious on 15-35 horsepower utility purchases.
Supply Chain Analysis
Regional distribution centers in Campo Grande, Rondonópolis, and Ludhiana anchor hub-and-spoke patterns for equipment delivery and aftermarket parts. Diesel engine manufacturing concentrates in Germany, India, and the United States, with turbocharger and after-treatment component supply resting on Bosch, Cummins, and FPT Industrial networks. Single-source vulnerability escalates as OEMs consolidate supplier counts around emissions-certified volumes, forcing procurement concentration among fewer Tier 1 powertrain manufacturers. Distribution runs through manufacturer-owned dealerships in North America and Europe, while cooperative financing structures dominate South Asian last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive engine manufacturing and controlled emissions certification timelines determine margin sustainability across horsepower tiers.
For Market Incumbents: Lock in Bharat Stage and Stage V certification timelines through backward integration into engine manufacturing, eliminating supplier dependency risk that delays product launches. Expand captive calibration capabilities in Ludhiana and Munich-area facilities to compress validation cycles, defending against margin pressure from assembly-dependent competitors lacking in-house powertrain control.
For New Entrants and Emerging Players: Agricultural cooperative societies in India's underpenetrated smallholder belt offer the most penetrable entry vector, bypassing dealership infrastructure requirements through pooled ownership financing. Target 15-35 horsepower electric utility platforms for European vineyard pilots, where zero-emission compliance and noise restrictions create white-space demand unaddressed by incumbent diesel-heavy portfolios.
For Investors and Strategic Acquirers: OEM announcements of managed fleet program expansions serve as the leading indicator that equipment-as-a-service contracting is displacing traditional ownership economics, signaling long-term viability for telemetry-enabled business models. Acquire mixed-model assemblers with established FPT Industrial supply relationships and regional variant expertise, positioning for consolidation gains as emissions compliance costs accelerate captive manufacturing advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Engine Manufacturing Expansion | Controlled Tier 4 Final and Stage V certification timelines eliminate supplier dependency for high-horsepower platforms. |
| Telemetry-Enabled Fleet Management Launch | John Deere and CNH Industrial bundle hardware, predictive maintenance, and per-acre pricing into recurring revenue streams. |
| Electric Platform Pilot Programs | Battery-electric sub-100 horsepower tractors address EU Green Deal carbon reduction incentives in vineyard operations. |
| Regional Distribution Hub Consolidation | Campo Grande and Rondonópolis facilities compress delivery lead times for Brazil's Mato Grosso soybean frontier. |
| Cooperative Financing Partnerships | Mahindra and regional Indian manufacturers lock in Punjab-Haryana demand through pooled ownership structures. |
Methodological Framework
Multi-period observation of EPA Tier 4 Final and EU Stage V compliance timelines, Bharat Stage regulatory trajectories, and precision agriculture hardware penetration anchored the trend analysis, supplemented by interviews with tractor OEM procurement directors, diesel engine manufacturing plant managers, agricultural cooperative society administrators, and aftermarket service heads. Secondary validation drew from EPA certification filings, European Commission Non-Road Mobile Machinery registration databases, Indian Central Pollution Control Board emission test reports, and customs trade data on engine component imports. Bottom-up tractor shipment modeling by horsepower tier and application triangulated against top-down agricultural mechanization indices across Brazil, India, Germany, and the United States.
Input-output matrices mapped diesel engine supply capacity, after-treatment component availability, and regional financing penetration to tractor production forecasts across the projection horizon. Segmentation dimensions included horsepower band, propulsion architecture, precision agriculture technology tier, and end-user capital access profile. CAGRs were derived from regression analysis of historical mechanization rates against arable land expansion and labor cost trends, with specific weighting for GPS guidance adoption curves and electric platform pilot scale-up trajectories.
Caveats apply where battery energy density breakthroughs or alternative fuel regulatory subsidies could materially shift the outlook for diesel-dependent high-horsepower platforms. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Agricultural Machinery Market
Agricultural Machinery
Compact Tractor Market
Agricultural Machinery
Rice Mill Machine Market
Agricultural Machinery
United Kingdom Agricultural Machinery Market
Agricultural Machinery
Autonomous Farm Equipment Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Tiller Machine Market
Agricultural Machinery
Australia Agricultural Machinery Market
Agricultural Machinery
Milking Robots Market
Agricultural Machinery
Garden and Orchard Tractors Market
Agricultural Machinery
Autonomous Agricultural Machinery Market
Agricultural Machinery
Orchard Tractor Market
Agricultural Machinery
Electric Farm Tractor Market
Agricultural Machinery
Vietnam Agricultural Tractor Market
Agricultural Machinery
Two-Wheeler Tractors Market
Agricultural Machinery
North America Agricultural Tractors Market