
 Europe Agricultural Sprayer Market | 2026-2036
Europe Agricultural Sprayer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Agricultural Sprayer Market Foresight
Capital-intensity divergence between precision-ready and conventional manufacturers is rotating competitive advantage toward firms with embedded sensor development. Deere & Company leverages its autonomous guidance stack to command premium positioning in self-propelled systems. Hardi International A/S anchors Nordic distribution through dealer networks purpose-built for cooperative procurement. Kuhn Group sustains manufacturing scale across multiple product tiers without fragmenting quality systems.
An agricultural sprayer is a field machine engineered to distribute crop protection chemicals, liquid fertilizers, or biological agents through pressurized boom assemblies, pump systems, and nozzle arrays calibrated to droplet spectra measured in microns. Its primary commercial purpose is to maximize chemical efficacy while minimizing off-target drift and input waste across variable terrain. Self-propelled units capture the dominant margin pool where farm scale justifies dedicated machinery, while tractor-mounted systems retain volume leadership among mid-sized European operations. Precision technology segments expand fastest as variable-rate application and GPS-section control become baseline specifications rather than upgrades.
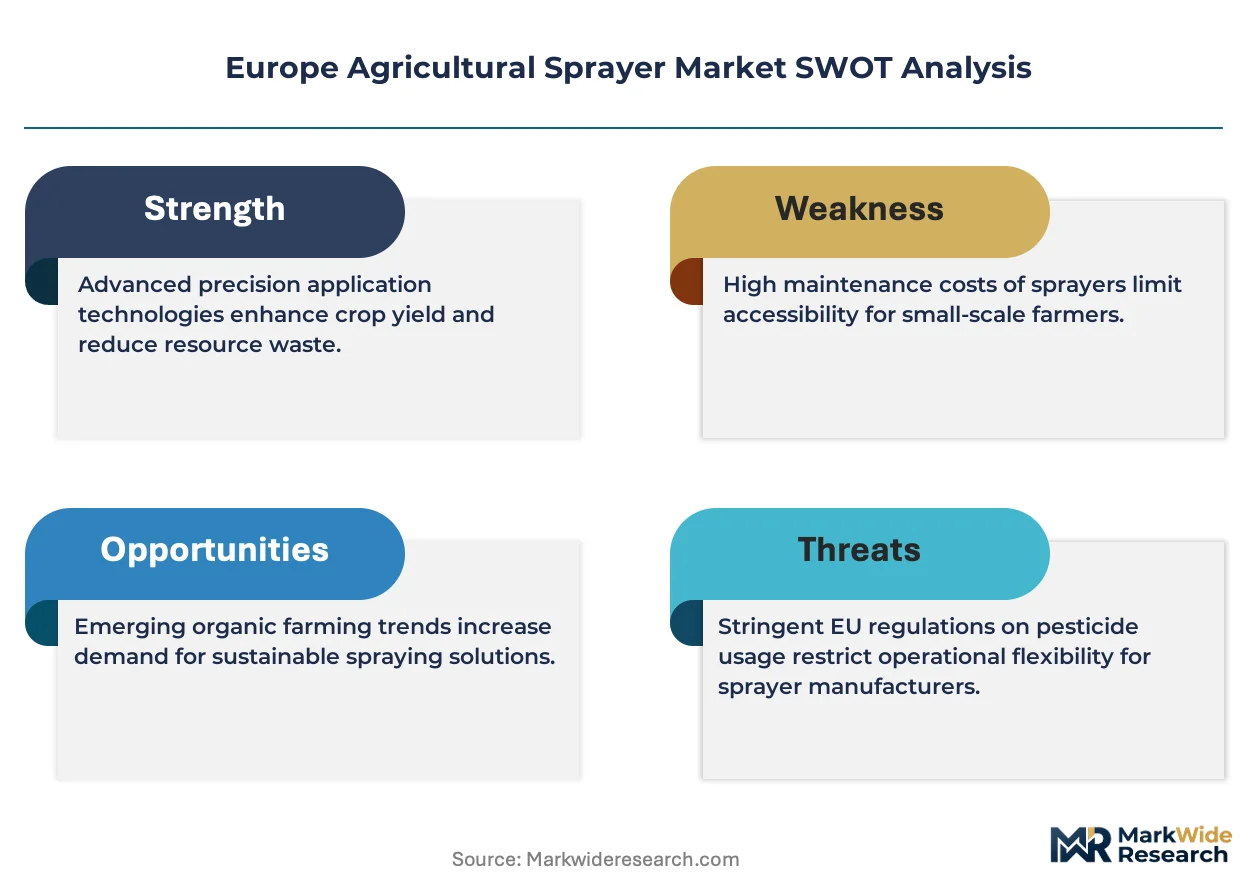
The EU Green Deal and F-Gas Regulation constrain active ingredient availability, compelling sprayer makers to engineer finer droplet control and lower-volume application systems. ECHA chemical reviews under REACH directly shape nozzle design standards and tank-mix compatibility requirements. CE marking and the Machinery Directive govern structural safety and electromagnetic compatibility for autonomous navigation features. Stakeholders must monitor how the EU AI Act classification rules will treat algorithmic boom control and path-planning software in field equipment.
Market Dynamics
EU Green Deal residue-limit protocols are compressing application windows and forcing sprayer replacement cycles across European arable and specialty crop sectors. Machinery investment decisions now hinge on precision droplet control capabilities rather than tank capacity or boom width alone.
Growth Catalysts
- Variable-rate application technology:GPS-section control and prescription mapping enable input savings of 15-25% on nitrogen and crop protection chemicals. German arable farms above 500 hectares deploy these systems as baseline specifications.
- Poland's cooperative consolidation:Farm machinery purchasing pools aggregate demand for self-propelled units previously concentrated in Western Europe. Mechanization gaps against French and German productivity benchmarks drive fleet expansion.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases accelerate adoption of electric pump systems and alternative pressurization technologies in new sprayer designs.
Market Restraints
- Steel and aluminum input volatility:Boom assembly fabrication depends on commodity metals whose price swings compress manufacturing margins and delay fleet renewal decisions among price-sensitive buyers.
- Hydraulic component supply concentration:Precision nozzle actuators and pump systems source from concentrated German and Italian supplier bases, creating vulnerability to single-source disruptions.
- REACH chemical review uncertainty:ECHA substance evaluations under ongoing regulatory reviews destabilize tank-mix compatibility planning and sprayer specification commitments across multiple active ingredient categories.
Strategic Opportunities
- Romanian and Bulgarian farm scale-up:Land consolidation in these accession states creates first-time demand for tractor-mounted boom sprayers as holdings shift from subsistence to commercial operation.
- Drone-based spot spraying convergence:Integration of unmanned aerial systems with ground-based fleet management platforms offers hybrid application models for vineyard and orchard geometries.
- EU AI Act algorithmic classification:Anticipated regulatory clarity on autonomous path-planning software creates compliance-first positioning for manufacturers with embedded sensor development capabilities.
Industry Challenges
- Precision agriculture technician scarcity:Calibration of micron-level droplet spectra and ISOBUS protocol troubleshooting require skills absent from traditional farm machinery repair networks.
- CE marking timeline compression:Machinery Directive conformity assessment for autonomous navigation features extends certification cycles beyond traditional 12-month product development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Agricultural Sprayer Market |
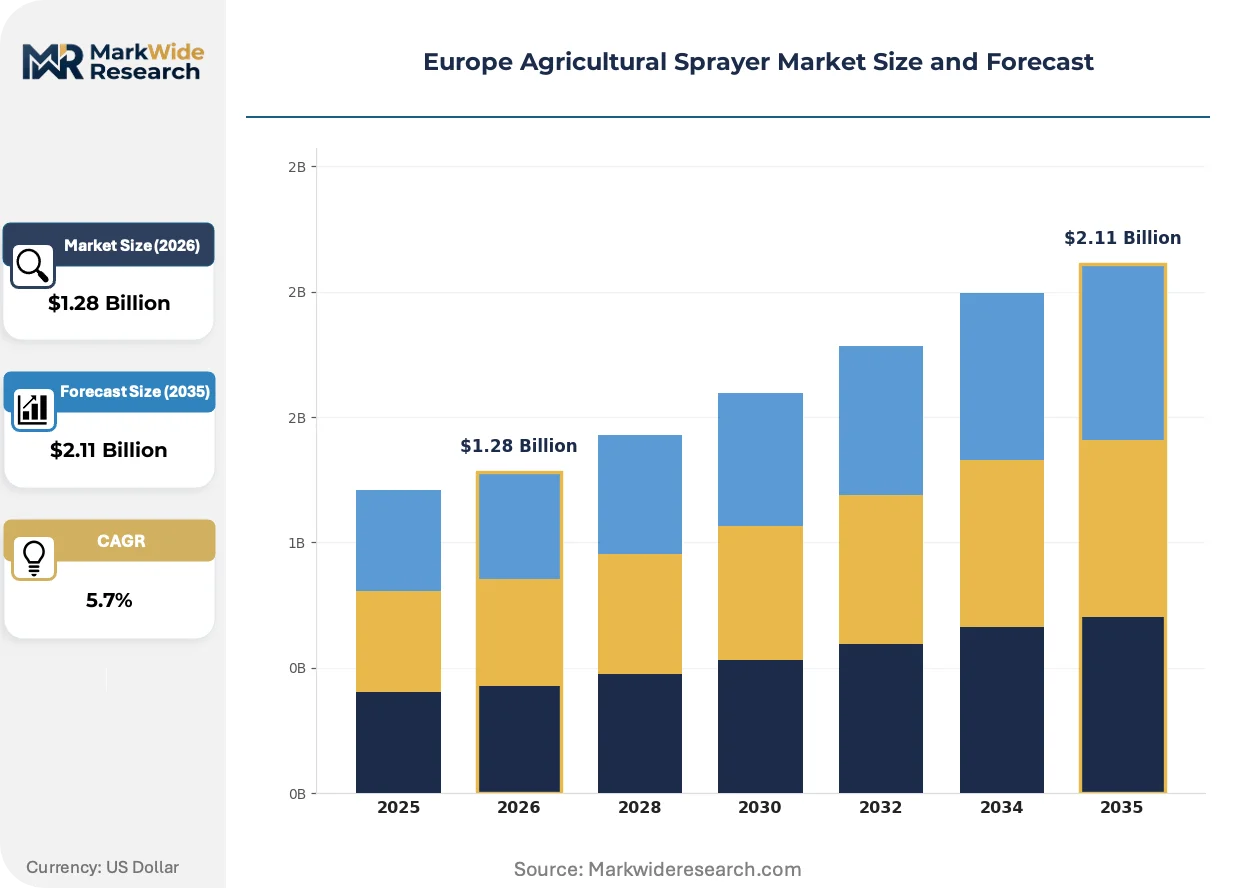
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.11 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractor-Mounted, Self-Propelled, Tow-Behind, Handheld Application: Crop Protection, Fertilization, Pest Control, Soil Treatment End User: Farmers, Agricultural Cooperatives, Commercial Growers, Research Institutions Technology: Conventional, Precision, Autonomous, Hybrid |
| Companies Covered | Deere & Company, KFMR Krukowiak, Hardi International A/S, Agrifac Machinery B.V., BGROUP SpA, Kuhn Group, Herbert Dammann GmbH, Amazonen-Werke, Exel Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Agricultural Sprayer Market Shifts & Advancements
Electrification of pressurization systems and algorithmic boom control are redefining sprayer architecture. Equipment specifications increasingly prioritize data integration over mechanical durability metrics.
Pulse-width modulation nozzle technology is fragmenting conventional fixed-orifice designs. French vineyard operators adopt these systems for targeted fungicide application in narrow row geometries. The technology enables real-time droplet size adjustment but fragments service and parts compatibility across manufacturer ecosystems.
EU AI Act classification rules for agricultural field equipment remain in draft consultation. Algorithmic boom height control and obstacle detection systems face uncertain conformity assessment pathways. German manufacturers delay autonomous feature rollouts pending ECHA coordination with machinery safety regulators on combined compliance obligations.
Cooperative procurement platforms now aggregate sprayer demand across multiple farm holdings. Poland's machinery purchasing pools negotiate fleet-scale discounts previously reserved for individual large estates. Channel intermediaries face margin compression as direct manufacturer-cooperative relationships displace traditional dealer networks in volume transactions.
Europe Agricultural Sprayer Market Segmentation
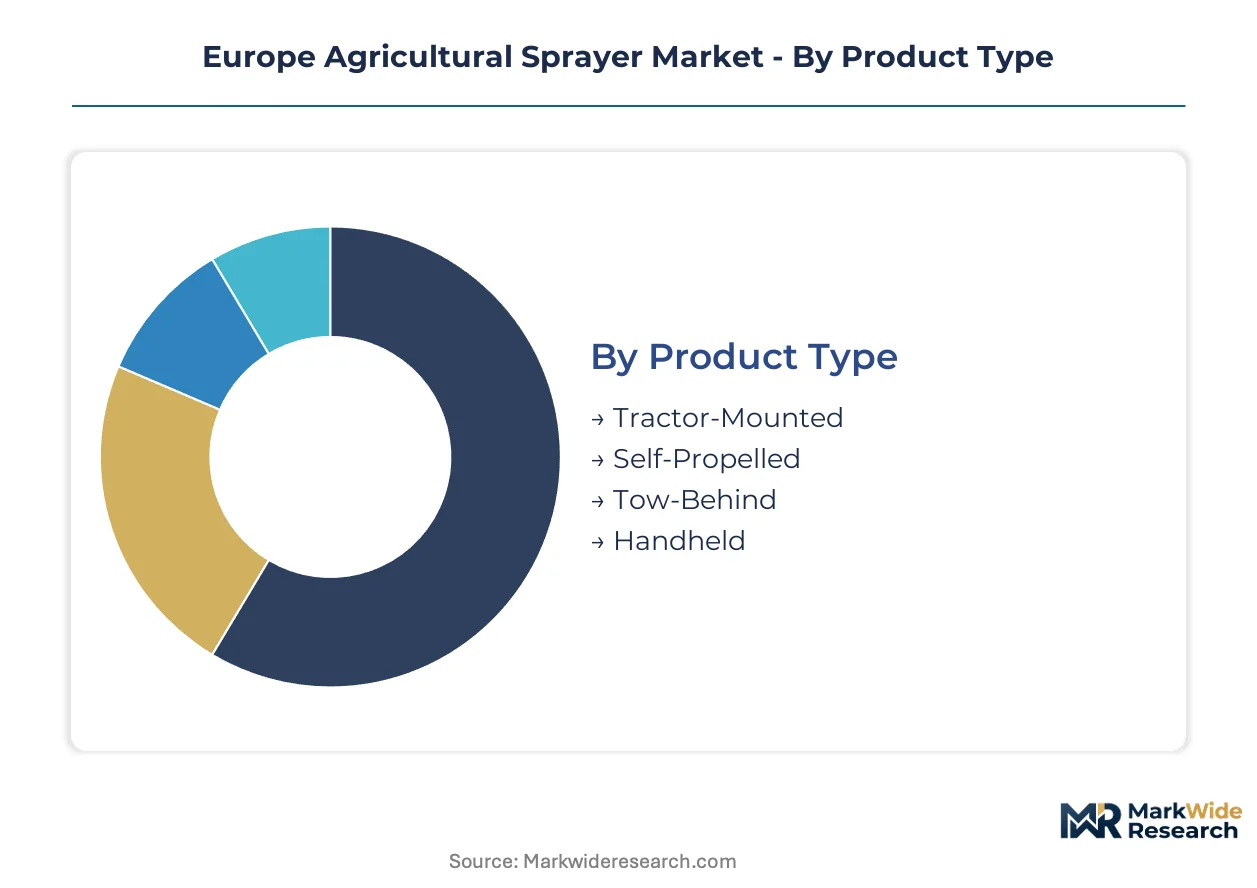
Segmentation in the Europe Agricultural Sprayer Market reveals how margin pools concentrate around precision-enabled equipment and self-propelled systems. Farm scale and regulatory compliance requirements fragment demand across four distinct dimensions.
Product Type:
Margin pools sit heaviest in self-propelled systems where dedicated chassis engineering and autonomous integration command premium positioning.
- Self-Propelled:Dedicated chassis designs integrate GPS guidance, boom suspension, and variable-rate pumps as factory-standard configurations. German arable operations above 500 hectares specify these systems to meet EU Green Deal residue protocols while minimizing soil compaction from tractor passes.
- Tractor-Mounted:Three-point hitch assemblies with PTO-driven pumps dominate mid-sized Polish and Romanian holdings where capital constraints limit dedicated machinery investment. Cooperatives in Poland's consolidating sector aggregate demand for ISOBUS-compatible units that integrate with existing tractor fleets.
- Tow-Behind:Trailed tank-and-boom configurations serve specialty crop operators in France and Spain with lower annual application intensity.
- Handheld:Backpack and knapsack units address vineyard terrains and smallholder plots inaccessible to mechanized equipment.
Self-propelled systems hold installed capacity in Western European arable belts. Tractor-mounted configurations are rotating up the share rankings as Poland's cooperative sector mechanizes.
Application:
Application segmentation tracks how chemical regulation reshapes equipment specification priorities across end-use cases.
- Crop Protection:Fungicide, herbicide, and insecticide distribution demands micron-level droplet calibration and drift mitigation systems. French vineyard operators under ECHA residue-limit pressure specify pulse-width modulation nozzles for targeted fungicide application in narrow row geometries.
- Fertilization:Liquid nitrogen and micronutrient application requires corrosion-resistant tank materials and variable-rate injection systems. German farms deploy GPS-section control to achieve input savings on nitrogen while maintaining yield targets.
- Pest Control:Vector and invasive species management drives demand for ultra-low volume application systems in Mediterranean specialty crops.
- Soil Treatment:Pre-plant herbicide incorporation and biological amendment distribution favors high-clearance boom configurations.
Crop protection commands the deepest installed base. Fertilization is climbing the fastest as nitrogen efficiency regulations tighten across EU member states.
End User:
Customer-type segmentation exposes how procurement concentration is restructuring distribution channels.
- Agricultural Cooperatives:Machinery purchasing pools in Poland aggregate demand for fleet-scale sprayer acquisitions, negotiating direct manufacturer relationships that displace traditional dealer intermediaries. These entities specify ISOBUS compatibility and telematics integration as baseline requirements.
- Commercial Growers:Large-scale specialty crop operations in Spain and Italy demand precision application technology to meet export-market residue protocols under EU Green Deal targets.
- Farmers:Individual holdings below 200 hectares retain tractor-mounted system preference where capital recovery periods stretch replacement cycles.
- Research Institutions:Trial plot application requires sub-meter accuracy and replicated treatment capabilities for field experiment protocols.
Commercial growers hold the deepest precision technology penetration. Agricultural cooperatives are gaining share fastest as Eastern European land consolidation accelerates.
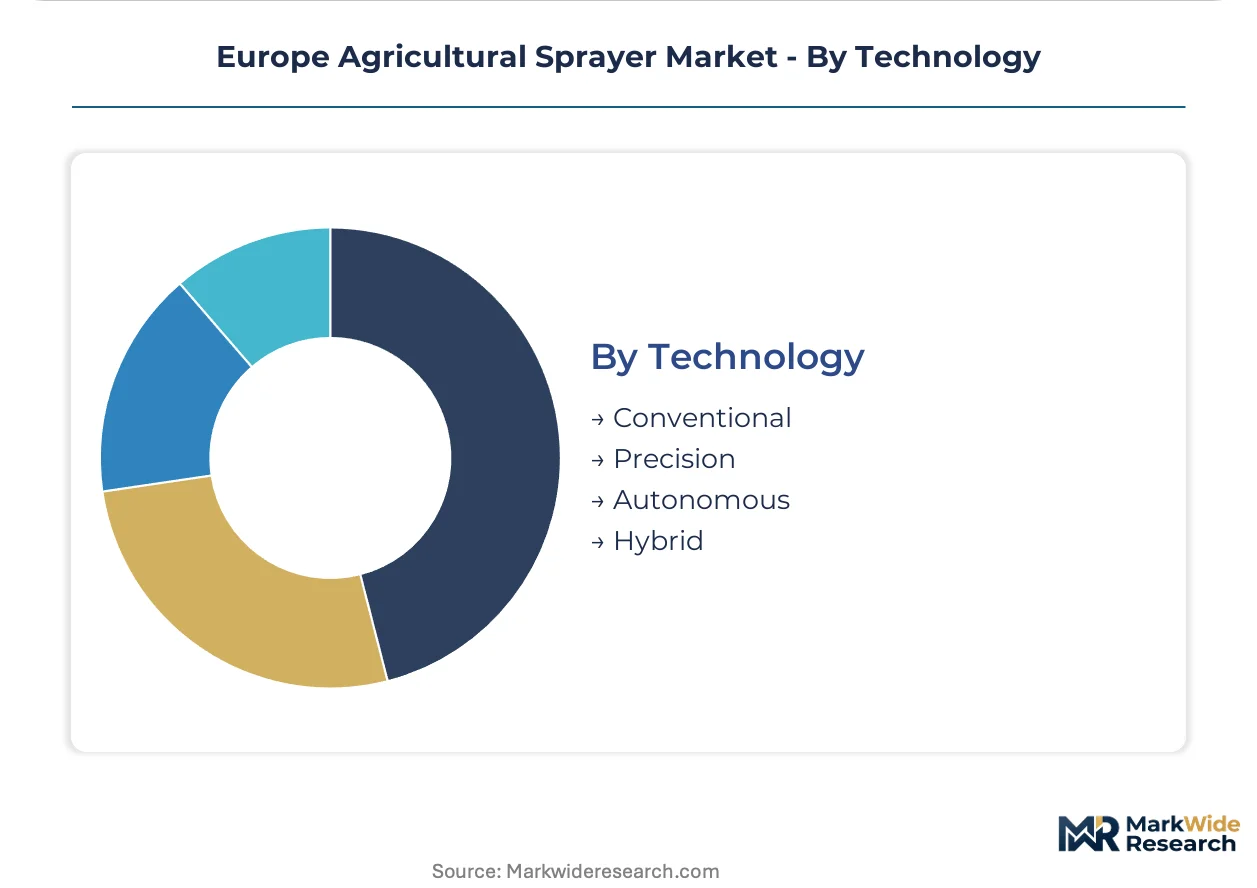
Technology:
Technology tiers map the displacement of mechanical specifications by data integration and algorithmic control capabilities.
- Precision:GPS-section control, prescription mapping, and real-time droplet size adjustment define this tier. Variable-rate application enables input savings of 15-25% on crop protection chemicals and nitrogen, with German operations deploying these systems as default specifications.
- Autonomous:Algorithmic boom height control, obstacle detection, and path-planning software face uncertain EU AI Act classification timelines. German manufacturers delay feature rollouts pending ECHA coordination with machinery safety regulators on combined compliance obligations.
- Conventional:Fixed-orifice nozzles and manual rate control retain volume presence in price-sensitive Romanian and Bulgarian markets where first-time mechanization precedes precision upgrade cycles.
- Hybrid:Partial automation packages combine GPS guidance with operator-retained boom control for transitional technology adoption.
Conventional systems hold installed capacity in accession state markets. Precision configurations are rotating up the share rankings as EU regulatory pressure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented machinery flows from Germany and France contrast with import dependence in Poland and Romania. Western European manufacturers ship precision-enabled systems eastward while Eastern European cooperatives absorb capacity. Intra-regional trade patterns concentrate high-value production in the Rhine-Ruhr and northern Italian industrial belts.
Germany
Arable operations above 500 hectares deploy GPS-section control as baseline specifications. The EU AI Act classification timeline delays autonomous feature rollouts pending ECHA coordination with machinery safety regulators. Stuttgart and Munich anchor development clusters where algorithmic boom control systems undergo pre-certification testing.
Poland
Machinery purchasing pools aggregate demand for self-propelled units previously concentrated in Western Europe. EU Green Deal residue protocols compress application windows across the country's consolidating farm sector. The Greater Poland Voivodeship hosts cooperative procurement platforms negotiating direct manufacturer relationships.
France
Specialty crop growers expand sprayer fleets to meet residue-limit protocols under EU F-Gas Regulation phase-down targets. ECHA chemical reviews under REACH reshape nozzle design standards for vineyard fungicide applications. The Champagne-Ardenne region concentrates pulse-width modulation adoption for narrow row geometries.
Spain
Commercial growers demand precision application technology to meet export-market residue protocols. CE marking and Machinery Directive compliance costs extend certification cycles for autonomous navigation features. Andalusia's olive cooperatives mechanize to match French and German productivity benchmarks.
Italy
Trailed tank-and-boom configurations serve specialty crop operators with lower annual application intensity. REACH substance evaluations destabilize tank-mix compatibility planning across multiple active ingredient categories. The Emilia-Romagna machinery district fabricates boom assemblies for German and French OEM supply chains.
Europe Agricultural Sprayer Market Competitive Landscape
Concentration sits with diversified agricultural machinery conglomerates and specialized sprayer fabricators. The vendor base spans three tiers: integrated equipment manufacturers with autonomous guidance stacks, dedicated sprayer specialists with regional distribution depth, and component suppliers scaling across multiple OEM relationships. Strategic moves center on sensor development capabilities and cooperative procurement channel access.
Among diversified machinery manufacturers, Deere & Company and Kuhn Group occupy positions defined by manufacturing scale across product tiers. Hardi International A/S represents the specialist archetype with Nordic distribution infrastructure. KFMR Krukowiak exemplifies regional fabricators serving Eastern European cooperative demand. These entities anchor competitive positioning around precision technology integration and regulatory compliance capabilities rather than mechanical specifications alone.
| Leading Market Players |
|---|
| Deere & Company |
| KFMR Krukowiak |
| Hardi International A/S |
| Agrifac Machinery B.V. |
| BGROUP SpA |
| Kuhn Group |
| Herbert Dammann GmbH |
| Amazonen-Werke |
| Exel Industries |
| Others |
Supply & Pricing Matrix
Electric pump system substitution for hydraulic pressurization simultaneously shifts component sourcing toward German and Italian electromechanical clusters and compresses pricing premiums on conventional pump assemblies. This dual restructuring rewards suppliers with embedded motor-control engineering while eroding margins on legacy hydraulic tier suppliers serving price-sensitive Eastern European cooperatives.
Pricing Analysis
The customization-premium spread between ISOBUS-compatible precision configurations and basic tractor-mounted units spans approximately three performance tiers. Pricing stratifies across premium autonomous-ready systems, mid-tier GPS-section control units, and economy conventional boom sprayers with fixed-orifice nozzles. Cost compression in the economy tier intensifies because Polish cooperative procurement pools aggregate volume and squeeze dealer margins. Commercial growers in France and Spain exhibit the lowest price sensitivity, prioritizing pulse-width modulation and telemetry integration over acquisition cost.
Supply Chain Analysis
Boom assembly fabrication chokepoints concentrate in the Rhine-Ruhr industrial belt and northern Italian machinery districts. Precision nozzle actuators and pump systems draw from concentrated German and Italian supplier bases, creating single-source vulnerability for tier-one OEMs. Steel and aluminum input volatility from commodity markets feeds through to manufacturing margins, delaying fleet renewal commitments. Distribution runs through cooperative procurement platforms in Poland that negotiate direct manufacturer relationships, displacing traditional dealer networks in volume transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone-based spot spraying convergence threatens ground-based sprayer incumbents with hybrid application models, forcing defensive positioning around fleet integration software and data platform control.
For Market Incumbents: Shield installed base relationships by embedding telematics platforms that lock cooperative customers into multi-year service contracts. Prioritize backward integration into sensor development to maintain algorithmic boom control differentiation as EU AI Act classification rules crystallize. Acquire specialist nozzle engineering capabilities before autonomous path-planning software commoditizes hardware margins. For New Entrants and Emerging Players: Differentiate on ISOBUS protocol specialization and aftermarket calibration services where incumbent dealer networks lack precision agriculture technician density. Target Romania and Bulgaria's first-time mechanization wave with tractor-mounted boom sprayers priced below Western European precision tiers. Pursue cooperative procurement channel partnerships that bypass established dealer infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision agriculture technology rollups consolidating regional nozzle and sensor specialists. Five-to-ten year viability hinges on regulatory compliance capability depth rather than manufacturing scale alone. Monitor ECHA substance evaluation timelines as inflection indicators for tank-mix compatibility-driven sprayer replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Development Acquisition | Algorithmic boom control differentiation depends on captive droplet spectrum calibration capabilities under REACH protocols. |
| Cooperative Procurement Partnership | Direct manufacturer relationships with Polish purchasing pools displace dealer intermediaries and secure volume commitments. |
| Electric Pump System Transition | F-Gas Regulation phase-down mandates electromechanical pressurization engineering that German and Italian suppliers dominate. |
| Telematics Platform Rollout | Fleet-scale data integration locks Eastern European cooperatives into recurring service revenue beyond hardware margins. |
| CE Marking Pre-Certification Investment | Machinery Directive conformity assessment for autonomous navigation features extends development cycles beyond traditional windows. |
Research Methodology
Cross-validation between OEM procurement director interviews and cooperative machinery manager surveys anchors the qualitative findings on purchasing decision criteria. Primary fieldwork engaged sprayer manufacturer product managers, precision agriculture service technicians, ECHA regulatory affairs consultants, and Polish cooperative board members. Secondary validation drew from EU Machinery Directive implementation guidance, ECHA substance evaluation databases, CE marking conformity assessment records, and customs trade flow data for agricultural machinery. Bottom-up demand aggregation across farm size strata and top-down supply capacity verification triangulate market sizing.
Sensitivity analysis tested forecast robustness across variable commodity metal price scenarios and regulatory implementation timing assumptions. The analytical framework segments by product type, application, end user, and technology tier across the projection horizon. CAGRs derive from installed base replacement cycle modeling and mechanization gap closure rates in accession states. Industry-specific inputs include EU Green Deal residue protocol compliance deadlines and F-Gas Regulation phase-down schedules.
Material uncertainties — ECHA substance evaluation outcomes, EU AI Act final classification rules, and commodity metal price volatility — sit outside the modeled envelope. Forecasts reflect assumptions about cooperative consolidation velocity and precision technology adoption curves. Practitioners should keep alternative scenarios live as regulatory coordination between ECHA and machinery safety authorities evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Japan Agricultural Machinery Market
Agricultural Machinery
Rice Mill Machine Market
Agricultural Machinery
Europe Agricultural Tractors Market
Agricultural Machinery
Germany Agricultural Machinery Market
Agricultural Machinery
Global Agricultural Sprayer Market
Agricultural Machinery
Cambodia Agricultural Machinery Market
Agricultural Machinery
United Kingdom Agricultural Machinery Market
Agricultural Machinery
Two Wheel Walking Tractor Market
Agricultural Machinery
Forestry Machinery Market
Agricultural Machinery
Agricultural Forestry Machinery Market
Agricultural Machinery
Argentina Agricultural Machinery Market
Agricultural Machinery
Italy Agricultural Machinery Market
Agricultural Machinery
United States Agricultural Tractor Market
Agricultural Machinery
Electric Tractors Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Cow Milking Machine Market