
 Agricultural Machinery Market | 2026-2036
Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Machinery Market Analysis
The dealer-to-farmer direct sales channel is narrowing as manufacturers build digital platforms and captive financing arms. John Deere leverages its proprietary Operations Center to lock in recurring software revenue alongside hardware sales. AGCO Corporation sustains broad geographic coverage through its Challenger, Fendt, and Massey Ferguson brand architecture. Kubota Corporation anchors its position in compact tractors and rice-farming equipment across Asian markets.
Agricultural machinery encompasses powered and towed equipment designed for soil cultivation, planting, harvesting, and crop management, typically featuring diesel engines rated from 25 to 600 horsepower and precision guidance systems with sub-inch accuracy. Its primary purpose is to replace manual labor, compress seasonal windows, and optimize input application across large landholdings. Tractors occupy the largest revenue pool given their role as universal platform vehicles, while autonomous machinery represents the fastest-expanding technology segment as labor costs rise and 24-hour operational windows become economically viable. Harvesters command premium pricing due to seasonal utilization intensity and complex threshing mechanisms.
EPA Tier 4 Final and EU Stage V emissions frameworks are forcing engine redesigns and after-treatment adoption, raising manufacturing costs but also creating replacement cycles for pre-compliant fleets. The USDA conservation programs and India's FAME-II subsidies for farm mechanization are redirecting procurement toward cleaner, more efficient equipment platforms. Stakeholders must weigh capital allocation between autonomous development and aftermarket service infrastructure as ownership models fragment across ownership, leasing, and robotics-as-a-service contracts.
Market Dynamics
The agricultural machinery sector faces a structural squeeze between EPA Tier 4 Final and EU Stage V compliance costs and the operational imperative to automate labor-intensive field operations before seasonal windows close.
Growth Catalysts
- Precision guidance systems:Sub-inch accuracy GPS and RTK correction networks enable variable-rate input application, cutting fertilizer waste and seed overplanting on large commercial farms.
- FAME-II subsidies:India's farm mechanization incentives redirect procurement toward cleaner diesel and electric platforms, accelerating fleet turnover in rice-wheat belts.
- 24-hour operational windows:Autonomous machinery eliminates operator fatigue constraints, compressing planting and harvest cycles in regions with narrow weather windows like the Canadian prairies.
Market Restraints
- After-treatment cost burden:Diesel particulate filters and selective catalytic reduction systems add manufacturing cost layers that squeeze margin on sub-100 horsepower equipment.
- Steel and rare earth volatility:Input cost swings for permanent magnets and high-strength alloys destabilize pricing for electric drivetrain components.
- Dealer network concentration:North American parts and service infrastructure clusters around legacy brands, creating switching friction for autonomous entrants.
Strategic Opportunities
- Robotics-as-a-service models:Pay-per-acre contracting eliminates upfront capital barriers for mid-size Brazilian soybean operations.
- Electrification of compact tractors:Battery platforms under 75 horsepower exploit shorter duty cycles and overnight charging windows in European horticulture.
- Carbon credit monetization:USDA conservation programs and EU Green Deal farm subsidies reward precision application that cuts nitrous oxide emissions.
Industry Challenges
- Autonomous systems integration:Retrofitting legacy hydraulic implements with ISOBUS 11783 compatibility demands scarce mechatronics talent.
- Homologation timeline compression:EU Stage V type-approval and EPA certification cycles now run parallel to product development, stretching engineering bandwidth.
- Data sovereignty architecture:Farmers resist cloud-based telemetry without clear ownership frameworks for yield maps and soil sensor data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Machinery Market |
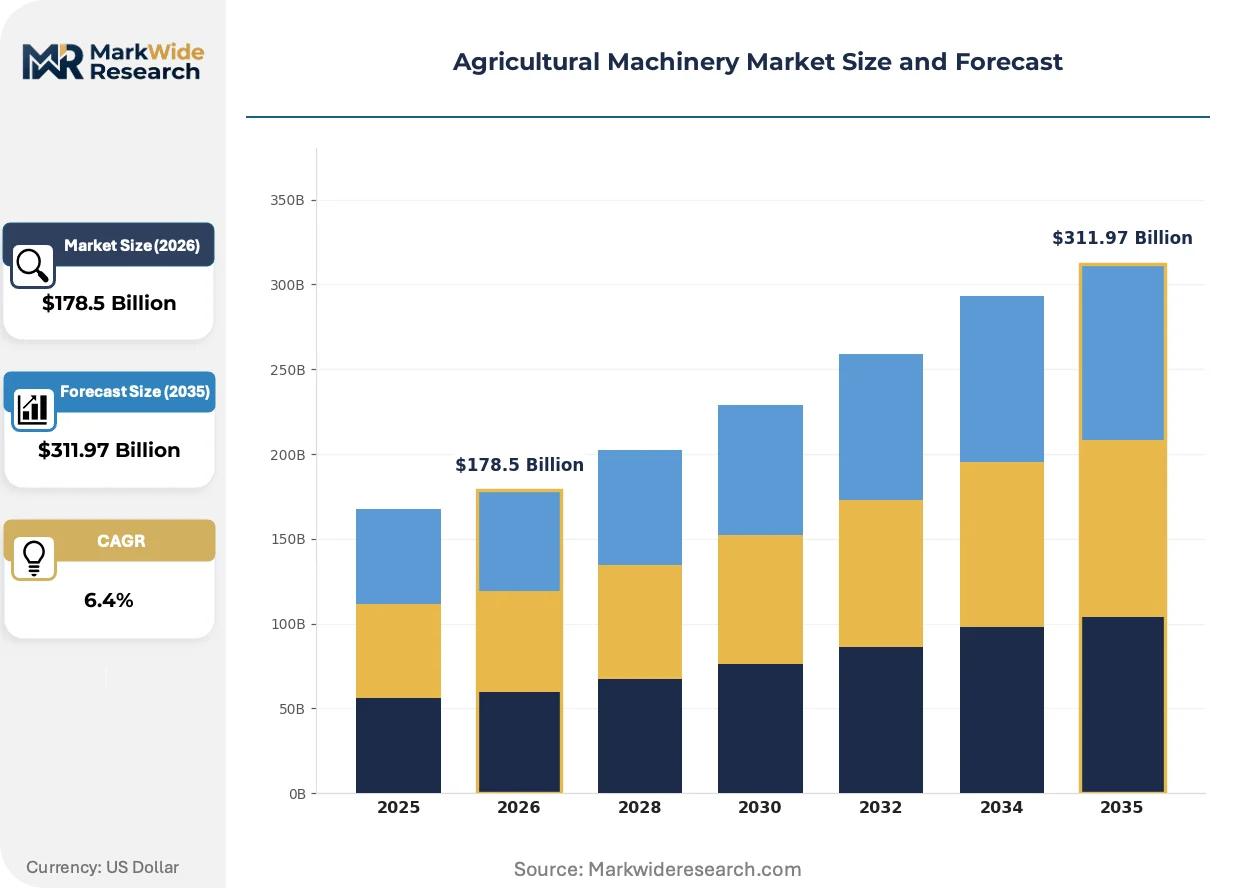
| Market Size in 2026 | $178.5 Billion |
| Market Size in 2035 | $311.97 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Plows, Harvesters, Seeders Technology: Precision Farming, Autonomous Machinery, Smart Irrigation, Drones Application: Crop Production, Soil Preparation, Pest Control, Irrigation End User: Farmers, Agricultural Cooperatives, Horticulturists, Agricultural Contractors |
| Companies Covered | Claas, Mahindra & Mahindra, John Deere, New Holland, Case IH, AGCO Corporation, Kubota Corporation, Fendt, CNH Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Machinery Market Emerging Trajectories
Three forces are actively restructuring competitive advantage: autonomy collapsing the operator-in-the-loop model, emissions regulations forcing engine architecture reinvention, and financing innovation fragmenting traditional ownership patterns.
Autonomous swarming technology is collapsing the economics of single large tractor deployment. Small electric units operating in coordinated fleets replace 300-horsepower platforms for tillage and seeding operations. Large grain operations in Australia and the US Midwest are piloting these configurations to eliminate labor recruitment risk during compressed planting windows.
EU Stage V and EPA Tier 4 Final are forcing parallel development tracks for diesel after-treatment and battery-electric powertrains. Manufacturers must maintain dual engineering competencies while aftertreatment suppliers consolidate. The 150-300 horsepower tractor segment bears the heaviest compliance burden as it serves both regulated European markets and cost-sensitive developing economies.
Captive financing arms are displacing independent agricultural credit channels. Manufacturers now bundle equipment, software subscriptions, and seasonal operating loans into unified contracts. This bundling is most advanced in Brazil and Germany, where interest rate sensitivity and seasonal cash flow volatility make integrated financing decisive in procurement decisions.
Agricultural Machinery Market Segmentation
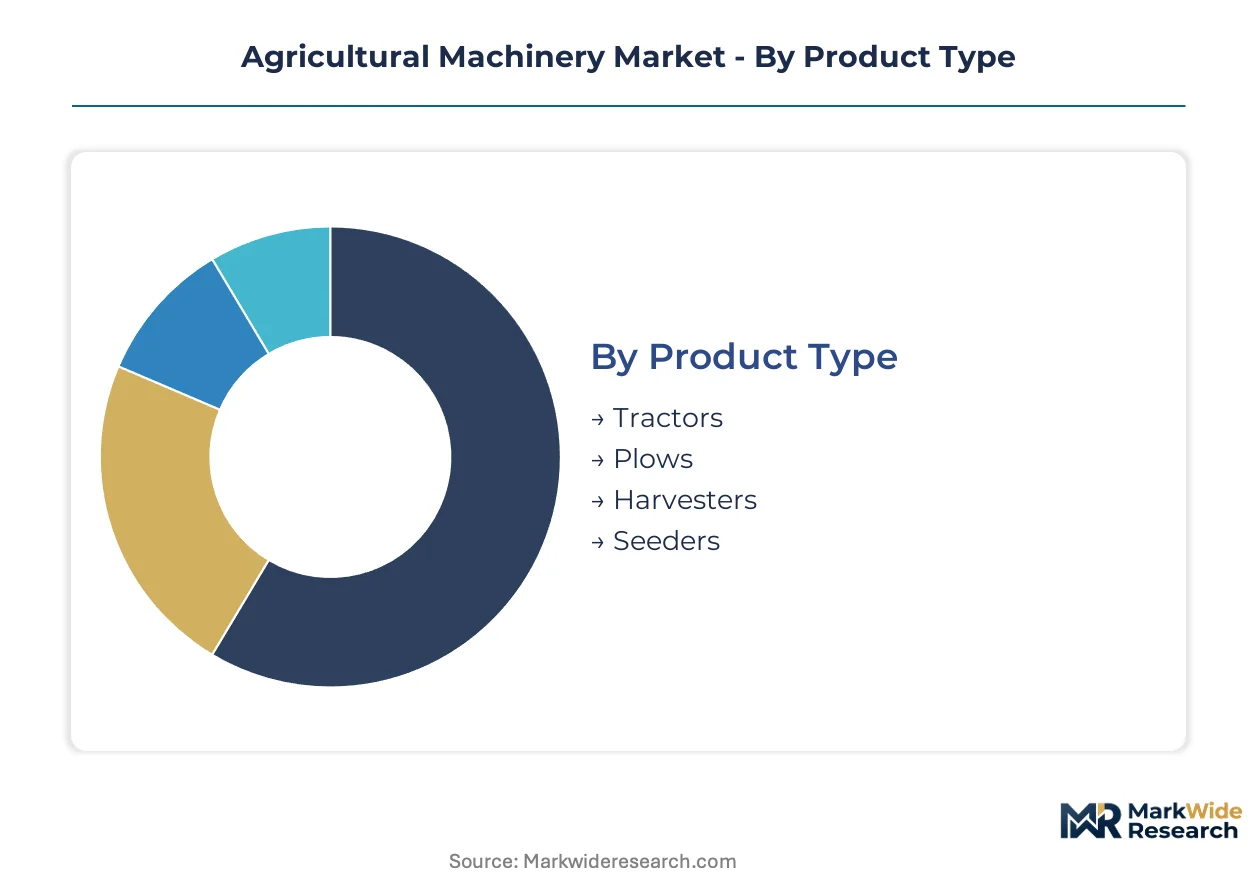
Equipment segmentation in agricultural machinery reveals divergent margin profiles across hardware platforms and digital layers. Tractor manufacturers capture recurring software revenue through precision guidance subscriptions, while harvester producers face compressed seasonal utilization windows. Understanding these structural differences enables targeted capital allocation between autonomous development and aftermarket service infrastructure.
Product Type:
Cost tier differentiation separates universal platform vehicles from specialized seasonal equipment with distinct depreciation curves and financing structures.
- Tractors:Diesel engines rated 25 to 600 horsepower serve as universal platform vehicles pulling implements across soil preparation, planting, and transport operations. Brazilian soybean operations and Indian rice-wheat belts are concentrating procurement in the 75-150 horsepower range where FAME-II subsidies offset EPA Tier 4 Final compliance costs.
- Harvesters:Complex threshing mechanisms and seasonal intensity command premium pricing relative to annual utilization hours. Australian grain operations and US Midwest cooperatives are prioritizing replacement cycles to compress narrow weather windows before crop losses accumulate.
- Plows:Towed implements with minimal onboard power systems occupy lower technology tiers but retain volume concentration in emerging mechanization markets.
- Seeders:Precision planting equipment with variable-rate capabilities links directly to GPS guidance subscriptions and input optimization software.
Tractors hold installed capacity across every geography. Harvesters are rotating up the share rankings in regions with labor recruitment constraints.
Technology:
Application maturity separates proven precision systems from emerging autonomous platforms requiring ISOBUS 11783 retrofit compatibility.
- Precision Farming:Sub-inch accuracy GPS with RTK correction networks enables variable-rate fertilizer and seed application, cutting input waste on large commercial farms. German operations and Canadian prairie grain producers are standardizing these systems to qualify for EU Green Deal farm subsidies and USDA conservation program credits.
- Autonomous Machinery:Swarming electric units operating 24-hour windows eliminate operator fatigue constraints and labor recruitment risk. Australian broadacre grain operations and US Midwest cooperatives are piloting coordinated small-tractor fleets to replace single 300-horsepower platforms.
- Smart Irrigation:Sensor-driven water management systems integrate with soil moisture telemetry and weather forecasting APIs.
- Drones:Aerial crop monitoring and targeted pesticide application platforms face regulatory fragmentation across national aviation authorities.
Precision Farming holds installed capacity. Autonomous Machinery is climbing the fastest as labor costs rise and seasonal compression intensifies.
Application:
Volume concentration tracks the crop calendar, with soil preparation and harvest windows commanding equipment utilization premiums over maintenance-period applications.
- Crop Production:Planting and cultivation operations spanning cereals, oilseeds, and specialty crops drive the largest equipment procurement volumes. Brazilian soybean belts and Indian Punjab rice-wheat systems are modernizing fleets through FAME-II mechanization incentives and cooperative financing structures.
- Soil Preparation:Tillage and residue management operations set yield ceilings for subsequent growing seasons. German operations and Ukrainian black-soil regions are prioritizing minimum-till equipment to meet EU Stage V emissions frameworks and carbon credit qualification thresholds.
- Pest Control:Spray application timing windows link equipment utilization to weather forecasting and disease pressure models.
- Irrigation:Water delivery system deployment concentrates in arid-zone agriculture and controlled-environment horticulture.
Crop Production holds installed capacity. Soil Preparation is rotating up the share rankings with conservation tillage adoption.
End User:
Customer type determines financing structure preferences, with cooperatives leveraging collective bargaining power and contractors prioritizing utilization-hour maximization.
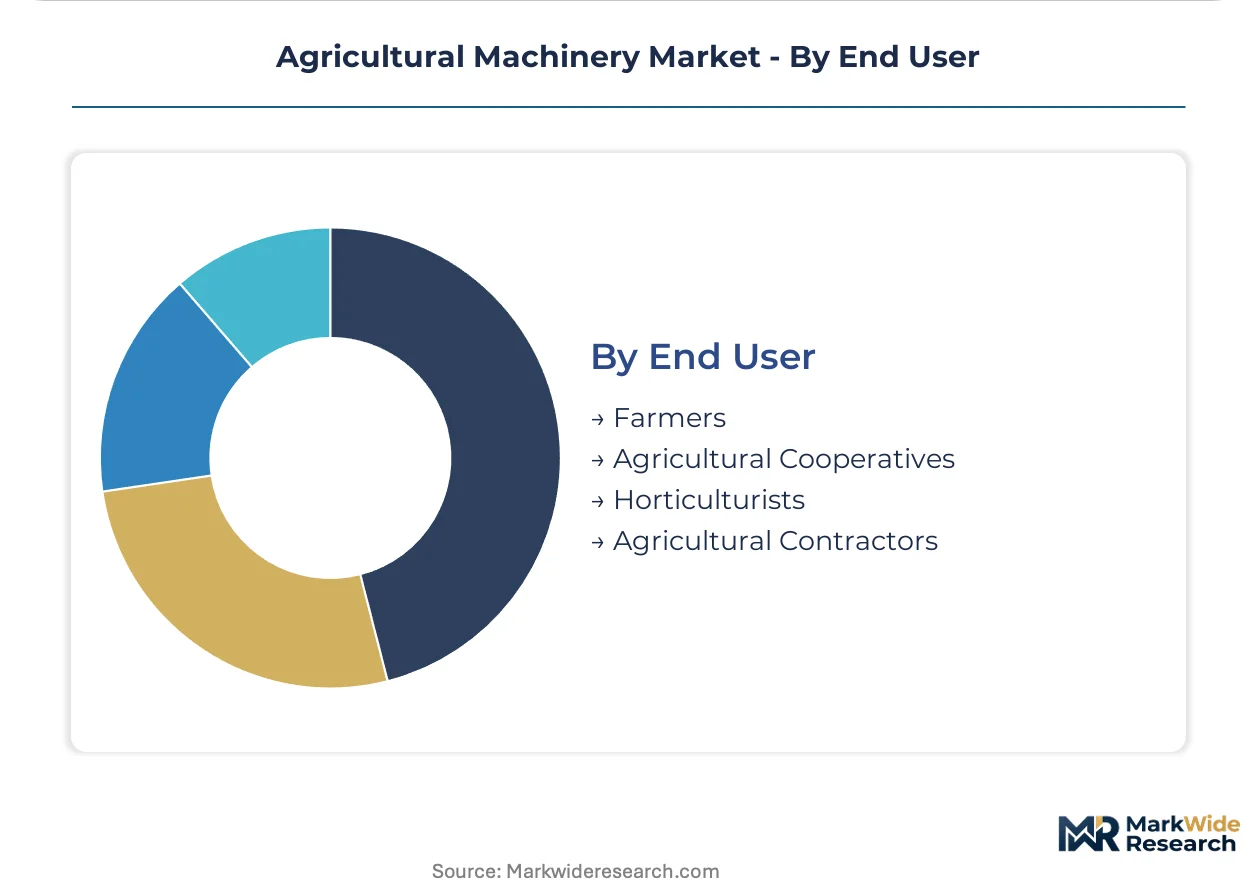
- Farmers:Individual owner-operators spanning subsistence holdings to large commercial enterprises represent the foundational demand base. Indian smallholders and Brazilian mid-size soybean producers are shifting toward robotics-as-a-service contracts to eliminate upfront capital barriers.
- Agricultural Cooperatives:Collective purchasing entities in Germany and the US Midwest aggregate seasonal equipment demand across member farms. These structures negotiate bundled software subscriptions and captive financing terms with manufacturer financing arms.
- Horticulturists:Specialized fruit and vegetable producers with shorter duty cycles drive compact tractor electrification in European markets.
- Agricultural Contractors:Custom service providers maximize equipment utilization across multiple client farms, prioritizing reliability and rapid parts availability.
Farmers hold installed capacity. Agricultural Cooperatives are rotating up the share rankings with procurement consolidation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River inland waterway system underwrites US agricultural machinery deployment, moving assembled equipment from Midwest manufacturing nodes to Gulf Coast export terminals. Brazil's Santos Port complex anchors South American distribution, while Hamburg's container terminals handle EU machinery transshipment into Eastern European farming belts.
United States
US grain cooperatives in Iowa and Illinois are consolidating equipment procurement through captive financing structures. EPA Tier 4 Final compliance deadlines accelerate replacement cycles for pre-2015 diesel fleets. Greater Des Moines hosts precision guidance R&D clusters where manufacturers test autonomous tillage algorithms on commercial test beds.
Brazil
Brazilian soybean operations in Mato Grosso are contracting robotics-as-a-service to bypass upfront capital barriers. ANVISA coordinates with agricultural regulators on autonomous machinery safety protocols. The Sorriso-Sinop corridor concentrates mid-size farm equipment demand as operators expand planted acreage.
Germany
German operations in Lower Saxony prioritize EU Stage V-compliant tractors to qualify for Green Deal farm subsidies. KBA type-approval timelines compress product development cycles for manufacturers serving regulated European markets. Stuttgart's industrial periphery anchors powertrain engineering clusters developing parallel diesel-electric platforms.
India
Indian rice-wheat belt farmers in Punjab and Haryana leverage FAME-II mechanization subsidies for 75-150 horsepower equipment. BIS certification requirements for farm machinery safety standards redirect procurement toward organized manufacturers. Ludhiana's metalworking clusters supply tillage implements to domestic tractor assemblers.
China
Chinese state farms in Heilongjiang Province are piloting autonomous swarming configurations for broadacre grain production. MIIT standards for agricultural robot navigation systems establish technical baselines for domestic equipment certification. Yangling Agricultural Hi-Tech Industries Demonstration Zone hosts precision farming equipment validation programs.
Agricultural Machinery Market Vendor Landscape
On the supply side, the industry is consolidating around integrated platform providers with captive financing arms and software subscription ecosystems. Tiered competition separates full-line manufacturers with precision guidance capabilities from regional specialists in compact equipment and towed implements. Two strategic archetypes dominate: vertically integrated OEMs bundling hardware-software-financing, and technology licensors supplying autonomy stacks to legacy manufacturers. Competitive intensity centers on M&A activity targeting precision agriculture startups and strategic partnerships securing rare earth magnet supply for electric drivetrains.
Among US-based full-line manufacturers, John Deere exemplifies the integrated platform archetype through its proprietary digital ecosystem and recurring revenue model. AGCO Corporation anchors multi-brand geographic coverage through its Challenger, Fendt, and Massey Ferguson portfolio structure. Kubota Corporation occupies a specialist position in compact tractors and rice-farming equipment across Asian markets.
| Leading Market Players |
|---|
| Claas |
| Mahindra & Mahindra |
| John Deere |
| New Holland |
| Case IH |
| AGCO Corporation |
| Kubota Corporation |
| Fendt |
| CNH Industrial |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese casting foundries is compressing component pricing for hydraulic transmission housings while simultaneously stretching payment terms for European precision guidance module suppliers. This utilization asymmetry between upstream metalworking and downstream electronics assembly is reshaping procurement leverage across the equipment tier structure.
Pricing Analysis
Volume-discount tiering separates cooperative procurement pools from individual farm purchases across the 75-300 horsepower tractor segment. Three-tier pricing structure across premium, standard, and economy levels reflects ISOBUS 11783 certification grade and captive financing bundling. Cost compression in sub-100 horsepower equipment is intensifying because EPA Tier 4 Final after-treatment systems add fixed cost layers that erode margin at lower price points. Smallholder farmers in India's rice-wheat belts exhibit highest price sensitivity, while German agricultural cooperatives prioritize total cost of ownership over upfront equipment expenditure.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize supplier relationships for diesel engine after-treatment systems and permanent magnet electric drivetrain components. Manufacturing concentration centers on Germany for precision hydraulic systems, Japan for compact transmission assemblies, and China for cast iron structural components. Rare earth magnet supply draws from processing facilities in China and separation plants in Australia. Single-source vulnerability in permanent magnet supply chains threatens electrification timelines for compact tractor platforms. Distribution runs through manufacturer-owned dealer networks in North America and independent agricultural equipment distributors in South American soybean belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The agricultural machinery sector functions as a defensive-moat market where regulatory entrenchment around EPA Tier 4 Final and EU Stage V compliance creates prohibitive re-certification barriers for prospective entrants.
For Market Incumbents: Pre-empt autonomous swarming technology deployment by acquiring precision agriculture startups with proven RTK correction network integration. Lock in rare earth magnet supply through offtake agreements with Australian separation facilities before electrification demand intensifies. Channel control through captive financing arms in Brazil and Germany remains the critical lever against robotics-as-a-service entrants. For New Entrants and Emerging Players: Mid-size Brazilian soybean operations contracting equipment on per-acre terms represent the most penetrable entry point for autonomous machinery challengers. European horticulture segments below 75 horsepower offer white-space opportunity for battery-electric compact tractor platforms with overnight charging compatibility. Go-to-market execution should prioritize direct digital sales channels bypassing legacy dealer network concentration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision guidance subscription providers with ISOBUS 11783-compliant telemetry infrastructure. Long-term viability across the analysis window favors acquisition targets with established data sovereignty frameworks addressing farmer resistance to cloud-based yield mapping. Watch autonomous swarming pilot program expansion in Australian broadacre grain operations as the inflection signal for fleet replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Swarming Technology Deployment | Coordinated electric tractor fleets eliminate labor recruitment risk during compressed Canadian prairie planting windows. |
| Rare Earth Magnet Supply Agreement | Captive magnet sourcing secures electrification timelines for 75-150 horsepower battery tractor development. |
| ISOBUS 11783 Certification Investment | Retrofit compatibility unlocks precision guidance subscription revenue from legacy hydraulic implement installed base. |
| Robotics-as-a-Service Platform Launch | Per-acre contracting eliminates upfront capital barriers for mid-size Brazilian soybean operations. |
| EU Stage V Parallel Development Track | Dual diesel-electric engineering competency maintains market access across regulated European and cost-sensitive developing economies. |
Methodological Framework
Initial hypotheses were tested against primary input from agricultural equipment procurement managers at Brazilian cooperatives, precision agriculture R&D directors at German manufacturers, aftermarket service heads at North American dealer networks, and Indian smallholder farmers in Punjab's rice-wheat belt, then refined against secondary validation from EPA certification filings, EU Stage V type-approval documentation, FAME-II subsidy disbursement records, and USDA conservation program enrollment data. Bottom-up equipment shipment tallies were triangulated with top-down agricultural GDP elasticity estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions spanning horsepower tier, guidance technology maturity, propulsion architecture, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and fleet turnover elasticity to subsidy programs. Forecast inputs incorporated FAME-II mechanization incentive trajectories and EU Green Deal farm subsidy qualification thresholds.
Stress conditions across steel price volatility, rare earth magnet supply disruption, and autonomous machinery regulatory approval timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about subsidy continuation and emissions framework stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Latin America Agricultural Machinery Market
Agricultural Machinery
Electric Tractors Market
Agricultural Machinery
Wheat Milling Machine Market
Agricultural Machinery
India Agricultural Tractor Market
Agricultural Machinery
Crawler Tractors Market
Agricultural Machinery
Agricultural Haying and Forage Machinery Market
Agricultural Machinery
North America Agricultural Tractors Market
Agricultural Machinery
South America Agricultural Machinery Market
Agricultural Machinery
Agricultural Spray Drone Market
Agricultural Machinery
Vietnam Combine Harvester Market
Agricultural Machinery
Global Autopilot Agricultural Vehicle Market
Agricultural Machinery
Asia-Pacific Utility Tractor Market
Agricultural Machinery
Canada Agricultural Machinery Market
Agricultural Machinery
Orchard Tractor Market
Agricultural Machinery
Africa Agricultural Tractor Market
Agricultural Machinery
Orchard Type Tractors Market