
 Agriculture Drone Software Market | 2026-2036
Agriculture Drone Software Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Drone Software Market Insights
The EU AI Act is consolidating compliance burdens for autonomous flight algorithms across European farmland. DJI Agriculture leverages its manufacturing scale to dominate hardware-software bundles in Asia-Pacific orchards. Trimble anchors North American market presence through deep GIS integration with existing farm management systems. AgEagle specializes in lightweight fixed-wing platforms that extend flight endurance for broad-acre crop monitoring.
Agriculture drone software encompasses flight planning, sensor data processing, and prescription map generation for aerial crop management, typically operating at sub-centimeter resolution via multispectral and RGB imaging payloads. The primary commercial purpose is converting drone-captured imagery into actionable agronomic decisions such as variable-rate nitrogen application or targeted fungicide deployment. Cloud-Based deployment leads adoption among mid-sized farms seeking minimal IT infrastructure, while AI-Powered Analytics captures the fastest growth as convolutional neural networks improve weed-versus-crop classification accuracy. Crop Monitoring occupies the largest product type share, though Pest Detection commands premium pricing where early intervention prevents yield loss.
The FAA governs beyond-visual-line-of-sight waivers that determine operational scalability for US service providers, while EASA's specific category framework shapes certification costs for European software vendors. India's DGFT drone import restrictions and PLI scheme for domestic manufacturing are redirecting procurement toward locally developed platforms. Stakeholders must weigh regulatory fragmentation against the margin advantages of unified global software architectures.
Market Dynamics
Precision agriculture platforms are consolidating flight planning, sensor fusion, and prescription analytics into unified cloud architectures. The EU F-Gas Regulation is compressing diesel-powered spray drone replacement cycles. Brazil's Mato Grosso soybean belt is digitizing cooperative workflows at scale.
Growth Catalysts
- Variable-Rate Nitrogen Application:Multispectral imaging at sub-centimeter resolution enables targeted fertilizer deployment. Large-scale corn operations in Iowa and Illinois are retrofitting existing sprayers with drone-guided prescription maps.
- EASA Specific Category Certification:Standardized type certification for autonomous flight algorithms reduces software vendor entry barriers. European orchard operators are expanding beyond-visual-line-of-sight waivers for seasonal crop monitoring.
- Convolutional Neural Networks:AI-powered weed-versus-crop classification accuracy improvements are compressing manual scouting labor. Australian broad-acre wheat farms are deploying real-time inference at the edge.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Cell production gravity centers on East Asian suppliers. European drone fleet electrification timelines face raw material procurement bottlenecks.
- FAA Beyond-Visual-Line-of-Sight Waiver Complexity:Case-by-case operational approvals constrain US service provider scalability. Spray contractors in Kansas and Nebraska face fragmented state-level altitude restrictions.
- RGB Imaging Substitution:Satellite-based crop health monitoring at 10-meter resolution captures commodity grain monitoring demand. Soybean cooperatives in Argentina are delaying drone investments where satellite revisit frequencies suffice.
Strategic Opportunities
- India PLI Scheme for Domestic Manufacturing:Production-linked incentives redirect procurement toward locally developed flight control software. DGFT import restrictions on complete drone systems create captive demand for indigenous platform integration.
- Pest Detection Premium Pricing:Early fungal pressure identification in vineyard blocks commands per-hectare service premiums. French and Italian wine cooperatives are unbundling disease scouting from full-season monitoring contracts.
- GIS-Farm Management System Convergence:Deep integration between aerial imagery archives and soil sampling databases unlocks longitudinal yield analysis. North American agronomy retailers are white-labeling bundled analytics for grower loyalty programs.
Industry Challenges
- Pilot Certification Bottlenecks:Remote pilot license throughput limits service fleet expansion. Australian spray contractors face 90-day training backlogs during narrow application windows.
- Legacy Farm Management System Integration:Proprietary data formats from 1990s-era desktop software block seamless cloud migration. Midwestern US grain elevators resist API investments for drone imagery ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Drone Software Market |
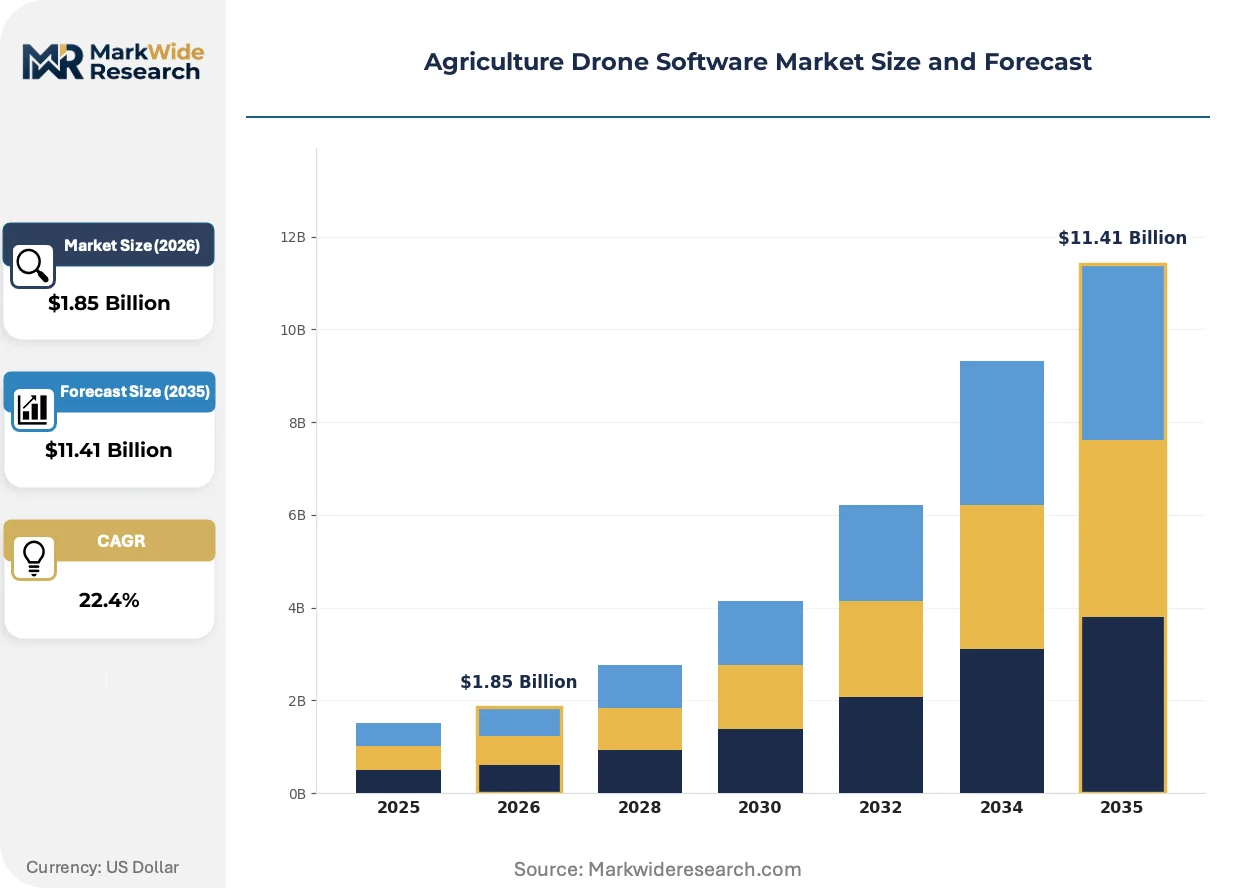
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $11.41 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crop Monitoring, Soil Analysis, Pest Detection, Yield Estimation End User: Farmers, Agricultural Cooperatives, Research Institutions, Crop Consultants Technology: AI-Powered Analytics, GIS Mapping, 3D Imaging, Data Integration Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Mobile Applications |
| Companies Covered | Trimble, AgEagle, DJI Agriculture, ABZ Innovation, Parrot, PrecisionHawk, Jinghong Drone, Anzu Robotics, XAG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Drone Software Market Trends and Innovations
Flight endurance extension through airframe lightweighting is compressing per-acre operational costs. Regulatory frameworks are formalizing autonomous decision thresholds. Procurement patterns are fragmenting across subscription, per-acre, and equipment-lease models.
Fixed-wing electric propulsion systems are electrifying broad-acre monitoring economics. Australian wheat belt operators are adopting 90-minute endurance platforms for 500-hectare daily coverage. The shift is compressing rotary-wing unit economics in commodity grain regions where flight time dominates cost structures.
The EU AI Act risk classification for autonomous flight algorithms is mandating human-in-the-loop documentation. European software vendors are restructuring development workflows to satisfy conformity assessment body requirements. Vineyard and orchard segments in France and Spain face 18-month certification timelines for fully automated spray missions.
Cooperative procurement consortia are displacing individual farm software licenses in Brazil's Mato Grosso region. Digitized spray monitoring and yield mapping workflows are consolidating through shared cloud infrastructure. The model concentrates negotiating leverage with platform vendors while fragmenting implementation support responsibilities across member technical staff.
Agriculture Drone Software Market Segmentation
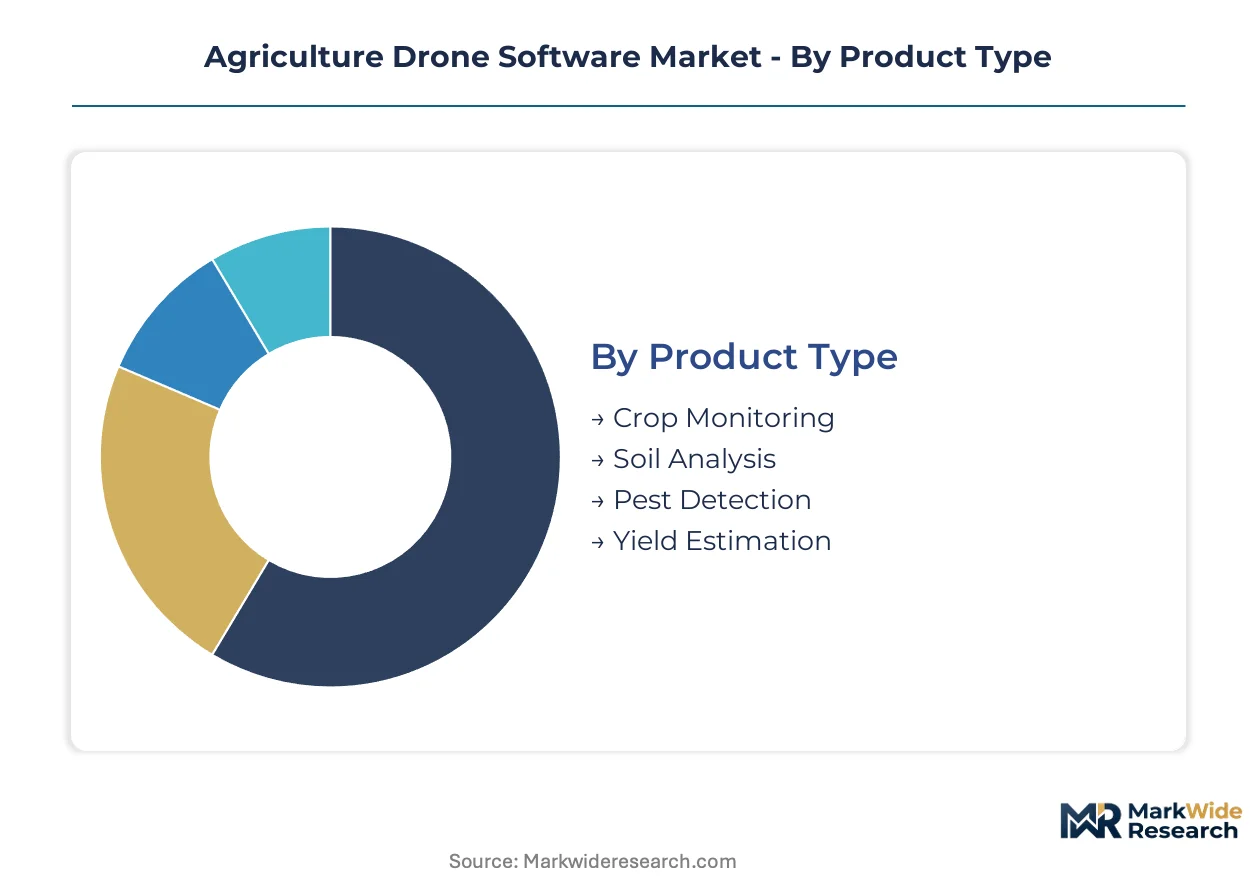
Agriculture drone software vendors configure product architectures around operational scale and technical sophistication. Deployment choices determine infrastructure investment, while technology selection shapes analytical depth and prescription accuracy.
Product Type:
Commercial buyers prioritize segments by frequency of agronomic intervention and per-hectare service pricing power.
- Crop Monitoring:Multispectral and RGB imaging pipelines track vegetation indices across growth stages. Iowa corn operations and Mato Grosso soybean cooperatives deploy weekly flight schedules during critical phenological windows. Volume concentration reflects commodity grain dominance where monitoring frequency justifies software subscriptions.
- Pest Detection:Convolutional neural networks classify fungal pressure and insect damage at sub-millimeter resolution. French and Italian vineyard blocks command premium per-hectare pricing where early intervention prevents vintage loss. Narrow application windows compress deployment timelines and elevate algorithm accuracy requirements.
- Soil Analysis:Electromagnetic induction and thermal sensors map moisture gradients and compaction zones.
- Yield Estimation:Machine learning models project harvest tonnage from flowering-stage canopy density metrics.
Volume sits with Crop Monitoring; growth tilts toward Pest Detection.
End User:
Procurement authority and technical staffing determine platform complexity and support requirements across buyer types.
- Farmers:Owner-operators below 500 hectares favor mobile-first interfaces with minimal training curves. Kansas and Nebraska spray contractors purchase per-acre analytics rather than annual licenses to match cash-flow cycles.
- Agricultural Cooperatives:Shared cloud infrastructure consolidates negotiating leverage with platform vendors. Brazil's Mato Grosso digitization initiatives fragment implementation support across member technical staff while centralizing data archives.
- Research Institutions:Phenotyping protocols and breeding trials demand raw sensor data export capabilities.
- Crop Consultants:White-label analytics bundles serve grower loyalty programs for North American agronomy retailers.
Cooperative procurement is accelerating fastest; individual farmer licenses retain absolute volume.
Technology:
Algorithm sophistication separates premium positioning from commodity functionality in vendor pricing architectures.
- AI-Powered Analytics:Edge-deployed inference engines execute weed-versus-crop classification without cloud latency. Australian broad-acre wheat farms process imagery in-flight to compress scouting labor. Convolutional neural network accuracy improvements are climbing the fastest adoption trajectory.
- GIS Mapping:Deep integration with soil sampling databases unlocks longitudinal yield analysis. Trimble anchors North American presence through existing farm management system compatibility.
- 3D Imaging:Photogrammetry pipelines generate elevation models for drainage design and irrigation planning.
- Data Integration:API bridges connect drone imagery archives to legacy desktop software and climate databases.
GIS Mapping holds installed base; AI-Powered Analytics gains share fastest.
Deployment:
IT infrastructure maturity and connectivity reliability shape architecture preferences across operational contexts.
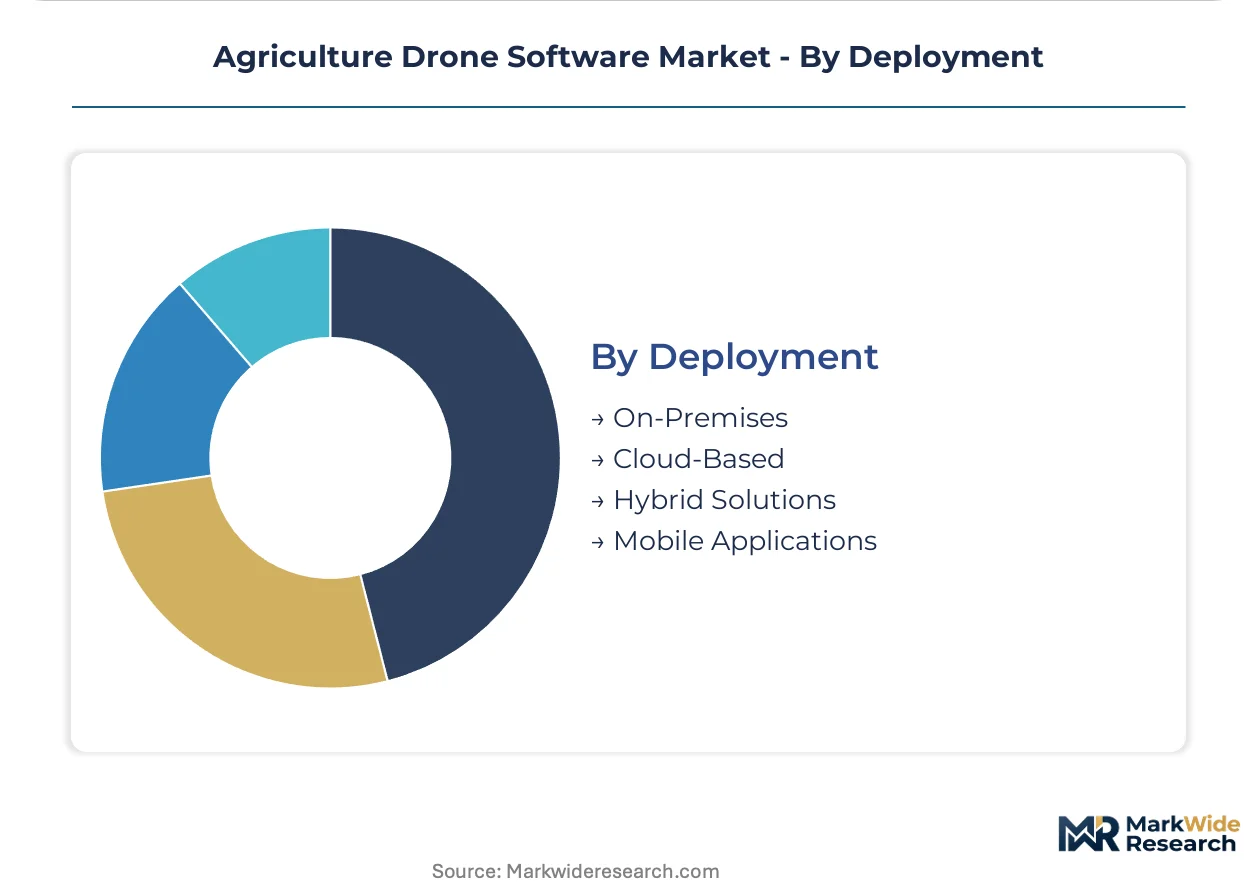
- Cloud-Based:Browser-accessible platforms minimize on-farm server investment. Mid-sized Illinois and Iowa operations subscribe to software-as-a-service models to outsource maintenance and security patching.
- On-Premises:Air-gapped installations satisfy data sovereignty requirements for institutional research programs and defense-adjacent agricultural facilities.
- Hybrid Solutions:Local preprocessing with cloud archival balances latency-sensitive field decisions against long-term storage economics.
- Mobile Applications:Tablet-native flight planning and real-time telemetry suit contract spray operators with dispersed daily routes.
Cloud-Based deployment dominates current procurement; Hybrid Solutions are expanding most quickly in bandwidth-constrained regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale commercial farming operations in the United States, Brazil, and Australia concentrate the heaviest software procurement volumes. The EU F-Gas Regulation and India's PLI scheme are redirecting fleet electrification timelines and domestic manufacturing incentives across three continents.
United States
Iowa and Illinois corn operations drive variable-rate nitrogen application demand through drone-guided prescription maps. The FAA governs beyond-visual-line-of-sight waivers that determine operational scalability for spray contractors in Kansas and Nebraska. Midwestern grain elevators resist API investments, blocking seamless cloud migration for legacy farm management systems.
Brazil
Mato Grosso soybean cooperatives digitize spray monitoring and yield mapping workflows at scale through shared cloud infrastructure. ANVISA coordinates with agricultural regulators on aerial chemical application protocols. Cooperative procurement consortia concentrate negotiating leverage with platform vendors while fragmenting implementation support.
European Union
French and Italian vineyard blocks command premium per-hectare pricing for early fungal pressure identification. The EU AI Act mandates human-in-the-loop documentation for autonomous flight algorithms, extending certification timelines to 18 months. EASA's specific category framework standardizes type certification for seasonal crop monitoring beyond-visual-line-of-sight.
India
DGFT drone import restrictions and the PLI scheme for domestic manufacturing redirect procurement toward locally developed flight control software. State-level agricultural extension programs in Maharashtra and Gujarat promote indigenous platform integration. Captive demand for domestic manufacturing creates procurement advantages for software vendors with local hardware partnerships.
Australia
Broad-acre wheat farms deploy real-time edge inference to compress manual scouting labor through convolutional neural networks. The TGA coordinates agricultural chemical regulation with aerial application standards. Western Australian operators adopt 90-minute endurance fixed-wing platforms for 500-hectare daily coverage, compressing rotary-wing unit economics.
Agriculture Drone Software Market Competitive Landscape
United States producers anchor one tier through deep GIS integration with existing farm management systems; Chinese specialists hold hardware-software bundle dominance in Asia-Pacific orchards. The vendor base concentrates around three strategic archetypes: manufacturing-scale bundlers, precision agriculture platform consolidators, and lightweight fixed-wing endurance specialists. Competitive moves center on M&A for sensor fusion capabilities and strategic partnerships for cloud architecture unification.
Within the precision agriculture tier, Trimble exemplifies North American market anchoring through farm management system compatibility, while DJI Agriculture occupies the manufacturing-scale bundler position. AgEagle represents the lightweight fixed-wing specialist archetype, extending flight endurance for broad-acre crop monitoring. These three companies illustrate the geographic and technological segmentation governing procurement decisions across commodity grain and specialty crop segments.
| Leading Market Players |
|---|
| Trimble |
| AgEagle |
| DJI Agriculture |
| ABZ Innovation |
| Parrot |
| PrecisionHawk |
| Jinghong Drone |
| Anzu Robotics |
| XAG |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating electric propulsion transitions that only certified hardware-software bundles satisfy. Vendors with EASA-compliant architectures capture pricing premiums while diesel-dependent operators face accelerated replacement cycles and margin compression.
Pricing Analysis
Short lead-time premiums apply to EASA-specific category certified flight control modules, while spot inventory of non-compliant diesel-powered spray systems trades at distressed levels. Pricing stratifies across premium, standard, and economy tiers based on AI inference accuracy certification and geographic delivery remoteness. Cost compression in economy-tier RGB-only analytics is intensifying because satellite-based monitoring substitutes commoditize basic vegetation indexing. Agricultural cooperatives in Brazil's Mato Grosso region exhibit highest price sensitivity through collective procurement leverage, while French vineyard operators show lowest sensitivity where vintage loss prevention justifies per-hectare service premiums.
Supply Chain Analysis
Reverse-logistics flows for lithium-ion battery packs and multispectral sensor refurbishment are emerging as cost centers, with end-of-life drone airframes feeding remanufacturing programs in China, South Korea, and Taiwan. Cell production draws from East Asian cathode and electrolyte suppliers, while imaging sensors rest on German and Japanese optical component ecosystems. Single-source vulnerability concentrates in rare-earth magnet supply for electric propulsion motors. Distribution runs through agricultural equipment dealers and direct-to-cooperative enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward integration into flight control chipset design to escape hardware margin capture by drone OEMs.
For Market Incumbents: Acquire convolutional neural network training datasets from Australian and North American broad-acre operations to defend algorithm accuracy leadership. Lock in EASA conformity assessment body pre-certification pathways before EU AI Act documentation requirements harden. Satellite-based monitoring substitutes threaten commodity grain segments; counter with edge-deployed inference speed advantages that cloud-dependent competitors cannot match. For New Entrants and Emerging Players: Real-time fungal pressure detection algorithms in Italian and French vineyard blocks offer the most penetrable white-space target. Brazil's Mato Grosso cooperative procurement consortia present second-tier entry through shared infrastructure revenue models. Pursue white-label partnerships with North American agronomy retailers seeking grower loyalty program differentiation. For Investors and Strategic Acquirers: FAA beyond-visual-line-of-sight waiver approval velocity is the leading indicator that US service provider scalability constraints are easing. Five-to-ten year viability favors vendors with unified cloud architectures spanning flight planning, sensor fusion, and prescription analytics. Monitor EASA specific category certification timeline compression as signal of European software vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Capability Acquisition | Consolidates multispectral, thermal, and RGB pipelines into unified prescription analytics platforms. |
| EASA Specific Category Pre-Certification | Accelerates market access for autonomous flight algorithms before EU AI Act documentation mandates fully deploy. |
| Cloud Architecture Unification Partnership | Integrates flight planning, data processing, and farm management system APIs through single vendor relationship. |
| Fixed-Wing Endurance Platform Launch | Captures Australian and US Midwest broad-acre economics where flight time dominates per-acre operational costs. |
| Cooperative Procurement Consortium Engagement | Locks multi-year revenue streams through Brazil's Mato Grosso shared infrastructure digitization initiatives. |
Research Methodology
Document review covered SEC filings from precision agriculture platform vendors, EASA regulatory guidance documents, and FAA waiver approval databases, complemented by interviews with agricultural cooperative technical directors, spray contractor fleet managers, and vineyard operations managers. Secondary validation drew from ANVISA aerial chemical application protocols, EU F-Gas Regulation implementation reports, and India DGFT drone import restriction circulars. Bottom-up triangulation aggregated individual farm and cooperative procurement patterns against top-down vendor revenue segmentation disclosures.
Segmented outputs across the projection horizon reflect deployment model, farm operational scale, crop type complexity, and regional regulatory framework clusters. CAGRs derive from installed base expansion rates and per-hectare service pricing trajectories modeled through convolutional neural network adoption curves and fixed-wing platform penetration assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FAA regulatory acceleration or East Asian battery supply disruption scenarios. Practitioners should monitor EASA conformity assessment body queue lengths and India PLI scheme disbursement velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Global Digital Agriculture Platform Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Variable Rate Technology Market
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Autonomous Crop Management Market
Precision Agriculture
Global Internet of Things (IoT) Agriculture Market
Precision Agriculture
Global Precision Irrigation Market
Precision Agriculture
Crop Monitoring Market
Precision Agriculture
Asia-Pacific Agricultural Sensors Market
Precision Agriculture
Agriculture Analytics Market
Precision Agriculture
Crop Nutrient Management Market
Precision Agriculture
Global Precision Farming Software and Services Market
Precision Agriculture
Global Precision Livestock Farming Market
Precision Agriculture
Precision Viticulture Market
Precision Agriculture
Global Agriculture Sensors Market