
 Bluetooth Smart Lock Market | 2026-2036
Bluetooth Smart Lock Market Size, Share, and Industry Trends Forecast 2026-2036
Bluetooth Smart Lock Market Insights
Buyer concentration in the multi-family housing sector is realigning procurement patterns toward enterprise-grade Bluetooth lock platforms. ASSA ABLOY leverages its Yale and August Home brands to dominate the North American retrofit channel. dormakaba Group anchors European commercial installations with SALTO Systems competing aggressively on mobile credential integration across hospitality portfolios.
Bluetooth smart locks are electromechanical locking devices that communicate via Bluetooth Low Energy protocols, typically operating on 2.4 GHz frequency bands with AES-128 encryption for credential transmission, and are engineered to replace or supplement traditional mechanical cylinders in access control applications. Deadbolts and lever handles command the largest installed base in residential settings, while biometric-enabled units represent the fastest-expanding technology tier as fingerprint sensors decline in cost. The commercial end-user segment generates the deepest margin pools due to recurring software subscription attach rates.
The Federal Communications Commission regulates radio frequency emissions for Bluetooth smart locks sold in the United States, while the European Union's Radio Equipment Directive mandates cybersecurity and interoperability standards for connected locking hardware. The EU AI Act is beginning to shape biometric authentication modules integrated into premium lock lines. Stakeholders must monitor evolving encryption standards and interoperability certifications as mobile wallet platforms from Apple and Google deepen their integration with residential and commercial access systems.
Market Dynamics
The Bluetooth smart lock market is undergoing a structural reconfiguration as multi-family residential operators consolidate procurement around enterprise-grade platforms, compressing vendor selection cycles and elevating cybersecurity certification requirements above hardware cost in sourcing decisions.
Growth Catalysts
- FCC radio frequency mandates:The Federal Communications Commission's emissions standards for 2.4 GHz devices have normalized Bluetooth Low Energy as the de facto protocol, reducing interoperability friction across North American installations.
- Multi-family housing consolidation:Portfolio operators with thousands of units are standardizing on single-platform keyless entry, creating concentrated demand pools that justify software subscription investments.
- AES-128 encryption maturation:Hardware costs for credential transmission security have declined sufficiently to embed enterprise-grade protection in mid-tier residential locks.
Market Restraints
- Semiconductor supply concentration:Fingerprint sensor and BLE chip fabrication clusters in East Asia expose lead times to single-source dependencies.
- EU Radio Equipment Directive compliance costs:Cybersecurity certification requirements for connected door hardware impose fixed-cost barriers for smaller hardware vendors.
- Mechanical lock substitution persistence:Traditional cylinder systems retain cost advantages in price-sensitive single-family retrofits and developing-market new construction.
Strategic Opportunities
- India multi-family construction acceleration:Urban housing development in Mumbai and Bangalore corridors is creating first-mover advantages for mobile credential platforms.
- Apple Wallet and Google Wallet convergence:Residential access credential integration with smartphone-native wallets is opening direct-to-consumer distribution bypassing traditional locksmith channels.
- EU AI Act biometric tailwinds:Regulatory clarity on fingerprint authentication modules is reducing compliance uncertainty for premium lock lines incorporating biometric tiers.
Industry Challenges
- Cybersecurity engineering talent scarcity:Embedded systems security expertise for IoT hardware remains concentrated among a limited pool of specialists.
- Legacy access control integration complexity:Retrofit deployments in commercial buildings with existing badge-reader infrastructure require custom middleware development.
- Interoperability certification timelines:Mobile wallet platform validation cycles with Apple and Google extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bluetooth Smart Lock Market |
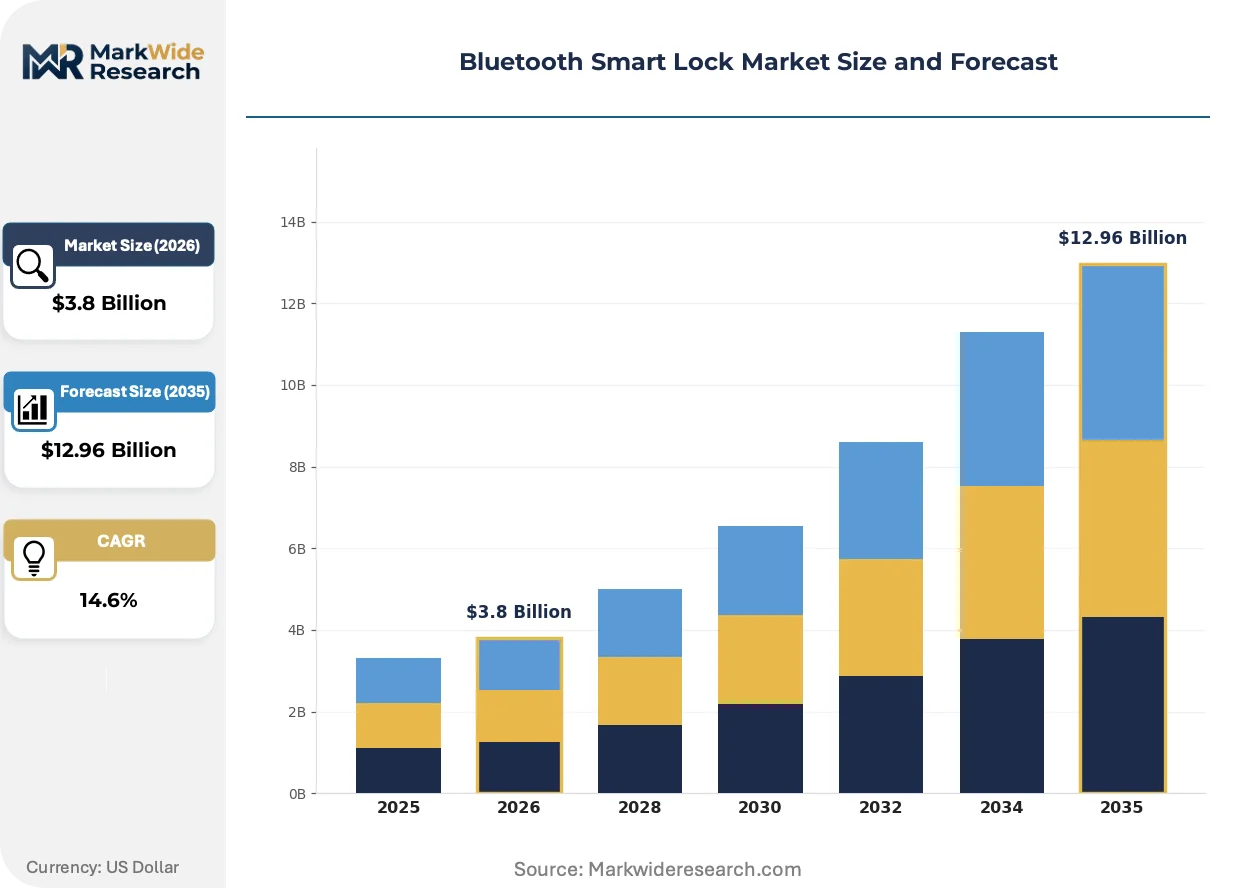
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deadbolts, Padlocks, Lever Handles, Smart Padlocks Technology: Keyless Entry, Remote Access, Biometric, Wireless Connectivity End User: Residential, Commercial, Industrial, Institutional Installation Type: Retrofit, New Construction, Wireless, Hardwired |
| Companies Covered | ASSA ABLOY, Allegion plc, Honeywell International Inc., Samsung Electronics Co., Ltd., Spectrum Brands, SALTO Systems, S.L., dormakaba Group, August Home, Yale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bluetooth Smart Lock Market Trends and Innovations
Bluetooth smart lock evolution is pivoting from hardware differentiation toward software-embedded service models, with biometric authentication and mobile wallet convergence reshaping both technical architectures and go-to-market economics.
Biometric fingerprint sensors are integrating into mid-tier lock lines as sensor module costs compress and liveness detection algorithms mature. Multi-family operators in Texas and Florida metropolitan corridors are deploying these units at accelerating velocity, displacing PIN-code backups as the secondary authentication method. The technology is integrating access logging with property management software, enabling real-time occupancy analytics that justify premium hardware investments through operational efficiency gains.
The European Union's AI Act is imposing algorithmic transparency requirements on biometric authentication modules, forcing hardware vendors to document training data provenance and decision logic. Manufacturers targeting European commercial installations must now maintain technical documentation dossiers that extend product development cycles. Hospitality portfolios in Spain and Italy are responding by prioritizing vendors with existing EU AI Act conformity assessments, creating certification-based vendor selection filters.
Enterprise procurement teams are consolidating vendor relationships around platforms offering unified mobile credential management across residential, commercial, and mixed-use portfolios. Traditional locksmith distribution channels in the United States are losing share to direct manufacturer relationships with national property management groups. This concentration is most visible in Sun Belt metropolitan statistical areas where new construction velocity supports large-scale single-source deployments.
Bluetooth Smart Lock Market Segmentation
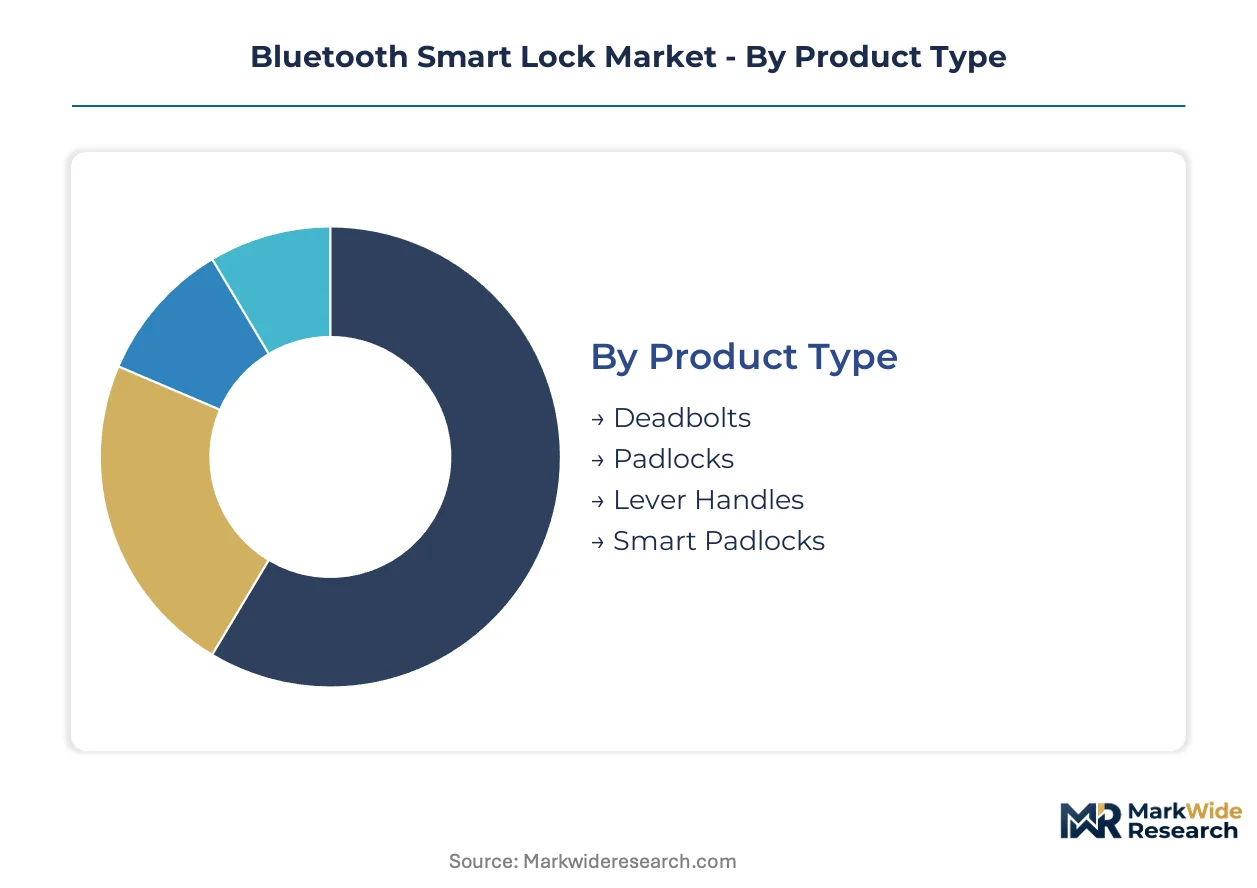
Bluetooth smart lock segmentation reveals how hardware specifications, authentication methods, and deployment contexts fragment procurement requirements. Understanding these divides exposes where margin pools concentrate and which technology tiers command premium positioning.
Product Type:
Supply concentration in deadbolt manufacturing has anchored procurement patterns for residential retrofit channels, while lever handle production clusters serve commercial specification teams with different lead time tolerances.
- Deadbolts:Electromechanical cylinders replacing traditional single-point locking mechanisms, typically integrating BLE modules within the escutcheon housing. Demand concentrates in United States multi-family housing corridors, particularly Texas and Florida metropolitan statistical areas, where portfolio operators standardize on single-platform keyless entry across thousands of units.
- Lever Handles:ANSI/BHMA Grade 1 and Grade 2 compliant hardware with integrated clutch mechanisms and motorized locking cores. Commercial end-users in European Union member states generate the deepest margin pools here, driven by recurring software subscription attach rates and SALTO Systems' hospitality portfolio penetration.
- Padlocks:Portable BLE-enabled shackles targeting temporary access scenarios and shared storage applications.
- Smart Padlocks:Weatherized units with extended battery life for outdoor and industrial perimeter applications.
Today's leader: Deadbolts. Tomorrow's challenger: Lever Handles.
Technology:
Authentication method selection now determines total cost of ownership more than hardware price, with biometric modules climbing the fastest as fingerprint sensor costs compress and liveness detection algorithms mature.
- Biometric:Capacitive fingerprint sensors with liveness detection and AES-128 encrypted template storage, increasingly embedding in mid-tier residential lines. European Union AI Act algorithmic transparency requirements are forcing documentation of training data provenance, extending product development cycles for vendors targeting EMA-regulated commercial installations.
- Keyless Entry:PIN-code and touchpad interfaces with offline credential caching for network-disrupted environments. United States Federal Communications Commission 2.4 GHz emissions standards have normalized this as the baseline protocol across North American residential retrofits.
- Remote Access:Cloud-connected locks with real-time status monitoring and over-the-air firmware update capability.
- Wireless Connectivity:Mesh network and Wi-Fi bridge integrations extending Bluetooth range for whole-property management.
Biometric authentication is gaining share fastest. Keyless Entry retains volume dominance.
End User:
Customer type segmentation separates recurring revenue potential from one-time hardware transactions, with institutional procurement teams now consolidating around enterprise-grade platforms that span residential, commercial, and mixed-use portfolios.
- Commercial:Office buildings, retail storefronts, and coworking facilities requiring audit trails and time-based access permissions. Property management groups in United States Sun Belt markets are compressing vendor selection cycles and elevating cybersecurity certification requirements above hardware cost in sourcing decisions.
- Residential:Single-family homes and multi-family apartments prioritizing smartphone-native wallet integration. Apple Wallet and Google Wallet credential convergence is opening direct-to-consumer distribution channels that bypass traditional locksmith networks.
- Industrial:Manufacturing facilities and warehouse operations with harsh-environment durability requirements.
- Institutional:Educational campuses, healthcare facilities, and government buildings with compliance-heavy procurement protocols.
Commercial segments capture the deepest software attach rates. Residential channels deliver the highest unit volumes.
Installation Type:
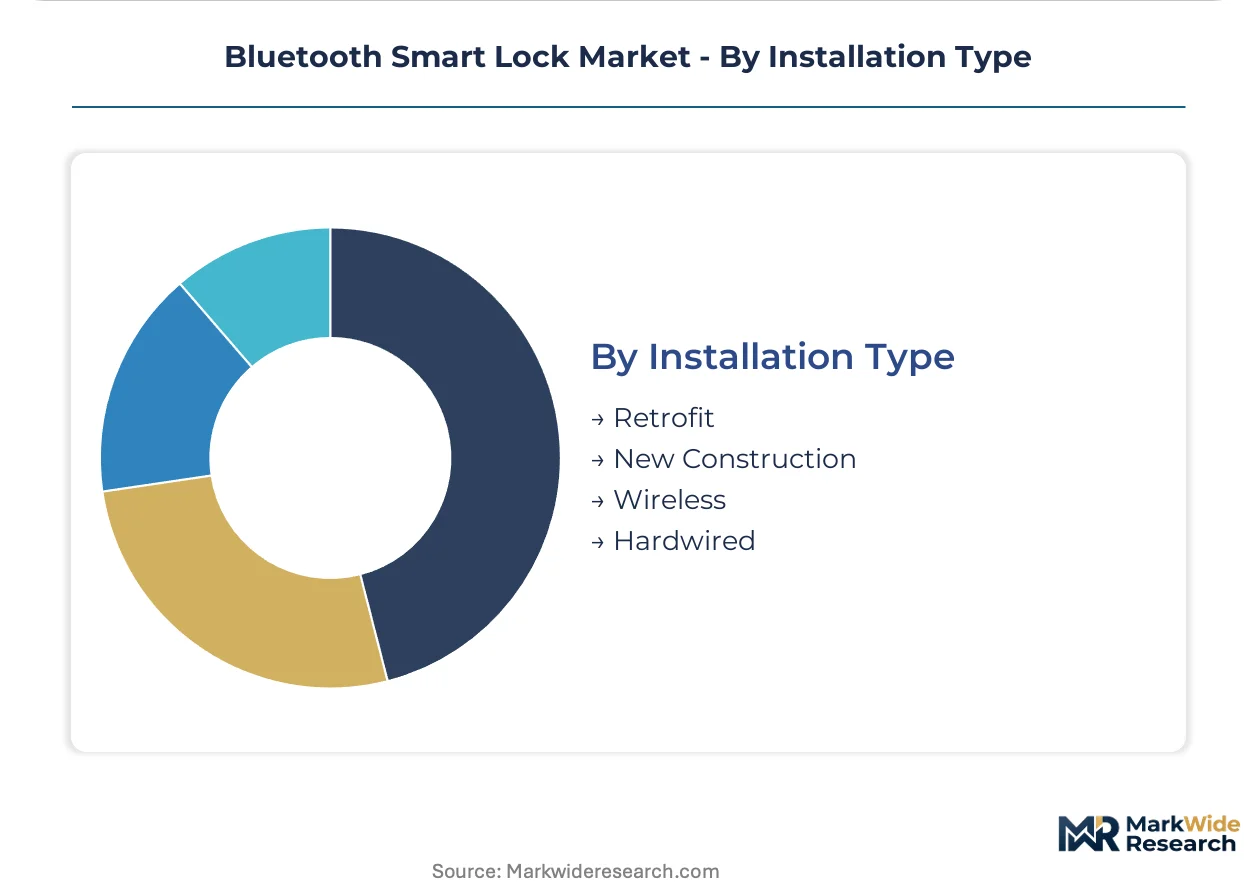
Deployment context determines integration complexity and margin structure, with retrofit installations requiring custom middleware development for legacy access control infrastructure while new construction enables clean-sheet specification.
- Retrofit:Replacement of existing mechanical cylinders without door modification, demanding backward compatibility with legacy strike plates and face bore dimensions. Middleware development for existing badge-reader infrastructure in United States commercial buildings creates implementation bottlenecks that extend project timelines.
- New Construction:Pre-wired and pre-drilled installations specified during architectural design phases. High-velocity construction corridors in India—specifically Mumbai and Bangalore urban housing developments—are creating first-mover advantages for mobile credential platforms that establish specification lock-in.
- Wireless:Battery-powered standalone units avoiding electrical rough-in requirements.
- Hardwired:PoE or low-voltage connected locks with continuous power and networked status monitoring.
New Construction commands specification influence. Retrofit dominates installed base expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools for embedded systems security and BLE firmware development concentrate in specific metropolitan clusters, anchoring regional competitive advantages for smart lock manufacturing and platform development.
United States
Multi-family housing operators in Texas and Florida metropolitan corridors are consolidating procurement around enterprise-grade keyless entry platforms. The Federal Communications Commission regulates 2.4 GHz emissions standards for Bluetooth Low Energy devices, normalizing protocol interoperability across North American installations. Austin and Miami housing development clusters are driving specification lock-in for mobile credential platforms that span thousands of units.
Germany
Commercial building specification teams prioritize cybersecurity certification above hardware cost in sourcing decisions for connected door hardware. The European Union's Radio Equipment Directive mandates interoperability and encryption standards that extend product development cycles. Munich and Frankfurt engineering centers anchor SALTO Systems' hospitality portfolio penetration across European Union member states.
China
Semiconductor fabrication clusters for fingerprint sensors and BLE system-on-chip modules expose supply chains to concentrated lead time dependencies. The Ministry of Industry and Information Technology oversees GB standards for radio frequency equipment and IoT security certification. Shenzhen and Dongguan manufacturing corridors supply component modules to global lock assembly operations.
India
Urban housing development in Mumbai and Bangalore corridors is creating first-mover advantages for mobile credential platforms in multi-family construction. The Bureau of Indian Standards implements electromagnetic compatibility requirements for wireless locking devices. Hyderabad and Pune technology campuses are emerging as firmware development hubs for residential access control systems.
United Kingdom
Coworking facility operators and flexible office providers are generating demand for audit-trail-enabled access systems with time-based permissions. The Information Commissioner's Office enforces data protection standards for biometric template storage in connected devices. London and Manchester property technology clusters are piloting Apple Wallet and Google Wallet credential convergence in mixed-use developments.
Bluetooth Smart Lock Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: diversified security conglomerates with broad access control portfolios, pure-play smart home specialists leveraging direct-to-consumer channels, and European commercial access control platforms with recurring software subscription models. Competitive moves center on strategic partnerships with mobile wallet platforms and vertical integration into firmware development capabilities.
Within the diversified conglomerate tier, ASSA ABLOY and Allegion plc represent integrated security hardware manufacturers with multi-brand portfolios spanning residential and commercial applications. SALTO Systems, S.L. exemplifies the European specialist archetype with hospitality-focused mobile credential platforms. Samsung Electronics Co., Ltd. occupies a position as a technology conglomerate leveraging consumer electronics distribution scale for residential smart home penetration.
| Leading Market Players |
|---|
| ASSA ABLOY |
| Allegion plc |
| Honeywell International Inc. |
| Samsung Electronics Co., Ltd. |
| Spectrum Brands |
| SALTO Systems, S.L. |
| dormakaba Group |
| August Home |
| Yale |
| Others |
Pricing and Supply Chain Analysis
Biometric sensor miniaturization is compressing hardware costs for mid-tier residential locks while simultaneously concentrating component sourcing around Shenzhen and Dongguan manufacturing corridors. This dual effect reshapes margin structures across authentication tiers and amplifies pricing power for vendors with captive firmware development capabilities.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive economics in Bluetooth smart lock procurement. Hardware-plus-subscription models dominate commercial segments, with recurring software attach rates generating margin pools that offset commoditizing mechanical components. Price differentiation hinges on cybersecurity certification tier and volume scale commitments from portfolio operators. Pricing pressure stems from semiconductor cost compression in fingerprint modules, though AES-128 encryption compliance costs partially offset this. Single-family retrofits exhibit highest price sensitivity, while multi-family operators with enterprise-grade platforms prioritize certification above unit cost.
Supply Chain Analysis
Freight cost volatility from East Asia has elevated inventory carrying costs for North American and European assembly operations. BLE system-on-chip modules and capacitive fingerprint sensors concentrate fabrication in China, Taiwan, and South Korea. Raw material dependencies span lithium-ion cells for battery packs, rare earth elements for sensor magnets, and copper for antenna substrates. Single-source vulnerability in BLE controller silicon exposes lead times to foundry allocation decisions. Distribution runs through direct manufacturer relationships with national property management groups, bypassing traditional locksmith channels in high-volume corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bluetooth smart lock market functions as a stable compounder, with multi-family housing digitization providing durable demand visibility across construction cycles.
For Market Incumbents: Extend platform stickiness through deeper mobile wallet integration and captive firmware development capabilities. Consolidate vendor relationships with Sun Belt portfolio operators before emerging entrants establish specification lock-in. Counter semiconductor supply concentration risk through dual-sourcing qualification programs for BLE controller silicon. For New Entrants and Emerging Players: The mid-tier price gap between premium biometric units and economy keyless-entry locks offers white-space entry for liveness-enabled fingerprint modules at standard-tier positioning. Target India multi-family construction corridors in Mumbai and Bangalore where first-mover mobile credential platforms can establish architectural lock-in. Pursue direct-to-consumer distribution through smartphone-native wallet integrations that bypass incumbent locksmith networks. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play firmware specialists with hospitality-focused mobile credential platforms and recurring SaaS attach rates. Long-term viability centers on cybersecurity engineering talent density and EU AI Act conformity assessment completion. Monitor Apple Wallet and Google Wallet credential convergence timelines as inflection indicators for distribution channel disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Wallet Platform Integration | Apple Wallet and Google Wallet credential convergence opens direct-to-consumer channels bypassing locksmith networks. |
| EU AI Act Conformity Assessment | Algorithmic transparency documentation for biometric modules creates certification-based vendor selection filters in European commercial installations. |
| Backward Integration into Firmware Development | In-house BLE stack and encryption protocol control differentiates enterprise-grade platforms from commodity hardware assemblers. |
| Multi-Family Portfolio Standardization | Single-platform keyless entry deployments across thousands of units justify software subscription investments and compress vendor selection cycles. |
| India Market Entry Partnership | Urban housing development in Mumbai and Bangalore corridors creates first-mover advantages for mobile credential specification lock-in. |
Research Methodology
Direct dialogue with smart lock hardware engineers, multi-family property technology directors, commercial access control specification consultants, and mobile wallet platform integration specialists grounded qualitative findings. Secondary validation drew from FCC equipment authorization databases, EU Radio Equipment Directive conformity assessments, Bluetooth SIG member filings, and property management software vendor disclosures. Bottom-up unit economics triangulated against top-down construction permitting data across Sun Belt metropolitan statistical areas.
Segmented outputs across product type, authentication technology, end-user vertical, and installation context informed the analytical framework throughout the projection horizon. CAGRs derived from housing starts velocity, multi-family operator consolidation patterns, and mobile credential adoption curves. Industry-specific inputs included BLE module cost trajectories, fingerprint sensor yield improvements, and cybersecurity certification timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for biometric liveness detection algorithms or mobile wallet platform exclusivity arrangements would alter the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Wireless Security System Market
Access Control Systems
Border Security System Market
Access Control Systems
Global Home Security Systems Market
Access Control Systems
Industrial Barrier Systems Market
Access Control Systems
Access Control and Authentication Market
Access Control Systems
Global Keyless Vehicle Access Control Systems Market
Access Control Systems
Europe Cylinder Lock Market
Access Control Systems
Italy Access Control Market
Access Control Systems
Europe Access Control Software Market
Access Control Systems
Japan Smart Lock Market
Access Control Systems
Mode Locking Device Market
Access Control Systems
Middle East and Africa Proximity Access Control Market
Access Control Systems
Canada Access Control Market
Access Control Systems
Asia-Pacific Pin-Based Access Control Market
Access Control Systems
Smart Door Lock Market
Access Control Systems
Global Commercial Security System Market