
 US Mass Notification Systems Market | 2026-2036
US Mass Notification Systems Market Size, Share, and Industry Trends Forecast 2026-2036
US Mass Notification Systems Market Intelligence
Platform licensing revenue is tilting toward cloud-hosted subscription models as agencies replace capital-intensive on-premises installations. Everbridge, Inc. leverages its IPAWS aggregation certification to anchor federal and state-level contracts. Motorola Solutions, Inc. sustains competitive positioning through deep integration with existing public-safety radio infrastructure. OnSolve, LLC specializes in weather-hazard correlation engines that differentiate its threat-intelligence layer from commodity alerting.
Mass notification systems are integrated communication platforms that disseminate time-critical alerts across multiple channels including SMS, email, voice calls, desktop pop-ups, and digital signage, typically achieving delivery confirmation within seconds to minutes depending on network topology and endpoint density. These systems serve primarily to coordinate emergency response, protect personnel assets, and maintain operational continuity during severe weather, active threats, or infrastructure failures. Wireless and SMS technologies dominate transaction volume due to near-universal mobile penetration, while cloud-based deployment captures the fastest expansion as municipal IT departments outsource infrastructure maintenance and disaster-recovery obligations. Government and education end users represent the most mature procurement segments with established bidding protocols, whereas healthcare manufacturing applications show emergent demand as workplace-safety regulations tighten.
FCC enforcement of wireless emergency alert technical standards and FEMA's IPAWS certification requirements directly determine vendor eligibility for public-sector contracts. OSHA workplace-emergency preparedness directives and state-level school-safety mandates in California, Texas, and Florida compound compliance-driven procurement cycles. Buyers must evaluate vendor IPAWS readiness, state-level certification reciprocity, and multi-tenant cloud architecture resilience before committing to decade-long service agreements.
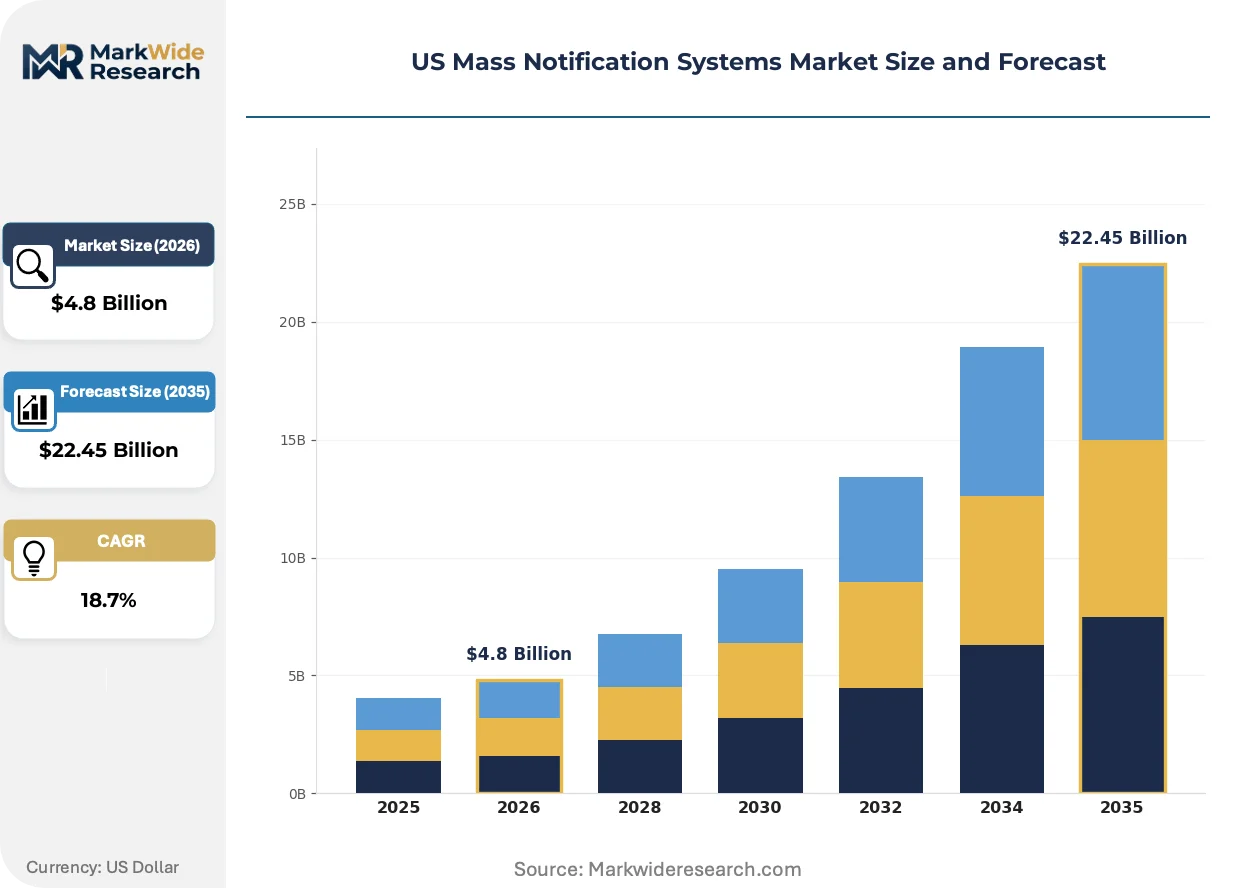
Market Dynamics
Cloud migration is collapsing the traditional capital-expenditure model for public-safety alerting infrastructure, forcing municipal IT departments to renegotiate decade-long service relationships and requalify vendors around FEMA IPAWS certification reciprocity rather than hardware durability benchmarks.
Growth Catalysts
- FEMA IPAWS certification mandates:Federal procurement rules now require IPAWS aggregation capability for all new mass notification contracts, disqualifying legacy on-premises vendors from state and municipal RFPs.
- K-12 school safety statutes:California, Texas, and Florida have enacted binding multi-channel alert requirements for district-wide emergency response, creating recurring subscription revenue pools.
- Wildfire and hurricane exposure clusters:Municipalities in high-frequency hazard zones are consolidating fragmented paging and SMS systems into unified platforms with automated weather-hazard correlation.
Market Restraints
- Telecom carrier dependency:SMS throughput and delivery confirmation reliability hinge on tier-one carrier peering agreements, creating single-point-of-failure risk during network congestion events.
- Legacy radio infrastructure lock-in:Public-safety agencies with Motorola ASTRO 25 or P25 trunked systems face switching costs that delay cloud-platform adoption by 3-5 replacement cycles.
- FCC wireless emergency alert technical standards:Device-level compatibility testing imposes 12-18 month certification timelines that compress vendor R&D runway and delay feature releases.
Strategic Opportunities
- Healthcare workplace-safety compliance:OSHA emergency preparedness directives for hospital campuses and manufacturing facilities are extending mass notification procurement beyond traditional government and education verticals.
- AI-powered threat-intelligence layering:Correlation engines that fuse NOAA weather data with active-shooter detection sensors are creating premium pricing tiers distinct from commodity alerting.
- Texas and Florida municipal consolidation:County-level emergency management districts are centralizing procurement for unincorporated areas, favoring vendors with multi-tenant cloud architecture and state-level certification reciprocity.
Industry Challenges
- IPAWS certification backlog:FEMA's testing queue for new aggregator platforms extends vendor time-to-revenue by 8-14 months, straining cash flow for mid-tier competitors.
- Interoperability with legacy paging systems:School districts and hospitals maintaining analog overhead paging require custom gateway development that fragments engineering resources and delays cloud-native feature parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Mass Notification Systems Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wireless, SMS, Email, Social Media End User: Government, Education, Healthcare, Manufacturing Application: Emergency Response, Event Management, Public Safety, Disaster Recovery Deployment: Cloud-Based, On-Premises, Hybrid, Mobile |
| Companies Covered | Everbridge, Inc., Motorola Solutions, Inc., OnSolve, LLC, Honeywell International Inc., Singlewire Software, LLC, Alertus Technologies, LLC, AlertMedia, Inc., Rave Mobile Safety, Federal Signal Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Mass Notification Systems Market Strategic Shifts & Innovations
Platform architectures are converging around API-first design patterns that enable third-party sensor integration, while regulatory pressure accelerates the displacement of hardware-centric delivery models.
Multi-tenant cloud architectures are collapsing the distinction between emergency alerting and routine operational communication, enabling K-12 districts and university campuses to consolidate snow-day notifications, IT outage alerts, and active-threat warnings onto unified subscription platforms. California school districts are retiring CapEx-intensive on-premises installations in favor of elastic consumption models that scale seat-counts seasonally.
FCC enforcement of wireless emergency alert technical standards is compressing device-certification timelines and forcing handset manufacturers to prioritize geo-targeting accuracy over broadcast range. Public-safety agencies in Texas and Florida are now specifying WEA 3.0 compatibility as a mandatory evaluation criterion, disqualifying vendors with legacy gateway dependencies.
Subscription pricing is displacing perpetual licensing across municipal procurement, with California and Florida emergency management departments now requiring SaaS terms with automatic disaster-recovery failover. State-level cooperative purchasing agreements are aggregating demand from smaller districts, concentrating contract awards with IPAWS-certified platforms that demonstrate 99.99% uptime SLAs.
US Mass Notification Systems Market Segmentation
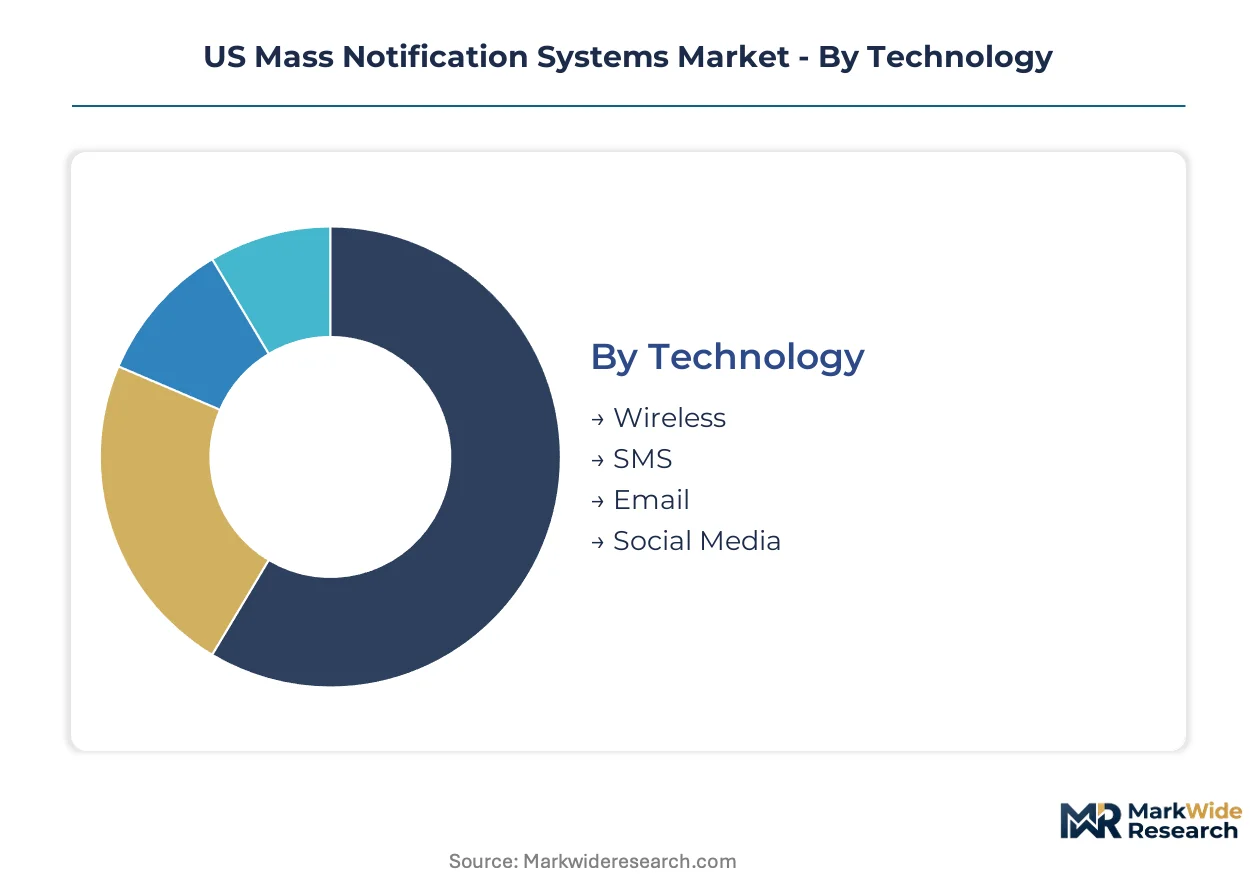
Mass notification procurement varies sharply by operational context, with federal certification requirements and hazard-exposure profiles driving technology selection. Segmentation reveals how cloud migration, regulatory mandates, and end-user risk tolerance reshape vendor competitive positioning across distinct deployment scenarios.
Technology:
The use-case spectrum spans from instantaneous mobile alerts to persistent social-media monitoring, with delivery speed and confirmation reliability determining channel priority.
- Wireless:Cellular broadcast infrastructure enables location-targeted alerts without subscriber opt-in, achieving sub-minute penetration in dense urban corridors. Texas and Florida emergency management districts specify wireless emergency alert compatibility as mandatory for county-level contracts, with FEMA IPAWS certification gating vendor eligibility.
- SMS:Text messaging leverages universal handset penetration but depends on tier-one carrier peering agreements for throughput during congestion events. California K-12 districts favor SMS for its audit trail and delivery confirmation, though carrier dependency creates single-point-of-failure exposure during seismic events.
- Email:Enterprise messaging integrates with identity management systems for role-based targeting in university and hospital campuses.
- Social Media:Platform-native alerting extends reach to unregistered populations but sacrifices delivery confirmation and control over timing.
Established volume favors Wireless; emerging adoption favors Social Media.
End User:
Cost tier stratification separates federally subsidized public-sector deployments from self-funded private installations.
- Government:Municipal and state agencies operate under FEMA IPAWS aggregation mandates that disqualify uncertified platforms from federal reimbursement eligibility. Procurement concentrates in California, Texas, and Florida where wildfire, hurricane, and seismic exposure justify multi-channel system investment.
- Education:K-12 districts and university campuses represent mature procurement segments with established cooperative purchasing agreements and binding multi-channel alert statutes in hazard-prone states. Seat-count elasticity drives preference for cloud-hosted subscription models over capital-intensive on-premises hardware.
- Healthcare:Hospital campuses face OSHA emergency preparedness directives that extend notification requirements beyond traditional fire-code compliance into workplace violence and severe weather protocols.
- Manufacturing:Industrial facilities show emergent demand as process-safety management regulations tighten and distributed workforces require coordinated evacuation protocols.
Procurement maturity favors Government; regulatory tailwinds favor Healthcare.
Application:
Application type dictates integration depth with external sensor networks and automated trigger mechanisms.
- Emergency Response:Active-threat and medical-emergency workflows demand sub-second initiation with automatic escalation chains, requiring deep integration with access control and video surveillance systems. Campus security departments in Texas and Florida specify shooter-detection sensor correlation as evaluation criterion.
- Public Safety:Severe weather and hazardous material releases trigger pre-scripted alerts correlated with NOAA data feeds and plume-dispersion modeling. County emergency management districts consolidate unincorporated area procurement around platforms with automated weather-hazard correlation engines.
- Event Management:Crowd-control and logistics coordination utilize lower-priority channels with scheduled delivery windows.
- Disaster Recovery:Business continuity alerts target IT infrastructure failover and supply-chain disruption with role-based contact trees.
System complexity favors Emergency Response; deployment frequency favors Public Safety.
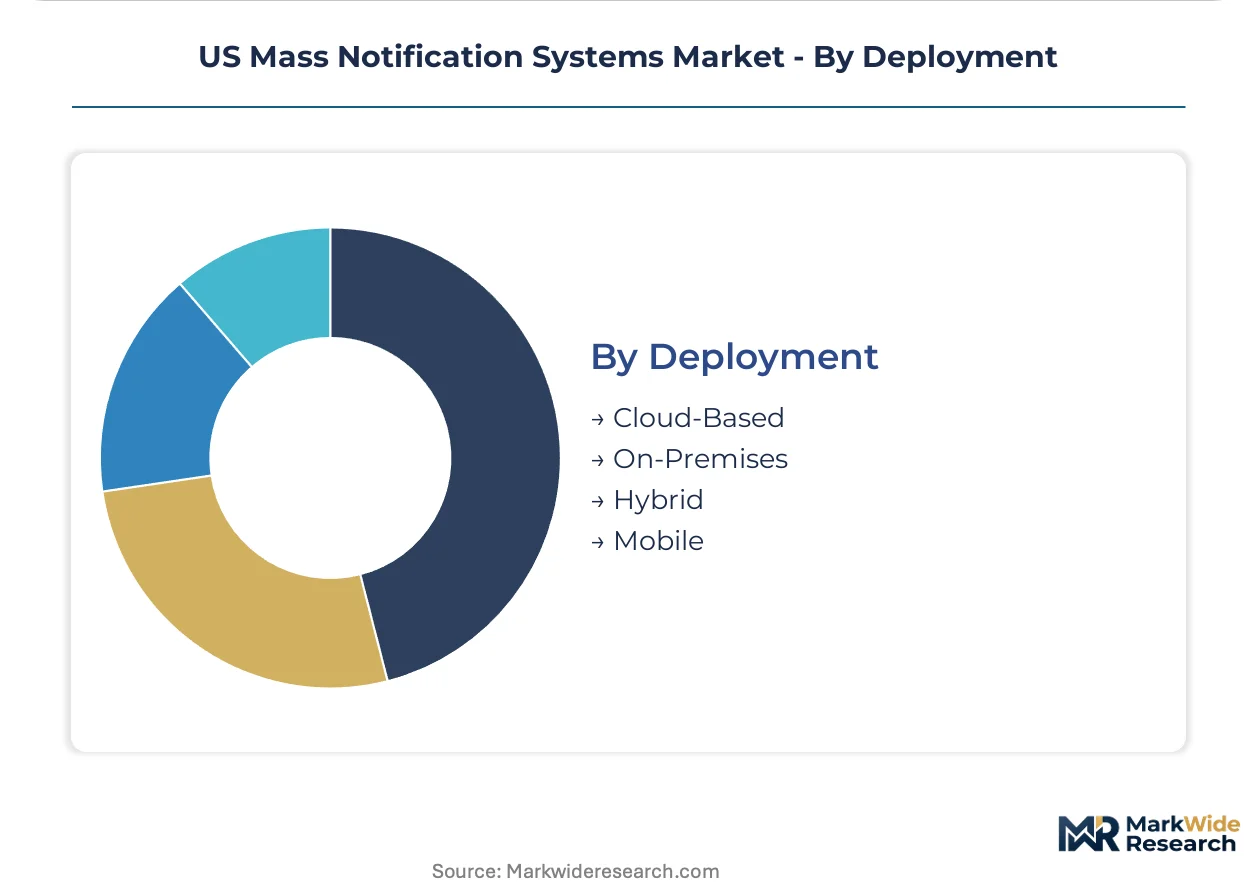
Deployment:
Customer IT resource availability and disaster-recovery obligation allocation determine architecture selection.
- Cloud-Based:Multi-tenant SaaS platforms outsource infrastructure maintenance and geographic failover to vendor-operated data centers, enabling seasonal seat-count scaling for academic calendars. California school districts lead migration away from capital-intensive on-premises installations toward elastic consumption models with 99.99% uptime SLAs.
- On-Premises:Legacy hardware installations persist where air-gapped security or specialized radio integration requirements override cloud economics. Public-safety agencies with Motorola ASTRO 25 trunked systems face switching costs that delay replacement by multiple procurement cycles.
- Hybrid:Split architectures preserve sensitive directory services on-site while leveraging cloud delivery for external channels.
- Mobile:Smartphone-native applications extend reach to field personnel without fixed workstation access.
Procurement momentum favors Cloud-Based; specialized integration favors Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor concentration clusters around federal certification hubs and state procurement centers where FEMA IPAWS compliance gates contract eligibility. California, Texas, and Florida dominate public-sector deployment volume due to concentrated hazard exposure and binding school-safety statutes.
California
Seismic risk and wildfire frequency drive K-12 district consolidation of fragmented paging systems into unified cloud platforms. The California Department of Education mandates multi-channel alert capability for district-wide emergency response under state school-safety statutes. Los Angeles Unified and San Diego County school districts anchor procurement volume, retiring capital-intensive on-premises installations for elastic subscription models.
Texas
Hurricane exposure and county-level emergency management consolidation fuel demand for automated weather-hazard correlation engines. The Texas Division of Emergency Management requires IPAWS aggregation certification for all municipal alert contracts. Houston-Galveston and Dallas-Fort Worth metro areas concentrate deployment, with county districts centralizing procurement for unincorporated jurisdictions.
Florida
High-frequency hurricane landfalls and state-level school-safety mandates create recurring subscription revenue pools for certified platforms. Florida Department of Education rules bind districts to multi-channel alert standards with specified delivery confirmation protocols. Miami-Dade and Broward County school districts lead migration toward cloud-hosted systems with 99.99% uptime SLAs.
New York
Urban density and critical infrastructure protection requirements drive enterprise and government adoption of layered alerting architectures. New York State Division of Homeland Security and Emergency Services coordinates procurement standards across municipal jurisdictions. New York City metro anchors deployment volume, integrating mass notification with existing public-safety radio networks.
Illinois
Manufacturing corridor workplace-safety regulations and healthcare campus emergency preparedness extend notification demand beyond traditional government verticals. Illinois Emergency Management Agency certifies platforms for state and local procurement eligibility. Chicago metropolitan area concentrates deployment, with hospital systems specifying OSHA-compliant multi-channel systems.
US Mass Notification Systems Market Key Industry Players
IPAWS-certified aggregators and legacy radio-integrated specialists split the market between cloud-native subscription platforms and infrastructure-hybrid deployments. Market structure tilts toward consolidation as federal certification requirements disqualify uncertified vendors from state and municipal RFPs. Three archetypes dominate: FEMA-certified cloud platforms, public-safety radio integrators, and threat-intelligence specialists. Competitive dynamics center on IPAWS certification reciprocity negotiations and multi-tenant cloud architecture resilience guarantees.
Within the certified-aggregator tier, Everbridge, Inc. and OnSolve, LLC exemplify cloud-native positioning anchored by federal aggregation credentials. Motorola Solutions, Inc. occupies a distinct infrastructure-integrator position, leveraging existing ASTRO 25 and P25 trunked system relationships to sustain competitive relevance during prolonged replacement cycles. These three companies represent the strategic poles—pure-play SaaS, radio-integrated hybrid, and weather-correlation specialization—around which mid-tier competitors must differentiate or exit.
| Leading Market Players |
|---|
| Everbridge, Inc. |
| Motorola Solutions, Inc. |
| OnSolve, LLC |
| Honeywell International Inc. |
| Singlewire Software, LLC |
| Alertus Technologies, LLC |
| AlertMedia, Inc. |
| Rave Mobile Safety |
| Federal Signal Corporation |
| Others |
Cost & Logistics Intelligence
Interstate data corridor freight costs from Northern Virginia cloud infrastructure hubs to Texas and Florida municipal data centers compress margins for on-premises hardware vendors while amplifying pricing power for SaaS platforms with distributed edge nodes. This logistics dynamic concentrates procurement leverage with multi-tenant cloud providers and forces legacy radio integrators into defensive bundling strategies.
Pricing Analysis
FEMA IPAWS certification mandates dictate the pricing tier structure across the US Mass Notification Systems Market, separating IPAWS-aggregated platforms from uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, with premium tiers commanding 40-60% spreads over economy offerings due to federal reimbursement eligibility. Cost compression in the standard tier is intensifying because county-level cooperative purchasing agreements aggregate demand and squeeze mid-tier vendors. K-12 school districts exhibit highest price sensitivity due to per-pupil funding constraints, while federal agencies show lowest sensitivity given disaster-preparediness budget insulation.
Supply Chain Analysis
Extended payment terms from tier-one cellular carriers and supply-chain finance facilities from cloud infrastructure vendors stabilize working capital for SaaS providers. Hardware component sourcing draws from Taiwan for semiconductor gateways, Mexico for radio equipment assembly, and domestic US facilities for ruggedized endpoints. Raw material dependencies center on rare earth elements for antenna systems, lithium-ion cells for backup power units, and specialized polymers for weatherproof enclosures. Single-source vulnerability concentrates in cellular modem chipsets from Qualcomm and MediaTek. Distribution runs through state-level cooperative purchasing agreements and GSA Schedule 70 contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
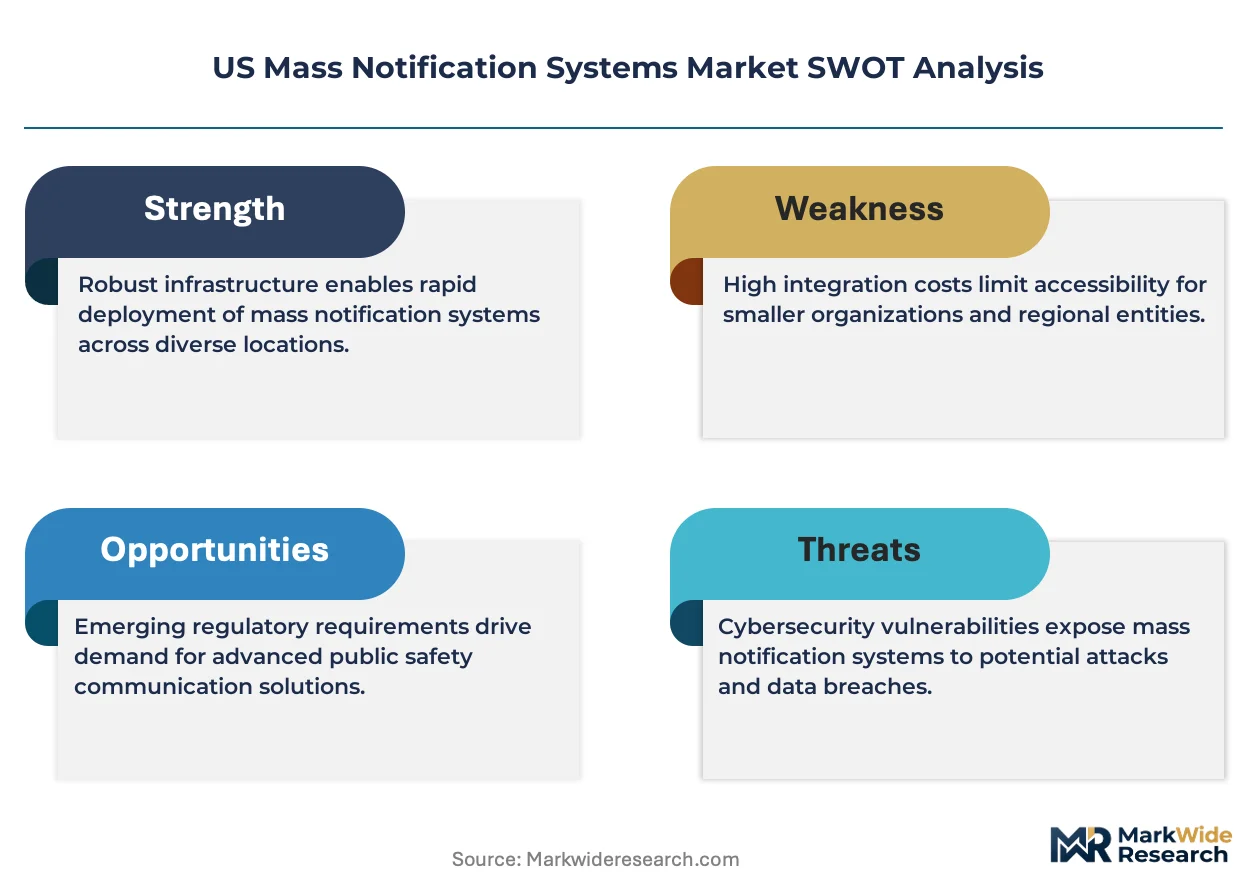
The US Mass Notification Systems Market operates as a regulatory-moat business where FEMA IPAWS certification creates network-effect lock-in that compounds with each municipal deployment. Switching costs escalate once agencies integrate multi-channel alerting with existing public-safety radio infrastructure.
For Market Incumbents: Entrench IPAWS certification reciprocity across state procurement frameworks to disqualify emerging competitors from RFP eligibility. Deepen integration with Motorola ASTRO 25 and P25 trunked systems to extend replacement cycle capture. Threat vector: AI-native threat-intelligence platforms could displace commodity alerting layers if sensor correlation becomes the primary evaluation criterion. Priority lever: vertical integration into weather-hazard data feeds from NOAA to anchor premium pricing tiers. For New Entrants and Emerging Players: Establish a beachhead in healthcare workplace-safety compliance where OSHA emergency preparedness directives extend addressable demand beyond saturated government verticals. White-space targets: hospital campuses in Illinois manufacturing corridors and distributed manufacturing facilities with process-safety management obligations. Most penetrable segment: mid-tier healthcare systems lacking dedicated emergency management staff. Go-to-market angle: outcome-based contracting tied to evacuation drill performance metrics rather than seat-count subscriptions. For Investors and Strategic Acquirers: Threat-intelligence specialists with NOAA data correlation engines and active-shooter sensor integration capabilities represent the most defensible acquisition archetype. Long-term viability hinges on regulatory entrenchment deepening through state-level school-safety mandate expansion. Signal to watch: Texas and Florida county-level emergency management district consolidation velocity as indicator of procurement concentration tipping points.| Strategic Initiative | Industry Significance |
|---|---|
| IPAWS Certification Investment | FEMA aggregation credentials gate federal reimbursement eligibility and state RFP participation. |
| Weather-Hazard Data Integration | NOAA correlation engines differentiate premium tiers from commodity alerting in hurricane-exposed markets. |
| Multi-Tenant Cloud Architecture | Elastic seat-count scaling captures K-12 district procurement shifting from CapEx to SaaS models. |
| Legacy Radio System Integration | Motorola ASTRO 25 and P25 trunked system compatibility sustains relevance during prolonged replacement cycles. |
| Healthcare Vertical Expansion | OSHA workplace-emergency preparedness directives extend addressable market beyond traditional government segments. |
Research Approach
The analysis maps cloud-hosted subscription platforms, on-premises hardware installations, hybrid architectures, and mobile-native applications, each validated through emergency management directors, K-12 district technology officers, university campus security chiefs, and healthcare facility safety managers. Primary interviews with municipal procurement specialists and state cooperative purchasing administrators combined with secondary validation against FEMA IPAWS certification databases, FCC wireless emergency alert technical standards filings, and state school-safety statute legislative records. Bottom-up deployment volume estimates triangulate with top-down budget allocation analysis across federal, state, and local emergency preparedness appropriations.
Assumptions held fixed include FEMA IPAWS certification mandate continuity, FCC wireless emergency alert technical standard enforcement intensity, and prevailing cellular carrier peering agreement structures. Variables tested across the analysis window encompass cloud migration velocity, K-12 district consolidation pace, and healthcare workplace-safety regulatory expansion. Segmentation dimensions modeled span technology channel, end-user vertical, application workflow, and deployment architecture. CAGR derivation rests on year-over-year procurement volume tracking and subscription renewal rate analysis. Industry-specific inputs include NOAA weather event frequency data and state-level school-safety mandate adoption timelines.
Sensitivities concentrate around FEMA certification backlog resolution speed, cellular network congestion during actual emergency events, and state budget stress impacts on education technology appropriations. Forecasts reflect documented assumptions regarding regulatory continuity and hazard exposure clustering. Macroeconomic contraction affecting municipal bond markets, regulatory deviation from IPAWS aggregation requirements, or technological disruption from satellite-based alerting alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Global Wireless Broadband in Public Safety Market
Public Safety
Global Public Safety Solution for Smart City Market
Public Safety
Crime Risk Report Market
Public Safety
Global Public Safety Analytics Market
Public Safety
Europe Road Safety Market
Public Safety
Voice Evacuation Systems Market
Public Safety
Global Public Safety in Building Wireless Das System Market
Public Safety
Asia-Pacific Public Safety Market
Public Safety
Latin America Public Safety Market
Public Safety
Europe Public Infrastructure Safety Market
Public Safety
Public Safety Market
Public Safety
Counter Terror and Public Safety Technology Market
Public Safety
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market
Public Safety
Europe Wireless Broadband in Public Safety Market
Public Safety
Global IoT for Public Safety Market
Public Safety
Safe City Market