
 Asia-Pacific Access Control Hardware Market | 2026-2036
Asia-Pacific Access Control Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Access Control Hardware Market Outlook
Cloud-native access management architectures is reshaping how hardware vendors design edge-to-core connectivity for biometric and mobile credential systems. ASSA ABLOY leverages its integrated lock and reader portfolio to sustain premium positioning across Australian commercial developments. Siemens AG anchors large-scale government and transportation installations through engineered system integration capabilities. dormakaba Group specializes in modular door hardware that competes on interoperability with third-party software platforms.
Asia-Pacific access control hardware comprises electromechanical and electronic devices—encompassing card readers, biometric scanners, control panels, and electric locking mechanisms—that authenticate credentials and manage physical entry points through configurable permission protocols. These systems typically operate on 12-24V DC power, communicate via Wiegand or OSDP protocols, and integrate with building management software to log timestamped entry events for audit compliance. Biometrics and mobile access technologies are capturing disproportionate investment as enterprises replace legacy card-based systems, while RFID retains volume dominance in cost-sensitive residential and mid-market commercial deployments across the region. Facial recognition modules command premium pricing in government and financial institution applications where contactless authentication reduces throughput friction.
China's GB standards for biometric data security, South Korea's MFDS guidelines for healthcare facility access protocols, and Australia's Privacy Act constraints on facial recognition storage collectively elevate product certification burdens and reshape vendor go-to-market requirements. BIS in India and Japan's METI further fragment compliance landscapes, forcing regional players to maintain multiple product variants or partner with local certification specialists. Stakeholders must weigh hardware-versus-software margin trajectories as platform economics shift value capture toward recurring license models and away from one-time device sales.
Market Dynamics
Cloud-native access management architectures are compressing hardware margins while redistributing value toward recurring software licenses across biometric and mobile credential systems.
Growth Catalysts
- Smart city infrastructure mandates:Southeast Asian metropolitan centers are accelerating biometric reader deployment in commercial complexes as urban digitization programs expand.
- BIS certification requirements:India's mandatory testing protocols for electronic security equipment are compelling manufacturers to upgrade quality assurance processes.
- Facial recognition integration:China's tier-one cities now specify contactless authentication systems as standard in building security procurements.
Market Restraints
- Semiconductor input volatility:Control panel manufacturers face margin pressure from fluctuating availability of specialized microcontrollers sourced from concentrated East Asian foundries.
- Biometric data localization rules:China's GB standards and Australia's Privacy Act impose conflicting storage requirements that fragment product architectures.
- Legacy RFID retention:Cost-sensitive residential segments across Indonesia and Vietnam continue specifying card-based systems despite biometric availability.
Strategic Opportunities
- Healthcare facility modernization:South Korea's MFDS guidelines for hospital access protocols are creating specification windows for infection-control-compliant contactless systems.
- Mobile credential convergence:Integration of smartphone-based authentication with existing Wiegand infrastructure opens retrofit pathways in Australia's aging commercial building stock.
- OSDP protocol migration:Encrypted communication standards adoption is enabling hardware vendors to capture security-upgrade budgets from government and financial institution buyers.
Industry Challenges
- Multi-jurisdiction certification timelines:Vendors must navigate parallel BIS, METI, and GB standard approval processes that extend product launch cycles.
- Legacy system integration complexity:Biometric retrofit projects require specialized engineering to interface with existing electric locking mechanisms and building management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Access Control Hardware Market |
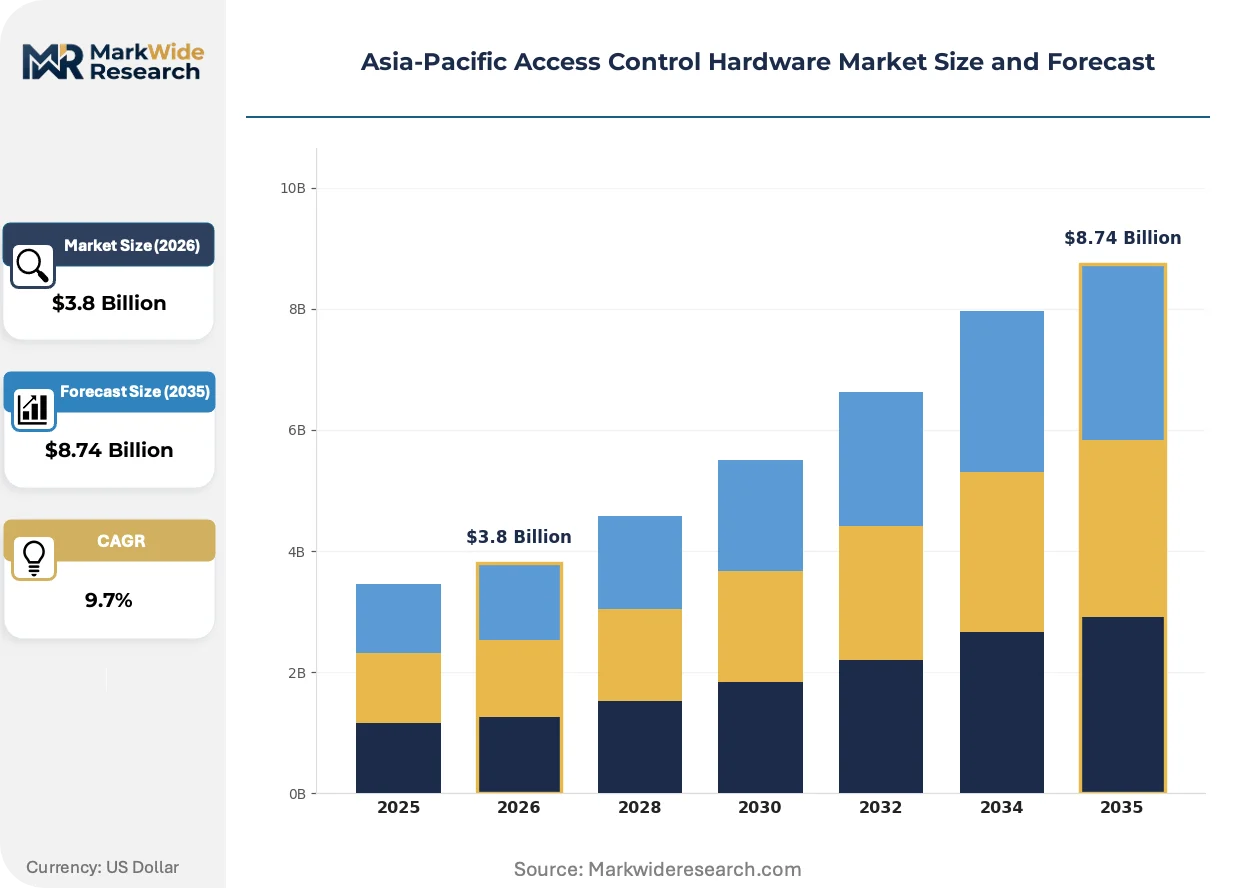
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Card Readers, Keypads, Biometrics, Controllers Application: Commercial, Residential, Government, Industrial Technology: RFID, Facial Recognition, Fingerprint, Mobile Access End User: Enterprises, Retailers, Educational Institutions, Healthcare |
| Companies Covered | ASSA ABLOY, Siemens AG, Bosch Security Systems GmbH, Schneider Electric SE, dormakaba Group, Suprema, Inc., Honeywell International, Inc., Hanwha Vision Co., Ltd., Johnson Controls International PLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Access Control Hardware Market Strategic Shifts
Biometric authentication modalities are displacing credential-based entry systems through hardware-software convergence that redefines how physical security integrates with enterprise IT infrastructure.
Multi-modal biometric readers combining facial recognition with palm vein scanning are digitizing identity verification workflows in high-throughput environments. Financial institutions and transportation hubs across Singapore and Hong Kong are deploying these systems to reduce authentication friction. The technology is digitizing traditional access control hardware into networked edge devices that stream encrypted biometric templates to cloud-based policy engines.
Japan's METI has issued updated guidelines for personal data protection in commercial security systems that mandate encryption standards for biometric template storage. Hardware manufacturers must now embed secure element chips that comply with these specifications or face exclusion from public sector tenders. Healthcare and government facility projects in Tokyo and Osaka are experiencing procurement delays as vendors recertify products.
Enterprise buyers are consolidating vendor relationships around integrated platform providers rather than assembling hardware from multiple suppliers. Large commercial developers in Sydney and Melbourne now specify single-source accountability for access control, video management, and intrusion detection. This concentration is most visible in Australia's premium office segment where facilities managers prioritize unified service level agreements over component cost optimization.
Asia-Pacific Access Control Hardware Market Segmentation
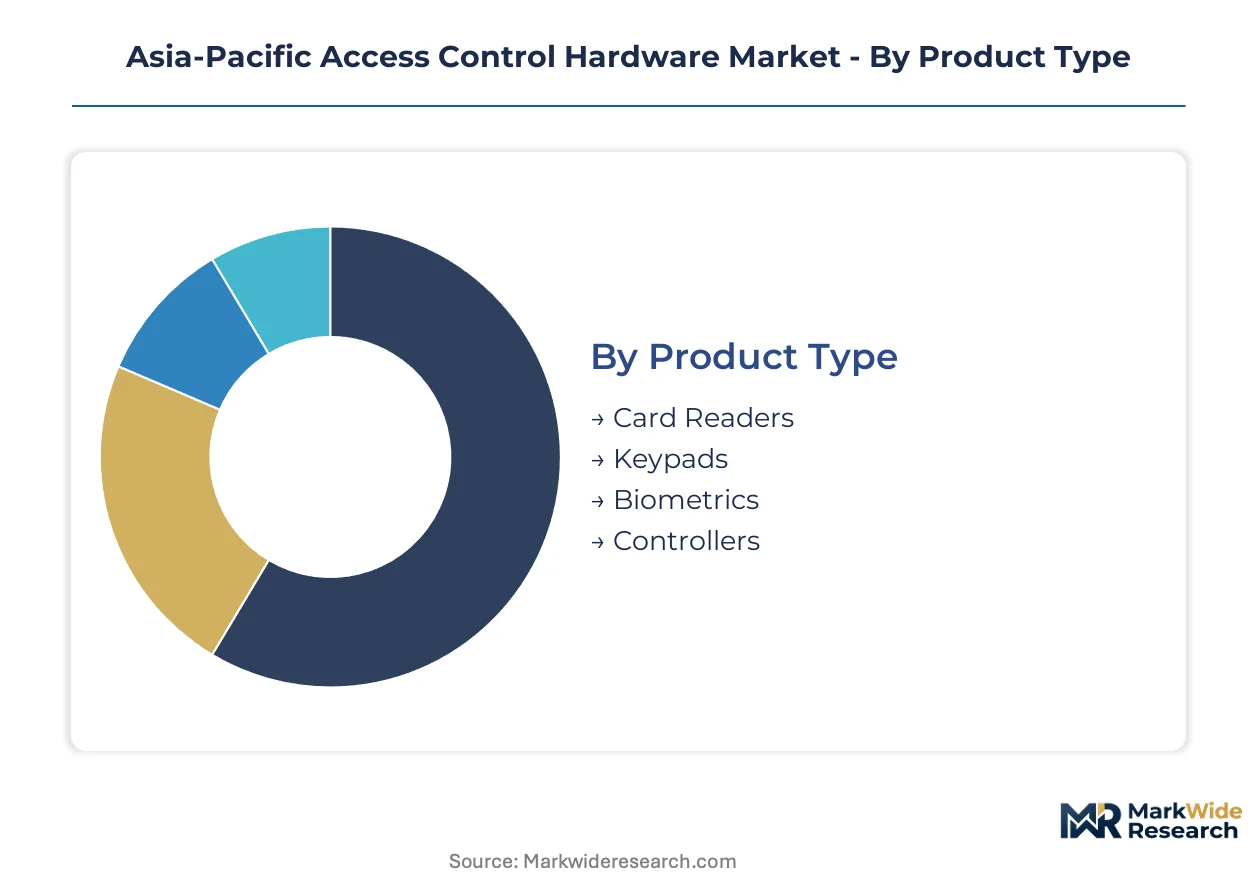
Segmentation of Asia-Pacific access control hardware reveals divergent technology lifecycles and procurement priorities across product architectures, deployment contexts, and authentication modalities. Understanding these fault lines enables vendors to align R&D investment with specification trends in tier-one cities versus cost-sensitive secondary markets.
Product Type:
Mature electromechanical formats coexist with emerging biometric platforms across the region's procurement landscape.
- Card Readers:Wiegand and OSDP-compatible readers process proximity and smart card credentials through 125kHz or 13.56MHz frequencies. Indonesia's residential developers and Vietnam's mid-market commercial builders specify these units for cost-controlled installations where legacy infrastructure dominates.
- Keypads:PIN-entry devices with tactile or capacitive interfaces provide standalone authentication for low-security zones. Australia's aging commercial building stock retains keypad systems in secondary access points where upgrade budgets remain constrained.
- Biometrics:Fingerprint, facial, and palm vein scanners embed optical or capacitive sensors with liveness detection algorithms. China's tier-one cities mandate biometric readers for government and financial institution procurements under GB standards compliance requirements.
- Controllers:Edge computing devices manage credential verification, door relay switching, and event logging for 4-32 door configurations. South Korean hospital modernization projects under MFDS guidelines specify infection-control-compliant controller enclosures with antimicrobial coatings.
Card readers retain volume leadership; biometrics holds the steepest expansion curve.
Application:
Cost tier stratification separates premium integrated systems from economy standalone deployments.
- Commercial:Multi-tenant office complexes and retail centers deploy networked access systems with centralized credential management. Singapore's financial district and Hong Kong's commercial towers specify facial recognition integration for lobby throughput optimization.
- Residential:Apartment buildings and gated communities prioritize RFID card systems with optional mobile credential add-ons. Cost sensitivity across Indonesia and the Philippines sustains demand for standalone keypad and card reader combinations.
- Government:Public sector facilities require certified biometric storage with encrypted template protection. Japan's METI guidelines and China's GB standards impose divergent data localization requirements that fragment product specifications.
- Industrial:Manufacturing plants and logistics hubs demand ruggedized readers with IP65+ ratings and wide temperature operating ranges. Australia's mining sector and Thailand's automotive manufacturing corridors specify heavy-duty electromechanical locking with biometric override capabilities.
Commercial applications command the highest per-door spend; residential represents the largest unit volume base.
Technology:
Authentication modalities are concentrating around contactless formats as hygiene protocols reshape procurement criteria.
- RFID:Proximity and contactless smart cards communicate via electromagnetic induction with reader coils. Volume dominance persists across Southeast Asia's cost-sensitive residential and small commercial segments despite biometric availability.
- Facial Recognition:3D structured light and time-of-flight cameras capture facial geometry for template matching. China's building security procurements now specify contactless facial authentication as standard in tier-one metropolitan centers.
- Fingerprint:Capacitive and optical sensors capture ridge patterns with anti-spoofing liveness detection. South Korea's MFDS healthcare guidelines and India's BIS certification requirements drive fingerprint reader upgrades in hospital and clinic environments.
- Mobile Access:Smartphone-based credentials using Bluetooth Low Energy or NFC replace physical cards in retrofit scenarios. Australia's commercial developers integrate mobile access with existing Wiegand infrastructure to extend system lifecycles.
RFID retains installed base dominance; facial recognition is gaining specification share fastest.
End User:
Customer type determines integration complexity and service level agreement requirements.
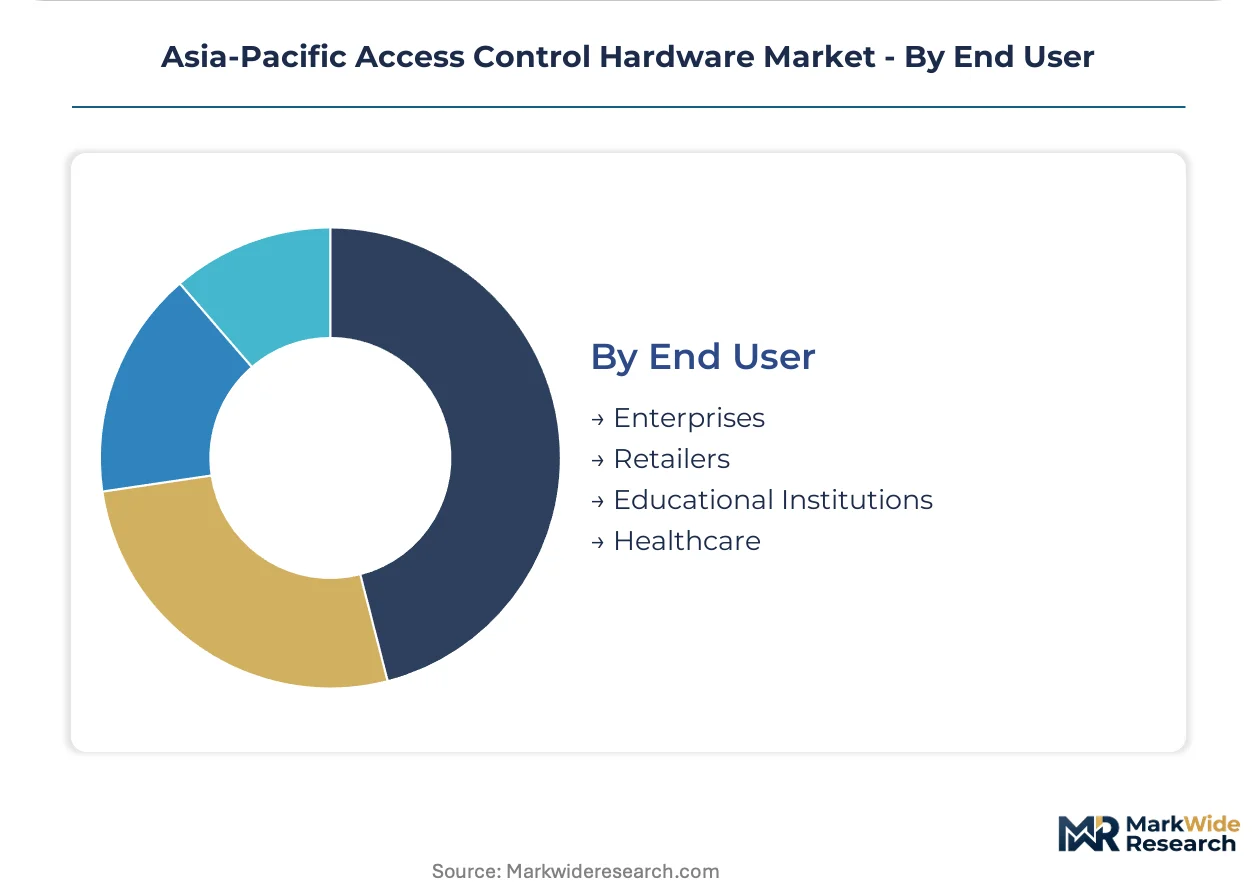
- Enterprises:Corporate campuses require unified access platforms with HR system integration and visitor management workflows. Large commercial developers in Sydney and Melbourne consolidate vendor relationships around single-source accountability for multi-site deployments.
- Retailers:Store chains prioritize rapid deployment and centralized monitoring across distributed locations. Franchise operators across Thailand and Malaysia specify cloud-managed readers to reduce on-site IT infrastructure.
- Educational Institutions:Universities and K-12 campuses balance open accessibility with controlled zone isolation. Student credential programs in Japan and South Korea increasingly incorporate mobile access to reduce card replacement costs.
- Healthcare:Hospitals and clinics demand infection-control-compliant contactless authentication with audit trail integration for regulatory compliance. Tokyo and Osaka facilities face procurement delays as vendors recertify products under updated METI encryption guidelines.
Enterprises drive premium system integration; healthcare represents the fastest-expanding specification segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports access control hardware to Southeast Asian smart city developers, while South Korean biometric component manufacturers supply Japanese integrators serving healthcare modernization programs. Cross-border certification reciprocity remains limited, forcing vendors to maintain parallel compliance tracks.
China
Tier-one cities mandate facial recognition integration in government and financial building procurements under GB standards. MIIT enforces data localization requirements for biometric template storage that fragment cloud-native architectures. Shanghai and Shenzhen clusters concentrate domestic manufacturing capacity for control panels and electric locking mechanisms.
Japan
Healthcare facilities drive contactless authentication specifications under updated METI encryption guidelines. METI mandates secure element chips for biometric template protection in commercial security systems. Tokyo and Osaka procurement cycles face delays as vendors recertify products for public sector tenders.
South Korea
Hospital modernization projects under MFDS guidelines specify infection-control-compliant controller enclosures with antimicrobial coatings. MFDS protocols for healthcare facility access reshape product testing requirements for biometric readers. Seoul Capital Area developers consolidate single-source vendor relationships for integrated security platforms.
Australia
Premium commercial developments in Sydney and Melbourne specify unified service level agreements covering access control, video management, and intrusion detection. Privacy Act constraints on facial recognition storage limit cloud deployment options for multinational vendors. Mining sector demand in Western Australia drives ruggedized reader specifications with IP65+ ratings.
India
BIS certification mandates for electronic security equipment compel manufacturers to upgrade quality assurance processes for control panel exports. BIS testing protocols extend product launch timelines for foreign suppliers entering government tenders. Maharashtra and Karnataka industrial corridors concentrate domestic assembly operations for card readers and keypads.
Asia-Pacific Access Control Hardware Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement channels. ASSA ABLOY and dormakaba Group anchor integrated hardware portfolios through specification relationships with large commercial developers. Siemens AG and Honeywell International occupy engineered system integration positions in government and transportation verticals. Strategic moves concentrate on M&A for biometric software capabilities and partnerships with local certification specialists to compress multi-jurisdiction approval timelines.
Among European-anchored conglomerates, ASSA ABLOY exemplifies premium positioning through integrated lock and reader portfolios, while dormakaba Group occupies a modular hardware specialization competing on third-party software interoperability. Siemens AG represents the engineered systems archetype with large-scale installation capabilities. These three entities anchor distinct competitive vectors without overlapping positioning.
| Leading Market Players |
|---|
| ASSA ABLOY |
| Siemens AG |
| Bosch Security Systems GmbH |
| Schneider Electric SE |
| dormakaba Group |
| Suprema, Inc. |
| Honeywell International, Inc. |
| Hanwha Vision Co., Ltd. |
| Johnson Controls International PLC |
| Others |
Value Chain & Pricing Dynamics
East Asian microcontroller foundries in Taiwan and South Korea concentrate specialized 32-bit processor supply, anchoring margin pools in control panel assembly rather than reader manufacturing. This upstream concentration forces biometric hardware vendors to absorb input volatility or push cost escalation toward systems integrators.
Pricing Analysis
Current-generation facial recognition modules command substantial premiums over prior-generation fingerprint readers, while next-generation multi-modal units with palm vein integration sit at the apex of product hierarchies. Three-tier pricing structure across premium, standard, and economy levels separates GB-certified biometric storage systems from uncertified imports and basic RFID card readers. Pricing pressure stems from cloud-native software vendors compressing hardware margins through subscription-based credential management. Residential developers across Indonesia and Vietnam exhibit acute price sensitivity, whereas Australian commercial facilities managers prioritize unified service level agreements over unit cost.
Supply Chain Analysis
Export-control regimes restricting advanced image sensor technology flow from Japan and the United States to Chinese integrators fragment component sourcing strategies. Manufacturing concentrates in China, South Korea, and Taiwan for control panels, electric locking mechanisms, and optical biometric sensors. Supply chains draw from specialized CMOS image sensors, secure element chips, and antimicrobial-coated enclosure materials. Single-source vulnerability in 3D structured light camera modules creates procurement risk for facial recognition system builders. Distribution runs through security systems integrators and direct OEM relationships with large commercial developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific access control hardware is recovering from cyclical compression as smart city infrastructure mandates reactivate deferred procurement cycles across Southeast Asian metropolitan centers.
For Market Incumbents: Pre-empt margin erosion from cloud-native software competitors by deepening in-house production of secure element chips and biometric algorithm stacks. Lock in specification relationships with Australian commercial developers consolidating around single-source accountability. Certification investment in parallel BIS, METI, and GB standard tracks compresses rival launch timelines.
For New Entrants and Emerging Players: Pursue retrofit mobile credential integration with Australia's aging Wiegand infrastructure as the most penetrable white-space opportunity. Target South Korean hospital modernization projects under MFDS guidelines where infection-control-compliant contactless specifications outpace incumbent product refresh cycles. Partner with local certification specialists to navigate fragmented approval landscapes.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed biometric software specialists holding cloud-native policy engine technology. Long-term viability hinges on recurring license revenue capture displacing one-time hardware sales. Watch for inflection when government tenders in China's tier-one cities mandate domestic biometric template storage architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Software Acquisition | Cloud-native policy engines from Suprema and domestic Chinese specialists capture recurring revenue streams from hardware vendors. |
| Multi-Jurisdiction Certification Partnership | Local testing laboratories in India and Japan compress parallel BIS and METI approval timelines for control panel launches. |
| OSDP Protocol Migration | Encrypted communication standards adoption opens security-upgrade budgets from Australian government and financial institution buyers. |
| Healthcare Facility Specialization | Antimicrobial-coated controller enclosures meeting MFDS guidelines secure specification windows in Seoul hospital modernization projects. |
| Mobile Credential Platform Integration | Bluetooth Low Energy smartphone authentication extends lifecycle value of existing Wiegand infrastructure in Australia's commercial building stock. |
Study Parameters
Two parallel data streams informed the analysis: structured interviews with security systems integrators, facilities managers at commercial developers, biometric algorithm engineers, and procurement officers at government agencies; and secondary validation against BIS certification registries, METI technical standards publications, GB standard documentation, and customs trade records for electromechanical locking mechanisms. Bottom-up unit shipment estimates triangulated against top-down construction spending data across tier-one Chinese cities and Australian commercial developments.
Forecast inputs considered technology substitution rates from RFID to biometric modalities, regulatory compliance timelines across fragmented certification regimes, and cloud-native software penetration in enterprise deployments. Segmentation dimensions spanned product architecture, authentication technology, application context, and end-user procurement sophistication. CAGRs were derived from fitted growth curves calibrated to observed specification shifts and infrastructure investment cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud providers into credential management would shift outcomes. Material shifts in China's GB biometric data localization requirements or India's BIS testing protocol expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Access Control Market
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
Global Keyless Vehicle Access Control Systems Market
Access Control Systems
Home Control and Security Systems Market
Access Control Systems
Global Home Security Systems Market
Access Control Systems
Asia-Pacific Pin-Based Access Control Market
Access Control Systems
Anti-Theft System Market
Access Control Systems
Network Access Control Market
Access Control Systems
Indoor Electromagnetic Lock Market
Access Control Systems
Modular Biometric Access Control Terminals Market
Access Control Systems
Perimeter Intrusion Detection Systems Market
Access Control Systems
Cylindrical Door Lock Market
Access Control Systems
Port Security Systems Market
Access Control Systems
US Restricted Access Barrier System Market
Access Control Systems
Japan Smart Lock Market
Access Control Systems
Mobile Turnstile Market