
 North America Keyless Vehicle Access Control System Market | 2026-2036
North America Keyless Vehicle Access Control System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Keyless Vehicle Access Control System Market Analytics
Subscription-based fleet leasing and asset-light vehicle management models is fragmenting capital requirements across the competitive landscape. Continental AG leverages its integrated hardware-software stack to sustain factory-installed dominance in premium OEM channels. Robert Bosch GmbH anchors aftermarket retrofit demand through its broad service network coverage. Denso Corporation specializes in Bluetooth Low Energy modules that compete on power efficiency for electric vehicle platforms.
North America Keyless Vehicle Access Control Systems encompass electronic authentication devices that replace mechanical keys through encrypted wireless handshakes, typically operating at 315 MHz or 433 MHz frequencies with rolling code encryption for theft prevention. These systems authenticate user identity via proximity sensing, biometric matching, or smartphone credential validation to enable engine start and door entry without physical key insertion. RFID-based passive entry retains the largest installed base across OEM factory installations, though smartphone applications represent the fastest-expanding segment as fleet operators mandate digital key pooling for shared mobility pools. Biometric systems command premium positioning in luxury vehicle configurations where fingerprint or facial recognition differentiates cabin personalization capabilities.
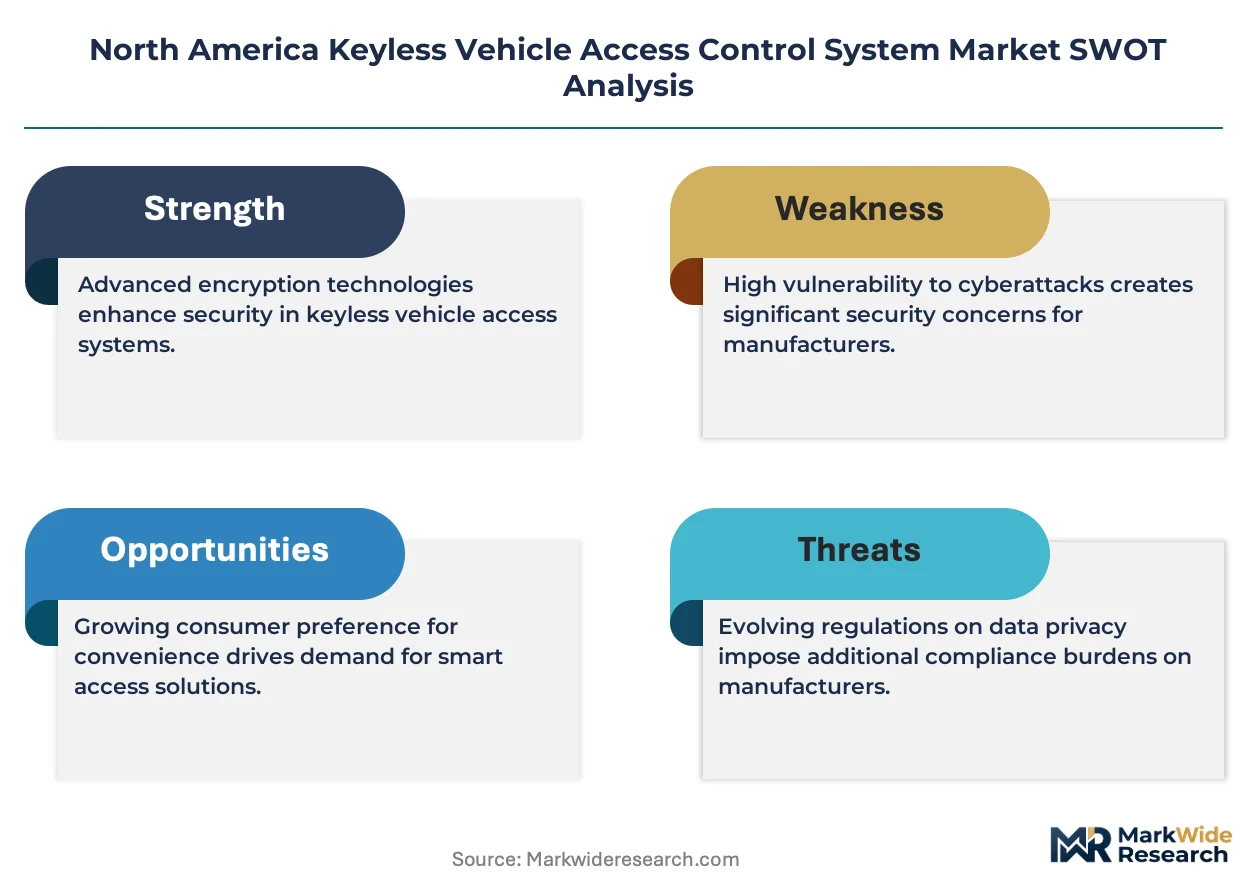
NHTSA cybersecurity directives, FCC Part 15 emissions standards for unlicensed radio devices, and ECPA electronic communications provisions collectively shape product certification requirements and liability frameworks for wireless vehicle entry systems. The EPA's fuel economy regulations indirectly accelerate demand by incentivizing weight reduction that electronic access modules enable versus mechanical locksets. Stakeholders must monitor evolving state-level privacy legislation in California and New York that could restrict biometric data retention practices in connected vehicle ecosystems.
Market Dynamics
NHTSA cybersecurity mandates are compressing development timelines across the North American supplier base, forcing encrypted wireless protocols to harden against relay attacks before 2026 model year certifications.
Growth Catalysts
- Fleet Digitalization Mandates:Corporate fleet operators across the United States and Canada now require smartphone-based credential pooling for shared vehicle pools, eliminating physical key handoff friction.
- EPA Weight Reduction Incentives:Fuel economy regulations indirectly accelerate electronic access module adoption by rewarding the elimination of mechanical lockset mass from vehicle architectures.
- Bluetooth Low Energy Maturation:Power-efficient BLE transceivers enable always-on proximity detection without draining electric vehicle battery reserves during standby periods.
Market Restraints
- Semiconductor Supply Concentration:Specialty RF chips for 315 MHz and 433 MHz transceivers concentrate among a limited set of foundry capacity in East Asian manufacturing corridors.
- Biometric Data Retention Liability:California and New York state privacy legislation creates uncertain compliance costs for fingerprint and facial recognition data storage in connected vehicle ecosystems.
- Mechanical Key Substitution Threshold:Cold-weather reliability concerns in the Great Lakes corridor slow complete abandonment of physical backup entry methods.
Strategic Opportunities
- Canadian Provincial Fleets:Ontario municipal and provincial government vehicle pools remain underpenetrated by smartphone credential systems relative to United States counterparts.
- Insurance Telematics Integration:Digital key authentication handshakes create data streams that insurers can leverage for usage-based policy pricing models.
- NHTSA Cybersecurity Labeling:Pending federal disclosure requirements will create competitive differentiation for suppliers with third-party penetration testing certifications.
Industry Challenges
- RF Engineering Talent Scarcity:The specialized skill set for 315 MHz and 433 MHz antenna design and FCC Part 15 emissions compliance concentrates among a shrinking pool of experienced practitioners.
- Legacy OEM Integration Complexity:Retrofitting encrypted wireless protocols into existing controller area network architectures requires extensive validation cycles without disrupting established supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Keyless Vehicle Access Control System Market |
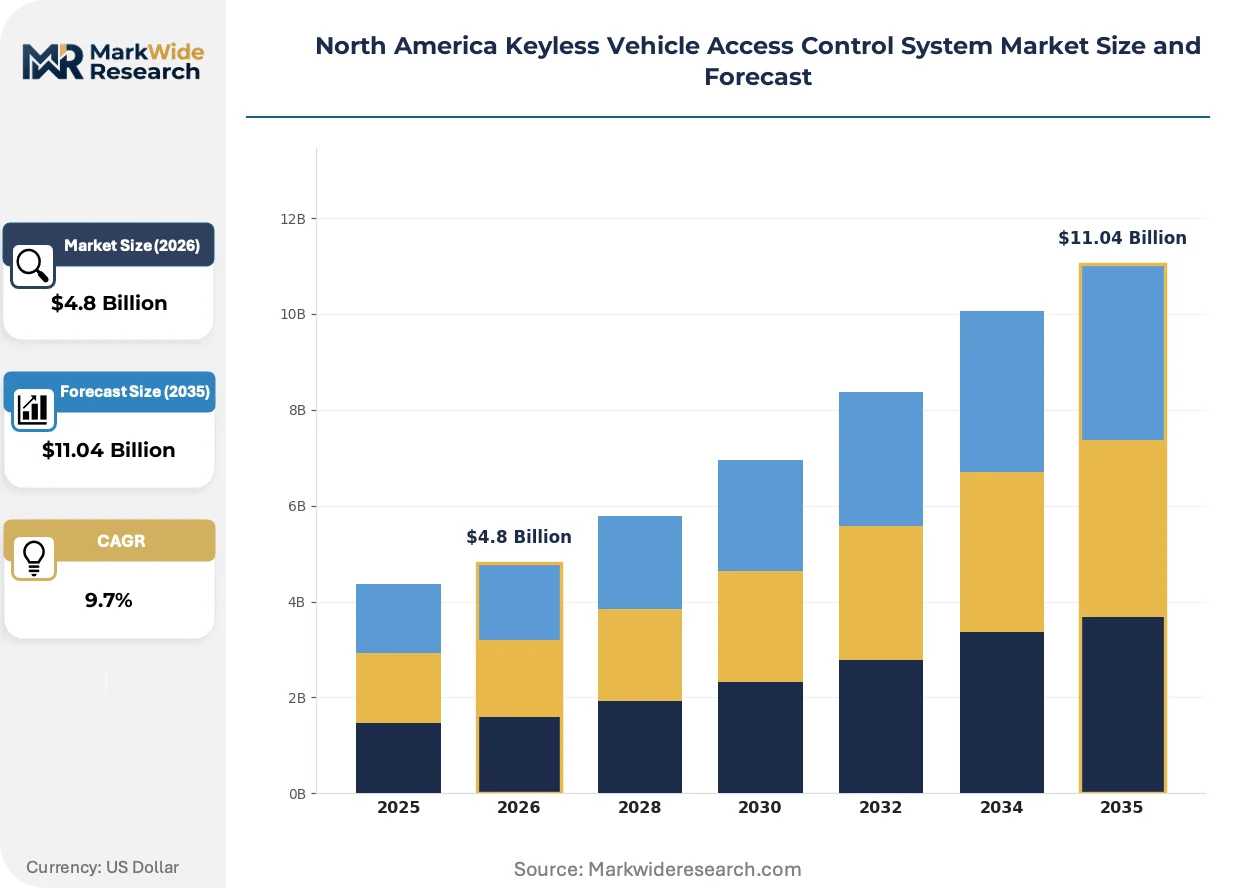
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, Bluetooth, NFC, Infrared Product Type: Smart Keys, Key Fobs, Smartphone Applications, Biometric Systems End User: OEMs, Fleet Operators, Aftermarket Providers, Vehicle Owners Installation Type: Factory Installed, Aftermarket, Retrofit, Modular Systems |
| Companies Covered | Continental AG, Denso Corporation, Valeo SA, Robert Bosch GmbH, ZF Friedrichshafen AG, Huf Hülsbeck & Fürst GmbH & Co. KG, HELLA GmbH & Co. KGaA, Gentex Corporation, Lear Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Keyless Vehicle Access Control System Market Evolving Landscape
Wireless authentication architectures are fragmenting across multiple frequency bands and credential formats, compressing the dominance of any single technical standard while expanding supplier specialization opportunities.
Ultra-wideband ranging chips are digitizing precise spatial awareness for passive entry systems, measuring distance between key fob and vehicle with centimeter accuracy rather than crude proximity detection. Luxury OEMs in the United States are adopting UWB for hands-free trunk access and anti-relay attack positioning. This precision is digitizing the trust boundary between authorized user and vehicle, compressing the attack surface for signal amplification theft.
NHTSA cybersecurity guidelines for connected vehicles are mandating encrypted firmware update channels and intrusion detection systems for all wireless entry modules. Suppliers must now document threat modeling and penetration testing before factory installation approvals. The Great Lakes manufacturing corridor faces the steepest compliance burden due to concentration of final vehicle assembly requiring synchronized certification timelines.
Asset-light fleet management platforms are unbundling hardware procurement from software subscription, allowing smaller operators to access enterprise-grade digital key pooling without capital-intensive installed base commitments. This model disrupts traditional two-tier distribution through automotive locksmiths and dealership parts departments. The shift is most visible among last-mile delivery fleets in dense United States metropolitan corridors where vehicle utilization rates exceed 18 hours daily.
North America Keyless Vehicle Access Control System Market Segmentation
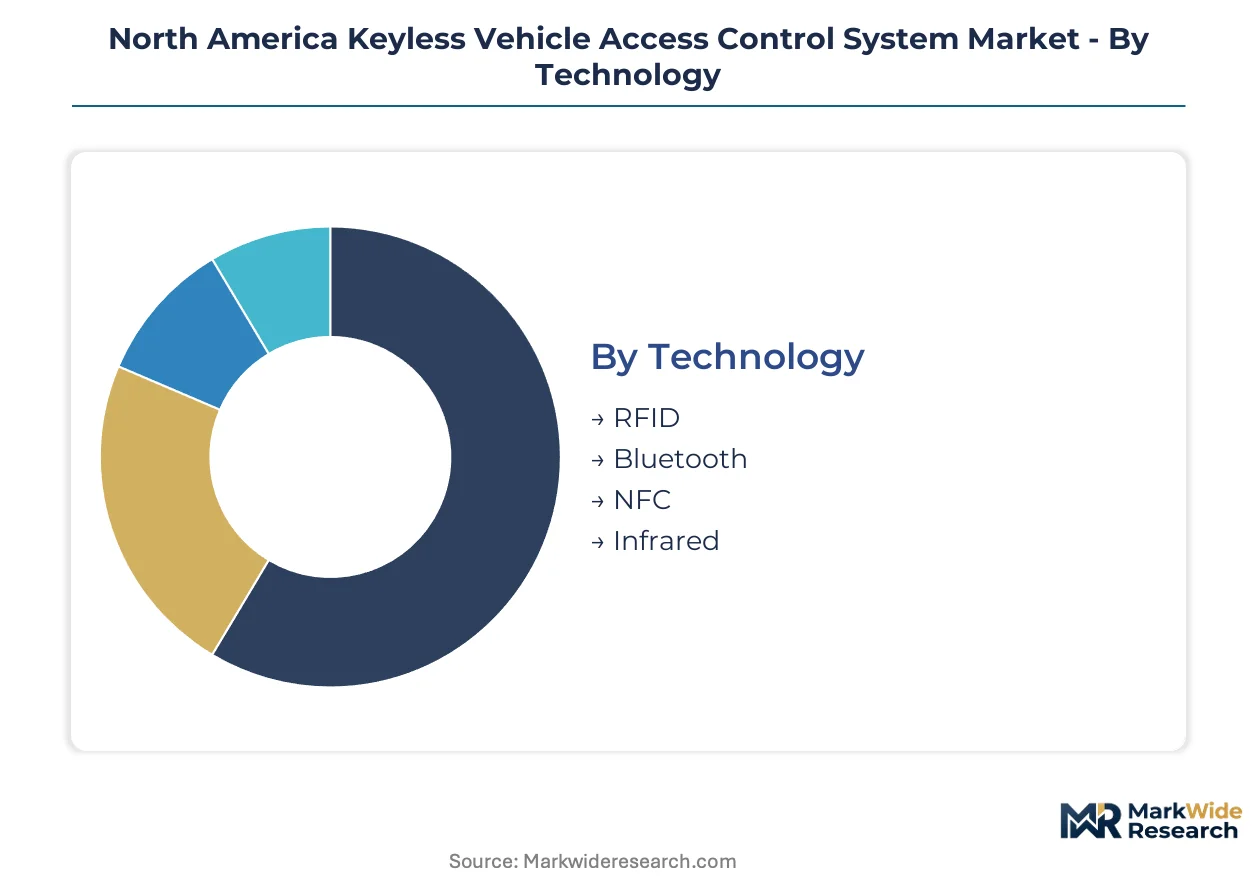
Technology choices in North American keyless access systems determine replacement cycles and supplier revenue stability. Product configurations span from mature hardware formats to rapidly iterating software platforms. End-user concentration and installation methods further stratify margin profiles across the value chain.
Technology:
RFID modules turn over slowest due to embedded factory installations, while smartphone credential protocols refresh quarterly through app updates.
- RFID:Passive entry systems operating at 315 MHz and 433 MHz frequencies with rolling code encryption dominate the installed base across Detroit Three and transplant OEM assembly lines. The Great Lakes corridor concentrates demand where legacy vehicle architectures resist protocol migration.
- Bluetooth:Low Energy transceivers enable always-on proximity detection with minimal electric vehicle battery drain. Fleet operators in dense United States metropolitan corridors mandate BLE for shared mobility pools where credential handoff friction must disappear.
- NFC:Near-field protocols suit short-range authentication scenarios requiring physical device tap.
- Infrared:Legacy directional signaling retains niche aftermarket retrofit applications in cold-climate regions.
RFID dominates installed base. Bluetooth is where expansion concentrates.
Product Type:
Hardware products stratify by capital intensity, while software platforms scale through subscription economics that compress upfront procurement barriers.
- Smart Keys:Integrated fob units combining mechanical backup with encrypted wireless transceivers anchor premium OEM factory specifications. NHTSA cybersecurity mandates are compressing development timelines for these devices before model year certifications.
- Smartphone Applications:Digital credential platforms enable fleet-wide key pooling without physical handoff logistics. Asset-light vehicle management platforms in the United States and Canada unbundle hardware from software subscription.
- Key Fobs:Standalone wireless entry devices persist in economy vehicle configurations.
- Biometric Systems:Fingerprint and facial recognition modules command luxury positioning where cabin personalization differentiates.
Smart Keys retain revenue concentration. Smartphone Applications are climbing the fastest.
End User:
Procurement authority concentrates with fleet operators demanding standardization, while fragmented vehicle owners prioritize price over protocol uniformity.
- OEMs:Factory installation contracts require synchronized certification timelines across the Great Lakes manufacturing corridor. Continental AG and Robert Bosch GmbH anchor supply relationships through integrated hardware-software stacks.
- Fleet Operators:Corporate and government vehicle pools across the United States and Canada now mandate smartphone-based credential systems. Ontario provincial fleets remain underpenetrated relative to United States counterparts.
- Aftermarket Providers:Automotive locksmiths and dealership parts departments face disruption from direct-to-fleet digital distribution.
- Vehicle Owners:Individual consumers drive biometric adoption in luxury configurations.
OEMs dominate volume concentration. Fleet Operators are gaining share fastest.
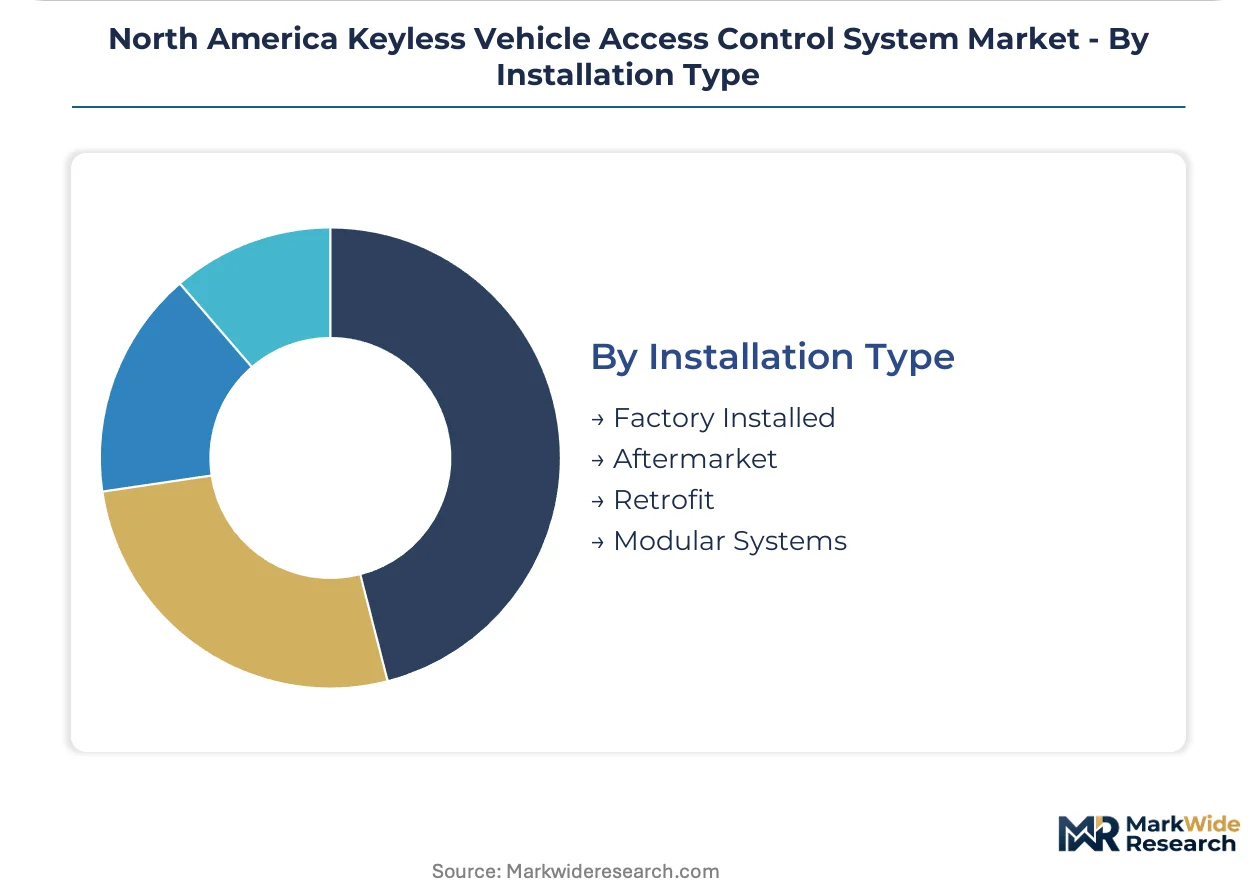
Installation Type:
Factory integration captures lifetime value through embedded supply contracts, while aftermarket channels face margin compression from modular retrofit alternatives.
- Factory Installed:Embedded modules during vehicle assembly lock in supplier relationships across multi-year platform cycles. EPA weight reduction incentives reward elimination of mechanical lockset mass from original equipment specifications.
- Modular Systems:Plug-and-play retrofit kits enable fleet operators to upgrade existing vehicle pools without capital-intensive replacement. Last-mile delivery fleets exceeding 18-hour daily utilization rates favor this procurement flexibility.
- Aftermarket:Post-sale installation through service networks retains price-sensitive segments.
- Retrofit:Legacy vehicle compatibility solutions address cold-weather reliability concerns in the Great Lakes corridor.
Factory Installed commands margin concentration. Modular Systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Great Lakes manufacturing corridor where Detroit Three OEMs anchor factory installation contracts, while Canadian provincial fleets negotiate from fragmented procurement positions.
United States
Fleet operators in dense metropolitan corridors mandate smartphone credential pooling for shared mobility pools exceeding 18-hour daily utilization. NHTSA cybersecurity directives compress development timelines for encrypted wireless protocols before 2026 model year certifications. The Great Lakes corridor spanning Michigan and Ohio concentrates final vehicle assembly requiring synchronized supplier certification timelines.
Canada
Ontario municipal and provincial government vehicle pools remain underpenetrated by smartphone-based entry systems relative to United States counterparts. Health Canada and PMRA coordinate with NHTSA on cross-border vehicle safety standards affecting wireless entry module approvals. The Ontario automotive manufacturing cluster in Windsor-Toronto corridor hosts transplant OEM assembly lines importing RFID-based passive entry specifications from United States parent operations.
Mexico
Transplant OEM assembly plants in Nuevo León and Bajío Region integrate keyless entry modules for export-bound vehicles serving United States demand. Mexico's federal consumer protection agency PROFECO enforces warranty standards on electronic vehicle components that affect aftermarket retrofit channel liabilities. The northern border states concentrate maquiladora operations where component suppliers stage pre-assembly for just-in-time delivery to Texas and California vehicle plants.
North America Keyless Vehicle Access Control System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying RF transceivers and antenna modules. The supplier base stratifies between consolidated hardware-software stacks and fragmented single-technology vendors. Three archetypes dominate: integrated Tier 1 automotive suppliers, specialized connectivity module producers, and aftermarket retrofit distributors. Competitive moves concentrate on strategic partnerships for cybersecurity certification and backward integration into semiconductor sourcing.
Within the integrated Tier 1 tier, Continental AG, Robert Bosch GmbH, and Denso Corporation exemplify contrasting strategic positions. Continental AG anchors factory-installed dominance through captive hardware-software integration. Robert Bosch GmbH occupies a position spanning OEM supply and aftermarket service network coverage. Denso Corporation represents specialization in power-efficient connectivity modules for electric vehicle platforms.
| Leading Market Players |
|---|
| Continental AG |
| Denso Corporation |
| Valeo SA |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Huf Hülsbeck & Fürst GmbH & Co. KG |
| HELLA GmbH & Co. KGaA |
| Gentex Corporation |
| Lear Corporation |
| Others |
Value Network & Pricing Analysis
The I-35 corridor freight network connecting Texas assembly plants to Midwest distribution centers shapes cost dynamics across the North American keyless access ecosystem. Supplier concentration in the Great Lakes manufacturing belt amplifies logistics premiums for configured-to-order modules, while EPA weight reduction incentives compress margins on standardized hardware tiers.
Pricing Analysis
The customization-premium spread separates factory-installed RFID systems from modular retrofit alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks NHTSA cybersecurity certification grades and volume procurement scale. Cost compression in the economy tier intensifies because semiconductor foundry concentration limits supplier negotiation leverage. Fleet operators in dense United States metropolitan corridors demonstrate lowest price sensitivity due to utilization-rate economics, while individual vehicle owners in cold-climate regions resist premium biometric configurations.
Supply Chain Analysis
Export-control regimes on RF semiconductor fabrication equipment constrain capacity expansion for 315 MHz and 433 MHz transceiver foundries. Taiwan, South Korea, and Japan anchor specialty RF chip supply, with raw material dependencies spanning gallium arsenide substrates, advanced packaging resins, and precision antenna alloys. Single-source vulnerability concentrates in East Asian backend testing facilities. Distribution runs through Tier 1 automotive suppliers holding captive relationships with Detroit Three OEMs, supplemented by direct-to-fleet digital channels disrupting traditional locksmith networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across authentication protocols creates specialization niches as fleet operators unbundle hardware procurement from software subscriptions. The demand-side shift toward asset-light vehicle management fragments capital requirements and opens entry points for modular retrofit specialists.
For Market Incumbents: Insulate factory-installed dominance through backward integration into BLE semiconductor sourcing and captive UWB ranging chip development. NHTSA cybersecurity labeling requirements threaten margin erosion for suppliers lacking third-party penetration testing certifications. Certification investment in the Great Lakes corridor locks in multi-year OEM platform relationships.
For New Entrants and Emerging Players: Pursue Ontario provincial fleet contracts where smartphone credential penetration lags United States counterparts. The underpenetrated Canadian municipal vehicle pool segment offers lowest competitive density. A direct-to-fleet SaaS pricing model bypasses traditional automotive locksmith distribution and captures recurring revenue from asset-light operators.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded automotive electronics divisions lacking connectivity module focus. Long-term viability hinges on electric vehicle platform alignment and cybersecurity certification depth. Watch NHTSA disclosure rule finalization as inflection signal for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | Third-party penetration testing unlocks NHTSA factory installation approvals for 2026 model year platforms. |
| BLE Semiconductor Backward Integration | Captive foundry relationships insulate against East Asian supply concentration and tariff exposure. |
| UWB Ranging Chip Development | Centimeter-precision spatial awareness differentiates anti-relay attack positioning for luxury OEM specifications. |
| Fleet SaaS Platform Launch | Subscription economics compress upfront procurement barriers for last-mile delivery operators exceeding 18-hour utilization. |
| Ontario Market Expansion | Provincial government vehicle pools remain underpenetrated relative to United States smartphone credential adoption. |
Research Methodology
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, fleet operations managers, and automotive aftermarket distributors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, NHTSA regulatory dockets, vehicle production databases, and customs records for RF component trade flows. Bottom-up unit economics triangulated with top-down market sizing across the projection horizon.
Scenario-bracketing framed demand trajectories under varying electric vehicle adoption curves and cybersecurity regulatory stringency levels. Segmentation dimensions modeled include technology protocol, product type, end-user category, and installation method alongside regional production cluster concentration. CAGRs derived from installed base turnover rates and replacement cycle compression across the analysis window. Key inputs encompassed fleet digitalization mandates and EPA fuel economy incentive evolution.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories and semiconductor capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding NHTSA rulemaking timelines and cross-border trade policy stability. Material shifts in export-control regime stringency or electric vehicle subsidy structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Modular Biometric Access Control Terminals Market
Access Control Systems
Global Keyless Vehicle Access Control Systems Market
Access Control Systems
Restricted Access Barrier System (RABS) Market
Access Control Systems
Pre-Departure Clearance System Market
Access Control Systems
Locks Market
Access Control Systems
Global Barrier Systems Market
Access Control Systems
Japan Smart Lock Market
Access Control Systems
Padlock Smart Lock Market
Access Control Systems
Indoor Electromagnetic Lock Market
Access Control Systems
Global Automatic Door Control Market
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
Smart Entry System Market
Access Control Systems
Global Digital Door Lock Systems Market
Access Control Systems
Access Control As a Service Market
Access Control Systems
Door Controller Systems Market
Access Control Systems
Global Industrial Security Systems Market