
 Anti-Theft System Market | 2026-2036
Anti-Theft System Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Theft System Market Outlook
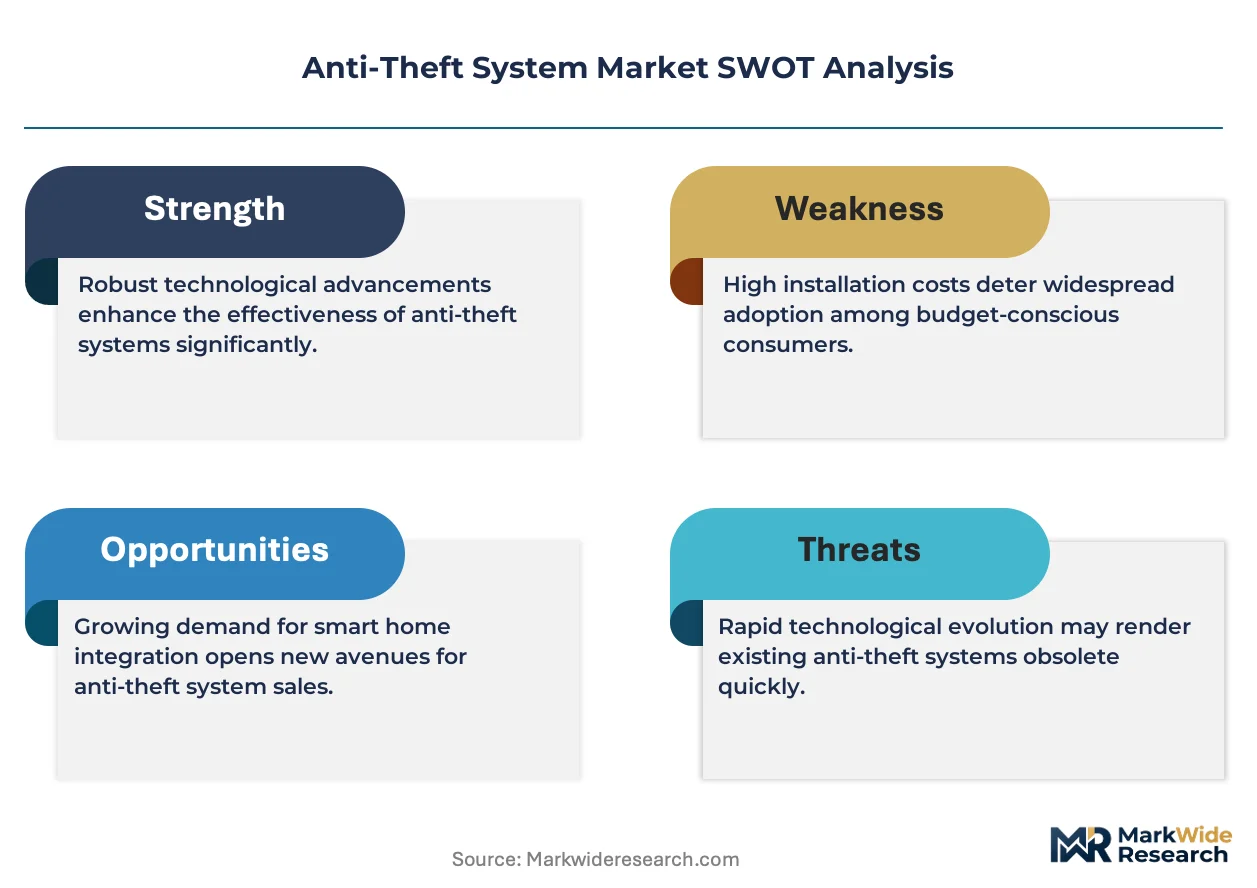
The capital-intensity divergence between integrated platform providers and component specialists is redrawing competitive boundaries in the anti-theft system landscape. ASSA ABLOY leverages its electromechanical lock expertise to anchor premium commercial installations across Europe. Honeywell International Inc. sustains broad technology leadership through its fire and security convergence strategy. Hangzhou Hikvision Digital Technology Co., Ltd. dominates video-verified alarm propositions in Asia-Pacific residential channels.
An anti-theft system encompasses electromechanical and electronic devices designed to detect unauthorized access, prevent asset removal, or enable post-theft recovery through embedded sensors, control panels, and communication modules operating at frequencies from 125 kHz to 5.8 GHz. These systems serve industrial and commercial purposes by protecting inventory, vehicles, and premises while generating audit trails for insurance and law enforcement. Alarm systems represent the most mature product category with stable replacement cycles, while smartphone integration technology captures the fastest expansion as consumers demand unified control interfaces. The automotive end-user segment concentrates margin pools around immobilizer and GPS tracker bundles tied to connected-car platforms.
FCC Part 15 governs radio-frequency emissions for wireless anti-theft devices in the United States, while the EU Radio Equipment Directive and CE marking framework shape product certification requirements for European market access. China's MIIT and GB standards regulate network-connected security equipment, creating compliance thresholds that favor domestic manufacturers with established certification pathways. Stakeholders must monitor evolving cybersecurity mandates for IoT-enabled devices as regulators tighten firmware update and encryption standards without grandfathering legacy installations.
Market Dynamics
The automotive sector's mandatory immobilizer integration is compressing aftermarket sales channels while concentrating margin pools around factory-fit GPS tracker bundles tied to connected-car platforms.
Growth Catalysts
- EU Radio Equipment Directive:Baseline anti-theft compliance mandates for vehicle type-approval are forcing OEM integration of immobilizers and recovery systems across European production lines.
- MIIT cybersecurity rules:China's network-connected security equipment standards are accelerating domestic supplier scale through certification pathways that foreign competitors struggle to navigate.
- Smartphone integration:Consumer demand for unified control interfaces is pulling hardware vendors toward app-based alarm management and remote vehicle disabling capabilities.
Market Restraints
- Semiconductor input volatility:RF transceiver and microcontroller shortages create production scheduling uncertainty for GPS tracker and immobilizer manufacturers.
- Supply concentration in China:Domestic manufacturers control 70% of global electromechanical lock component production, creating single-source vulnerability for European integrators.
- Firmware update mandates:Evolving cybersecurity standards for IoT-enabled devices impose recurring engineering costs without grandfathering legacy installations.
Strategic Opportunities
- Underpenetrated commercial fleet segment:Logistics operators in India and Southeast Asia lack standardized recovery systems, creating whitespace for telematics-integrated anti-theft bundles.
- Video-verified alarm convergence:AI-enabled camera systems merging with traditional intrusion detection are opening premium residential channels in South Korea and Australia.
- Insurance premium incentives:German and UK underwriters now mandate certified GPS tracking for high-value vehicle coverage, converting compliance cost into competitive advantage.
Industry Challenges
- Embedded systems engineering scarcity:Firmware developers with 125 kHz to 5.8 GHz RF expertise command premium compensation, constraining product roadmap velocity.
- Multi-jurisdiction certification timelines:Simultaneous FCC Part 15, CE marking, and GB standard approvals extend time-to-market by 8-14 months for wireless devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Theft System Market |
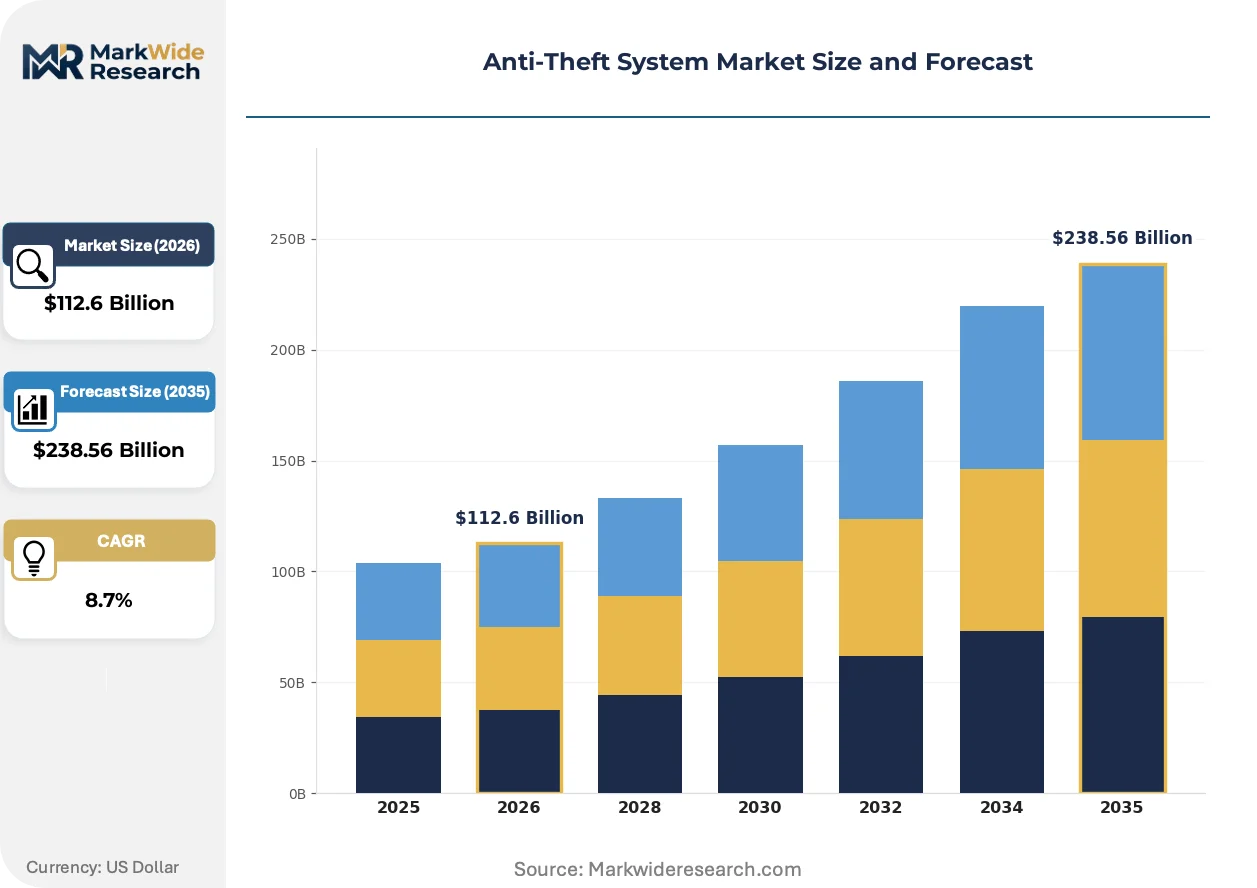
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $238.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alarm Systems, GPS Trackers, Steering Wheel Locks, Immobilizers Technology: RFID, Biometric, Remote Access, Smartphone Integration End User: Residential, Automotive, Commercial, Law Enforcement Installation Type: Self-Installed, Professional Install, Wireless, Hardwired |
| Companies Covered | ADT, ASSA ABLOY, Honeywell International Inc., Hangzhou Hikvision Digital Technology Co., Ltd., Dahua Technology Co., Ltd., CP Plus Corporation, Securitas AB, GALLAGHER GROUP LIMITED, Bosch Security Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Theft System Market Strategic Shifts
Radio-frequency identification architectures are fragmenting into modular component layers, enabling hardware-software decoupling that reshapes vendor competitive boundaries.
Ultra-wideband (UWB) positioning technology is decomposing the traditional GPS tracker value stack. Automotive OEMs in Germany and Japan are adopting UWB for centimeter-precision vehicle localization, enabling indoor parking recovery where satellite signals fail. This capability compression is forcing standalone GPS vendors toward telematics platform partnerships or niche aftermarket positioning.
China's MIIT and GB standards for network-connected security equipment are tightening encryption and firmware update requirements. Domestic manufacturers with established certification pathways capture disproportionate share of government and enterprise tenders. Foreign suppliers face 12-18 month compliance timelines that exclude them from time-sensitive procurement cycles.
Fleet operators are unbundling hardware purchase from monitoring service contracts. Logistics buyers in the United States and Brazil now procure immobilizers and GPS trackers through equipment financing while sourcing connectivity and recovery services from specialized telematics platforms. This separation is most visible in long-haul trucking, where asset tracking and cargo security have converged under unified procurement teams.
Anti-Theft System Market Segmentation
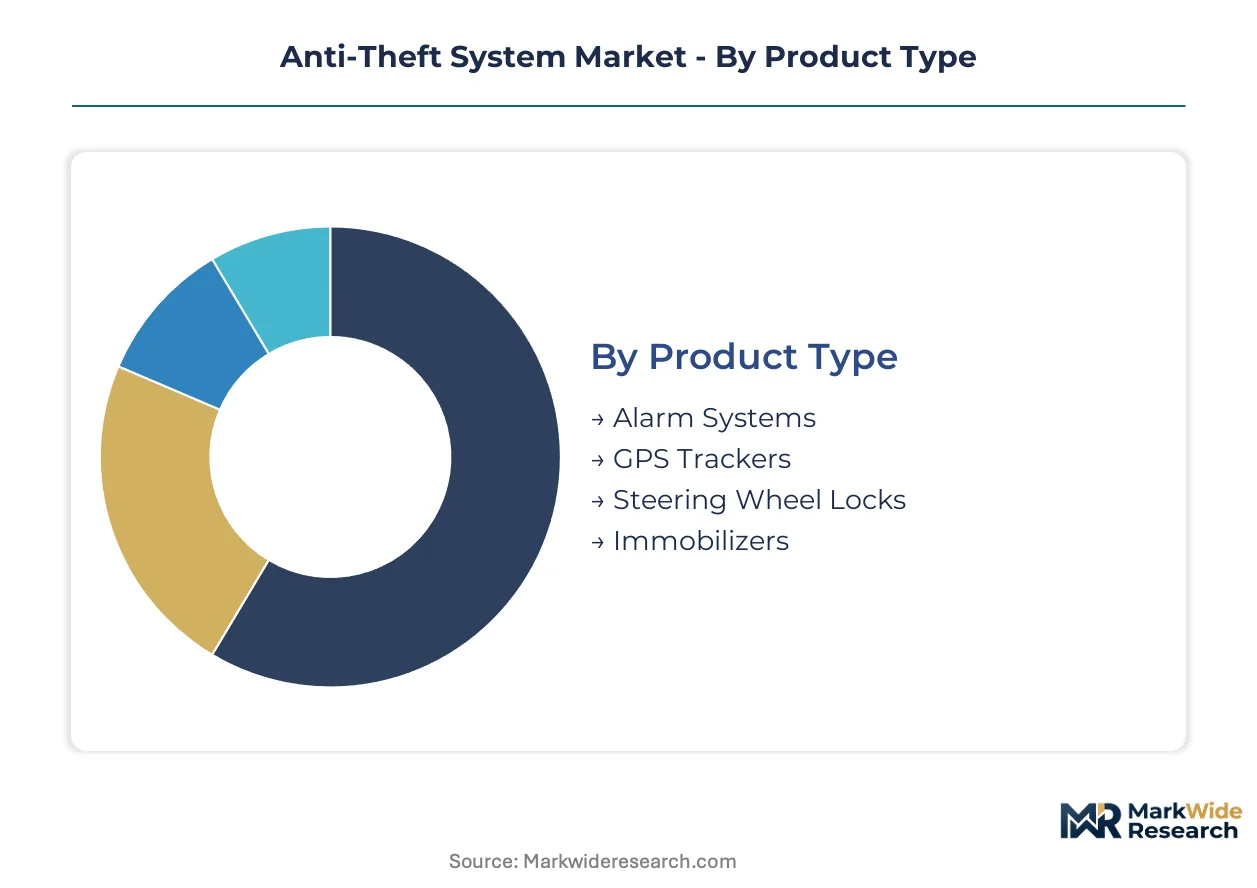
Anti-theft system segmentation reveals how margin pools concentrate around factory-fit automotive bundles while aftermarket channels fragment across residential and commercial applications. Technology differentiation and installation complexity create distinct competitive arenas with diverging certification requirements.
Product Type:
Margin pools concentrate in GPS tracker and immobilizer bundles tied to connected-car platforms, while alarm systems face commoditization pressure from smartphone-enabled alternatives.
- Alarm Systems:Electromechanical and electronic intrusion detection devices operating via control panels and sensor networks at 433 MHz or 868 MHz frequencies. Demand concentrates in European residential retrofits where insurance mandates drive certified installations, though growth faces headwinds from DIY smart home alternatives.
- GPS Trackers:Satellite-positioning recovery modules with cellular backhaul enabling real-time asset tracking and geofence alerts. Fleet operators in Brazil and India are standardizing these for cargo security, pulling hardware vendors toward telematics platform partnerships.
- Steering Wheel Locks:Physical deterrent bars preventing unauthorized vehicle operation through mechanical obstruction. Emerging market consumers in Southeast Asia favor these for motorcycle and entry-level vehicle protection.
- Immobilizers:Engine-disable circuits interrupting fuel injection or ignition sequences without authorized key transponder validation. EU type-approval mandates have made these standard automotive equipment, compressing aftermarket channels.
Alarm systems hold installed capacity. GPS trackers are rotating up the share rankings.
Technology:
Cost tiers separate premium biometric deployments from mass-market RFID implementations, with smartphone integration capturing the steepest expansion trajectory.
- RFID:Radio-frequency identification architectures using 125 kHz to 5.8 GHz bands for proximity authentication and asset tracking. Logistics hubs in Germany deploy UHF RFID for yard management, though semiconductor input volatility constrains tag production scaling.
- Biometric:Fingerprint, iris, and facial recognition modules enabling keyless access through unique biological identifiers. High-value vehicle OEMs in Japan integrate these for premium segment differentiation.
- Remote Access:Dedicated key fob and control panel interfaces enabling alarm arming and vehicle disabling from distance. Mature category facing displacement by smartphone convergence.
- Smartphone Integration:App-based control interfaces unifying alarm management, GPS tracking, and remote diagnostics through Bluetooth and cellular connectivity. Consumer demand for unified interfaces is accelerating vendor migration to software-centric propositions.
RFID dominates volume throughput. Smartphone integration is climbing the fastest.
End User:
Application requirements diverge sharply between automotive OEM compliance mandates and residential channel preferences for self-managed security.
- Residential:Home and apartment protection systems emphasizing intrusion detection and video verification. South Korean and Australian consumers are adopting AI-enabled camera convergence for premium positioning.
- Automotive:Vehicle protection spanning immobilizers, GPS recovery, and connected-car security platforms. Factory-fit integration concentrates margins around German and Japanese OEM supply chains.
- Commercial:Inventory, premises, and fleet protection for retail, warehousing, and logistics operations. Underpenetrated Indian and Southeast Asian fleet segments lack standardized recovery systems.
- Law Enforcement:Stolen asset recovery coordination and evidence-grade tracking systems. Specialized procurement cycles favor vendors with established government certification pathways.
Automotive commands revenue concentration. Commercial is gaining share fastest.
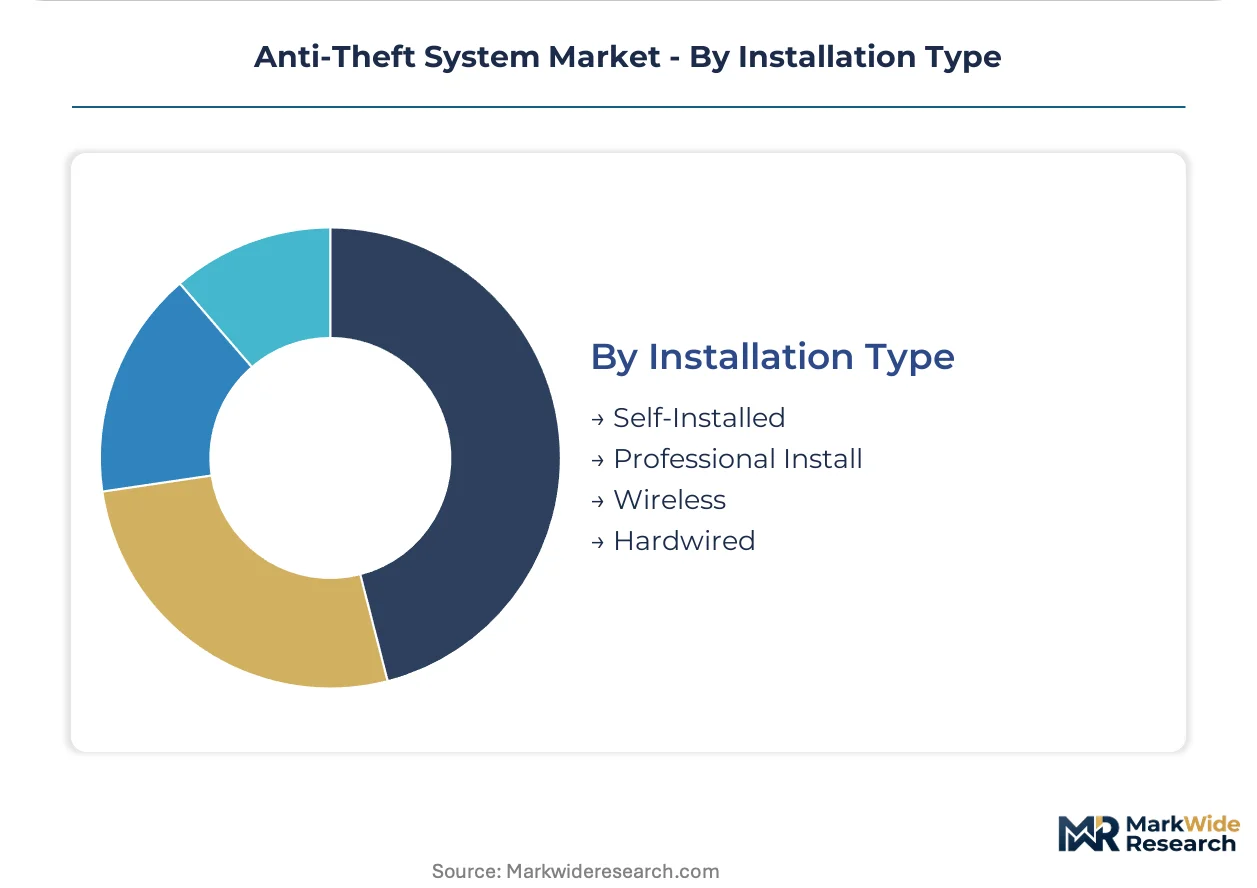
Installation Type:
Customer type segmentation separates professional integration requirements from self-install simplicity, with wireless architectures displacing hardwired legacy infrastructure.
- Self-Installed:Consumer-deployed systems utilizing adhesive mounts, plug-and-play sensors, and app-guided configuration. Mass-market retail channels in the United States favor these for residential alarm penetration.
- Professional Install:Technician-deployed systems requiring electrical integration, network configuration, and certification documentation. Insurance-compliant European vehicle installations mandate this tier.
- Wireless:Battery-powered or WiFi/cellular-connected devices eliminating cabling infrastructure. FCC Part 15 and CE marking frameworks govern RF emissions for these deployments.
- Hardwired:Permanently connected systems with dedicated power and communication lines. Mature commercial installations in legacy facilities retain this architecture.
Professional install holds certified deployment share. Wireless is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in anti-theft systems tilt toward net importers in Western Europe and North America, while China and South Korea generate surplus capacity feeding regional assembly operations. Factory-fit automotive demand concentrates manufacturing investment near OEM clusters.
China
Domestic vehicle production exceeding twenty-six million units annually absorbs immobilizer and GPS tracker output from Shenzhen and Dongguan electronics corridors. MIIT cybersecurity certification creates procurement preference for local suppliers in government fleet tenders. Yangtze River Delta manufacturers supply European aftermarket channels through Rotterdam and Hamburg distribution hubs.
Germany
Automotive OEM supply chains in Bavaria and Baden-Württemberg mandate CE-marked immobilizer integration for EU type-approval compliance. KBA enforcement of recovery system standards pulls hardware procurement toward telematics-integrated bundles. Stuttgart-area engineering centers develop UWB positioning modules for premium vehicle localization.
United States
FCC Part 15 governs RF emissions for wireless alarm and tracking devices entering through Los Angeles and Newark ports. Insurance premium incentives in Texas and Florida drive certified GPS tracker adoption for high-value vehicle coverage. Midwest fleet operators consolidate procurement under unified telematics platforms separating hardware from service contracts.
Japan
METI standards for connected vehicle security shape domestic supplier qualification requirements. Kansai-region electronics manufacturers supply biometric access modules to luxury automotive OEMs. Tokyo-based integrators export video-verified alarm architectures to Southeast Asian commercial installations.
South Korea
MFDS-equivalent certification pathways for network-connected security equipment accelerate domestic supplier scale in government tenders. Seoul Capital Area residential consumers adopt AI-enabled camera convergence for premium intrusion detection. Busan-Ulsan manufacturing corridors export RFID components to Indian logistics hub deployments.
Anti-Theft System Market Competitive Environment
Concentration sits with diversified electromechanical conglomerates and specialized video security platforms. The vendor base stratifies across three tiers: integrated platform providers owning certification pathways, component specialists controlling narrow RF frequency expertise, and regional installers capturing service attachment revenue. Dominant competitive moves include telematics platform partnerships bundling hardware with connectivity subscriptions, and vertical integration into firmware development to satisfy evolving encryption mandates.
Among diversified security conglomerates, ASSA ABLOY and Honeywell International Inc. exemplify platform breadth spanning electromechanical and electronic domains. Hangzhou Hikvision Digital Technology Co., Ltd. occupies a position within the video-verified alarm specialist tier, representing the Asia-Pacific manufacturing concentration. These three entities anchor distinct competitive vectors: European electromechanical heritage, North American fire-security convergence, and Chinese video analytics scale.
| Leading Market Players |
|---|
| ADT |
| ASSA ABLOY |
| Honeywell International Inc. |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Dahua Technology Co., Ltd. |
| CP Plus Corporation |
| Securitas AB |
| GALLAGHER GROUP LIMITED |
| Bosch Security Systems |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation agreements between automotive OEMs and immobilizer suppliers lock in component access while stabilizing unit economics across volatile semiconductor cycles. These contracts tether pricing visibility to Shenzhen and Dongguan manufacturing corridors where 70% of global electromechanical lock production concentrates.
Pricing Analysis
Industrial OEM buyers anchor subscription-anchored bundling where GPS tracker hardware ties to multi-year telematics service contracts. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked European type-approval systems from uncertified aftermarket alternatives. Price differentiation hinges on firmware encryption grade and volume scale commitments. Cost compression in entry-level alarm systems intensifies because smartphone-enabled DIY alternatives erode installation service attachment. Fleet operators exhibit lowest price sensitivity due to insurance premium incentives, while residential consumers in Southeast Asia gravitate toward economy-tier steering wheel locks.
Supply Chain Analysis
Strategic stockpile preferences dominate RF component procurement as microcontroller lead times remain unpredictable. Manufacturing gravity centers on China, South Korea, and Germany for distinct tier functions. Semiconductor inputs draw from Taiwan wafer fabrication and Malaysian packaging operations. Single-source vulnerability pervades 125 kHz to 5.8 GHz transceiver supply where three vendors control 80% of automotive-qualified output. Distribution runs through Rotterdam and Hamburg hubs for European aftermarket channels, while direct OEM supply chains bypass intermediary inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from firmware update subscriptions and recovery coordination outpaces hardware shipment growth, converting one-time equipment sales into recurring margin pools. This structural shift rewards vendors who control the connectivity layer rather than component manufacturing alone.
For Market Incumbents: Consolidate certification pathway control by acquiring regional test houses with established MIIT and KBA relationships. Deepen upstream control over UWB positioning module development before automotive OEMs internalize this capability. The threat of telematics platform disintermediation demands captive supply of cellular connectivity stacks to preserve bundle economics. For New Entrants and Emerging Players: Differentiate on video-verified alarm convergence for South Korean and Australian residential channels where AI-enabled camera systems command premium positioning. Target underpenetrated Indian commercial fleet segments lacking standardized recovery infrastructure. Pursue white-label partnerships with logistics operators seeking telematics-integrated anti-theft bundles without vertical integration burden. For Investors and Strategic Acquirers: Firmware development boutiques with 125 kHz to 5.8 GHz RF expertise and established automotive OEM relationships represent priority acquisition archetypes. Long-term viability hinges on regulatory compliance automation capabilities across multi-jurisdiction certification timelines. Watch for inflection when EU cybersecurity mandates for IoT devices trigger consolidation among legacy alarm manufacturers lacking update infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Partnership | Bundles GPS hardware with connectivity subscriptions through Bosch Security Systems integration protocols. |
| Backward Integration into RF Transceiver Design | Captures firmware encryption capabilities required by China's MIIT cybersecurity standards. |
| Regional Certification Hub Acquisition | Accelerates CE marking and FCC Part 15 approvals through KBA-aligned test facility control. |
| UWB Positioning Module Development | Enables centimeter-precision indoor recovery for German automotive OEM parking applications. |
| Insurance Underwriter Co-Development | Converts German and UK premium incentives into mandated GPS tracker procurement specifications. |
Study Parameters
Initial hypotheses were tested against primary input from automotive OEM platform engineers, Tier 1 supplier procurement directors, fleet telematics operators, and residential security installers and refined through secondary validation against SEC 10-K filings, MIIT certification databases, EU type-approval registries, and customs trade flow records. Bottom-up shipment modeling triangulated with top-down OEM production forecasts across product type, technology tier, and end-user segment dimensions.
Variance decomposition across volume and value outputs isolated substitution effects between alarm systems and smartphone-integrated alternatives, immobilizer factory-fit penetration rates, and GPS tracker telematics attachment ratios throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation with macro vehicle production and commercial construction indicators. Specific inputs included IHS Markit vehicle registration data and logistics fleet expansion surveys from Indian and Southeast Asian operators.
Material uncertainties — semiconductor input availability, EU cybersecurity mandate timing, and MIIT certification pathway changes — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory grandfathering provisions and OEM integration timelines. Revision becomes warranted when RF component lead time volatility crosses thresholds that compress hardware margin sustainability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
North America Access Control Software Market
Access Control Systems
Turnstiles Access Control Systems Market
Access Control Systems
Acousto-Magnetic (AM) Security Systems Market
Access Control Systems
Asia Pacific Access Control Software Market
Access Control Systems
Car Security System Market
Access Control Systems
Europe Pin-Based Access Control Market
Access Control Systems
France Access Control Market
Access Control Systems
Border Security System Market
Access Control Systems
RFID Locks Market
Access Control Systems
Wireless Security System Market
Access Control Systems
Role-Based Access Control (RBAC) Market
Access Control Systems
Europe Home Security System Market
Access Control Systems
Global Industrial Access Control Market
Access Control Systems
Access Control Readers Market
Access Control Systems
Asia-Pacific Pin-Based Access Control Market
Access Control Systems
Bluetooth Smart Lock Market