
 Modular Biometric Access Control Terminals Market | 2026-2036
Modular Biometric Access Control Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Biometric Access Control Terminals Market Analytics
Silicon-based capacitive sensor substrates are recalibrating terminal economics as manufacturers shift from rigid ceramic packages to flexible polymer alternatives. HID Global Corporation leverages its vertical integration across secure credentialing to sustain pricing power in enterprise deployments. ASSA ABLOY AB anchors European distribution through its architectural hardware channels, while ZKTeco Europe competes aggressively on volume manufacturing of fingerprint modules for mid-market installations.
Modular biometric access control terminals are electromechanical devices that authenticate identity through physiological or behavioral characteristics, typically incorporating sensor arrays with liveness detection algorithms and tamper-resistant enclosures rated for continuous operation. Their primary purpose is to enforce granular physical access policies across facilities while maintaining audit trails for compliance and security operations. Fingerprint recognition occupies the largest installed base due to mature sensor costs and established user familiarity, though facial recognition modules are capturing the fastest expansion as contactless protocols persist in healthcare and corporate settings. Cloud-based installation architectures are drawing disproportionate R&D investment because recurring software revenue and centralized fleet management improve lifetime customer value relative to standalone hardware sales.
The EU AI Act and GDPR impose strict boundaries on biometric data retention and automated decision-making, compelling terminal vendors to architect edge-processing capabilities that minimize cloud transmission of raw biometric templates. In the United States, NIST testing protocols and state-level biometric privacy laws in Illinois and Texas create a fragmented compliance landscape that favors modular designs permitting rapid firmware and sensor swaps. Stakeholders must monitor evolving algorithmic auditing requirements and decide whether to prioritize interoperable open-platform architectures or proprietary ecosystems that lock in recurring service revenue.
Market Dynamics
Edge-processing architectures are forcing terminal vendors to redesign hardware-software interfaces as the EU AI Act and GDPR mandate local biometric template storage, compressing cloud dependency and shifting R&D budgets toward on-device inference engines.
Growth Catalysts
- Healthcare contactless mandates:Hospital systems across Germany and France are replacing fingerprint readers with facial recognition modules to reduce pathogen transmission risks.
- EU AI Act transparency requirements:The regulation is accelerating demand for explainable liveness detection algorithms that audit decision trails without exposing raw biometric data.
- Industrial campus retrofit cycles:Manufacturing facilities in Bavaria and Baden-Württemberg are modernizing legacy badge systems with multi-factor biometric terminals.
Market Restraints
- Silicon substrate cost volatility:Capacitive sensor manufacturers face margin pressure from fluctuating 300mm wafer pricing and polymer substrate qualification delays.
- Algorithmic audit infrastructure gaps:The absence of standardized third-party testing frameworks for edge-processed biometric matching creates procurement hesitation among risk-averse buyers.
- Biometric template interoperability limits:Proprietary encoding formats from dominant hardware vendors lock deployed fleets into single-supplier maintenance contracts.
Strategic Opportunities
- Research park security modernization:Science and technology clusters in Heidelberg and Dresden are consolidating access control across multi-tenant facilities with modular terminal deployments.
- Convergence of biometric and mobile credentialing:Bluetooth Low Energy pairing with smartphone-based identity wallets is opening channel partnerships between terminal OEMs and enterprise mobility platforms.
- GDPR Article 35 data protection impact assessment services:Compliance consulting bundled with hardware sales creates recurring revenue streams for vendors serving mid-market buyers.
Industry Challenges
- Embedded systems firmware talent scarcity:Vendors struggle to recruit engineers with expertise in real-time operating systems and secure boot architectures for tamper-resistant enclosures.
- Legacy access control integration complexity:Retrofitting modular terminals into decades-old physical security infrastructure requires custom middleware development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Biometric Access Control Terminals Market |
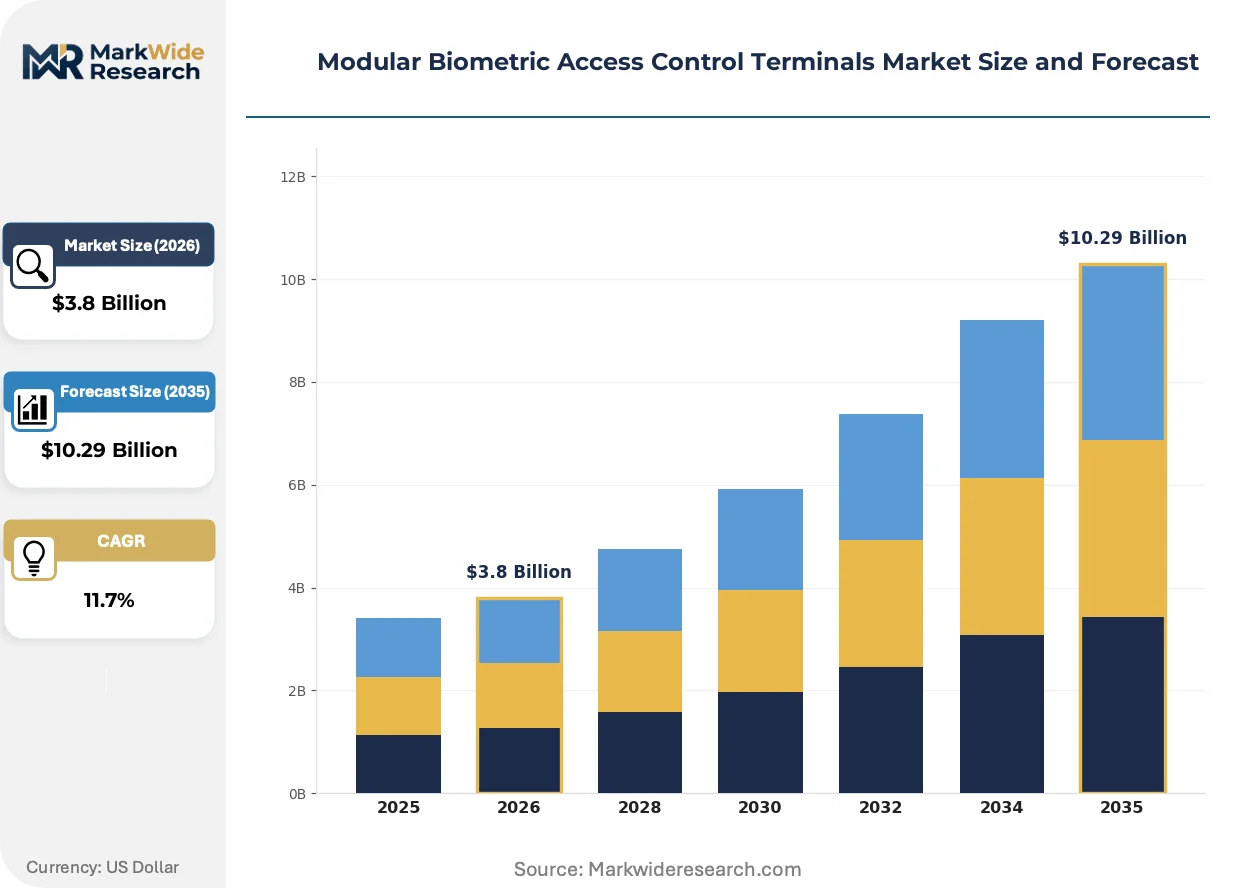
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerprint, Iris Recognition, Facial Recognition, Voice Recognition Technology: Optical Sensors, Capacitive Sensors, Thermal Sensors, Ultrasonic Sensors End User: Corporate Offices, Government Buildings, Educational Institutions, Healthcare Facilities Installation Type: Standalone, Networked, Integrated Solutions, Cloud-Based |
| Companies Covered | HID Global Corporation, BioSec Group Ltd., IDEMIA, NEXT Biometrics, Anviz Global, ASSA ABLOY AB, ZKTeco Europe, IdentyTech Solutions Ltd., Suprema Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Biometric Access Control Terminals Market Evolving Landscape
Algorithmic transparency mandates and substrate material shifts are compressing hardware margins while opening service revenue streams, redefining how terminal vendors capture lifetime value from enterprise deployments.
Flexible polymer sensor substrates are consolidating terminal form factor possibilities as manufacturers abandon rigid ceramic packages. Automotive and aerospace facilities with vibration-sensitive installations are adopting these substrates fastest. The shift is consolidating supplier power among polymer film coaters with cleanroom capabilities.
The EU AI Act's risk classification system for biometric identification is forcing architectural redesigns across the vendor base. High-risk system designations trigger mandatory conformity assessments and post-market monitoring obligations. German industrial buyers are prioritizing terminals with pre-certified algorithmic stacks to compress procurement timelines.
Facility managers are unbundling hardware acquisition from software subscription decisions, treating biometric terminals as interoperable endpoints rather than vertically integrated systems. This pattern is displacing traditional bundled pricing in corporate headquarters and data center deployments. The behavior is most pronounced in Frankfurt's financial district and Munich's technology corridors.
Modular Biometric Access Control Terminals Market Segmentation
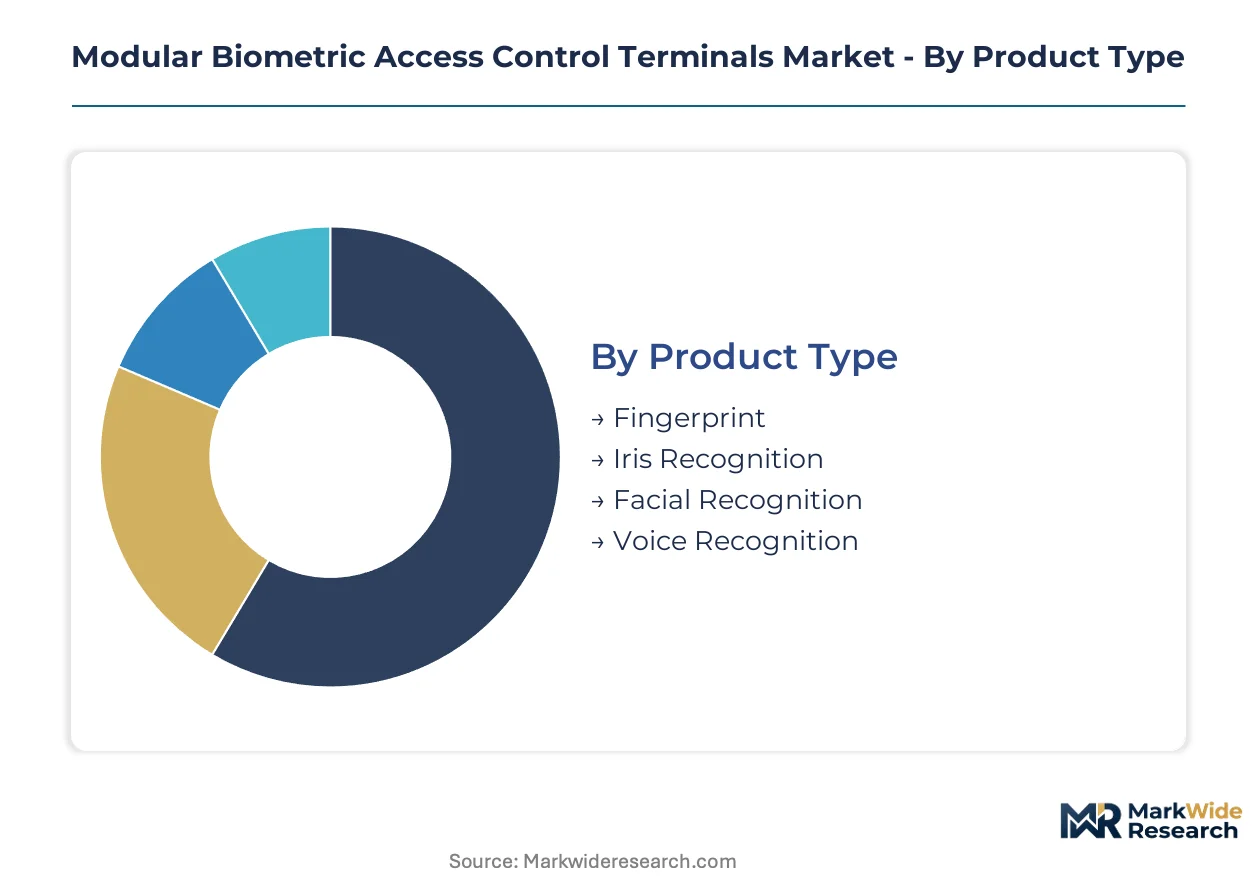
Modular biometric access control terminals fragment across sensor technologies, deployment architectures, and institutional buyer profiles. Procurement patterns diverge sharply between cost-sensitive volume buyers and compliance-driven premium adopters.
Product Type:
Buyers in this category differentiate primarily by hygiene protocols, throughput requirements, and user enrollment friction.
- Facial Recognition:Contactless authentication using structured light or time-of-flight depth mapping eliminates surface contact. Hospital systems in Germany and France are replacing legacy fingerprint readers to reduce nosocomial transmission risks. The EU AI Act's high-risk system classification is accelerating demand for pre-certified algorithmic stacks with explainable liveness detection.
- Fingerprint:Capacitive or optical ridge pattern matching dominates installed base economics due to mature sensor costs and established user familiarity. Bavarian manufacturing facilities continue specifying fingerprint modules for high-throughput worker turnstiles where enrollment speed outweighs contactless preferences.
- Iris Recognition:Near-infrared imaging of unique stromal patterns delivers false acceptance rates below one in one million. Critical infrastructure operators in Frankfurt's financial district specify iris modules for data center mantraps requiring maximum template security.
- Voice Recognition:Spectral analysis of vocal biometrics remains niche due to environmental noise sensitivity and replay attack vulnerabilities. Limited deployments concentrate in hands-free industrial settings where PPE prevents physical sensor contact.
Volume sits with fingerprint modules; growth tilts toward facial recognition.
Technology:
Sensor substrate selection determines terminal durability, power consumption, and integration complexity across deployment environments.
- Capacitive Sensors:Silicon-based substrates detect ridge patterns through electrical field distortion at the dermal interface. Manufacturers are shifting from rigid ceramic packages to flexible polymer alternatives to reduce unit costs and enable curved form factors for automotive facility installations.
- Optical Sensors:Charge-coupled device or CMOS imaging captures fingerprint ridges via frustrated total internal reflection. These modules retain cost advantages in mid-market corporate deployments where environmental sealing requirements remain moderate.
- Ultrasonic Sensors:Piezoelectric transducers emit acoustic pulses to map subdermal tissue structure, penetrating contaminants and moisture. Premium industrial specifications in Baden-Württemberg favor ultrasonic modules for outdoor turnstiles exposed to manufacturing debris.
- Thermal Sensors:Pyroelectric arrays detect temperature differentials between fingerprint ridges and valleys. Limited adoption persists in legacy government installations with established maintenance contracts.
Cost concentration favors optical architectures; capability premiums accrue to ultrasonic and capacitive alternatives.
End User:
Institutional procurement authority and compliance exposure shape specification rigor and replacement cycle timing.
- Healthcare Facilities:Contactless mandates and GDPR Article 35 data protection impact assessments drive rapid facial recognition adoption. German hospital systems prioritize terminals with edge-processing to minimize cloud transmission of raw biometric templates.
- Government Buildings:Security-cleared facility managers demand Common Criteria-certified enclosures and algorithmic transparency documentation. Federal procurement frameworks in Berlin and state-level contracts impose extended vendor qualification timelines.
- Corporate Offices:Lobby security modernization and multi-tenant access consolidation favor modular terminals with Bluetooth Low Energy mobile credential pairing. Frankfurt financial district tenants unbundle hardware from software subscriptions, treating terminals as interoperable endpoints.
- Educational Institutions:Budget-constrained universities in Heidelberg and Dresden defer replacement cycles, maintaining legacy badge systems with incremental biometric add-ons rather than full terminal swaps.
Revenue concentrates in corporate and government verticals; healthcare represents the steepest expansion trajectory.
Installation Type:
Architecture decisions determine recurring revenue capture and fleet management scalability for terminal vendors.
- Cloud-Based:Biometric templates process at edge while audit logs and configuration management centralize in vendor-hosted infrastructure. This architecture draws disproportionate R&D investment because recurring software revenue improves lifetime customer value relative to standalone hardware sales.
- Integrated Solutions:Biometric modules embed within broader physical security platforms combining video management, intrusion detection, and identity credentialing. Munich technology corridor deployments favor this approach to compress vendor management overhead.
- Networked:IP-connected terminals communicate with on-premises access control servers via encrypted channels. Mid-market manufacturing facilities in industrial parks specify networked architectures to retain data sovereignty while enabling centralized policy administration.
- Standalone:Self-contained terminals store templates locally without network dependency. Small commercial installations and remote outposts specify standalone units where infrastructure reliability or cybersecurity risk precludes connectivity.
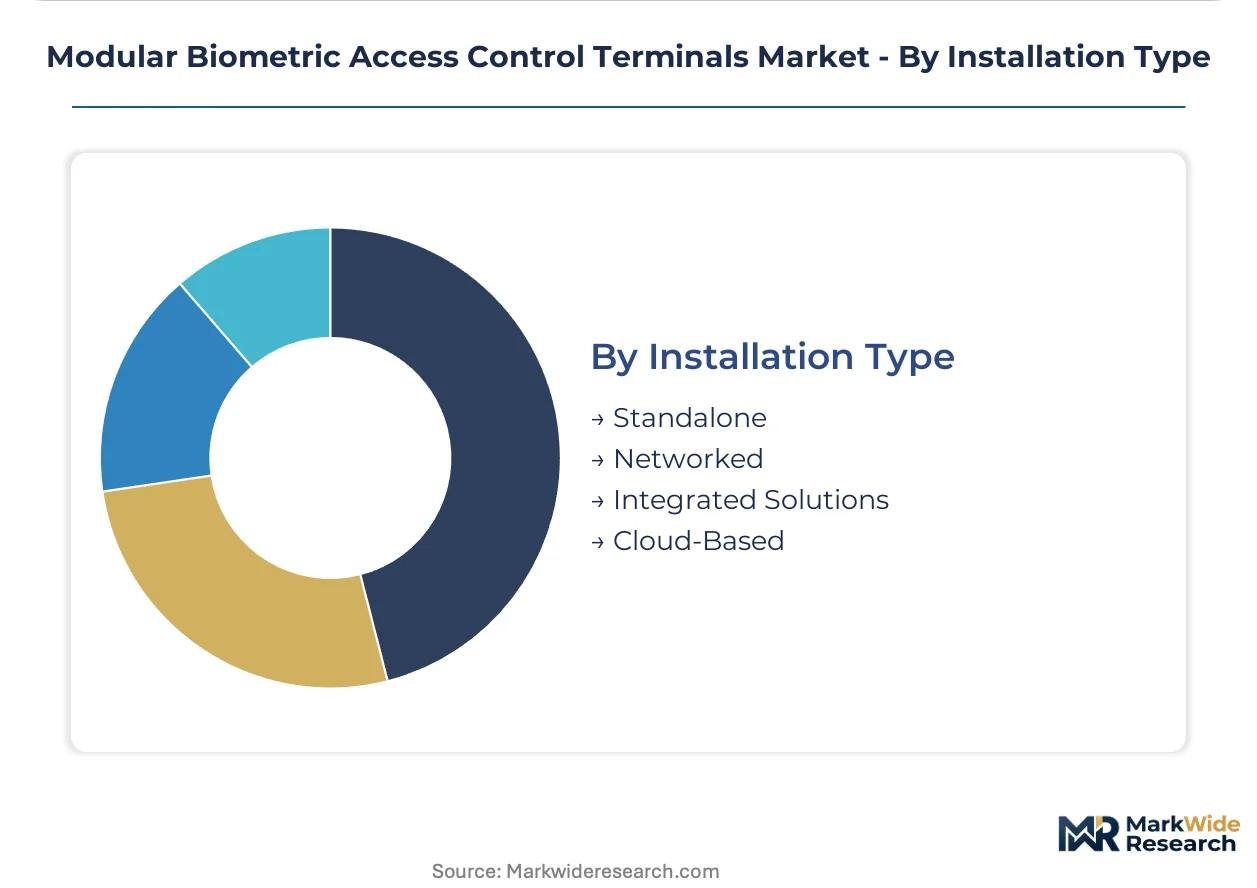
Deployment volume clusters in networked configurations; vendor strategic interest concentrates on cloud-based architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for modular biometric access control terminals concentrates in Germany, where industrial campuses and research parks drive retrofit cycles. Regulatory pressure from the EU AI Act and GDPR shapes procurement specifications across European markets. Corporate offices and healthcare facilities in specific metropolitan clusters anchor volume deployment.
Germany
Industrial campuses in Bavaria and Baden-Württemberg are retrofitting legacy badge systems with multi-factor biometric terminals. The EU AI Act's high-risk system classification triggers mandatory conformity assessments that compress procurement timelines for vendors with pre-certified algorithmic stacks. Frankfurt's financial district exhibits pronounced unbundling behavior, treating terminals as interoperable endpoints rather than vertically integrated systems.
France
Hospital systems across Paris and Lyon are replacing fingerprint readers with facial recognition modules to reduce nosocomial transmission risks. CNIL enforcement of GDPR Article 35 data protection impact assessments drives specification rigor for healthcare procurement. Science and technology clusters in the Île-de-France region are consolidating access control across multi-tenant facilities with modular terminal deployments.
United States
NIST testing protocols and state-level biometric privacy laws in Illinois and Texas create a fragmented compliance landscape favoring modular designs. Corporate headquarters in Chicago and Dallas specify terminals permitting rapid firmware and sensor swaps to navigate regulatory heterogeneity. Data center operators in Northern Virginia prioritize iris recognition modules for mantrap installations requiring maximum template security.
United Kingdom
London's financial services sector unbundles hardware acquisition from software subscription decisions, treating biometric terminals as interoperable endpoints. The Information Commissioner's Office guidance on automated decision-making shapes architectural preferences for edge-processing capabilities. Research parks in Cambridge and Oxford are consolidating access control infrastructure with modular deployments across multi-tenant science clusters.
Japan
Manufacturing facilities in the Chubu region around Nagoya specify ultrasonic sensor modules for outdoor turnstiles exposed to industrial debris. METI standards for industrial IoT security influence terminal procurement specifications in automotive and aerospace facilities. Tokyo-based corporate headquarters are adopting flexible polymer sensor substrates for vibration-sensitive lobby installations.
Modular Biometric Access Control Terminals Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium enterprise deployments favoring credentialing-integrated portfolios while mid-market installations gravitate toward volume-manufactured modules. The vendor base organizes into three strategic archetypes: secure identity conglomerates with hardware-software-credentialing integration, volume-focused sensor module specialists, and regional system integrators with custom middleware capabilities. Dominant competitive moves include backward integration into secure element manufacturing and geographic expansion through architectural hardware distribution channels.
Among the secure identity conglomerates, HID Global Corporation exemplifies the credentialing-integrated archetype through its vertical span across secure issuance and access control, while ASSA ABLOY AB anchors European distribution reach through architectural hardware channels. ZKTeco Europe occupies a position within the volume-manufacturing tier, competing aggressively on unit economics for fingerprint modules in mid-market installations. These three entities collectively represent the competitive spectrum from premium enterprise bundling to cost-optimized module supply.
| Leading Market Players |
|---|
| HID Global Corporation |
| BioSec Group Ltd. |
| IDEMIA |
| NEXT Biometrics |
| Anviz Global |
| ASSA ABLOY AB |
| ZKTeco Europe |
| IdentyTech Solutions Ltd. |
| Suprema Inc. |
| Others |
Value Network & Pricing Analysis
Embedded systems firmware engineers with real-time operating systems expertise cluster disproportionately in Bavaria and Baden-Württemberg, and this workforce concentration widens pricing spreads between premium certified terminals and mid-market alternatives as labor-cost differentials transmit through tiered product positioning.
Pricing Analysis
Volume concentrates in fingerprint modules while margins accrue to facial recognition with edge-processing capabilities. Three-tier pricing structure across premium, standard, and economy levels separates Common Criteria-certified government installations from mid-market corporate deployments and unbranded volume products. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because polymer substrate qualification delays are extending production cycles. Healthcare facilities in Germany exhibit lowest price sensitivity due to GDPR compliance mandates, while educational institutions in Heidelberg and Dresden drive economy-tier procurement.
Supply Chain Analysis
Common Criteria and EU AI Act pre-certification requirements gate supplier participation, compressing the qualified vendor base for high-risk biometric deployments. Silicon wafer fabrication concentrates in Taiwan, South Korea, and Germany, while flexible polymer film coating localizes in Japan and select European cleanroom facilities. Capacitive sensor production draws from 300mm silicon wafers, polymer substrates, and piezoelectric transducer materials. Single-source vulnerability runs through Taiwan-based foundry capacity for secure element manufacturing. Distribution runs through architectural hardware channels and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where credentialing-secure element manufacturing and algorithmic stack ownership represent the decisive upstream levers for sustainable margin capture.
For Market Incumbents: Deploy edge-processing algorithm certification as a defensive moat. HID Global and ASSA ABLOY should deepen in-house production of secure elements to reduce dependency on external foundry capacity. ZKTeco Europe must reinforce channel control through architectural hardware partnerships to defend against modular interoperability trends that commoditize hardware margins. The threat of GDPR Article 35 compliance consulting bundled by competitors necessitates rapid service-layer expansion. For New Entrants and Emerging Players: Ultrasonic sensor modules for debris-exposed industrial environments offer a technology-first wedge into underpenetrated outdoor turnstile specifications in Baden-Württemberg manufacturing corridors. Target research park security modernization in Dresden and Heidelberg where multi-tenant consolidation creates greenfield deployment opportunities. A go-to-market angle pairing Bluetooth Low Energy mobile credential integration with GDPR compliance consulting compresses procurement friction for mid-market buyers lacking in-house data protection expertise. For Investors and Strategic Acquirers: Re-rating potential sits with modular firmware specialists possessing real-time operating systems expertise given the embedded systems talent scarcity constraining incumbent R&D velocity. Long-term viability centers on vendors with captive algorithmic stacks and edge-processing architectures that minimize cloud dependency under EU AI Act constraints. Acquisition target archetype: mid-cap terminal OEMs with pre-certified biometric engines and established German industrial customer relationships. Watch for inflection when CNIL or German data protection authorities issue precedent-setting enforcement actions on cloud template transmission.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Secure Elements | Captive supply of tamper-resistant chips compresses foundry dependency for vendors targeting government certification. |
| Pre-Certified Algorithmic Stack Development | EU AI Act high-risk system designation accelerates procurement timelines for vendors with completed conformity assessments. |
| GDPR Compliance Service Bundling | Article 35 data protection impact assessment consulting creates recurring revenue streams sticky to hardware deployments. |
| Flexible Polymer Substrate Adoption | Automotive and aerospace lobby installations in Tokyo and Nagoya drive form factor differentiation. |
| Bluetooth Low Energy Mobile Credential Integration | Enterprise mobility platform partnerships open channel access to corporate headquarters unbundling hardware from software decisions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with access control system integrators, facility security managers at German industrial campuses, biometric sensor procurement leads, and GDPR compliance officers combined with secondary validation from EU AI Act implementation guidance, NIST biometric testing protocols, and ETSI cybersecurity standards. SEC filings from ASSA ABLOY and sector-specific trade publications provided demand-side triangulation against bottom-up terminal shipment estimates and top-down facility modernization spend patterns.
Granularity-level modeling disaggregated revenue across sensor technology, deployment architecture, and end-user vertical throughout the projection horizon. Segment-specific CAGRs derived from replacement cycle timing, regulatory compliance deadlines, and technology substitution curves. Installation type splits modeled cloud-based versus networked versus standalone configurations. Regional allocation incorporated country-specific GDPR enforcement intensity and EU AI Act risk classification implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU AI Act enforcement escalation or polymer substrate supply disruption. Forecasts reflect assumptions regarding edge-processing adoption rates, certification timeline compression, and healthcare contactless mandate persistence. A model refresh is warranted upon material change in CNIL enforcement precedent or NIST biometric testing protocol revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Mobile Turnstile Market
Access Control Systems
Turnstiles Access Control Systems Market
Access Control Systems
Global Fingerprint Access Control Systems Market
Access Control Systems
Door Controller Systems Market
Access Control Systems
Indoor Electromagnetic Lock Market
Access Control Systems
Smart Entry System Market
Access Control Systems
North America Keyless Vehicle Access Control System Market
Access Control Systems
Europe Cylinder Lock Market
Access Control Systems
APAC Home Security System Market
Access Control Systems
Middle East and Africa Card-Based Access Control Market
Access Control Systems
Car Security System Market
Access Control Systems
Mode Locking Device Market
Access Control Systems
Global Automated Border Control Market
Access Control Systems
GPS Smart Locks Market
Access Control Systems
Automatic Gate and Door Opening System Market
Access Control Systems
North America Access Control Software Market