
 North America Pin-Based Access Control Market | 2026-2036
North America Pin-Based Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pin-Based Access Control Market Insights
Enterprise data center operators is collapsing the historical dominance of pure commercial office buyers in North America pin-based access control procurement. HID Global Corporation leverages its dominance in credential interoperability standards across federal and enterprise accounts. Honeywell International Inc anchors its position through backward integration into building management software that unifies HVAC, fire, and access control on single dashboards. Bosch Security and Safety Systems competes through manufacturing scale in its North American production footprint, sustaining cost advantages on integrated system bundles.
North America pin-based access control comprises electromechanical entry devices that authenticate users through numeric credential entry, typically operating on 12-24V DC power with relay outputs for door strikes and magnetic locks, designed to restrict physical access to secured facilities and log entry events for audit compliance. Keypad and integrated system product categories command the largest installed base, though biometric scanner modules represent the fastest-growing attachment as facilities layer multi-factor authentication atop legacy PIN infrastructure. Cloud-based technology deployments are displacing standalone installations in mid-market commercial accounts, while hybrid architectures that bridge on-premises controllers with remote management portals capture the strongest margin pools across the technology dimension.
FCC equipment authorization requirements govern wireless transmission protocols, while NIST cybersecurity frameworks shape encryption standards for credential data transmission across networked controllers, and state biometric privacy laws in Illinois BIPA and Texas CUBI regulate how PIN systems interface with fingerprint or facial recognition modules. Compliance with these overlapping standards determines market access for hardware vendors and influences R&D allocation toward FIPS 140-2 validated encryption engines. Stakeholders must monitor evolving state-level privacy legislation that could restrict data retention periods for access logs and force architectural shifts toward edge-processed authentication.
Market Dynamics
Cloud-managed credential systems are collapsing the traditional standalone controller architecture across United States and Canadian facilities, forcing hardware vendors to reengineer firmware stacks for zero-trust network segmentation.
Growth Catalysts
- Multi-factor authentication mandates:NIST SP 800-63 guidelines compel federal contractors and critical infrastructure operators to layer biometric verification atop legacy PIN entry. Procurement specifications now require FIPS 140-2 validated encryption modules.
- Data center construction boom:Hyperscale cloud providers across Northern Virginia, Phoenix, and Toronto are specifying networked access control with API integrations into visitor management platforms.
- State biometric privacy statutes:Illinois BIPA and Texas CUBI create compliance-driven replacement cycles for facilities upgrading from pure PIN to PIN-plus-biometric systems.
Market Restraints
- Semiconductor supply concentration:Microcontroller shortages concentrated in Taiwanese foundries delay controller board production for North American OEMs.
- Cybersecurity liability exposure:Networked controllers create attack surfaces that property insurers increasingly exclude from standard commercial policies.
- Installation labor scarcity:Certified low-voltage technicians in the Great Lakes corridor command premium wages that compress integrator margins on retrofit projects.
Strategic Opportunities
- Edge-processed authentication:On-device biometric matching eliminates cloud data retention risks and satisfies Illinois BIPA's storage limitation requirements.
- Mid-market commercial penetration:Canadian multi-tenant office buildings in Calgary and Montreal remain underpenetrated by cloud-managed systems.
- API-first platform architectures:Native integrations with building management software and occupancy analytics create recurring revenue streams beyond hardware sales.
Industry Challenges
- Legacy system interoperability:Wiegand protocol dependencies in installed base force complex middleware development for hybrid cloud-on-premises deployments.
- State-by-state compliance fragmentation:Divergent biometric data retention rules across Illinois, Texas, and emerging state statutes multiply firmware variant testing requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pin-Based Access Control Market |
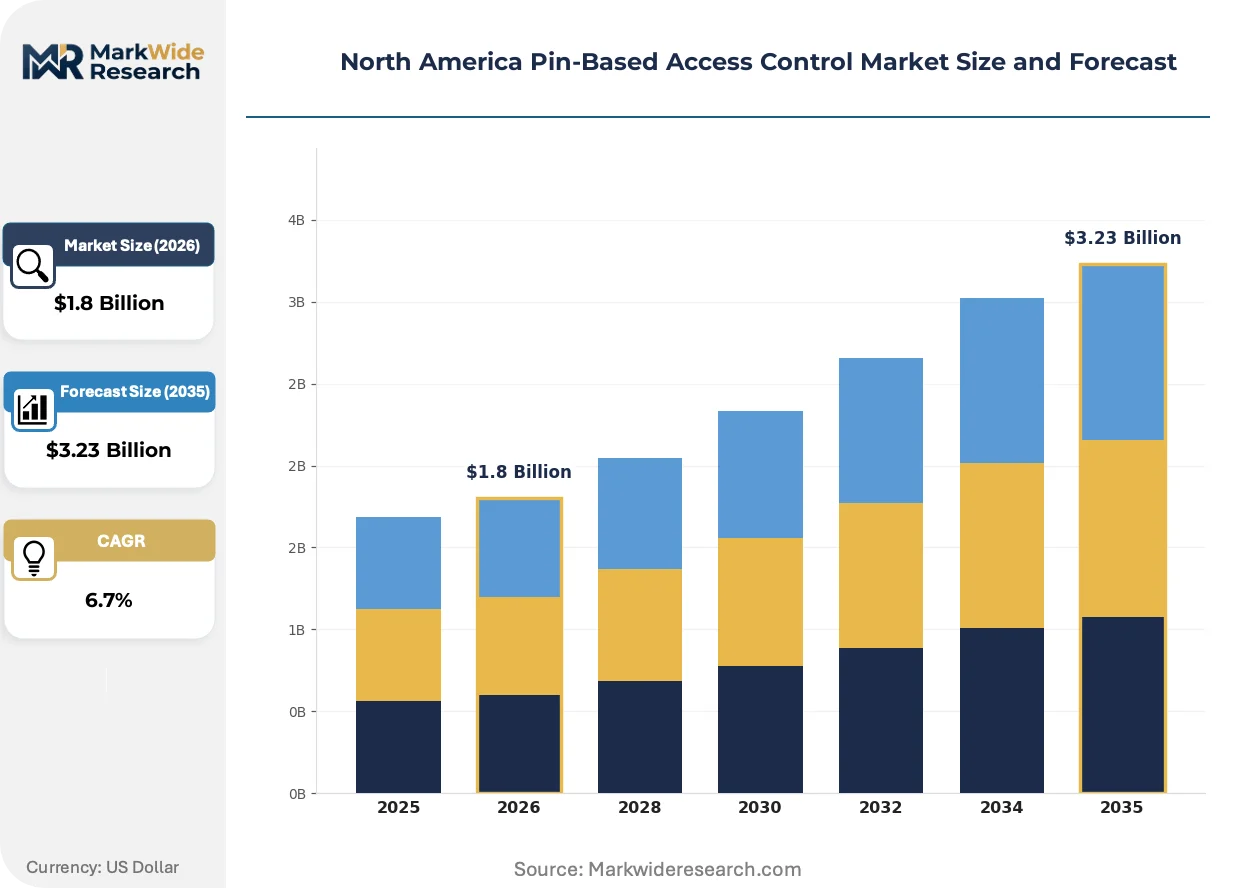
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Keypad, Card Reader, Biometric Scanner, Integrated System End User: Commercial, Residential, Government, Industrial Technology: Wireless, Wired, Hybrid, Cloud-Based Installation Type: Standalone, Centralized, Networked, Mobile |
| Companies Covered | Johnson Controls, HID Global Corporation, Honeywell International Inc, Bosch Security and Safety Systems, Salto Systems SL, Axis Communications AB, Napco Security Technologies Inc, dormakaba Group, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pin-Based Access Control Market Trends and Innovations
Authentication hardware is fragmenting into two distinct performance tiers as buyers separate high-security federal applications from cost-optimized commercial retrofits.
Mobile credential technology is bifurcating the installed base. Smartphone-based Bluetooth and NFC entry eliminates physical credential provisioning costs for enterprise campuses. University and healthcare systems in California and Massachusetts are piloting phone-as-credential at scale. This shift is compressing demand for traditional keypad-only devices in price-sensitive segments while creating premium attach rates for dual-authentication controllers.
FCC Part 15 equipment authorization rules are tightening emission standards for wireless access control modules. Manufacturers must redesign 2.4 GHz transceiver circuits to satisfy updated unintentional radiator limits. Federal facility integrators face extended certification timelines that delay deployment schedules.
Buyer contracting patterns are consolidating purchasing authority. Corporate real estate departments are centralizing access control procurement across distributed facility portfolios. National account pricing agreements are displacing branch-level vendor selection in retail and hospitality chains. This concentration is most visible among quick-service restaurant operators standardizing on single-platform rollouts.
North America Pin-Based Access Control Market Segmentation
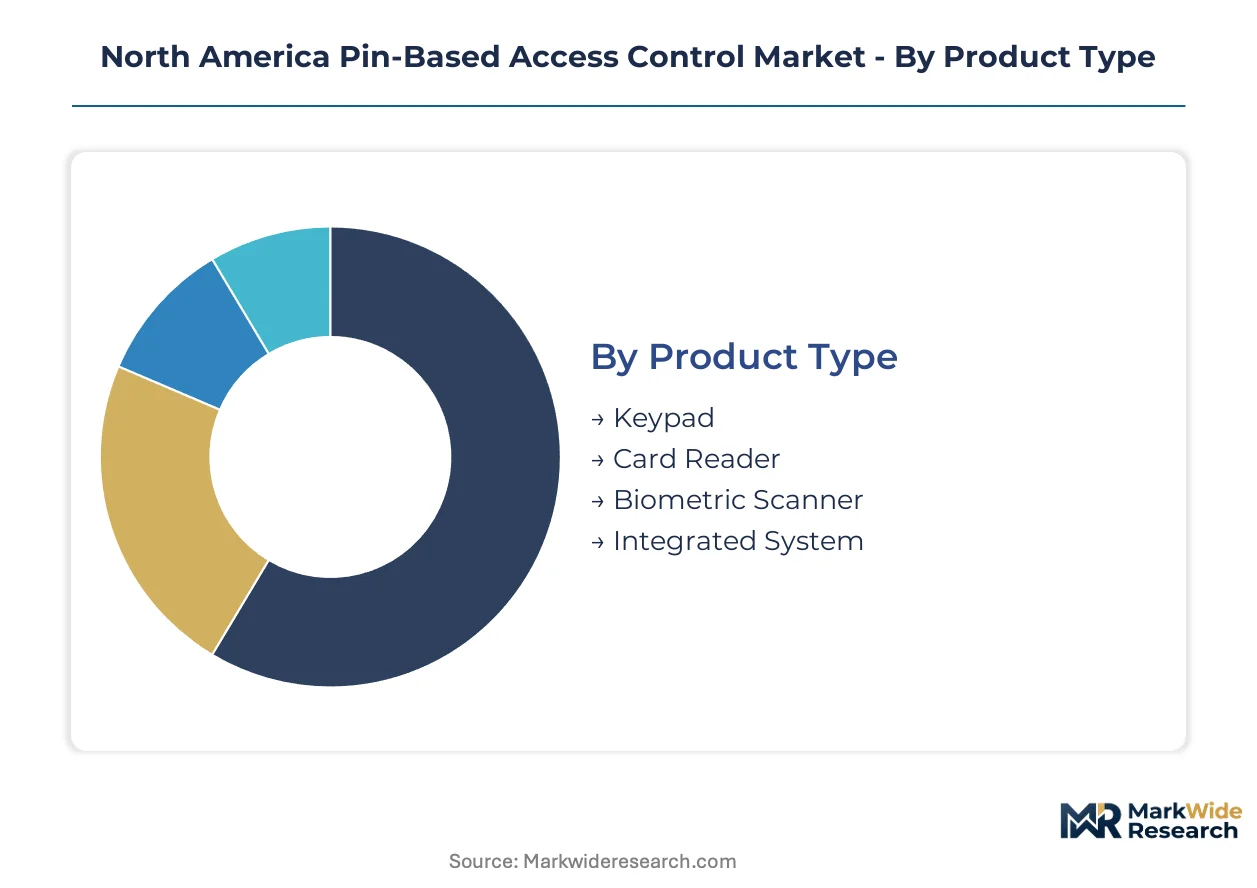
Pin-based access control procurement patterns diverge sharply across product architectures and deployment contexts. Understanding these fault lines clarifies where substitution pressure from mobile credentials and biometric alternatives will reshape vendor revenue pools.
Product Type:
Keypad-only hardware faces the most acute substitution threat as facilities layer biometric and mobile authentication atop legacy PIN infrastructure.
- Keypad:Standalone numeric entry devices operating on 12-24V DC power with relay outputs for door strikes. Demand concentrates in cost-sensitive commercial retrofits across the Great Lakes industrial corridor where automotive facilities prioritize perimeter modernization over interior credential complexity.
- Integrated System:Multi-factor controllers combining PIN entry with card readers, biometric modules, and network connectivity. Data center operators in Northern Virginia and Toronto specify these for visitor management platform integration, driving specification upgrades from pure keypad systems.
- Card Reader:Magnetic stripe and proximity credential readers with PIN verification backup.
- Biometric Scanner:Fingerprint and facial recognition modules attaching to legacy PIN controllers.
Keypad devices anchor the volume base while integrated systems gain share at the steepest rate.
End User:
Cost tier differentiation separates high-compliance federal applications from price-optimized commercial installations.
- Commercial:Office campuses, retail chains, and hospitality properties deploying networked credential systems. Corporate real estate departments centralizing procurement across distributed portfolios favor cloud-managed platforms with API integrations into building management software.
- Government:Federal facilities and critical infrastructure operators subject to NIST SP 800-63 multi-factor mandates. FIPS 140-2 validated encryption modules and zero-trust network segmentation requirements drive premium specification tiers unavailable to commercial buyers.
- Industrial:Manufacturing and logistics facilities requiring ruggedized hardware for harsh environments.
- Residential:Multi-tenant apartment buildings and gated communities with simplified credential management needs.
Commercial installations dominate unit shipments while government procurement commands the highest average selling prices.
Technology:
Volume concentration favors established wired architectures, though cloud deployments capture expanding margin pools.
- Cloud-Based:Remote management portals with edge-processed authentication eliminating centralized data retention. Mid-market commercial accounts in Canadian cities including Calgary and Montreal are displacing standalone installations with subscription-managed platforms.
- Hybrid:Bridging on-premises controllers with remote management capabilities. This architecture satisfies Illinois BIPA biometric data storage limitations by processing credentials at the device level while maintaining centralized audit logging.
- Wired:Traditional RS-485 and Ethernet-connected controller networks.
- Wireless:2.4 GHz transceiver modules subject to tightening FCC Part 15 emission standards.
Wired infrastructure retains the largest installed base while cloud-based deployments expand most quickly across new construction.
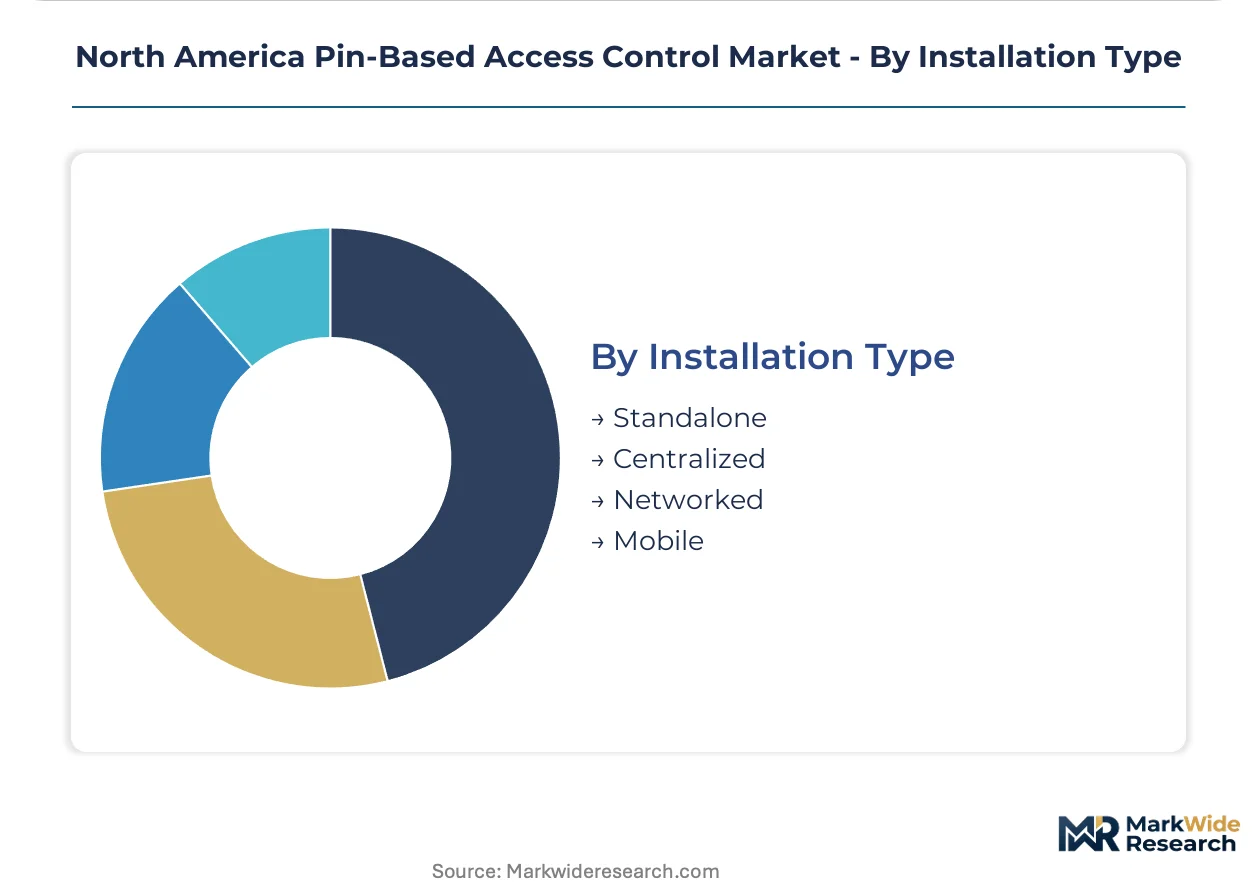
Installation Type:
Customer type fragmentation separates enterprise centralized deployments from distributed standalone retrofits.
- Networked:IP-connected controllers with real-time event logging and centralized credential provisioning. Hyperscale cloud providers across Phoenix and Toronto specify these for API integration into facility-wide security orchestration.
- Standalone:Single-door controllers with local programming and no network dependency. Price-sensitive retail and hospitality chains favor these for rapid deployment without IT infrastructure dependencies.
- Centralized:Master controller architectures managing multiple entry points from a single processor.
- Mobile:Smartphone-based Bluetooth and NFC entry systems eliminating physical credential provisioning.
Standalone devices retain dominance in retrofit applications while networked systems capture the majority of new construction specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Controller board manufacturing concentrates in Taiwanese foundries, creating supply bottlenecks that ripple through North American OEM procurement cycles. Regional deployment patterns diverge sharply between federal compliance corridors and commercial retrofit zones.
United States
Hyperscale data center construction across Northern Virginia and Phoenix is driving networked access control specifications with API integration requirements. NIST SP 800-63 guidelines mandate FIPS 140-2 validated encryption for federal contractors. Illinois BIPA and Texas CUBI statutes are forcing PIN-plus-biometric upgrades in Chicago and Dallas corporate campuses.
Canada
Multi-tenant office buildings in Calgary and Montreal remain underpenetrated by cloud-managed platforms, creating whitespace for subscription-based deployments. Health Canada equipment authorization rules govern wireless module certification timelines. Toronto's financial district is specifying hybrid architectures that bridge on-premises controllers with remote management portals.
Mexico
Manufacturing facilities in Nuevo León and the Bajío Region are modernizing physical security perimeters as nearshoring accelerates automotive and electronics production. Mexican federal cybersecurity standards are aligning with NIST frameworks for cross-border facility operators. Monterrey industrial parks are deploying ruggedized keypad systems for harsh factory environments.
North America Pin-Based Access Control Market Competitive Landscape
Concentration sits with diversified building technology conglomerates that leverage backward integration into software platforms and credential interoperability standards. Three to five integrated security providers command premium positions in federal and enterprise accounts, while mid-tier specialists compete on cost-optimized commercial retrofits. Strategic moves center on API-first platform development and edge-processed authentication architectures that satisfy state biometric privacy constraints. Partnerships with building management software vendors are displacing standalone hardware sales models.
Among diversified technology conglomerates, Johnson Controls and Honeywell International Inc occupy positions that exemplify building-systems integration strategies, anchoring their market presence through unified HVAC, fire, and access control dashboards. HID Global Corporation represents the credential interoperability archetype, with its federal and enterprise account penetration shaped by standards adoption patterns. Bosch Security and Safety Systems sits within the manufacturing-scale tier, competing through North American production footprint advantages on bundled system offerings.
| Leading Market Players |
|---|
| Johnson Controls |
| HID Global Corporation |
| Honeywell International Inc |
| Bosch Security and Safety Systems |
| Salto Systems SL |
| Axis Communications AB |
| Napco Security Technologies Inc |
| dormakaba Group |
| Thales Group |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation contracts with Taiwanese foundries lock in microcontroller supply for North American OEMs while fixing component costs across volatile semiconductor cycles. This arrangement grants price visibility to integrators bidding on federal projects with FIPS 140-2 encryption requirements.
Pricing Analysis
NIST SP 800-63 guidelines dictate the pricing tier structure across federal and commercial segments. Three-tier pricing structure across premium, standard, and economy levels separates FIPS-validated encryption modules from commercial-grade controllers and basic keypad units. Certification grade and volume scale drive price differentiation, with hyperscale data center operators commanding enterprise discounts unavailable to mid-market buyers. Cost compression in the keypad-only tier intensifies because mobile credential substitution erodes hardware attach rates. Price-sensitive retail and hospitality chains favor standalone devices, while federal contractors absorb premium pricing for zero-trust network compliance.
Supply Chain Analysis
Taiwan Strait transit vulnerability exposes North American controller board production to geopolitical disruption. Semiconductor fabrication concentrates in Taiwan, South Korea, and Japan, while final assembly draws from Mexico and the United States. Microcontroller shortages, relay modules, and 2.4 GHz transceiver circuits constitute critical input dependencies. Single-source vulnerability in Taiwanese foundries creates procurement bottlenecks that delay OEM production schedules. Distribution runs through security integrators and building automation distributors serving federal, enterprise, and commercial verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
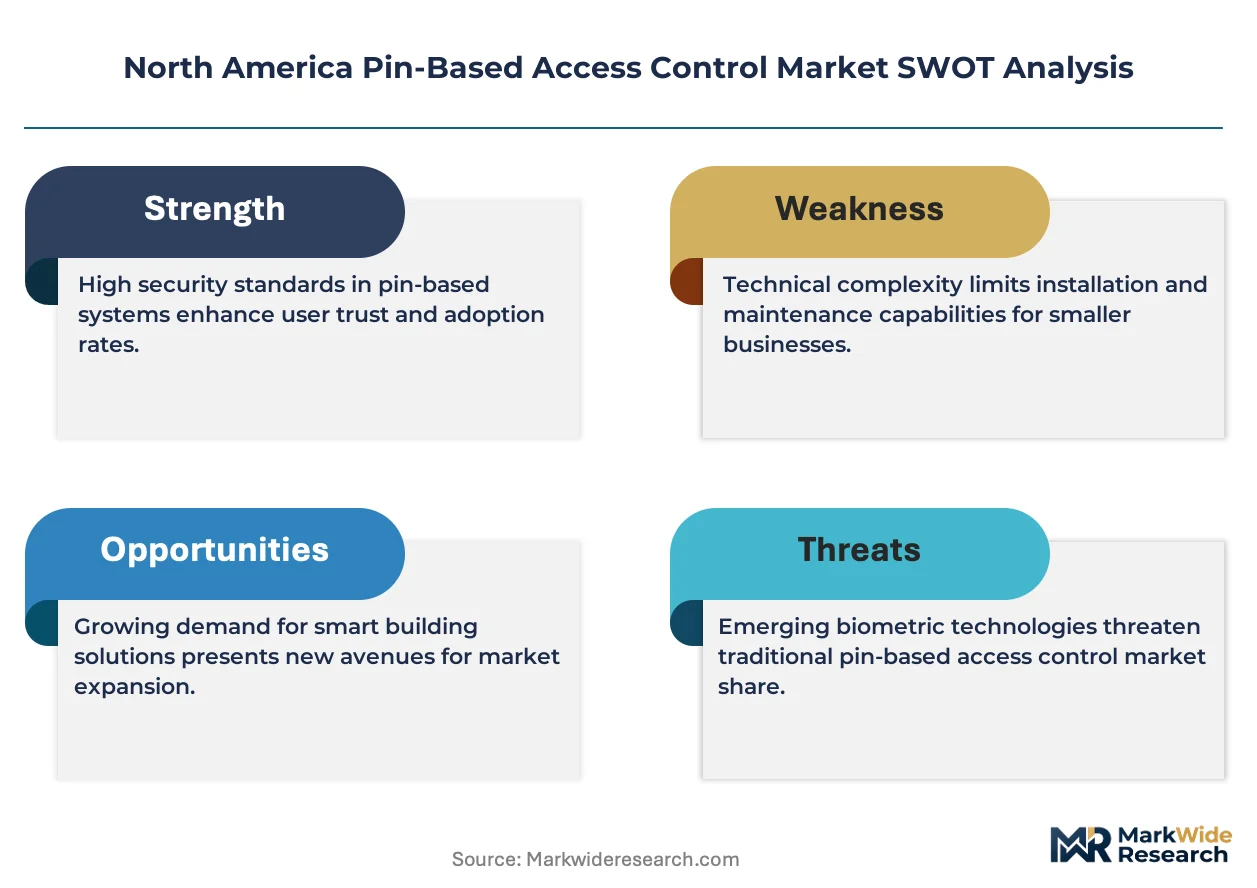
Fragmentation across state biometric privacy statutes creates specialized compliance niches for vendors architecting edge-processed authentication. Mid-market commercial accounts remain underserved by unified platform providers.
For Market Incumbents: Compound software platform stickiness through API-first architectures that embed access control into building management dashboards. Defend against mobile credential substitution by attaching biometric modules to legacy PIN infrastructure. Prioritize backward integration into edge-processing chipsets that satisfy Illinois BIPA storage limitations without cloud dependency. Channel control through certified integrator networks in the Great Lakes corridor protects margin pools from price-optimized competitors. For New Entrants and Emerging Players: Anchor in Canadian multi-tenant office buildings across Calgary and Montreal, where cloud-managed platform penetration lags United States adoption curves. Target mid-market commercial retrofits with subscription-priced hybrid architectures bridging on-premises controllers with remote management portals. Pursue a vertical-specialist go-to-market angle focused on healthcare systems piloting phone-as-credential deployments in California and Massachusetts. For Investors and Strategic Acquirers: Capital is best deployed toward edge-authentication specialists with FIPS 140-2 validation and state privacy compliance firmware. Long-term viability hinges on architectural flexibility as biometric regulations proliferate across jurisdictions. The acquisition target archetype combines hardware manufacturing scale with native software platform development. Watch for inflection signals in state-level data retention rule expansions beyond Illinois and Texas.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Processed Authentication Development | On-device biometric matching satisfies Illinois BIPA storage constraints without cloud data retention risks. |
| API-First Platform Integration | Native building management software connections create recurring revenue beyond hardware transaction cycles. |
| State Privacy Compliance Certification | Firmware variants addressing Illinois BIPA and Texas CUBI unlock procurement specifications in regulated corridors. |
| Canadian Market Expansion | Cloud-managed platform deployment in underpenetrated Calgary and Montreal multi-tenant buildings captures whitespace. |
| Zero-Trust Network Architecture | Federal contractor mandates for NIST SP 800-63 compliance drive premium-tier controller specifications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with security integrators, federal procurement officers, and building automation engineers; and secondary validation through FCC equipment authorization databases, NIST cybersecurity framework publications, state legislative records for Illinois BIPA and Texas CUBI, and SEC filings from diversified building technology conglomerates. Bottom-up triangulation across controller shipment estimates and top-down reconciliation against facility construction permits anchored market sizing.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product architecture, end-user compliance tier, deployment technology, and regional regulatory cluster. CAGRs were derived from facility modernization cycle analysis and substitution elasticity between keypad, biometric, and mobile credential modalities. Forecast inputs incorporated hyperscale data center construction pipelines and state biometric privacy statute adoption trajectories.
Decision-makers should treat outputs as directional under assumptions of stable NIST guideline continuity and no federal preemption of state biometric privacy laws; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as semiconductor supply concentration and state-level data retention rule expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Global Automatic Door Control Market
Access Control Systems
Europe Proximity Access Control Market
Access Control Systems
Latin America Proximity Access Control Market
Access Control Systems
Middle East and Africa Proximity Access Control Market
Access Control Systems
Mobile Turnstile Market
Access Control Systems
Latin America Card-Based Access Control Market
Access Control Systems
Asia-Pacific Proximity Access Control Market
Access Control Systems
GPS Smart Locks Market
Access Control Systems
Japan Smart Lock Market
Access Control Systems
Europe Access Control Software Market
Access Control Systems
Acousto-Magnetic (AM) Security Systems Market
Access Control Systems
APAC Home Security System Market
Access Control Systems
Smart Locker Locks Market
Access Control Systems
Asia-Pacific Access Control Hardware Market
Access Control Systems
Global Automated Border Control Market
Access Control Systems
Port Security Systems Market