
 US Restricted Access Barrier System Market | 2026-2036
US Restricted Access Barrier System Market Size, Share, and Industry Trends Forecast 2026-2036
US Restricted Access Barrier System Market Intelligence
Aftermarket service revenue is tilting from equipment-only transactions toward lifecycle containment management contracts. SKAN AG leverages its Swiss-engineered isolator heritage to sustain premium positioning in US biologics fill-finish operations. Germfree Laboratories, Inc. anchors its competitive stance through modular cleanroom-barrier integration for military and pharmaceutical clients. COMECER S.p.A. differentiates via integrated decontamination and material transfer systems for radiopharmaceutical applications.
A restricted access barrier system constitutes an enclosure providing defined levels of separation between an aseptic processing line and its surrounding environment, typically achieving ISO 5 internal conditions through unidirectional airflow of 0.36–0.54 m/s and positive pressure differentials of 10–20 Pascals. Its primary purpose is to protect sterile drug products from microbial and particulate contamination while permitting operator intervention through glove ports. Automatic barriers lead product type demand as continuous manufacturing lines replace batch operations in vaccine and cell therapy production. RFID technology segments gain structural momentum as facilities integrate electronic batch records with physical access logging for FDA audit trails. Permanent installations dominate capital expenditure, though portable solutions expand in clinical trial material suites requiring rapid reconfiguration.
FDA cGMP guidance and USP <797> compounding standards mandate physical separation technologies for sterile hazardous and non-hazardous preparations, directly shaping barrier system specifications and validation protocols. OSHA workplace exposure limits and EPA containment requirements for potent compound handling further tighten engineering control obligations across pharmaceutical manufacturing and hospital pharmacy settings. Stakeholders must monitor evolving FDA guidance on advanced manufacturing technologies and determine whether isolator-based continuous processing investments align with upcoming product pipelines and inspection precedents.
Market Dynamics
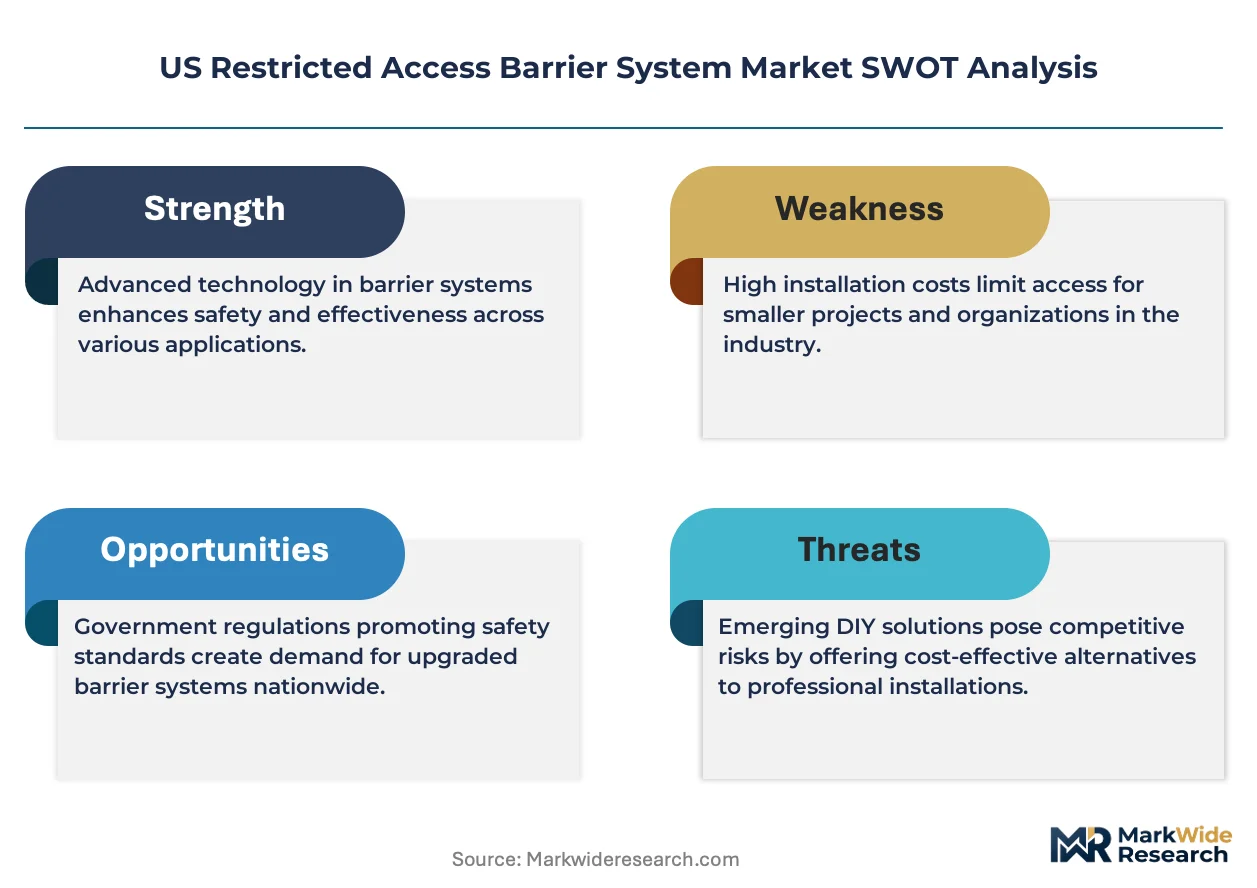
FDA cGMP Annex 1 revisions and USP <797> enforcement are compressing upgrade timelines for sterile processing infrastructure across pharmaceutical manufacturing and hospital compounding facilities.
Growth Catalysts
- Biologics fill-finish expansion:Cell therapy and mRNA vaccine production lines require closed barrier systems to maintain ISO 5 conditions during high-potency drug handling.
- FDA cGMP Annex 1:The 2022 revision mandates physical separation technologies for aseptic processing, compelling facilities to replace open fronted cabinets with restricted access barriers.
- OSHA workplace exposure limits:Stricter containment requirements for hazardous drug compounding in hospital pharmacies drive glove-port isolator installations.
Market Restraints
- Stainless steel and HEPA filter cost volatility:Input material price swings compress margins for barrier system fabricators during project bidding cycles.
- Validation timeline extension:FDA inspection backlogs and IQ/OQ/PQ documentation requirements stretch project completion from 12 to 18 months.
- Skilled containment engineer scarcity:Limited pool of professionals qualified in unidirectional airflow modeling and smoke pattern analysis restricts installation capacity.
Strategic Opportunities
- RFID-integrated access logging:Electronic batch record synchronization with physical barrier entry creates audit-ready documentation for FDA inspections.
- Portable barrier systems:Clinical trial material suites in Research Triangle Park and San Diego demand rapid reconfiguration capabilities for multi-product campaigns.
- Radiopharmaceutical containment:PET tracer production expansion requires integrated decontamination and material transfer systems with lead shielding compatibility.
Industry Challenges
- Legacy facility retrofit complexity:Older pharmaceutical plants in Puerto Rico and New Jersey face HVAC infrastructure constraints when upgrading to positive pressure differentials of 10–20 Pascals.
- Continuous manufacturing integration:Isolator-based processing lines require revalidation of existing cleaning protocols and environmental monitoring programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Restricted Access Barrier System Market |
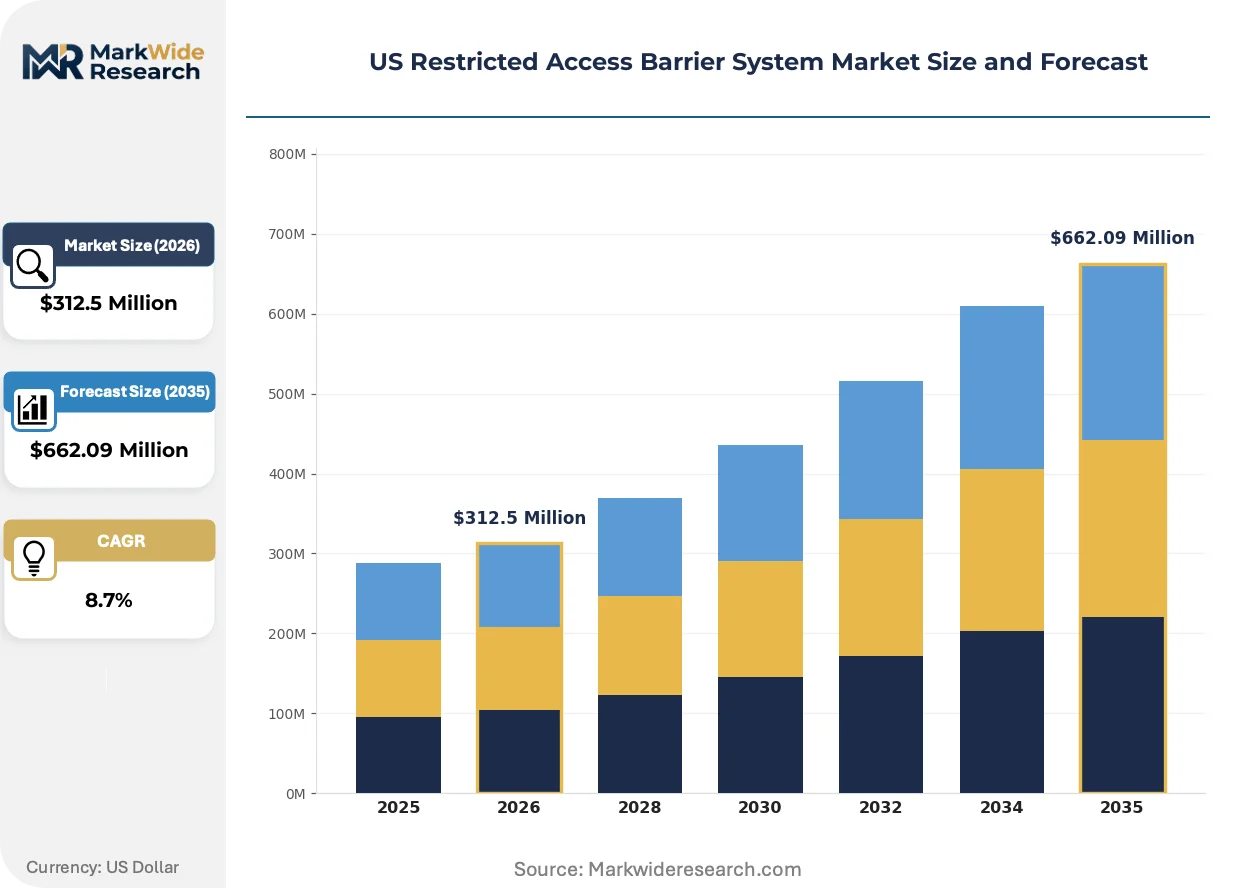
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Barriers, Manual Barriers, Mobile Barriers, Arm Barriers End User: Commercial Properties, Airports, Parking Facilities, Industrial Sites Technology: RFID, Biometric Systems, Keypad Entry, Remote Control Installation Type: Temporary Installation, Permanent Installation, Portable Solutions, Integrated Systems |
| Companies Covered | I.M.A. Industria Macchine Automatiche S.P.A., Germfree Laboratories, Inc., Extract Technology, AZBIL TELSTAR, S.L.U., Syntegon Technologies GmbH, Isolation Systems Inc., COMECER S.p.A., SKAN AG, Ortner Reinraumtechnik GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Restricted Access Barrier System Market Strategic Shifts & Innovations
Barrier system architecture is converging with digital manufacturing infrastructure and advanced decontamination modalities, reshaping how facilities validate and operate containment environments.
Isolator technology is hybridizing with vaporized hydrogen peroxide (VHP) biodecontamination systems to achieve 6-log spore kill validation in under 90 minutes. Biologics manufacturers in Massachusetts and California are retrofitting existing lines with this integrated approach. The convergence is compressing batch turnover cycles and enabling same-day product changeovers that were previously impossible with manual cleaning protocols.
FDA guidance on advanced manufacturing technologies is forcing barrier system suppliers to pre-validate digital twin configurations for continuous processing submissions. The agency's emerging framework for real-time release testing demands sensor-integrated isolators with embedded particle counters and pressure differential telemetry. Fill-finish operations in North Carolina's Research Triangle are piloting these connected systems to align with upcoming inspection precedents.
Service contract unbundling is fragmenting the traditional equipment-plus-installation sale. Hospital compounding pharmacies in the Northeast corridor now procure barrier systems through third-party equipment financiers while negotiating separate lifecycle containment management agreements with original manufacturers. The disaggregation is most pronounced in multi-site health systems seeking standardized validation protocols across Massachusetts, Connecticut, and New Jersey facilities.
US Restricted Access Barrier System Market Segmentation
Barrier system procurement in the US diverges sharply across operational environments, from pharmaceutical cleanrooms requiring ISO 5 unidirectional airflow to hospital compounding suites governed by USP <797>. Segmentation reveals how FDA cGMP Annex 1 enforcement and OSHA workplace exposure limits reshape equipment specifications and validation protocols across distinct use cases.
Product Type:
Use-case spectrum spans continuous manufacturing lines demanding automated containment to flexible clinical trial configurations requiring manual intervention capabilities.
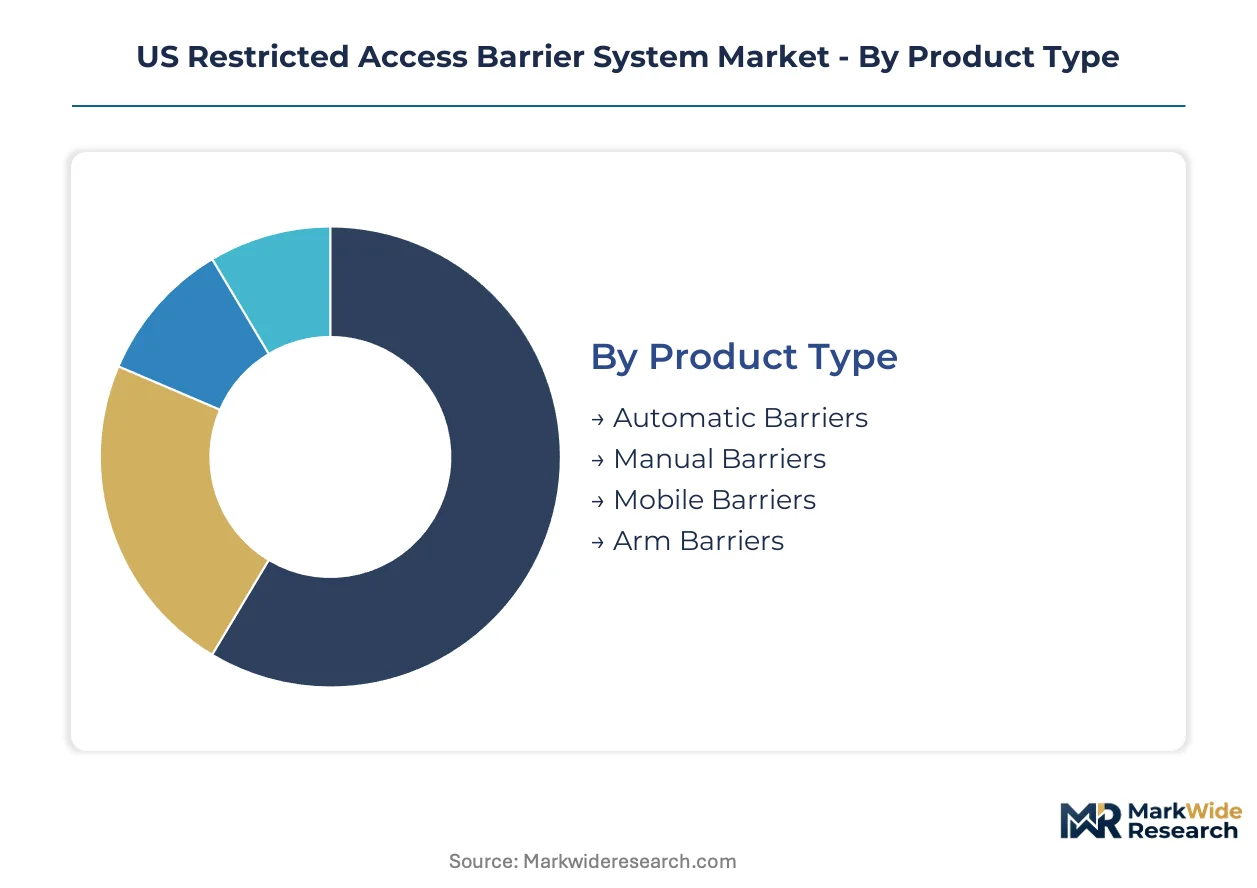
- Automatic Barriers:Enclosures with integrated glove ports and robotic material handling achieve 0.36–0.54 m/s unidirectional airflow without operator breach. Massachusetts biologics fill-finish facilities deploy these for mRNA vaccine production where batch integrity demands zero human contact during critical processing phases. FDA cGMP Annex 1 physical separation mandates accelerate replacement of open-fronted cabinets with these closed systems.
- Manual Barriers:Operator-dependent glove-port configurations permit direct intervention through sealed sleeve systems. Hospital compounding pharmacies in the Northeast corridor favor these for hazardous drug preparation where USP <797> requires physical separation but batch sizes don't justify full automation. OSHA workplace exposure limits for chemotherapy compounding tighten engineering control specifications.
- Mobile Barriers:Castor-mounted isolators with quick-connect HVAC interfaces enable rapid suite reconfiguration. Research Triangle Park clinical trial material operations use these for multi-product campaigns requiring frequent decontamination cycles.
- Arm Barriers:Articulated sleeve systems extend operator reach into confined processing zones. Radiopharmaceutical PET tracer production in California employs lead-shielded variants for isotope handling.
Established volume favors automatic barriers; emerging adoption favors mobile barriers.
End User:
Cost tier stratification separates capital-intensive pharmaceutical infrastructure from operational expenditure models in healthcare and logistics settings.
- Commercial Properties:Corporate campus cleanrooms and biotechnology incubator facilities require scalable containment for contract manufacturing organizations. San Diego and Boston-Cambridge clusters drive specification demand for modular barrier integration with shared HVAC infrastructure.
- Airports:Federal screening operations and customs pharmaceutical inspection facilities utilize portable glove-port systems for controlled substance handling. TSA and CBP operational requirements shape durability and access logging specifications.
- Parking Facilities:Hospital pharmacy receiving docks and pharmaceutical distribution centers deploy weatherized barriers for controlled-environment material transfer. Cold chain integrity demands intersect with physical security protocols.
- Industrial Sites:Chemical manufacturing and potent compound handling operations require explosion-rated isolator configurations. EPA containment requirements for hazardous air pollutants govern material selection and pressure differential engineering.
Pharmaceutical manufacturing commands premium pricing tiers; hospital and logistics applications expand through standardized validation packages.
Technology:
Application criticality determines authentication complexity, from batch record integration to basic access control.
- RFID:Embedded credential systems synchronize physical access with electronic batch records for FDA audit trail compliance. North Carolina fill-finish operations pilot these for real-time release testing alignment with emerging inspection precedents.
- Biometric Systems:Fingerprint and iris recognition eliminate credential transfer risks in high-potency drug handling. New Jersey pharmaceutical corridors adopt these for DEA-controlled substance containment where operator identity verification is non-negotiable.
- Keypad Entry:PIN-based access suits lower-risk hospital compounding of non-hazardous preparations. USP <797> physical separation requirements are satisfied without the cost burden of biometric infrastructure.
- Remote Control:Wireless actuation enables external operation during VHP decontamination cycles. Integrated biodecontamination systems in California cell therapy facilities leverage this for 6-log spore kill validation.
RFID and biometric systems gain share fastest in regulated pharmaceutical environments; keypad and remote configurations persist in cost-constrained healthcare settings.
Installation Type:
Customer type and facility lifecycle stage dictate capital deployment flexibility versus permanent infrastructure commitment.
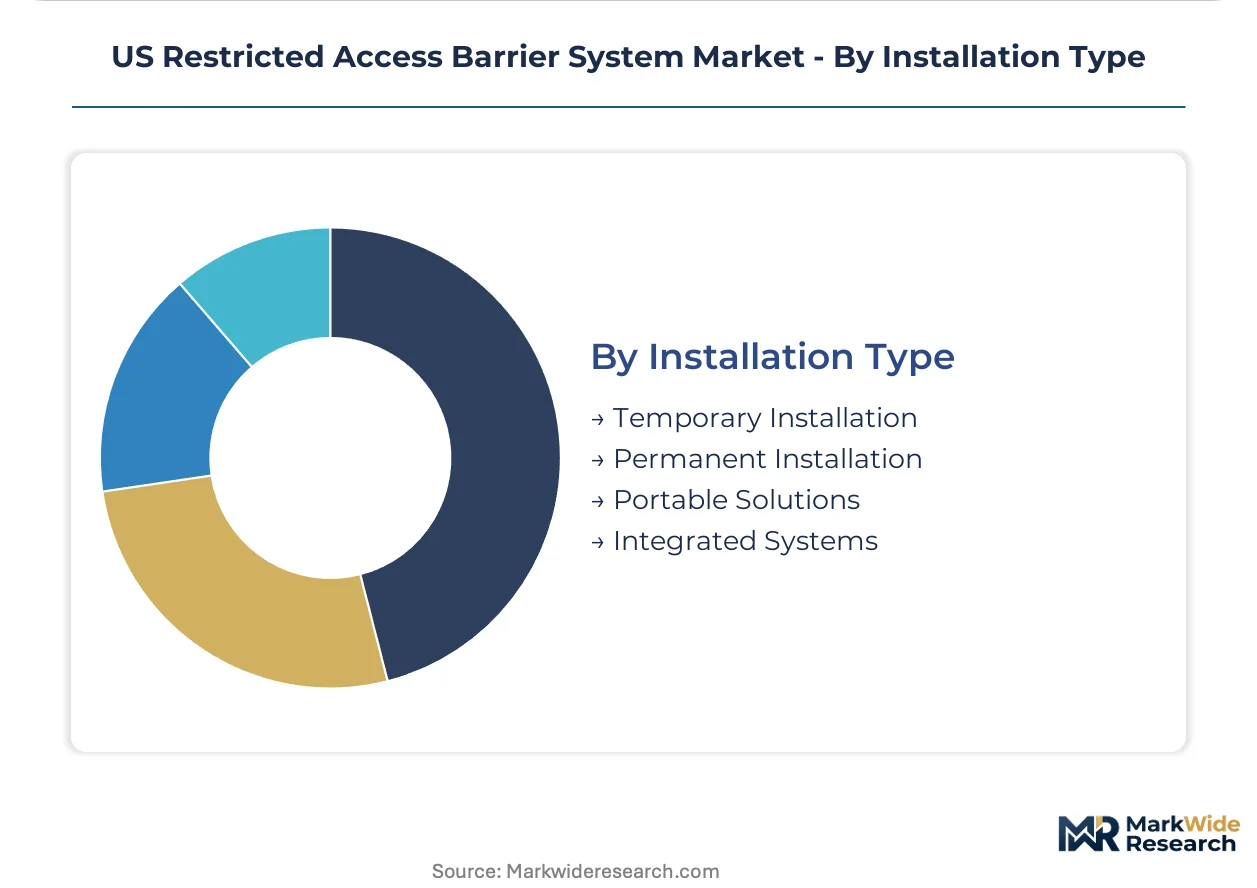
- Temporary Installation:Lease-based barrier deployment with validation support services suits clinical-stage biotechnology companies. Third-party equipment financiers in Massachusetts and Connecticut health systems structure these around milestone-based payment schedules.
- Permanent Installation:Fixed isolator lines with integrated HVAC and decontamination infrastructure dominate commercial manufacturing. Puerto Rico and New Jersey legacy facilities face retrofit complexity from existing ductwork constraints when achieving 10–20 Pascal positive pressure differentials.
- Portable Solutions:Rapid-reconfiguration glove-port systems serve multi-product clinical trial suites. Research Triangle Park and San Diego demand these for accelerated product changeover without dedicated cleanroom construction.
- Integrated Systems:Pre-validated isolator-VHP combinations with digital twin configurations compress project timelines. FDA advanced manufacturing technology guidance pushes suppliers toward these pre-validated submissions.
Permanent installations anchor revenue concentration; portable and temporary solutions expand fastest among emerging biotechnology ventures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barrier system fabrication clusters heavily in the Northeast and Mid-Atlantic, where pharmaceutical infrastructure density and FDA inspection frequency create concentrated demand for containment engineering expertise.
Northeast Corridor
Massachusetts and New Jersey biologics fill-finish operations drive specification demand for automatic barriers with integrated VHP decontamination. FDA cGMP Annex 1 enforcement compresses upgrade timelines for legacy facilities in Boston-Cambridge and Princeton-New Brunswick corridors. Cambridge cell therapy manufacturers deploy closed isolator lines for mRNA vaccine production requiring ISO 5 unidirectional airflow validation.
Mid-Atlantic
North Carolina's Research Triangle Park anchors clinical trial material production requiring rapid-reconfiguration portable barriers. USP <797> compounding standards tighten engineering controls for hospital pharmacies across Virginia and Maryland health systems. Durham and Chapel Hill biotechnology incubators lease temporary isolator installations with milestone-based validation support.
Puerto Rico
Legacy pharmaceutical manufacturing infrastructure faces retrofit complexity when upgrading to 10–20 Pascal positive pressure differentials. EPA containment requirements for potent compound handling intersect with hurricane-resilient facility design standards. Juana Díaz and Barceloneta injectable drug plants navigate HVAC ductwork constraints during barrier system integration.
California
Radiopharmaceutical PET tracer production in San Diego and Los Angeles demands lead-shielded isolators with integrated material transfer systems. OSHA workplace exposure limits for isotope handling drive glove-port specifications with remote actuation capabilities. Bay Area cell therapy facilities pilot sensor-integrated barriers for FDA real-time release testing alignment.
Texas
Houston medical center compounding pharmacies expand containment capacity for hazardous drug preparation under USP <797> enforcement. Texas Medical Center health systems standardize validation protocols across multi-site barrier deployments. Dallas-Fort Worth contract manufacturing organizations procure modular cleanroom-barrier integration for shared HVAC infrastructure.
US Restricted Access Barrier System Market Key Industry Players
Swiss-engineered specialists and modular cleanroom integrators split the market between premium biologics applications and flexible healthcare deployments. The vendor base organizes around three strategic archetypes: European precision fabricators with isolator heritage, North American modular system builders, and integrated decontamination technology providers. Consolidation pressure intensifies as lifecycle containment management contracts displace equipment-only transactions, while technology licensing agreements accelerate VHP biodecontamination integration.
Among European precision fabricators, SKAN AG and COMECER S.p.A. exemplify the premium-tier positioning anchored in pharmaceutical aseptic processing heritage. SKAN AG occupies a position consistent with Swiss-engineered isolator specialization for fill-finish operations, while COMECER S.p.A. represents the integrated decontamination archetype with radiopharmaceutical containment capabilities. Germfree Laboratories, Inc. anchors the North American modular integration segment, serving military and pharmaceutical clients through flexible cleanroom-barrier configurations.
| Leading Market Players |
|---|
| I.M.A. Industria Macchine Automatiche S.P.A. |
| Germfree Laboratories, Inc. |
| Extract Technology |
| AZBIL TELSTAR, S.L.U. |
| Syntegon Technologies GmbH |
| Isolation Systems Inc. |
| COMECER S.p.A. |
| SKAN AG |
| Ortner Reinraumtechnik GmbH |
| Others |
Cost & Logistics Intelligence
Stainless steel and HEPA filter cost volatility compresses margin structures across project bidding cycles while simultaneously forcing fabricators toward premium-tier positioning and lifecycle service bundling. This input-driven risk vector widens pricing spreads between Swiss-engineered isolator specialists and modular cleanroom integrators as buyers weigh capital expenditure against total cost of ownership.
Pricing Analysis
FDA cGMP Annex 1 dictates the pricing tier structure by mandating physical separation technologies that stratify procurement across certification-grade specifications. Three-tier pricing structure across premium, standard, and economy levels separates validated isolator-VHP integrations from basic glove-port configurations and portable clinical trial units. Cost compression in the standard tier intensifies because hospital compounding pharmacies face USP <797> enforcement without biologics-scale volume justification. Academic medical centers and multi-site health systems exhibit highest price sensitivity due to operational expenditure constraints, while Massachusetts cell therapy manufacturers show lowest sensitivity given batch integrity imperatives.
Supply Chain Analysis
Stainless steel feedstock draws from domestic mills in Pennsylvania and Ohio, specialty HEPA media from Switzerland and Germany, and precision glove-port assemblies from Italian and Swiss component suppliers. Electropolished 316L stainless steel, borosilicate glass viewing panels, and silicone-sealed glove sleeves constitute critical input dependencies. Single-source vulnerability concentrates in pharmaceutical-grade HEPA filtration media where European specialty manufacturers anchor supply. Distribution runs through direct OEM sales for permanent installations and third-party equipment financiers for temporary lease arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US restricted access barrier system market functions as a service-attach opportunity where lifecycle containment management contracts expand faster than hardware transactions as facilities outsource validation and maintenance obligations.
For Market Incumbents: Entrench market position through backward integration into HEPA filter refurbishment capabilities and captive supply of validation documentation services. Swiss-engineered specialists face emerging pressure from modular cleanroom integrators offering faster deployment timelines; defensive consolidation through certification investment in FDA pre-validated digital twin configurations protects premium positioning against commoditization. For New Entrants and Emerging Players: Pursue white-space opportunity in portable barrier systems for clinical trial material suites across Research Triangle Park and San Diego biotechnology clusters. Hospital compounding pharmacies in the Northeast corridor represent the most penetrable segment given USP <797> enforcement without existing supplier lock-in. A go-to-market angle emphasizing rapid-reconfiguration capabilities with milestone-based validation support addresses unmet flexibility demands. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated decontamination technology providers with VHP biodecontamination capabilities over pure-play fabricators. Long-term viability across the projection horizon hinges on service revenue attachment rates exceeding hardware margins. The signal to watch is FDA inspection precedent on real-time release testing adoption, which would accelerate sensor-integrated isolator valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Lifecycle Containment Management Contracts | Shifts revenue from equipment sales to recurring validation and maintenance services across multi-site health systems. |
| VHP Biodecontamination Integration | Compresses batch turnover cycles for Massachusetts biologics fill-finish operations seeking same-day product changeovers. |
| RFID-Integrated Access Logging | Synchronizes physical barrier entry with electronic batch records for FDA audit trail compliance in North Carolina facilities. |
| Portable Barrier System Development | Addresses rapid-reconfiguration demands from Research Triangle Park clinical trial material operations running multi-product campaigns. |
| Pre-Validated Digital Twin Configurations | Aligns with FDA advanced manufacturing technology guidance for continuous processing submissions in cell therapy production. |
Research Approach
A standing panel of barrier system procurement directors, containment validation engineers, hospital pharmacy operations managers, and biologics manufacturing executives provided ongoing calibration across the study period. Primary interviews combined with secondary validation against FDA 483 inspection observations, USP <797> revision comment filings, and SEC 10-K disclosures from publicly traded pharmaceutical equipment suppliers. Bottom-up and top-down triangulation reconciled facility-level capital expenditure tracking with aggregate market sizing.
Scenario-bracketing framed the analytical approach across the projection horizon by modeling product type segmentation across automatic, manual, mobile, and arm barriers alongside technology tiers spanning RFID, biometric, keypad, and remote control configurations. End-user segmentation captured commercial properties, airports, parking facilities, and industrial sites with distinct cost tier stratification. CAGRs derived from facility expansion pipeline analysis and regulatory enforcement timeline assumptions, with biologics fill-finish capacity buildouts and hospital compounding pharmacy upgrade mandates serving as primary volume drivers.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity indices, interest rate environments affecting equipment financing, or FDA inspection resource allocation would shift the trajectory. Cross-checking against IQVIA pharmaceutical capital expenditure surveys and ASHP hospital pharmacy infrastructure reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
India Access Control Hardware Market
Access Control Systems
GPS Smart Locks Market
Access Control Systems
Smart Door Lock Market
Access Control Systems
Home Control and Security Systems Market
Access Control Systems
Global Automated Border Control Market
Access Control Systems
Global Barrier Systems Market
Access Control Systems
Middle East and Africa Pin-Based Access Control Market
Access Control Systems
North America Access Control Software Market
Access Control Systems
Mechanical Locks Market
Access Control Systems
North America Pin-Based Access Control Market
Access Control Systems
Card-Based Electronic Access Control Systems Market
Access Control Systems
Europe Airport Passenger Screening Systems Market
Access Control Systems
Middle East and Africa Card-Based Access Control Market
Access Control Systems
Programmable Safety Systems Market
Access Control Systems
Door Controller Systems Market
Access Control Systems
Keyless Entry System Market