
 Facial Recognition Access Control Solution Market | 2026-2036
Facial Recognition Access Control Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Recognition Access Control Solution Market Analytics
ISO 30107-3 PAD Level 2 compliance is redrawing competitive requirements for liveness detection hardware. Suprema leverages in-house algorithm development to sustain premium positioning in enterprise biometric portfolios. IDEMIA anchors government credentialing contracts across multiple continents through its civil identity expertise. NEC Corporation dominates large-scale public safety installations with facial recognition engines optimized for crowded environments.
Facial recognition access control solutions integrate camera arrays, neural processing units, and matching algorithms to verify identity against enrolled templates for physical entry authorization. Systems typically operate with false acceptance rates below 0.001% at the primary authentication layer, serving critical infrastructure, commercial real estate, and institutional security applications. Embedded solutions lead hardware shipments due to edge-computing latency advantages in high-throughput settings, while cloud-based platforms capture expanding recurring revenue from multi-site enterprise accounts. Government agencies represent the most concentrated buyer segment, though educational institutions are emerging as fast-growth accounts driven by campus safety mandates.
The EU AI Act imposes conformity obligations on biometric systems deployed in public spaces, directly shaping product roadmaps for vendors seeking European market access. China's GB/T standards for facial recognition data security and the US NIST Face Recognition Vendor Testing program collectively establish the technical baseline for algorithm procurement across major economies. Stakeholders must monitor evolving data localization requirements and cross-border template transfer restrictions as these determine cloud-versus-hybrid deployment architecture decisions.
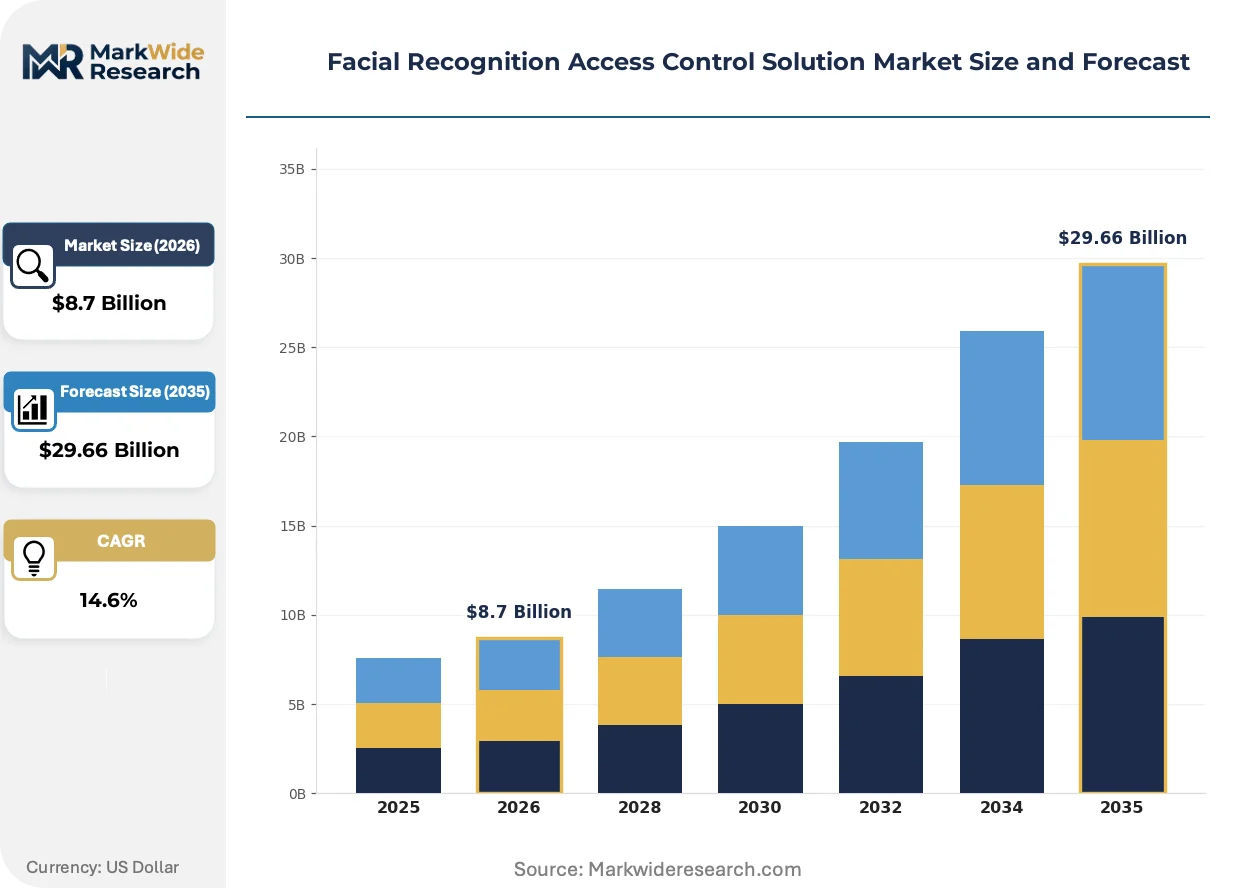
Market Dynamics
ISO 30107-3 PAD Level 2 compliance requirements are forcing hardware vendors to redesign liveness detection modules, compressing development timelines and elevating R&D budgets across the supplier base.
Growth Catalysts
- EU AI Act biometric classification:The regulation's risk-tier framework for biometric identification systems is accelerating vendor investment in algorithm transparency and audit trails to maintain European market access.
- Smart city infrastructure:Municipal surveillance modernization programs in China are deploying facial recognition access control at transit hubs, public buildings, and residential compounds at unprecedented scale.
- Edge neural processing units:Embedded NPU architectures are enabling sub-500-millisecond authentication latency, eliminating cloud dependency for high-throughput corporate campuses and data centers.
Market Restraints
- CMOS sensor supply concentration:Image sensor fabrication for biometric cameras concentrates among Taiwanese and South Korean foundries, exposing hardware vendors to geopolitical supply disruption.
- Template storage localization mandates:China's GB/T facial recognition data security standards and EU GDPR biometric data provisions impose conflicting data residency requirements, complicating multi-national enterprise deployments.
- 3D mask spoofing vulnerability:Presentation attack instruments using hyper-realistic silicone masks continue to defeat single-camera systems lacking structured light or multispectral illumination.
Strategic Opportunities
- Educational institution safety mandates:Campus security legislation across multiple US states is creating first-time demand for touchless entry systems in K-12 and university facilities previously reliant on card readers.
- Healthcare facility integration:Convergence of facial recognition with EMR systems and operating room access protocols is opening specialized procurement channels for HIPAA-compliant biometric solutions.
- India smart city mission:The country's urban infrastructure modernization program represents underpenetrated volume for vendors capable of meeting BIS certification and local manufacturing requirements.
Industry Challenges
- Algorithm bias remediation:Demographic performance disparities in facial recognition accuracy require continuous dataset expansion and adversarial testing, extending product validation cycles.
- Legacy access control retrofit:Integration with installed Wiegand and OSDP protocol infrastructure demands custom middleware development, inflating deployment costs and technical risk.
- ISO 30107-3 certification backlog:Limited accredited testing laboratory capacity is creating six-to-nine-month delays for vendors seeking PAD Level 2 validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Recognition Access Control Solution Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Systems, Mobile Devices, Embedded Solutions, Cloud-Based Platforms End User: Government Agencies, Educational Institutions, Commercial Enterprises, Residential Users Technology: 3D Recognition, Machine Learning, Artificial Intelligence, Deep Learning Deployment Model: On-Premise, Cloud, Hybrid, Others |
| Companies Covered | Suprema, IDEMIA, ZKTeco, Hikvision, Dahua Technology, Hanwha Techwin, Anviz Global, NEC Corporation, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Recognition Access Control Solution Market Evolving Landscape
Multispectral imaging architectures are displacing conventional RGB camera arrays as the primary sensing modality for high-security access control deployments. Vendors are racing to embed these capabilities at price points accessible to mid-market commercial real estate.
Structured light depth sensing is supplanting passive stereo vision in premium biometric hardware. Corporate data centers and financial trading floors are adopting these modules to defeat sophisticated presentation attacks. The technology is compressing the competitive window for single-camera vendors unable to match spoof resistance.
The EU AI Act's conformity assessment obligations for biometric systems are reshaping product roadmaps for vendors targeting European public sector procurement. Algorithm explainability requirements and human-in-the-loop mandates are forcing redesigns of fully automated entry workflows. Government credentialing contracts across France, Germany, and the Netherlands now specify audit trail capabilities as mandatory evaluation criteria.
Enterprise buyers are consolidating vendor relationships through multi-site framework agreements, displacing point-solution procurement at individual facilities. Facility management conglomerates and integrated security providers are capturing decision-making authority previously held by property-level managers. This concentration is most visible in North American commercial real estate, where REITs are standardizing biometric platforms across portfolios exceeding fifty properties.
Facial Recognition Access Control Solution Market Segmentation
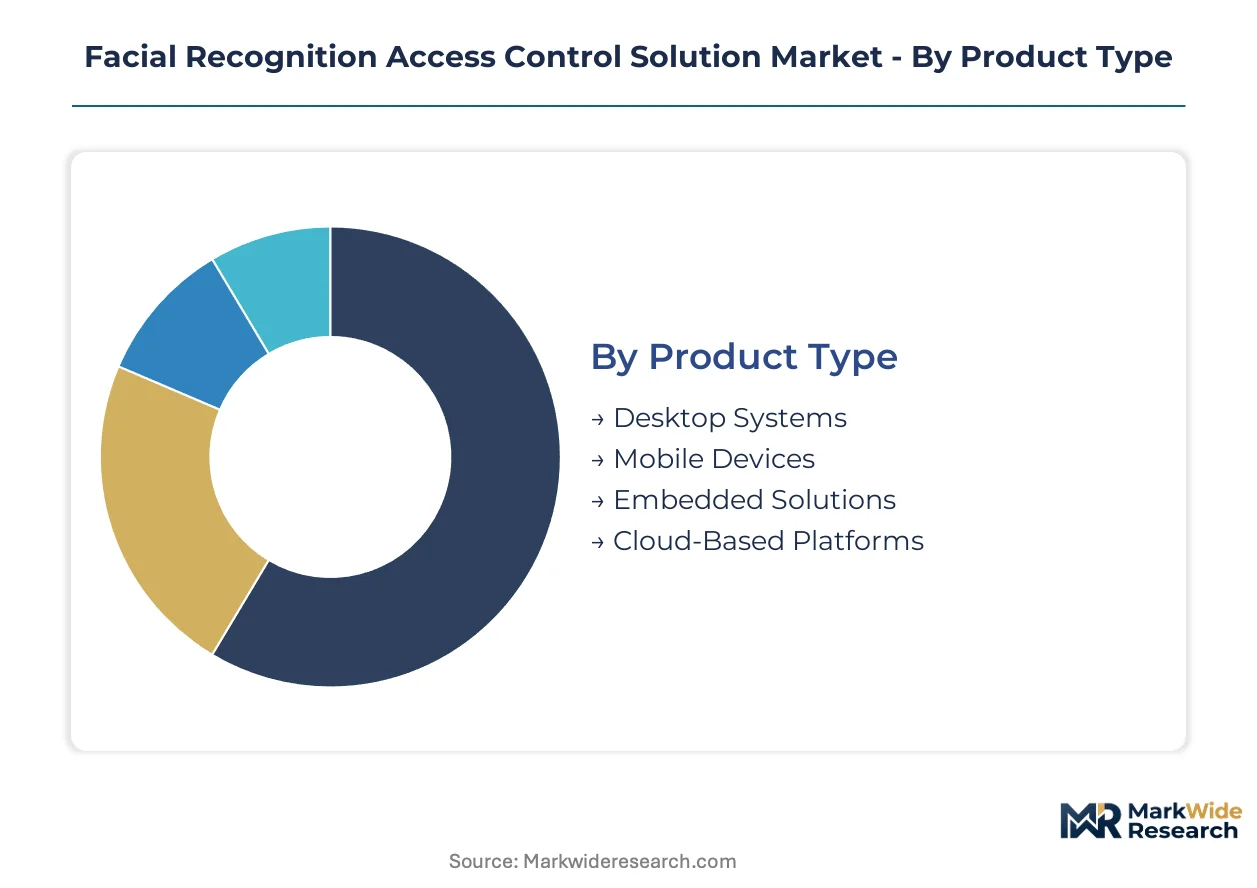
Segmentation in facial recognition access control reveals how hardware economics, compliance burdens, and integration complexity concentrate value differently across product architectures and buyer types. Vendors must align R&D priorities with the specific performance thresholds and procurement timelines governing each segment.
Product Type:
Premium margins pool in systems that embed neural processing and liveness detection at the edge, where latency requirements and security mandates justify higher unit economics.
- Desktop Systems:Stationary biometric terminals with integrated displays and local template storage serve reception areas and small office entry points. Demand concentrates in European commercial real estate, where GDPR biometric data provisions favor on-device processing over cloud transmission.
- Mobile Devices:Handheld or tablet-based facial recognition units enable temporary access control for events, construction sites, and pop-up facilities. These systems are expanding most quickly in India's smart city mission, where municipal authorities require portable authentication for informal settlements and transit checkpoints lacking fixed infrastructure.
- Embedded Solutions:Camera-NPU modules designed for integration into turnstiles, door hardware, and elevator systems.
- Cloud-Based Platforms:Centralized matching services with multi-site template synchronization and API-driven access management.
The dominant share belongs to Embedded Solutions, while Cloud-Based Platforms are gaining share fastest as enterprise buyers consolidate multi-site frameworks.
End User:
Procurement authority and compliance stringency vary sharply across buyer categories, with government credentialing programs demanding the most extensive certification documentation.
- Government Agencies:National ID systems, border control, and secure facility access drive demand for PAD Level 2 certified hardware with full audit trails. China's public security modernization programs dominate deployment volumes, with municipal governments mandating facial recognition for building entry across administrative campuses.
- Educational Institutions:K-12 and university campuses are adopting touchless entry systems under state-level safety mandates. US school districts in Texas, Florida, and California represent concentrated new demand as bond-funded security upgrades displace legacy card readers.
- Commercial Enterprises:Corporate campuses, data centers, and financial trading floors seeking high-throughput authentication.
- Residential Users:Smart home entry systems and multi-family building access control.
Government Agencies command the largest revenue pool, though Educational Institutions are climbing the fastest as first-time biometric procurement accelerates.
Technology:
Algorithm sophistication determines competitive differentiation, with vendors investing most heavily in architectures that defeat presentation attacks while maintaining sub-second matching speed.
- 3D Recognition:Structured light and time-of-flight depth sensing capture facial geometry to defeat photographic and video spoofing. Corporate data centers and financial institutions in Germany and the Netherlands specify these modules for high-security zones under EU AI Act conformity requirements.
- Machine Learning:Traditional feature-extraction and classification pipelines optimized for constrained compute environments. These systems retain share in cost-sensitive Indian and Southeast Asian deployments where BIS certification and local manufacturing requirements limit algorithm complexity.
- Artificial Intelligence:End-to-end neural network architectures with continuous learning capabilities.
- Deep Learning:Multi-layer convolutional and transformer-based models trained on billion-scale datasets.
3D Recognition holds the installed base leadership, while Deep Learning is advancing most rapidly as training efficiency improves and edge NPUs absorb larger model footprints.
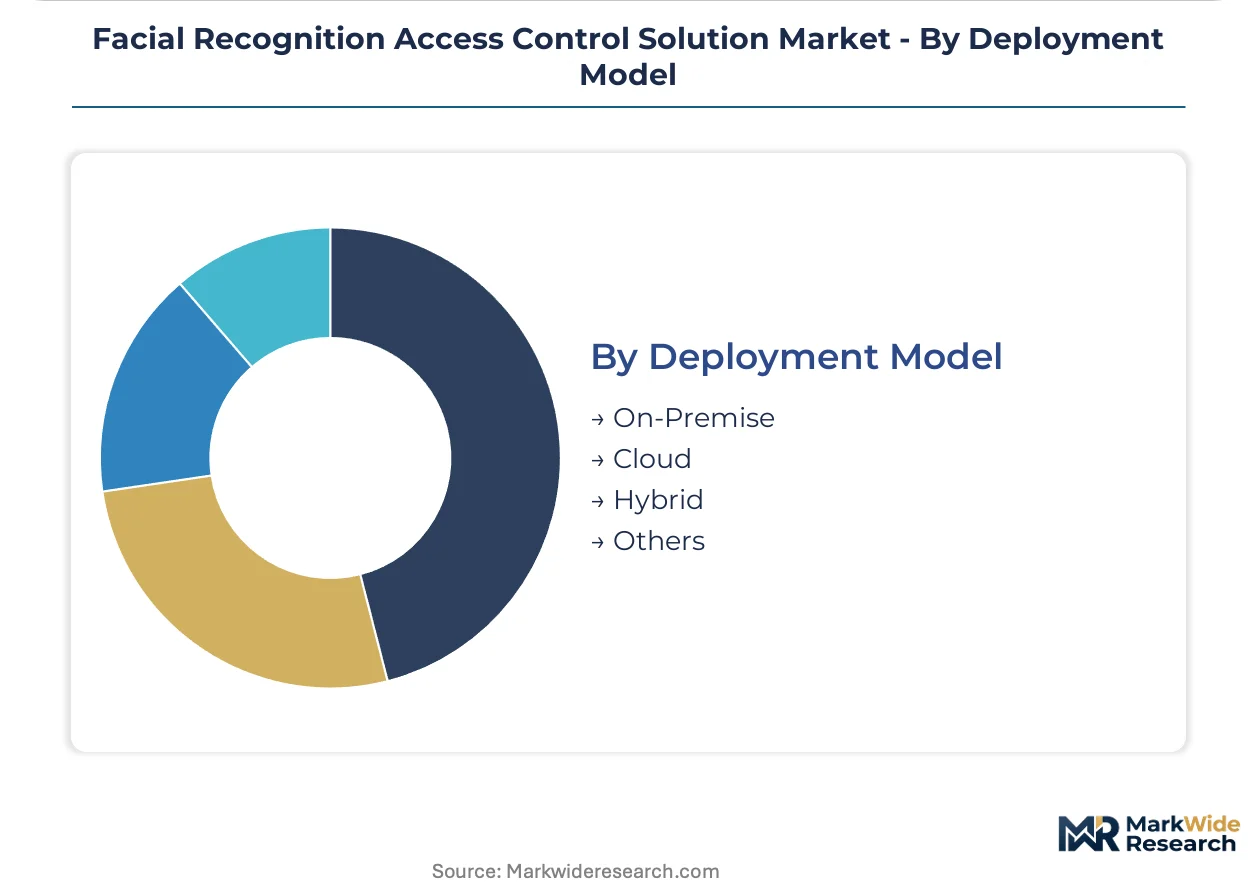
Deployment Model:
Data residency mandates and latency requirements create divergent architectural preferences across geographies with conflicting biometric data regulations.
- On-Premise:Local template storage and matching within facility-controlled infrastructure. China's GB/T facial recognition data security standards and Russia's data localization laws compel this architecture for government and critical infrastructure deployments, eliminating cross-border cloud dependencies.
- Cloud:Centralized template databases with API-based authentication and multi-site synchronization. US healthcare facilities leverage these platforms for HIPAA-compliant EMR integration, with business associate agreements governing biometric data handling.
- Hybrid:Edge enrollment with cloud backup and cross-site template federation.
- Others:Federated and blockchain-anchored identity verification architectures.
On-Premise deployments retain the largest footprint, though Hybrid architectures are expanding most quickly as multinational enterprises navigate fragmented regulatory requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Camera sensor fabrication concentrates among Taiwanese and South Korean foundries, while algorithm development and system integration distribute across North America, Europe, and Asia-Pacific based on regulatory proximity and data residency requirements.
China
Public security modernization programs and smart city infrastructure deployment dominate procurement volumes. GB/T facial recognition data security standards mandate on-premise template storage for government and critical infrastructure. Shenzhen and Hangzhou host dense clusters of biometric hardware manufacturers serving municipal surveillance contracts.
United States
Educational institutions under state-level campus safety mandates drive first-time biometric adoption, particularly in Texas, Florida, and California. HIPAA governs healthcare facility deployments requiring EMR integration. Data center operators in Northern Virginia and Dallas-Fort Worth specify sub-500-millisecond authentication latency for high-throughput environments.
Germany
EU AI Act conformity requirements shape public sector procurement with mandatory algorithm audit trails and human-in-the-loop provisions. Corporate data centers in Frankfurt and financial trading floors in Frankfurt and Munich specify 3D depth-sensing modules for high-security zones. KBA and federal data protection authorities enforce strict biometric data handling protocols.
India
The Smart Cities Mission generates volume demand for portable and fixed biometric systems in informal settlements and transit checkpoints. BIS certification and local manufacturing requirements under PLI schemes constrain algorithm complexity for cost-sensitive deployments. Mumbai and Bangalore municipal authorities lead procurement for urban infrastructure modernization.
Netherlands
European government credentialing contracts specify PAD Level 2 certified hardware with full audit capabilities. Amsterdam and Rotterdam host financial institutions adopting structured light authentication for trading floor access. CNIL-aligned data protection frameworks influence hybrid deployment architectures for multinational enterprises.
Facial Recognition Access Control Solution Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where premium algorithm developers coexist with high-volume hardware fabricators. The vendor base spans integrated security conglomerates, specialized biometric firms, and diversified electronics manufacturers. Three archetypes dominate: in-house algorithm developers commanding enterprise premiums, government credentialing specialists with civil identity expertise, and scale-driven hardware producers serving price-sensitive Asian markets. Competitive moves center on ISO 30107-3 PAD certification acquisition and multi-site enterprise framework agreements displacing point-solution procurement.
Within the premium-tier vector, Suprema and IDEMIA exemplify contrasting strategic positions—Suprema anchors in-house algorithm development for enterprise biometric portfolios, while IDEMIA occupies government credentialing contracts across multiple continents. NEC Corporation sits within the large-scale public safety installation segment, representing vendors with facial recognition engines optimized for crowded environments. These three companies illustrate how algorithm sophistication, civil identity expertise, and public sector specialization create defensible positioning against commoditizing hardware competition.
| Leading Market Players |
|---|
| Suprema |
| IDEMIA |
| ZKTeco |
| Hikvision |
| Dahua Technology |
| Hanwha Techwin |
| Anviz Global |
| NEC Corporation |
| Panasonic Corporation |
| Others |
Value Network & Pricing Analysis
Multi-site enterprise framework agreements lock in both supply access and price visibility for facial recognition access control vendors, binding hardware manufacturers to volume commitments that secure CMOS sensor allocation from Taiwanese foundries while stabilizing unit economics across procurement cycles.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across European deployments, separating PAD Level 2 certified systems from uncertified alternatives through mandatory audit trail capabilities and human-in-the-loop provisions. Three-tier pricing structure across premium, standard, and economy levels reflects algorithm sophistication, with deep learning architectures commanding premiums over machine learning baselines. Cost compression in the standard tier is intensifying because Chinese hardware fabricators are flooding mid-market channels with GB/T-compliant embedded solutions. Educational institutions in US states with campus safety mandates exhibit highest price sensitivity, while Frankfurt data center operators show lowest sensitivity due to latency-driven performance requirements.
Supply Chain Analysis
Strait of Malacca transit underwrites critical logistics for CMOS image sensors fabricated in Taiwanese and South Korean foundries, with Shenzhen and Hangzhou assembly clusters drawing from these inputs to produce embedded NPU modules. Neural processing units, structured light depth sensors, and multispectral camera arrays constitute the core component dependencies. Single-source vulnerability concentrates in advanced node semiconductor fabrication, where geopolitical disruption threatens hardware vendor production schedules. Distribution runs through integrated security providers and facility management conglomerates that have displaced property-level procurement authority across North American commercial real estate portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facial recognition access control sits in early-cycle expansion, with EU AI Act compliance deadlines and US campus safety mandates creating simultaneous tailwinds across enterprise and institutional buyer segments.
For Market Incumbents: Compound algorithm differentiation through ISO 30107-3 PAD Level 2 certification investment, defending against Chinese hardware commoditization by embedding liveness detection at the edge rather than outsourcing to cloud platforms. Deepen backward integration into neural processing unit design to capture margin pool currently allocated to Taiwanese semiconductor vendors, while anchoring multi-site framework agreements with REITs before facility management conglomerates consolidate vendor relationships further. For New Entrants and Emerging Players: Lead with healthcare facility integration as the most penetrable white-space target, where HIPAA-compliant EMR convergence and operating room access protocols create specialized procurement channels absent incumbent saturation. India's Smart Cities Mission offers secondary volume opportunity for portable biometric systems in informal settlements, with BIS certification requirements filtering out algorithm-heavy competitors unable to meet local manufacturing mandates. For Investors and Strategic Acquirers: Government credentialing specialists with civil identity expertise and cross-continental contract portfolios represent the highest-conviction acquisition archetype, given the regulatory moats surrounding national ID system deployments. Long-term viability hinges on algorithm transparency capabilities that satisfy EU AI Act audit requirements across the analysis window. Watch ISO 30107-3 certification backlog resolution as the inflection signal—laboratory capacity expansion would accelerate vendor validation timelines and compress competitive windows for uncertified entrants.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 30107-3 PAD Level 2 Certification | EU AI Act conformity obligations make this mandatory for European public sector procurement access. |
| Edge Neural Processing Unit Integration | Sub-500-millisecond latency requirements in Northern Virginia data centers drive embedded architecture preference. |
| Healthcare EMR System Convergence | HIPAA-compliant biometric integration opens specialized procurement channels for operating room access protocols. |
| Multi-Site Enterprise Framework Agreements | REIT portfolio standardization across fifty-plus properties displaces point-solution facility-level procurement. |
| Indian Local Manufacturing Compliance | PLI scheme and BIS certification requirements filter algorithm-heavy competitors from Smart Cities Mission volume. |
Research Methodology
Cross-validation between primary interviews with security systems integrators and secondary validation through customs records anchors the qualitative findings in this analysis. Chief technology officers at data center operators, facility management procurement directors, biometric hardware R&D leads, and municipal smart city program officers provided operational perspective across deployment archetypes. SEC 10-K filings, EU procurement contract databases, NIST Face Recognition Vendor Testing program results, and Chinese GB/T standard documentation supplied quantitative grounding. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Sensitivity analysis across algorithm performance tiers, deployment model architectures, and regulatory compliance scenarios shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type, end user category, technology sophistication, and deployment model, with neural processing unit cost curves and CMOS sensor supply constraints as industry-specific forecast inputs. CAGRs derived from installed base growth rates and replacement cycle assumptions rather than extrapolated point estimates.
The analysis sits within stated boundaries; outcomes outside sustained EU AI Act enforcement, continued US state-level campus safety mandate expansion, or stable Taiwan-South Korea semiconductor supply would require recalibration. Practitioners should keep alternative scenarios live as geopolitical supply disruption and algorithm bias litigation exposure evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Europe Access Control Hardware Market
Access Control Systems
Access Control and Authentication Market
Access Control Systems
RFID Locks Market
Access Control Systems
Residential Smart Lock Market
Access Control Systems
Pedestrian Entrance Control System Market
Access Control Systems
Acousto-Magnetic (AM) Security Systems Market
Access Control Systems
Mechanical Locks Market
Access Control Systems
Europe Access Control Software Market
Access Control Systems
North America Safety Systems Market
Access Control Systems
North America Home Security System Market
Access Control Systems
North America Access Control Market
Access Control Systems
Border Security System Market
Access Control Systems
Parking Access Control Market
Access Control Systems
Australia Industrial Barrier Systems Market
Access Control Systems
Pedestrian Access Control System Market
Access Control Systems
Door Controller Systems Market