
 US 5G Radio Access Network Professional Services Market | 2026-2036
US 5G Radio Access Network Professional Services Market Size, Share, and Industry Trends Forecast 2026-2036
US 5G Radio Access Network Professional Services Market Insights
The shift from single-source RAN procurement to multi-vendor ecosystems is decoupling traditional supplier relationships across the US market. Ericsson leverages its installed base of macro-cell infrastructure to sustain long-term service contracts with tier-one carriers. Nokia anchors its position through deep specialization in massive MIMO integration and field optimization protocols. Samsung competes aggressively on price-performance metrics while extending its professional services footprint into private 5G deployments for industrial clients.
US 5G Radio Access Network Professional Services encompass the design, deployment, optimization, and ongoing management of gNodeB infrastructure, fronthaul/backhaul coordination, and spectrum-efficient cell planning across sub-6 GHz and mmWave bands. These services ensure carrier-grade latency thresholds below 10 milliseconds and support network slicing for differentiated enterprise SLAs. Integration services currently dominate value capture as operators merge legacy 4G assets with 5G standalone cores, while Open RAN consulting emerges as the fastest-expanding margin pool amid disaggregated procurement mandates. Managed services for cloud RAN orchestration remain structurally underdeveloped but attract strategic investment from hyperscale platform providers seeking recurring revenue streams.
The FCC governs spectrum allocation and equipment authorization timelines that directly compress or extend deployment schedules for professional services firms. NIST cybersecurity frameworks and the NTIA's rip-and-replace directives for designated equipment further constrain vendor eligibility and reshape subcontractor qualification requirements. Stakeholders must monitor evolving O-RAN Alliance certification standards and state-level small-cell siting reforms to anticipate where deployment velocity and service pricing power will concentrate next.
Market Dynamics
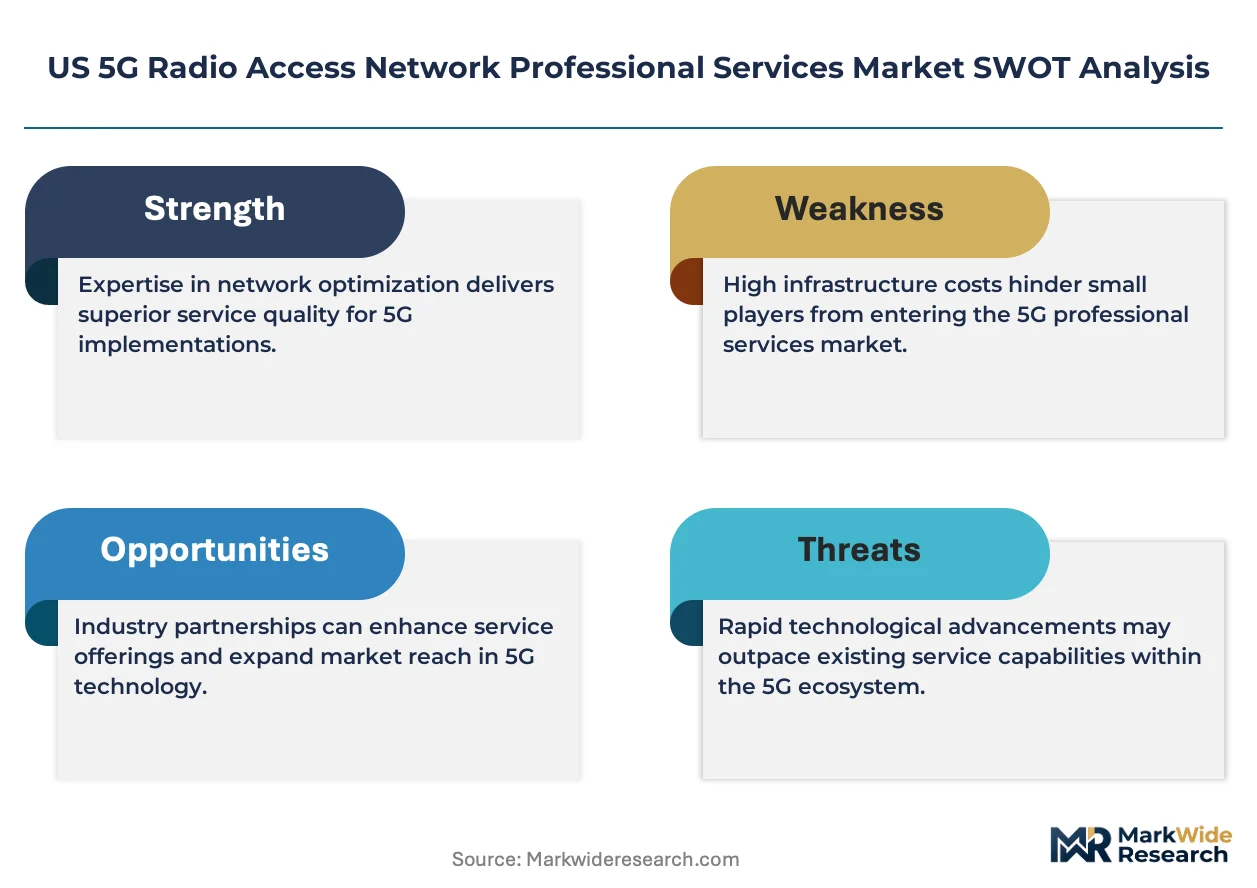
Open RAN disaggregation mandates from the FCC are fragmenting vendor relationships and forcing carriers to rebuild procurement frameworks around multi-source interoperability standards.
Growth Catalysts
- Mid-band spectrum deployment:The FCC's C-band auction allocations are compressing buildout timelines across California, Texas, and the Northeast corridor.
- NTIA rip-and-replace directives:Federal mandates to remove designated equipment are generating replacement service contracts for compliant infrastructure integration.
- Industrial private networks:Manufacturing and logistics facilities in the Midwest are commissioning dedicated 5G campus deployments requiring specialized RAN engineering.
Market Restraints
- Semiconductor supply concentration:gNodeB baseband processor availability remains bottlenecked by foundry capacity constraints in East Asian manufacturing hubs.
- Small-cell siting friction:Municipal permitting variance across US jurisdictions extends deployment cycles and inflates site acquisition costs.
- Legacy 4G integration complexity:Non-standalone architecture dependencies limit standalone core migration velocity for tier-two carriers.
Strategic Opportunities
- Rural coverage gaps:USDA Rural Development broadband initiatives are unlocking subsidy-funded deployment contracts across underserved Appalachian and Great Plains markets.
- Cloud RAN orchestration:Convergence of containerized network functions with hyperscale edge infrastructure is creating managed service revenue pools.
- O-RAN Alliance certification:Early compliance with open interface standards is positioning specialized integrators for carrier RFP preference.
Industry Challenges
- RF engineering talent scarcity:mmWave propagation modeling and beamforming optimization expertise concentrates among a limited pool of experienced specialists.
- Multi-vendor interoperability testing:Disaggregated RAN stacks require extended validation cycles to guarantee carrier-grade latency thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US 5G Radio Access Network Professional Services Market |
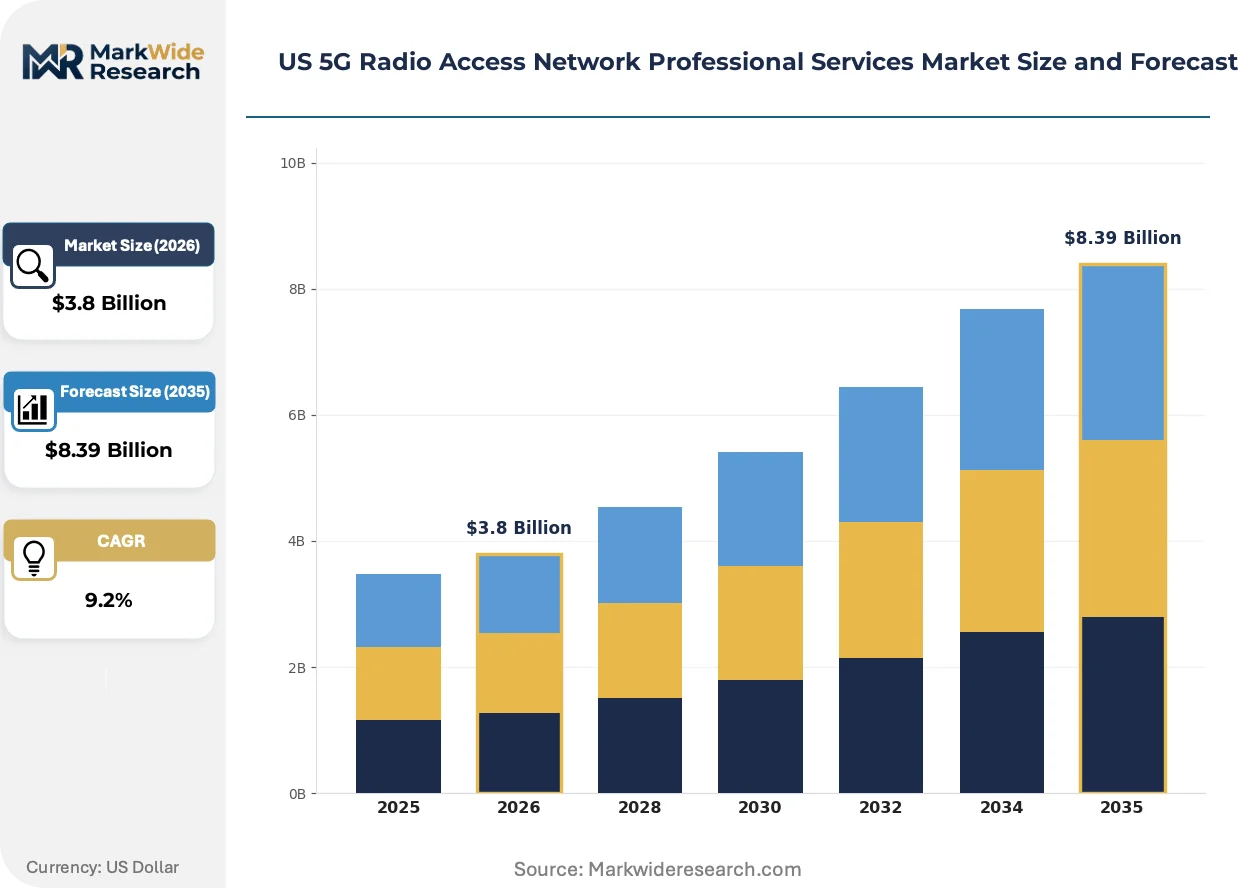
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Integration, Maintenance, Managed Services Technology: Open RAN, Virtualized RAN, Cloud RAN, Massive MIMO End User: Telecom Operators, Enterprises, Government Agencies, OEMs Engagement Model: Fixed Price, Time & Material, Subscription, Retainer |
| Companies Covered | Telefonaktiebolaget LM Ericsson, Nokia Corporation, Intel Corporation, Infovista, Dell EMC, Tata Consultancy Services, Tech Mahindra USA, Samsung Electronics Co., Ltd., GRANDMETRIC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US 5G Radio Access Network Professional Services Market Trends and Innovations
Disaggregation of hardware and software layers is redrawing competitive boundaries and enabling new entrants to challenge incumbent RAN suppliers.
Virtualized RAN (vRAN) architectures are overtaking purpose-built baseband hardware as the dominant deployment model for greenfield 5G standalone cores. Tier-one carriers are migrating radio intelligence to centralized cloud infrastructure to reduce cell site power consumption and cooling requirements. This technology shift is overtaking traditional distributed baseband deployment economics and compressing capital intensity per cell site.
The FCC's Open RAN policy framework is mandating interoperability testing for federally subsidized network builds. Equipment vendors must now certify against O-RAN Alliance specifications to qualify for Universal Service Fund support. Rural carriers in the Southeast and Mountain West are delaying procurement decisions pending compliance verification.
Service contracts are unbundling from hardware procurement, with carriers separating multi-year managed services from initial deployment scope. Systems integrators are capturing standalone optimization and assurance contracts previously bundled with equipment sales. This pattern is most pronounced among cable operators entering wireless markets through MVNO infrastructure partnerships.
US 5G Radio Access Network Professional Services Market Segmentation
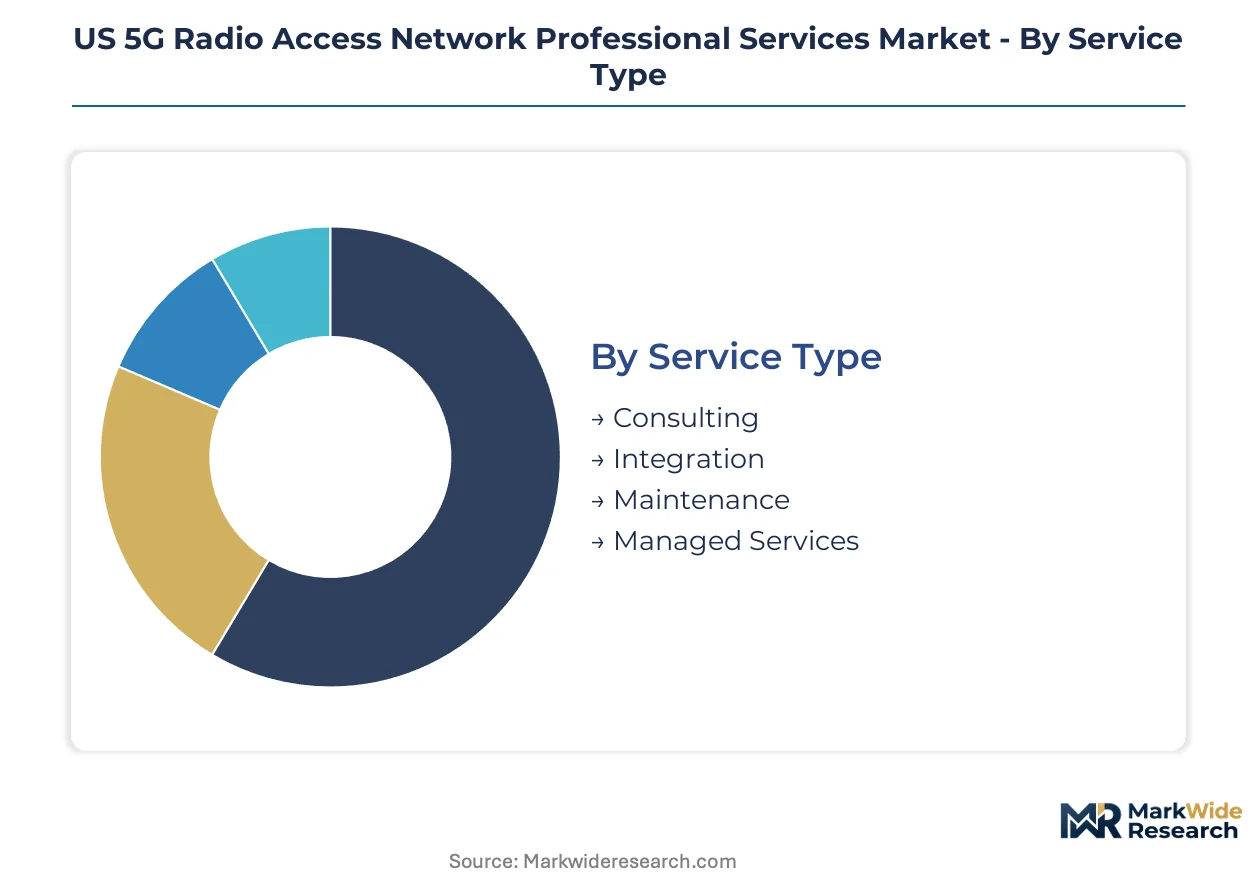
Professional services in US 5G RAN deployment fragment across service delivery models, technology architectures, and procurement structures. Each segmentation axis reveals distinct margin profiles and competitive dynamics that shape vendor positioning and carrier sourcing strategies.
Service Type:
Volume concentrates in integration and maintenance contracts, while consulting and managed services command premium pricing tiers.
- Consulting:Strategic advisory on spectrum strategy, vendor selection, and network architecture design for carriers navigating Open RAN procurement mandates. Demand concentrates among tier-one operators in California and Texas restructuring multi-vendor sourcing frameworks under FCC policy directives.
- Integration:Physical deployment of gNodeB infrastructure, fronthaul fiber coordination, and legacy 4G interworking across sub-6 GHz and mmWave bands. Deployment velocity is highest in the Northeast corridor where C-band buildout timelines compress and carrier-grade latency thresholds below 10 milliseconds are mandatory.
- Maintenance:Field repair, software patching, and hardware replacement services for operational RAN assets. Contracts typically extend 3-5 years post-deployment with pricing indexed to site density.
- Managed Services:Cloud RAN orchestration, performance monitoring, and SLA-guaranteed network assurance delivered as ongoing operational support. Adoption lags in tier-two carriers with constrained IT modernization budgets.
Mature deployment sits with Integration. Newer deployment is concentrated in Managed Services.
Technology:
Technology segmentation tracks the architectural shift from proprietary hardware to disaggregated, software-defined infrastructure layers.
- Open RAN:Multi-vendor interoperability implementation requiring O-RAN Alliance certification compliance and extended validation cycles. Federal subsidy eligibility under FCC frameworks is accelerating carrier procurement decisions in rural Southeast and Mountain West markets.
- Virtualized RAN:Containerized baseband function deployment on commercial-off-the-shelf servers, reducing cell site power consumption and cooling requirements. Tier-one carriers migrating radio intelligence to centralized cloud infrastructure are driving adoption fastest.
- Cloud RAN:Hyperscale edge infrastructure integration with centralized orchestration platforms for dynamic resource allocation. Hyperscale platform providers are investing strategically to capture recurring revenue streams in this structurally underdeveloped segment.
- Massive MIMO:64T64R and 32T32R antenna array optimization for spectral efficiency in dense urban corridors. Specialized field engineering for beamforming calibration commands premium service rates.
Massive MIMO dominates current revenue capture. Virtualized RAN is climbing the fastest as greenfield standalone core deployments accelerate.
End User:
End user segmentation reflects divergent procurement sophistication, with enterprise and government buyers emerging as distinct service categories from traditional carrier relationships.
- Telecom Operators:Traditional mobile network operators and cable MVNOs sourcing design, deployment, and optimization services. Procurement is unbundling from hardware sales, with standalone service contracts capturing optimization and assurance scope previously bundled with equipment.
- Enterprises:Manufacturing and logistics facilities in the Midwest commissioning dedicated 5G campus deployments requiring specialized RAN engineering for private network isolation. These deployments demand network slicing expertise for differentiated enterprise SLAs.
- Government Agencies:Federal, state, and municipal entities procuring secure RAN infrastructure with NTIA rip-and-replace compliance requirements. Replacement service contracts for designated equipment removal are generating substantial integration revenue.
- OEMs:Equipment manufacturers outsourcing field services, commissioning, and technical support to specialized professional services firms. This channel is expanding as disaggregation fragments vendor direct-service capabilities.
Telecom Operators anchor current service volumes. Enterprises are gaining share fastest as private 5G deployment accelerates across industrial verticals.
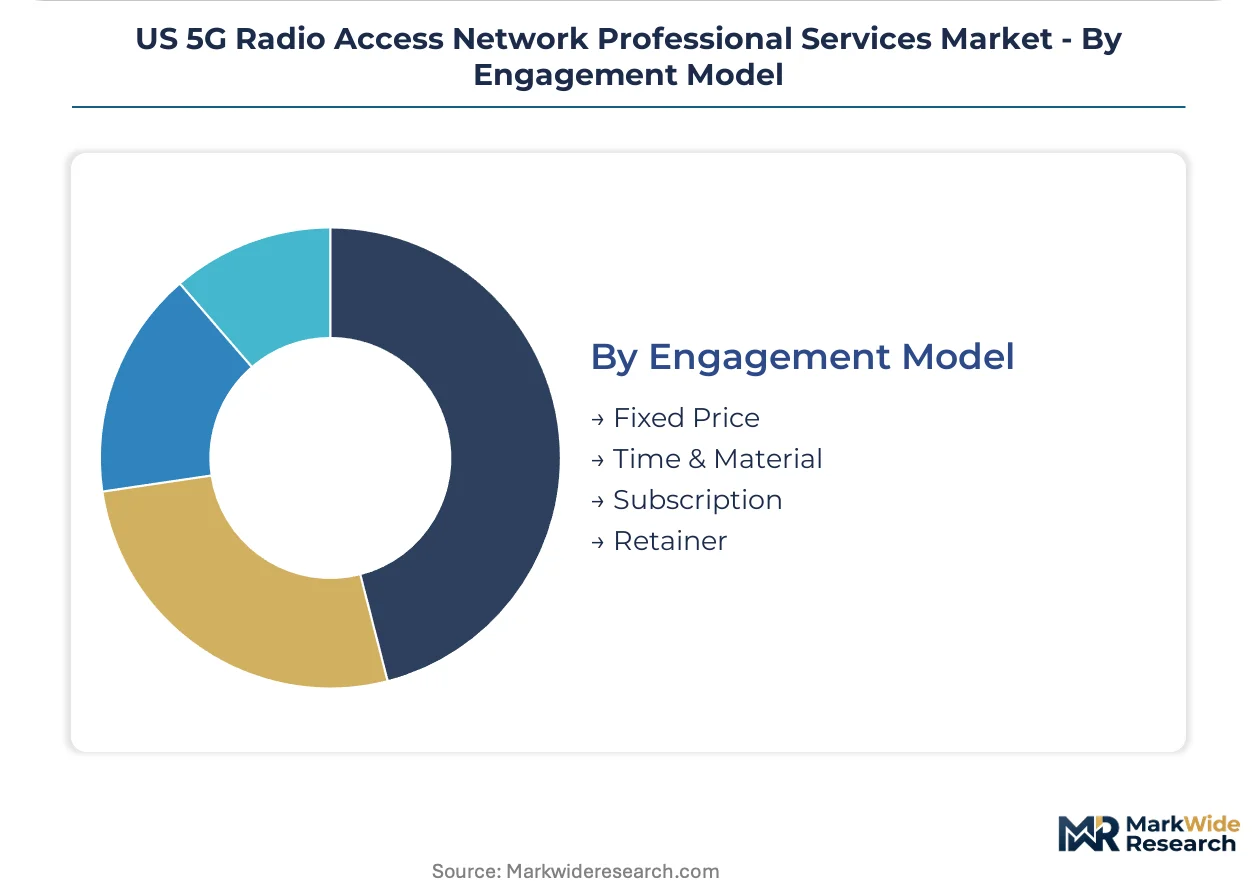
Engagement Model:
Engagement structures are shifting from capital-intensive project delivery toward recurring revenue relationships that align vendor incentives with network performance outcomes.
- Fixed Price:Lump-sum contracting for defined deployment scopes with risk allocation to service providers. Municipal small-cell siting friction and permitting variance across US jurisdictions are inflating contingency reserves in these contracts.
- Time & Material:Hourly or daily rate structures for advisory, troubleshooting, and optimization services with scope flexibility. This model dominates early-stage Open RAN consulting where requirements evolve during multi-vendor interoperability testing.
- Subscription:Recurring monthly or annual fees for managed network operations, performance monitoring, and continuous optimization. Cable operators entering wireless markets through MVNO partnerships are driving adoption of this model.
- Retainer:Prepaid access to specialized engineering expertise for on-call support and rapid response. RF engineering talent scarcity for mmWave propagation modeling is concentrating retainer pricing power among limited specialist pools.
Time & Material structures dominate consulting and integration phases. Subscription models are expanding most quickly as service contracts unbundle from initial deployment scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for 5G RAN professional services concentrates in coastal states and major metropolitan corridors where spectrum auctions, enterprise adoption, and federal infrastructure programs intersect. The FCC's policy framework and NTIA directives are redistributing deployment velocity across sub-regional markets.
California
Telecom operators in California are accelerating C-band densification projects across Los Angeles and San Francisco Bay Area corridors. The state's CPUC small-cell streamlining orders are compressing municipal permitting timelines for urban 5G builds. Enterprise private network deployments in Silicon Valley manufacturing campuses are generating specialized RAN engineering demand.
Texas
Dallas-Fort Worth and Houston metro areas are seeing concentrated gNodeB integration activity tied to mid-band auction commitments. The Texas PUC's pole attachment reforms are reducing site acquisition friction for distributed antenna systems. Industrial facilities in the Permian Basin are commissioning dedicated 5G networks for remote operations.
Northeast Corridor
Deployment velocity peaks between Boston and Washington DC where carrier-grade latency requirements drive massive MIMO optimization contracts. State-level small-cell siting legislation in New York and New Jersey is standardizing municipal approval processes. Financial services firms in Manhattan are procuring network slicing expertise for low-latency trading infrastructure.
Southeast
Rural carriers across Georgia, Florida, and the Carolinas are delaying procurement decisions pending O-RAN Alliance compliance verification for federal subsidy eligibility. The USDA Rural Development broadband initiatives are unlocking deployment contracts across underserved Appalachian markets. Agricultural processing facilities in the region are piloting private 5G for supply chain automation.
Midwest
Manufacturing and logistics hubs in Michigan, Ohio, and Illinois are driving demand for industrial private network deployments. Automotive assembly plants in Detroit and EV battery facilities across the region require specialized RAN engineering for deterministic wireless control systems. State broadband offices are coordinating with NTIA on rip-and-replace implementation timelines.
US 5G Radio Access Network Professional Services Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors reposition around Open RAN disaggregation mandates. The market structure reflects a tiered hierarchy: incumbent infrastructure suppliers with installed base leverage, systems integrators capturing unbundled service contracts, and specialized engineering firms targeting private network verticals. Three archetypes define positioning: full-stack RAN vendors extending professional services, IT consultancies bridging cloud-native deployment, and field engineering specialists optimizing radio performance. M&A activity and O-RAN certification investments are the primary competitive moves reshaping vendor relationships.
Within the full-stack vendor tier, Telefonaktiebolaget LM Ericsson and Nokia Corporation exemplify incumbents leveraging macro-cell infrastructure relationships into long-term service contracts. Samsung Electronics Co., Ltd. occupies a position on the price-performance vector, particularly in private 5G engagements. Systems integrators such as Tech Mahindra USA and Tata Consultancy Services represent the IT consultancy archetype, capturing standalone optimization scope as carriers unbundle services from hardware procurement. Intel Corporation and Dell EMC anchor the cloud-native infrastructure layer, supplying compute platforms for virtualized RAN deployments. Specialists in radio frequency engineering include GRANDMETRIC and Infovista, focusing on propagation modeling and network assurance.
| Leading Market Players |
|---|
| Telefonaktiebolaget LM Ericsson |
| Nokia Corporation |
| Intel Corporation |
| Infovista |
| Dell EMC |
| Tata Consultancy Services |
| Tech Mahindra USA |
| Samsung Electronics Co., Ltd. |
| GRANDMETRIC |
| Others |
Pricing and Supply Chain Analysis
Carrier unbundling of professional services from hardware procurement is forcing integrators to absorb project risk while competing on outcome-based metrics. This demand-side restructuring compresses margins on fixed-price deployment contracts while elevating premium capture for specialized RF engineering retainers.
Pricing Analysis
Volume concentrates in integration and maintenance at compressed margins, while consulting and managed services sustain premium tiers. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth and SLA guarantees. Pricing pressure stems from carrier procurement consolidation and Open RAN interoperability testing cost overruns. Tier-two carriers exhibit highest price sensitivity; hyperscale platform providers show lowest, prioritizing performance guarantees over unit economics.
Supply Chain Analysis
Regional distribution centers in Dallas, Chicago, and Atlanta anchor hub-and-spoke patterns for field engineering deployment. gNodeB baseband processors draw from Taiwan and South Korea; specialized RF test equipment sources from Germany and Japan. Single-source vulnerability in mmWave beamforming chipsets creates procurement risk. Distribution runs through carrier-certified logistics partners with bonded warehousing for spectrum-controlled equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RF engineering talent scarcity constrains service delivery capacity, propping pricing power for certified specialists across the analysis window. This supply bottleneck favors incumbents with captive workforce pipelines.
For Market Incumbents: Deepen vertical integration into cloud RAN orchestration software to defend against hyperscale platform encroachment. Secure O-RAN Alliance certification early to lock carrier RFP preference. Expand field engineering training pipelines in Texas and California to mitigate talent scarcity risk.
For New Entrants and Emerging Players: The mid-market price-point gap between premium tier-one integrators and economy resellers offers entry space. Target rural Southeast carriers awaiting federal subsidy eligibility verification. Lead with O-RAN compliance consulting to bypass hardware scale disadvantages.
For Investors and Strategic Acquirers: The window for entry favors specialized RF engineering firms with mmWave propagation expertise. Long-term viability hinges on software-defined service revenue recurring across deployment cycles. Watch NTIA rip-and-replace contract award velocity as inflection indicator for replacement service demand.
| Strategic Initiative | Industry Significance |
|---|---|
| O-RAN Alliance Certification | FCC subsidy eligibility mandates compliance for rural carrier procurement decisions. |
| Cloud RAN Platform Integration | Hyperscale edge infrastructure convergence creates recurring managed service revenue pools. |
| RF Engineering Talent Acquisition | Specialist scarcity in mmWave beamforming limits competitive field service capacity expansion. |
| Private 5G Vertical Expansion | Midwest manufacturing campuses drive specialized RAN engineering for deterministic control systems. |
| Managed Services Unbundling | Cable operator MVNO entry separates optimization contracts from initial deployment scope. |
Research Methodology
FCC spectrum auction records, NTIA procurement databases, and carrier capital expenditure disclosures formed the secondary backbone for market sizing. Primary interviews with RAN engineering directors, carrier procurement leads, Open RAN systems integrators, and field deployment contractors validated demand assumptions. Bottom-up triangulation against top-down spectrum allocation timelines anchored volume estimates.
Bottom-up modeling tracked gNodeB deployment commitments by carrier and geography; top-down analysis cross-referenced professional services intensity ratios from comparable infrastructure buildouts. Segmentation dimensions included service type, technology architecture, end-user category, and engagement model. CAGRs derived from deployment timeline compression and service unbundling velocity. Inputs from semiconductor foundry capacity constraints and municipal permitting variance informed supply-side adjustments.
Inputs from carrier network engineering teams were available through the study window; gaps in private 5G enterprise contract disclosure introduce uncertainty bands in non-carrier segments. Forecasts reflect documented assumptions regarding FCC policy continuity and Open RAN procurement mandate adherence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Indonesia Telecom Towers Market
Telecommunications
Ghana Telecom Market
Telecommunications
Voice Over LTE (Volte) Market
Telecommunications
LTE and LTE Advance Market
Telecommunications
Turkey Telecom Market
Telecommunications
Global B2B Telecommunication Market
Telecommunications
United States Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Land Professional Mobile Radio Market
Telecommunications
China ICT Market
Telecommunications
IoT Telecom Services Market
Telecommunications
LTE Base Station System Market
Telecommunications
Global Telecom Operations Management Market
Telecommunications
Global Radio Access Network Market
Telecommunications
GPON Market
Telecommunications
Ireland Telecom Market
Telecommunications
Global Virtual PBX Market