
 Global Telecom Operations Management Market | 2026-2036
Global Telecom Operations Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Telecom Operations Management Market Foresight
India is rewriting competitive dynamics in telecom operations management through its accelerated 5G spectrum deployment and indigenous equipment mandates. Ericsson sustains technology leadership in cloud-native orchestration platforms for multi-vendor environments. Nokia dominates radio access network automation with its real-time analytics layer integrated into operator workflows. Huawei leverages its captive silicon and software stack to control end-to-end deployment costs in emerging markets.
Telecom Operations Management encompasses the integrated software systems, processes, and analytics frameworks that monitor, configure, and optimize telecommunications network infrastructure in real time, typically processing millions of events per second through fault correlation engines and predictive maintenance algorithms. These systems enable mobile network operators, internet service providers, and cable operators to maintain service continuity, enforce quality-of-service thresholds, and automate remediation across physical and virtualized network layers. Cloud-based deployment models are capturing the fastest expansion as operators migrate away from capital-intensive on-premises installations toward elastic consumption models. Service assurance solutions command the deepest margin pools because they embed directly into operator revenue protection through SLA enforcement and customer experience guarantees. Network optimization use cases are maturing rapidly as artificial intelligence-driven traffic prediction becomes standard in tier-one operator architectures.
The European Telecommunications Standards Institute and the EU AI Act impose algorithmic transparency requirements on automated network management systems deployed across member states. The Federal Communications Commission in the United States enforces outage reporting mandates that drive investment in real-time fault detection and root-cause analysis capabilities. Stakeholders must monitor how national spectrum auctions and data sovereignty regulations fragment vendor certification requirements across priority deployment geographies.
Market Dynamics
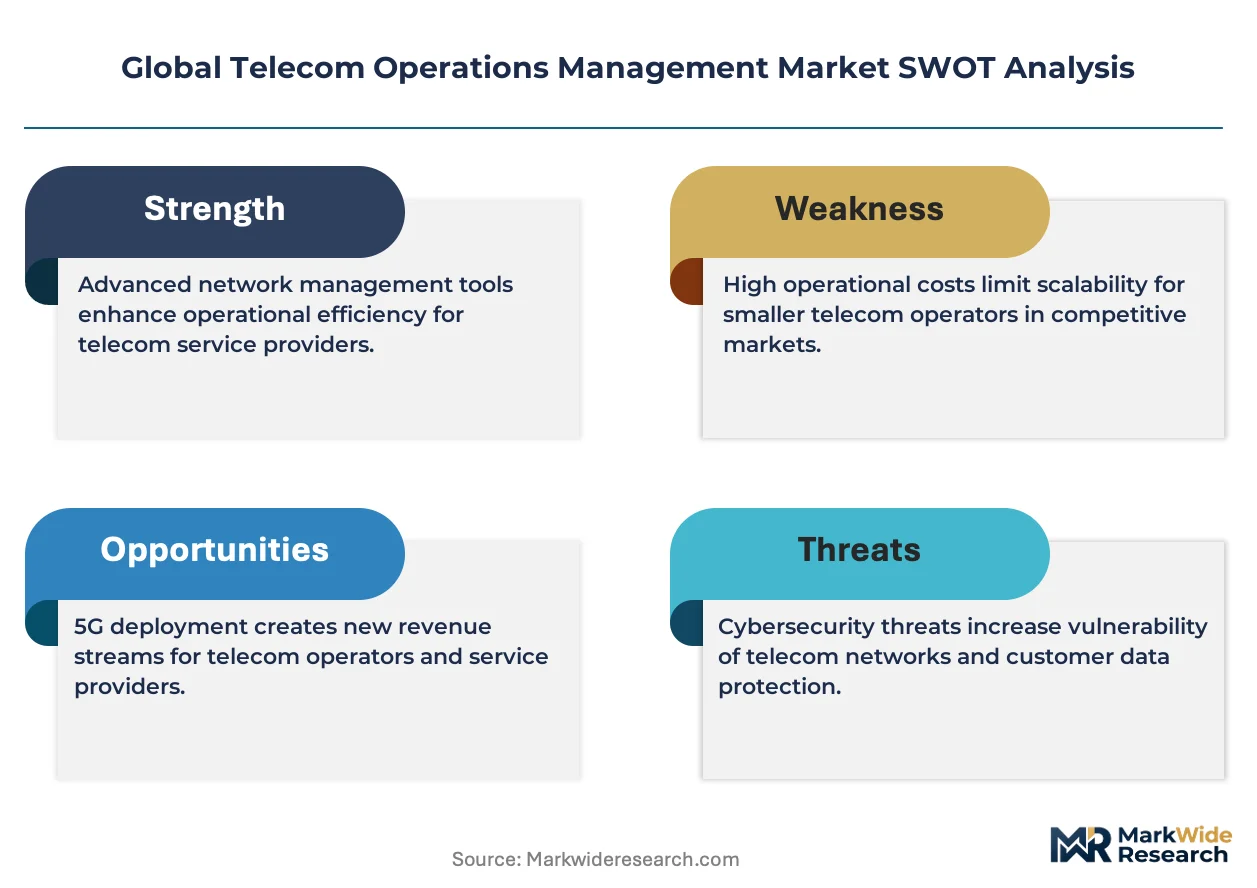
Cloud-native orchestration architectures are compressing deployment cycles for 5G network slicing while forcing incumbent vendors to restructure their delivery models around microservices and containerized workloads.
Growth Catalysts
- EU AI Act compliance mandates:European mobile operators must deploy algorithmically transparent assurance systems, creating immediate procurement pull for explainable AI in fault correlation engines.
- India's indigenous equipment mandates:Local sourcing requirements under the PLI scheme are accelerating domestic vendor capability building in network management software stacks.
- Open RAN interoperability frameworks:Multi-vendor radio access networks require standardized northbound APIs, expanding addressable market for vendor-agnostic orchestration platforms.
Market Restraints
- Specialized engineering talent scarcity:Cloud-native telco software development requires rare combinations of Kubernetes expertise and 3GPP protocol knowledge, constraining vendor scaling velocity.
- Silicon supply concentration:Custom network processing units for real-time analytics depend on TSMC and Samsung foundry capacity, exposing deployment timelines to geopolitical fabrication bottlenecks.
- Legacy system integration friction:Decades-old OSS/BSS installations in tier-one operators resist API-based interoperability, extending implementation timelines and inflating professional services costs.
Strategic Opportunities
- Brazil's national broadband plan:Federal connectivity mandates are creating greenfield deployment opportunities for integrated operations management suites in underserved regional markets.
- Edge computing convergence with AI inference:Distributed machine learning workloads at cell towers require localized assurance platforms, opening new product categories for ultra-low-latency monitoring.
- Germany's critical infrastructure designation:Enhanced cybersecurity requirements for telecom networks under BSI guidelines are mandating sovereign-hosted operations management deployments.
Industry Challenges
- Container security certification delays:Kubernetes-based network functions face prolonged Common Criteria evaluation timelines, stalling production deployments in regulated European markets.
- Multi-cloud orchestration complexity:Operators distributing workloads across AWS, Azure, and private infrastructure struggle with unified observability across heterogeneous environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Telecom Operations Management Market |
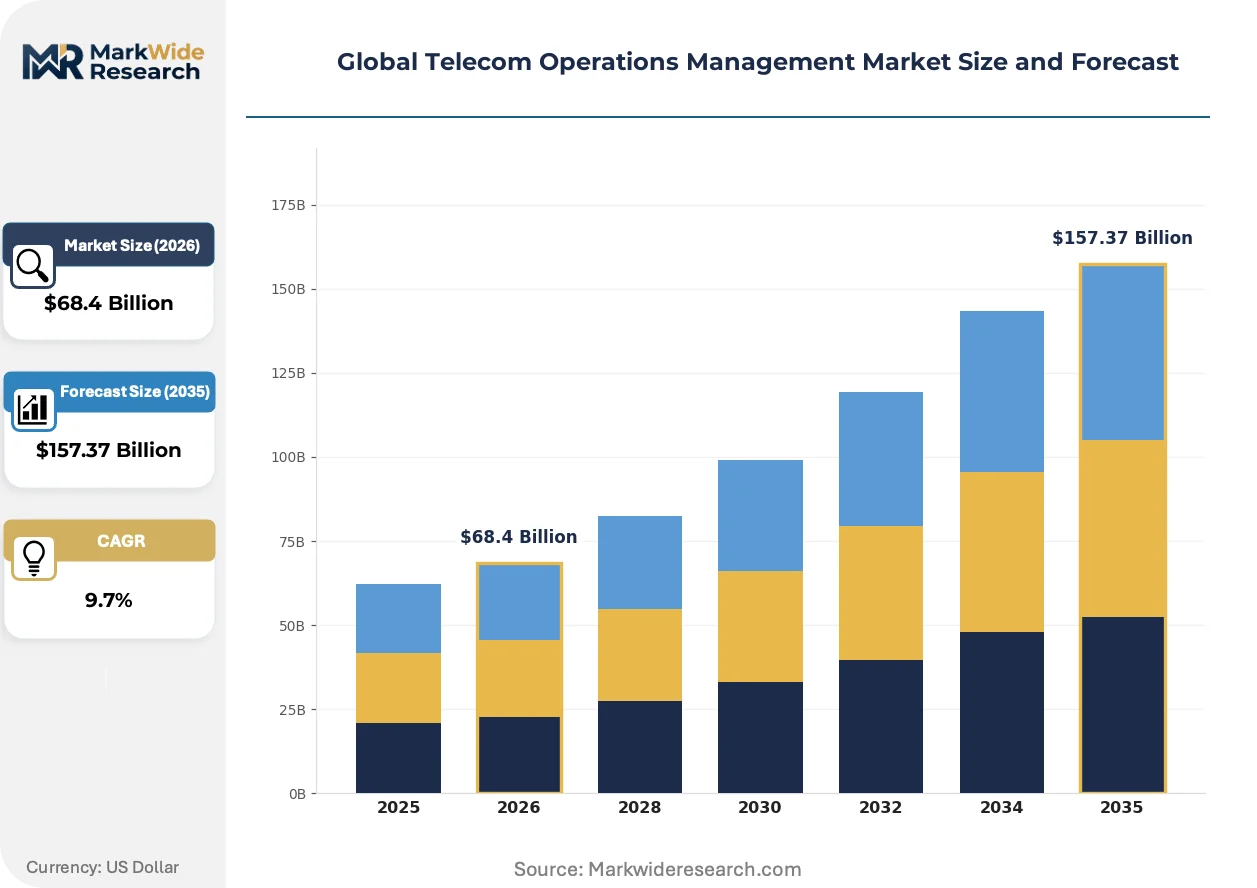
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $157.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Virtualized, Edge Computing Solution: Fault Management, Configuration Management, Performance Management, Security Management, Service Assurance Use Case: Network Optimization, Customer Experience Management, Fraud Detection, Revenue Management, Capacity Planning End User: Mobile Network Operators, Internet Service Providers, Cable Operators, Satellite Service Providers |
| Companies Covered | IBM Corporation, Telefonaktiebolaget LM Ericsson, Oracle Corporation, Hewlett Packard Enterprise Development LP, Amdocs, Nokia Corporation, Cisco Systems, Huawei Technologies, Accenture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Telecom Operations Management Market Shifts & Advancements
Artificial intelligence is restructuring how network events are processed, with inference engines moving from centralized data centers toward distributed edge locations to meet millisecond-scale remediation requirements.
Intent-based networking is migrating from experimental pilots to production deployments in tier-one mobile operators. Network engineering teams in Germany and Japan are adopting declarative configuration models that abstract vendor-specific command structures. This shift is compressing mean-time-to-repair metrics while reducing dependency on specialized CLI expertise.
The EU AI Act's algorithmic transparency requirements are forcing vendors to expose decision logic in automated remediation workflows. European operators must now maintain audit trails for AI-driven capacity scaling actions. Radio access network automation suites face the steepest compliance burden, with vendors redesigning analytics layers to satisfy explicability mandates.
Consumption-based licensing models are displacing perpetual software entitlements across procurement negotiations. Mobile operators in India and Brazil prefer elastic pricing tied to subscriber volume or network element count. This transition is visible most acutely in managed services contracts, where infrastructure-as-a-service wrappers now dominate new vendor relationships.
Global Telecom Operations Management Market Segmentation
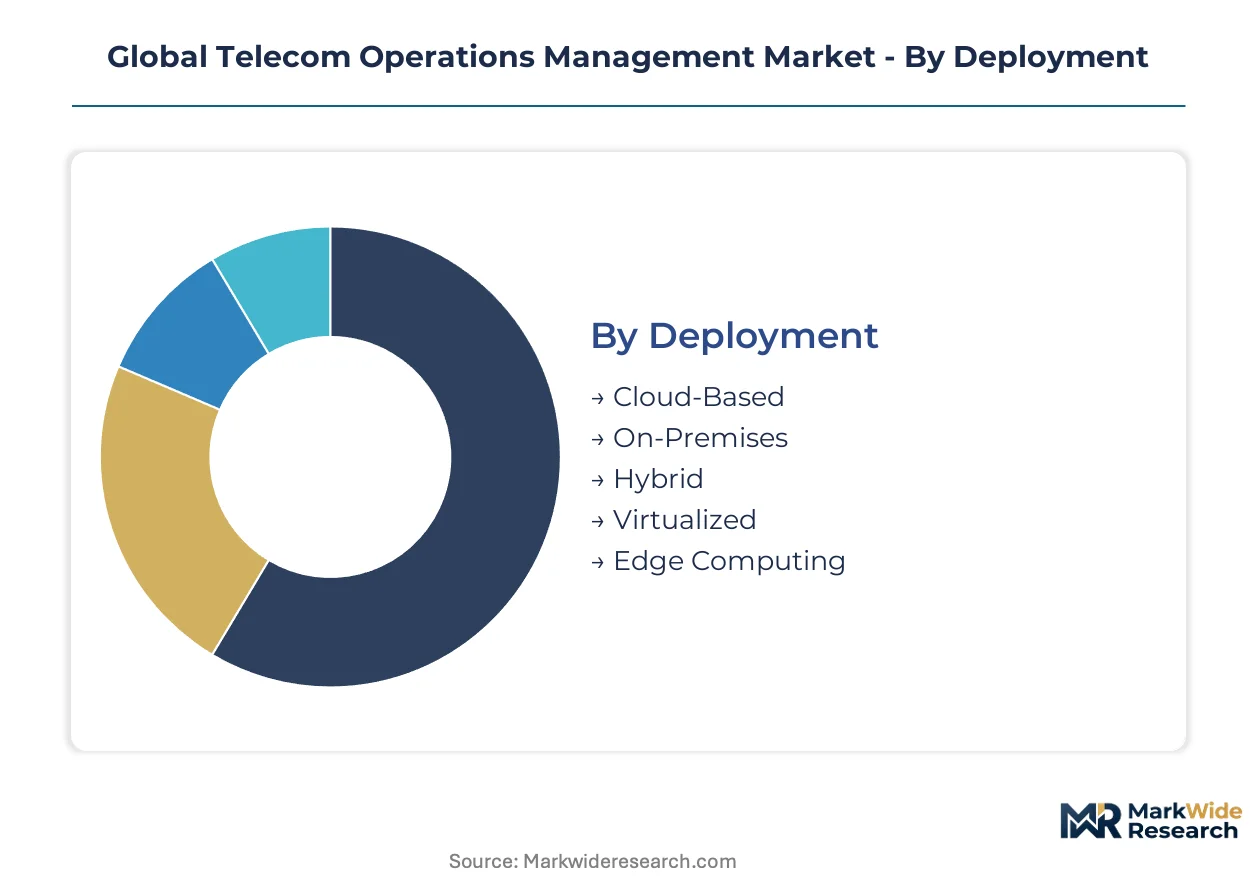
Telecom operations management segments exhibit divergent replacement cycles that reshape vendor resource allocation. Cloud-native solutions refresh every 18-24 months while on-premises installations persist for 7-10 years. Understanding these temporal patterns clarifies where procurement urgency concentrates versus where incumbents defend entrenched positions.
Deployment:
Cycle times vary dramatically across deployment architectures, with cloud-based platforms refreshing fastest and edge computing installations accelerating as 5G standalone networks mature.
- Cloud-Based:Elastic infrastructure consumption models enable operators to scale compute resources dynamically without capital commitments. Tier-one mobile operators in Germany and India are migrating core assurance workloads to sovereign-hosted cloud instances to satisfy data residency mandates while retaining operational flexibility.
- On-Premises:Capital-intensive perpetual license models dominate legacy operator environments where decades-old OSS/BSS integrations resist cloud migration. Tier-one cable operators in the United States maintain these installations to preserve custom-developed fault correlation engines that embed proprietary network topology knowledge.
- Hybrid:Split workloads between private data centers and public cloud instances address transitional compliance requirements. European operators under BSI and EU AI Act jurisdiction favor this architecture to isolate sensitive subscriber data while leveraging cloud analytics for non-critical workloads.
- Virtualized:Network function virtualization decouples software from proprietary hardware, enabling faster patch cycles and vendor substitution. Brazilian regional ISPs deploy virtualized assurance functions to minimize physical infrastructure in remote service territories.
- Edge Computing:Distributed processing at cell towers and aggregation points supports millisecond-scale remediation for autonomous vehicle and industrial IoT traffic. Japanese operators are deploying localized inference engines to meet METI latency requirements for critical infrastructure communications.
On-Premises deployments anchor the volume base while Edge Computing gains share at the steepest rate.
Solution:
Margin concentration follows functional criticality, with revenue-adjacent solutions commanding premium pricing versus infrastructure maintenance tools facing procurement compression.
- Fault Management:Real-time event correlation engines process millions of network alarms to isolate root causes and trigger automated remediation. FCC outage reporting mandates in the United States drive investment in these systems to minimize regulatory exposure from service disruptions.
- Configuration Management:Intent-based networking tools translate high-level service policies into device-specific command sequences. German operators under BSI critical infrastructure guidelines deploy these solutions to enforce standardized security baselines across multi-vendor radio access networks.
- Performance Management:KPI dashboards and threshold alerting monitor quality-of-service metrics across physical and virtualized layers. Indian mobile operators leverage these tools to demonstrate compliance with TRAI service-level mandates during 5G network expansion.
- Security Management:Threat detection and access control systems protect management plane interfaces from targeted attacks. Satellite service providers integrate these solutions to secure ground station telemetry links against geopolitical interference.
- Service Assurance:End-to-end SLA monitoring correlates network performance with customer experience metrics to trigger proactive retention interventions. These solutions embed directly into operator revenue protection and command the deepest margin pools in procurement negotiations.
Service Assurance captures the premium tier while Fault Management sustains the broadest installed base across operator categories.
Use Case:
Application maturity determines vendor competitive positioning, with optimization and fraud detection commanding established budgets versus emerging AI-driven planning tools requiring proof-of-concept investment.
- Network Optimization:AI-driven traffic prediction and dynamic resource allocation maximize spectral efficiency in congested urban cells. Ericsson and Nokia compete intensely for these deployments in Japanese dense metropolitan markets where subscriber density strains capacity.
- Customer Experience Management:Real-time quality scoring and proactive issue resolution reduce churn in saturated subscriber markets. Brazilian operators deploy these solutions to differentiate service offerings in federally mandated broadband expansion territories.
- Fraud Detection:Pattern recognition algorithms identify anomalous usage signaling subscription fraud or revenue leakage. These mature applications face procurement pressure as operators demand outcome-based pricing tied to detected leakage recovery.
- Revenue Management:Usage metering and billing mediation ensure accurate charging for complex 5G service bundles. Cable operators in the United States rely on these systems to unify billing across legacy video and emerging mobile offerings.
- Capacity Planning:Predictive models forecast infrastructure investment requirements based on subscriber growth and traffic mix projections. Indian operators under PLI scheme indigenous equipment mandates use these tools to align domestic manufacturing capacity with deployment timelines.
Network Optimization anchors procurement volume while Capacity Planning climbs fastest as AI inference capabilities mature.
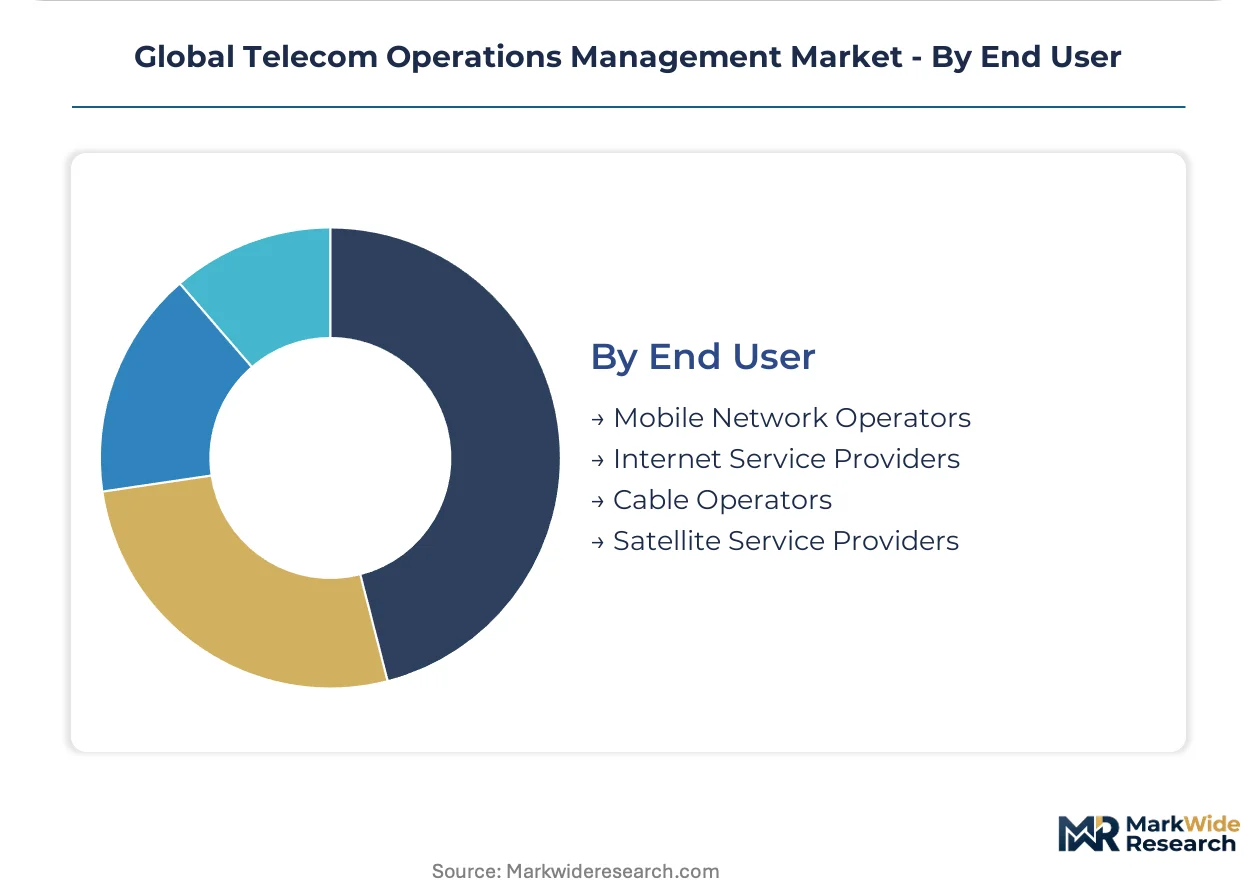
End User:
Customer scale and technical sophistication fragment vendor go-to-market approaches, with mobile operators demanding integrated suites versus specialized providers serving niche infrastructure categories.
- Mobile Network Operators:Multi-domain orchestration platforms spanning radio, transport, and core networks support 5G standalone complexity. These customers drive the largest contract values and most stringent interoperability requirements in vendor selection processes.
- Internet Service Providers:Fiber and fixed-wireless operators prioritize subscriber-facing assurance tools over radio-specific functionality. Indian regional ISPs under national broadband targets represent concentrated demand for cost-optimized deployment models.
- Cable Operators:Hybrid fiber-coaxial networks require specialized monitoring for shared medium contention and upstream noise aggregation. United States operators leverage DOCSIS-specific performance management to compete against fiber overbuilders.
- Satellite Service Providers:Geostationary and low-earth-orbit constellations demand link-budget-aware fault management for variable atmospheric conditions. Emerging commercial constellations drive new requirements for autonomous ground segment orchestration.
Mobile Network Operators dominate contract value while Satellite Service Providers expand most quickly as commercial space infrastructure proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC enforces outage reporting mandates that shape procurement patterns across the United States, while India's TRAI drives indigenous equipment mandates through the PLI scheme. Germany's BSI critical infrastructure designation and Brazil's national broadband plan create concentrated demand centers where regulatory compliance determines vendor selection.
United States
Mobile network operators and cable providers dominate procurement volumes as 5G standalone deployments accelerate. The FCC mandates real-time fault detection capabilities to minimize regulatory exposure from service disruptions. The Greater Boston cluster hosts specialized OSS/BSS integration firms serving tier-one operators with legacy system modernization.
Germany
BSI cybersecurity guidelines mandate sovereign-hosted operations management deployments for critical infrastructure protection. The EU AI Act imposes algorithmic transparency requirements on automated assurance systems across member states. The Bavaria industrial corridor concentrates vendor engineering centers serving Deutsche Telekom and Vodafone with intent-based networking solutions.
India
TRAI service-level mandates and PLI scheme indigenous equipment requirements accelerate domestic vendor capability building. Mobile operators migrate core assurance workloads to sovereign cloud instances to satisfy data residency requirements. The Karnataka technology cluster in Bangalore anchors cloud-native orchestration development centers for regional deployment.
Brazil
Federal connectivity mandates under the national broadband plan create greenfield opportunities in underserved regional markets. ANVISA-equivalent telecom regulators enforce stricter service-level accountability from infrastructure providers. The São Paulo metropolitan area concentrates operator headquarters procurement decisions for integrated operations management suites.
Japan
METI latency requirements for critical infrastructure communications drive edge computing convergence with AI inference at cell towers. Dense metropolitan subscriber density strains capacity and intensifies competition between Ericsson and Nokia for network optimization deployments. The Kanto region around Tokyo anchors tier-one operator engineering centers adopting declarative configuration models.
Global Telecom Operations Management Market Competitive Landscape
Integrated platform providers and specialized assurance vendors split the market between comprehensive orchestration suites and point solutions. The vendor base concentrates around three strategic archetypes: cloud-native software specialists, incumbent network equipment providers with captive management layers, and systems integrators with telco-specific professional services capabilities. Competitive dynamics center on M&A activity targeting Kubernetes expertise and strategic partnerships with hyperscale cloud providers.
Within the integrated platform tier, IBM Corporation and Oracle Corporation exemplify enterprise software incumbents repositioning cloud-native portfolios for telecom workloads. Telefonaktiebolaget LM Ericsson occupies a position representing Nordic equipment providers extending orchestration capabilities into multi-vendor environments. These anchors illustrate how vendor origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| IBM Corporation |
| Telefonaktiebolaget LM Ericsson |
| Oracle Corporation |
| Hewlett Packard Enterprise Development LP |
| Amdocs |
| Nokia Corporation |
| Cisco Systems |
| Huawei Technologies |
| Accenture |
| Others |
Supply & Pricing Matrix
Single-source dependency on TSMC and Samsung foundry capacity for custom network processing units creates pricing tier spreads exceeding threefold between sovereign-certified assurance platforms and commodity orchestration tools while forcing operators toward multi-year silicon pre-purchase commitments.
Pricing Analysis
European deployments command premium pricing over Indian and Brazilian markets due to EU AI Act compliance certification costs and sovereign hosting requirements. Three-tier pricing structure across premium, standard, and economy levels separates cloud-native SaaS subscriptions from perpetual on-premises licenses and managed service wrappers. Cost compression in standard-tier fault management tools is intensifying because hyperscaler partnerships enable operators to bypass traditional vendor professional services. Mobile network operators exhibit lowest price sensitivity due to SLA enforcement revenue protection, while regional ISPs in Brazil's underserved markets demonstrate acute elasticity.
Supply Chain Analysis
Extended payment terms from tier-one operators in Germany and India now stretch to 180 days, forcing mid-tier vendors toward supply-chain finance facilities anchored by receivables from sovereign-backed deployments. Manufacturing concentrates in Taiwan for advanced NPUs, South Korea for memory components, and China for commodity server hardware. The stack draws from specialized silicon foundries, container orchestration software licenses, and telecommunications-grade cooling infrastructure. Single-source vulnerability in TSMC's 5nm and 3nm process nodes exposes deployment timelines to geopolitical fabrication bottlenecks. Distribution runs through systems integrators with telco-specific professional services capabilities rather than direct vendor-to-operator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
5G standalone network slicing adoption represents an early-cycle expansion story as mobile operators accelerate procurement of automated assurance platforms to manage multi-vendor complexity.
For Market Incumbents: Build switching-cost moats through deep OSS/BSS integration that embeds proprietary network topology knowledge into fault correlation engines. Incumbents should consolidate Kubernetes expertise through targeted capability acquisition to counter cloud-native software specialists. Capacity addition in India's Karnataka technology cluster addresses PLI scheme indigenous equipment mandates while securing proximity to fastest-growing demand. For New Entrants and Emerging Players: Build out edge computing assurance platforms for Japanese METI latency requirements and Brazilian regional ISP greenfield deployments as the most penetrable white-space targets. New entrants should pursue consumption-based licensing models tied to subscriber volume, mirroring procurement preferences emerging in India and Brazil's managed services contracts. For Investors and Strategic Acquirers: The market sits at an infrastructure-replacement phase that favors cloud-native software specialists with demonstrated Kubernetes-telco protocol hybrid expertise. Long-term viability hinges on algorithmic transparency capabilities satisfying EU AI Act mandates across the European footprint. The signal to watch is container security certification timelines under Common Criteria evaluation, which currently stall production deployments and create acquisition windows for pre-certified assets.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Integration | Microservices architectures compress 5G network slicing deployment cycles for Deutsche Telekom and Vodafone. |
| Acquisition of Kubernetes Specialist | Rare combinations of container expertise and 3GPP protocol knowledge accelerate vendor scaling velocity. |
| Sovereign Cloud Partnership | BSI-compliant hosting deployments satisfy Germany's critical infrastructure cybersecurity requirements. |
| Edge Computing Product Launch | Localized inference engines at Japanese cell towers meet METI millisecond-scale remediation mandates. |
| PLI Scheme Joint Venture | Domestic manufacturing alignment with India's indigenous equipment mandates secures operator procurement preference. |
Research Methodology
A standing panel of network operations executives, cloud infrastructure architects, regulatory compliance officers, and procurement directors at tier-one mobile operators provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation from 3GPP standards documentation, FCC outage reporting databases, EU AI Act regulatory filings, and TRAI service-level compliance records. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates across deployment architectures and solution categories.
Scenario-bracketing framed optimistic and conservative adoption curves for cloud-native migration and edge computing penetration across the projection horizon. Segmentation dimensions modeled include deployment model, solution functional category, end-user operator type, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and net new deployment velocity incorporated 5G standalone rollout timelines and sovereign cloud procurement patterns as industry-specific forecast inputs.
Sensitivities concentrate around container security certification delays, foundry capacity allocation shifts, and national spectrum auction timing. Forecasts reflect documented assumptions regarding interoperability framework maturation and hyperscaler partnership expansion. Macroeconomic contraction, regulatory acceleration of algorithmic transparency requirements, or breakthrough open-source orchestration alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
United Kingdom Telecom Market
Telecommunications
Argentina ICT Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
IP Telephony Market
Telecommunications
5G Remote Radio Head Market
Telecommunications
Global Broadband Services Market
Telecommunications
Vietnam ICT Market
Telecommunications
India Optical Transport Network (OTN) Market
Telecommunications
Global 5G Services Market
Telecommunications
5G Monetization Market
Telecommunications
Satcom Terminal Market
Telecommunications
Angola Telecom Market
Telecommunications
Cloud Radio Access Network (C-RAN) Market
Telecommunications
International Wholesale Voice Carrier Market
Telecommunications
North America Underwater Communication Systems Market
Telecommunications
Mission Critical Communication (MCX) Market