
 Land Professional Mobile Radio Market | 2026-2036
Land Professional Mobile Radio Market Size, Share, and Industry Trends Forecast 2026-2036
Land Professional Mobile Radio Market Foresight
Distribution through government procurement frameworks is tilting toward vendors with in-country certification and local manufacturing presence. Motorola Solutions leverages its P25 and TETRA portfolios to sustain dominance in North American public safety contracts. Hytera Communications Corporation Limited anchors its position through competitive digital radio offerings across Asia-Pacific and European utilities sectors. L3Harris Technologies, Inc. specializes in mission-critical communications for defense and federal agencies, competing on encryption standards and interoperability testing.
Land Professional Mobile Radio comprises terrestrial wireless communication systems operating in VHF, UHF, and 700/800 MHz bands, engineered for push-to-talk voice and narrowband data transmission in environments where cellular networks fail or remain prohibited. These systems integrate trunking infrastructure, dispatch consoles, and ruggedized subscriber units to ensure coordinated response across public safety and industrial operations. Digital radios command the largest product type position as agencies retire analog fleets, while LTE-enabled technology represents the fastest-expanding segment as broadband-data requirements displace narrowband voice-only architectures. The public safety end user category absorbs the deepest investment cycles, though oil and gas applications in remote extraction zones generate premium-margin demand for intrinsically safe and satellite-backhauled configurations.
The FCC mandates P25 interoperability standards for federal grant eligibility in the United States, while ETSI governs TETRA and DMR specifications across European member states; Japan's ARIB standards create distinct certification requirements that fragment vendor access. China's MIIT imposes domestic encryption protocols and type-approval processes that condition market participation for foreign equipment suppliers. Stakeholders must monitor spectrum auction outcomes and migration timelines for 6 GHz and sub-700 MHz reallocations that will determine replacement cadence and technology selection across major procurement jurisdictions.
Market Dynamics
Spectrum scarcity is compressing channel availability across VHF, UHF, and 700/800 MHz bands, forcing public safety agencies and industrial operators toward spectrally efficient digital architectures that consolidate voice and data traffic onto narrower bandwidth allocations.
Growth Catalysts
- FCC P25 Mandates:Federal grant eligibility in the United States requires P25 interoperability compliance, accelerating analog replacement cycles among municipal police and fire departments.
- Remote Extraction Zones:Oil and gas operations in isolated territories generate premium demand for intrinsically safe radios with satellite backhaul capabilities.
- LTE Convergence:Broadband-data requirements among transportation authorities are displacing narrowband voice-only systems with hybrid LTE-LMR configurations.
Market Restraints
- Semiconductor Supply Concentration:RF component fabrication concentrates in East Asian foundries, exposing vendors to geopolitical disruption and allocation delays.
- Proprietary Encryption Protocols:China's MIIT domestic encryption standards fragment vendor access and inflate certification costs for foreign equipment suppliers.
- Legacy Infrastructure Sunk Costs:Analog system investments by budget-constrained rural agencies delay full-network digital migration timelines.
Strategic Opportunities
- Critical Infrastructure Protection:German utilities and railway operators are modernizing grid communication networks under federal resilience mandates.
- FirstNet Integration:Broadband priority access frameworks for emergency responders create attach opportunities for LTE-enabled subscriber units.
- Japan's ARIB Certification Gap:Distinct national standards limit incumbent competition, opening procurement windows for compliant foreign vendors.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized expertise in trunking infrastructure design and propagation modeling commands premium compensation, constraining vendor scaling.
- Interoperability Testing Complexity:Multi-vendor P25 compliance verification extends deployment timelines and inflates pre-award engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Land Professional Mobile Radio Market |
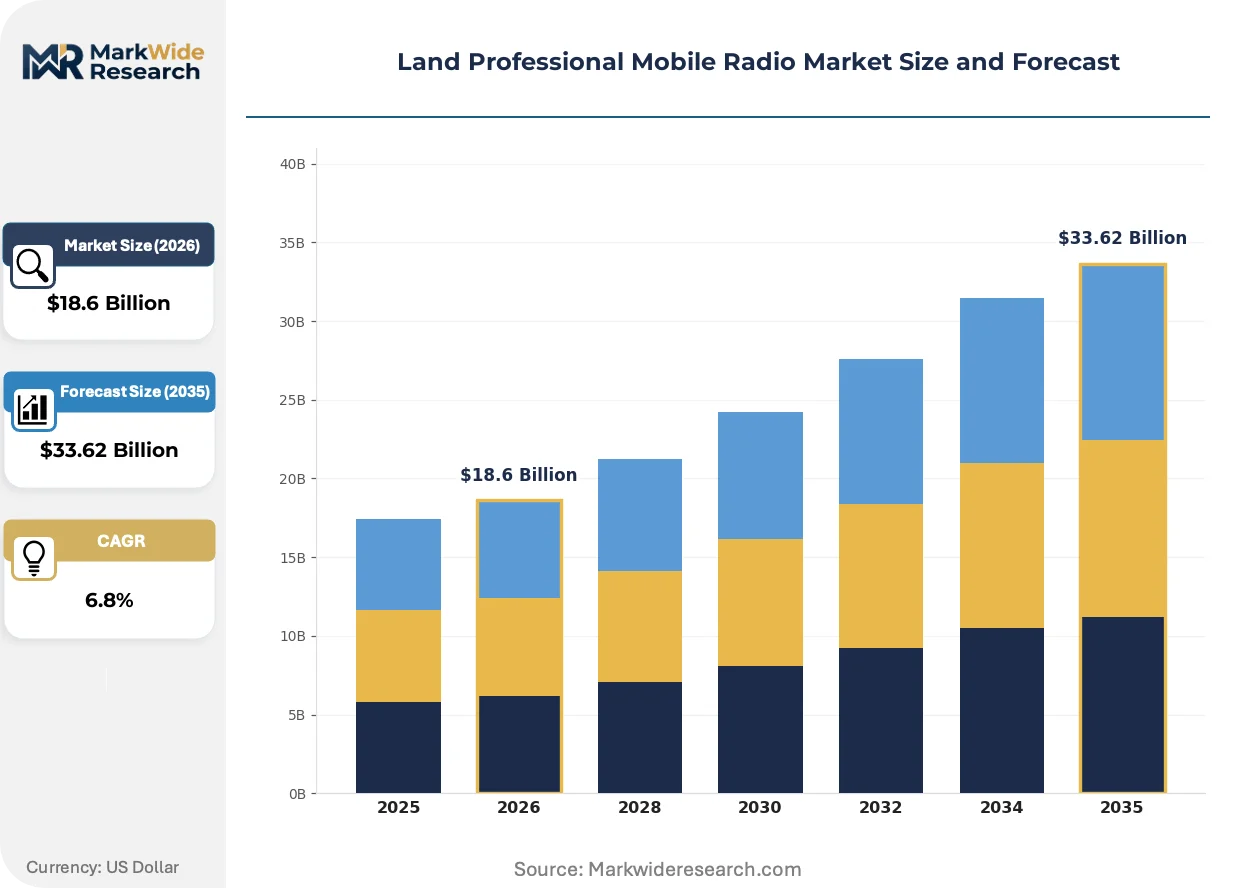
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Radios, Digital Radios, Hybrid Radios, Portable Radios Technology: DMR, P25, TETRA, LTE End User: Public Safety, Transportation, Utilities, Oil & Gas Connectivity: Wired, Wireless, Satellite, Cellular |
| Companies Covered | Motorola Solutions, Inc., Hytera Communications Corporation Limited, L3Harris Technologies, Inc., Airbus Defence and Space, JVCKENWOOD Corporation, Thales, Tait Communications, Sepura Limited, Icom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Land Professional Mobile Radio Market Shifts & Advancements
Digital modulation schemes and broadband integration are redefining professional mobile radio architectures, compressing the transition window between legacy narrowband voice and unified critical-communications platforms.
Project 25 Phase 2 TDMA technology doubles spectral efficiency through two-slot channel sharing, enabling simultaneous voice and data transmission. State-level emergency communications agencies in the United States are adopting Phase 2 core infrastructure at accelerated procurement cadences. The technology is migrating from early-adopter metropolitan departments toward mid-size county systems, consolidating vendor relationships around trunking specialists.
ETSI's harmonized spectrum frameworks for TETRA and DMR are standardizing cross-border interoperability for European public safety coalitions. The policy compresses national certification fragmentation, enabling multi-country fleet contracts for transportation and utility operators. German federal police and French gendarmerie procurement frameworks now prioritize ETSI-compliant equipment, reshaping vendor qualification requirements.
Consolidated purchasing through state-level emergency communications authorities is displacing municipal-level RFP fragmentation. Texas, California, and Florida procurement offices now negotiate master service agreements covering subscriber units, infrastructure, and maintenance. This concentration shifts pricing leverage toward volume-scale vendors and compresses margins for regional system integrators.
Land Professional Mobile Radio Market Segmentation
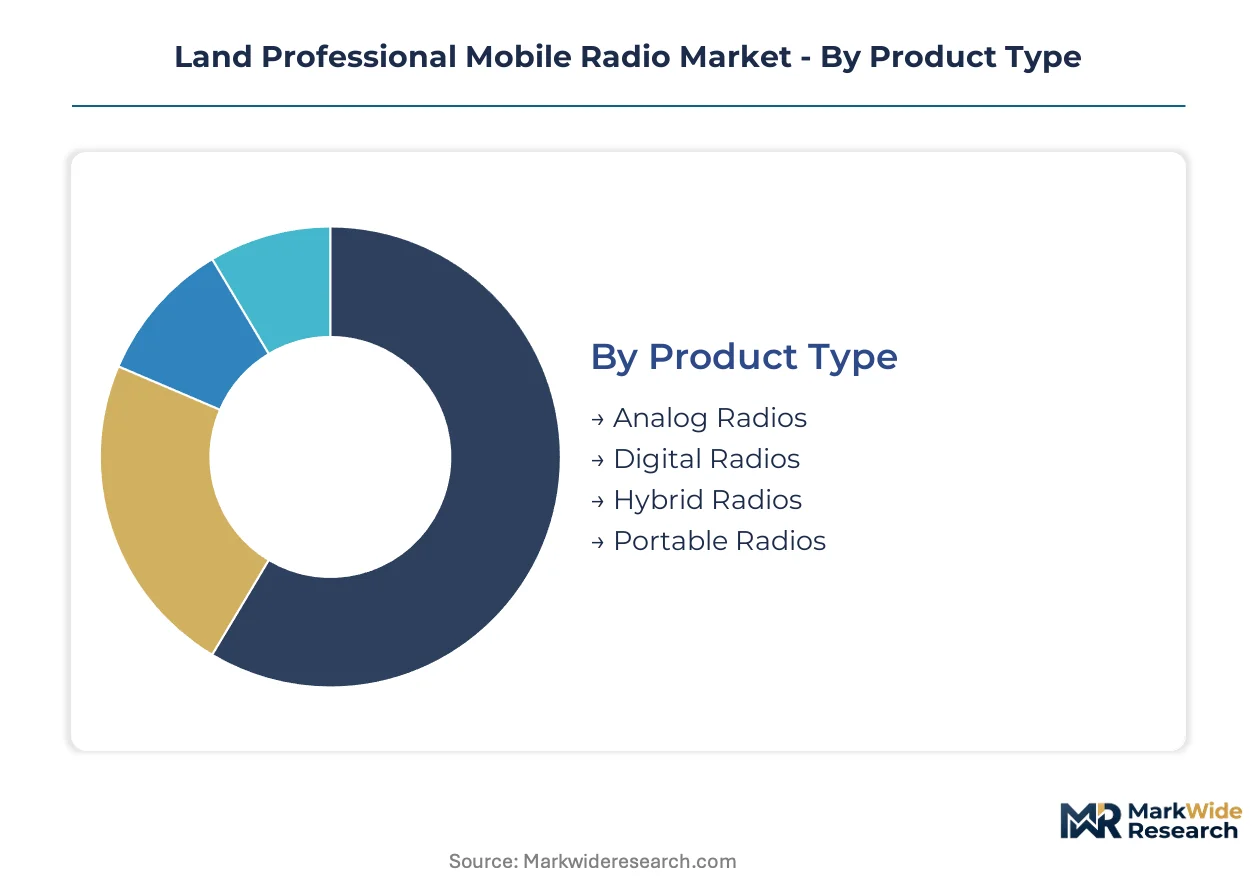
Land Professional Mobile Radio systems serve divergent operational requirements across first responder networks, industrial extraction sites, and transportation corridors. Segmentation reveals how spectral efficiency mandates, broadband convergence pressures, and hazardous environment certifications reshape procurement patterns across subscriber unit categories.
Product Type:
Use-case spectrum spans legacy analog fleets in budget-constrained rural agencies through LTE-enabled hybrid platforms serving metropolitan transportation authorities.
- Digital Radios:P25 Phase 2 TDMA and TETRA architectures consolidate voice and narrowband data onto spectrally efficient channels. United States public safety agencies retiring analog infrastructure under FCC grant mandates concentrate procurement here, compressing replacement timelines for municipal police and fire departments.
- Portable Radios:Ruggedized subscriber units engineered for 700/800 MHz trunking networks integrate GPS location services and encryption modules. German federal police procurement frameworks prioritize intrinsically safe portable configurations for tactical response teams.
- Analog Radios:Legacy narrowband FM systems persist in rural jurisdictions with sunk infrastructure costs and limited interoperability requirements.
- Hybrid Radios:Dual-mode devices bridge LMR voice with LTE broadband data, serving transportation authorities managing unified critical communications platforms.
The dominant share belongs to Digital Radios, while Hybrid Radios are closing the gap fastest.
Technology:
Cost tier separation runs from TETRA infrastructure investments through software-defined LTE migration paths.
- P25:North American interoperability standard mandating AES encryption and ISSI/CSSI trunking interfaces for federal grant eligibility. State-level emergency communications authorities in Texas and California consolidate procurement around P25 Phase 2 core infrastructure.
- LTE:Broadband priority access frameworks enable video streaming, database queries, and situational awareness applications beyond narrowband voice constraints. FirstNet integration creates attach opportunities for mission-critical LTE subscriber units among United States first responder agencies.
- DMR:ETSI Tier II and Tier III specifications serve European commercial and industrial operators with cost-efficient digital migration from analog fleets.
- TETRA:TDMA-based trunking standard dominates European public safety and transportation sectors under harmonized ETSI spectrum frameworks.
P25 commands the installed base, though LTE is expanding most quickly.
End User:
Application intensity varies from life-safety response latency requirements through remote extraction zone survivability specifications.
- Public Safety:Police, fire, and emergency medical services demand sub-second push-to-talk latency, hardened encryption, and interoperability across jurisdictional boundaries. FCC P25 mandates accelerate analog replacement cycles among United States municipal departments.
- Oil & Gas:Offshore platforms and remote drilling operations require intrinsically safe certifications, satellite backhaul capabilities, and extreme temperature resilience. Premium-margin demand concentrates in North Sea extraction zones and Middle East production facilities.
- Transportation:Railway operators and aviation ground services prioritize trunking capacity for coordinated fleet dispatch across wide-area coverage footprints.
- Utilities:Grid operators and pipeline controllers modernize field force communications under federal resilience mandates, particularly German electricity distribution networks.
Public Safety absorbs the deepest investment cycles, while Oil & Gas generates the steepest expansion trajectory.
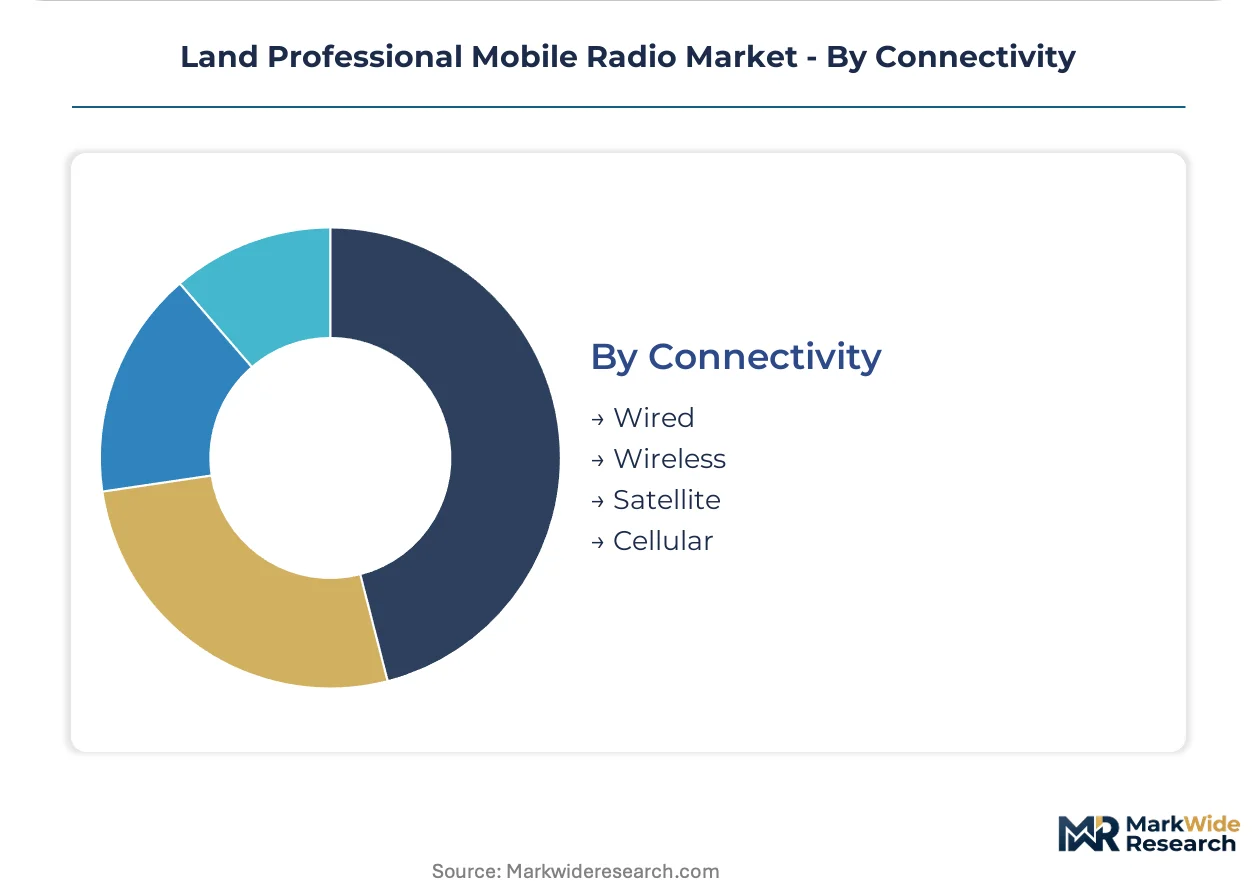
Connectivity:
Supply concentration for RF components shapes reliability differentiation across terrestrial and satellite-dependent architectures.
- Wireless:VHF, UHF, and 700/800 MHz terrestrial trunking networks deliver push-to-talk services where cellular coverage fails or remains prohibited. Japanese ARIB standards create distinct certification requirements for wireless infrastructure deployments.
- Satellite:BGAN and VSAT backhaul extends LMR coverage beyond terrestrial infrastructure into maritime, aviation, and polar extraction zones. Remote oil field operations in isolated territories generate premium demand for satellite-integrated subscriber units.
- Cellular:Commercial LTE/5G networks supplement mission-critical voice with broadband data, though priority access frameworks remain essential for emergency responder preemption.
- Wired:Dispatch console and core network infrastructure relies on fiber and copper backhaul for trunking site connectivity and centralized network management.
Wireless maintains the dominant share, while Satellite is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where P25 and TETRA procurement frameworks favor certified incumbents, while Chinese vendors compete on cost in spectrum-restricted emerging markets.
United States
First responder agencies in Texas, California, and Florida drive replacement cycles through consolidated state-level procurement agreements. FCC P25 mandates condition federal grant eligibility on AES encryption and ISSI/CSSI trunking compliance. Motorola Solutions anchors manufacturing and certification operations in Illinois while serving metropolitan police departments with Phase 2 core infrastructure.
Germany
Federal police and railway operators modernize grid communications under federal resilience mandates for critical infrastructure protection. ETSI harmonized spectrum frameworks standardize TETRA and DMR specifications across European coalitions. Thales and Airbus Defence and Space concentrate engineering resources in Munich and Ulm, supplying trunking systems to Bundeswehr and Deutsche Bahn.
China
MIIT domestic encryption protocols and type-approval processes condition market participation for public safety and transportation authorities. Hytera Communications Corporation Limited anchors digital radio production in Shenzhen, serving utilities and municipal police across Asia-Pacific. The Yangtze River Delta cluster concentrates RF component fabrication and system integration capacity.
Japan
ARIB standards create distinct certification requirements that fragment vendor access to first responder and industrial markets. JVCKENWOOD Corporation maintains engineering and manufacturing presence in Yokohama, supplying intrinsically safe configurations to Tokyo Metropolitan Police and offshore extraction operators. METI spectrum reallocation policies compress available channels in the 700/800 MHz bands.
United Kingdom
Home Office procurement frameworks prioritize ETSI-compliant equipment for police and emergency services transitioning from Airwave TETRA networks. Sepura Limited, headquartered in Cambridge, supplies subscriber units and infrastructure to British Transport Police and regional fire authorities. The Midlands manufacturing corridor hosts final assembly and interoperability testing facilities.
Land Professional Mobile Radio Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying RF modules and encryption chipsets. The vendor base stratifies between trunking infrastructure providers, subscriber unit manufacturers, and software-defined radio developers. Three archetypes dominate: defense-heritage conglomerates with classified program experience, commercial communications specialists with public safety certification depth, and Asian cost-optimized producers serving price-sensitive utilities. Consolidation pressures intensify through state-level procurement concentration and multi-year managed service contracts that favor balance-sheet scale.
Among defense-heritage conglomerates, L3Harris Technologies, Inc. exemplifies the mission-critical encryption tier, while Motorola Solutions, Inc. anchors the North American public safety certification vector. Hytera Communications Corporation Limited occupies the cost-optimized international expansion position, competing on digital migration economics across Asia-Pacific and European utilities. These three represent distinct competitive postures rather than interchangeable substitutes.
| Leading Market Players |
|---|
| Motorola Solutions, Inc. |
| Hytera Communications Corporation Limited |
| L3Harris Technologies, Inc. |
| Airbus Defence and Space |
| JVCKENWOOD Corporation |
| Thales |
| Tait Communications |
| Sepura Limited |
| Icom Inc. |
| Others |
Supply & Pricing Matrix
East Asian foundry concentration for RF power amplifiers and baseband processors concentrates margin capture upstream, while downstream pricing power fragments across municipal procurement offices, state-level emergency communications authorities, and industrial fleet operators with divergent volume scales and certification requirements.
Pricing Analysis
Configured-to-order pricing for P25 Phase 2 trunking infrastructure and intrinsically safe portable units commands substantial premiums over standard analog subscriber units. Three-tier pricing structure across mission-critical encryption, public safety grade, and commercial utility tiers separates buyers by certification depth and interoperability testing burden. Pricing pressure stems from consolidated state-level procurement agreements in Texas and California that compress margins through volume-scale master service agreements. Rural municipal departments exhibit highest price sensitivity due to federal grant dependency and legacy sunk costs, while oil and gas operators in remote extraction zones demonstrate lowest sensitivity given operational criticality and premium safety specifications.
Supply Chain Analysis
Contract manufacturing for ruggedized subscriber units concentrates in Shenzhen and Dongguan electronics clusters, with Foxconn and Jabil holding dominant EMS capacity for Motorola Solutions and Hytera production lines. RF component fabrication draws from Taiwan Semiconductor Manufacturing Company foundries in Hsinchu, South Korean Samsung and SK Hynix memory suppliers in Pyeongtaek, and Japanese Murata ceramic filter manufacturers in Kyoto. Single-source vulnerability in GaN-on-SiC power amplifier supply from Wolfspeed's North Carolina fab exposes vendors to geopolitical disruption and allocation delays. Distribution runs through government procurement frameworks requiring in-country certification and local manufacturing presence for federal grant eligibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through state-level emergency communications authorities that displace municipal RFP fragmentation, consolidating procurement leverage around volume-scale vendors with Phase 2 infrastructure and managed service capabilities.
For Market Incumbents: Entrench position through backward integration into RF module design and captive trunking software development to defend against LTE convergence threats from cellular equipment vendors. Deepen certification moats by accelerating P25 Phase 2 core infrastructure deployments in consolidated state procurement frameworks before FirstNet integration displaces narrowband voice architectures. Prioritize encryption chipset supply agreements with domestic foundries to mitigate East Asian semiconductor concentration risks. For New Entrants and Emerging Players: Mid-size county public safety agencies in the United States represent the most penetrable entry point, as these jurisdictions lag metropolitan Phase 2 adoption and lack incumbent vendor lock-in from legacy analog infrastructure. German railway and utility operators modernizing under federal resilience mandates offer secondary white-space opportunity given ETSI harmonization compressing national certification fragmentation. Pursue go-to-market positioning through interoperability testing partnerships with established trunking specialists rather than direct infrastructure competition. For Investors and Strategic Acquirers: Capital is best deployed toward software-defined radio developers with LTE-LMR hybrid platforms and established FirstNet integration pathways, as broadband-data requirements displace narrowband architectures across the analysis window. Long-term viability hinges on spectrum auction outcomes and 6 GHz reallocation timelines that will determine replacement cadence for legacy infrastructure. Monitor FCC grant disbursement velocity and state-level procurement office consolidation announcements as early inflection indicators for vendor market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| P25 Phase 2 Infrastructure Deployment | State-level emergency communications authorities in Texas and California consolidate procurement around TDMA trunking systems. |
| FirstNet Integration Partnership | Broadband priority access frameworks create attach opportunities for LTE-enabled subscriber units among first responder agencies. |
| Intrinsic Safety Certification Investment | ATEX and IECEx approvals unlock premium-margin demand from North Sea and Middle East oil and gas operators. |
| RF Component Supply Agreement | GaN power amplifier sourcing from Wolfspeed mitigates East Asian foundry concentration and allocation delay risks. |
| ETSI Harmonization Compliance | German federal police and French gendarmerie procurement frameworks prioritize cross-border interoperable TETRA equipment. |
Research Methodology
Operator-level perspectives from public safety communications directors, state procurement officers, RF engineering leads at infrastructure vendors, and oil and gas field operations managers anchored the qualitative base for this study. Primary interview findings triangulated against FCC grant disbursement databases, ETSI standardization documentation, SEC 10-K filings from listed equipment vendors, and customs records for RF component trade flows. Bottom-up subscriber unit shipment estimates and top-down infrastructure deployment valuations converged through iterative reconciliation across the projection horizon.
Scenario-bracketing around spectrum reallocation timelines, federal grant funding velocity, and LTE migration pace framed the analytical approach across the modeling period. Segmentation dimensions modeled include product type, technology standard, end-user vertical, and connectivity architecture, with additional granularity on certification tier and procurement channel. CAGRs derived from logistic diffusion curves fitted to analog replacement cycles and broadband adoption patterns, incorporating MIIT type-approval delays and ARIB certification bottlenecks as industry-specific forecast inputs.
Practitioners should monitor FCC 6 GHz auction outcomes, state-level procurement consolidation announcements, and FirstNet coverage expansion metrics for early signals of technology substitution inflection. Forecasts reflect assumptions regarding federal grant continuity, East Asian semiconductor supply stability, and ETSI harmonization enforcement without guarantee. Quarterly review of infrastructure deployment permits, interoperability testing backlog durations, and satellite backhaul contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
GPON Market
Telecommunications
Carrier Aggregation Solutions Market
Telecommunications
Asia Pacific Telecom Expense Management Market
Telecommunications
Telecom Radio System Software Market
Telecommunications
LTE Advanced Pro Market
Telecommunications
Norway Telecom Market
Telecommunications
Europe Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Bahrain Telecom Market
Telecommunications
Denmark Telecom Market
Telecommunications
Global GPON Technology Market
Telecommunications
Austria ICT Market
Telecommunications
Global 5G in Healthcare Market
Telecommunications
Germany Fixed Wireless Access (FWA) Market
Telecommunications
US 5G Radio Access Network Professional Services Market
Telecommunications
Poland Telecom Market
Telecommunications
Asia-Pacific IPTV Market